
 Time-Of-Flight Chip Market | 2026-2036
Time-Of-Flight Chip Market Size, Share, and Industry Trends Forecast 2026-2036
Time-Of-Flight Chip Market Insights
Software-defined calibration layers for ToF modules is realigning vendor economics away from pure hardware shipments. STMicroelectronics leverages its MEMS foundry integration to sustain cost leadership in consumer-grade 3D sensors. Texas Instruments anchors its position through programmable DSP architectures that let automotive clients re-tune depth algorithms post-deployment. Infineon Technologies competes by specializing in automotive-qualified indirect-ToF arrays with extended temperature ranges.
A time-of-flight chip measures photon transit time between emitter and receiver to calculate depth, typically operating at near-infrared wavelengths with modulation frequencies above 20 MHz for millimeter-scale precision. These devices enable spatial mapping for gesture recognition, collision avoidance, and volumetric measurement across industrial and consumer systems. Optical Sensors command the largest revenue pool today because smartphone face-authentication modules still ship in hundred-million-unit volumes. Lidar Sensors represent the fastest-expanding category as robotic vacuum and last-mile delivery vehicle producers adopt solid-state scanning. Consumer Electronics Manufacturers absorb the dominant share of unit volume, though Automotive OEMs are pulling higher average selling prices per socket.
FCC Part 15 laser safety rules and FDA eye-safety classifications constrain emitter power levels in US-designed modules, while CE marking under the EU MDR governs medical imaging applications of ToF technology. China's GB standards for optoelectronic devices and MIIT frequency allocation rules shape what modulation schemes domestic suppliers can deploy. Stakeholders must track how automotive functional-safety certifications migrate from camera-based systems toward depth-sensor architectures.
Market Dynamics
Automotive OEMs are forcing a recalibration of ToF chip architectures toward functional-safety compliance, pulling design priorities away from consumer electronics optimization and toward extended temperature ranges and redundant depth computation.
Growth Catalysts
- EU AI Act compliance mandates:Vehicle manufacturers must certify depth-sensing systems for automated decision-making, creating certified socket demand for automotive-qualified indirect-ToF arrays.
- China EV production concentration:Domestic smartphone brands and electric vehicle producers are integrating ToF arrays at scale, absorbing module supply from Shenzhen and Shanghai clusters.
- Solid-state lidar substitution:Robotic vacuum and last-mile delivery vehicle producers are abandoning mechanical scanning for chip-scale ToF solutions, compressing bill-of-materials costs.
Market Restraints
- III-V semiconductor supply concentration:Vertical-cavity surface-emitting laser epitaxy concentrates in Taiwanese and US foundries, exposing module makers to single-source risk during capacity constraints.
- FCC Part 15 power ceilings:Laser safety rules constrain emitter output in US-designed modules, capping effective range for outdoor automotive applications.
- Indirect-ToF precision limits:Phase-wrap ambiguity at extended distances prevents single-chip solutions from displacing direct-ToF in long-range lidar sockets.
Strategic Opportunities
- Medical imaging certification pathway:CE marking under the EU MDR for optoelectronic diagnostic devices opens surgical navigation and patient monitoring applications.
- India PLI scheme leverage:Domestic smartphone assembly incentives are pulling module integration toward Noida and Chennai manufacturing corridors.
- Software-defined calibration convergence:Programmable DSP architectures combined with MEMS foundry integration enable post-deployment algorithm re-tuning, creating recurring revenue streams.
Industry Challenges
- Automotive functional-safety certification timelines:ISO 26262 ASIL-D qualification for depth-sensor architectures extends development cycles 18-24 months beyond consumer-grade equivalents.
- Multi-junction VCSEL integration complexity:Stacking emitter arrays with diffractive optical elements requires precision alignment expertise scarce in tier-two module houses.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Time-Of-Flight Chip Market |
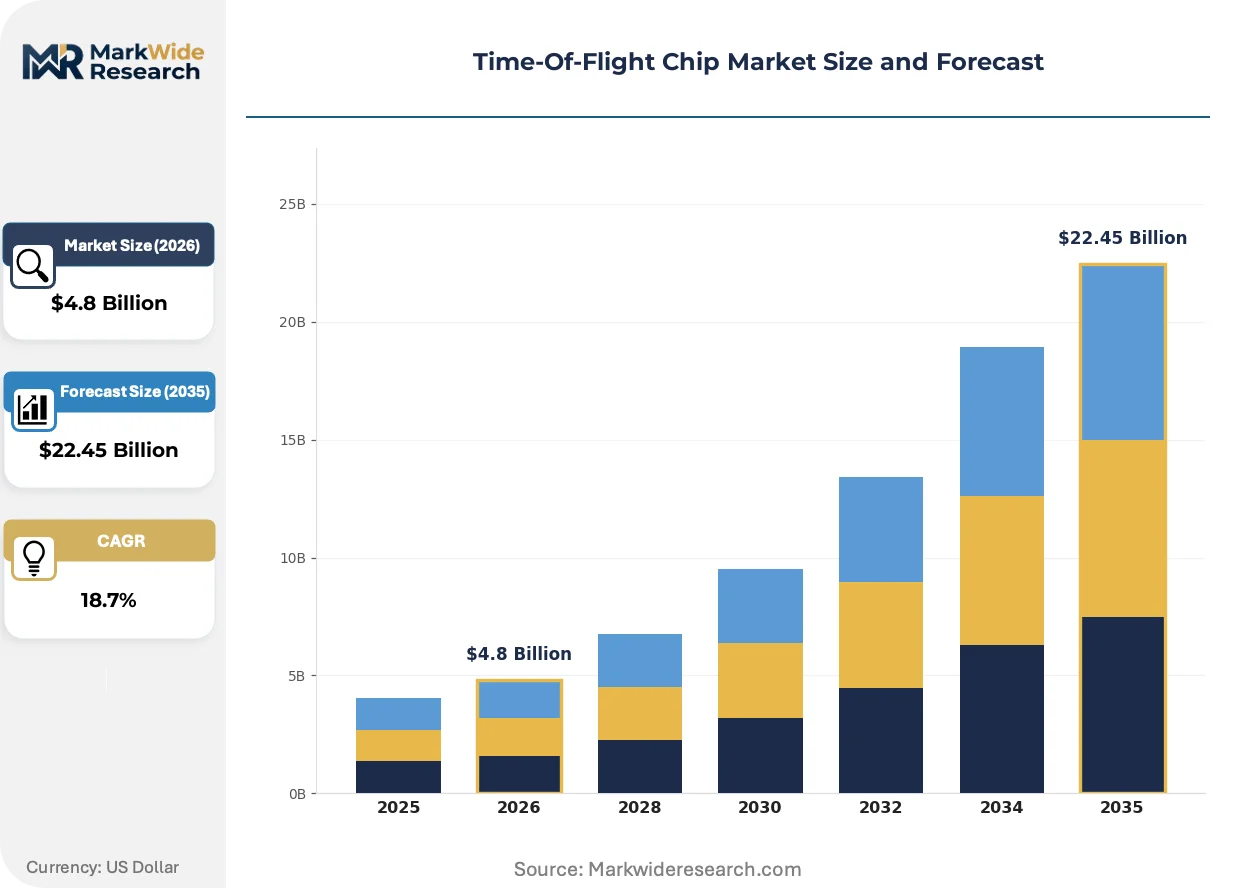
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $22.45 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 3D Sensors, Lidar Sensors, Optical Sensors, Ultrasonic Sensors Application: Robotics, Automotive, Consumer Electronics, Industrial Automation Technology: Time-of-Flight, Structured Light, Stereo Vision, Laser Scanning End User: Consumer Electronics Manufacturers, Automotive OEMs, Industrial Equipment Makers, Research Institutions |
| Companies Covered | STMicroelectronics, Texas Instruments, Infineon Technologies, Sony Semiconductor Solutions, Samsung Electronics, onsemi, ams-OSRAM, Panasonic, pmdtechnologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Time-Of-Flight Chip Market Trends and Innovations
Silicon photonics integration is collapsing the boundary between emitter and receiver functions, enabling chip-scale solid-state scanning that rewrites module form-factor assumptions across automotive and robotics applications.
SPAD-based direct-ToF arrays are absorbing the precision demands previously served by discrete photon-counting modules. Automotive tier-1 suppliers are qualifying these devices for cabin monitoring and exterior collision avoidance, compressing the cost premium over indirect-ToF from 3x to 1.5x within a single design generation. The structural consequence is a tier collapse: mid-range automotive sockets now demand direct-ToF performance at indirect-ToF price points.
REACH restriction proposals on indium phosphide are forcing emitter suppliers to accelerate gallium arsenide alternative development. Compound semiconductor foundries in Europe and Asia-Pacific are requalifying epitaxial processes to maintain CE marking eligibility for high-power VCSELs. Medical imaging and industrial metrology applications face the steepest compliance timelines, with MDR technical documentation requiring updated material safety datasheets by Q3 2026.
Fleet operators and robotics OEMs are consolidating procurement around vertically integrated module suppliers capable of delivering calibrated depth stacks rather than discrete components. Tier-1 automotive buyers now specify millimeter-accurate factory calibration as a delivered specification, displacing the historical model of uncalibrated chip sales to module integrators. This specification compression is most visible in Germany and Japan, where KBA and METI type-approval processes reward pre-certified subsystem sourcing.
Time-Of-Flight Chip Market Segmentation
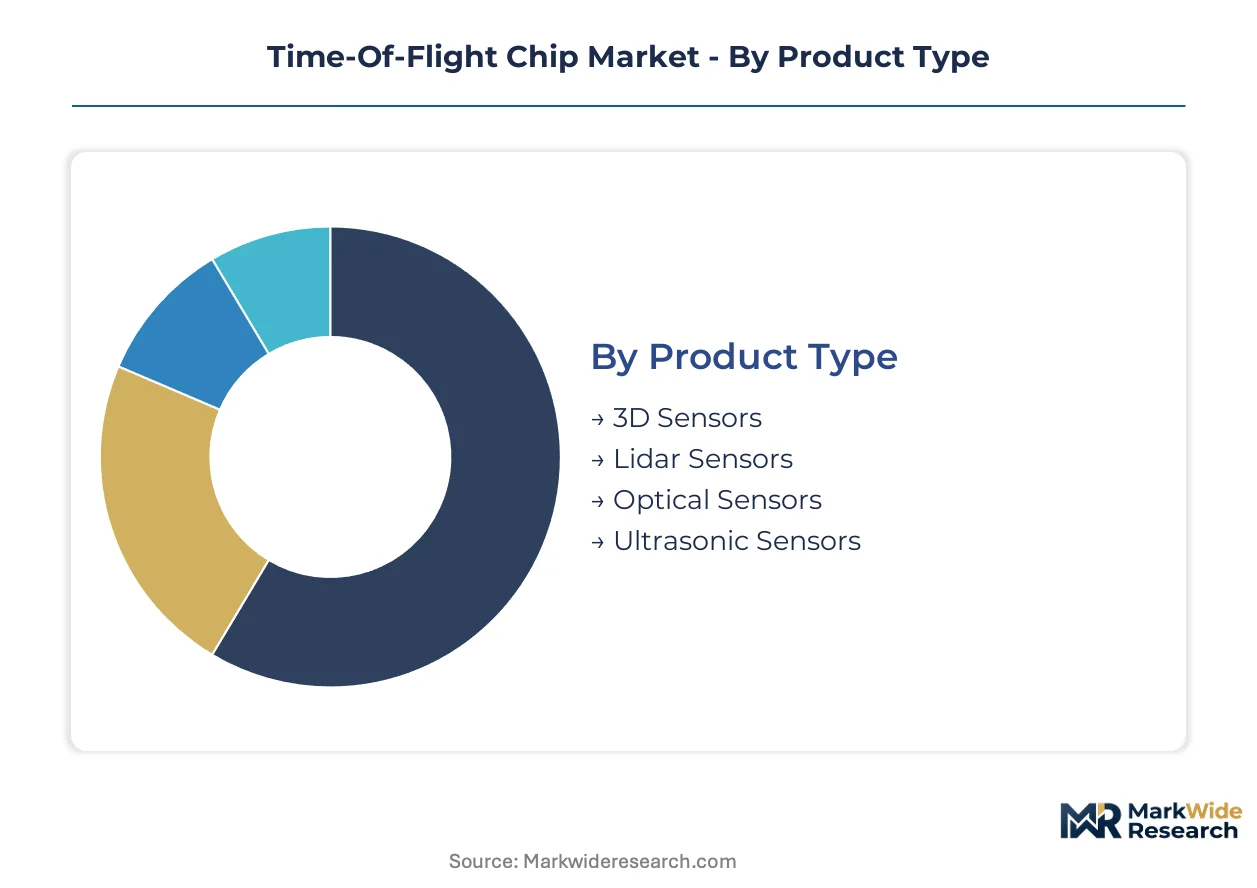
ToF chip procurement patterns diverge sharply across application contexts, with automotive qualification cycles and consumer electronics volume economics pulling architectures in opposing directions. Upgrade cycles in smartphone face-authentication and EV cabin-monitoring systems are reshaping vendor portfolio priorities.
Product Type:
Replacement dynamics in smartphone and automotive platforms are accelerating sensor format transitions, with module makers phasing out legacy discrete designs in favor of integrated depth-sensing stacks.
- Optical Sensors:Near-infrared emitter-receiver arrays operating above 20 MHz modulation frequencies deliver millimeter-scale depth precision for face-authentication modules. China-based smartphone brands in Shenzhen and Shanghai absorb the dominant share of unit placements, though FCC Part 15 power ceilings constrain effective range for US-designed variants.
- Lidar Sensors:Solid-state scanning architectures abandon mechanical rotating assemblies in favor of chip-scale beam steering, compressing bill-of-materials costs for robotic vacuum and last-mile delivery vehicle producers. Robotic OEMs in Japan and Germany specify these devices for warehouse automation and autonomous navigation sockets.
- 3D Sensors:Integrated depth-sensing modules combining emitter, receiver, and processing logic in single packages serve gesture recognition and spatial mapping applications.
- Ultrasonic Sensors:Acoustic time-of-flight alternatives supplement optical systems in environments where ambient light interference degrades infrared performance.
Volume placements concentrate in Optical Sensors; the faster expansion belongs to Lidar Sensors.
Application:
Cost tier differentiation separates safety-critical automotive deployments from price-sensitive consumer electronics integrations, with certification overhead creating margin stratification across application contexts.
- Consumer Electronics:Smartphone and tablet manufacturers integrate compact indirect-ToF arrays for face unlock and portrait depth effects, prioritizing form-factor miniaturization over extended range. Domestic brands in China are pulling module supply toward Shenzhen assembly clusters at scale.
- Automotive:Cabin-monitoring and exterior collision-avoidance systems demand automotive-qualified indirect-ToF arrays with extended temperature ranges and redundant depth computation. EU AI Act compliance mandates are forcing recertification of depth-sensing architectures for automated decision-making.
- Robotics:Robotic vacuum and warehouse automation platforms adopt solid-state lidar for simultaneous localization and mapping.
- Industrial Automation:Volumetric measurement and quality inspection applications require sub-millimeter precision for manufacturing process control.
Automotive applications command the highest average selling prices per socket; Consumer Electronics dominates absolute unit volume.
Technology:
Technology maturity curves are separating phase-based indirect methods from photon-counting direct approaches, with precision requirements and cost constraints determining adoption boundaries.
- Time-of-Flight:Photon transit measurement between emitter and receiver enables depth calculation at near-infrared wavelengths, with direct-ToF SPAD arrays absorbing precision demands previously served by discrete photon-counting modules. Phase-wrap ambiguity at extended distances prevents single-chip solutions from displacing direct-ToF in long-range lidar sockets.
- Structured Light:Projected pattern deformation analysis delivers high-fidelity depth maps for close-range applications where power consumption must stay minimal.
- Stereo Vision:Dual-camera triangulation methods persist in cost-constrained applications lacking dedicated depth-sensing hardware.
- Laser Scanning:Mechanical beam steering retains niche positioning in high-precision industrial metrology despite solid-state substitution pressure.
Time-of-Flight holds the dominant installed base; direct-ToF variants within this category are climbing the fastest as automotive tier-1 suppliers compress cost premiums.
End User:
Customer type determines specification rigor, with automotive OEMs imposing factory calibration requirements that displace uncalibrated chip sales to module integrators.
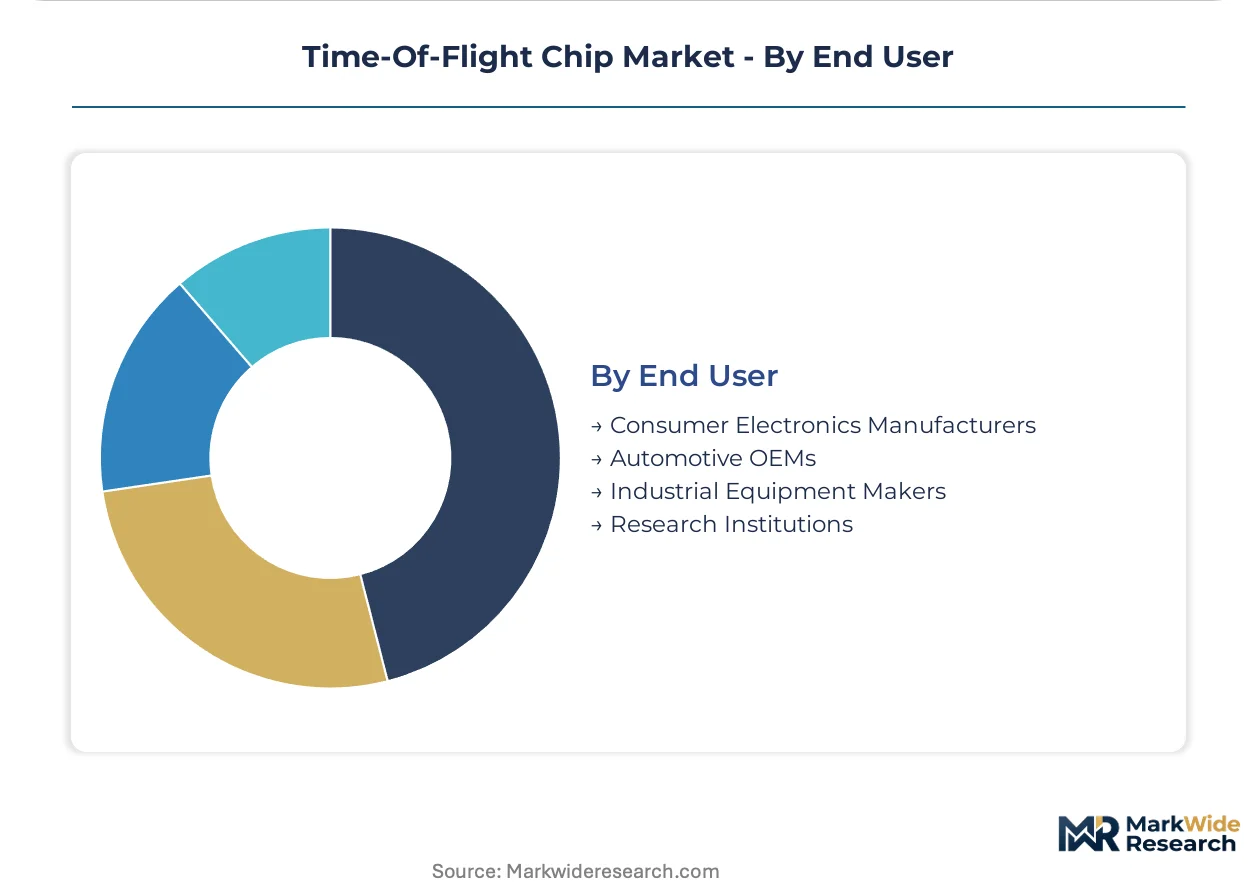
- Consumer Electronics Manufacturers:Smartphone and wearable device makers specify compact, low-power depth-sensing modules for face authentication and gesture recognition, with procurement consolidating around vertically integrated suppliers capable of delivering calibrated depth stacks.
- Automotive OEMs:Vehicle manufacturers now specify millimeter-accurate factory calibration as a delivered specification, extending ISO 26262 ASIL-D qualification timelines substantially beyond consumer-grade equivalents. KBA and METI type-approval processes in Germany and Japan reward pre-certified subsystem sourcing.
- Industrial Equipment Makers:Factory automation and logistics system builders integrate ToF arrays for dimensioning and collision avoidance.
- Research Institutions:Academic and government laboratories prototype next-generation depth-sensing architectures for medical imaging and scientific instrumentation.
Consumer Electronics Manufacturers absorb the greatest unit volume; Automotive OEMs generate the highest revenue per socket.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China consumes the dominant share of ToF chip output while Taiwan and the United States concentrate critical emitter epitaxy capacity. Module integration clusters in Shenzhen and Shanghai pull supply toward domestic EV and smartphone brands. Regulatory divergence across major economies is fragmenting certification pathways and reshaping vendor geographic priorities.
China
Domestic EV producers and smartphone manufacturers integrate ToF arrays at scale, absorbing module supply from Shenzhen and Shanghai assembly clusters. MIIT frequency allocation rules and GB standards for optoelectronic devices shape permissible modulation schemes for domestic suppliers. The Yangtze River Delta and Pearl River Delta regions concentrate both module fabrication and downstream system integration for automotive and consumer applications.
United States
Autonomous vehicle developers and robotics OEMs drive demand for automotive-qualified depth-sensing architectures. FCC Part 15 laser safety rules and NHTSA testing protocols constrain emitter power levels and tighten performance benchmarks for optical sensing systems. Silicon Valley and Austin tech corridors anchor design activity, though critical III-V semiconductor epitaxy remains concentrated in specialized foundries.
Germany
Automotive tier-1 suppliers specify millimeter-accurate factory calibration for cabin-monitoring and collision-avoidance systems. KBA type-approval processes reward pre-certified subsystem sourcing, extending ISO 26262 ASIL-D qualification timelines. Bavaria and Baden-Württemberg host the densest concentration of automotive sensor qualification labs and tier-1 module integration facilities.
Japan
Robotics OEMs and automotive manufacturers adopt solid-state lidar for warehouse automation and autonomous navigation sockets. METI standards and JIS certification requirements shape procurement specifications for industrial depth-sensing modules. The Kanto region around Tokyo and the Chubu region near Nagoya concentrate both robotics system builders and precision optical component suppliers.
South Korea
Consumer electronics manufacturers and automotive suppliers integrate compact ToF arrays for face authentication and gesture recognition. MFDS medical device regulations and national optoelectronic standards influence certification pathways for diagnostic imaging applications. The Seoul Capital Area anchors both smartphone brand headquarters and display-integrated sensor module production.
Time-Of-Flight Chip Market Competitive Landscape
Top-tier vendors anchor automotive qualification and MEMS foundry integration, while mid-tier specialists compete on software-defined calibration and programmable DSP architectures. The vendor base stratifies across three tiers: integrated semiconductor conglomerates with captive MEMS capacity, fabless chip designers licensing DSP cores, and module houses consolidating around vertically integrated depth stack delivery. Two strategic archetypes dominate: MEMS-integrated cost leaders leveraging foundry scale, and programmable architecture providers enabling post-deployment algorithm re-tuning. Competitive moves concentrate on backward integration into emitter epitaxy and strategic partnerships with automotive tier-1 suppliers for pre-certified subsystem sourcing.
Within the integrated semiconductor tier, STMicroelectronics exemplifies MEMS foundry-anchored cost leadership in consumer-grade 3D sensors. Texas Instruments occupies a position on the programmable DSP architecture vector, enabling automotive clients to re-tune depth algorithms post-deployment. Infineon Technologies sits within the automotive-qualified specialization archetype, focusing on indirect-ToF arrays with extended temperature ranges.
| Leading Market Players |
|---|
| STMicroelectronics |
| Texas Instruments |
| Infineon Technologies |
| Sony Semiconductor Solutions |
| Samsung Electronics |
| onsemi |
| ams-OSRAM |
| Panasonic |
| pmdtechnologies |
| Others |
Pricing and Supply Chain Analysis
Captive MEMS foundry integration anchors both cost position and pricing power for tier-one ToF chip vendors, locking in emitter-receiver co-fabrication advantages that fabless competitors cannot replicate without massive capital deployment. This integration choice compresses bill-of-materials for indirect-ToF arrays while forcing module makers toward multi-source qualification strategies that fragment procurement leverage.
Pricing Analysis
Margin tightening in automotive-grade indirect-ToF sockets reflects ISO 26262 ASIL-D certification overhead and extended temperature-range qualification costs. Three-tier pricing structure across premium, standard, and economy levels separates automotive OEM factory-calibrated stacks from consumer-grade uncalibrated chips and industrial metrology modules. Price differentiation hinges on certification grade and vertical integration depth. Cost compression accelerates as robotic vacuum OEMs consolidate procurement around vertically integrated depth-stack suppliers. Consumer electronics manufacturers exhibit highest price sensitivity; automotive tier-1 buyers absorb premium pricing for pre-certified subsystem sourcing.
Supply Chain Analysis
Dual-sourcing requirements from automotive OEMs mandate multi-supplier qualification for VCSEL epitaxy, forcing module makers to maintain relationships with both Taiwanese and US compound semiconductor foundries. Geographic supply concentration centers on Taiwan, the United States, and China for III-V semiconductor epitaxy, with Shenzhen and Shanghai clusters handling downstream module integration. Raw material dependencies include indium phosphide, gallium arsenide substrates, and diffractive optical elements. Single-source vulnerability concentrates in vertical-cavity surface-emitting laser epitaxy capacity. Distribution runs through tier-1 automotive suppliers and vertically integrated module houses rather than discrete component channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Solid-state lidar architectures are displacing mechanical scanning systems across robotics and automotive applications, compressing the addressable premium for legacy discrete photon-counting modules and forcing vendor portfolio recalibration.
For Market Incumbents: To counter direct-ToF SPAD array cost compression from 3x to 1.5x premiums within a single design generation, tier-one vendors should accelerate backward integration into multi-junction VCSEL epitaxy and deepen factory calibration service offerings. Captive MEMS foundry capacity remains the priority lever for sustaining cost leadership against fabless DSP specialists. For New Entrants and Emerging Players: Digital-channel routes through cloud-based calibration-as-a-service platforms offer the fastest penetration path. White-space targets concentrate in India PLI scheme corridors for domestic smartphone assembly and medical imaging CE marking pathways under EU MDR. The most penetrable segment spans surgical navigation and patient monitoring applications lacking incumbent depth-sensing integration. For Investors and Strategic Acquirers: Exit pathways concentrate in automotive tier-1 subsystem acquisitions and programmable DSP architecture licensing deals. Long-term viability over a five-to-ten year window favors vendors with software-defined calibration layers and recurring revenue streams. The signal to watch is NHTSA testing protocol migration from camera-based systems toward depth-sensor architectures.| Strategic Initiative | Industry Significance |
|---|---|
| MEMS Foundry Integration | Captive fabrication of emitter-receiver arrays locks in cost advantages against fabless competitors. |
| Automotive ASIL-D Certification | ISO 26262 qualification opens certified socket demand from EU AI Act compliance mandates. |
| Software-Defined Calibration | Programmable DSP architectures enable post-deployment algorithm re-tuning for recurring revenue. |
| III-V Epitaxy Backward Integration | Multi-junction VCSEL production reduces single-source exposure to Taiwanese foundry concentration. |
| Medical Imaging CE Marking | EU MDR compliance opens surgical navigation and patient monitoring application sockets. |
Research Methodology
Document review covered SEC filings, MIIT frequency allocation records, and EU MDR technical documentation, complemented by interviews with automotive tier-1 procurement directors, MEMS foundry operations managers, robotics OEM system architects, and compound semiconductor epitaxy specialists. Secondary validation drew from NHTSA testing protocol disclosures, KBA type-approval databases, and METI standards publications. Bottom-up module shipment estimates triangulated against top-down automotive production and smartphone assembly forecasts.
Cross-referencing historical VCSEL cost curves with expert panel input on silicon photonics integration timelines shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, application context, technology maturity tier, and end-user specification rigor. CAGRs derived from slope-consistency checks against automotive content-per-vehicle trajectories and consumer electronics upgrade cycle compression. Industry-specific forecast inputs incorporated EU AI Act implementation pacing and China EV production cluster expansion.
The model holds under stable III-V semiconductor foundry capacity and REACH restriction timelines; deviation in indium phosphide substitution acceleration or FCC Part 15 power ceiling adjustments would shift automotive lidar adoption curves. Forecasts reflect documented assumptions on solid-state scanning substitution rates and tier-1 supplier consolidation patterns. A model refresh is warranted upon material change in automotive functional-safety certification migration timelines or MIIT frequency allocation rule revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Communication Chips & Hardware
Data Transmission Module Market
Communication Chips & Hardware
Mixed Signal System-On-Chip (Mxsoc) Market
Communication Chips & Hardware
Smart TV Chip Market
Communication Chips & Hardware
GNSS Chip Market
Communication Chips & Hardware
VR Device Chips Market
Communication Chips & Hardware
Global Narrowband IoT (NB IoT) Chipset Market
Communication Chips & Hardware
Global Wireless Gigabit Market
Communication Chips & Hardware
Global Network Processing Unit (NPU) Market
Communication Chips & Hardware
Earphone Bluetooth Chip Market
Communication Chips & Hardware
Wifi Chip Market
Communication Chips & Hardware
Intelligent Cockpit Chip Market
Communication Chips & Hardware
I2C Bus Market
Communication Chips & Hardware
Transceiver Chip Market
Communication Chips & Hardware
Interface Transceiver Market
Communication Chips & Hardware
Communication Standard Logic IC Market
Communication Chips & Hardware
Ethernet PHY Chip Market