
 Wireless Access Point Market | 2026-2036
Wireless Access Point Market Size, Share, and Industry Trends Forecast 2026-2036
Wireless Access Point Market Outlook
Enterprise campus networking is restructuring how organizations evaluate wireless infrastructure, shifting procurement criteria from coverage density to latency-sensitive application support. Cisco Systems leverages its Meraki cloud platform to anchor mid-market deployments, while HPE Aruba Networks competes through integrated security fabric positioning. Ubiquiti Networks specializes in cost-optimized distributed architectures for hospitality and education verticals.
A wireless access point functions as a network device that bridges wireless client devices to a wired local area network, typically operating across 2.4 GHz, 5 GHz, and 6 GHz radio bands with throughput specifications now routinely exceeding 5 Gbps in enterprise-grade hardware. Indoor access points dominate installed volume but face margin compression as cloud-based deployment models capture higher recurring revenue streams. Mesh access points represent the fastest-growing product configuration for multi-dwelling units and extended outdoor coverage scenarios.
The FCC's 6 GHz spectrum rules in the United States, combined with ETSI harmonization efforts across European member states and China's MIIT radio type approval requirements, collectively determine which frequency bands and power levels manufacturers must support for market access. These regulatory frameworks directly shape chipset roadmaps and regional SKU strategies. Stakeholders must monitor spectrum auction outcomes and certification timelines to align product development with addressable market expansion.
Market Dynamics
Enterprise procurement criteria are pivoting from coverage density metrics to latency-sensitive application support, driven by the convergence of Wi-Fi 6E/7 hardware capabilities and spectrum reallocation across major economies.
Growth Catalysts
- 6 GHz Spectrum Liberation:The FCC's 2020 rules opening 1,200 MHz of contiguous spectrum in the United States eliminated channel congestion bottlenecks, enabling 320 MHz channel bonding for high-throughput enterprise use cases.
- Smart Manufacturing Corridors:China's MIIT radio type approval requirements for industrial wireless are mandating deterministic latency specifications, pulling infrastructure upgrades across automotive and electronics assembly clusters.
- Cloud-Native Management Platforms:Meraki-style dashboard architectures are absorbing mid-market procurement budgets previously allocated to on-premises controllers, compressing deployment timelines from weeks to hours.
Market Restraints
- Chipset Supply Concentration:Advanced Wi-Fi 7 radio frequency front-end modules depend on a concentrated supplier base in Taiwan, creating exposure to geopolitical friction and foundry allocation constraints.
- Power Amplifier Cost Volatility:Gallium nitride substrate prices for high-efficiency 6 GHz power stages have experienced input cost swings tied to rare earth processing capacity in China's Inner Mongolia processing zones.
- Legacy 2.4 GHz Interference:Co-channel saturation from unlicensed IoT devices and microwave ovens continues degrading effective throughput in dense residential and hospitality deployments, limiting spectral efficiency claims.
Strategic Opportunities
- India Commercial Real Estate Hubs:Bengaluru and Mumbai's Grade A office stock expansion is generating greenfield deployment demand for mesh-configured outdoor access points in mixed-use developments.
- Private 5G Convergence:Enterprises are piloting hybrid architectures where Wi-Fi 7 access points absorb traffic handoffs from localized 5G small cells, creating unified policy enforcement layers.
- EU Radio Equipment Directive Harmonization:ETSI's 6 GHz power-level alignment across member states is reducing SKU fragmentation, enabling pan-European product platforms that capture scale economies.
Industry Challenges
- RF Engineering Talent Scarcity:Enterprise IT departments lack personnel trained in 6 GHz propagation modeling and automated radio resource management configuration.
- Multi-Vendor Interoperability Certification:Wi-Fi Alliance's Wi-Fi 7 certification timelines lag hardware availability, forcing premature deployments on draft standards with backward-compatibility risks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wireless Access Point Market |
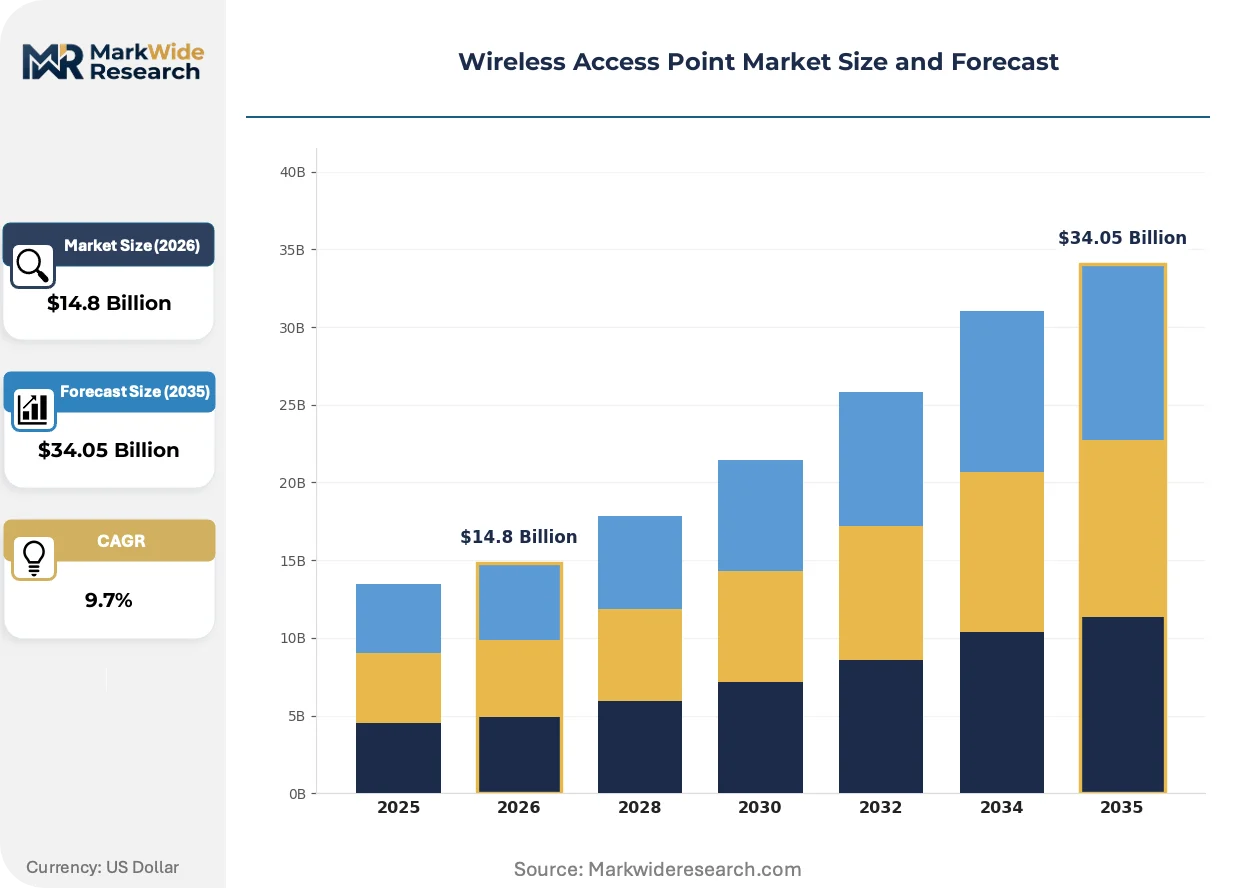
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $34.05 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Indoor Access Points, Outdoor Access Points, Mesh Access Points, PoE Access Points Deployment Model: On-Premises, Cloud-Based, Hybrid, Distributed Channel Type: Retail, E-Commerce, Direct Sales, Value-Added Resellers End User: Enterprise, Education, Hospitality, Healthcare |
| Companies Covered | Cisco Systems, HPE Aruba Networks, Ubiquiti Networks, CommScope Ruckus Wireless, Juniper Networks, Fortinet, TP-Link, Netgear, Extreme Networks, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wireless Access Point Market Strategic Shifts
Radio frequency engineering and cloud orchestration are converging to redefine how wireless infrastructure is deployed, monitored, and monetized across enterprise environments.
Multi-user multiple-input multiple-output technology is absorbing spatial stream allocation from legacy single-user architectures, enabling simultaneous high-definition video streaming to hundreds of client devices in stadium and convention center deployments. Higher education institutions with dense lecture hall environments are adopting 16-stream configurations at accelerated refresh cycles. This density capability is compressing the per-seat infrastructure cost calculus for venue operators.
ETSI's harmonization of 6 GHz standard power access point rules across European member states is eliminating the fragmented national exemptions that previously forced market-specific firmware loads. Industrial facilities in Germany's Ruhr manufacturing belt are deploying outdoor-rated standard power units for yard logistics automation. The unified regulatory framework is enabling vendors to consolidate regional product variants into single stock-keeping units.
Subscription-based licensing for cloud-managed access points is displacing perpetual ownership models in North American mid-market hospitality chains. Franchise operators are trading capital expenditure for operational expenditure structures that bundle hardware refreshes into monthly fees. This financing preference rotation is most visible in limited-service hotel portfolios across Texas and Florida where property-level IT staffing remains minimal.
Wireless Access Point Market Segmentation
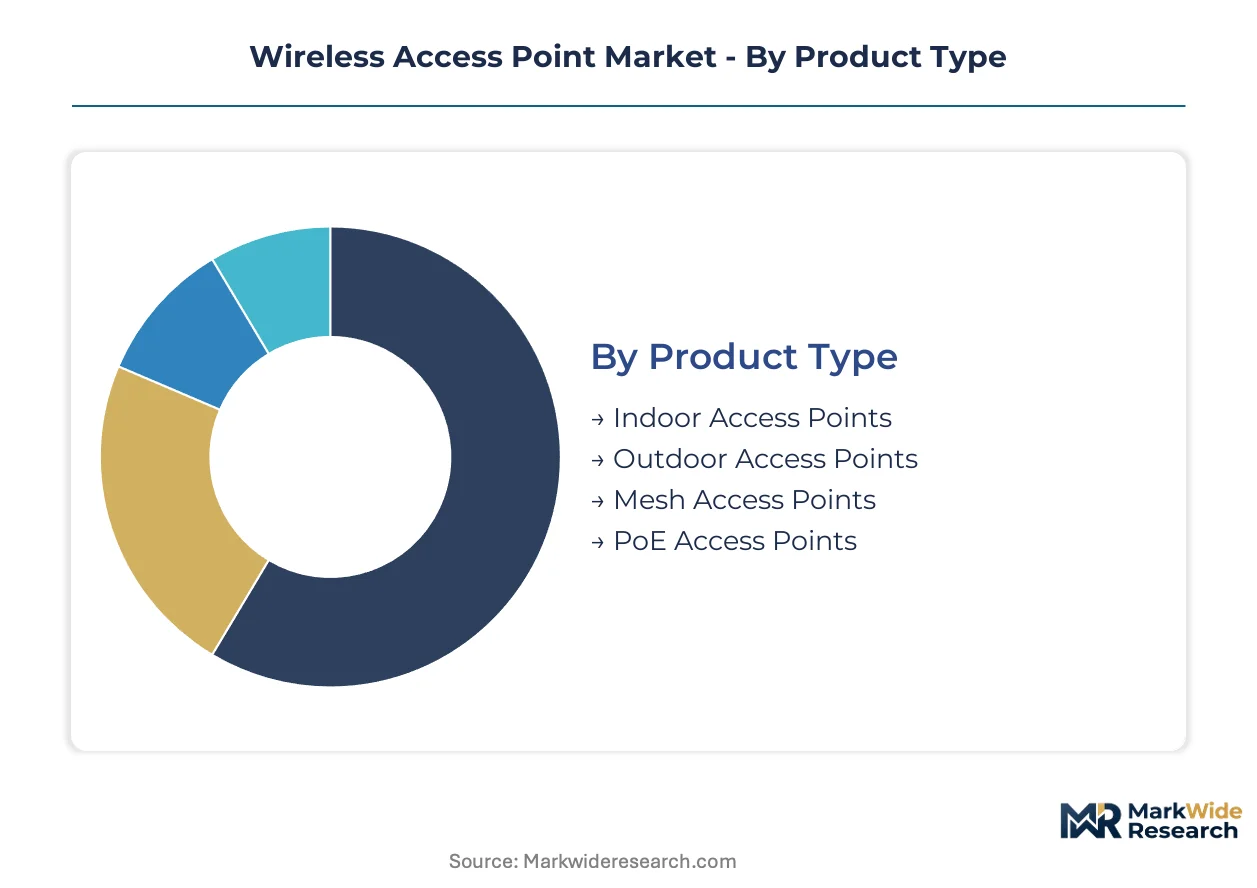
Wireless access point segmentation reveals how procurement criteria fragment across technical specifications, operational models, and vertical requirements. Understanding these divisions exposes where hardware refresh cycles concentrate and which configurations capture premium pricing.
Product Type:
Upgrade cycles vary sharply by mounting environment and power architecture, with indoor units facing compressed margins while outdoor and mesh configurations retain pricing power through weatherproofing complexity.
- Indoor Access Points:Wall- or ceiling-mounted units with integrated antennas dominate enterprise campus deployments. China's smart manufacturing corridors and India's commercial real estate hubs are absorbing volume for 2.4 GHz/5 GHz/6 GHz tri-band hardware as FCC spectrum rules accelerate 6 GHz refreshes.
- Outdoor Access Points:IP67-rated enclosures with directional antenna arrays withstand temperature extremes and moisture ingress. Demand clusters in mixed-use developments across Bengaluru and Mumbai where mesh-configured outdoor units enable campus-wide coverage without trenching for fiber backhaul.
- Mesh Access Points:Self-organizing multi-hop configurations eliminate cabling requirements in historic buildings and temporary venues. Hospitality chains in Texas and Florida deploy these for rapid property onboarding with minimal IT staffing.
- PoE Access Points:IEEE 802.3bt-powered units draw up to 90W over Ethernet cabling, simplifying installation where AC outlets are scarce. Education institutions favor these for lecture hall retrofits avoiding electrical contractor costs.
Volume placements concentrate in Indoor Access Points; the faster expansion belongs to Mesh Access Points.
Deployment Model:
Operational expenditure preferences are restructuring how organizations balance control against agility, with cloud-native architectures capturing mid-market budgets previously reserved for on-premises controllers.
- On-Premises:Dedicated hardware controllers manage radio resource allocation and client authentication within facility boundaries. Financial services and defense contractors in Germany's Ruhr belt retain these for air-gapped security compliance.
- Cloud-Based:Dashboard-managed access points stream telemetry to vendor-hosted platforms, compressing deployment timelines from weeks to hours. North American hospitality franchises increasingly specify these for operational expenditure treatment.
- Hybrid:Local controllers handle latency-sensitive traffic while cloud portals manage policy and analytics. Enterprises piloting private 5G convergence favor this architecture for unified handoff management.
- Distributed:Controller-less architectures embed intelligence in each access point for peer-to-peer coordination. Cost-optimized education and hospitality verticals deploy these across geographically scattered sites.
Cloud-Based deployments are climbing the fastest as mid-market procurement shifts toward subscription financing; Hybrid architectures gain share among convergence pilots.
Channel Type:
Route-to-market selection reflects buyer technical sophistication and project scale, with direct relationships dominating complex enterprise refreshes while self-service channels capture standardized configurations.
- Retail:Big-box electronics and office supply chains stock consumer-grade units for small office and residential installations. Volume concentrates in suburban markets with limited IT contractor penetration.
- E-Commerce:Online marketplaces enable specification comparison and rapid procurement for standardized enterprise SKUs. Education institutions with centralized purchasing leverage these for multi-site rollouts.
- Direct Sales:Vendor field teams engineer custom coverage designs and negotiate enterprise licensing terms. Healthcare systems with 24/7 uptime requirements rely on these relationships for SLA-backed implementations.
- Value-Added Resellers:Systems integrators bundle access points with cabling, switching, and security appliances. Regional VARs in China's industrial corridors specialize in MIIT-compliant industrial wireless deployments.
Value-Added Resellers capture the steepest expansion trajectory in industrial verticals; Direct Sales retains pricing power in healthcare.
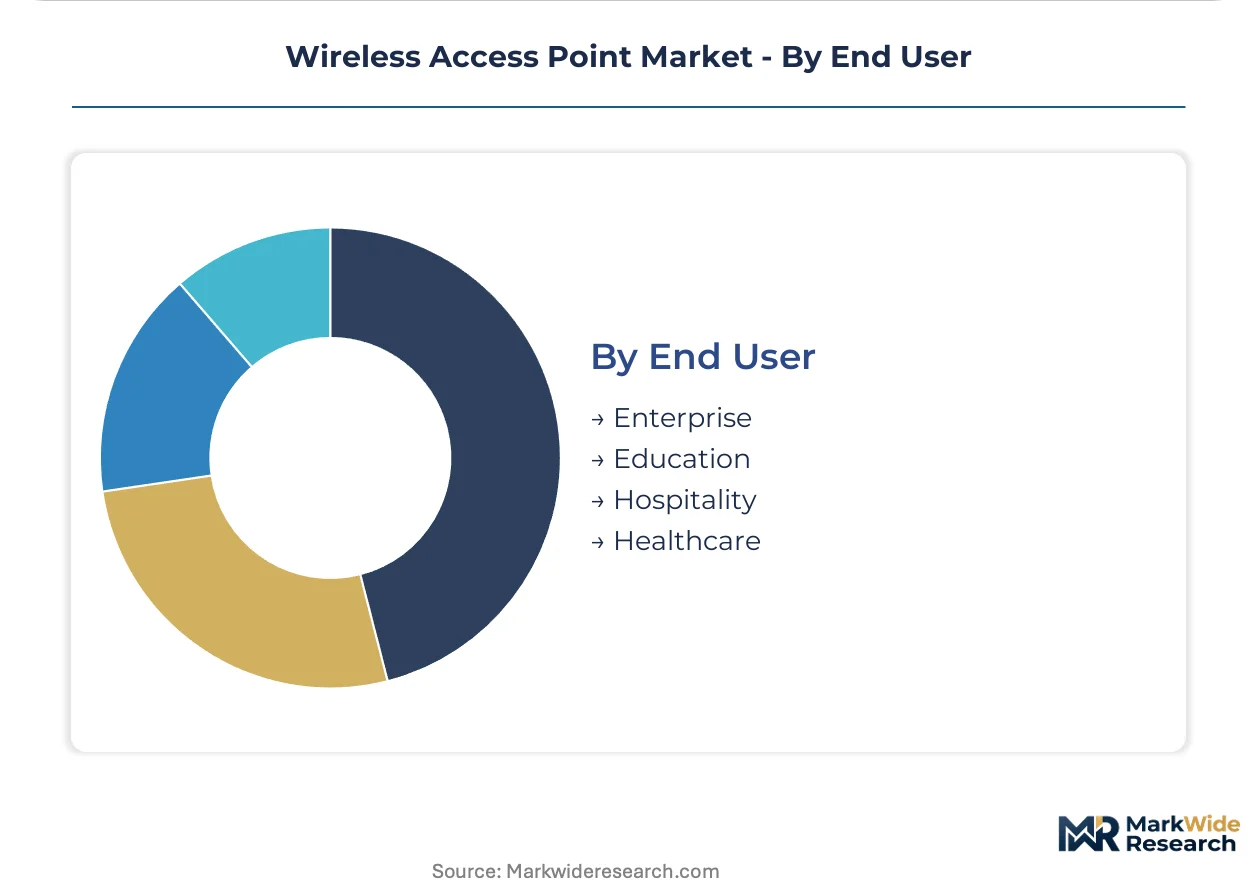
End User:
Vertical-specific latency and density requirements are fragmenting product specifications, with education and hospitality prioritizing cost optimization while healthcare and enterprise emphasize deterministic performance.
- Enterprise:Campus networks supporting voice, video, and IoT convergence specify Wi-Fi 6E/7 hardware with 320 MHz channel bonding. Automotive and electronics assembly clusters in China mandate deterministic latency for automated guided vehicle coordination.
- Education:Dense lecture halls and dormitories drive 16-stream MU-MIMO configurations at compressed refresh cycles. Higher education institutions prioritize per-seat infrastructure cost reduction over premium feature sets.
- Hospitality:Franchise operators favor cloud-managed, subscription-licensed deployments minimizing property-level IT overhead. Limited-service hotel portfolios across Texas and Florida represent concentrated demand for operational expenditure structures.
- Healthcare:Medical device connectivity and electronic health record access require continuous availability and interference resilience. HIPAA-covered entities specify hardware with dedicated radio monitoring for co-channel saturation mitigation.
Enterprise placements dominate absolute volume; Hospitality is expanding most quickly through franchise operational expenditure conversion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen's Qianhai Special Economic Zone concentrates contract manufacturing for radio frequency modules serving global access point brands, while Bengaluru's Electronics City SEZ anchors software-defined networking development for cloud-managed deployments.
United States
Enterprise campus refreshes and smart manufacturing adoption drive hardware procurement across automotive and electronics assembly clusters. FCC spectrum allocation decisions for the 6 GHz band determine which channel bonding configurations manufacturers certify for market entry. Austin and Raleigh-Durham host dense concentrations of cloud-native networking startups competing against established infrastructure vendors.
China
MIIT radio type approval requirements for industrial wireless mandate deterministic latency specifications across automotive and electronics assembly corridors. The country's dual carbon goals push power efficiency requirements into access point procurement criteria for state-owned enterprise campuses. Guangdong and Jiangsu provinces concentrate export-oriented manufacturing while Beijing anchors headquarters operations for domestic networking champions.
Germany
Ruhr manufacturing belt facilities deploy outdoor-rated standard power units for yard logistics automation requiring continuous connectivity. ETSI harmonization of 6 GHz power-level rules enables unified product platforms across European member states reducing SKU fragmentation. Munich and Stuttgart host automotive OEM headquarters driving private 5G and Wi-Fi 7 convergence pilots.
India
Bengaluru and Mumbai Grade A office stock expansion generates greenfield demand for mesh-configured outdoor access points in mixed-use developments. TRAI spectrum management consultations influence enterprise expectations for unlicensed band availability in commercial real estate. Hyderabad's HITEC City corridor concentrates technology campus deployments with centralized IT procurement favoring cloud-managed operational expenditure models.
Japan
Meti's industrial digitalization subsidies accelerate Wi-Fi 6E refreshes across precision manufacturing facilities requiring low-latency machine coordination. JIS standards for electromagnetic compatibility shape certification requirements for enterprise-grade hardware imports. Osaka and Nagoya industrial corridors concentrate demand from automotive and robotics manufacturers upgrading legacy 802.11ac infrastructure.
Wireless Access Point Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with cloud-native platforms capturing mid-market budgets while on-premises controllers retain financial services and defense accounts. The vendor base organizes into three archetypes: silicon-integrated platform providers, security-centric converged infrastructure vendors, and cost-optimized distributed architecture specialists. Consolidation pressure operates through strategic partnerships for radio frequency front-end supply and geographic expansion via value-added reseller channel development.
Within the cloud-native tier, Cisco Systems and HPE Aruba Networks exemplify platform-centric positioning, while Ubiquiti Networks occupies a distinct position among cost-optimized distributed architecture specialists. These three anchors represent divergent strategic bets on how enterprise procurement criteria evolve between integrated security fabric requirements and operational expenditure minimization.
| Leading Market Players |
|---|
| Cisco Systems |
| HPE Aruba Networks |
| Ubiquiti Networks |
| CommScope Ruckus Wireless |
| Juniper Networks |
| Fortinet |
| TP-Link |
| Netgear |
| Extreme Networks |
| Others |
Value Chain & Pricing Dynamics
Gallium nitride substrate costs for 6 GHz power amplifier stages cascade through three pricing tiers, with rare earth processing capacity in China's Inner Mongolia zones compressing margins at the standard-power tier while premium Wi-Fi 7 enterprise hardware retains pricing power through FCC certification scarcity.
Pricing Analysis
Lead-time premiums of six to eight weeks separate cloud-managed subscription tiers from spot-inventory transactional pricing. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with FCC 6 GHz standard-power units commanding brand premiums over draft-standard hardware. Pricing pressure stems from gallium nitride input cost volatility tied to rare earth processing constraints. Franchise hospitality operators in North American mid-markets exhibit highest price sensitivity, while defense contractors in Germany's Ruhr belt accept premium positioning for air-gapped security compliance.
Supply Chain Analysis
MIIT radio type approval requirements in China and ETSI harmonization mandates across European member states are reshaping sourcing footprints, pushing contract manufacturers toward dual-facility strategies. Radio frequency front-end module production concentrates in Taiwan, South Korea, and Malaysia, drawing from gallium nitride substrates, silicon carbide wafers, and advanced packaging substrates. Single-source vulnerability around Taiwan foundry allocation creates exposure to geopolitical friction. Distribution runs through value-added resellers in industrial corridors and direct sales for healthcare SLA requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Foundry allocation constraints for Wi-Fi 7 radio frequency front-end modules prop pricing power, with Taiwan semiconductor capacity serving as the binding bottleneck sustaining margin structures across enterprise tiers.
For Market Incumbents: Deepen captive supply relationships for gallium nitride substrates through backward integration into rare earth processing partnerships, while accelerating ETSI pre-certification investments to compress European SKU fragmentation ahead of MIIT harmonization deadlines. Cloud-native platform competition from Meraki-architecture specialists threatens mid-market subscription retention. For New Entrants and Emerging Players: Enter via India's Grade A commercial real estate expansion in Bengaluru and Mumbai, where mesh-configured outdoor access points face limited incumbent saturation and cloud-managed operational expenditure models remain underpenetrated. Target education verticals in Texas and Florida through distributed controller-less architectures minimizing property-level IT overhead. For Investors and Strategic Acquirers: FCC 6 GHz spectrum auction completion timelines are the leading indicator that hardware refresh acceleration will concentrate procurement budgets toward certified Wi-Fi 7 platforms. Over a five-to-ten-year horizon, acquisition targets should emphasize RF engineering talent pools with 6 GHz propagation modeling capabilities and existing MIIT type approval portfolios.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Platform Integration | Meraki-style dashboard architectures absorb mid-market budgets previously allocated to on-premises controllers. |
| RF Front-End Supply Agreement | Gallium nitride substrate partnerships with Inner Mongolia processing zones secure 6 GHz power stage allocation. |
| ETSI Pre-Certification Investment | Harmonized standard power rules across European member states reduce firmware fragmentation into single SKUs. |
| Private 5G Convergence Pilot | Hybrid Wi-Fi 7 and small cell architectures create unified policy enforcement layers for automotive OEMs. |
| India Channel Development | Value-added reseller relationships in Bengaluru and Mumbai corridors capture greenfield commercial real estate demand. |
Study Parameters
SEC 10-K filings, FCC equipment authorization databases, and ETSI harmonization documentation formed the secondary backbone, supplemented by primary interviews with enterprise IT procurement officers, RF engineering directors at contract manufacturers, and value-added reseller principals in China's industrial corridors. Bottom-up volume estimates triangulated against top-down spectrum allocation forecasts across the analysis window.
Historical trendline analysis for Wi-Fi 6E/7 hardware refresh cycles anchored the projection framework, with segmentation across deployment model, end-user vertical, and regional regulatory cluster driving CAGR derivation. Inputs included MIIT type approval timelines, TRAI spectrum consultation outcomes, and cloud-managed subscription adoption trajectories in North American hospitality.
Forecast precision tightens around the base case; tail outcomes carry wider variance under Taiwan foundry allocation disruptions or gallium nitride supply shocks. Forecasts reflect assumptions around ETSI harmonization completion and MIIT industrial wireless latency mandates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wireless Technologies
Wireless Paging Systems Market
Wireless Technologies
5G Small Cell Market
Wireless Technologies
Multefire Market
Wireless Technologies
Wireless USB (WUSB) Devices Market
Wireless Technologies
Wireless LAN Controller Market
Wireless Technologies
Wireless Smart Home Market
Wireless Technologies
P2P Antennas Market
Wireless Technologies
Base Transceiver Station (BTS) Market
Wireless Technologies
Asia-Pacific Distributed Antenna System Market
Wireless Technologies
Global Wireless Data Communication Market
Wireless Technologies
Latin America Wireless Mesh Networking Market
Wireless Technologies
Wireless Intercoms Market
Wireless Technologies
Mobile Signal Booster Market
Wireless Technologies
Underwater Wireless Communication Market
Wireless Technologies
Global Bluetooth Beacon and Ibeacon Market
Wireless Technologies
Telecom Millimeter Wave (MMW) Technology Market