
 Wireless Antenna Market | 2026-2036
Wireless Antenna Market Size, Share, and Industry Trends Forecast 2026-2036
Wireless Antenna Market Outlook
Southeast Asia is rewriting supply chain maps for passive antenna components as Vietnam and Thailand expand substrate manufacturing parks. Huawei Technologies leverages captive semiconductor foundry partnerships to shield its Massive MIMO portfolio from external supply shocks. Amphenol Corporation anchors North American aerospace and defense antenna demand through long-term qualification programs with prime contractors. CommScope Holding Company competes in small cell densification by extending its fiber-to-the-antenna integration capabilities into street-level deployments.
A wireless antenna is a transducer that converts electrical radio frequency signals into electromagnetic waves and vice versa, typically engineered with precise impedance matching, gain specifications measured in dBi, and polarization control to optimize radiation patterns for specific coverage geometries. Its primary commercial purpose is enabling reliable over-the-air connectivity across fixed, mobile, and satellite communication systems. Omnidirectional antennas dominate indoor enterprise Wi-Fi deployments where uniform horizontal coverage matters more than range, while directional and panel variants capture margin pools in point-to-point backhaul and stadium venues where beam steering justifies premium positioning. 5G technology segments are displacing legacy LTE attachment rates in telecom infrastructure, though LTE persists in IoT and rural broadband applications where capital constraints favor proven hardware economics.
FCC Part 15 rules in the United States and the EU Radio Equipment Directive constrain transmit power, spurious emissions, and interoperability testing, forcing antenna vendors to maintain parallel certification laboratories in both jurisdictions. China's MIIT issues network access licenses that tie antenna approvals to specific base station configurations, creating a regulatory moat for domestic suppliers like Huawei and Sunway Communication. India's WPC and TEC certification requirements add procedural friction for imported active antenna systems, favoring local assembly partnerships. Stakeholders must monitor spectrum reallocation decisions across these three regulatory spheres, as mid-band and mmWave rule changes will cascade through antenna gain requirements, form factor standards, and filter integration complexity faster than typical product development cycles can absorb.
Market Dynamics
Base station densification programs are compressing procurement cycles for Massive MIMO arrays while FCC spectrum reallocations and EU Radio Equipment Directive compliance deadlines force parallel certification investments. This structural tension between deployment velocity and regulatory fragmentation defines competitive positioning.
Growth Catalysts
- 5G Infrastructure Buildouts:Telecom providers in China are accelerating urban corridor deployments, creating sustained demand for high-gain antenna systems with beam-steering capabilities.
- FCC Spectrum Auctions:Mid-band and mmWave license releases in the United States are mandating new antenna form factors with integrated filtering.
- Substrate Manufacturing Parks:Vietnam and Thailand are expanding passive component fabrication capacity, shortening lead times for printed circuit board assemblies.
Market Restraints
- Semiconductor Supply Concentration:Captive foundry partnerships in East Asia create vulnerability for non-integrated antenna vendors seeking gallium nitride power amplifiers.
- MIIT Network Access Licensing:China's equipment-type approval process ties antenna certifications to specific base station configurations, extending time-to-market for foreign suppliers.
- Legacy LTE Hardware Economics:Rural broadband and IoT deployments favor proven antenna designs over 5G upgrades where capital constraints persist.
Strategic Opportunities
- India Local Assembly Partnerships:WPC and TEC certification requirements favor domestic manufacturing joint ventures for active antenna systems.
- Street-Level Small Cell Integration:Fiber-to-the-antenna capabilities extended into municipal infrastructure create new procurement channels.
- Aerospace Qualification Programs:Long-term defense contractor relationships in North America lock in specialized antenna demand with multi-year visibility.
Industry Challenges
- Parallel Certification Laboratories:Maintaining FCC Part 15 and EU Radio Equipment Directive testing capabilities strains mid-tier engineering budgets.
- Beamforming Algorithm Integration:Active antenna systems require software-hardware co-development skills scarce in traditional passive antenna engineering teams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wireless Antenna Market |
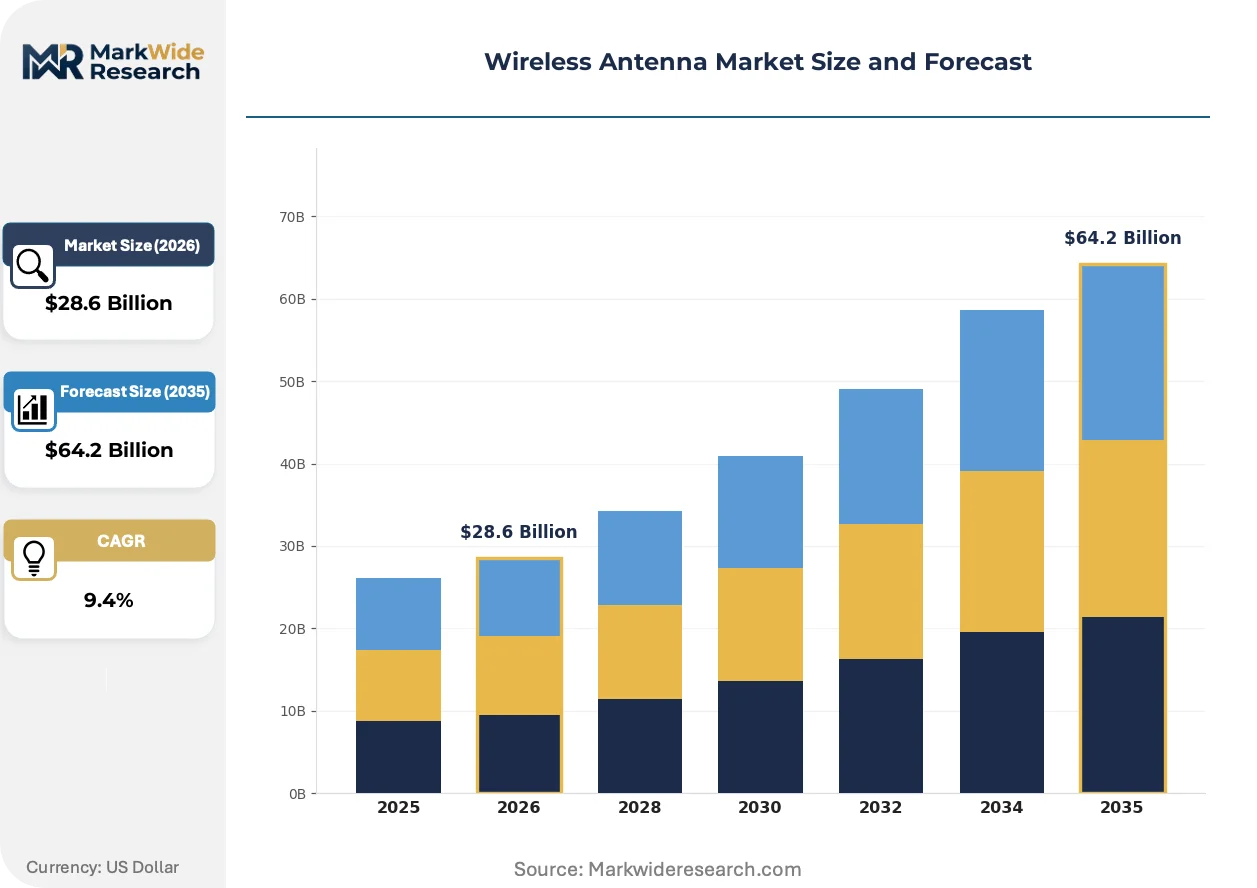
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $64.2 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Omnidirectional, Directional, Panel, Yagi Application: Telecommunications, Military, Automotive, IoT Technology: 5G, LTE, Wi-Fi, Satellite End User: Telecom Providers, Government, Enterprises, Consumer Electronics |
| Companies Covered | Huawei Technologies, Amphenol Corporation, CommScope Holding Company, Airgain, Molex, Cisco Systems, Ericsson, Taoglas, Sunway Communication, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wireless Antenna Market Strategic Shifts
Antenna architectures are converging with semiconductor and software layers, collapsing traditional boundaries between hardware suppliers and system integrators. This integration is compressing value chain margins while opening new performance tiers.
Integrated active antenna units with embedded radio frequency front-ends are collapsing the distinction between antenna and transceiver hardware. Telecom infrastructure buyers in China and South Korea are specifying these combined modules for 5G base stations. This convergence is collapsing procurement categories, forcing pure-play antenna vendors to develop semiconductor partnerships or exit the high-performance segment entirely.
The EU Radio Equipment Directive's 2024 cybersecurity and interoperability amendments are mandating encrypted firmware update mechanisms for network-connected antennas. Industrial consequence includes extended validation timelines and third-party penetration testing costs. Infrastructure vendors serving European mobile operators are responding by pre-integrating security modules from specialized semiconductor suppliers rather than developing proprietary solutions.
Enterprise Wi-Fi buyers are compressing vendor evaluation cycles from eighteen months to under six months, prioritizing cloud-managed antenna systems with automated RF optimization. Value-added distributors are displacing direct OEM relationships in mid-market procurement. This behavioral shift is most visible in United States healthcare and education verticals where IT staffing constraints favor fully managed connectivity subscriptions over capital equipment purchases.
Wireless Antenna Market Segmentation
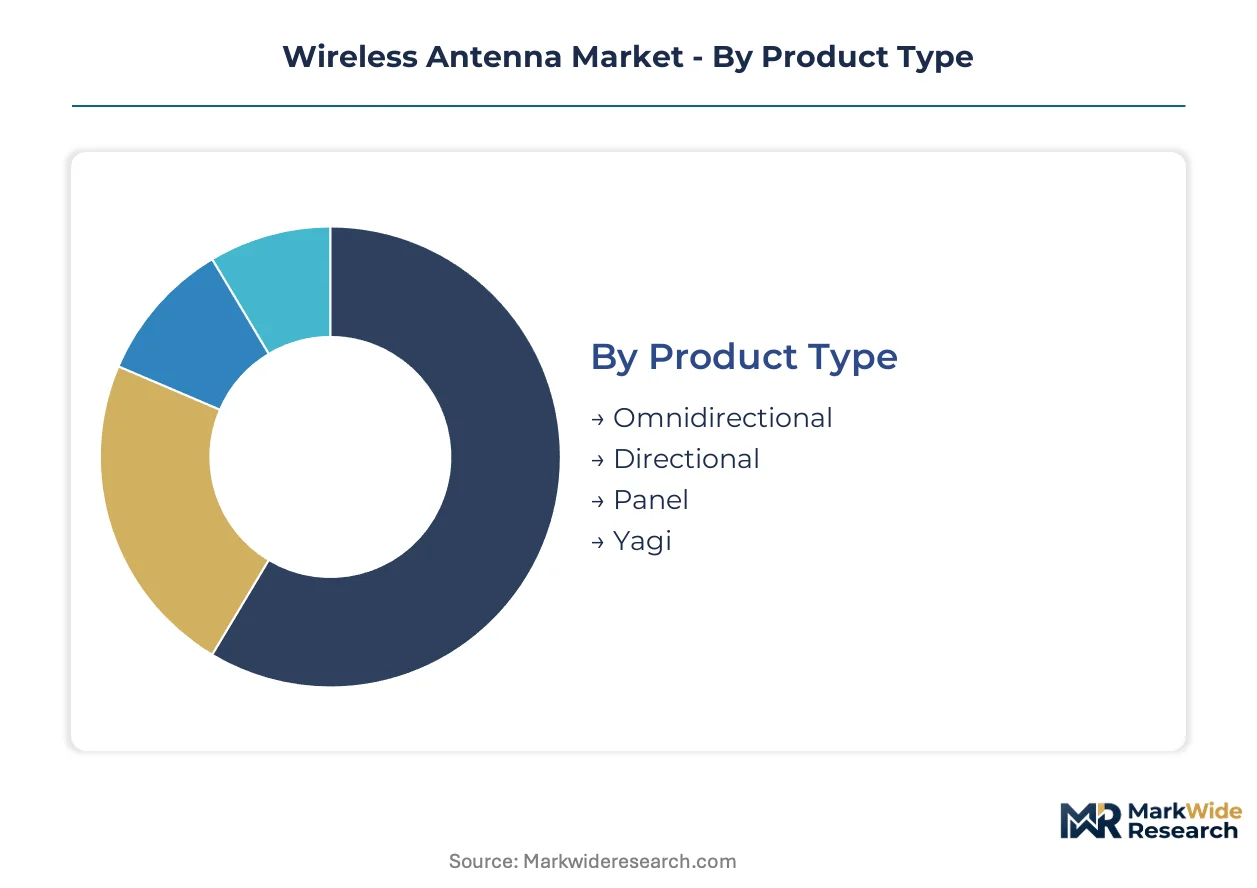
Antenna procurement patterns diverge sharply across installation environments and performance requirements. Service intensity varies from passive hardware replacement cycles to active systems demanding continuous firmware calibration and field optimization.
Product Type:
After-sales service intensity escalates dramatically from passive omnidirectional units to beam-steering directional arrays requiring remote diagnostics and field technician dispatch.
- Omnidirectional:These antennas radiate signal uniformly across horizontal planes with simple dipole or collinear element configurations. Enterprise Wi-Fi deployments in United States healthcare campuses and education facilities favor cloud-managed omnidirectional units where IT staffing shortages drive demand for automated RF optimization subscriptions.
- Directional:Parabolic and horn designs concentrate radiation into narrow beams for point-to-point backhaul links. Telecom infrastructure buyers in China specify high-gain directional arrays for 5G fronthaul corridors where beam alignment precision determines link stability and service call frequency.
- Panel:Flat planar arrays with microstrip patch elements serve sectorized coverage zones in stadium and venue deployments.
- Yagi:Log-periodic and folded dipole configurations persist in rural broadband and amateur radio applications where legacy hardware economics dominate procurement decisions.
Directional systems command the largest revenue share; momentum sits with panel arrays gaining traction in dense urban small cell deployments.
Application:
Cost tier stratification separates commodity IoT attachment modules from military-grade qualification programs spanning multi-year development cycles.
- Telecommunications:Base station and small cell infrastructure demands active antenna units with embedded RF front-ends. Massive MIMO procurement in China and South Korea is collapsing traditional distinctions between antenna and transceiver hardware, forcing suppliers to develop semiconductor partnerships or exit high-performance segments entirely.
- Military:Aerospace and defense programs require specialized form factors surviving extreme environmental stressors. Amphenol Corporation anchors North American demand through long-term qualification relationships with prime contractors, locking in multi-year visibility absent in commercial markets.
- Automotive:Connected vehicle platforms integrate shark-fin and glass-mounted antennas for cellular V2X communications.
- IoT:Low-power wide-area networks favor compact ceramic chip antennas with minimal gain requirements and replacement-driven service models.
Telecommunications generates the highest absolute revenue; automotive connectivity platforms are expanding most quickly as OEMs integrate 5G modems across vehicle tiers.
Technology:
Volume concentration shifts from mature LTE hardware toward 5G active antenna systems, though legacy attachment rates persist where capital constraints delay infrastructure refresh.
- 5G:Massive MIMO and beamforming architectures integrate semiconductor layers directly into antenna assemblies. FCC mid-band and mmWave spectrum releases mandate new form factors with integrated filtering, compressing procurement cycles for qualified suppliers.
- LTE:Proven hardware economics dominate rural broadband and industrial IoT deployments where total cost of ownership calculations favor extended equipment lifecycles over performance upgrades.
- Wi-Fi:Enterprise buyers compress vendor evaluation cycles from eighteen months to under six months, prioritizing cloud-managed systems with automated RF optimization over capital equipment purchases.
- Satellite:Flat-panel phased arrays for low-earth orbit constellations demand specialized manufacturing processes distinct from terrestrial cellular architectures.
LTE retains the largest installed base; 5G infrastructure is gaining share fastest as urban densification programs accelerate across China and South Korea.
End User:
Customer type determines procurement channel structure, from direct OEM relationships with telecom providers to distributor-mediated enterprise transactions.
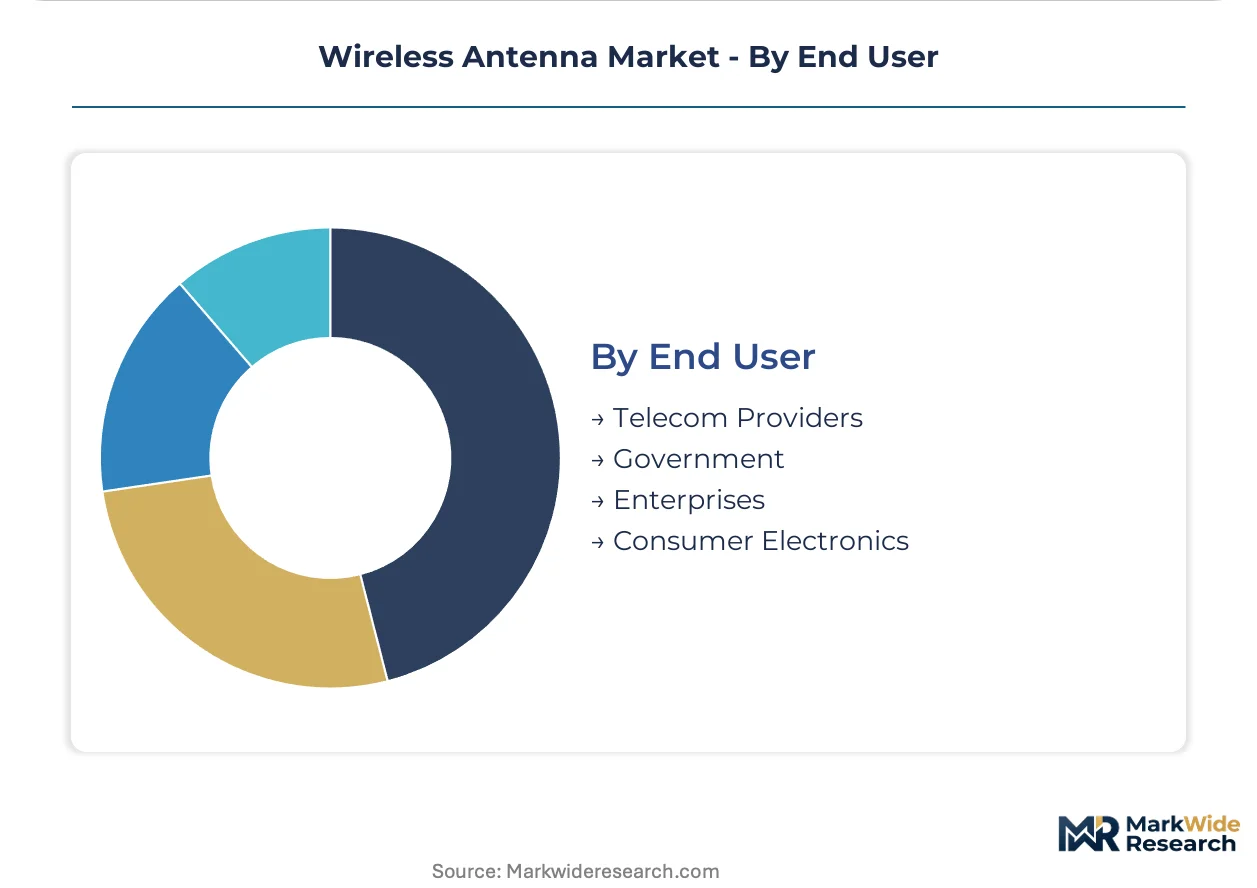
- Telecom Providers:Infrastructure buyers specify integrated active antenna units combining RF front-ends with radiating elements. China's MIIT network access licensing ties antenna approvals to specific base station configurations, creating regulatory moats favoring domestic suppliers.
- Government:Defense and public safety agencies mandate extended qualification timelines and traceability documentation incompatible with commercial product cycles.
- Enterprises:Healthcare and education verticals in the United States favor fully managed connectivity subscriptions over capital purchases, displacing direct OEM relationships with value-added distributors.
- Consumer Electronics:Smartphone and laptop manufacturers source compact multi-band antennas through consolidated Asian supply chains with minimal service attachment.
Telecom providers dominate procurement value; enterprise managed services represent the steepest expansion trajectory as IT staffing constraints deepen across mid-market organizations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China deploys Massive MIMO arrays for urban densification while the United States prioritizes small cell fiber-to-the-antenna integration; Germany and South Korea concentrate on automotive 5G connectivity platforms.
China
MIIT network access licensing ties antenna approvals to specific base station configurations, accelerating procurement for domestic suppliers. Base station densification programs in Beijing, Shanghai, and Shenzhen compress deployment cycles for active antenna units. Yangtze River Delta manufacturing clusters supply printed circuit board assemblies to telecom infrastructure builders.
United States
FCC mid-band and mmWave spectrum auctions mandate new antenna form factors with integrated filtering for urban corridors. Part 15 rules constrain transmit power and spurious emissions, forcing parallel certification investments. Texas and California data center corridors drive demand for high-gain directional arrays in fronthaul applications.
Germany
EU Radio Equipment Directive cybersecurity amendments mandate encrypted firmware mechanisms for network-connected antennas. Automotive OEMs in Bavaria and Baden-Württemberg integrate 5G modems across vehicle tiers, sourcing shark-fin and glass-mounted configurations. Industrial automation clusters in North Rhine-Westphalia deploy private 5G networks with specialized panel arrays.
South Korea
Telecom providers specify integrated active antenna units combining RF front-ends with radiating elements for Seoul metropolitan densification. MFDS equipment certification aligns with international standards while favoring domestic semiconductor integration. Busan-Ulsan manufacturing zones produce substrate materials for regional antenna assembly.
India
WPC and TEC certification requirements favor local assembly partnerships for active antenna systems over direct import channels. Rural broadband programs under BharatNet sustain LTE hardware economics where capital constraints delay 5G upgrades. Tamil Nadu and Karnataka electronics manufacturing clusters attract joint ventures for telecom component fabrication.
Wireless Antenna Market Competitive Environment
Capability concentration sits with semiconductor-integrated specialists; scale advantage sits with diversified connectivity conglomerates. The vendor base separates into three tiers: captive foundry operators shielding supply chains, qualification-heavy defense contractors, and distributor-mediated enterprise specialists. Dominant competitive moves include backward integration into gallium nitride power amplifier supply and geographic joint ventures to satisfy local content mandates.
Among East Asian technology conglomerates, Huawei Technologies exemplifies the captive supply chain archetype through foundry partnerships. Amphenol Corporation occupies a position within the North American aerospace and defense contractor tier. CommScope Holding Company represents the fiber-to-the-antenna integration specialist segment serving municipal infrastructure deployments.
| Leading Market Players |
|---|
| Huawei Technologies |
| Amphenol Corporation |
| CommScope Holding Company |
| Airgain |
| Molex |
| Cisco Systems |
| Ericsson |
| Taoglas |
| Sunway Communication |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in Vietnam and Thailand substrate manufacturing parks is compressing component lead times while forcing suppliers to absorb cost compression through volume commitments rather than price escalation. This utilization dynamic rewards buyers with procurement leverage in passive antenna assemblies while pressuring margins for non-integrated vendors competing on spot-market gallium nitride procurement.
Pricing Analysis
Long-term offtake agreements dominate telecom infrastructure procurement, with China's MIIT-licensed base station programs locking in multi-year active antenna supply contracts at fixed unit economics. Price differentiation separates FCC Part 15-certified premium tiers from economy-grade IoT attachment modules lacking spurious emissions testing. Cost compression in passive omnidirectional units is intensifying because substrate fabrication capacity expansion outstrips enterprise Wi-Fi deployment velocity. Small cell integrators exhibit highest price sensitivity due to municipal budget constraints, while aerospace qualification programs demonstrate lowest sensitivity given multi-year development timelines and traceability documentation requirements.
Supply Chain Analysis
Contract manufacturing concentration sits with Foxconn and Jabil EMS facilities in the Yangtze River Delta and Vietnam's Bac Ninh province for printed circuit board assembly and final antenna integration. Geographic supply concentration centers on China for Massive MIMO substrate fabrication, Taiwan for gallium nitride foundry capacity, and South Korea for RF front-end semiconductor packaging. Raw material dependencies draw from copper-clad laminates, ceramic dielectric substrates, and rare-earth magnetics for polarization control. Single-source vulnerability in gallium nitride power amplifier supply creates exposure for non-captive vendors. Distribution runs through value-added distributors in North American enterprise channels and direct OEM relationships with telecom providers in East Asia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The wireless antenna market is undergoing high-growth disruption as 5G beamforming architectures collapse traditional hardware boundaries, with FCC mid-band spectrum releases and EU cybersecurity mandates accelerating procurement cycle compression.
For Market Incumbents: Entrench semiconductor partnerships or captive foundry access to shield Massive MIMO portfolios from gallium nitride supply shocks. Extend fiber-to-the-antenna integration capabilities into municipal small cell infrastructure to lock in street-level deployment channels. The threat of integrated active antenna units displacing pure-play vendors demands backward integration into RF front-end design or exit from high-performance segments entirely. For New Entrants and Emerging Players: Establish a beachhead in India's WPC and TEC certification-compliant local assembly partnerships, where regulatory friction favors domestic manufacturing joint ventures over direct import channels. Target rural broadband LTE hardware replacement cycles where capital constraints delay 5G upgrades and proven antenna economics dominate procurement. Pursue cloud-managed Wi-Fi subscriptions in United States healthcare and education verticals, displacing direct OEM relationships with fully managed connectivity offerings. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among enterprise Wi-Fi distributors with automated RF optimization subscriptions, offering superior cash flow quality versus project-based telecom infrastructure sales. Long-term viability across the projection horizon favors vendors with MIIT network access licensing in China or FCC Part 15 certification laboratories in the United States. Monitor spectrum reallocation decisions in mid-band and mmWave as the signal indicating antenna gain requirement shifts and form factor standard changes.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Foundry Partnership | Huawei Technologies shields Massive MIMO supply from external gallium nitride shocks through integrated semiconductor access. |
| Fiber-to-the-Antenna Extension | CommScope Holding Company locks in municipal small cell procurement by integrating street-level fiber connectivity. |
| India Local Assembly Joint Venture | WPC and TEC compliance requirements favor domestic manufacturing partnerships over direct import channels. |
| EU Cybersecurity Pre-Integration | Radio Equipment Directive amendments force security module sourcing from specialized semiconductor suppliers. |
| Aerospace Qualification Program | Amphenol Corporation secures multi-year defense contractor visibility through long-term North American relationships. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of FCC equipment authorization databases, MIIT network access license filings, EU Radio Equipment Directive compliance registries, and telecom infrastructure procurement disclosures. Primary interviews engaged base station procurement directors at tier-1 operators, RF engineering leads at antenna OEMs, certification laboratory managers, and substrate manufacturing plant operators. Bottom-up triangulation across unit shipment estimates and top-down validation against disclosed infrastructure capex aggregates cross-check volume assumptions.
Forecast inputs incorporate base station densification program timelines, spectrum auction release schedules, and substrate manufacturing capacity utilization trajectories across the modeling period. Segmentation dimensions span product architecture, application environment, technology generation, and end-user procurement channel. CAGRs derive from logistic adoption curves fitted to infrastructure deployment velocity and replacement cycle compression. Industry-specific inputs include MIIT license issuance rates and FCC Part 15 certification throughput as leading indicators of qualified supply availability.
Sensitivities concentrate around spectrum reallocation decisions, gallium nitride foundry capacity constraints, and cybersecurity regulatory amendments that compress product development cycles. Forecasts reflect assumptions on infrastructure investment continuity and semiconductor supply normalization without guarantee of realization. Quarterly review of MIIT license issuance, FCC equipment authorization throughput, and substrate manufacturing capacity utilization is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wireless Technologies
Global Wireless Data Communication Market
Wireless Technologies
Mobile WLAN Access Points Market
Wireless Technologies
Wireless Smart Home Market
Wireless Technologies
Wireless Paging Systems Market
Wireless Technologies
Wireless Camera Market
Wireless Technologies
Asia-Pacific Wi-Fi 6 Market
Wireless Technologies
Global Wireless Data Radio Modem Market
Wireless Technologies
Europe Fixed Wireless Access (FWA) Market
Wireless Technologies
Wireless Connectivity Market
Wireless Technologies
5G Fixed Wireless Access Market
Wireless Technologies
North America Wireless Microphone Market
Wireless Technologies
Industrial Wireless Broken Signal Solutions Market
Wireless Technologies
Voice Over Wifi Market
Wireless Technologies
Mobile Signal Booster Market
Wireless Technologies
Visible Light Communication (VLC) Market
Wireless Technologies
5G Mmwave Technology Market