
 5G Technology ROI Market | 2026-2036
5G Technology ROI Market Size, Share, and Industry Trends Forecast 2026-2036
5G Technology ROI Market Outlook
Market Dynamics and Competitive Landscape
Enterprise buyer concentration is broadening as manufacturing conglomerates and municipal governments join telecommunications carriers as direct 5G infrastructure purchasers. Verizon Communications Inc. leverages its millimeter-wave spectrum depth to anchor premium private network contracts with industrial clients. Huawei Technologies Co., Ltd. sustains R&D intensity in massive MIMO antenna systems despite Western market access constraints. Nokia Corporation competes through Open RAN interoperability commitments that appeal to European operators diversifying vendor portfolios.
Technical Foundations and Segment Architecture
5G Technology ROI quantifies the financial return on capital deployed for fifth-generation wireless infrastructure, measured through latency reduction below one millisecond, spectral efficiency gains, and energy-per-bit improvements over 4G LTE networks. The analysis evaluates payback periods across hardware, software, and spectrum assets that enable enhanced mobile broadband, ultra-reliable low-latency communications, and massive machine-type communications. Smart Cities applications lead capital deployment within the Application dimension as municipal governments prioritize traffic management and public safety networks. The Deployment Model dimension shows Hybrid configurations capturing margin pools by blending cloud orchestration with on-premises core functions for data sovereignty-sensitive enterprises. Industrial Automation within Industry Vertical is accelerating fastest as manufacturers quantify downtime reduction and predictive maintenance savings.
Regulatory Environment and Strategic Imperatives
FCC spectrum allocation rules in the United States, EU 5G security requirements under the NIS2 Directive, and China's MIIT equipment certification standards collectively shape vendor market access and operator procurement criteria. The EU AI Act intersects with autonomous vehicle applications by mandating algorithmic transparency for edge-computing nodes processing real-time traffic decisions. Stakeholders must monitor spectrum reallocation proceedings and cross-border data governance frameworks that determine where private 5G networks can interoperate with public infrastructure.
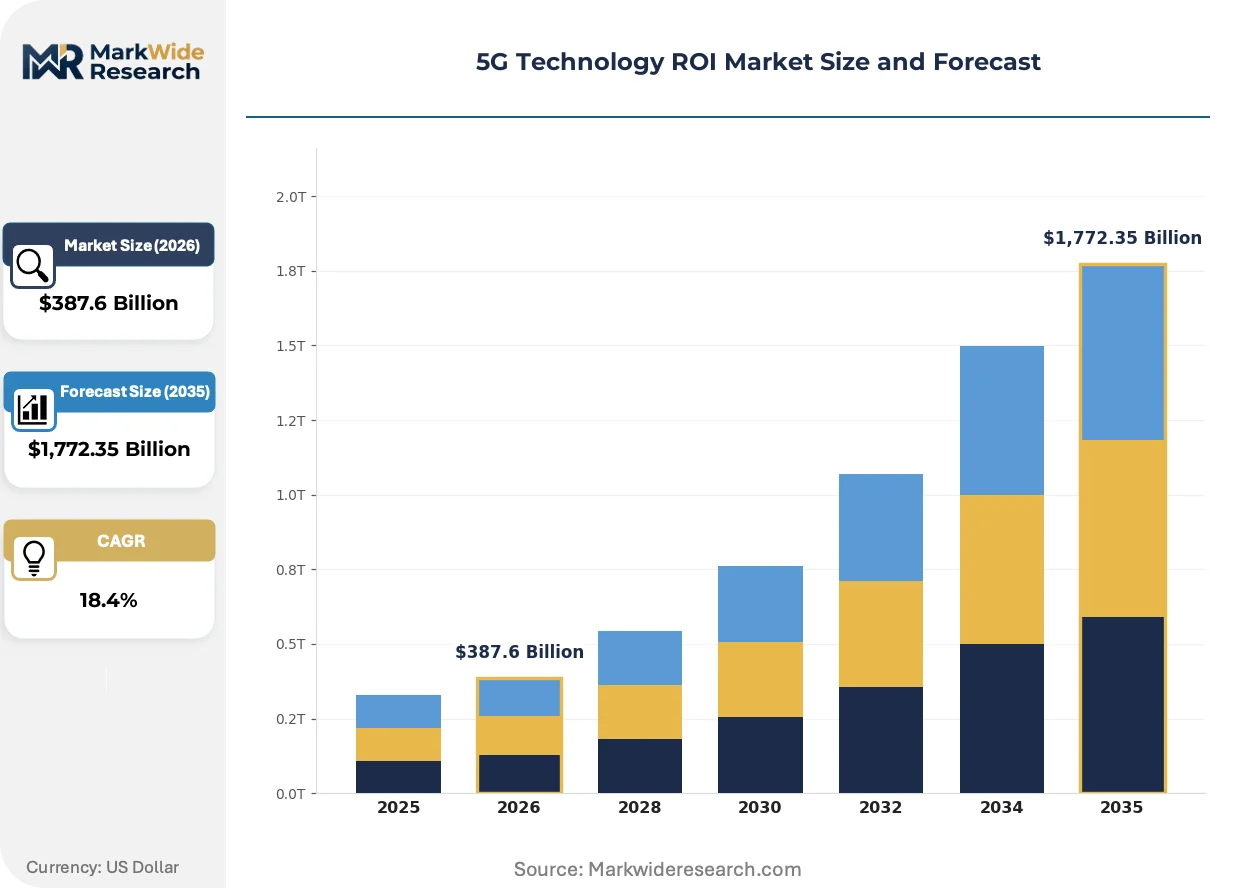
Market Dynamics
Enterprise procurement of private 5G networks is displacing carrier-centric deployment models as manufacturers and municipal governments demand direct infrastructure ownership with quantifiable latency guarantees.
Growth Catalysts
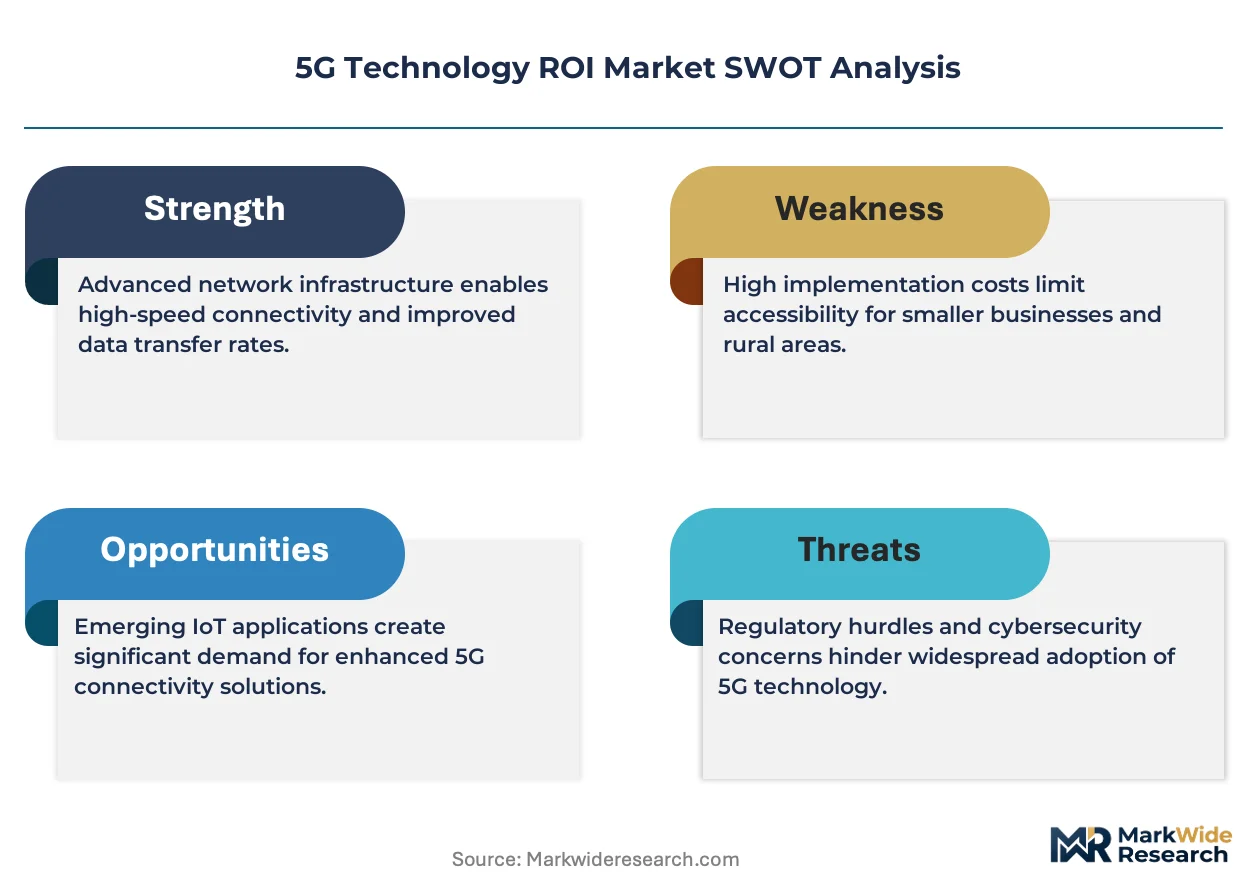
- EU NIS2 Directive:Cybersecurity mandates for critical infrastructure operators are accelerating private network investments as enterprises seek sovereign control over data routing and edge computing nodes.
- Industrial Automation:Smart manufacturing facilities are deploying massive machine-type communications for predictive maintenance systems that reduce unplanned downtime through real-time sensor telemetry.
- South Korea:Government-backed testbeds in manufacturing clusters are validating private 5G ROI models that neighboring Asian economies are replicating for port automation and logistics hubs.
Market Restraints
- Millimeter-wave spectrum licensing costs:Dense urban deployments require expensive high-frequency auctions that extend payback periods for infrastructure investors.
- Baseband semiconductor concentration:Advanced chip fabrication for massive MIMO arrays depends on concentrated Asian foundry capacity vulnerable to export control disruptions.
- Optical fiber backhaul limitations:Fronthaul density requirements for ultra-reliable low-latency communications exceed existing fiber penetration in industrial zones outside major metropolitan areas.
Strategic Opportunities
- Germany Industrie 4.0 clusters:Automotive and precision engineering corridors remain underpenetrated for campus-wide private networks with guaranteed quality-of-service tiers.
- Network slicing convergence with edge AI:Partitioned virtual network instances combined with localized inference engines create new service revenue streams for system integrators.
- US IRA manufacturing reshoring incentives:Domestic production facility construction is triggering demand for private wireless infrastructure with localized data governance.
Industry Challenges
- Radio frequency engineering specialization:Shortages of professionals capable of optimizing beamforming configurations for complex industrial environments delay deployment timelines.
- Multi-vendor Open RAN integration:Interoperability testing between disaggregated radio units and cloud-native baseband software extends commissioning cycles and increases system failure modes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 5G Technology ROI Market |
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $1,772.35 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Smart Cities, Remote Healthcare, Autonomous Vehicles, Industrial Automation Industry Vertical: Telecommunications, Transportation, Healthcare, Manufacturing Deployment Model: Cloud-based, On-premises, Hybrid, Private End User: Enterprises, Government, Consumers, Service Providers |
| Companies Covered | SK Telecom, KDDI Corporation, Huawei Technologies Co., Ltd., Verizon Communications Inc., AT&T Inc., China Mobile, NTT DOCOMO, INC., Nokia Corporation, KT Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
5G Technology ROI Market Strategic Shifts
Software-defined radio architectures and cloud-native core networks are compressing hardware refresh cycles while enabling programmable network services that adapt to application-specific latency requirements.
Open RAN disaggregation is consolidating vendor relationships as telecommunications operators dismantle integrated equipment stacks in favor of interoperable subsystems from specialized suppliers. Deutsche Telekom and Rakuten Mobile are accelerating multi-vendor deployments that separate radio units from baseband processing. This architecture is consolidating procurement leverage toward systems integrators capable of orchestrating heterogeneous hardware environments.
The EU AI Act is imposing algorithmic transparency requirements on edge computing nodes processing autonomous vehicle traffic decisions in real time. German automotive manufacturers must now document inference logic for safety-critical 5G-connected systems. Industrial automation deployments across Bavaria and Baden-Württemberg are most affected, with suppliers accelerating certification pipelines for explainable AI middleware.
Enterprise buyers are unbundling network infrastructure from managed service contracts and acquiring direct ownership of private 5G assets with self-operated core functions. Manufacturing conglomerates in the United States are replacing carrier-managed subscriptions with capitalized equipment purchases that depreciate on balance sheets. This pattern is most visible in automotive assembly plants across Michigan and Tennessee where IT departments are absorbing radio network operations.
5G Technology ROI Market Segmentation
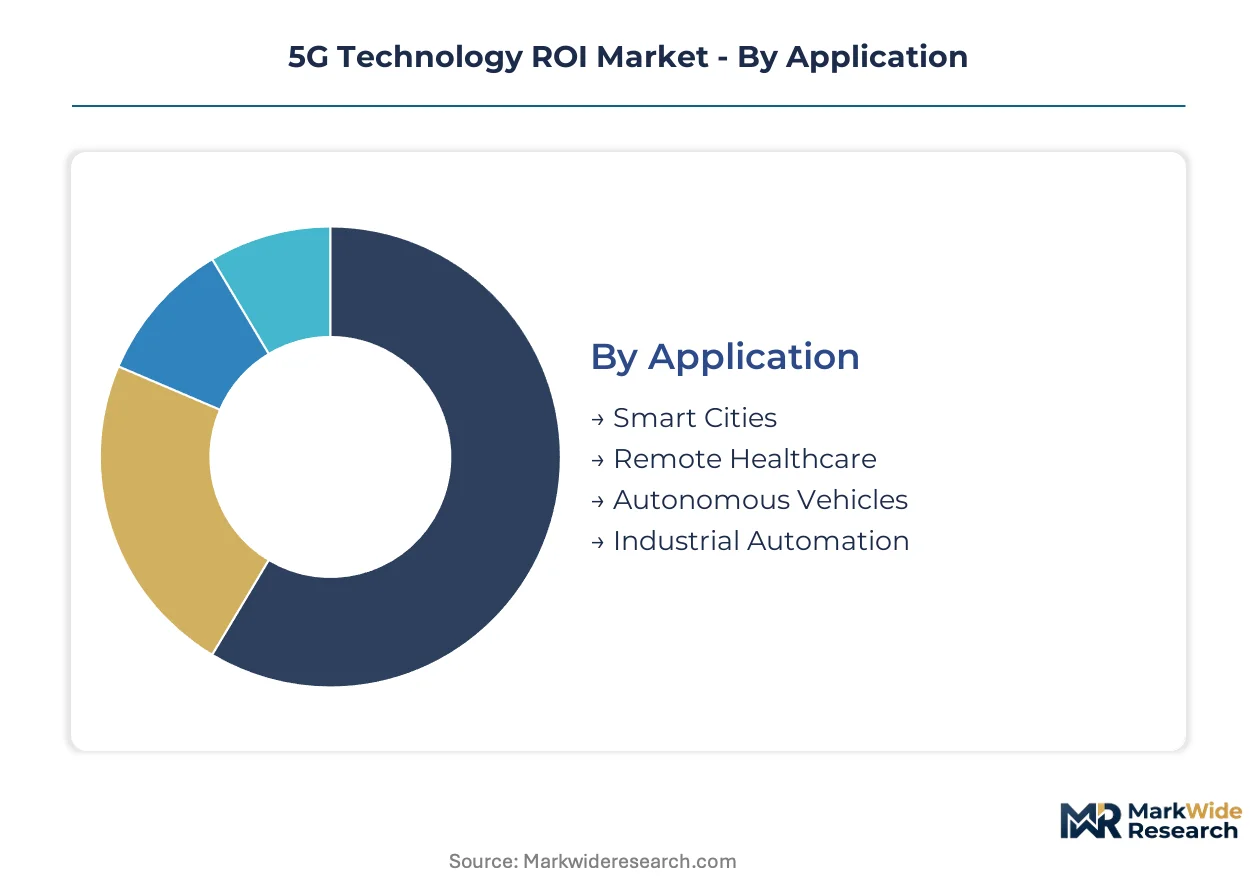
5G Technology ROI segmentation reveals how capital allocation priorities diverge across buyer types and deployment architectures. Understanding these fault lines helps vendors calibrate pricing models and implementation roadmaps to specific purchaser risk profiles.
Application:
Enterprise buyers select applications based on measurable latency thresholds and regulatory compliance burdens rather than speculative future capabilities.
- Smart Cities:Municipal traffic management and public safety networks dominate current procurement. German cities including Munich and Hamburg are prioritizing intersection sensor grids with sub-10 millisecond response guarantees for emergency vehicle preemption.
- Industrial Automation:Predictive maintenance systems using massive machine-type communications are compressing payback periods below 36 months for automotive manufacturers. South Korean government testbeds in Busan manufacturing clusters validated these ROI models for regional replication.
- Remote Healthcare:Telemedicine platforms and remote surgical consultation networks require guaranteed bandwidth tiers that challenge carrier SLA structures.
- Autonomous Vehicles:Edge computing nodes processing real-time traffic decisions face EU AI Act algorithmic transparency mandates that extend certification timelines.
Volume sits with Smart Cities; growth tilts toward Industrial Automation.
Industry Vertical:
Capital intensity and spectrum access rights determine which verticals can bypass carrier intermediaries for direct infrastructure ownership.
- Manufacturing:Campus-wide private networks with guaranteed quality-of-service tiers are displacing Wi-Fi in precision engineering facilities. German Industrie 4.0 clusters in Bavaria and Baden-Württemberg remain underpenetrated for this deployment pattern.
- Telecommunications:Traditional carrier infrastructure investment is concentrating on millimeter-wave spectrum depth for premium enterprise contracts. Verizon Communications leverages this position for private network anchoring in industrial zones.
- Transportation:Port automation and logistics hubs across Asian economies are replicating South Korean 5G testbed validation models for container tracking and autonomous yard vehicles.
- Healthcare:Hospital systems are acquiring direct spectrum leases for medical device connectivity that exceeds commercial carrier reliability benchmarks.
Revenue concentrates in Telecommunications; margin expansion favors Manufacturing.
Deployment Model:
Data sovereignty requirements and edge computing latency budgets drive architecture selection more than total cost of ownership calculations.
- Hybrid:Blending cloud orchestration with on-premises core functions captures margin pools from data sovereignty-sensitive enterprises. This configuration dominates European financial services and automotive compliance environments.
- Private:Direct infrastructure ownership with self-operated core functions is accelerating among US manufacturing conglomerates replacing carrier-managed subscriptions. IT departments in Michigan and Tennessee automotive plants are absorbing radio network operations.
- Cloud-based:Fully virtualized core networks appeal to mid-market enterprises lacking in-house RF engineering specialization.
- On-premises:Physical baseband and core installations persist in defense and critical infrastructure applications with air-gapped security requirements.
Deployment velocity favors Hybrid; absolute spend shifts toward Private.
End User:
Procurement authority migration from carriers to direct enterprise buyers is restructuring vendor sales channels and contract structures.
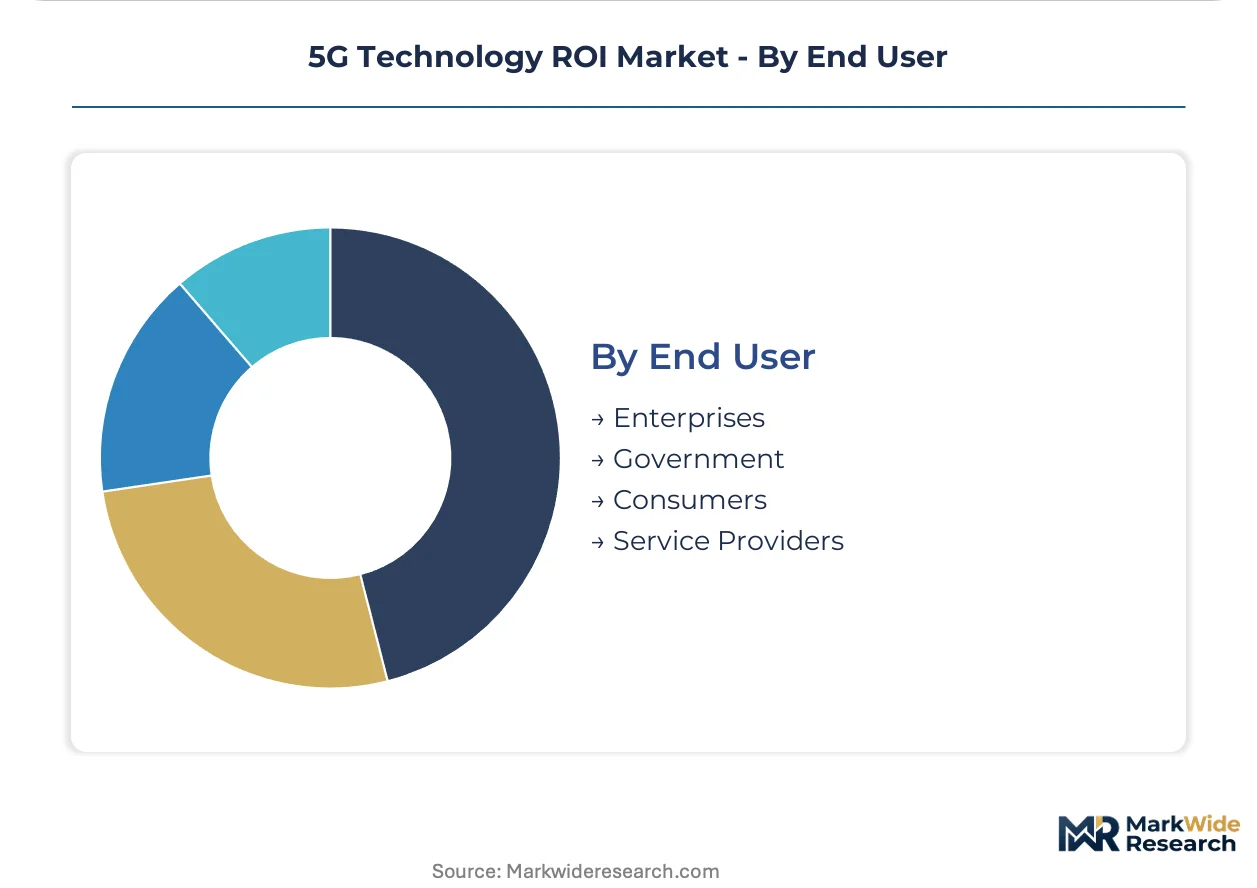
- Enterprises:Manufacturing conglomerates and municipal governments are joining telecommunications carriers as direct infrastructure purchasers. These buyers demand quantifiable latency guarantees and balance sheet depreciation treatment rather than operational expenditure models.
- Government:Federal and municipal agencies are leveraging sovereign spectrum allocations for public safety and transportation networks that bypass commercial carrier infrastructure.
- Service Providers:Traditional carriers are repositioning toward systems integration and managed services as enterprise direct ownership erodes equipment subscription revenues.
- Consumers:Residential 5G fixed wireless access remains a carrier-managed proposition with limited direct infrastructure purchase pathways.
Contract value concentrates with Enterprises; policy influence rests with Government.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise procurement of private 5G networks concentrates in the United States, Germany, and South Korea where industrial automation and smart city investments demand measurable latency guarantees. Municipal governments and manufacturing conglomerates in these markets are bypassing carrier intermediaries for direct infrastructure ownership. Spectrum allocation frameworks and sovereign data requirements are accelerating deployment timelines in each jurisdiction.
United States
Automotive assembly plants across Michigan and Tennessee are absorbing radio network operations into corporate IT departments. FCC spectrum auctions for millimeter-wave bands are reshaping vendor eligibility for dense urban deployments. The IRA manufacturing reshoring incentives are triggering demand for private wireless infrastructure with localized data governance at new domestic production facilities.
Germany
Automotive and precision engineering corridors in Bavaria and Baden-Württemberg remain underpenetrated for campus-wide private networks with guaranteed quality-of-service tiers. The EU NIS2 Directive cybersecurity mandates are accelerating sovereign control investments over data routing and edge computing nodes. Munich and Hamburg are prioritizing intersection sensor grids with sub-10 millisecond response guarantees for emergency vehicle preemption.
South Korea
Government-backed testbeds in Busan manufacturing clusters are validating private 5G ROI models for predictive maintenance systems. The national regulator supports spectrum allocations that enable direct enterprise ownership without carrier intermediation. Port automation and logistics hubs are replicating these validation models for container tracking and autonomous yard vehicles.
China
MIIT equipment certification standards are shaping vendor market access criteria for domestic and international suppliers. Manufacturing facilities are deploying massive machine-type communications for real-time sensor telemetry across production lines. Yangtze River Delta industrial zones are integrating 5G infrastructure with existing automation investments at scale.
Japan
Automotive manufacturers in the Chubu region around Nagoya are requiring algorithmic transparency for edge-computing nodes processing safety-critical systems. METI industrial policy frameworks are supporting private network deployments in precision manufacturing clusters. Kansai region electronics producers are quantifying downtime reduction savings to justify infrastructure capital allocation.
5G Technology ROI Market Competitive Environment
United States producers anchor one tier; Asian specialists hold equipment manufacturing depth. The vendor base separates between integrated stack providers and disaggregated subsystem suppliers. Three archetypes dominate: spectrum-rich carriers pivoting to private network anchoring, equipment vendors pursuing Open RAN interoperability commitments, and systems integrators orchestrating multi-vendor deployments. Competitive moves concentrate on strategic partnerships for edge AI convergence and geographic expansion into underpenetrated Industrie 4.0 corridors.
Among Asian equipment manufacturers, Huawei Technologies Co., Ltd. and Nokia Corporation exemplify divergent strategic positioning within the same competitive space. Verizon Communications Inc. occupies a distinct tier as a carrier-origin player leveraging licensed spectrum depth for enterprise direct contracts. These three anchors illustrate how vendor origin—equipment manufacturing versus telecommunications services—determines go-to-market architecture and customer relationship patterns in private network procurement.
| Leading Market Players |
|---|
| SK Telecom |
| KDDI Corporation |
| Huawei Technologies Co., Ltd. |
| Verizon Communications Inc. |
| AT&T Inc. |
| China Mobile |
| NTT DOCOMO, INC. |
| Nokia Corporation |
| KT Corporation |
| Others |
Value Chain & Pricing Dynamics
Massive MIMO baseband semiconductor fabrication costs cascade through three distinct pricing tiers as foundry capacity in Taiwan and South Korea feeds hardware procurement decisions for telecommunications carriers, systems integrators, and direct enterprise buyers. These upstream input costs concentrate pricing power with equipment vendors possessing captive chip supply relationships while compressing margins for assemblers dependent on spot-market component sourcing.
Pricing Analysis
Volume concentrates with carrier-managed subscription models while margin pools shift toward direct enterprise ownership of private network infrastructure. Three-tier pricing structure across premium, standard, and economy levels differentiates based on spectrum depth guarantees and edge computing node density. Cost compression in the standard tier is intensifying because Open RAN interoperability commitments are commoditizing radio unit hardware. Municipal governments exhibit highest price sensitivity due to budget approval cycles, whereas automotive manufacturers prioritize latency guarantees over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with advanced baseband semiconductor foundry capacity concentrated in Taiwan, South Korea, and China. Massive MIMO antenna arrays, millimeter-wave transceivers, and optical fronthaul components draw from specialized manufacturing clusters across these geographies. Regulatory restriction risk emanates from export control frameworks affecting chip fabrication equipment transfers. Distribution runs through tier-one systems integrators capable of orchestrating multi-vendor Open RAN deployments for enterprise direct buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
5G Technology ROI markets are transitioning from carrier-centric deployment models toward enterprise direct ownership as cloud-native core networks displace legacy hardware-defined infrastructure. This technology-transition phase rewards vendors capable of unbundling network software from proprietary hardware stacks.
For Market Incumbents: Cement spectrum depth advantages through long-term private network anchoring contracts with industrial automation clients in Michigan and Tennessee manufacturing corridors. Prioritize Open RAN certification investments to defend against disaggregated subsystem suppliers eroding integrated equipment margins. Channel control through direct enterprise sales teams offers the strongest defensive lever against systems integrators consolidating procurement influence.
For New Entrants and Emerging Players: EU NIS2 Directive cybersecurity mandates in Germany open a window for sovereign data routing solutions targeting Bavaria and Baden-Württemberg precision engineering clusters. Campus-wide private networks with guaranteed quality-of-service tiers represent the most penetrable segment given underinvestment by incumbent carriers in Industrie 4.0 corridors. A go-to-market angle emphasizing algorithmic transparency compliance for EU AI Act edge computing deployments differentiates against hardware-focused competitors.
For Investors and Strategic Acquirers: Enterprise IT departments absorbing radio network operations into balance-sheet depreciation treatment is the leading indicator that carrier-managed subscription erosion will accelerate. Position for a five-to-ten year horizon where systems integrators with multi-vendor orchestration capabilities capture margin expansion from equipment commoditization. Acquisition target archetype: mid-scale Open RAN software specialists with existing certification pipelines in European automotive manufacturing zones.
| Strategic Initiative | Industry Significance |
|---|---|
| Open RAN Certification Investment | Deutsche Telekom multi-vendor deployments validate interoperability commitments for European operator diversification. |
| Edge AI Middleware Development | German automotive manufacturers require algorithmic transparency documentation for EU AI Act compliance in safety-critical systems. |
| Private Network Direct Sales Expansion | US automotive plants in Michigan and Tennessee demonstrate enterprise IT absorption of radio operations. |
| Spectrum Lease Portfolio Accumulation | FCC millimeter-wave auction outcomes reshape vendor eligibility for dense urban infrastructure deployment. |
| Systems Integrator Partnership | Rakuten Mobile multi-vendor architectures consolidate procurement leverage toward orchestration specialists. |
Study Parameters
SEC filings, FCC spectrum auction records, and EU regulatory impact assessments formed the secondary backbone for market sizing and competitive positioning analysis. Primary interviews with telecommunications carrier procurement executives, enterprise IT directors at automotive manufacturers, Open RAN systems integrators, and RF engineering specialists validated demand assumptions and deployment timeline estimates. Bottom-up triangulation across hardware shipment data and top-down reconciliation against carrier capex disclosures anchored volume forecasts.
Bottom-up modeling of baseband unit deployments, antenna system installations, and software licensing volumes across the projection horizon integrated with top-down carrier and enterprise budget allocation surveys. Segmentation dimensions included deployment model architecture, industry vertical capital intensity, application latency requirements, and regional spectrum allocation frameworks. CAGRs were derived from slope analysis of infrastructure investment curves correlated with measurable ROI validation from South Korean government testbeds.
Caveats apply where FCC spectrum reallocation proceedings, EU NIS2 Directive implementation variance across member states, or export control disruption to Asian foundry capacity could materially shift the outlook. Forecasts reflect documented assumptions regarding enterprise procurement authority migration and Open RAN interoperability maturation timelines. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wireless Technologies
Outdoor Wi-Fi Market
Wireless Technologies
Wireless USB (WUSB) Devices Market
Wireless Technologies
Global Bluetooth Beacon and Ibeacon Market
Wireless Technologies
Global Bluetooth Audio Codec Market
Wireless Technologies
Mesh Wifi System Market
Wireless Technologies
Enterprise WLAN Market
Wireless Technologies
Asia-Pacific Wireless Microphone Market
Wireless Technologies
Optical Wireless Communication and Li-Fi Market
Wireless Technologies
Wireless Paging Systems Market
Wireless Technologies
5G Mmwave Technology Market
Wireless Technologies
Asia-Pacific Distributed Antenna System Market
Wireless Technologies
Global Massive MIMO Market
Wireless Technologies
Wireless Camera Market
Wireless Technologies
Wi-Fi Booster Market
Wireless Technologies
Europe Wireless Charging Market
Wireless Technologies
Wireless Communication Equipment Market