
 TPU Hydrogel Screen Protectors Market | 2026-2036
TPU Hydrogel Screen Protectors Market Size, Share, and Industry Trends Forecast 2026-2036
TPU Hydrogel Screen Protectors Market Insights
Multi-pack bundling with charging accessories is pivoting how consumers evaluate screen protection value. Smartdevil leverages its Shenzhen manufacturing base to anchor low-cost transparent film output across Asia-Pacific e-commerce channels. ESR competes through specialized anti-glare formulations aimed at remote-work laptop users in North America. Belkin International sustains premium positioning via electronics store partnerships and Apple-certified compatibility programs.
TPU hydrogel screen protectors are thin, elastomeric films composed of thermoplastic polyurethane matrices swollen with water or glycerin, typically measuring 0.1 to 0.3 millimeters in thickness and engineered to self-repair minor scratches through polymer chain reorganization at room temperature. Their primary commercial purpose is to absorb impact energy and conform to curved display edges without optical distortion. Transparent films dominate volume shipments across smartphones and tablets, while anti-bacterial variants command margin premiums in healthcare and education procurement channels where hygiene protocols have tightened. Self-healing formulations represent the fastest-growing product type as Korean and Chinese material suppliers refine catalyst-free crosslinking processes that eliminate yellowing.
REACH restrictions on isocyanate precursors in Europe and RoHS compliance for electronics accessories constrain formulation choices and supplier qualification timelines. The FDA regulates antimicrobial efficacy claims on anti-bacterial variants marketed in the United States, requiring substantiation that shapes R&D allocation. China's GB standards for electronics accessories and SAMR product quality inspections add parallel certification layers for export-bound manufacturers. Stakeholders must monitor evolving chemical disclosure rules across multiple jurisdictions to preempt supply chain disruption and maintain market access.
Market Dynamics
Smartphone OEM bundling strategies in East Asia are compressing aftermarket pricing power while REACH compliance costs in Europe force reformulation investments that favor larger material suppliers with dedicated regulatory teams.
Growth Catalysts
- Antimicrobial certification demand:FDA substantiation requirements for healthcare procurement channels in the United States are creating premium product tiers that command higher margins than standard transparent films.
- Curved display penetration:Thermoplastic polyurethane matrices conform to edge-to-edge smartphone screens where tempered glass fails, driving replacement cycles in the premium handset segment.
- Shenzhen manufacturing scale:Coating capacity concentration in Guangdong Province enables rapid turnaround on custom hydrogel formulations for direct-to-consumer brands.
Market Restraints
- Isocyanate precursor volatility:REACH restrictions on aromatic diisocyanates in Europe constrain crosslinking chemistry options and extend supplier qualification timelines.
- Single-source coating concentration:Bulk TPU film production clusters in Shenzhen and Seoul create geographic supply risk without viable secondary capacity in South Asia or Mexico.
- Tempered glass substitution:Chemically strengthened glass retains cost advantage in flat-screen applications and dominates budget smartphone accessories.
Strategic Opportunities
- India domestic manufacturing:PLI scheme incentives for electronics components could attract hydrogel coating investment to reduce import dependence from China.
- Automotive interior displays:Curved infotainment screens in electric vehicles present untapped application volume with distinct optical clarity requirements.
- SAMR quality enforcement:Stricter GB standard inspections for electronics accessories are weeding out substandard suppliers and creating shelf space for certified brands.
Industry Challenges
- Catalyst-free formulation R&D:Eliminating yellowing in self-healing films requires polymer science expertise that concentrates in Korean and Chinese material labs, creating talent scarcity elsewhere.
- Dual certification timelines:Simultaneous REACH dossier preparation and FDA antimicrobial claim substantiation stretches regulatory affairs capacity at mid-sized suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | TPU Hydrogel Screen Protectors Market |
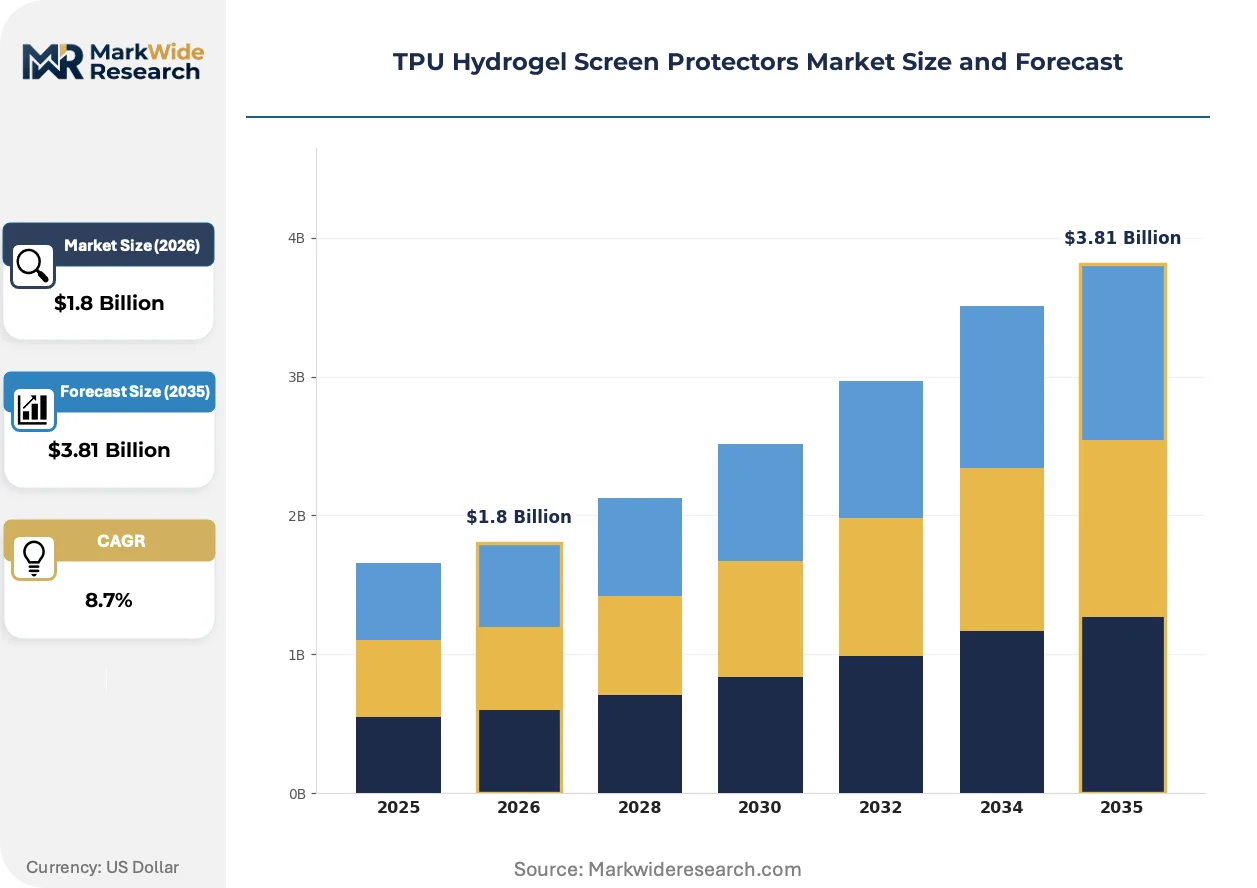
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Transparent, Anti-Bacterial, Anti-Glare, Self-Healing Application: Smartphones, Tablets, Laptops, Wearable Devices End User: Consumers, Businesses, Schools, Retailers Distribution Channel: Online Retail, Electronics Stores, Supermarkets, Specialty Shops |
| Companies Covered | Smartdevil, Pisen, ESR, Benks, Baseus, Ugreen, Spigen, Belkin International, ZAGG Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
TPU Hydrogel Screen Protectors Market Trends and Innovations
Material science breakthroughs and procurement model disruption are converging to reshape competitive positioning in screen protection, with formulation chemistry and channel access becoming the primary differentiation vectors.
Catalyst-free crosslinking chemistry is rewriting the performance baseline for self-healing TPU films. Korean material suppliers have eliminated photoinitiators that cause UV-induced yellowing, enabling clear-film warranties that extend past 24 months. Premium smartphone OEMs in Seoul are qualifying these formulations for factory-applied protection bundles.
REACH Annex XVII restrictions on isocyanate precursors are forcing European market participants to reformulate with aliphatic crosslinkers that increase raw material costs. German electronics distributors are consolidating supplier lists to partners with completed ECHA dossiers, compressing the vendor base available to regional brands.
Direct-to-consumer channel expansion is fragmenting traditional retail distribution for screen protectors. Shenzhen-based manufacturers are launching owned-brand storefronts on regional e-commerce platforms, bypassing electronics retailers that previously controlled shelf placement. This pattern is most visible in Southeast Asia where mobile-first purchasing dominates accessory transactions.
TPU Hydrogel Screen Protectors Market Segmentation
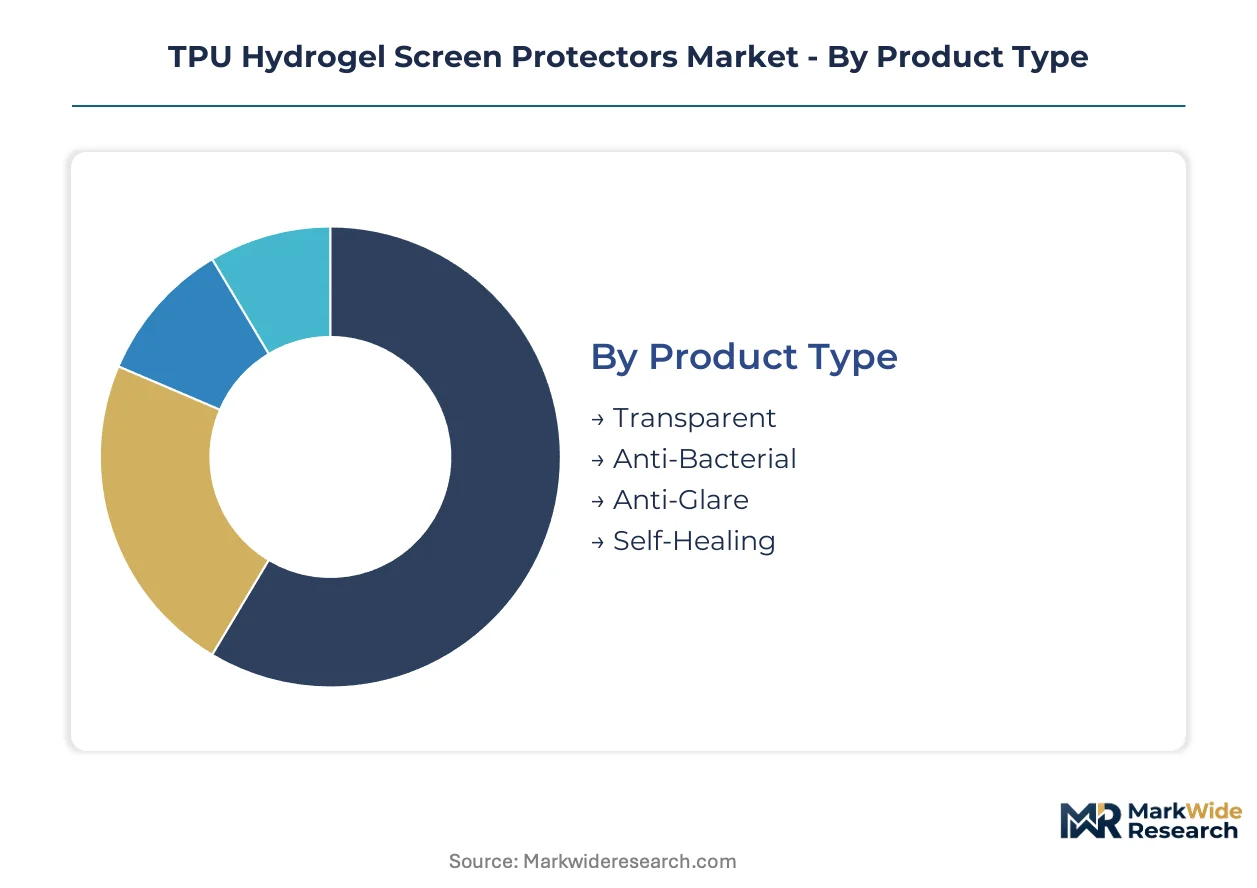
Segmentation in TPU hydrogel screen protectors reveals how formulation chemistry, device form factors, and procurement channels create distinct margin profiles and capital requirements. Each dimension shapes where coating capacity gets allocated and which regulatory certifications prove decisive for market access.
Product Type:
Capital intensity varies sharply across formulation tiers, with antimicrobial certification and self-healing chemistry demanding dedicated R&D infrastructure that transparent films avoid entirely.
- Transparent:Standard TPU matrices without functional additives dominate volume production. Shenzhen coating lines run these formulations at highest throughput for smartphone OEM bundles across China and Vietnam.
- Self-Healing:Catalyst-free crosslinking processes eliminate photoinitiator-induced yellowing through polymer chain reorganization. Korean material labs in Seoul supply premium smartphone manufacturers with 24-month clarity warranties.
- Anti-Bacterial:FDA-substantiated claims for healthcare procurement require dedicated antimicrobial testing infrastructure.
- Anti-Glare:Surface microstructuring for laptop displays adds etching equipment costs without self-healing complexity.
Transparent films absorb the bulk of installed capacity; self-healing formulations are expanding most quickly.
Application:
Device curvature and surface area determine coating thickness tolerances and edge-conformance testing requirements.
- Smartphones:Edge-to-edge curved displays demand 0.1-0.2mm films with elastomeric recovery. Chinese OEMs in Shenzhen and Seoul-based manufacturers bundle hydrogel protection with premium handset launches.
- Tablets:Larger surface areas increase material consumption per unit without proportionate price premiums, compressing margins for standardized formulations.
- Laptops:Anti-glare variants target remote-work productivity needs in North American enterprise procurement.
- Wearable Devices:Small form factors require precision die-cutting capabilities and flexible substrate handling.
Smartphone applications command the greatest coating capacity allocation; automotive interior displays represent the steepest expansion trajectory outside consumer electronics.
End User:
Procurement sophistication and compliance requirements separate institutional buyers from individual consumers.
- Businesses:Enterprise mobility programs specify bulk procurement with standardized device protection. REACH-compliant documentation and RoHS certification gates supplier qualification.
- Schools:Hygiene protocols post-pandemic drive anti-bacterial specification in education technology tenders.
- Consumers:Price-sensitive individual purchasers evaluate multi-pack value against single-unit retail pricing.
- Retailers:Private-label sourcing from Shenzhen manufacturers competes with branded shelf placement.
Business procurement absorbs the bulk of certified supply; school district tenders are gaining share fastest in North America and Europe.
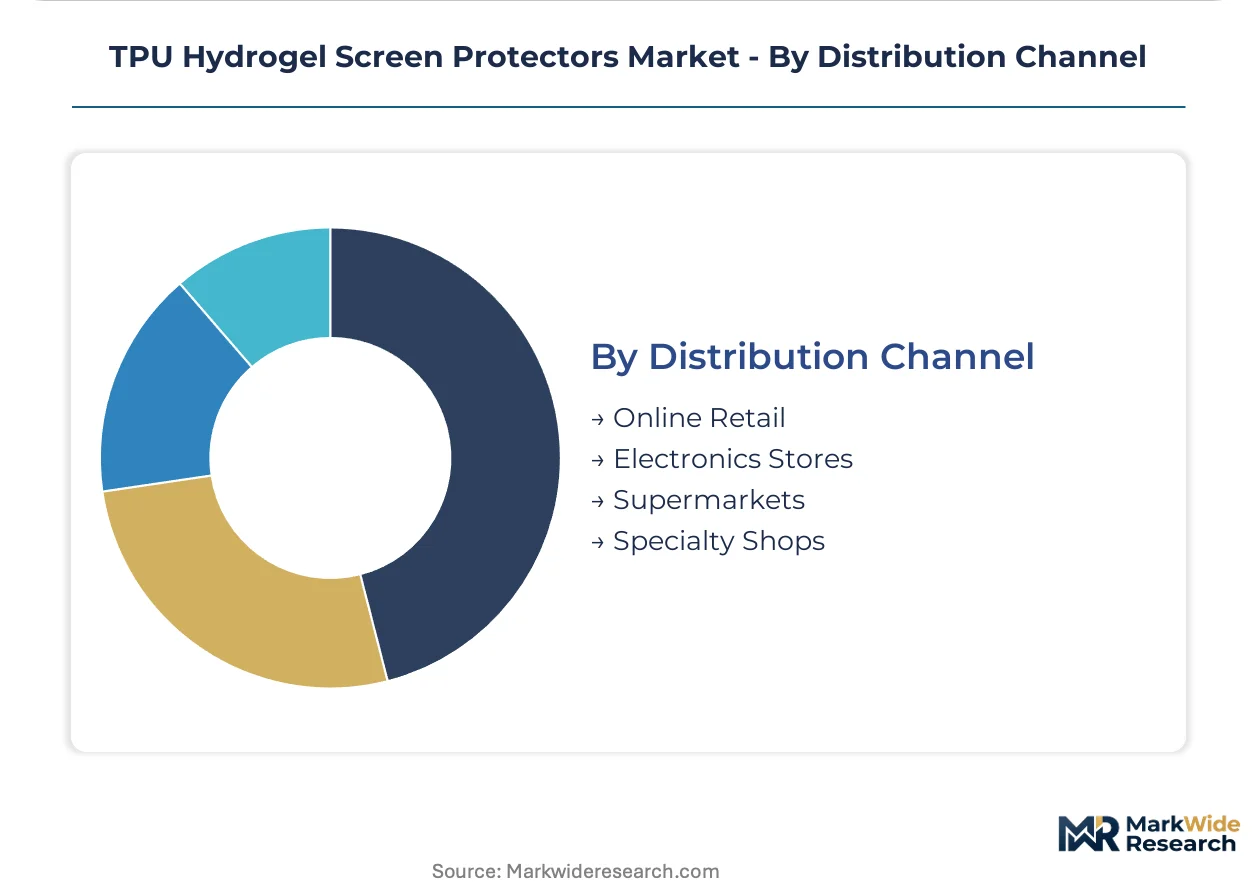
Distribution Channel:
Channel control determines margin capture and brand visibility versus price competition.
- Online Retail:Direct-to-consumer storefronts on regional e-commerce platforms bypass traditional electronics retail. Shenzhen-based manufacturers own-brand sales dominate Southeast Asia mobile-first purchasing.
- Electronics Stores:Apple-certified compatibility programs and premium positioning sustain Belkin International's retail partnerships.
- Supermarkets:Impulse-purchase placement for budget transparent films with minimal packaging differentiation.
- Specialty Shops:Custom cutting services and installation support justify premium pricing for curved device applications.
Online retail channels absorb the bulk of volume growth; electronics store partnerships retain the highest margin concentration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity concentrates in East Asian coating clusters while consumption spreads across North American healthcare procurement and European regulatory-compliant channels. Shenzhen and Seoul control bulk TPU film output, yet demand fragmentation across jurisdictions creates divergent certification burdens for suppliers.
United States
Healthcare procurement drives anti-bacterial specification in hospital and education technology tenders. FDA substantiation requirements for antimicrobial claims gate market access and compress supplier qualification timelines. California-based electronics distributors prioritize REACH-compliant documentation for imported accessories.
China
Shenzhen coating lines supply global smartphone OEM bundles and direct-to-consumer e-commerce channels. SAMR quality inspections under GB standards weed out substandard suppliers and consolidate shelf space for certified brands. Pearl River Delta manufacturing clusters enable rapid turnaround on custom hydrogel formulations.
Germany
REACH Annex XVII restrictions on aromatic diisocyanates force reformulation with aliphatic crosslinkers. ECHA dossier completion gates supplier qualification for electronics distributors consolidating vendor lists. Bavaria-based industrial buyers specify RoHS certification for enterprise mobility programs.
South Korea
Seoul material labs supply catalyst-free self-healing formulations to premium smartphone OEMs with 24-month clarity warranties. MFDS-aligned quality protocols shape export documentation for regional brands. Busan-Ulsan coating capacity serves domestic handset manufacturers and export markets.
India
PLI scheme incentives for electronics components attract coating investment to reduce import dependence from China. BIS certification requirements for electronics accessories create parallel compliance layers for domestic and export-bound production. Maharashtra and Karnataka industrial corridors host emerging assembly operations for regional brands.
TPU Hydrogel Screen Protectors Market Competitive Landscape
The competitive structure tilts toward Shenzhen-based manufacturers with captive coating capacity and direct-to-consumer channel control. Three archetypes dominate: scale-driven fabricators running transparent film at highest throughput, premium-tier specialists with catalyst-free self-healing chemistry, and regulatory-certified suppliers with completed REACH dossiers and FDA-substantiated antimicrobial claims. Capacity expansion and strategic partnerships with smartphone OEMs constitute the dominant competitive moves, with bundling agreements compressing aftermarket pricing power.
Among Chinese fabricators, Smartdevil and Baseus exemplify the scale-driven archetype with manufacturing footprints in Guangdong Province. Belkin International occupies a position within the premium-tier certification vector through Apple-compatible positioning and electronics retail partnerships. ESR represents the specialization archetype with anti-glare formulations targeting North American remote-work procurement channels.
| Leading Market Players |
|---|
| Smartdevil |
| Pisen |
| ESR |
| Benks |
| Baseus |
| Ugreen |
| Spigen |
| Belkin International |
| ZAGG Incorporated |
| Others |
Pricing and Supply Chain Analysis
Aromatic diisocyanate price volatility cascades through TPU hydrogel formulation costs, compressing margin buffers for European suppliers forced into aliphatic crosslinker substitutions while Shenzhen manufacturers exploit Pearl River Delta petrochemical feedstock proximity to anchor economy-tier transparent film pricing.
Pricing Analysis
Margin tightening in premium self-healing tiers reflects catalyst-free R&D amortization and Korean patent licensing fees, while economy transparent films face relentless cost-down pressure from direct-to-consumer brands sourcing at Shenzhen coating-line scale. Three-tier pricing structure across premium, standard, and economy levels separates FDA-substantiated antimicrobial variants from REACH-compliant standard grades and uncertified bulk transparent films. Healthcare procurement in the United States exhibits lowest price sensitivity due to bundled device-protection contracts; Southeast Asian e-commerce consumers drive hardest bargain evaluation against multi-pack alternatives.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale smartphone bundling demand from Shenzhen and Seoul headquarters, while aftermarket distribution runs through Amazon, Shopee, and regional electronics retailers. Bulk TPU film production concentrates in China, South Korea, and emerging India PLI corridors. Raw material dependencies span thermoplastic polyurethane resin, photoinitiator chemicals, and antimicrobial additive compounds. Single-source coating concentration in Guangdong Province creates tariff-exposure vulnerability for North American and European buyers lacking qualified secondary capacity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The TPU hydrogel screen protector market functions as a cost-of-compliance arena where REACH dossier completion and FDA antimicrobial substantiation erect formidable barriers to uncertified entrants, consolidating viable supplier lists around regulatory-affairs-capable incumbents.
For Market Incumbents: Deploy backward integration into catalyst-free polymer synthesis to capture self-healing formulation premiums and escape Korean patent royalty structures. Consolidate distributor relationships in Germany and California where REACH and FDA documentation gates are tightening fastest. Tempered glass substitution in budget flat-screen segments and Shenzhen direct-to-consumer brand erosion threaten aftermarket pricing power. For New Entrants and Emerging Players: Direct-to-consumer storefronts on Southeast Asian e-commerce platforms offer lowest customer-acquisition friction for unbranded transparent film volume. Target India's domestic manufacturing incentive zones where PLI scheme subsidies offset Chinese import dependence and BIS certification creates defensible positioning. Specialty anti-glare formulations for North American remote-work laptop procurement represent the most penetrable premium niche. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier Chinese fabricators with completed ECHA dossiers and idle coating capacity in Guangdong Province. Long-term viability hinges on regulatory certification durability rather than transient volume share. Watch for SAMR enforcement waves triggering supplier consolidation as the inflection signal for certified-brand shelf space expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Catalyst-Free Formulation Licensing | Korean patent holders extract royalties from global smartphone OEM qualification programs. |
| REACH Dossier Completion | German electronics distributors consolidate vendor lists around ECHA-compliant suppliers exclusively. |
| Direct-to-Consumer Channel Launch | Shenzhen manufacturers bypass retail margin capture through owned-brand Southeast Asian e-commerce storefronts. |
| India PLI Manufacturing Footprint | Maharashtra coating investment reduces tariff exposure and qualifies for electronics component subsidies. |
| FDA Antimicrobial Claim Substantiation | Healthcare procurement tenders in the United States gate access to premium-margin institutional buyers. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with coating line operators, polymer R&D directors, electronics distributor procurement leads, and smartphone OEM accessory bundling managers. ECHA REACH dossiers, FDA 510(k) antimicrobial substantiation documents, SAMR GB standard inspection reports, and Shenzhen customs export declarations furnished triangulation points. Bottom-up capacity modeling across Guangdong Province coating clusters reconciled against top-down smartphone accessory attach-rate projections.
Data-stream reconciliation across shipment volume, raw material consumption, and end-device production estimates shaped the analytical framework throughout the forecast period. Segmentation dimensions spanned formulation chemistry tier, device application curvature requirement, procurement channel structure, and regional regulatory compliance cluster. CAGRs derived from elasticity-adjusted attach-rate trajectories and coating capacity expansion schedules. Self-healing formulation penetration curves and antimicrobial certification adoption timelines served as industry-specific forecast inputs.
The model holds under stable REACH enforcement intensity and continued smartphone curved-display penetration; deviation in isocyanate precursor availability or tempered glass price collapse would shift volume and margin trajectories. Forecasts reflect base-case assumptions around regulatory timeline adherence and OEM bundling contract renewal rates. Periodic stress-testing of base assumptions against SAMR inspection frequency and PLI scheme disbursement pacing is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Display Technologies
Automotive LCD Display Market
Display Technologies
Global Portable Monitor Market
Display Technologies
Global Next Generation Display Market
Display Technologies
Asia-Pacific E-Paper Display Market
Display Technologies
Global Smartphone Display Panel Market
Display Technologies
Smartphone Display Market
Display Technologies
Interactive Video Wall Market
Display Technologies
OLED Laptops Market
Display Technologies
Projector Screen Market
Display Technologies
Europe Transparent Conductive Films Market
Display Technologies
Smartwatch Display Panel Market
Display Technologies
Global 4K Display Resolution Market
Display Technologies
4K Drawing Tablet with Screen Market
Display Technologies
Smart Privacy Glass Market
Display Technologies
Display Control and Management System Market
Display Technologies
Electronic Display Signs Market