
 Phosphor Screen Market | 2026-2036
Phosphor Screen Market Size, Share, and Industry Trends Forecast 2026-2036
Phosphor Screen Market Analytics
East Asian manufacturing capacity is narrowing the supply gap for high-resolution phosphor coatings used in advanced imaging. Hamamatsu Photonics K.K. leverages its vertical integration across photomultiplier and scintillation material production. Konica Minolta, Inc. anchors its position through sustained R&D spending on medical-grade phosphor formulations. Scintacor specializes in customized phosphor solutions for scientific instrumentation, competing primarily on application-specific performance.
A phosphor screen is a luminescent panel composed of inorganic crystalline materials such as cesium iodide or gadolinium oxysulfide that converts incident radiation or electron beams into visible light, typically manufactured through vacuum deposition or thermal evaporation processes to achieve uniform grain structure and optimal emission efficiency. Inorganic phosphors dominate current revenue streams due to established reliability in medical and industrial imaging, while hybrid phosphors represent the fastest-expanding category as manufacturers blend organic light-emitting properties with inorganic stability to address next-generation display requirements. Imaging systems command the largest application share driven by persistent hospital infrastructure investment, whereas display technologies are capturing accelerated interest from automotive head-up display programs.
Japan's PMDA and METI enforce stringent purity and performance standards for phosphor screens deployed in diagnostic equipment, directly elevating compliance costs for imported components. The US FDA maintains parallel requirements under its medical device quality system regulation, creating dual-certification burdens for suppliers serving both markets. China's NMPA has aligned its medical imaging component rules with international electromagnetic compatibility protocols, reshaping market access conditions for foreign manufacturers. Stakeholders must monitor evolving rare earth material sourcing policies across these jurisdictions to anticipate phosphor cost trajectories and supply security.
Market Dynamics
East Asian display fabrication clusters are compressing lead times for high-resolution phosphor coatings while medical imaging digitization in Germany and Japan pulls procurement volumes upward. This dual-demand structure is straining rare earth supply chains and elevating purity certification requirements simultaneously.
Growth Catalysts
- Digital radiography infrastructure:Hospital systems in Germany and Japan are replacing analog film with computed radiography plates, directly lifting phosphor screen procurement volumes for flat-panel detectors.
- Automotive head-up display mandates:Windshield projection requirements in premium vehicle segments are accelerating demand for high-brightness phosphor layers in augmented reality clusters.
- China's NMPA alignment with IEC 60601:Electromagnetic compatibility harmonization is streamlining market access for certified foreign component suppliers, reducing duplicate testing burdens.
Market Restraints
- Rare earth concentrate volatility:Europium and terbium pricing swings from Chinese export quota adjustments transmit directly into phosphor manufacturing cost structures.
- Dual-certification burdens:Suppliers serving both FDA-regulated US hospitals and PMDA-enforced Japanese diagnostic equipment face redundant quality system audits.
- Organic LED substitution in consumer displays:Self-emissive OLED panels are capturing smartphone and television segments previously served by phosphor-converted backlight units.
Strategic Opportunities
- Scientific instrumentation customization:Synchrotron facilities and electron microscopy labs require application-specific phosphor formulations with tailored decay characteristics and emission spectra.
- India's PLI scheme for medical devices:Domestic manufacturing incentives are attracting phosphor screen assembly operations to serve South Asian imaging equipment demand.
- Hybrid organic-inorganic convergence:Blending solution-processable organic emitters with inorganic host stability addresses flexible display requirements unconstrained by vacuum deposition.
Industry Challenges
- Vacuum deposition technician scarcity:Specialized thin-film coating expertise concentrates in legacy Japanese and German equipment hubs, constraining capacity expansion.
- Legacy imaging system integration:Hospital IT departments face protocol mismatches when retrofitting phosphor-based digital detectors into existing PACS architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Phosphor Screen Market |
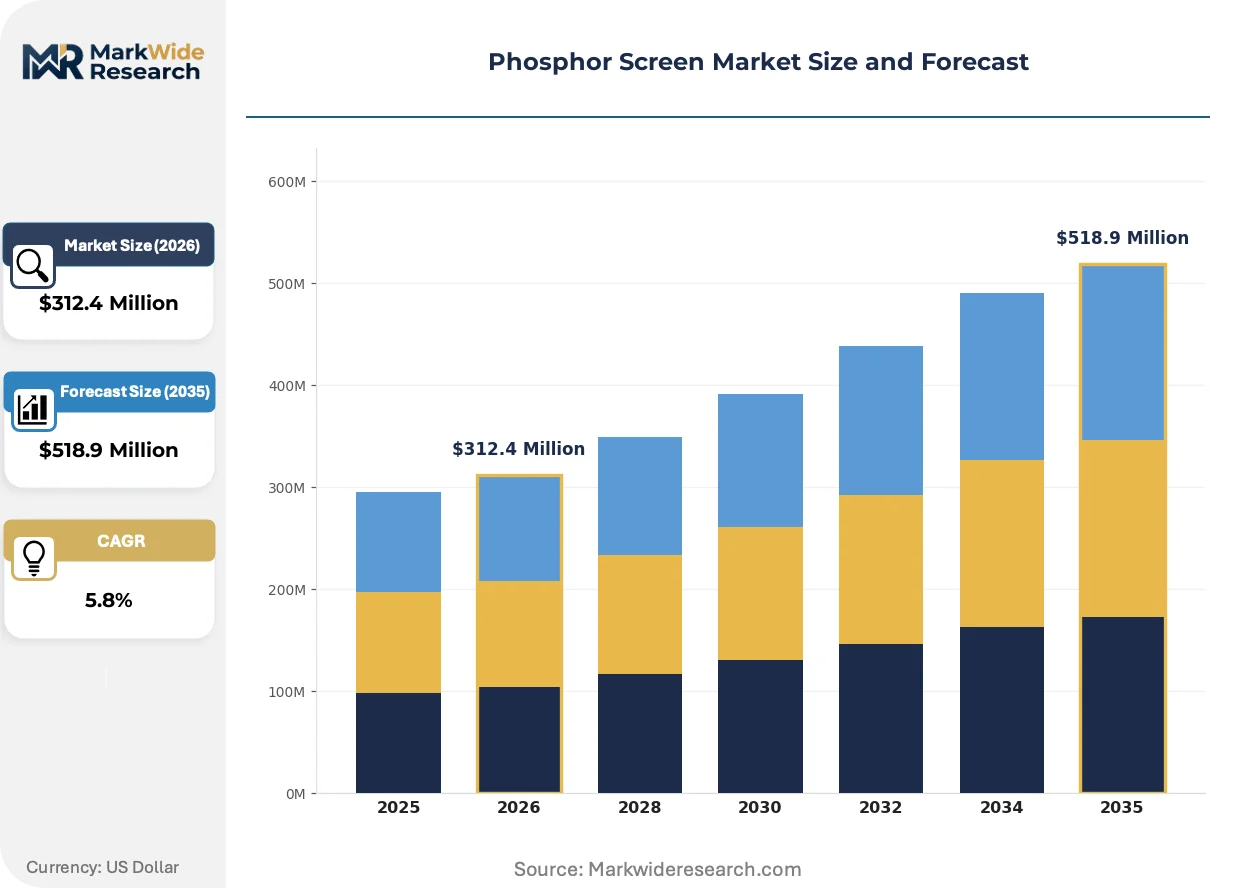
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $518.9 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inorganic Phosphors, Organic Phosphors, Hybrid Phosphors, Coating Phosphors End User: Healthcare, Consumer Electronics, Automotive, Aerospace Application: Display Technologies, Lighting Solutions, Imaging Systems, Security Systems Technology: Vacuum Deposition, Thermal Evaporation, Crystallization, Chemical Vapor Deposition |
| Companies Covered | General Electric Company, Hamamatsu Photonics K.K., Koninklijke Philips N.V., Phosphor Technology Ltd, Dr. Gassler Electron Devices, Scintacor, Konica Minolta, Inc., GIDS GmbH, Kimball Physics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Phosphor Screen Market Evolving Landscape
Computational lithography and materials informatics are compressing phosphor formulation development cycles from years to months. These tools are virtualizing traditional empirical screening while regulatory pressure on rare earth traceability intensifies supply chain documentation requirements.
Nanostructured cesium iodide scintillators with columnar crystal growth are virtualizing conventional powder phosphor layers in dental and mammography sensors. Sensor manufacturers in Japan and Germany are adopting these structures to reduce light spread and improve spatial resolution. The technology is virtualizing the trade-off between sensitivity and sharpness that constrained earlier detector designs.
Japan's METI has mandated supply chain due diligence for rare earth elements under its Resource Recycling Promotion Act, requiring phosphor manufacturers to document smelter and refiner origins. This policy is elevating compliance costs for imported concentrates while creating competitive advantage for vertically integrated domestic producers. Medical imaging component suppliers are responding by consolidating sourcing relationships and investing in spectroscopic traceability systems.
Hospital procurement departments are unbundling phosphor screen replacement cycles from full detector service contracts, creating direct component markets previously captured by OEM captive supply. Independent service organizations in the United States are capturing this disintermediated volume through refurbished detector programs. This pattern is most visible in outpatient imaging centers where capital constraints favor modular upgrade paths over system replacement.
Phosphor Screen Market Segmentation
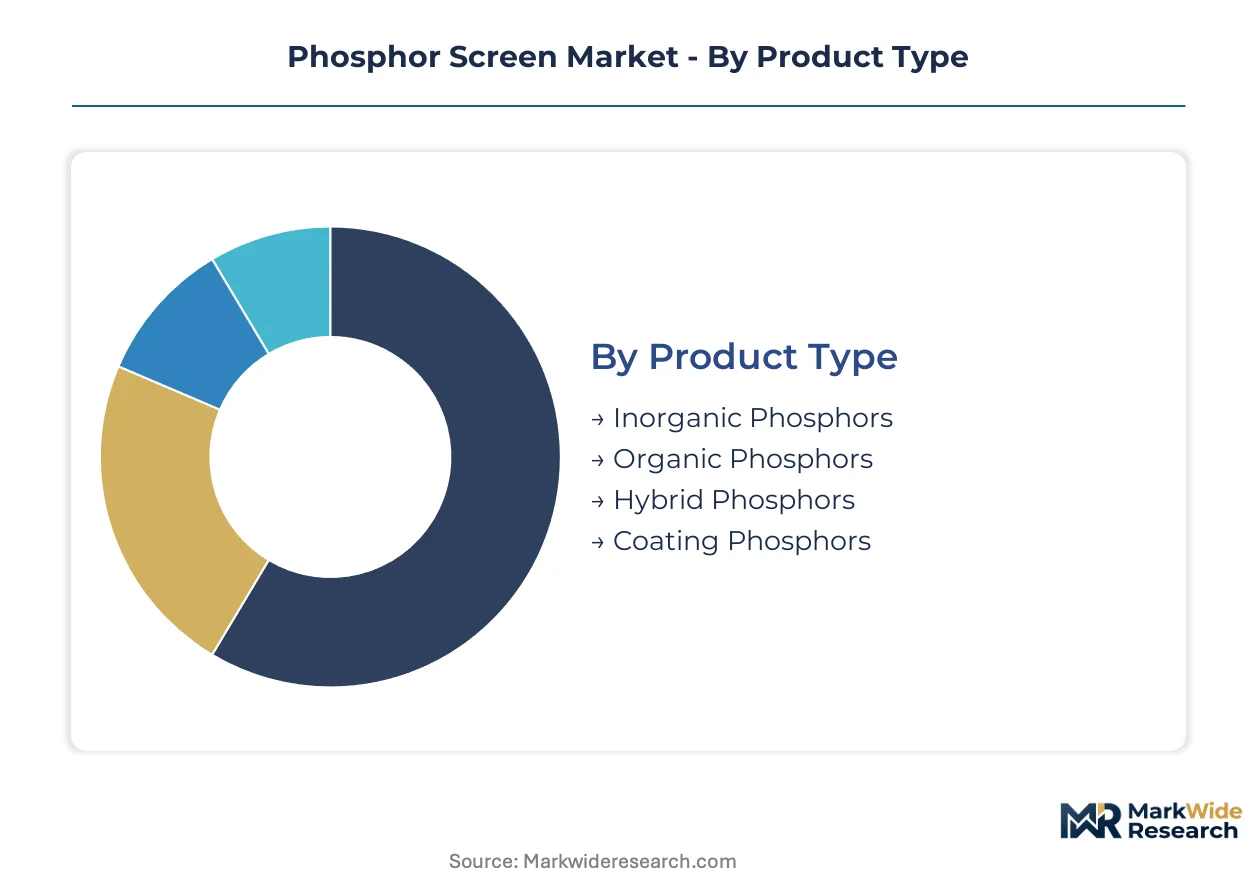
Phosphor screen procurement patterns diverge sharply across material chemistry, fabrication method, and end-use certification requirements. Segmentation clarity enables suppliers to align inventory cycles with hospital capital planning, automotive program launches, and display fab ramp schedules.
Product Type:
Replacement cycles stretch from months in experimental hybrid formulations to decades in legacy inorganic installations, creating divergent revenue recognition profiles across the category.
- Inorganic Phosphors:Crystalline compounds such as gadolinium oxysulfide and cesium iodide deliver established quantum efficiency and radiation hardness for medical imaging. German hospital systems and Japanese diagnostic equipment manufacturers sustain procurement volumes for computed radiography plates and flat-panel detectors.
- Hybrid Phosphors:Blends of organic emitters within inorganic host matrices combine solution processability with thermal stability for emerging flexible display applications. East Asian panel manufacturers are piloting these formulations for automotive head-up display programs requiring conformal coating capability.
- Organic Phosphors:Pure organic luminescent materials offer tunable emission spectra through molecular design, though limited operational lifetime constrains deployment to consumer electronics with short replacement cycles.
- Coating Phosphors:Suspension-based application methods enable rapid deposition over large areas for architectural lighting and general illumination products where cost efficiency dominates performance optimization.
Inorganic phosphors anchor the volume base while hybrid phosphors gain share at the steepest rate.
End User:
Certification intensity and performance specifications stratify sharply across customer categories, with medical applications demanding traceable supply chains absent in consumer segments.
- Healthcare:Diagnostic imaging equipment requires phosphor screens meeting PMDA purity standards and FDA quality system regulations. Hospital procurement departments in Japan and Germany are unbundling replacement cycles from full system service contracts.
- Consumer Electronics:Smartphone and television backlight units face substitution pressure from self-emissive OLED panels, compressing addressable market scope for phosphor-converted architectures.
- Automotive:Windshield projection systems and augmented reality clusters specify high-brightness phosphor layers with wide operating temperature ranges. Premium vehicle programs in Germany are accelerating qualification timelines for head-up display components.
- Aerospace:Cockpit display and radiation detection applications impose MIL-STD reliability requirements with extended qualification periods that filter out non-specialized suppliers.
Healthcare commands the largest revenue concentration while automotive expands most quickly among qualified suppliers.
Application:
Technical performance thresholds and unit economics diverge substantially across use cases, with medical imaging tolerating premium pricing for resolution and safety-critical display applications prioritizing luminance stability.
- Imaging Systems:Computed radiography and digital radiography detectors rely on phosphor screens for X-ray-to-light conversion with minimal light spread. Columnar cesium iodide structures from Japanese and German sensor manufacturers are displacing conventional powder layers in dental and mammography equipment.
- Display Technologies:Phosphor-converted backlights and direct-emission panels serve automotive, industrial, and specialty monitor segments where color gamut and thermal management specifications exceed OLED capability.
- Lighting Solutions:General illumination and architectural applications utilize coating phosphors for white-light generation from blue LED excitation, competing on lumen-per-dollar metrics against alternative down-conversion technologies.
- Security Systems:Baggage scanners and cargo inspection equipment employ high-density phosphor screens for radiation detection, with procurement concentrated in government and critical infrastructure programs.
Imaging systems generate the highest margin contribution while display technologies show the steepest volume expansion trajectory.
Technology:
Capital equipment requirements and technical workforce availability constrain manufacturing scale-up for precision deposition methods, concentrating capacity in established industrial clusters.
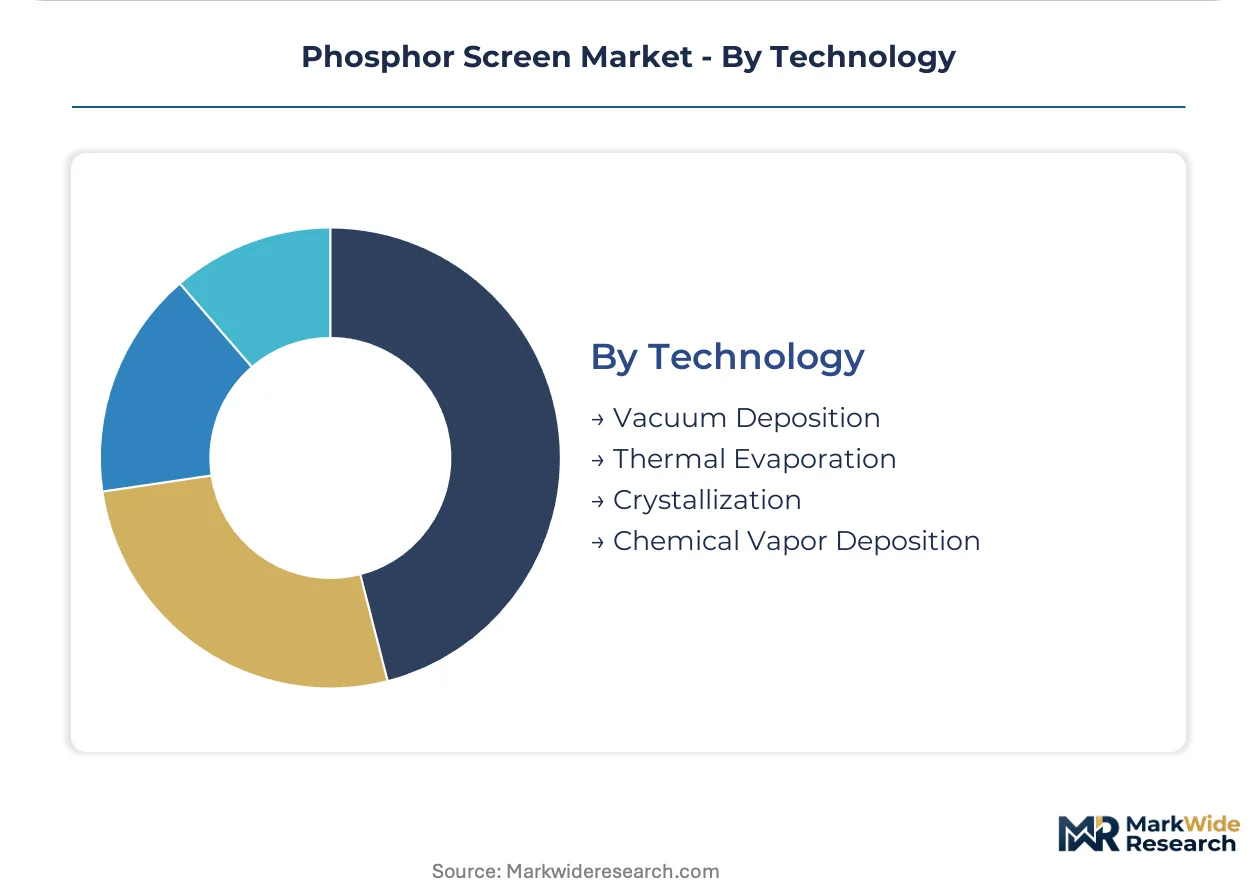
- Vacuum Deposition:Physical vapor deposition under controlled atmosphere produces uniform thin-film phosphor layers with precise thickness control for medical imaging sensors. Technician scarcity in legacy Japanese and German equipment hubs limits capacity expansion despite demand pull from hospital digitization programs.
- Thermal Evaporation:Heated source material condensation enables high-purity coating of complex substrate geometries for scientific instrumentation and aerospace applications.
- Crystallization:Controlled solidification from melt or solution generates bulk phosphor crystals for scintillation applications requiring large active volumes.
- Chemical Vapor Deposition:Gas-phase precursor reactions deposit conformal phosphor coatings over three-dimensional structures for emerging MEMS and optical component applications.
Vacuum deposition dominates current manufacturing output while chemical vapor deposition attracts the most rapid process development investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Phosphor screen fabrication concentrates in East Asian industrial clusters and German precision manufacturing hubs, with regulatory harmonization efforts reshaping cross-border component flows. Hospital digitization programs and automotive display mandates pull demand toward established supply bases while rare earth sourcing policies fragment procurement strategies.
Japan
Hamamatsu Photonics K.K. and Konica Minolta, Inc. anchor domestic production of medical-grade phosphor formulations for digital radiography detectors. METI and PMDA enforce stringent purity standards under the Resource Recycling Promotion Act, mandating documented rare earth supply chain due diligence. The Kanto region surrounding Tokyo concentrates vacuum deposition expertise for flat-panel detector manufacturing.
Germany
Hospital systems in Bavaria and North Rhine-Westphalia are scaling computed radiography plate procurement as analog film replacement accelerates. The KBA and national medical device regulations align with EU MDR requirements, elevating quality system burdens for imported phosphor components. The Stuttgart industrial corridor hosts specialized thin-film coating operations serving diagnostic equipment manufacturers.
China
East Asian display fabrication clusters in the Yangtze River Delta compress lead times for high-resolution phosphor coatings used in automotive head-up displays. NMPA tightened medical device registration rules for imaging components, aligning electromagnetic compatibility protocols with IEC 60601 standards. Shanghai-based sensor manufacturers are adopting nanostructured cesium iodide scintillators for dental and mammography equipment.
United States
Outpatient imaging centers in Texas and California are unbundling phosphor screen replacement cycles from full detector service contracts, creating direct component markets. FDA quality system regulations under 21 CFR Part 820 impose parallel certification requirements to Japanese PMDA standards. Independent service organizations in the Midwest are capturing refurbished detector volume through modular upgrade programs.
India
Domestic medical device manufacturing incentives under the PLI scheme are attracting phosphor screen assembly operations to serve South Asian imaging equipment demand. CDSCO and BIS certification requirements for diagnostic components are streamlining as the country harmonizes with international standards. The Maharashtra industrial belt around Mumbai is emerging as a hub for computed radiography plate integration.
Phosphor Screen Market Competitive Landscape
Vertically integrated conglomerates and specialized coating houses split the market into distinct capability tiers. The vendor base clusters around photonics heritage manufacturers with captive scintillation material production and independent precision deposition shops serving scientific instrumentation. Three archetypes dominate: diversified electronics conglomerates with medical imaging divisions, pure-play phosphor formulation specialists, and vacuum equipment-integrated coating service providers. Competitive moves concentrate on backward integration into rare earth sourcing and technology licensing partnerships for hybrid organic-inorganic formulations.
Among diversified industrial conglomerates, General Electric Company and Koninklijke Philips N.V. exemplify scale-driven positions spanning upstream material production through downstream imaging system integration. Hamamatsu Photonics K.K. occupies a distinct tier as a photonics-native manufacturer with in-house photomultiplier and scintillation material capabilities. Specialized houses including Scintacor and GIDS GmbH sit within the application-specific formulation segment, competing on tailored decay characteristics and emission spectra for scientific instrumentation rather than volume scale.
| Leading Market Players |
|---|
| General Electric Company |
| Hamamatsu Photonics K.K. |
| Koninklijke Philips N.V. |
| Phosphor Technology Ltd |
| Dr. Gassler Electron Devices |
| Scintacor |
| Konica Minolta, Inc. |
| GIDS GmbH |
| Kimball Physics |
| Others |
Value Network & Pricing Analysis
Overcapacity in East Asian display fabrication clusters is compressing spot pricing for high-resolution phosphor coatings while elevating bargaining power among automotive head-up display procurement teams. This utilization asymmetry between medical imaging sensor lines and consumer display coating houses is fragmenting supplier pricing postures across the value chain.
Pricing Analysis
FDA quality system regulation dictates the pricing tier structure across medical-grade phosphor screens, separating PMDA-certified premium formulations from standard diagnostic tiers and economy-grade replacement components. Three-tier pricing structure across premium, standard, and economy levels reflects differentiation by certification grade and volume scale. Cost compression in standard tiers is intensifying because OLED substitution in consumer displays is forcing phosphor suppliers to defend medical imaging margins through service bundling. Outpatient imaging centers exhibit highest price sensitivity due to capital constraints, while synchrotron facilities tolerate premium positioning for customized decay characteristics.
Supply Chain Analysis
Contract manufacturing capacity for vacuum deposition services concentrates in legacy Japanese equipment hubs and German precision coating houses, with limited expansion into Chinese Yangtze River Delta facilities. Raw material sourcing draws from Chinese rare earth concentrate suppliers for europium and terbium, Japanese cesium iodide crystal growers, and German thermal evaporation equipment fabricators. Single-source vulnerability in terbium supply chains exposes phosphor manufacturers to export quota volatility from Chinese resource policy adjustments. Distribution runs through OEM captive supply agreements for hospital systems and independent service organizations for refurbished detector programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
OLED self-emissive panel substitution in consumer electronics threatens phosphor screen incumbents, forcing defensive repositioning toward medical imaging and automotive display segments where phosphor performance advantages persist.
For Market Incumbents: Insulate core medical imaging revenue streams through backward integration into rare earth sourcing and spectroscopic traceability systems that satisfy Japan's Resource Recycling Promotion Act documentation requirements. Expand vacuum deposition technician training programs in German and Japanese equipment hubs to relieve capacity constraints constraining hospital digitization procurement. Hybrid organic-inorganic formulation R&D represents the priority capability investment to address flexible automotive display requirements. For New Entrants and Emerging Players: Pursue scientific instrumentation customization contracts with synchrotron facilities and electron microscopy labs where application-specific performance requirements filter out volume-scale competitors. India's PLI scheme for medical devices offers the most penetrable geography for phosphor screen assembly operations serving South Asian imaging equipment demand. Direct component sales to unbundled hospital procurement departments bypass OEM captive supply relationships. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated photonics manufacturers with in-house scintillation material production and established PMDA/FDA certification pathways. Long-term viability hinges on positioning upstream of rare earth traceability mandates and downstream of hospital digitization replacement cycles. Watch for NMPA electromagnetic compatibility enforcement intensity as inflection indicator for Chinese market access conditions.| Strategic Initiative | Industry Significance |
|---|---|
| Rare Earth Supply Chain Consolidation | Vertical integration into documented smelter relationships satisfies Japan's METI due diligence mandates. |
| Hybrid Formulation Development Partnership | Technology licensing agreements with East Asian panel manufacturers accelerate automotive head-up display qualification. |
| Refurbished Detector Program Expansion | Independent service organization partnerships capture unbundled phosphor screen replacement volume from outpatient imaging centers. |
| Vacuum Deposition Technician Training | Workforce development in German and Japanese equipment hubs relieves capacity constraints limiting hospital digitization supply. |
| Spectroscopic Traceability System Investment | Spectroscopic origin verification infrastructure addresses Resource Recycling Promotion Act compliance cost elevation. |
Research Methodology
The analysis maps inorganic phosphor formulations, hybrid organic-inorganic blends, vacuum deposition processes, and thermal evaporation techniques, each validated through phosphor formulation chemists, hospital biomedical engineers, diagnostic equipment procurement managers, and automotive display program directors. Primary interview insights triangulate against secondary validation from FDA 510(k) filings, PMDA approval databases, NMPA medical device registration records, and SEC 10-K disclosures from listed imaging equipment manufacturers. Bottom-up phosphor screen shipment estimates and top-down imaging equipment production data converge through iterative reconciliation.
Assumptions hold rare earth concentrate pricing volatility within historical bands, regulatory harmonization progressing without abrupt reversal, and OLED substitution rates in consumer displays following observed trajectories. Segmentation dimensions modeled span material chemistry, fabrication technology, end-use certification intensity, and regional regulatory cluster across the projection horizon. CAGRs derive from fitted growth curves applied to hospital capital expenditure cycles, automotive program launch schedules, and display fab ramp timelines. Forecast inputs incorporate PACS architecture retrofit adoption rates and nanostructured cesium iodide displacement curves for dental and mammography sensors.
The forecast holds incumbent behavior within observed patterns; aggressive backward integration moves by diversified industrial conglomerates or sudden rare earth export quota tightening would shift outcomes. Forecasts reflect assumptions about technician training pipeline expansion and regulatory documentation burden trajectory. Quarterly review of NMPA enforcement intensity, METI supply chain audit frequency, and hospital procurement unbundling rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Display Technologies
Wireless Display Market
Display Technologies
Europe Transparent Conductive Films Market
Display Technologies
3D Holographic Display Market
Display Technologies
DLP Projector Market
Display Technologies
Global UHD Display Market
Display Technologies
Flexible OLED Market
Display Technologies
Tablets and Notebook Display Market
Display Technologies
Global Next Generation Display Market
Display Technologies
Display Material Market
Display Technologies
Electronic Display Signs Market
Display Technologies
Smart Privacy Glass Market
Display Technologies
Low Power Next Generation Display Market
Display Technologies
Display Port Market
Display Technologies
Display Control and Management System Market
Display Technologies
Touch and Display Integration IC for Tablet Market
Display Technologies
Automotive LCD Display Market