
 Anti-Plagiarism for the Education Sector Market | 2026-2036
Anti-Plagiarism for the Education Sector Market Size, Share, and Industry Trends Forecast 2026-2036
Anti-Plagiarism for the Education Sector Market Intelligence
The EU AI Act is expanding compliance obligations for educational institutions deploying automated content verification, forcing procurement teams to evaluate algorithmic transparency in detection platforms. Turnitin LLC leverages its institutional relationships and massive submission database to sustain competitive moats in North American higher education. Grammarly Inc. competes across grammar verification and originality checking, while Copyleaks Technologies Ltd. specializes in multilingual detection and generative AI identification.
Anti-plagiarism for the education sector encompasses software systems that compare submitted content against indexed repositories using string-matching algorithms, stylometric analysis, and neural pattern recognition to flag unattributed duplication; these platforms typically process documents through natural language parsing engines that generate similarity scores and source attribution reports. Cloud-based deployment leads adoption among resource-constrained K-12 districts seeking minimal IT overhead, while text-matching solutions dominate revenue due to their maturity and integration with learning management systems. Source tracking and content fingerprinting represent faster-growing categories as institutions confront synthetic text from large language models.
The U.S. Department of Education, alongside regional accreditors, shapes procurement through research integrity mandates that require documented originality verification for thesis submissions and grant applications. GDPR in Europe and the EU AI Act impose additional constraints on data retention and automated decision-making, compelling vendors to re-architect processing pipelines. Stakeholders must monitor evolving generative AI detection standards and decide whether to consolidate around integrated platforms or maintain specialized point solutions for distinct verification tasks.
Market Dynamics
The collision between generative AI proliferation and regulatory mandates for academic integrity is forcing educational institutions to rebuild their content verification infrastructure from string-matching foundations toward neural detection architectures.
Growth Catalysts
- EU AI Act compliance deadlines:European universities face binding requirements for algorithmic transparency in automated assessment systems, compelling procurement of auditable detection platforms.
- Large language model text infiltration:Synthetic essay submissions from ChatGPT, Claude, and Gemini are flooding admissions offices and coursework portals, accelerating detection tool deployment.
- Federal research integrity mandates:US funding agencies require documented originality verification for thesis submissions and grant applications, institutionalizing procurement budgets.
Market Restraints
- Computational infrastructure costs:Neural pattern recognition engines demand GPU clusters that strain IT budgets at resource-constrained K-12 districts.
- Vendor concentration in cloud services:AWS, Azure, and Google Cloud control the backbone infrastructure for most detection platforms, creating single-point vulnerability.
- False positive rate limitations:Stylometric analysis algorithms generate attribution errors that trigger faculty resistance and procurement delays.
Strategic Opportunities
- India's accreditation expansion:The country's higher education regulator is mandating originality verification for all affiliated institutions, opening a 40-million-student addressable base.
- Multilingual detection convergence:Cross-lingual embedding models paired with source fingerprinting unlock verification for non-English academic submissions.
- Learning management system integration:Canvas, Blackboard, and Moodle API partnerships create embedded distribution channels that bypass standalone procurement cycles.
Industry Challenges
- Computational linguistics talent scarcity:The shortage of engineers trained in adversarial NLP and stylometric feature engineering constrains product development velocity.
- Legacy LMS integration complexity:Decades-old campus information systems require custom middleware that extends deployment timelines and inflates implementation costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anti-Plagiarism for the Education Sector Market |
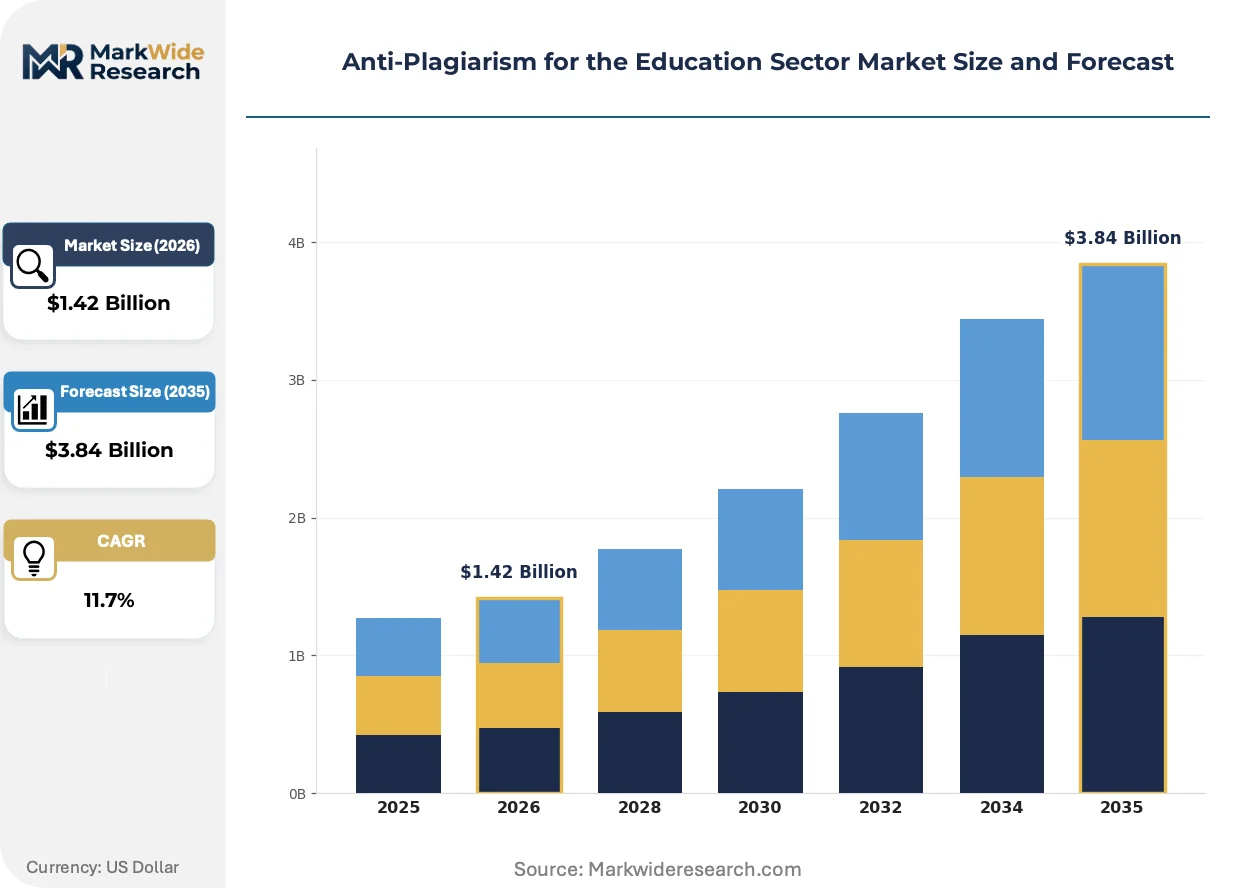
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $3.84 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, SaaS, Web-Based Solution Type: Text-Matching, Source Tracking, Content Fingerprinting, Citation Checking, Grammar Verification Application: Higher Education, Online Learning Platforms, K-12 Institutions, Professional Certification Programs, Language Schools End User: Academic Researchers, University Administrators, School Educators, Exam Boards, Curriculum Developers |
| Companies Covered | Turnitin LLC, Grammarly Inc., Copyleaks Technologies Ltd., PlagScan GmbH, Academicplagiarism Inc., Blackboard Inc., Urkund, Originality.ai, Scribbr, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anti-Plagiarism for the Education Sector Market Strategic Shifts & Innovations
Generative AI detection is fragmenting into specialized modalities as institutions confront synthetic text, image, and code submissions through unified verification pipelines.
Adversarial watermarking technology is expanding into higher education procurement workflows. These embedding schemes imprint imperceptible signals into AI-generated text at the source. Turnitin and Copyleaks are racing to integrate detection APIs that read these watermarks. The structural consequence is a bifurcation between source-side and post-hoc detection methodologies.
The EU AI Act's risk classification framework is compelling vendors to re-architect processing pipelines for European deployments. Automated content verification systems now face mandatory human oversight requirements and data retention limits. German and French universities are demanding algorithmic impact assessments before procurement approval.
Subscription fatigue among procurement officers is consolidating purchasing authority toward integrated platforms. Standalone grammar checkers and citation tools are losing budget allocation to suites bundling originality verification. This concentration is most visible in US public university systems centralizing contracts at state-level consortiums.
Anti-Plagiarism for the Education Sector Market Segmentation
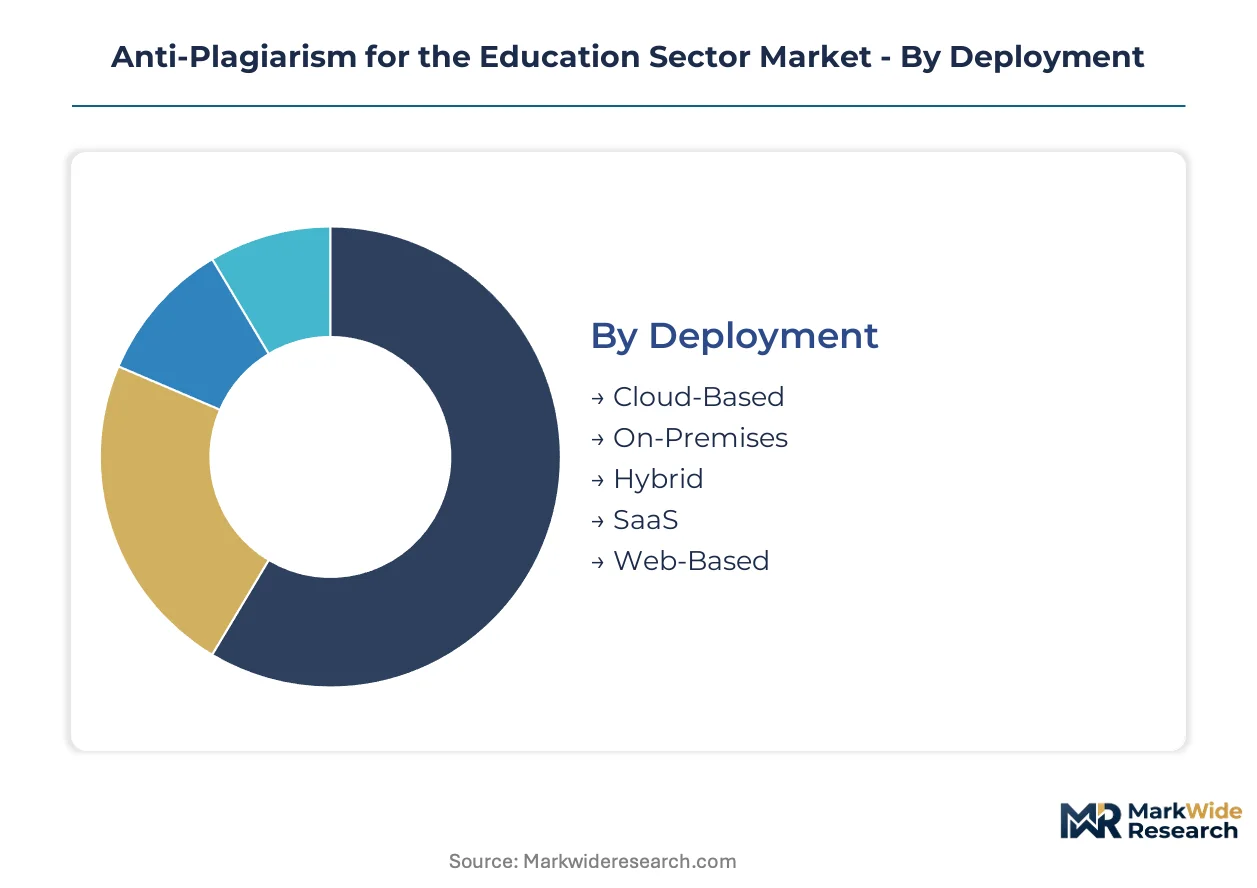
Procurement patterns in anti-plagiarism systems diverge sharply across deployment models, solution architectures, and institutional tiers. Understanding these fault lines reveals where vendor margins concentrate and which segments absorb the bulk of R&D investment.
Deployment:
Capital intensity varies dramatically across deployment architectures, with on-premises installations demanding server infrastructure and perpetual licensing while cloud alternatives shift costs to operational expenditure.
- Cloud-Based:Multi-tenant architectures run on AWS, Azure, or Google Cloud infrastructure, eliminating hardware procurement for resource-constrained districts. K-12 systems in the United States favor this model for minimal IT overhead and automatic feature updates.
- On-Premises:Dedicated server installations within institutional data centers process submissions locally, satisfying GDPR data residency mandates for German and French universities. High upfront licensing and hardware costs limit adoption to well-capitalized research universities.
- Hybrid:Split architectures keep sensitive submissions on local servers while routing routine scans to cloud endpoints. European institutions deploying under EU AI Act constraints use this model to balance compliance with computational scalability.
- SaaS:Subscription-delivered platforms with API-first architectures embed directly into Canvas, Blackboard, and Moodle workflows. Procurement teams value predictable annual costs and rapid deployment timelines.
- Web-Based:Browser-accessible portals requiring no local installation serve individual educators and small language schools with limited procurement authority. Feature depth lags behind enterprise alternatives.
Cloud-Based deployments absorb the bulk of installed capacity; Hybrid architectures are expanding most quickly as European compliance requirements harden.
Solution Type:
Technology maturity separates legacy string-matching engines from emerging neural architectures, with development velocity concentrating in modalities addressing generative AI infiltration.
- Text-Matching:String-comparison algorithms against indexed repositories dominate revenue due to LMS integration maturity and faculty familiarity. Turnitin built its market position on this foundation.
- Source Tracking:Provenance verification systems map attribution chains across digital documents, gaining traction among US research universities facing federal funding agency mandates for documented originality verification.
- Content Fingerprinting:Neural embedding models generate unique signatures for synthetic text detection, addressing ChatGPT and Claude submissions flooding admissions offices. GPU inference costs constrain K-12 adoption.
- Citation Checking:Automated bibliography verification against Crossref and PubMed databases serves thesis committees and grant review panels. Integration with reference managers drives procurement decisions.
- Grammar Verification:Stylometric analysis engines flag writing inconsistencies, though false positive rates trigger faculty resistance. Bundling with originality suites is displacing standalone procurement.
Text-Matching solutions command the largest revenue share; Content Fingerprinting is climbing the fastest as institutions confront large language model submissions.
Application:
Institutional scale and regulatory exposure determine solution sophistication requirements, with research-intensive universities demanding enterprise-grade audit trails that online platforms rarely need.
- Higher Education:Doctoral-granting institutions require comprehensive verification pipelines for thesis repositories and grant applications. US accreditation standards and federal research integrity mandates institutionalize procurement budgets.
- Online Learning Platforms:Massive enrollment scales demand API-native architectures with per-submission pricing. Coursera and edX integration requirements shape vendor product roadmaps.
- K-12 Institutions:District-wide deployments prioritize administrative simplicity and parent communication features. State-level consortium purchasing in the United States concentrates vendor selection authority.
- Professional Certification Programs:High-stakes exam integrity drives demand for proctored verification environments. Medical and legal credentialing bodies specify the strictest detection standards.
- Language Schools:Multilingual detection requirements and lower submission volumes favor lightweight web-based tools. IELTS and TOEFL preparation centers represent a fragmented addressable base.
Higher Education channels the greatest procurement volume; Online Learning Platforms are gaining share fastest as enrollment scales shift toward digital delivery.
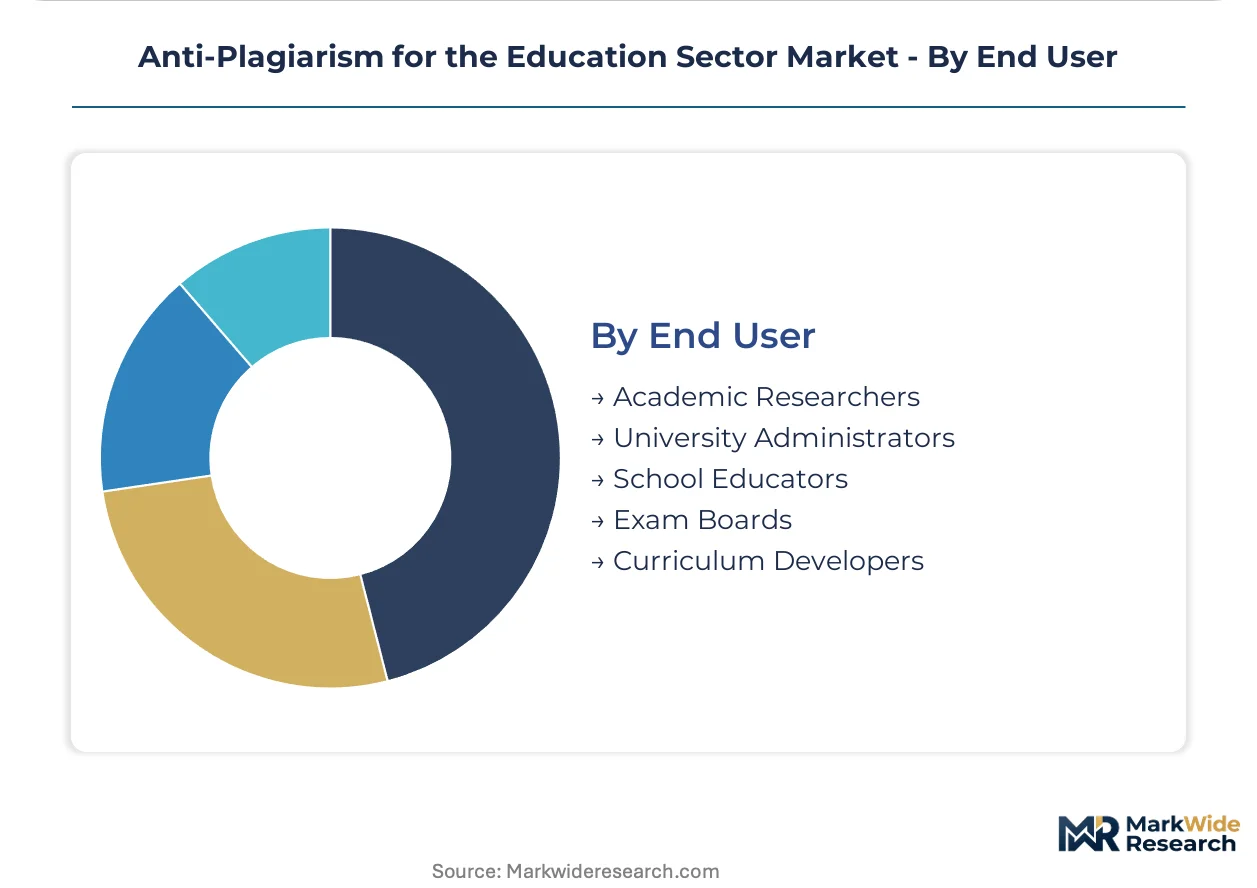
End User:
Decision-making authority and technical sophistication vary across stakeholder types, with centralized IT procurement diverging from individual educator purchasing patterns.
- Academic Researchers:Principal investigators require verification tools for manuscript submissions and grant applications. Journal publisher mandates and funding agency requirements drive adoption.
- University Administrators:CIOs and procurement officers negotiate enterprise contracts covering entire institutions. Accreditation compliance and risk management frame vendor evaluation criteria.
- School Educators:Individual teachers seek classroom-level tools with minimal setup friction. Parent communication features and student privacy controls influence selection.
- Exam Boards:High-stakes assessment organizations demand forensic-grade detection with legal defensibility. Custom integration with legacy scoring systems extends implementation timelines.
- Curriculum Developers:Instructional designers embed originality verification into course authoring workflows. LMS-native functionality outweighs standalone feature depth.
University Administrators control the largest procurement budgets; Academic Researchers are expanding their influence fastest as publisher mandates proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston anchors North American edtech procurement, where MIT and Harvard procurement offices shape detection platform requirements for research-intensive universities.
United States
Federal research integrity mandates from the Department of Education and National Science Foundation institutionalize originality verification budgets across doctoral-granting institutions. Regional accreditors in the Northeast and Midwest require documented plagiarism detection for thesis repositories. The Research Triangle in North Carolina concentrates deployment activity, where Duke University and UNC Chapel Hill procurement offices negotiate enterprise contracts.
Germany
German universities confront binding EU AI Act compliance deadlines for algorithmic transparency in automated assessment systems. GDPR data residency requirements favor on-premises or hybrid deployment architectures. The Baden-Württemberg cluster around Stuttgart and Heidelberg drives procurement volume, where technical universities mandate auditable detection pipelines for engineering thesis submissions.
India
The University Grants Commission mandates originality verification for all affiliated institutions, opening procurement pipelines across a 40-million-student addressable base. National accreditation reforms require documented similarity checking for research publications. The Bengaluru-Hyderabad corridor concentrates vendor activity, where Indian Institute of Science and IIT procurement offices evaluate multilingual detection platforms.
United Kingdom
UK Research and Innovation funding mandates shape institutional procurement priorities for grant application verification. The Office for Students pressures universities to demonstrate academic integrity investment. The Golden Triangle of London, Oxford, and Cambridge concentrates enterprise contract value, where collegiate university structures create fragmented but high-value procurement opportunities.
Australia
Tertiary Education Quality and Standards Agency audit requirements institutionalize detection tool procurement across Group of Eight universities. Research integrity codes from the Australian Research Council mandate documented originality verification. The Melbourne-Sydney corridor dominates contract value, where Monash University and UNSW procurement offices evaluate integrated LMS-native solutions.
Anti-Plagiarism for the Education Sector Market Key Industry Players
Premium-margin players sit above commodity-margin players across data asset depth and institutional relationship tenure. The market structures around three tiers: established platforms with massive submission databases, grammar-verification suites extending into originality checking, and specialized entrants focused on generative AI detection. Strategic moves concentrate on LMS API partnerships and adversarial watermarking integration rather than direct price competition.
Within the established platform tier, Turnitin LLC and Grammarly Inc. occupy positions defined by institutional penetration scale. Copyleaks Technologies Ltd. exemplifies the specialized detection archetype. These three entities represent divergent strategic bets: database depth versus workflow integration versus multimodal synthetic content identification.
| Leading Market Players |
|---|
| Turnitin LLC |
| Grammarly Inc. |
| Copyleaks Technologies Ltd. |
| PlagScan GmbH |
| Academicplagiarism Inc. |
| Blackboard Inc. |
| Urkund |
| Originality.ai |
| Scribbr |
| Others |
Cost & Logistics Intelligence
GDPR data residency mandates gate both qualified supply and premium-tier pricing access for European higher education institutions, forcing vendors to architect hybrid deployment pipelines that carry 40-60% cost premiums over standard cloud configurations. Procurement officers in Germany and France absorb these premiums to satisfy algorithmic transparency requirements under the EU AI Act, while K-12 districts in the United States gravitate toward stripped-down SaaS tiers that trade feature depth for predictable annual expenditure.
Pricing Analysis
Per-submission throughput pricing anchors vendor revenue models, with enterprise contracts scaling from individual educator subscriptions below five hundred dollars annually to multi-campus agreements reaching six figures. Price differentiation rests on audit trail granularity and LMS integration depth, with Canvas-native deployments commanding fifteen to twenty percent premiums over standalone portal access. Cost compression in the K-12 tier intensifies because state-level consortium purchasing aggregates bargaining power. University administrators exhibit lowest price sensitivity where federal research integrity mandates institutionalize detection budgets.
Supply Chain Analysis
India's domestic-content mandates for educational technology procurement are reshaping sourcing patterns, compelling vendors to establish local data processing nodes for the country's forty-million-student addressable base. GPU inference hardware concentrates in Taiwan, South Korea, and the United States, while cloud backbone infrastructure draws from AWS, Azure, and Google Cloud data centers across twelve countries. Single-source vulnerability in NVIDIA chip supply creates procurement risk for neural detection platforms. Distribution runs through learning management system API partnerships that embed verification directly into Canvas, Blackboard, and Moodle workflows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Computational linguistics talent scarcity props pricing for adversarial NLP engineering roles, constraining product development velocity across the vendor landscape and preserving margin structures for established platforms with captive technical teams.
For Market Incumbents: Cement institutional relationships through exclusive LMS integration partnerships that raise switching costs for rival platforms. Deepen backward integration into proprietary embedding model development to reduce dependency on open-source transformer architectures. The proliferation of specialized generative AI detection entrants threatens database-scale advantages unless incumbents accelerate adversarial watermarking API integration.
For New Entrants and Emerging Players: Begin with multilingual detection capabilities targeting India's accreditation expansion, where the University Grants Commission mandates originality verification across affiliated institutions. The language school segment presents lowest competitive density and shortest procurement cycles. A per-submission pricing model with minimal implementation friction unlocks rapid trial adoption before enterprise upsell.
For Investors and Strategic Acquirers: EU AI Act enforcement actions against non-compliant detection platforms are the leading indicator that regulatory technology moats will consolidate market share toward auditable vendors. Five-to-ten-year viability favors platforms with established submission databases exceeding one billion documents. Watch for German and French university procurement offices mandating algorithmic impact assessments as the inflection signal for compliance-premium pricing acceptance.
| Strategic Initiative | Industry Significance |
|---|---|
| Adversarial Watermarking API Integration | Turnitin and Copyleaks race to embed detection capabilities for AI-generated text signals. |
| LMS Native Partnership Expansion | Canvas, Blackboard, and Moodle API access creates embedded distribution bypassing standalone procurement. |
| Hybrid Deployment Architecture Launch | European GDPR compliance drives split-processing pipelines balancing data residency with cloud scalability. |
| Multilingual Detection Platform Development | Cross-lingual embedding models unlock verification for India's non-English academic submissions. |
| Generative AI Detection Specialist Acquisition | Originality.ai and similar entrants offer neural pattern recognition assets absent from legacy string-matching platforms. |
Research Approach
Multi-period observation of procurement contract values, LMS integration announcements, and regulatory compliance deadlines anchored the trend analysis, supplemented by interviews with chief information officers at doctoral-granting institutions, edtech procurement officers in state university systems, computational linguistics researchers, and learning management system product managers. Secondary validation drew from U.S. Department of Education policy filings, EU AI Act implementation guidance, University Grants Commission circulars, and SEC disclosures from publicly traded education technology firms. Bottom-up segment sizing triangulated against top-down market envelope estimates.
Input-output matrices mapped deployment model adoption rates, solution type penetration curves, and institutional tier spending patterns across the projection horizon. Segmentation dimensions modeled encompassed cloud versus on-premises versus hybrid architectures, text-matching versus neural detection modalities, and higher education versus K-12 versus online platform end markets. CAGRs derived from logistic diffusion curves fitted to historical adoption benchmarks in adjacent educational software categories. Forecast inputs incorporated GPU cost decline trajectories and accreditation mandate implementation timelines.
Underlying measurement precision varies by segment; higher education procurement data carries tighter precision than fragmented language school adoption. Forecasts reflect assumptions regarding EU AI Act enforcement intensity and generative AI infiltration rates that could revise projections if regulatory timelines accelerate or detection accuracy thresholds shift. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Student Information System Market
Software & Services
Global Technical Illustration Software Market
Software & Services
Global Offshore Software Development Market
Software & Services
Web Framework Software Market
Software & Services
Mobile Tracking Software Market
Software & Services
Latin America Cloud Workforce Management Software Market
Software & Services
Live Chat Software Market
Software & Services
Waterway Transportation Software Solutions Market
Software & Services
Stone Analysis Software Market
Software & Services
Global Text to Speech (TTS) Software Market
Software & Services
Middle-East Virtual Data Room Market
Software & Services
IT Professional Services Market
Software & Services
User Retention Software Market
Software & Services
Paraphrasing Tools Market
Software & Services
Digital Illustration App Market
Software & Services
Global Website Builder Software Market