
 Web Framework Software Market | 2026-2036
Web Framework Software Market Size, Share, and Industry Trends Forecast 2026-2036
Web Framework Software Market Intelligence
Platform licensing revenue is fragmenting between framework core distributions and managed deployment services. Meta sustains technology leadership through React's component ecosystem and backward compatibility guarantees. Google dominates enterprise Angular deployments with deep tooling integration across its cloud stack. Vercel differentiates by controlling the serverless edge runtime layer adjacent to its Next.js framework.
Web framework software comprises reusable code libraries, runtime environments, and tooling conventions that standardize server request handling, routing, state management, and UI rendering across distributed applications. These systems typically expose APIs for database abstraction, middleware chaining, and template compilation, serving to reduce boilerplate code and enforce architectural patterns in commercial software production. Full-stack frameworks anchor the largest installed base by unifying frontend and backend logic, while component-based variants capture the fastest expansion as micro-frontend architectures proliferate across enterprise codebases. Cloud-based deployment models concentrate margin pools through recurring platform fees, whereas on-premises installations retain traction in financial services and telecommunications sectors with stringent data residency requirements.
The EU AI Act and GDPR impose algorithmic accountability and cross-border data flow constraints that framework vendors must embed into routing and middleware layers. The US FCC and SEC scrutiny of digital platform liability further shapes how open-source frameworks structure commercial support and indemnification offerings. Stakeholders must monitor whether regulatory fragmentation between Brussels and Washington forces divergence in framework compliance architectures or sustains demand for jurisdiction-agnostic deployment abstractions.
Market Dynamics
Component-based architectures are fragmenting the traditional full-stack framework installed base as enterprises decompose monolithic applications into independently deployable micro-frontends.
Growth Catalysts
- EU AI Act:Algorithmic accountability mandates in Brussels are forcing framework vendors to embed explainability hooks and audit logging into routing layers, creating upgrade cycles across European enterprise deployments.
- Micro-frontend architectures:Component-based variants are capturing expansion as fintech and health-tech clusters in San Francisco and New York demand modular codebases that enable team autonomy.
- Edge computing:Serverless runtime layers adjacent to frameworks are compressing latency for real-time applications, with managed deployment services concentrating recurring platform fees.
Market Restraints
- Skill scarcity:The shallow talent pool for Rust and WebAssembly optimization constrains adoption of high-performance framework variants despite their technical superiority.
- Supply concentration:Cloud-based deployment models concentrate margin pools through recurring platform fees, locking enterprises into vendor-specific runtime abstractions with limited portability.
- GDPR friction:Cross-border data flow constraints impose middleware complexity that inflates engineering overhead for multi-region SaaS providers.
Strategic Opportunities
- Financial services:On-premises installations retain traction in US and European banking sectors with stringent data residency requirements, creating demand for jurisdiction-agnostic deployment abstractions.
- WebAssembly-React convergence:The fusion of near-native execution speeds with established component ecosystems opens performance-critical applications previously closed to JavaScript frameworks.
- India's PLI scheme:Domestic software product incentives are nurturing indigenous framework vendors targeting cost-sensitive enterprise segments across South Asia.
Industry Challenges
- Backward compatibility maintenance:Framework vendors face escalating engineering burden sustaining long-term support for deprecated APIs while pushing innovation cycles.
- Regulatory fragmentation:Divergence between Brussels algorithmic transparency requirements and Washington liability frameworks forces compliance architecture duplication.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Web Framework Software Market |
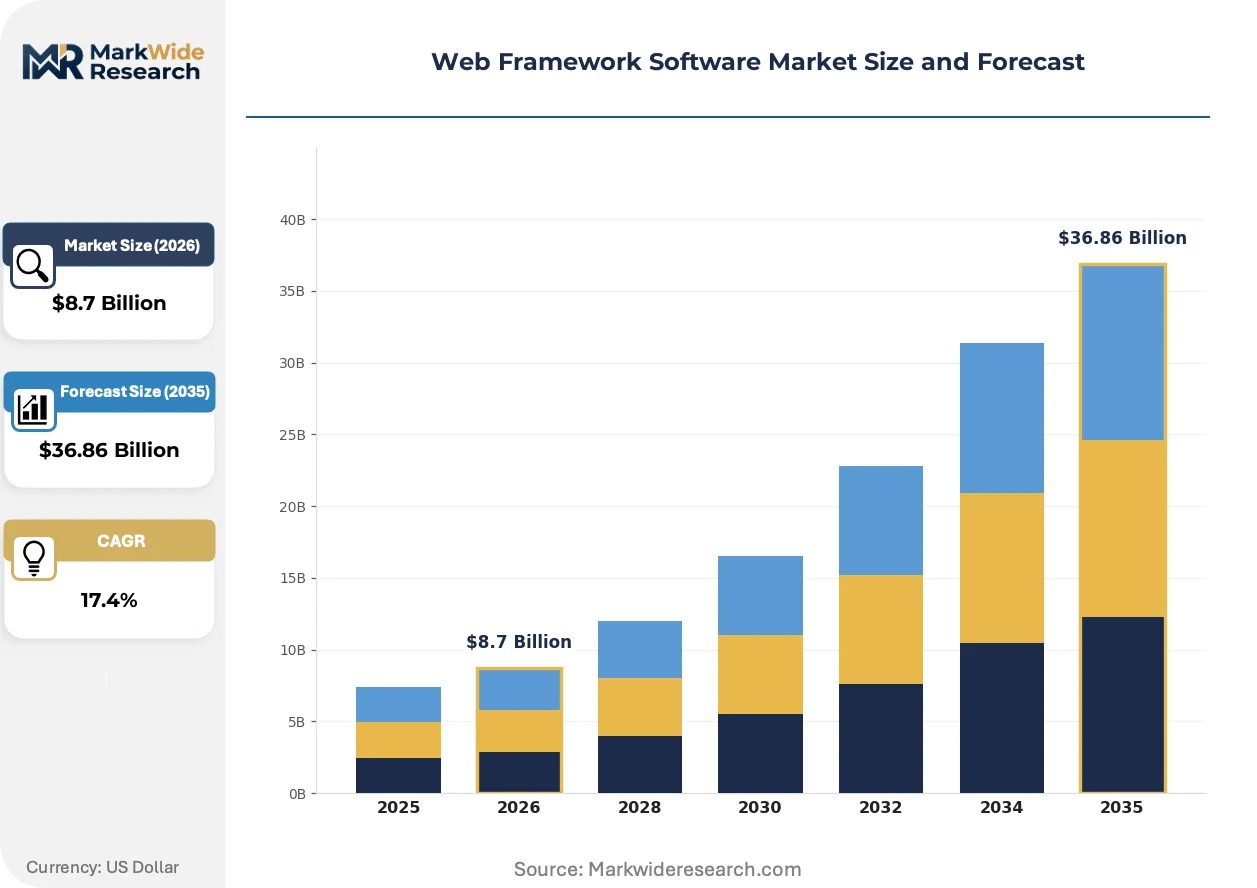
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $36.86 Billion |
| CAGR (2026 – 2036) | 17.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Framework Type: Full-Stack, Microframework, Asynchronous, Component-Based, Real-Time, Modular Programming Language: JavaScript, Python, Ruby, PHP, Java, TypeScript Deployment Model: Cloud-Based, On-Premises, Hybrid, Serverless, Containers, Edge Computing Target Industry: eCommerce, Media & Entertainment, Education Technology, Financial Services, Travel & Hospitality, Telecommunications |
| Companies Covered | Acquia (Drupal), Remix Software (Remix), Meta (React), Astro Technology (Astro), NestJS (NestJS), Google (Angular), Vercel (Next.js), Laravel (Laravel), Automattic (WordPress), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Web Framework Software Market Strategic Shifts & Innovations
Server-side rendering patterns are re-emerging as performance and search engine discoverability requirements override pure client-side execution models in enterprise SaaS development.
Isomorphic JavaScript execution is rendering obsolete the hard separation between frontend and backend codebases that dominated the 2010s SPA era. Enterprise SaaS providers in fintech and health-tech clusters are adopting Next.js and Nuxt.js architectures at accelerating pace. This convergence is compressing full-stack team structures and collapsing the distinction between frontend specialists and backend engineers.
GDPR and the EU AI Act are imposing algorithmic accountability and cross-border data flow constraints that framework vendors must embed into routing and middleware layers. The industrial consequence is mandatory audit logging and explainability hooks that inflate framework complexity. European enterprise deployments are responding by prioritizing vendors with pre-certified compliance architectures over raw performance benchmarks.
Consumption patterns are shifting from perpetual open-source adoption toward recurring platform fees for managed deployment and edge runtime services. The channel being disrupted is self-hosted infrastructure management, replaced by serverless abstraction layers controlled by framework-adjacent platforms. This shift is most visible in United States fintech clusters where engineering velocity trumps infrastructure ownership.
Web Framework Software Market Segmentation
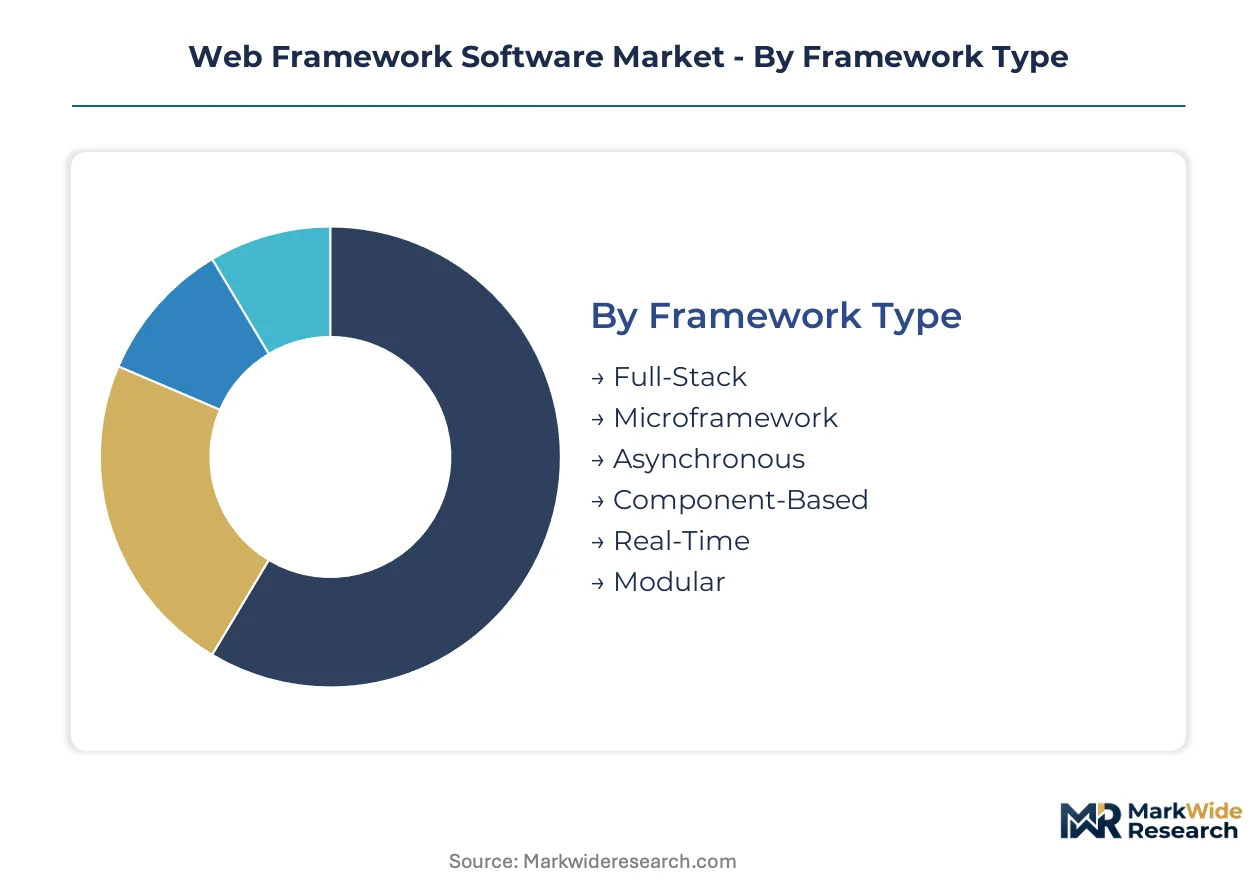
Segmentation in web framework software reveals how architectural choices, infrastructure constraints, and industry compliance requirements fragment purchasing behavior. Vendors must align feature roadmaps with the specific performance, security, and deployment mandates of each cluster.
Framework Type:
The maturity spectrum spans from established full-stack architectures to emerging real-time and modular variants that address specialized latency and team-autonomy requirements.
- Full-Stack:Unified frontend-backend codebases dominate enterprise SaaS production with pre-integrated ORM, templating, and session management. United States fintech clusters in San Francisco and New York favor these for rapid team consolidation and reduced stack complexity.
- Component-Based:Micro-frontend decomposition enables independent deployment of UI modules by autonomous product teams. Health-tech clusters in New York adopt these architectures to accelerate release velocity while maintaining design system consistency across distributed engineering organizations.
- Microframework:Minimalist routing and middleware layers suit lightweight API services and prototyping pipelines.
- Asynchronous:Event-loop concurrency patterns optimize I/O-bound workloads in high-throughput data ingestion scenarios.
- Real-Time:WebSocket-native architectures support collaborative editing and live data streaming applications.
- Modular:Pluggable core systems allow selective feature activation for resource-constrained edge deployments.
Full-Stack retains volume leadership; Component-Based holds the steepest expansion curve.
Programming Language:
Cost-tier stratification separates premium TypeScript tooling ecosystems from economy-tier PHP deployments in cost-sensitive hosting environments.
- JavaScript:Browser-native execution and npm ecosystem depth sustain the largest installed base across consumer-facing applications. European enterprises under GDPR constraints prioritize JavaScript frameworks with established audit-logging middleware from vendors with Brussels compliance pre-certification.
- TypeScript:Static type safety at scale drives adoption in financial services codebases where refactoring confidence reduces regulatory review cycles. United States banking sectors migrating from legacy Java stacks favor TypeScript for its gradual migration path and IDE integration depth.
- Python:Data science integration and Django's administrative scaffolding dominate education technology and research tooling deployments.
- Ruby:Convention-over-configuration philosophy sustains boutique agency workflows and rapid prototyping engagements.
- PHP:Shared-hosting compatibility and WordPress ecosystem lock-in retain massive WordPress-adjacent plugin market share.
- Java:Spring Boot's enterprise integration patterns dominate telecommunications and legacy system modernization pipelines.
JavaScript commands the broadest deployment footprint; TypeScript is climbing the fastest among enterprise migrations.
Deployment Model:
Customer-type differentiation separates cloud-native SaaS builders from on-premises financial services institutions with data residency mandates.
- Cloud-Based:Managed infrastructure abstraction eliminates operational overhead for engineering-velocity-focused teams. United States fintech startups in San Francisco clusters adopt cloud-based deployment to compress time-to-market for payment processing applications.
- Serverless:Event-driven billing and automatic scaling align cost structures with unpredictable traffic patterns in media and entertainment viral content scenarios.
- On-Premises:Physical hardware control satisfies GDPR data sovereignty requirements and SEC audit trail mandates in US and European banking sectors.
- Hybrid:Split workload placement optimizes latency-sensitive operations at edge while centralizing analytics in cloud cores.
- Containers:Kubernetes orchestration standardizes packaging across multi-cloud and development-to-production pipelines.
- Edge Computing:Sub-50ms latency requirements for real-time gaming and IoT telemetry push compute toward CDN nodes.
Cloud-Based sustains the dominant revenue pool; Serverless is gaining share fastest among venture-backed application startups.
Target Industry:
Application-specific requirements drive divergence in security certification, compliance middleware, and performance benchmarking priorities.
- Financial Services:PCI-DSS and SOX compliance frameworks mandate encrypted session handling and immutable audit logging. United States banking sectors in New York and Chicago demand frameworks with pre-built compliance modules to accelerate regulatory approval timelines.
- eCommerce:Cart abandonment optimization and payment gateway integration depth determine framework selection for conversion-critical storefronts.
- Media & Entertainment:Adaptive bitrate streaming and DRM plugin architectures prioritize frameworks with extensible middleware chaining.
- Education Technology:Accessibility standards and multi-tenant isolation for student data shape procurement criteria.
- Travel & Hospitality:Global distribution system integrations and multi-currency transaction handling dominate technical requirements.
- Telecommunications:5G network function virtualization and subscriber data management impose carrier-grade reliability benchmarks.
Financial Services anchors premium pricing tiers; eCommerce is expanding most quickly as direct-to-consumer channels proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply between United States cloud-native adoption and European compliance-first procurement, with Asia-Pacific markets splitting between India's cost-optimized indigenous development and Japan's enterprise integration priorities.
United States
San Francisco and New York fintech clusters drive demand for component-based architectures that accelerate engineering velocity. SEC scrutiny of digital platform liability shapes how open-source frameworks structure commercial indemnification offerings. Health-tech deployments in Boston prioritize frameworks with pre-built HIPAA compliance modules to compress regulatory review timelines.
Germany
Industrial software producers in Baden-Württemberg favor TypeScript frameworks for legacy system modernization with gradual migration paths. GDPR and the EU AI Act mandate algorithmic accountability hooks that inflate middleware complexity. Munich-based automotive software teams adopt full-stack architectures to consolidate engineering teams across connected vehicle platforms.
India
Domestic software product incentives under the PLI scheme nurture indigenous framework vendors targeting cost-sensitive enterprise segments. RBI data localization requirements push banking sector deployments toward on-premises and hybrid models. Bengaluru's SaaS startups leverage cloud-based deployment to compress time-to-market for payment processing applications.
Japan
Enterprise integration patterns dominate framework selection as METI digital transformation mandates accelerate legacy modernization. Financial institutions in Tokyo demand frameworks with immutable audit logging to satisfy JFSA operational resilience requirements. Osaka-based manufacturers prioritize frameworks with deep ERP connector ecosystems for supply chain digitization.
United Kingdom
Fintech clusters in London anchor demand for serverless deployment models that align cost structures with unpredictable transaction volumes. The Information Commissioner's Office enforcement of GDPR cross-border data flow constraints shapes middleware procurement criteria. Manchester's health-tech sector adopts component-based architectures to enable team autonomy across distributed engineering organizations.
Web Framework Software Market Key Industry Players
Capability concentration sits with hyperscale cloud providers; scale advantage sits with open-source foundations with massive contributor ecosystems. The market structures around three tiers: infrastructure-integrated platforms controlling edge runtime layers, foundation-backed frameworks with dominant npm ecosystem share, and boutique specialists serving vertical compliance requirements. Consolidation pressure is accelerating through strategic partnerships between framework vendors and managed deployment services, alongside technology licensing deals that embed frameworks into cloud control planes.
Within the infrastructure-integrated tier, Vercel and Google exemplify contrasting approaches to platform adjacency. Meta anchors the open-source foundation tier through React's component ecosystem and backward compatibility guarantees. Automattic occupies a distinct position bridging consumer publishing tools with enterprise content management requirements.
| Leading Market Players |
|---|
| Acquia (Drupal) |
| Remix Software (Remix) |
| Meta (React) |
| Astro Technology (Astro) |
| NestJS (NestJS) |
| Google (Angular) |
| Vercel (Next.js) |
| Laravel (Laravel) |
| Automattic (WordPress) |
| Others |
Cost & Logistics Intelligence
Bengaluru's SaaS engineering clusters generate pricing leverage through concentrated talent pools and cloud-native deployment expertise that compresses managed service margins. This geographic supply concentration shapes how framework vendors tier subscription offerings across enterprise and startup buyer archetypes.
Pricing Analysis
Long-term enterprise offtake contracts dominate framework procurement as financial services institutions lock in multi-year managed deployment agreements with indemnification riders. Three-tier pricing structure across premium, standard, and economy levels separates SOC-2 certified managed services from self-hosted community editions and unsupported open-source distributions. Pricing pressure stems from India's PLI scheme nurturing indigenous vendors targeting cost-sensitive South Asian segments. Startup buyers in San Francisco clusters exhibit highest price sensitivity; European banking sectors under GDPR mandates demonstrate lowest sensitivity due to compliance-driven procurement criteria.
Supply Chain Analysis
Upstream feedstock for web framework software centers on TypeScript compiler tooling, npm registry infrastructure, and hyperscaler compute capacity concentrated in the United States, Ireland, and Singapore. Core dependencies draw from GitHub's code repository layer, Cloudflare's edge network nodes, and AWS Lambda serverless runtime provisioning. Single-source vulnerability concentrates around GitHub's version control monopoly and npm's package distribution centrality. Distribution runs through direct vendor sales teams for enterprise accounts and self-serve cloud marketplaces for developer-led adoption.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
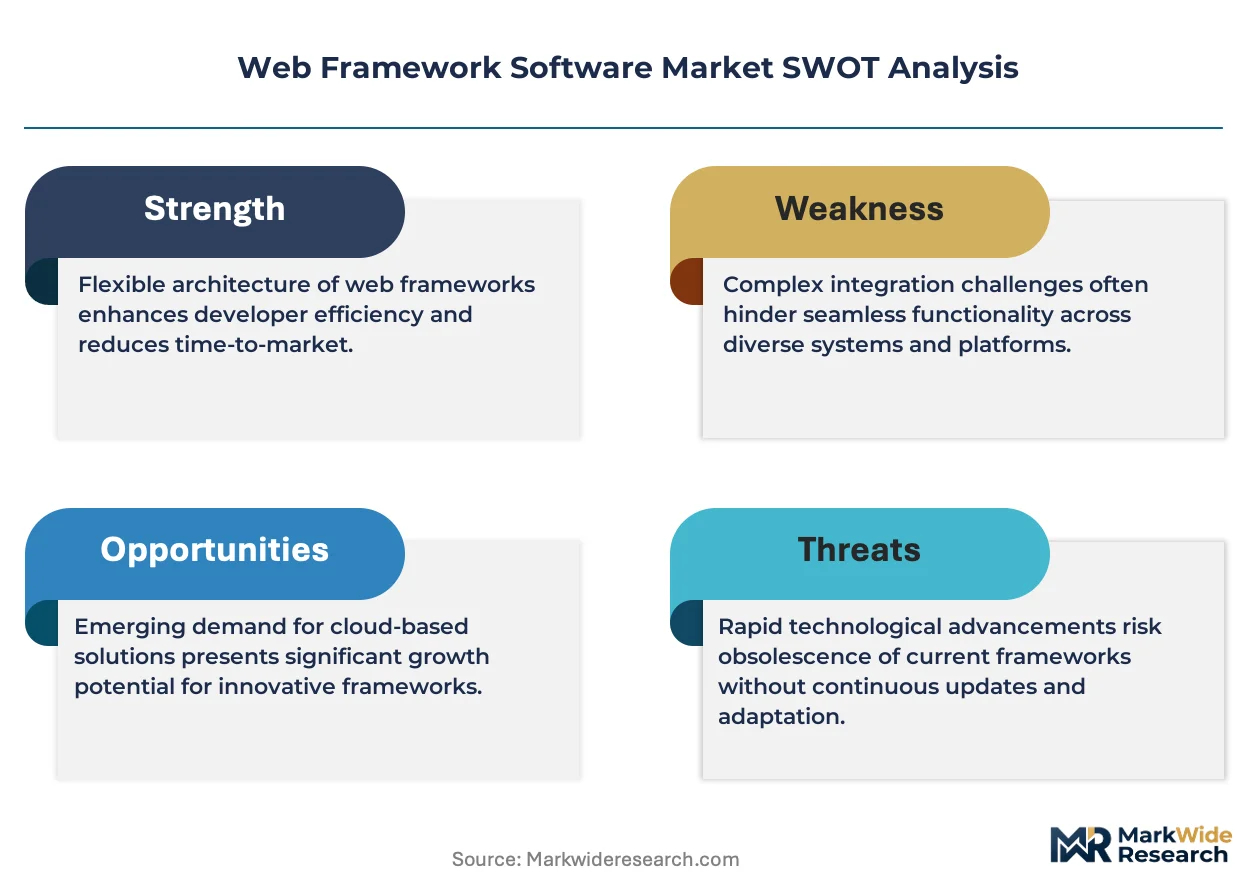
Web framework software presents a service-attach opportunity where managed deployment and edge runtime recurring revenue layers expand faster than core licensing, mirroring hyperscaler cloud consumption patterns.
For Market Incumbents: Pre-empt regulatory fragmentation by embedding Brussels-compliant audit architectures into routing layers before Washington mandates diverge. Consolidate through acquisition of boutique compliance specialists serving verticals like HIPAA-certified health-tech or PCI-DSS fintech modules. Vertical integration into serverless runtime layers adjacent to framework cores defends margin pools against hyperscaler encroachment. For New Entrants and Emerging Players: India's cost-optimized enterprise segments offer underpenetration white-space where PLI scheme incentives reduce effective customer acquisition costs. Target on-premises financial services deployments in Mumbai and Delhi seeking jurisdiction-agnostic alternatives to US-controlled cloud stacks. Go-to-market through channel partnerships with domestic system integrators possessing RBI data localization implementation expertise. For Investors and Strategic Acquirers: Carve-out targets emerge from hyperscaler-adjacent framework teams seeking independence from platform control plane integration mandates. Long-term viability hinges on contributor ecosystem depth and backward compatibility maintenance capacity rather than feature velocity alone. Monitor GitHub repository fork rates and npm download velocity shifts as early inflection indicators for framework momentum decay.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Deep Angular tooling across Google Cloud stack locks enterprise deployments into managed service tiers. |
| Strategic Partnership | Vercel's serverless edge runtime adjacency to Next.js compresses latency for real-time fintech applications. |
| Acquisition of Specialist Firm | Meta's React ecosystem consolidation through component library vendors strengthens backward compatibility guarantees. |
| Geographic Expansion | Indigenous framework vendors in Bengaluru leverage PLI scheme incentives to capture South Asian cost-sensitive segments. |
| Product Launch | WebAssembly-React convergence products open performance-critical applications previously closed to JavaScript frameworks. |
Research Approach
Desk research of SEC 10-K filings, hyperscaler capex disclosures, and npm registry statistics preceded structured interviews with CTOs, platform engineers, IT procurement officers, and channel integration specialists. Primary fieldwork captured deployment model preferences and compliance architecture requirements across fintech and health-tech clusters. Secondary validation drew from GitHub repository activity metrics, cloud vendor service catalogs, and EU regulatory filing databases. Bottom-up framework adoption estimates triangulated against top-down enterprise SaaS spending projections.
Assumptions held fixed include sustained GDPR enforcement intensity and current hyperscaler market share distributions; variables tested encompass PLI scheme subsidy levels and EU AI Act implementation timelines. Segmentation dimensions modeled span deployment model, organization size, vertical industry, integration complexity, and regional adoption pattern. CAGRs derived from slope-intercept fitting of historical adoption curves against projected enterprise micro-frontend decomposition rates. Forecast inputs incorporated WebAssembly browser penetration trajectories and edge computing infrastructure buildout schedules.
The forecast holds incumbent behavior within observed patterns; aggressive moves by China's indigenous framework vendors or India's PLI-nurtured alternatives would shift outcomes materially. Cross-checking against hyperscaler earnings call commentary on developer platform attach rates is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Newsroom Software Market
Software & Services
Global Construction Punch List Software Market
Software & Services
Collaborative Authoring Tools Market
Software & Services
Global Core Human Resource Software Market
Software & Services
Global Servicenow Store Apps Market
Software & Services
Saas for Spa Management Market
Software & Services
Latin America Human Resource (HR) Technology Market
Software & Services
Testing As a Service (Taas) Market
Software & Services
Enterprise Capture Software Market
Software & Services
Quality and Lifecycle Management Software Market
Software & Services
Software-Defined Machine Market
Software & Services
Cloud Backup and Recovery Software Market
Software & Services
Consignment Software Market
Software & Services
App Uninstall Software Market
Software & Services
Mobile Tracking Software Market
Software & Services
Medical E-Commerce Software Market