
 Manufacturing Quoting and Estimating Software Market | 2026-2036
Manufacturing Quoting and Estimating Software Market Size, Share, and Industry Trends Forecast 2026-2036
Manufacturing Quoting and Estimating Software Market Insights
Subscription-based pricing for CAD-integrated estimation modules is hardening as the dominant commercial model. CloudNC leverages its autonomous machining intelligence to anchor premium positioning in aerospace quoting workflows. PandaDoc sustains competitive pressure through document automation that extends into manufacturing proposal generation. aPriori specializes in real-time cost analytics that dominate automotive supplier evaluations.
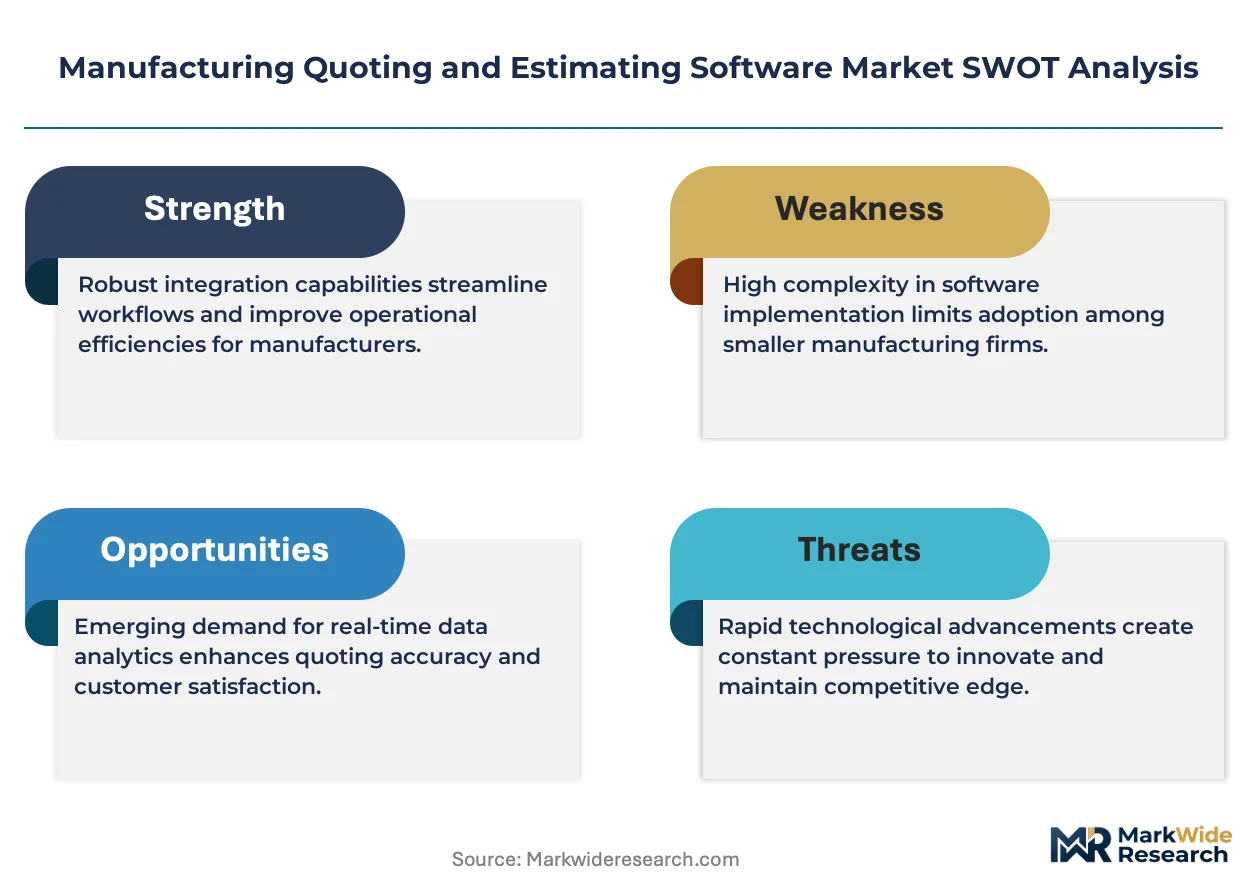
Manufacturing quoting and estimating software comprises algorithmic platforms that compute material costs, labor rates, machine cycle times, and overhead allocations from CAD files, BOMs, and process parameters to generate binding price quotes for custom production orders. The primary purpose is compressing quote turnaround from days to minutes while standardizing margin protection across distributed sales teams. Cloud-based deployment leads solution uptake among mid-tier contract manufacturers seeking lower IT overhead, while on-premise installations retain strongholds in defense and regulated medical device supply chains where data residency controls dominate procurement criteria. Quote management functionality captures the largest revenue pool today, though workflow automation modules targeting engineer-to-order environments represent the fastest-expanding segment as labor scarcity intensifies.
ISO 9001 quality management standards shape software validation requirements for suppliers serving automotive OEMs, while FDA 21 CFR Part 11 electronic records rules constrain quoting system deployments for medical device contract manufacturers in the United States. The EU AI Act introduces emerging compliance dimensions for platforms embedding machine learning into cost prediction engines, particularly for European Tier-1 suppliers. Stakeholders must evaluate whether their estimation algorithms will face algorithmic accountability audits before expanding across EU manufacturing clients.
Market Dynamics
Cloud deployment mandates under GDPR and data sovereignty frameworks are compressing vendor compliance timelines while fragmenting procurement criteria across precision manufacturing clusters in Germany, the United States, and Japan.
Growth Catalysts
- GDPR Article 44 cross-border transfer rules:European contract manufacturers are accelerating cloud-native quoting platform adoption to satisfy data residency requirements without maintaining on-premise infrastructure.
- Aerospace engineer-to-order workflows:Complex multi-axis machining requirements are driving demand for CAD-integrated estimation modules that compute cycle times from native geometry files.
- Japan METI Smart Manufacturing initiative:Subsidies for digital transformation in precision component suppliers are expanding addressable market for automated quoting systems in automotive Tier-1 networks.
Market Restraints
- Input cost volatility in cloud infrastructure:AWS, Azure, and Google Cloud pricing fluctuations are squeezing SaaS gross margins for mid-tier vendors serving job shops.
- Defense sector data residency lock-in:ITAR and CMMC requirements in United States defense supply chains are blocking cloud migration for quoting systems, preserving high-cost on-premise architectures.
- Legacy ERP integration complexity:Proprietary data formats in SAP and Oracle manufacturing modules are extending implementation timelines and inflating professional services costs.
Strategic Opportunities
- India PLI scheme for precision manufacturing:Production-linked incentives for component exporters are creating first-mover advantage for vendors offering localized cloud instances with BIS-compliant data handling.
- EU AI Act algorithmic accountability:Early certification of machine learning cost prediction engines will unlock preferred vendor status with European automotive OEMs conducting supply chain audits.
- Convergence of generative AI with CAD parsing:Natural language interfaces for quote specification are opening new buyer segments among non-technical procurement staff in mid-sized contract manufacturers.
Industry Challenges
- Cost estimation engineering talent scarcity:Retirements of experienced manufacturing estimators are outstripping training pipeline output, forcing software vendors to embed more domain expertise in automated workflows.
- FDA 21 CFR Part 11 validation timelines:Medical device contract manufacturers face 12-18 month software qualification cycles that delay revenue recognition for new platform deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Manufacturing Quoting and Estimating Software Market |
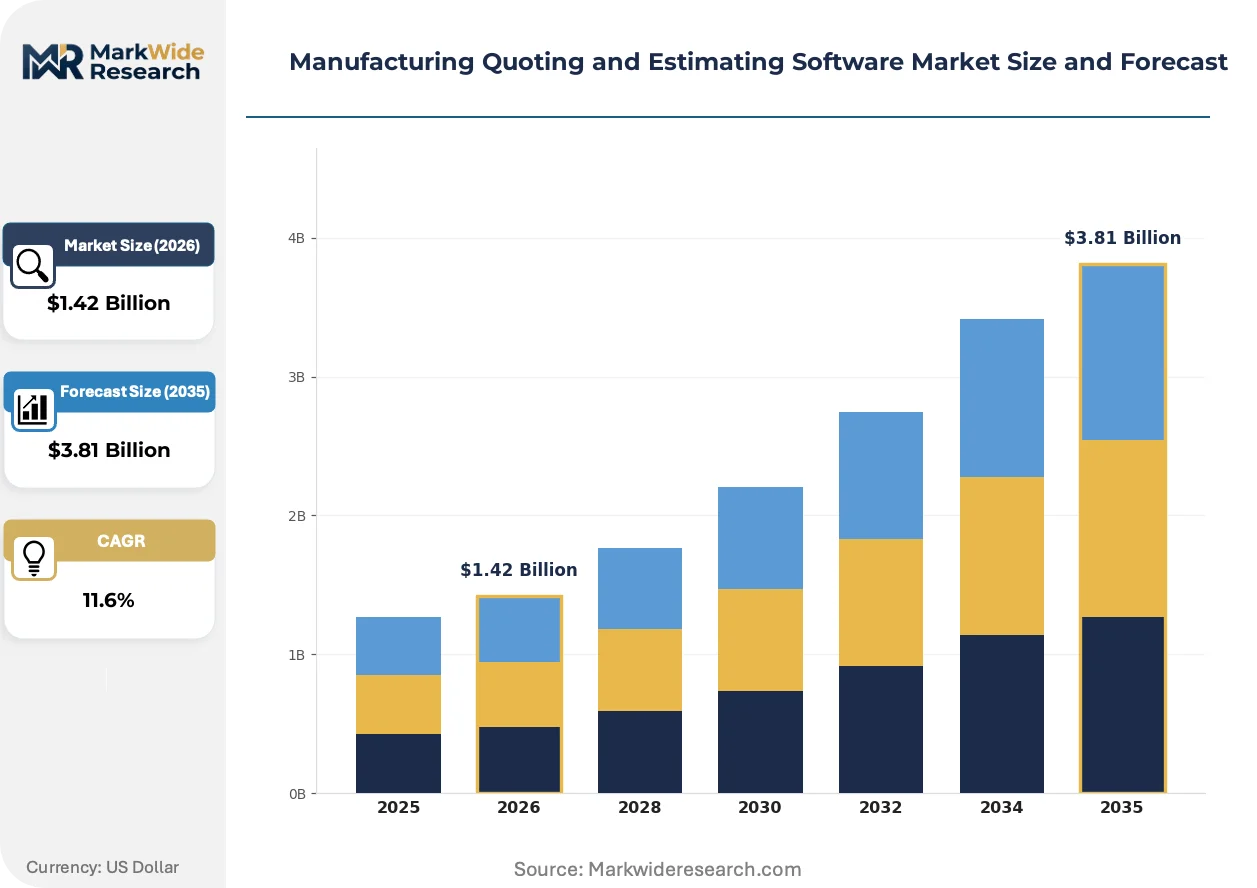
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, SaaS, Private Cloud Solution Offering: Quote Management, Cost Estimation, Workflow Automation, Integration Tools, Analytics & Reporting Application: Metal Fabrication, Electronics Assembly, Custom Machinery, Textile Production, Packaging Design End User Industry: OEMs, Tier-1 Suppliers, Aftermarket Providers, Contract Manufacturers, Job Shops |
| Companies Covered | CloudNC, PandaDoc, aPriori, Jobscope, DigiFabster, Costimator, SOLIDWORKS, MTI Systems, Kapow, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Manufacturing Quoting and Estimating Software Market Trends and Innovations
Machine learning cost prediction engines are absorbing human estimation expertise while regulatory compliance automation is reshaping vendor R&D priorities. Buyer procurement patterns are fragmenting as engineer-to-order manufacturers demand modular pricing over enterprise licenses.
Neural network-based feature recognition from CAD geometry is absorbing traditional methods of manual machining time estimation. Job shops with under fifty machines are adopting these tools fastest, compressing quote turnaround from days to minutes and eroding competitive advantage of established estimators.
The EU AI Act risk classification framework is mandating algorithmic transparency for automated pricing systems used in safety-critical manufacturing. Automotive suppliers in Germany and France must document training data provenance and decision logic, forcing vendors to reengineer black-box cost models into auditable rule sets.
Subscription fatigue among mid-tier manufacturers is fragmenting procurement into module-specific purchases rather than suite-wide commitments. Job shops in the United States Midwest are prioritizing standalone quoting tools over integrated ERP modules, favoring vendors with open API architectures and month-to-month terms.
Manufacturing Quoting and Estimating Software Market Segmentation
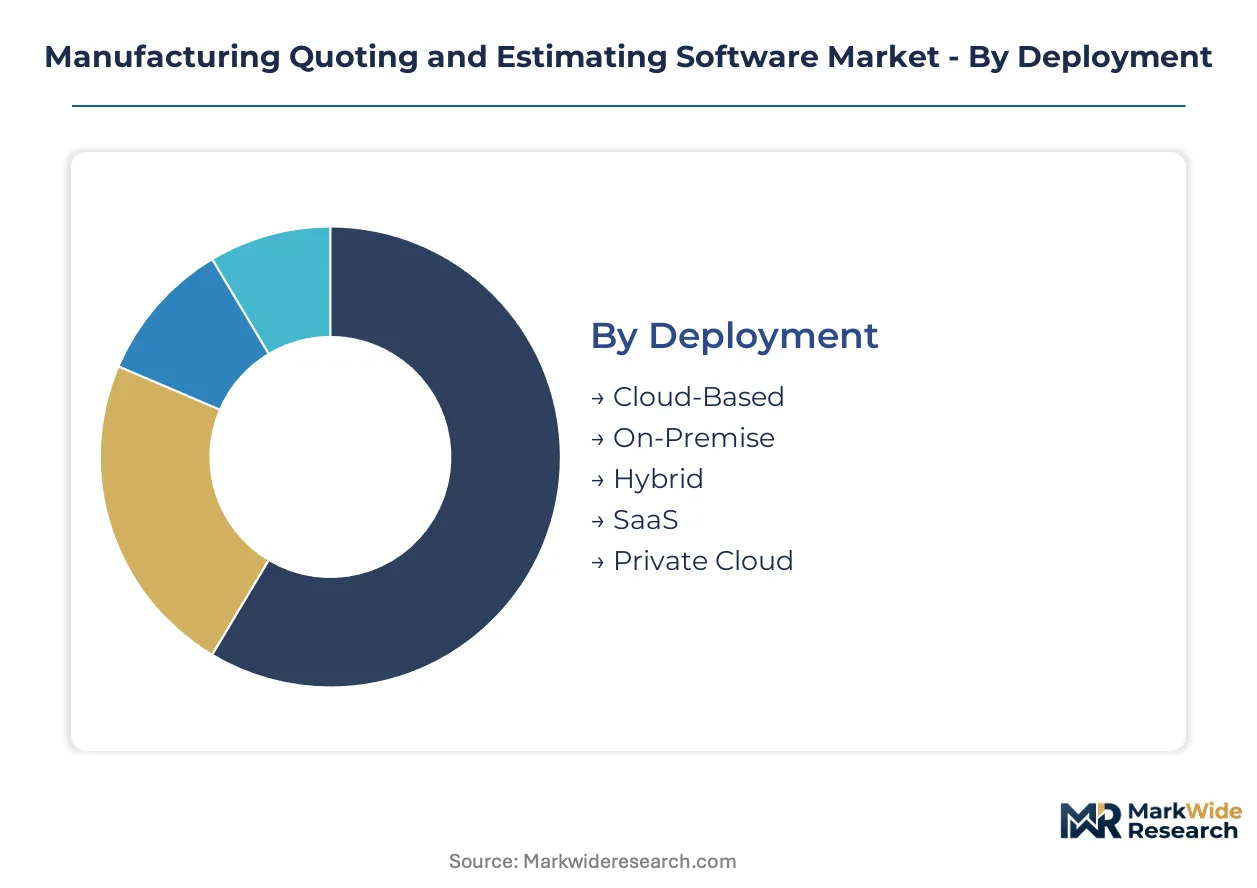
Deployment architecture and solution modularity determine vendor selection criteria across precision manufacturing clusters. Buyers prioritize data residency controls in regulated supply chains while engineer-to-order workflows demand CAD-native integration depth.
Deployment:
Procurement teams evaluate total cost of ownership against compliance mandates when selecting infrastructure models.
- Cloud-Based:Multi-tenant architectures with regional data center localization satisfy GDPR Article 44 requirements for European contract manufacturers. German automotive Tier-1 suppliers dominate demand as they migrate legacy on-premise systems to meet compressed quoting timelines.
- On-Premise:Air-gapped installations with hardware-level encryption serve ITAR-constrained defense subcontractors and FDA-regulated medical device manufacturers. United States Department of Defense supply chains mandate this architecture despite higher capital expenditure burdens.
- Hybrid:Split configurations process sensitive cost data locally while pushing non-critical analytics to public cloud tiers. Japanese precision component suppliers favor this model under METI Smart Manufacturing guidelines.
- SaaS:Browser-accessible platforms with API-first design enable rapid deployment across distributed sales teams. Mid-sized job shops in the United States Midwest adopt these tools to bypass IT staffing constraints.
- Private Cloud:Single-tenant environments with dedicated infrastructure address data sovereignty requirements in India and Brazil. Production-linked incentive beneficiaries in Indian precision manufacturing seek BIS-compliant localized instances.
Cloud-Based leads on scale; Hybrid leads on momentum.
Solution Offering:
Functional depth correlates directly with buyer sophistication and contract complexity.
- Quote Management:Centralized repositories for version-controlled proposals with margin protection rules. OEM procurement departments in Germany require audit trails for automotive RFQ compliance.
- Cost Estimation:Algorithmic engines computing material, labor, and overhead from CAD geometry and process parameters. Aerospace engineer-to-order manufacturers in the United States drive demand for multi-axis machining cycle time accuracy.
- Workflow Automation:Rules-based routing of quote approvals and exception handling. Contract manufacturers facing estimator retirements deploy these modules fastest.
- Integration Tools:Pre-built connectors for SAP, Oracle, and specialized MES platforms. ERP synchronization complexity extends implementation timelines for Tier-1 suppliers.
- Analytics & Reporting:Margin leakage detection and win-rate analytics across sales territories. Aftermarket providers use these capabilities to optimize spare parts pricing.
Quote Management dominates revenue capture; Workflow Automation expands most quickly.
Application:
Process physics and material variability shape estimation algorithm requirements.
- Metal Fabrication:Nesting optimization for sheet metal combined with laser cutting and bending cycle calculations. German machinery OEMs demand micron-level tolerance cost modeling.
- Electronics Assembly:SMT placement time estimation and component obsolescence risk pricing. Japanese automotive electronics suppliers drive refinement of these modules.
- Custom Machinery:Engineer-to-order configurations with parametric cost scaling for one-off production. United States oilfield equipment manufacturers anchor this segment.
- Textile Production:Weave pattern complexity indexing and dye lot variability allowances. Italian luxury fashion supply chains require specialized implementations.
- Packaging Design:Structural simulation for corrugated and folding carton material efficiency. Fast-moving consumer goods contract manufacturers in the United States prioritize throughput optimization.
Metal Fabrication leads on scale; Custom Machinery gains share fastest.
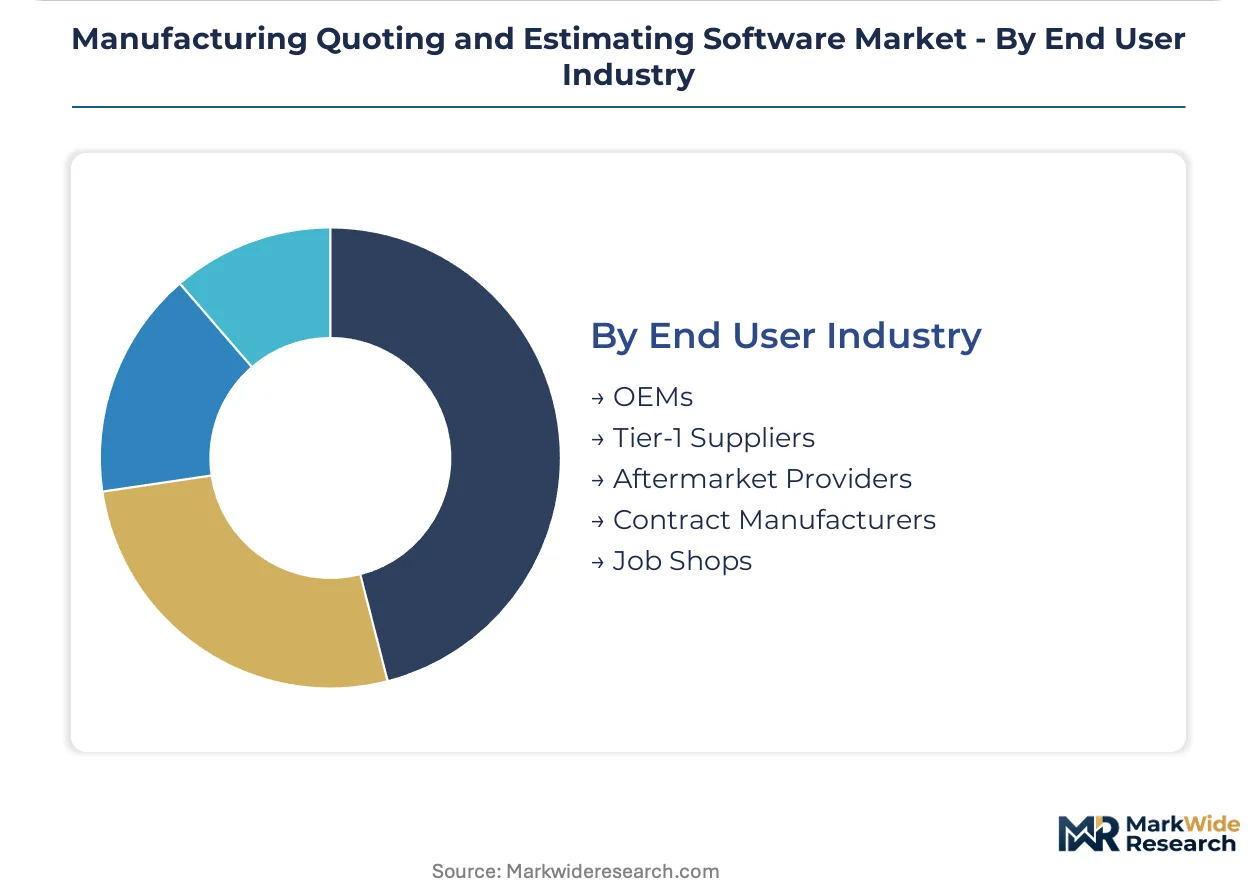
End User Industry:
Organizational scale and contract predictability determine pricing model tolerance.
- OEMs:Enterprise-wide deployments with multi-division cost center allocation and centralized supplier negotiation. German automotive manufacturers mandate ISO 9001-validated estimation workflows.
- Tier-1 Suppliers:OEM-mandated platform standardization with customer-specific reporting formats. EU AI Act compliance requirements are reshaping vendor selection in France and Germany.
- Aftermarket Providers:Spare parts catalog integration with obsolete component substitution logic. United States aerospace maintenance networks drive demand for reverse engineering cost modules.
- Contract Manufacturers:Multi-customer quote pipelines with confidentiality-segregated data architectures. Indian precision exporters under PLI schemes represent the steepest expansion trajectory.
- Job Shops:Rapid-turn quoting for opportunistic capacity fill with minimal implementation overhead. Midwest United States metalworking shops favor month-to-month SaaS terms.
OEMs lead on scale; Contract Manufacturers lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing quoting software procurement patterns diverge sharply based on data residency costs. European contract manufacturers absorb GDPR compliance premiums while United States defense suppliers maintain air-gapped infrastructure regardless of cloud economics.
United States
Defense subcontractors dominate on-premise demand under ITAR and CMMC mandates. Aerospace engineer-to-order manufacturers in Connecticut and Washington State drive CAD-integrated estimation module procurement. Midwest job shops in Ohio and Michigan favor SaaS deployment for rapid-turn metal fabrication quoting.
Germany
Automotive Tier-1 suppliers anchor European demand for ISO 9001-validated estimation workflows. Bavarian precision machining clusters migrate legacy systems to GDPR-compliant cloud instances under Article 44 transfer rules. Stuttgart and Munich manufacturing networks prioritize algorithmic transparency for EU AI Act preparedness.
Japan
METI Smart Manufacturing subsidies accelerate digital transformation in Nagoya automotive component suppliers. Chubu region precision manufacturers adopt hybrid deployments balancing local cost data processing with cloud analytics. Osaka-based electronics assembly houses refine SMT placement time estimation modules.
India
PLI scheme beneficiaries in precision component exports create localized cloud demand with BIS-compliant data handling. Gujarat and Maharashtra contract manufacturers represent the steepest expansion trajectory for automated quoting adoption. Bangalore aerospace subcontractors integrate estimation platforms with AS9100 quality workflows.
United Kingdom
Midlands aerospace supply chains require quotation systems supporting AS9100 and defense accreditation standards. London-based contract manufacturers serving European OEMs navigate post-Brexit data transfer complexity. Northern England metal fabrication clusters prioritize month-to-month SaaS terms over enterprise commitments.
Manufacturing Quoting and Estimating Software Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments. The vendor base organizes around three tiers: CAD-native estimation engines, document automation platforms, and autonomous machining intelligence providers. Consolidation pressure concentrates among mid-tier SaaS vendors facing AWS and Azure infrastructure cost volatility. Dominant competitive moves include API-first architecture development and regional cloud instance localization for data sovereignty compliance.
Within the autonomous machining tier, CloudNC exemplifies premium positioning anchored in aerospace quoting workflows. Document automation specialists include PandaDoc, which occupies a position extending into manufacturing proposal generation. Real-time cost analytics providers are represented by aPriori, sitting within the automotive supplier evaluation segment. These three archetypes illustrate how technical specialization maps to end-use industry procurement criteria without overlapping functional territory.
| Leading Market Players |
|---|
| CloudNC |
| PandaDoc |
| aPriori |
| Jobscope |
| DigiFabster |
| Costimator |
| SOLIDWORKS |
| MTI Systems |
| Kapow |
| Others |
Pricing and Supply Chain Analysis
Horizontal API-first architecture choices by mid-tier SaaS vendors anchor supply positions while compressing pricing power against hyperscaler infrastructure cost volatility. Cloud-native quoting platforms in the United States Midwest and German automotive Tier-1 networks absorb divergent compliance premiums that fragment procurement willingness-to-pay across deployment models.
Pricing Analysis
Distributor margin compression in ERP-integrated channels forces direct-to-job-shop SaaS pricing that undercuts enterprise license bundles by sixty percent or more. Three-tier pricing structure across premium CAD-native estimation, standard quote management, and economy workflow automation modules stratifies buyer segments by implementation complexity. Pricing pressure stems from AWS and Azure infrastructure cost volatility squeezing vendor gross margins, with mid-tier contract manufacturers exhibiting highest price sensitivity while defense subcontractors accept on-premise premiums for ITAR compliance.
Supply Chain Analysis
Estimator workforce availability constraints in Germany, the United States, and Japan are forcing vendors to embed domain expertise in automated workflows rather than staffing implementation teams locally. Cloud infrastructure provisioning draws from hyperscaler data centers in Ireland, Frankfurt, and Virginia, while specialized CAD parsing engines rest on proprietary machine learning training pipelines. Single-source vulnerability in NVIDIA GPU supply for neural network feature recognition creates procurement risk for algorithmic cost prediction vendors. Distribution runs through direct sales teams for OEM accounts and self-service portals for job shop adoption.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Data residency compliance costs in Europe run triple those in United States Midwest job shop markets, creating arbitrage opportunity for vendors with regional cloud localization capabilities.
For Market Incumbents: Hedge against subscription fatigue fragmentation by modularizing enterprise suites into standalone API-accessible components with month-to-month terms. Acquire specialized CAD-native estimation engines to defend against CloudNC's autonomous machining positioning in aerospace workflows. Prioritize EU AI Act algorithmic transparency certification to lock in German automotive Tier-1 supplier relationships ahead of audit mandates. For New Entrants and Emerging Players: Begin with India PLI scheme beneficiaries in Gujarat and Maharashtra precision component exports, where localized BIS-compliant cloud instances face minimal incumbent saturation. Target engineer-to-order workflow automation for United States oilfield equipment manufacturers, a segment with retiring estimator populations and low SaaS penetration. Pursue OEM procurement department bypass through direct sales to non-technical contract manufacturer staff using natural language quote specification interfaces. For Investors and Strategic Acquirers: Roll-up economics work for fragmented mid-tier SaaS vendors with complementary API architectures because defense sector data residency lock-in preserves high-margin on-premise revenue streams alongside cloud growth. Platform consolidation across quote management, cost estimation, and workflow automation modules offers five-to-ten year viability as labor scarcity intensifies automation demand. Monitor EU AI Act enforcement timing in France and Germany as inflection signal for algorithmic accountability premium realization.| Strategic Initiative | Industry Significance |
|---|---|
| Regional Cloud Instance Localization | GDPR Article 44 compliance unlocks German automotive Tier-1 procurement budgets. |
| API-First Architecture Development | Open integration with SAP and Oracle modules reduces professional services drag. |
| EU AI Act Algorithmic Certification | Auditable cost prediction engines secure preferred vendor status with European OEMs. |
| Generative AI-Natural Language Interface | Non-technical procurement staff adoption expands addressable market in mid-sized job shops. |
| Hybrid Deployment Configuration | METI Smart Manufacturing guidelines in Japan favor split local-cloud architectures. |
Research Methodology
Direct dialogue with CTOs at contract manufacturers, IT procurement officers at automotive Tier-1 suppliers, platform engineers at CAD-integrated vendors, and integration specialists at ERP implementation firms grounded qualitative findings. Secondary validation drew from SEC 10-K filings of publicly traded manufacturing software vendors, hyperscaler capex disclosures from AWS and Azure, EU regulatory filings under GDPR and AI Act frameworks, and automotive OEM supplier quality audit documentation. Bottom-up and top-down triangulation cross-checked segment-level adoption rates against aggregate market sizing.
Bottom-up modeling of deployment architecture, solution modularity, and end-user industry segments across the analysis window generated volume and value outputs. CAGRs derived from regression of historical adoption curves against estimator workforce retirement timelines and cloud infrastructure cost trajectories. Industry-specific inputs included METI Smart Manufacturing subsidy disbursement patterns, India PLI scheme beneficiary registrations, and FDA 21 CFR Part 11 validation cycle durations for medical device contract manufacturers.
Several conditions sit outside the modeled scope, including abrupt hyperscaler pricing resets, defense sector CMMC requirement revisions, and EU AI Act enforcement intensity variations. Forecasts reflect documented assumptions about estimator workforce attrition rates and cloud migration elasticity. Material deviation in GDPR cross-border transfer rule interpretations or automotive OEM platform standardization timelines warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
File Analysis Software Market
Software & Services
Global Restaurant Management Software Market
Software & Services
Fitness App Market
Software & Services
Global Employee Engagement and Feedback Software Market
Software & Services
Curriculum Mapping Software Market
Software & Services
Europe Business Software Market
Software & Services
Customer Advocacy Software Market
Software & Services
Adaptive Learning Software Market
Software & Services
Service Scheduling Software Market
Software & Services
Application Virtualization Market
Software & Services
Cemetery Software Market
Software & Services
Australia HR Payroll Software Market
Software & Services
Staffing Agency Software Market
Software & Services
Global Ad Server Software Market
Software & Services
Workstation Software Market
Software & Services
Asia-Pacific Accounting Software Market