
 Federal Government Software Market | 2026-2036
Federal Government Software Market Size, Share, and Industry Trends Forecast 2026-2036
Federal Government Software Market Insights
FedRAMP High authorization tier is reorganizing competitive dynamics for sensitive federal workloads. Microsoft Corporation leverages its Azure Government cloud to sustain dominance in classified environments. IBM anchors its position through specialized mainframe and quantum-safe cryptography services for legacy federal infrastructure. Oracle Corporation competes aggressively on database sovereignty requirements across civilian agencies.
Federal government software encompasses applications, platforms, and infrastructure tools procured by national government entities to execute administrative, defense, and citizen-service functions, typically requiring FIPS 140-2 cryptographic validation and continuous monitoring protocols. Cloud-based deployment models now capture the fastest expansion as agencies migrate from aging on-premises data centers, though hybrid architectures retain the largest installed base due to classified network isolation requirements. Defense end users command the deepest procurement budgets, while workflow automation functionality shows the strongest growth trajectory as agencies pursue executive mandates for operational efficiency.
FedRAMP, NIST SP 800-53, and FISMA frameworks collectively dictate product certification pathways and vendor eligibility for federal contracts. These standards elevate barriers for commercial software providers while creating sustained demand for accredited consulting and engineering services. Stakeholders must monitor pending OMB guidance on zero-trust architecture mandates to anticipate procurement priority shifts.
Market Dynamics
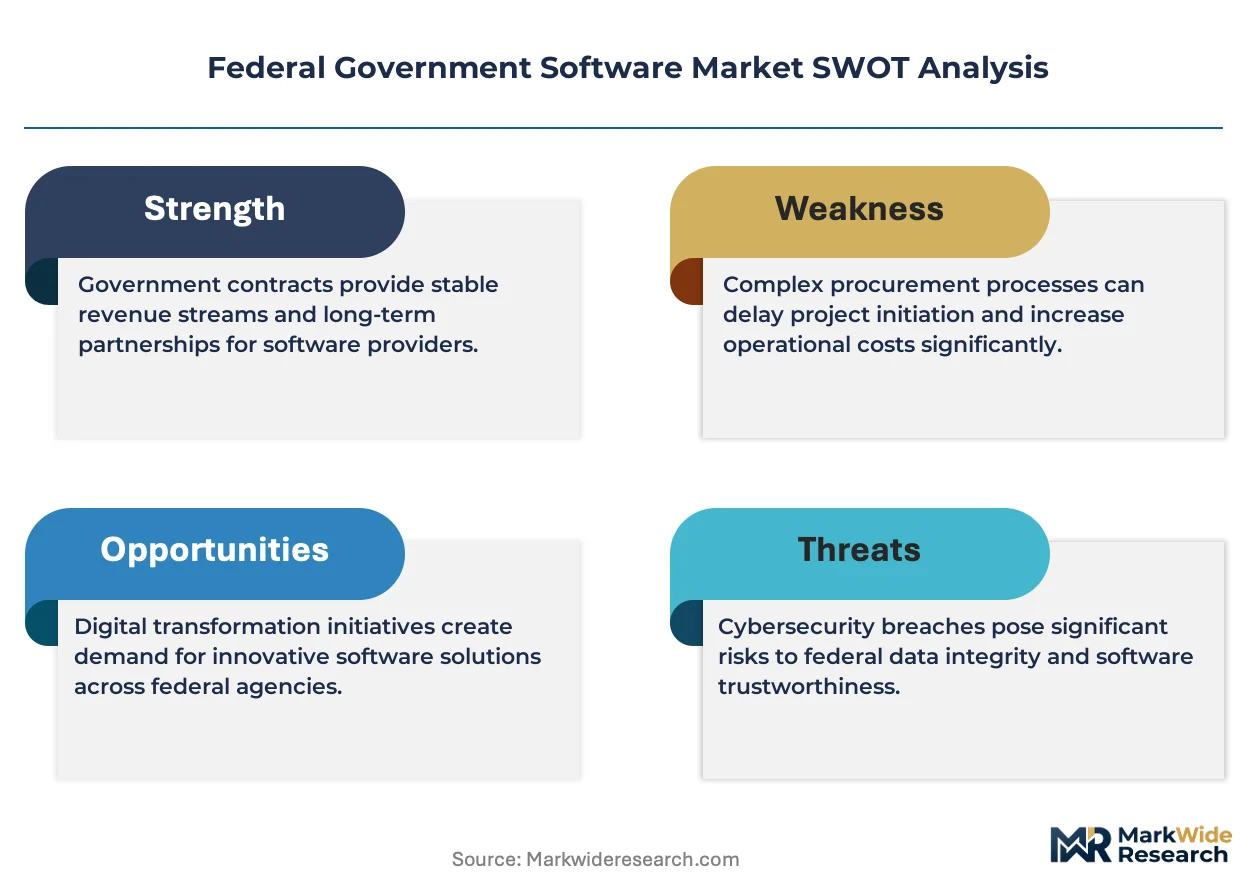
FedRAMP authorization tiers are compressing vendor eligibility windows while accelerating cloud migration mandates across civilian and defense agencies. This dual pressure is restructuring competitive entry costs and procurement timelines simultaneously.
Growth Catalysts
- FedRAMP High authorization tier:Defense agencies and intelligence communities mandate this certification for classified workloads, creating sustained demand for accredited platform engineering.
- Zero-trust architecture mandates:OMB guidance requires continuous verification protocols, forcing infrastructure refresh cycles across civilian departments.
- Northern Virginia technology corridor concentration:Proximity to Washington DC procurement offices attracts specialized system integrators and cleared personnel pools.
Market Restraints
- FISMA compliance timelines:Authorization processes extend 12-18 months, freezing procurement decisions and delaying revenue recognition for vendors.
- Cleared talent scarcity:TS/SCI clearance backlogs constrain engineering capacity for classified environment deployments.
- Hybrid architecture lock-in:Classified network isolation requirements prevent full cloud migration, fragmenting vendor addressable market.
Strategic Opportunities
- Quantum-safe cryptography transition:NIST post-quantum standards create replacement demand for legacy federal cryptographic infrastructure.
- Workflow automation mandates:Executive orders targeting operational efficiency expand robotic process automation procurement across civilian agencies.
- State-level Medicaid platform modernization:Federal matching funds drive software procurement for health and human services digitization.
Industry Challenges
- Continuous monitoring engineering:FedRAMP requires real-time security telemetry, demanding scarce DevSecOps expertise for sustained compliance.
- Legacy mainframe integration:COBOL-dependent agencies face skill extinction risks when bridging modern cloud platforms to antiquated core systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Federal Government Software Market |
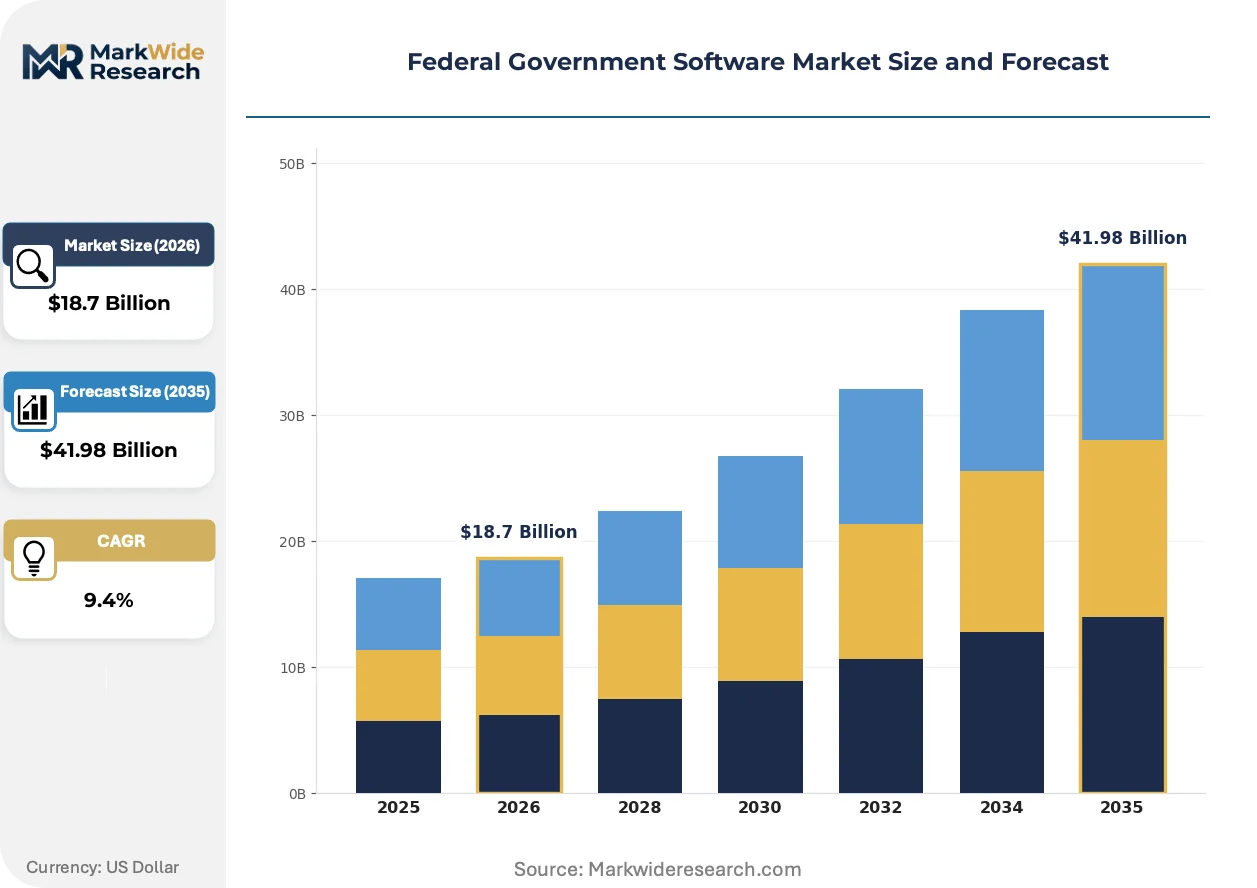
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $41.98 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application Type: Procurement, Compliance, Security, Project Management Deployment Model: On-Premises, Cloud-Based, Hybrid, Virtual End User: Defense, Public Safety, Federal Agencies, Intelligence Functionality: Data Analysis, Workflow Automation, Risk Management, Reporting |
| Companies Covered | Microsoft Corporation, IBM, Oracle Corporation, SAP SE, Dell, Cisco, Accenture, Booz Allen Hamilton, Amazon Web Services, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Federal Government Software Market Trends and Innovations
Cloud-native platforms are penetrating classified environments while zero-trust mandates rewire network architecture procurement. These forces are compressing legacy infrastructure replacement cycles and elevating security engineering to primary vendor selection criteria.
Container orchestration is bifurcating deployment patterns across federal agencies. Kubernetes enables portable workload management for unclassified systems while defense programs adopt hardened distributions for tactical edge environments. This split is forcing vendors to maintain dual certification tracks and engineering streams.
FISMA reporting modernization is compressing audit preparation cycles for federal contractors. Continuous authorization frameworks replace point-in-time assessments, requiring automated compliance tooling. Civilian agencies with dispersed IT estates face the steepest adaptation costs.
Software-as-a-service procurement is displacing perpetual license models across civilian departments. Subscription pricing aligns with annual appropriation cycles while reducing upfront capital requirements. Defense programs retain capital expenditure models for air-gapped installations, creating parallel revenue recognition patterns.
Federal Government Software Market Segmentation
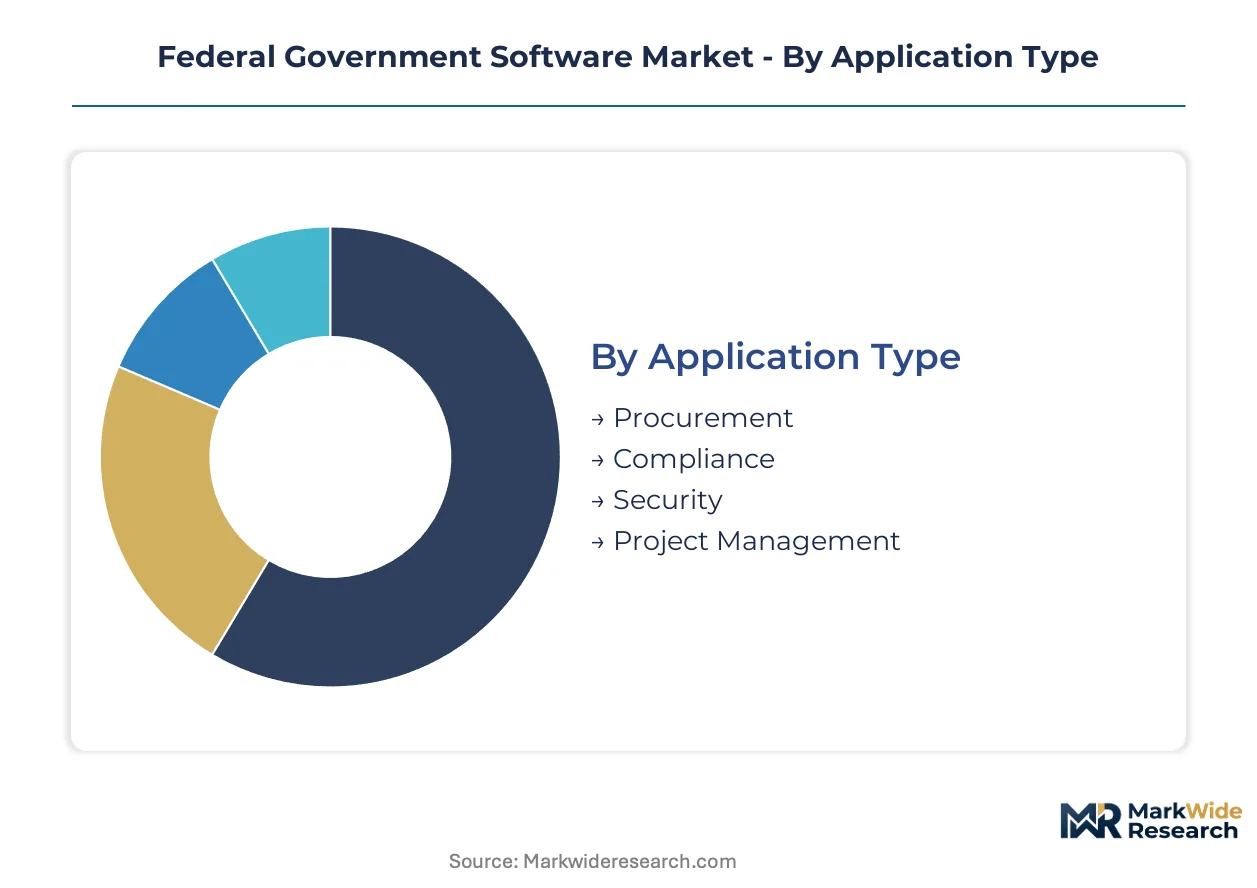
Federal procurement officers segment software purchases by security classification, deployment constraints, and mission-critical functionality. These divisions dictate vendor eligibility, pricing structures, and contract vehicles available to suppliers.
Application Type:
Substitution pressure intensifies where commercial off-the-shelf solutions can satisfy federal requirements without customization overhead.
- Procurement:Contract lifecycle management platforms automate solicitation, evaluation, and award processes for federal acquisition regulations. Demand concentrates at the General Services Administration and Defense Logistics Agency as these entities process the highest transaction volumes under Federal Acquisition Regulation mandates.
- Compliance:Automated policy enforcement engines map agency operations to FISMA, FedRAMP, and NIST control frameworks. The Department of Homeland Security and civilian financial agencies drive procurement as continuous monitoring requirements expand audit preparation burdens.
- Security:Identity and access management with zero-trust architecture enforcement protects classified networks.
- Project Management:Gantt-based scheduling and resource allocation tools track capital program execution.
Procurement retains volume leadership; Compliance holds the steepest expansion curve.
Deployment Model:
Cost tier stratification separates capital-intensive on-premises installations from operational expenditure cloud subscriptions.
- On-Premises:Air-gapped installations within agency-owned data centers maintain physical control over sensitive workloads. The intelligence community and tactical military commands mandate these deployments where network isolation prevents exfiltration risks.
- Cloud-Based:FedRAMP-authorized multi-tenant platforms deliver elastic compute without infrastructure ownership. Civilian health and human services agencies accelerate migration here as OMB mandates cloud-first procurement policies.
- Hybrid:Split architectures route unclassified workloads to commercial cloud while retaining classified data on-premises.
- Virtual:Containerized environments abstract hardware dependencies for portable software delivery.
Hybrid deployments retain volume leadership; Cloud-Based solutions gain share fastest.
End User:
Customer type determines clearance requirements, budget scale, and procurement cycle length.
- Defense:Military departments and combatant commands operate the deepest procurement budgets with classified network mandates. The Pentagon's software factories and program executive offices concentrate demand in Northern Virginia and Maryland corridors near Washington DC.
- Intelligence:Signals intelligence and human intelligence agencies require TS/SCI-cleared engineering teams for system integration. The National Security Agency and Central Intelligence Agency drive specialized cryptographic and counterintelligence platform procurement.
- Public Safety:Federal law enforcement and emergency response coordination systems.
- Federal Agencies:Civilian departments with standard security clearance requirements.
Defense retains volume leadership; Intelligence holds the steepest expansion curve.
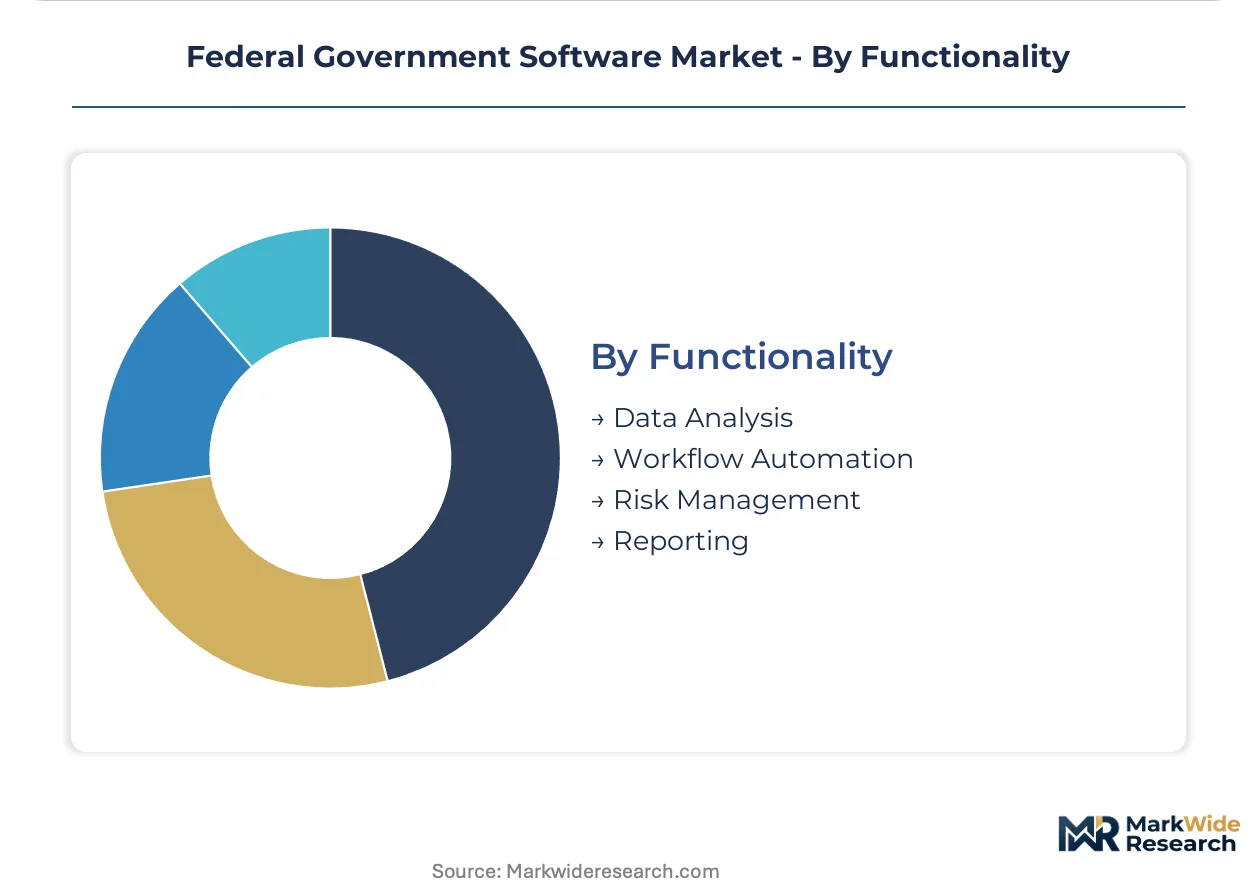
Functionality:
Maturity gradients separate established reporting tools from emerging automation capabilities.
- Workflow Automation:Robotic process automation and low-code platforms eliminate manual data entry across administrative functions. The Office of Personnel Management and Treasury Department expand procurement as executive orders mandate operational efficiency targets.
- Data Analysis:Business intelligence and predictive analytics platforms extract decision-support insights from agency data lakes. Program evaluation offices at HHS and USDA concentrate demand for fraud detection and outcome measurement capabilities.
- Risk Management:Quantitative assessment tools model operational and financial exposures.
- Reporting:Standardized dashboard and visualization systems for congressional and public transparency mandates.
Reporting retains volume leadership; Workflow Automation climbs the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States software vendors export FedRAMP-authorized platforms to allied defense and intelligence agencies across NATO member states and Five Eyes partners. This trade corridor channels procurement specifications from Washington DC to Canberra, London, and Ottawa.
United States
Defense agencies and civilian departments drive demand through cloud migration mandates and zero-trust architecture requirements. FedRAMP authorization tiers reshape vendor eligibility windows across all procurement channels. Northern Virginia's technology corridor concentrates system integrators and cleared engineering talent pools near Pentagon and intelligence community headquarters.
United Kingdom
Ministry of Defence digital transformation programs and Government Digital Service cloud-first policies accelerate platform procurement. NCSC Cyber Essentials and NIS2 implementation timelines compress vendor certification cycles. London and Bristol tech clusters host specialized defense contractors serving NATO interoperability requirements.
Germany
Bundeswehr IT consolidation and federal cybersecurity agency mandates expand secure software procurement. BSI IT-Grundschutz compliance requirements and Gaia-X sovereignty initiatives reshape cloud vendor selection criteria. Berlin and Munich cybersecurity hubs concentrate cleared engineering capacity for classified Bundesnachrichtendienst workloads.
Canada
Shared Services Canada cloud migration and Department of National Defence modernization programs drive platform demand. Canadian Centre for Cyber Security guidance and Protected B classification requirements filter vendor eligibility. Ottawa-Gatineau corridor concentrates defense procurement offices and cleared contractor presence.
Australia
Australian Signals Directorate cloud certification and Defence Department REDSPICE investment program expand secure software procurement. Information Security Registered Assessors Program audits compress vendor onboarding timelines. Canberra hosts the concentrated federal procurement apparatus and defense contractor ecosystem.
Federal Government Software Market Competitive Landscape
Listed leaders compete with private specialists across authorization tier depth and cleared personnel scale. Tier-one technology conglomerates anchor positions through FedRAMP High certifications and existing enterprise relationships with civilian agencies. Tier-two defense contractors specialize in TS/SCI-cleared engineering for intelligence community deployments. Tier-three cloud-native challengers penetrate through DevSecOps automation and continuous monitoring tooling. Dominant competitive moves include strategic partnerships with system integrators and portfolio diversification into zero-trust architecture components.
Within the tier-one platform tier, Microsoft Corporation and Amazon Web Services exemplify cloud-native scale advantages across civilian and defense workloads. IBM anchors the legacy infrastructure segment through specialized mainframe and quantum-safe cryptography services. Oracle Corporation occupies a position emphasizing database sovereignty and on-premises deployment retention across security-conscious agencies.
| Leading Market Players |
|---|
| Microsoft Corporation |
| IBM |
| Oracle Corporation |
| SAP SE |
| Dell |
| Cisco |
| Accenture |
| Booz Allen Hamilton |
| Amazon Web Services |
| Others |
Pricing and Supply Chain Analysis
Eighteen-month FedRAMP authorization timelines compress vendor cash conversion cycles while amplifying pricing power for pre-accredited incumbents. Defense procurement officers pay clearance premiums for TS/SCI-cleared engineering talent that civilian agencies cannot access, bifurcating rate cards across classification tiers.
Pricing Analysis
Defense agencies anchor subscription pricing through multi-year enterprise agreements that bundle FedRAMP High certification maintenance with dedicated engineering support. Pricing stratifies across FedRAMP authorization tiers, customization depth for legacy mainframe bridges, and cleared personnel premiums. Cost compression in civilian SaaS procurement intensifies as OMB cloud-first mandates expand vendor pools. Small disadvantaged businesses exhibit highest price sensitivity; intelligence community buyers show lowest elasticity due to sole-source security requirements.
Supply Chain Analysis
Just-in-time talent deployment dominates unclassified civilian workloads while defense programs maintain strategic stockpiles of cleared engineers through multi-year retention contracts. Engineering capacity concentrates in the United States, the United Kingdom, and Australia among Five Eyes partners. Supply rests on TS/SCI-cleared personnel pipelines, FedRAMP-accredited cloud infrastructure, and quantum-safe cryptographic modules. Single-source vulnerability sits with cleared talent backlogs extending fourteen months. Distribution runs through GSA Schedule contracts and DoD enterprise licensing vehicles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FedRAMP authorization entrenchment constructs defensive moats through regulatory switching costs that freeze out unaccredited competitors. Incumbents leverage multi-year compliance investments to sustain premium positioning.
For Market Incumbents: Compound authorization tier depth by accelerating FedRAMP High reciprocity across allied defense markets. Expand cleared engineering bench capacity in Northern Virginia to capture REDSPICE and similar foreign investment programs. Vertical integration into continuous monitoring tooling offsets DevSecOps talent scarcity threatening margin sustainability.
For New Entrants and Emerging Players: FedRAMP Ready fast-track programs unlock civilian agency procurement before full High authorization. Target workflow automation segments at Treasury and OPM where executive mandates compress evaluation cycles. Partner with established system integrators to bypass direct clearance requirements while building accreditation runway.
For Investors and Strategic Acquirers: Carve-out targets emerge from defense primes spinning non-core software assets lacking standalone authorization infrastructure. Long-term viability hinges on quantum-safe cryptography transition timing and zero-trust architecture deployment velocity. Watch OMB guidance on continuous authorization frameworks as inflection signal for compliance tooling demand.
| Strategic Initiative | Industry Significance |
|---|---|
| FedRAMP High Authorization Expansion | Unlocks classified defense and intelligence procurement channels requiring sovereign cloud isolation. |
| Quantum-Safe Cryptography Transition | Captures NIST post-quantum standard replacement cycles across legacy federal infrastructure. |
| Zero-Trust Architecture Integration | Aligns vendor portfolios with OMB continuous verification mandates reshaping network procurement. |
| Cleared Talent Acquisition | Secures TS/SCI engineering capacity that constrains deployment velocity for classified workloads. |
| Workflow Automation Platform Launch | Addresses executive efficiency mandates driving RPA procurement at civilian administrative agencies. |
Research Methodology
Operator-level perspectives from FedRAMP authorization officers, defense program executive office leads, civilian agency CTOs, and cleared system integrators anchored the qualitative base. Secondary validation drew from FedRAMP marketplace disclosures, GSA Schedule contract awards, DoD budget justification documents, and NIST cybersecurity framework publications. Bottom-up segment sizing triangulated against top-down federal IT spending allocations.
Sensitivity analysis tested authorization timeline compression, clearance backlog scenarios, and cloud migration acceleration assumptions across the projection horizon. The analytical framework modeled deployment model, end-user classification tier, and functionality maturity gradients. CAGRs derived from historical procurement velocity patterns and mandate-driven replacement cycle analysis. Quantum-safe cryptography transition timing and zero-trust architecture penetration served as industry-specific forecast inputs.
Decision-makers should treat outputs as directional under sustained FedRAMP reciprocity and stable appropriation growth assumptions; material deviation would warrant model refresh. Revision becomes warranted when authorization timeline compression or clearance backlog resolution crosses thresholds that reshape competitive entry economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Vending Software Market
Software & Services
Global Bill of Material Management Software Market
Software & Services
HVAC Solution Software Market
Software & Services
Global Java Web Frameworks Software Market
Software & Services
Sales Compensation Software Market
Software & Services
Global Employee Engagement and Feedback Software Market
Software & Services
MCAD Software Market
Software & Services
Global Maintenance Management Software Market
Software & Services
Saas for Spa Management Market
Software & Services
Global Quoting Software Market
Software & Services
Eclinical Solutions and Software Market
Software & Services
Embroidery Design Software Market
Software & Services
Asia Pacific Human Capital Management Software (HCM) Market
Software & Services
Radio Propagation Software Market
Software & Services
Car-Hailing Software Market
Software & Services
B2B Gateway Software Market