
 Global Voting Software Market | 2026-2036
Global Voting Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Voting Software Market Foresight
The capability gap between hardware-integrated platform providers and pure-play SaaS vendors is bifurcating competitive dynamics across the Global Voting Software Market. Smartmatic leverages its end-to-end election infrastructure footprint across Latin America and Africa to sustain multi-cycle contracts with national electoral bodies. Dominion Voting Systems anchors its position through manufacturing scale in the United States, where it controls county-level deployment networks for optical scan and ballot-marking devices.
Voting software comprises applications that manage voter registration, ballot casting, tabulation, and result transmission through encrypted digital channels, typically requiring ISO 27001 certification and hardware security module integration for cryptographic key protection. Its primary commercial purpose is to reduce manual counting errors while creating immutable audit trails for electoral integrity verification. Cloud-based deployment leads among corporate and academic users seeking rapid provisioning without capital expenditure, though government election commissions still favor on-premise or hybrid architectures to maintain air-gapped security boundaries. Blockchain technology segments are expanding fastest within pilot programs for overseas and military voting, yet optical scan technology dominates transactional volume due to its paper-ballot backup requirement in jurisdictions with mandatory recount provisions.
The U.S. Election Assistance Commission and NIST set voluntary voting system guidelines that shape federal certification requirements, while the EU AI Act and GDPR impose algorithmic transparency and data residency constraints on vendors serving European member states. India's Election Commission and BIS standards mandate domestic data localization for electoral infrastructure, creating market access barriers for foreign-hosted platforms. Stakeholders must monitor how divergent national cybersecurity frameworks reshape procurement eligibility and force architecture fragmentation across border-spanning product roadmaps.
Market Dynamics
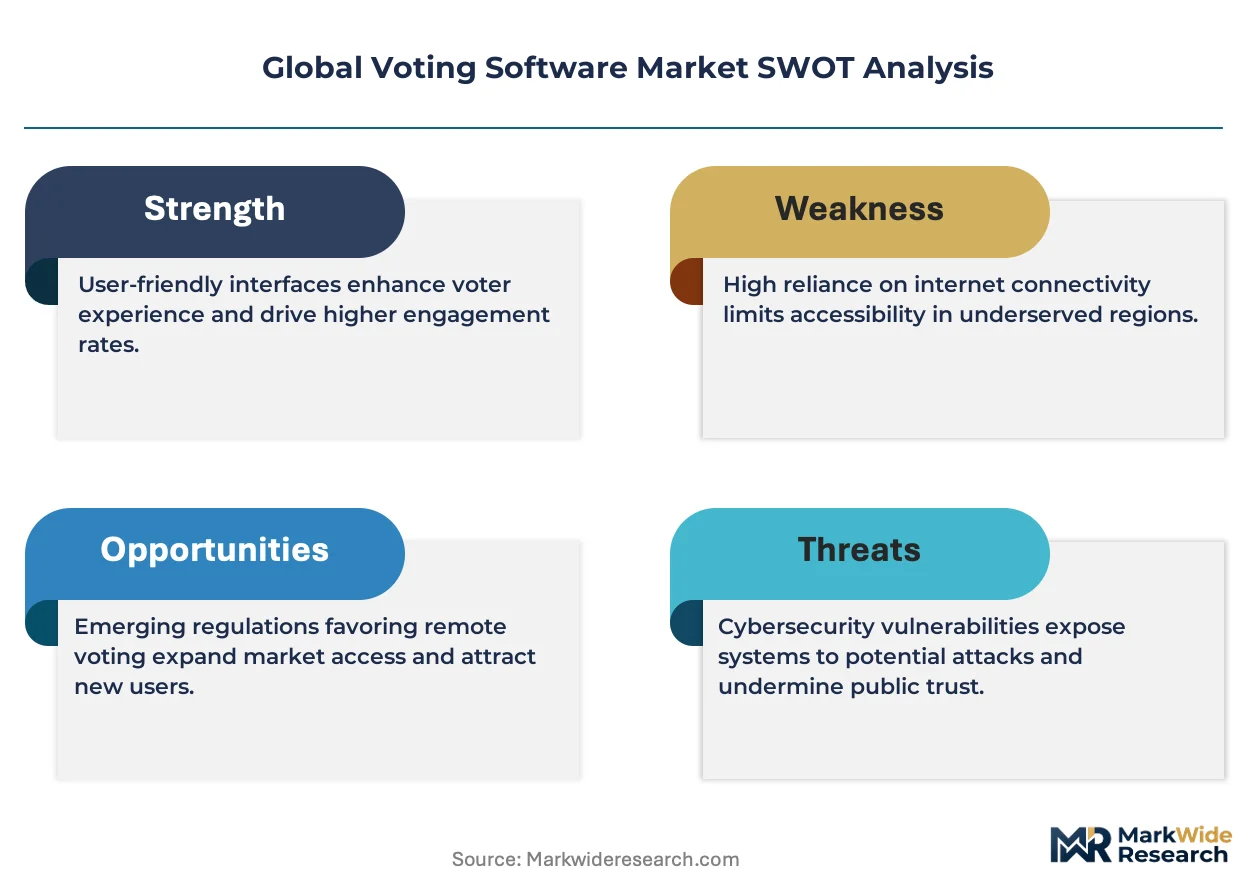
The divergence between hardware-integrated election infrastructure and pure-play SaaS delivery models is fragmenting procurement pathways across national electoral commissions and corporate governance bodies.
Growth Catalysts
- EU AI Act algorithmic transparency mandates:European electoral authorities now require explainable audit trails for tabulation software, accelerating replacement cycles for legacy black-box systems.
- Blockchain-verified remote voting pilots:India's Election Commission validates cryptographic proof-of-vote mechanisms for overseas citizen participation, creating reference architectures for diaspora enfranchisement.
- ISO 27001 certification as procurement gate:Government tenders in emerging democracies now mandate information security management system compliance, filtering vendor pools.
Market Restraints
- Hardware security module cost concentration:Cryptographic key protection requirements impose capital barriers for SaaS-only entrants lacking manufacturing scale.
- Domestic data localization mandates:India's BIS standards and EU GDPR residency rules fragment cloud architectures and inflate operational complexity.
- Paper-ballot backup statutory requirements:Jurisdictions with mandatory recount provisions limit pure digital adoption regardless of software maturity.
Strategic Opportunities
- Underpenetrated academic and corporate governance segments:Universities and shareholder meeting platforms remain reliant on manual tabulation, presenting SaaS conversion potential.
- Hybrid cloud-airgap architectures:Converged on-premise and encrypted cloud deployments satisfy security-conscious government buyers without full capital burden.
- Military and overseas absentee voting automation:Remote credential verification using biometric-mobile convergence addresses historically disenfranchised voter cohorts.
Industry Challenges
- Specialized cryptographic engineering talent scarcity:Election software requires rare cross-functional expertise combining secure coding, hardware integration, and electoral law compliance.
- Federal certification timeline compression:U.S. Election Assistance Commission and NIST guideline updates lag software release cycles, delaying market entry.
- Legacy optical scan infrastructure interoperability:Decades-old county-level device fleets resist API standardization, complicating modular software upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Voting Software Market |
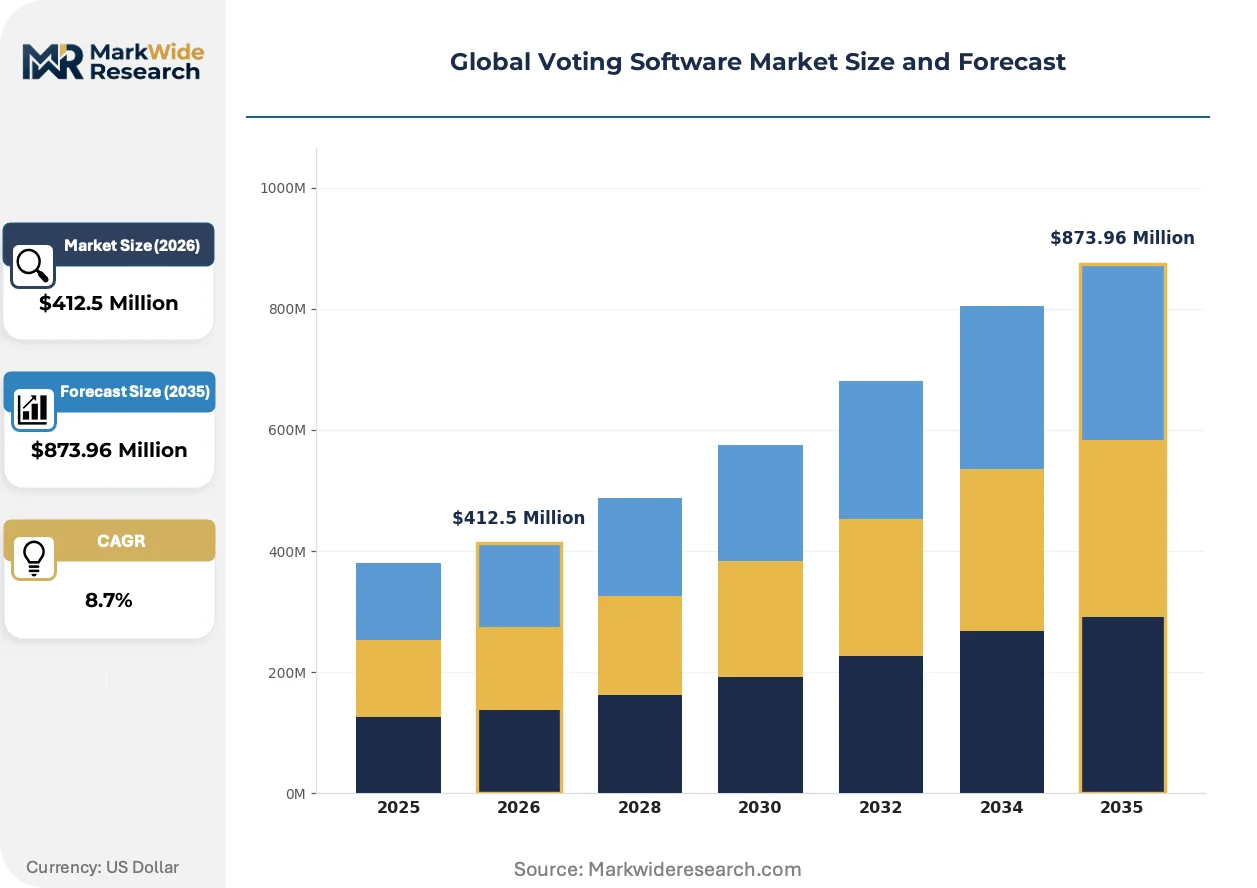
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $873.96 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, Hosted Application: Government Elections, Corporate Elections, Academic Institutions, Non-Profit Organizations, Shareholder Voting Technology: Blockchain, Biometric Authentication, Optical Scan, Electronic Poll Books, End-to-End Encryption End User: Election Commissions, Polling Agencies, Corporate Entities, Universities, Advocacy Groups |
| Companies Covered | Smartmatic, Dominion Voting Systems, Election Systems & Software, Hart InterCivic, Scytl Election Technologies, Simply Voting Inc., ElectionBuddy Inc., BigPulse Voting Pty Ltd, Voatz, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Voting Software Market Shifts & Advancements
Software-defined tabulation is eroding the hardware-software bundling that historically dominated electoral procurement, while regulatory fragmentation forces architectural specialization by geography.
Blockchain-based immutable audit logging is supplanting centralized database record-keeping in pilot deployments for military and overseas voting. National electoral bodies in India and select European member states are validating distributed ledger architectures for voter-verified paper audit trail enhancement. This shift is compressing vendor differentiation around cryptographic proof mechanisms rather than interface design or reporting features.
The EU AI Act risk classification framework now categorizes election management systems as high-risk AI applications, mandating conformity assessment procedures and post-market monitoring. Vendors serving European member states must document algorithmic decision pathways and maintain human oversight protocols for tabulation anomalies. This regulatory architecture is bifurcating product roadmaps, with EU-bound platforms diverging from U.S. and other jurisdiction variants on transparency and explainability features.
Electoral commissions are unbundling device procurement from software licensing, compressing traditional multi-cycle bundled contracts. County-level buyers in the United States now separately source ballot-marking devices, optical scanners, and tabulation platforms, fragmenting vendor relationships. This purchasing pattern shift is most visible in competitive procurement jurisdictions where federal Help America Vote Act funding flexibility enables modular acquisition strategies.
Global Voting Software Market Segmentation
Segmentation in voting software reveals how procurement pathways fracture across security postures, regulatory jurisdictions, and organizational risk appetites. Buyers sort into irreconcilable camps—air-gapped government purists versus cloud-native corporate adopters—with technology choices hardening these divides.
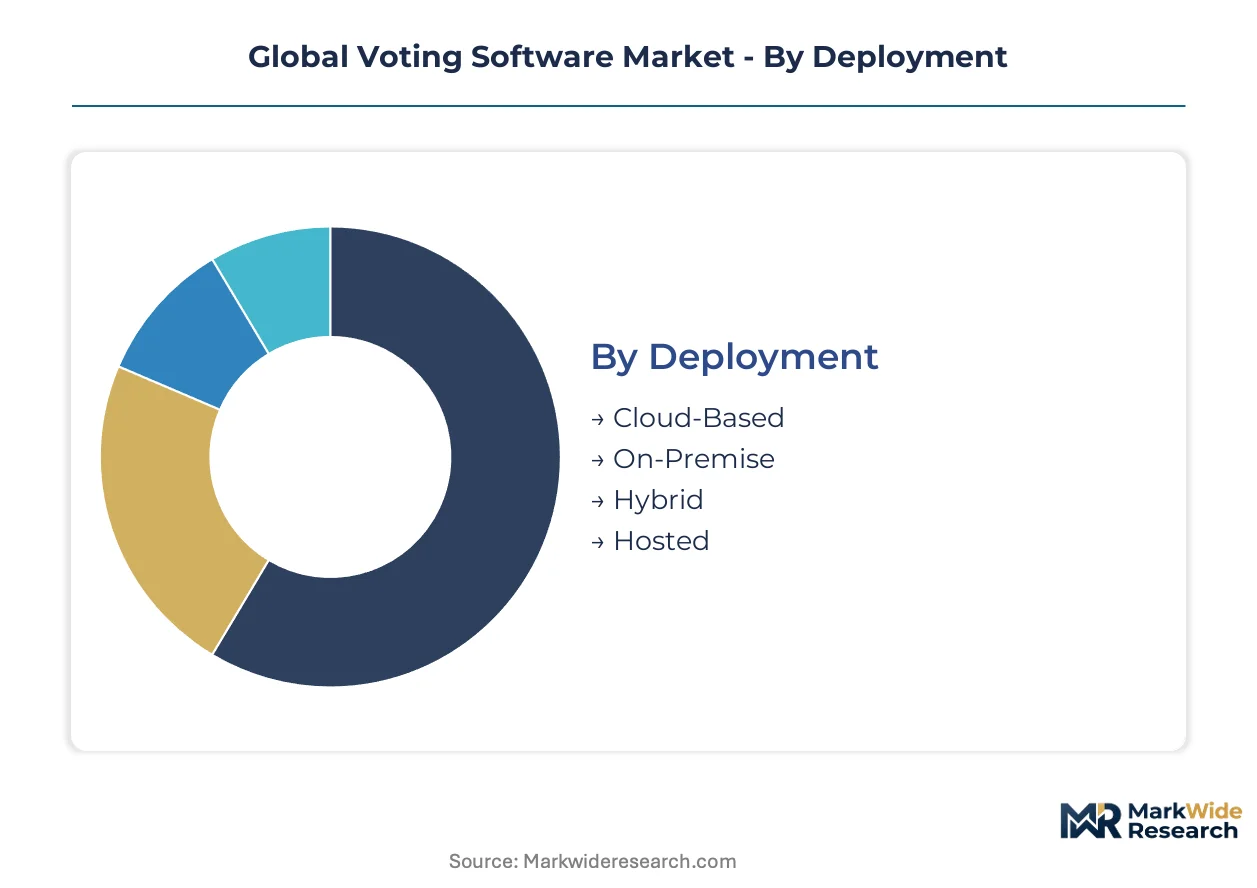
Deployment:
Substitution pressure runs deepest where cloud economics confront sovereign data mandates, forcing architectural hybrids that satisfy neither pure-play camp.
- Cloud-Based:Multi-tenant SaaS architectures with ISO 27001-certified data centers enable rapid provisioning for corporate shareholder meetings and university governance. Procurement concentrates in North American and European private-sector buyers where GDPR and state-level privacy laws permit transnational hosting.
- On-Premise:Air-gapped server installations with hardware security module integration serve national election commissions in India and Brazil demanding domestic data localization. Capital intensity and multi-year depreciation schedules lock buyers into single-vendor relationships spanning hardware and software maintenance.
- Hybrid:Split architectures isolate tabulation engines on-premise while pushing voter registration and result reporting to encrypted cloud gateways. India's Election Commission pilots this model for overseas citizen voting, bridging security and accessibility requirements.
- Hosted:Dedicated single-tenant cloud instances with jurisdictional data residency guarantees address mid-tier government buyers lacking capital for full on-premise builds. Operational expenditure models attract sub-national electoral bodies in Germany and Canada.
On-Premise retains volume leadership; Cloud-Based holds the steepest expansion curve.
Application:
Cost tiering separates capital-constrained buyers seeking per-election licensing from institutions amortizing platforms across recurring voting cycles.
- Government Elections:Federal and sub-national electoral commissions deploy end-to-end encrypted tabulation with voter-verified paper audit trails. Procurement in India and Brazil drives demand for biometric-mobile credential verification at polling stations.
- Corporate Elections:Board resolutions and shareholder proxy voting migrate to SaaS platforms with real-time quorum verification. North American and European publicly traded companies dominate this segment, driven by SEC and ESMA disclosure timeline pressures.
- Academic Institutions:Student government and faculty senate elections adopt lightweight cloud solutions with ranked-choice voting modules. Underpenetration persists at research universities in Australia and South Korea still using manual tabulation.
- Non-Profit Organizations:Membership-driven advocacy groups require low-cost, high-integrity voting for bylaws amendments. Demand clusters in European civil society organizations navigating CSRD governance disclosure requirements.
- Shareholder Voting:Specialized platforms integrate with proxy advisory services and institutional investor voting policies. Reforms to the UK's Stewardship Code and Australia's Corporate Governance Principles accelerate platform consolidation.
Government Elections commands the largest procurement budgets; Corporate Elections is gaining share fastest.
Technology:
Volume concentration favors mature optical infrastructure while emerging cryptographic methods capture pilot investment and regulatory attention.
- Blockchain:Distributed ledger architectures generate cryptographic proof-of-vote receipts for military and overseas absentee ballots. India's Election Commission validates these mechanisms for diaspora enfranchisement, creating reference implementations for other jurisdictions.
- Biometric Authentication:Fingerprint and iris recognition systems reduce duplicate registration and impersonation at polling stations. Deployment concentrates in African and South Asian electoral commissions seeking to clean voter rolls ahead of high-stakes national contests.
- Optical Scan:Paper ballot digitization with centralized tabulation dominates transactional volume due to mandatory recount provisions in U.S. state law. County-level procurement in swing states sustains multi-decade equipment refresh cycles.
- Electronic Poll Books:Tablet-based voter check-in replaces paper rolls, reducing queue times and enabling real-time turnout analytics. Adoption accelerates in Canadian provinces and German municipalities modernizing precinct operations.
- End-to-End Encryption:Cryptographic protocols protecting ballot secrecy in transit and at rest underpin all certified platforms. EU AI Act high-risk system classification mandates third-party conformity assessment for implementations serving European electoral bodies.
Optical Scan retains volume leadership; Blockchain holds the steepest expansion curve.
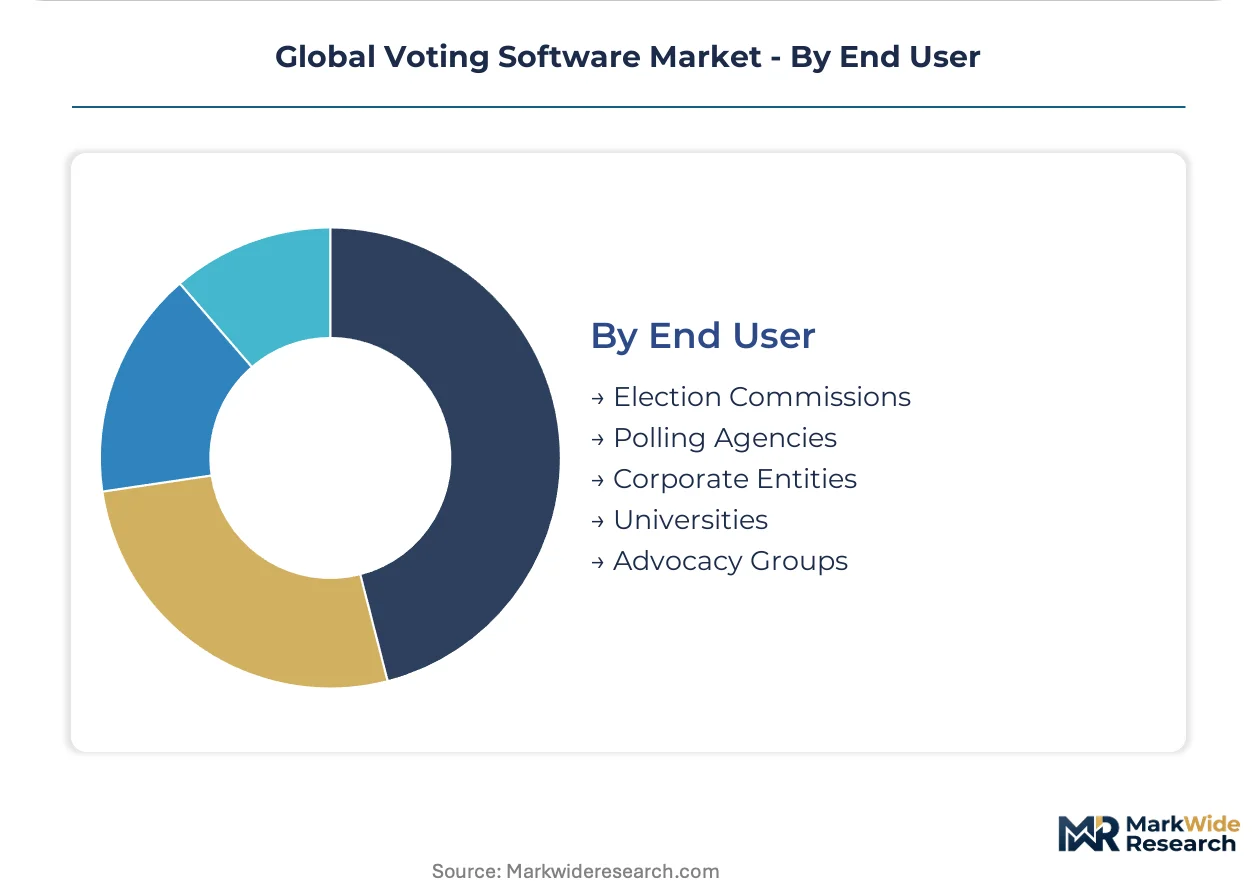
End User:
Customer type determines procurement complexity, with sovereign buyers imposing certification barriers that exclude pure-play SaaS vendors.
- Election Commissions:National and sub-national electoral management bodies mandate hardware-integrated solutions with domestic data localization. India's BIS standards and EU GDPR residency rules fragment vendor eligibility across geographies.
- Polling Agencies:Private election administration contractors serving political parties and trade unions require rapid-deployment platforms with customizable ballot design. Demand clusters in Latin American and Southeast Asian markets with frequent electoral cycles.
- Corporate Entities:Fortune 500 and mid-cap companies seek SOC 2 Type II certified platforms for board and shareholder governance. North American buyers prioritize proxy advisor integration; European buyers emphasize CSRD-aligned audit documentation.
- Universities:Research institutions and liberal arts colleges adopt ranked-choice and multi-winner voting methods for faculty and student governance. Procurement lags in East Asian academic systems with centralized administrative control.
- Advocacy Groups:Membership organizations with dispersed constituencies leverage mobile-optimized voting for bylaws ratification. Grassroots campaign finance reform drives adoption in U.S. and Canadian civil society sectors.
Election Commissions retain volume leadership; Corporate Entities is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across electoral procurement regimes, with emerging democracies prioritizing per-cycle licensing costs while established jurisdictions absorb capital-intensive hardware integration. Sovereign buyers in India and Brazil demand domestic manufacturing content, compressing margins for foreign-hosted platforms. Corporate and academic segments in North America and Europe trade security absolutism for cloud elasticity and rapid deployment.
United States
County-level election administration drives fragmented procurement across optical scan and ballot-marking device refresh cycles. The U.S. Election Assistance Commission and NIST voluntary voting system guidelines shape federal certification timelines, compressing vendor eligibility windows. Swing-state counties in Pennsylvania, Michigan, and Arizona sustain multi-decade equipment replacement schedules amid Help America Vote Act funding flexibility.
India
The Election Commission pilots blockchain-verified remote voting for overseas citizens, validating cryptographic proof-of-vote architectures for diaspora enfranchisement. BIS standards and domestic data localization mandates force foreign vendors into joint venture structures or local hosting partnerships. Hyderabad and Bangalore clusters concentrate engineering talent for biometric-mobile credential verification systems deployed at polling stations.
Germany
Sub-national electoral bodies in Bavaria and North Rhine-Westphalia modernize precinct operations through electronic poll book adoption. The EU AI Act high-risk system classification mandates third-party conformity assessment for tabulation platforms serving European electoral bodies. Berlin-based procurement agencies emphasize CSRD-aligned audit documentation for municipal governance technology acquisitions.
Brazil
Biometric authentication deployment accelerates ahead of high-stakes national contests, with fingerprint and iris recognition systems reducing duplicate registration. The national electoral authority mandates hardware-integrated solutions with domestic manufacturing content, filtering pure-play SaaS vendors. São Paulo state concentrates systems integration capacity for multi-cycle national election infrastructure contracts.
United Kingdom
Reforms to the Stewardship Code accelerate platform consolidation for shareholder voting and proxy advisory integration. The Information Commissioner's Office enforces GDPR residency constraints on electoral data processing, fragmenting cloud architectures for vendors serving British issuers. London's financial services cluster drives demand for real-time quorum verification in listed company governance.
Global Voting Software Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with hardware-integrated platform providers commanding multi-cycle government contracts while pure-play SaaS vendors capture corporate and academic segments. The bifurcation reflects irreconcilable security postures: air-gapped sovereignty versus cloud-native accessibility. Three archetypes dominate—end-to-end election infrastructure integrators, modular software licensors, and vertical SaaS specialists. Competitive moves concentrate on geographic certification stacking and hybrid architecture development to bridge procurement pathway fragmentation.
Within the integrated infrastructure tier, Smartmatic leverages its Latin American and African footprint to sustain national electoral body relationships, while Dominion Voting Systems anchors position through U.S. manufacturing scale and county-level deployment networks. Scytl Election Technologies occupies a position bridging government and private-sector segments with hosted single-tenant architectures. These three exemplify how vendor archetypes align with divergent buyer risk appetites across sovereign, corporate, and academic procurement channels.
| Leading Market Players |
|---|
| Smartmatic |
| Dominion Voting Systems |
| Election Systems & Software |
| Hart InterCivic |
| Scytl Election Technologies |
| Simply Voting Inc. |
| ElectionBuddy Inc. |
| BigPulse Voting Pty Ltd |
| Voatz |
| Others |
Supply & Pricing Matrix
Manufacturing scale in hardware security module production concentrates supplier power among U.S. and German component vendors, establishing price floors that filter SaaS-only entrants from multi-cycle government contracts. This scale asymmetry forces procurement bifurcation: capital-intensive on-premise deployments absorb depreciation-heavy cost structures while cloud-native corporate buyers negotiate subscription elasticity against ISO 27001 certification premiums.
Pricing Analysis
Multi-year service and maintenance contracts generate lifetime value exceeding initial licensing revenue by substantial margins across government electoral commissions. Pricing stratifies across premium, standard, and economy tiers based on hardware integration depth and EU AI Act conformity assessment tier. Cost compression in pure-play SaaS segments intensifies as corporate governance buyers consolidate vendor relationships. Academic institutions exhibit highest price sensitivity; national election commissions absorb premium tiering for air-gapped sovereignty.
Supply Chain Analysis
Strategic stockpiling of cryptographic processors and hardware security modules dominates procurement patterns given federal certification timeline rigidity. Component manufacturing concentrates in the United States, Germany, and Taiwan. Raw material dependencies span silicon wafers, tamper-evident enclosure substrates, and specialized firmware. Single-source vulnerability in FIPS 140-2 certified chip supply creates systemic exposure. Distribution runs through systems integrators holding national electoral body relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward county-level procurement officers in the United States as federal Help America Vote Act funding flexibility enables modular unbundling of device and software acquisitions. This fragmentation fragments vendor lock-in and compresses pricing leverage for integrated infrastructure providers.
For Market Incumbents: Consolidate certification stacking across EU AI Act, GDPR, and India's BIS standards to defend against modular SaaS entrants. Deepen backward integration into hardware security module production to offset cryptographic engineering talent scarcity. Prioritize hybrid cloud-airgap architecture R&D to bridge procurement pathway divergence. For New Entrants and Emerging Players: Lead with lightweight SaaS platforms targeting underpenetrated academic institutions in Australia and South Korea still using manual tabulation. Corporate shareholder voting in North America offers fastest penetration given SEC disclosure timeline pressures. Position through proxy advisor integration partnerships rather than direct electoral commission sales cycles. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vendors with cryptographic proof-of-vote patent portfolios and military absentee voting pilot references. Long-term viability hinges on navigating divergent national data localization mandates without architecture fragmentation. Watch India's Election Commission blockchain pilot outcomes as inflection indicator for diaspora enfranchisement market expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Cloud-Airgap Architecture Development | Bridges security-conscious government buyers with operational expenditure flexibility. |
| EU AI Act Conformity Assessment Investment | Opens procurement eligibility across European electoral commissions and corporate issuers. |
| Biometric-Mobile Credential Verification Integration | Addresses India's Election Commission requirements for polling station modernization. |
| Blockchain Proof-of-Vote Patent Portfolio | Captures reference architecture status for military and overseas absentee voting pilots. |
| Proxy Advisor Platform Integration | Accelerates SaaS conversion in North American corporate governance segments. |
Research Methodology
A spread of perspectives from electoral commission procurement officers, hardware security module engineers, SaaS platform architects, and corporate governance compliance leads converged on the working assumptions. Primary field engagement combined with secondary validation against U.S. Election Assistance Commission certification databases, EU AI Act implementation guidance, India's BIS standards documentation, and NIST voting system guidelines. Bottom-up segment sizing and top-down macro constraint triangulation anchored volume and value estimates.
Segmentation dimensions modeled span deployment architecture, application category, underlying technology, and end-user type across the projection horizon. CAGRs derived from fitted growth curves against historical procurement cycle data and regulatory mandate implementation schedules. Industry-specific forecast inputs include federal funding authorization trajectories and overseas citizen enfranchisement policy momentum.
Forecasts assume regulatory continuity in EU AI Act enforcement, India's BIS localization mandates, and U.S. EAC certification timelines; material policy shifts would require re-modeling. Revision becomes warranted when blockchain pilot validation outcomes or hardware security module supply disruptions cross thresholds affecting vendor eligibility or procurement cycle timing.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Driving School Software Market
Software & Services
Newsroom Software Market
Software & Services
Global Calendar Scheduling Software Market
Software & Services
Workflow Automation and Optimization Software Market
Software & Services
Cloud Testing and ASQ Software Market
Software & Services
Global Club Management Software Market
Software & Services
Smartphone OS Market
Software & Services
Spend Analysis Software Market
Software & Services
Online Lottery Software Market
Software & Services
LTFS Copy Software Market
Software & Services
VFX Software Market
Software & Services
HR Saas Market
Software & Services
Embedded Graphical User Interface (GUI) Development Software Market
Software & Services
APAC Interior Design Software Market
Software & Services
Business Rules Management System Market
Software & Services
User Feedback Software Market