
 Legal Software Market | 2026-2036
Legal Software Market Size, Share, and Industry Trends Forecast 2026-2036
Legal Software Market Analysis
Proprietary on-premise infrastructure is consolidating around cloud-native architectures, collapsing deployment timelines and reshaping vendor economics. Harvey leverages generative AI to automate contract analysis and due diligence workflows for enterprise legal teams. Clio sustains dominance in small-to-midsize law firm practice management through deep channel partnerships with bar associations. iManage anchors high-stakes document and email management for Magic Circle and White Shoe firms requiring stringent security protocols.
Legal software encompasses applications that manage case lifecycles, automate document generation, track billable hours, and ensure regulatory compliance through encrypted, permissioned databases with audit trails. Cloud-based deployment leads segment expansion as law firms abandon capital-intensive server maintenance for subscription models with automatic security patches. Case management tools capture the fastest growth trajectory, driven by unified workflow demands from litigation-heavy practices. On-premise installations persist only in jurisdictions with data sovereignty mandates or client-mandated air-gapped environments.
The EU AI Act imposes transparency obligations on automated legal decision tools, compelling vendors to document training data provenance and human oversight mechanisms. State bar ethics committees in California and New York are issuing formal opinions on AI-assisted legal research competence standards, directly influencing product roadmap prioritization. The SEC's cybersecurity disclosure rules for public companies extend liability frameworks to legal software handling material contract data. Stakeholders must monitor evolving professional responsibility standards that will determine which automation features qualify as authorized practice of law.
Market Dynamics
Generative AI deployment is compressing contract review cycles from weeks to hours, forcing vendors to reprice subscription tiers around automation depth rather than seat counts. This shift is redistributing value capture toward inference-layer providers and away from traditional per-matter billing structures.
Growth Catalysts
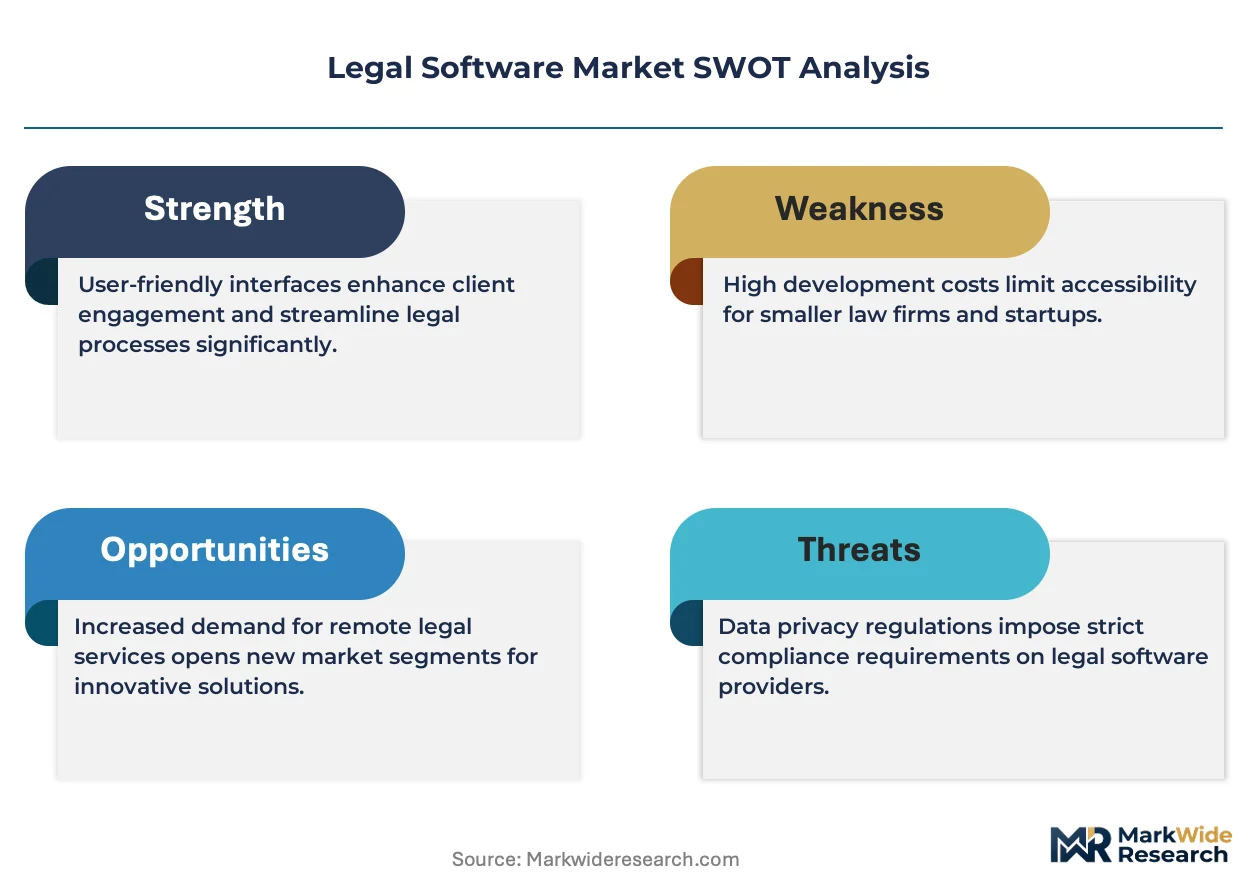
- EU AI Act transparency mandates:Automated decision documentation requirements create recurring compliance software demand across European legal departments. Vendors embedding audit-trail functionality capture premium positioning.
- SEC cybersecurity disclosure rules:Public company legal teams must instrument contract databases for material incident reporting, driving encrypted repository upgrades.
- Magic Circle firm cloud migration:London-headquartered practices abandoning air-gapped servers for private cloud instances normalize security architectures for mid-market adoption.
Market Restraints
- GPU compute cost volatility:Large language model inference expenses fluctuate with semiconductor supply constraints, squeezing vendor margins on fixed-price AI features.
- State bar ethics opinion fragmentation:Divergent competence standards across California, New York, and Texas create product localization burdens that slow multi-jurisdictional rollouts.
- Client-mandated data sovereignty:Financial services and government legal work requires jurisdictional data residency, preventing full cloud consolidation.
Strategic Opportunities
- India legal process outsourcing integration:Hybrid platforms connecting Western law firms with Indian document review centers capture labor arbitrage value through unified workflow orchestration.
- Convergence of contract lifecycle management and spend analytics:Combined legal operations and procurement dashboards penetrate Fortune 500 legal departments seeking vendor consolidation.
- State-level data privacy statute proliferation:California, Virginia, Colorado, and Connecticut patchwork laws generate recurring compliance module demand for multi-state practices.
Industry Challenges
- Prompt engineering talent scarcity:Legal domain expertise combined with LLM fine-tuning skills commands compensation premiums that vendor R&D budgets struggle to absorb.
- Legacy document management system integration:Decades of iManage and OpenText deployments create data migration friction that extends implementation timelines and strains customer success teams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Legal Software Market |
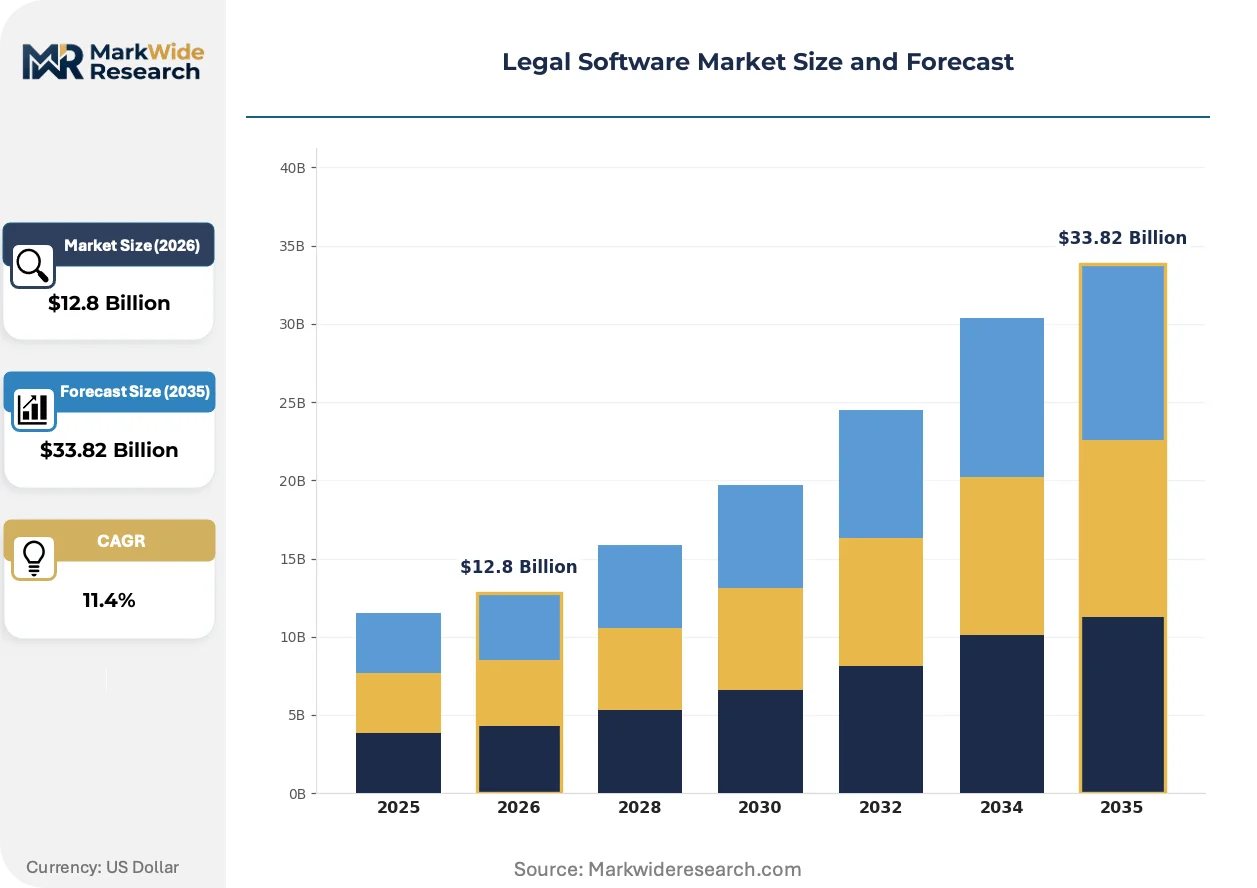
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $33.82 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Document Management, Case Management, Time Tracking, E-Billing End User: Law Firms, Corporations, Government Agencies, Compliance Departments Deployment: Cloud-Based, On-Premise, Hybrid, Mobile Feature: Automation, Analytics, Integration, Collaboration Tools |
| Companies Covered | Harvey, Brightflag, Clio, Smokeball, iManage, Relativity, Filevine, Nextpoint, Everlaw, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Legal Software Market Emerging Trajectories
Foundation model fine-tuning for legal corpora is commoditizing point-solution AI features, collapsing the pricing power of standalone contract analytics vendors. This compression is forcing platform consolidation and API-layer specialization.
Retrieval-augmented generation architectures are expanding into due diligence and discovery workflows, grounding LLM outputs in verified clause libraries and precedent databases. Am Law 200 firms piloting these systems report 40-60% reduction in first-pass review hours. The structural consequence is a workforce recomposition toward senior attorney oversight and away from associate document grinding.
The EU AI Act's risk classification framework for legal decision support tools is compelling vendors to document training data provenance and human-in-the-loop protocols. High-risk system providers must maintain conformity assessment records accessible to national market surveillance authorities. German and French legal departments are advancing procurement requirements that disqualify non-compliant vendors from RFP processes.
Subscription fatigue among mid-size law practices is accelerating preference for consumption-based pricing tied to matter volume rather than per-attorney licensing. This behavioral shift pressures incumbent practice management platforms to unbundle feature tiers and introduce metered billing. The Southwest and Mountain West US markets exhibit the fastest migration toward this model, driven by regional firm consolidation and shared services arrangements.
Legal Software Market Segmentation
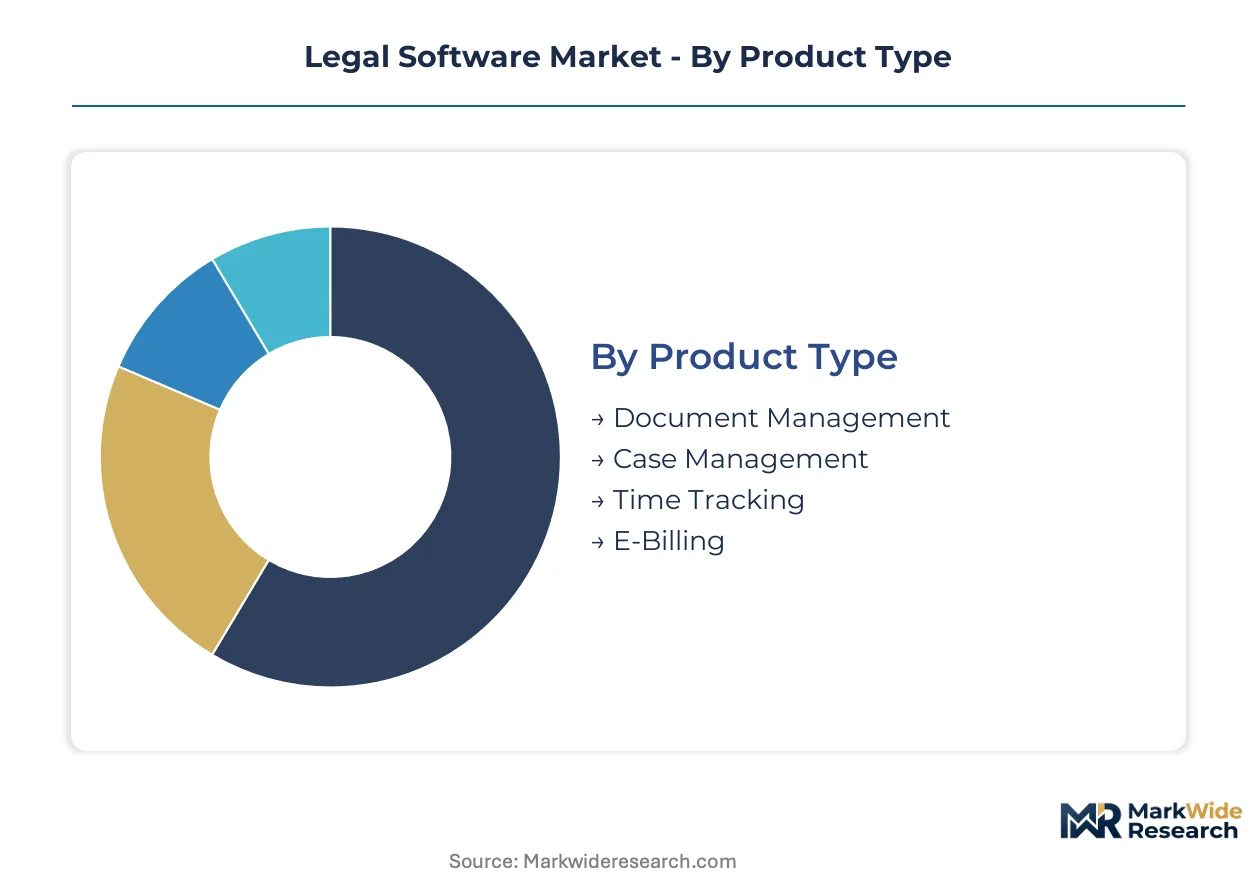
Legal software procurement decisions hinge on regulatory compliance burdens, data residency mandates, and workflow complexity. Segmentation reveals which product configurations align with specific jurisdiction requirements and client risk profiles.
Product Type:
EU AI Act conformity assessments and SEC cybersecurity disclosure rules impose distinct certification loads across product categories.
- Document Management:Encrypted repositories with granular permission hierarchies and immutable audit trails. Am Law 200 firms in New York and London drive demand for AI-assisted contract classification that satisfies EU AI Act transparency mandates.
- Case Management:Unified workflow platforms orchestrating litigation timelines, calendaring, and court filing integrations. Litigation-heavy practices in California and Texas concentrate procurement here, compelled by state bar ethics opinions on AI-assisted competence standards.
- Time Tracking:Automated capture systems with ethical wall protocols separating billable from non-billable activities.
- E-Billing:LEDES-standard invoice validation with outside counsel spend analytics and accrual forecasting.
Leading the category by volume: Document Management. Growing fastest: Case Management.
End User:
Cost tier stratification separates enterprise-grade security investments from mid-market subscription thresholds.
- Law Firms:Practice management platforms spanning solo practitioners to Magic Circle partnerships. Fortune 500 legal operations in the United States anchor premium segment spending, while bar association channel partnerships penetrate regional markets.
- Corporations:In-house legal departments integrating contract lifecycle management with procurement systems. Multi-state data privacy compliance in California, Virginia, and Colorado drives modular feature expansion.
- Government Agencies:Air-gapped deployments with FedRAMP or equivalent sovereign certification requirements.
- Compliance Departments:Regulatory monitoring tools tracking EU AI Act, GDPR, and patchwork US state privacy statute evolution.
Highest security spend: Law Firms. Fastest feature adoption: Corporations.
Deployment:
Application context dictates infrastructure choice — client-mandated data sovereignty overrides cloud economics in regulated sectors.
- Cloud-Based:Subscription models with automatic security patching and elastic compute for generative AI inference. Mid-market US firms in the Southwest and Mountain West exhibit steepest expansion trajectory toward consumption-based pricing.
- On-Premise:Capital-intensive server maintenance persisting only where financial services or government clients mandate jurisdictional data residency.
- Hybrid:Sensitive matter data on-premise with collaboration layers in private cloud instances.
- Mobile:iOS and Android applications with biometric authentication and offline document access.
Dominant architecture: Cloud-Based. Constrained growth: On-Premise.
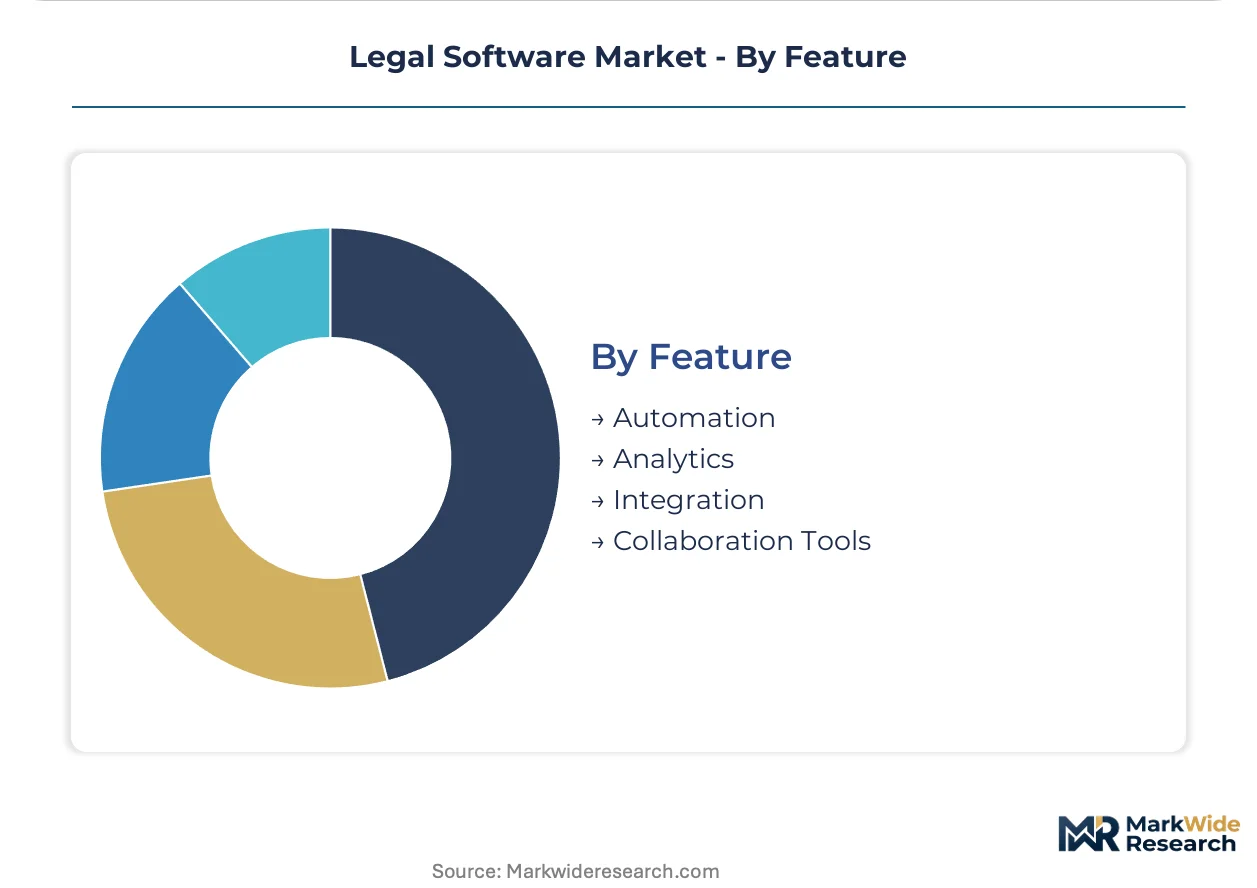
Feature:
Customer type segmentation separates automation depth investments from baseline collaboration requirements.
- Automation:Generative AI contract analysis, due diligence acceleration, and document generation grounded in retrieval-augmented generation architectures. Harvey and comparable vendors compress review cycles from weeks to hours for enterprise legal teams.
- Analytics:Spend forecasting, matter outcome prediction, and vendor performance dashboards. Fortune 500 legal operations demand convergence with procurement analytics for unified vendor consolidation.
- Integration:API connectivity with iManage, OpenText, and legacy document management systems.
- Collaboration Tools:Real-time co-authoring, client portal access, and secure external sharing with ethical wall enforcement.
Top RFP priority: Automation. Emerging requirement: Analytics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Legal software procurement concentrates in jurisdictions with dense corporate litigation activity and stringent data governance frameworks. The United States, United Kingdom, Germany, Japan, and India collectively anchor enterprise adoption curves.
United States
Am Law 200 firms and Fortune 500 legal operations drive cloud migration at scale. SEC cybersecurity disclosure rules compel encrypted contract repository upgrades for public company clients. New York and California legal departments pilot retrieval-augmented generation architectures for due diligence compression.
United Kingdom
Magic Circle partnerships normalize private cloud security architectures for mid-market adoption. The EU AI Act imposes transparency obligations on automated legal decision tools deployed across London-headquartered practices. The City of London financial district mandates jurisdictional data residency for sensitive matter files.
Germany
Industrial conglomerate legal departments integrate contract lifecycle management with procurement analytics. National market surveillance authorities enforce EU AI Act conformity assessments for high-risk legal decision support systems. Frankfurt and Munich legal operations lead private cloud instance deployment among DAX-listed enterprises.
Japan
Keiretsu corporate legal teams adopt hybrid deployment models balancing cloud collaboration with on-premise sensitive data retention. METI guidelines on AI governance influence vendor selection criteria for enterprise legal departments. Tokyo legal operations anchor regional adoption of automated document generation platforms.
India
Legal process outsourcing centers capture labor arbitrage value through unified workflow orchestration with Western law firms. The country's national data protection framework shapes client-mandated data sovereignty requirements for cross-border matter handling. Bangalore and Hyderabad legal technology delivery centers expand retrieval-augmented generation pilot programs.
Legal Software Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with platform consolidation accelerating around cloud-native architectures. The vendor base stratifies into three tiers: inference-layer specialists, practice management incumbents, and legacy document management anchors. Dominant competitive moves include M&A-driven feature bundling and geographic expansion through bar association channel partnerships.
Among North American platform vendors, Harvey, Clio, and iManage occupy distinct archetype positions. Harvey exemplifies the inference-layer specialist model, Clio anchors the mid-market practice management tier through channel density, and iManage represents the legacy document management incumbent defending high-security segments. These three collectively illustrate how vendor economics redistribute toward automation depth and away from per-seat licensing structures.
| Leading Market Players |
|---|
| Harvey |
| Brightflag |
| Clio |
| Smokeball |
| iManage |
| Relativity |
| Filevine |
| Nextpoint |
| Everlaw |
| Others |
Supply Flow & Price Mechanics
Prompt engineering talent scarcity in Bangalore and Hyderabad widens pricing-tier spreads between premium AI-enabled suites and baseline practice management tools, as vendors absorb compensation premiums for legal-domain LLM fine-tuning expertise.
Pricing Analysis
Volume concentrates in consumption-based tiers while margins accrue to automation-depth subscriptions. Three-tier pricing structure across premium, standard, and economy levels separates Harvey-grade inference layers from Clio-channel mid-market seats and basic document repositories. Price differentiation hinges on EU AI Act conformity certification and generative AI inference depth. Pricing pressure stems from GPU compute cost volatility squeezing fixed-price AI features. Mid-size Southwest and Mountain West practices exhibit highest price sensitivity; Magic Circle firms show lowest.
Supply Chain Analysis
Freight costs for on-premise server hardware from Taiwan and South Korea sustain hybrid deployment premiums against pure cloud economics. Software supply chains draw from US hyperscaler compute, Indian legal process outsourcing labor, and German-French compliance certification bodies. Raw material dependencies include NVIDIA GPU allocations, encrypted storage arrays, and API-layer orchestration tools. Single-source vulnerability concentrates in foundation model providers. Distribution runs through bar association channel partnerships and direct enterprise sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race. Players are pursuing backward integration into Indian document review centers to capture labor arbitrage and unify workflow orchestration.
For Market Incumbents: Deploy API-layer specialization to defend against inference-layer disintermediation. Consolidate around retrieval-augmented generation architectures that ground outputs in verified clause libraries. Acquire Indian legal process outsourcing capabilities to capture hybrid platform value. Counter GPU compute cost volatility through long-term hyperscaler commitments. For New Entrants and Emerging Players: Launch via consumption-based pricing models targeting Southwest and Mountain West mid-market consolidation. Penetrate state-level data privacy compliance modules for multi-state practices. Exploit subscription fatigue among regional firms. Target bar association channel partnerships for density economics. For Investors and Strategic Acquirers: Re-rating potential sits with inference-layer specialists given EU AI Act transparency mandate acceleration. Long-term viability favors vendors embedding audit-trail functionality and human-in-the-loop protocols. Watch German and French procurement requirements disqualifying non-compliant vendors as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into LPO Centers | Captures labor arbitrage value through unified workflow orchestration with Western firms. |
| EU AI Act Conformity Certification | Opens German and French procurement pipelines requiring documented training provenance. |
| Retrieval-Augmented Generation Deployment | Compresses due diligence cycles by grounding LLM outputs in verified precedent databases. |
| Consumption-Based Pricing Unbundling | Addresses subscription fatigue in Southwest and Mountain West mid-market consolidation. |
| Bar Association Channel Deepening | Replicates Clio's density economics for regional market penetration and retention. |
Methodological Framework
SEC filings, EU regulatory submissions, and hyperscaler capex disclosures formed the secondary backbone. Primary interviews with legal technology CTOs, law firm managing partners, corporate legal operations directors, and bar association technology committees validated demand assumptions. Bottom-up triangulation across vendor revenue disclosures and top-down macroeconomic modeling anchored projections.
Historical trendline analysis tracked cloud migration velocity and generative AI adoption curves across the analysis window. Segmentation dimensions modeled deployment model, organization size, practice area complexity, and regional regulatory cluster. CAGRs derived from elasticity-adjusted penetration curves and vendor pricing trajectory analysis. Forecast inputs included GPU supply constraints and state bar ethics opinion fragmentation timelines.
Regulatory enforcement variance, foundation model commoditization acceleration, and prompt engineering talent availability are the dominant revision risks. Forecasts reflect assumptions about EU AI Act implementation pacing and SEC cybersecurity disclosure adoption. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Strategy Management Software Market
Software & Services
API Testing Market
Software & Services
Time Series Databases Software Market
Software & Services
Global Charity Accounting Software Market
Software & Services
Architectural Rendering Software Market
Software & Services
Global Distribution Software Market
Software & Services
Enterprise Capture Software Market
Software & Services
Meditation Management Apps Market
Software & Services
Office Productivity Software Market
Software & Services
Talent Acquisition Software Market
Software & Services
Skills Management Software Market
Software & Services
User Research Repositories Software Market
Software & Services
Remote Browser Market
Software & Services
Global Affiliate Software Market
Software & Services
Shift Planning Software Market
Software & Services
Global Application Development Software Market