
 Global Accreditation Management Software Market | 2026-2036
Global Accreditation Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Accreditation Management Software Market Foresight
Platform licensing revenue is tilting toward subscription-based cloud delivery as vendors abandon perpetual license models. Watermark leverages deep integration with learning management ecosystems to sustain renewal rates among U.S. universities. Qualtrax anchors its position through specialized workflow engines for healthcare compliance audits. Armature Solutions competes on configurable assessment frameworks that reduce implementation cycles for certification bodies.
Accreditation management software comprises configurable platforms that automate standards mapping, evidence collection, peer review coordination, and outcome reporting against institutional or programmatic criteria. These systems typically integrate document control modules, audit scheduling engines, and role-based dashboards to maintain continuous compliance with accreditor requirements. Cloud-based deployment leads solution type demand as educational institutions and certification bodies prioritize remote accessibility and reduced IT overhead. Document control and compliance tracking solution types capture concentrated margin pools due to their regulatory necessity and integration complexity. On-premises installations retain share among government agencies with stringent data sovereignty mandates.
FDA quality system regulations, EU MDR conformity assessment requirements, and ISO 17011 standards for accreditation bodies collectively elevate software sophistication thresholds. CSRD reporting obligations and GDPR data governance rules in Europe are forcing vendors to embed granular audit trails and consent management architectures. Stakeholders must monitor how AI Act risk classification requirements reshape evidence documentation workflows for certification bodies operating across multiple jurisdictions.
Market Dynamics
Cloud-native architectures are compressing deployment timelines for accreditation management platforms, forcing legacy on-premise vendors to accelerate SaaS migrations or face displacement from university and healthcare procurement cycles.
Growth Catalysts
- EU CSRD disclosure mandates:Certification bodies operating across European member states must embed granular audit trails and consent management architectures, expanding platform feature requirements and renewal stickiness.
- Healthcare compliance audits:FDA quality system regulations and ISO 17011 standards for accreditation bodies are elevating workflow automation thresholds, particularly for peer review coordination modules.
- United States higher education cloud migration:Universities are abandoning perpetual license models for subscription-based delivery, prioritizing remote accessibility and reduced IT overhead in procurement decisions.
Market Restraints
- Data sovereignty compliance costs:Government agencies in Germany and Australia require on-premise installations with localized server infrastructure, fragmenting vendor R&D allocation across deployment architectures.
- Integration complexity with legacy LMS ecosystems:Deep embedding with learning management systems creates switching friction that slows competitive displacement but also extends implementation cycles for new entrants.
- Specialized workflow engine development:Healthcare compliance audits demand domain-specific assessment frameworks that concentrate technical talent among vendors with multi-year healthcare vertical investment.
Strategic Opportunities
- AI Act risk classification workflows:Certification bodies operating across multiple jurisdictions must document evidence against EU AI Act requirements, creating demand for configurable standards mapping modules.
- Professional program accreditation in India:BIS standards expansion and CDSCO regulatory alignment are opening procurement channels for cloud-based platforms among technical and medical training institutes.
- API-first architecture convergence:Integration with student information systems and research data repositories is enabling continuous compliance monitoring rather than episodic accreditation cycles.
Industry Challenges
- Evidence collection automation:Natural language processing for unstructured document ingestion remains technically immature, requiring manual curation that compresses margin on fixed-price implementations.
- Multi-jurisdictional audit trail standardization:GDPR consent management architectures must coexist with FDA 21 CFR Part 11 electronic records requirements, complicating single-platform deployment for global certification bodies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Accreditation Management Software Market |
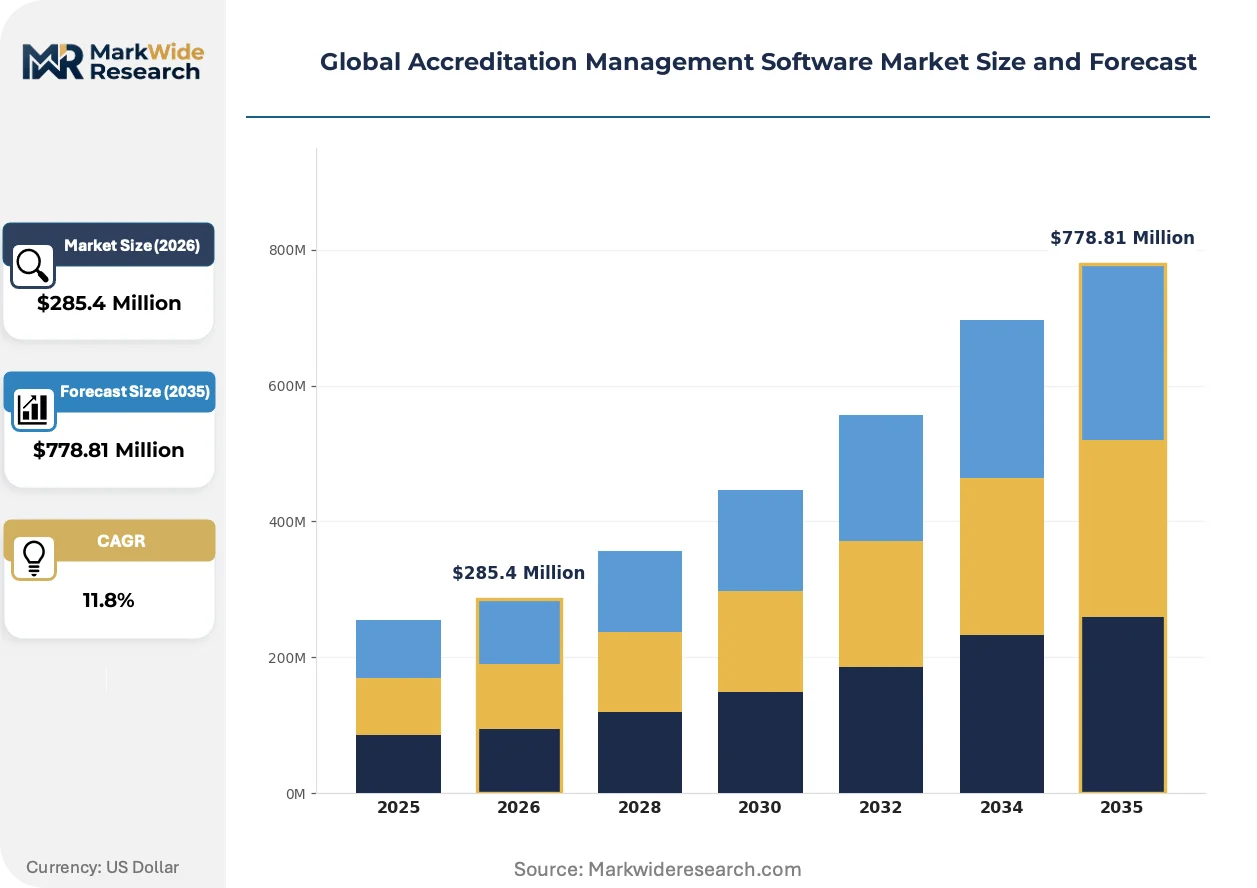
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $778.81 Million |
| CAGR (2026 – 2036) | 11.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, Hosted Solution Type: Document Control, Audit Management, Compliance Tracking, Training Management, Risk Management Application: Certification Bodies, Educational Institutions, Manufacturing Firms, Healthcare Providers, Government Agencies End User: Quality Managers, Compliance Officers, IT Departments, Training Coordinators, Regulatory Authorities |
| Companies Covered | Watermark, Qualtrax, Armature Solutions, Liaison International, Accredible, SoftTech Health, WizeHive, SPOL, Dossier Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Accreditation Management Software Market Shifts & Advancements
Artificial intelligence and machine learning capabilities are embedding into accreditation workflows, compressing evidence review cycles and enabling predictive compliance monitoring that shifts vendor competitive positioning from document storage to outcome analytics.
Natural language processing engines trained on accreditation standards corpora are rendering obsolete manual evidence tagging and peer reviewer assignment processes. Large research universities in the United States and Australia are deploying these tools to reduce preparation cycles for regional accreditor site visits. The structural consequence is collapsing implementation timelines for new programs seeking initial accreditation, compressing the addressable window for professional services revenue.
The EU AI Act risk classification framework is forcing certification bodies to document algorithmic decision-making processes with granular audit trails. Vendors serving European conformity assessment organizations must embed explainability modules that trace evidence weighting through automated assessment workflows. Healthcare technology certifiers in Germany and France are prioritizing platforms with pre-configured high-risk system documentation templates to accelerate CE marking timelines.
Subscription pricing with usage-based tiers is displacing perpetual licensing with annual maintenance in procurement negotiations. University consortiums in Australia and Canada are consolidating vendor relationships through shared service agreements that demand API interoperability and data portability guarantees. This consolidation concentrates purchasing power among fewer buyers while rewarding vendors with established learning management system partnerships and configurable assessment frameworks.
Global Accreditation Management Software Market Segmentation
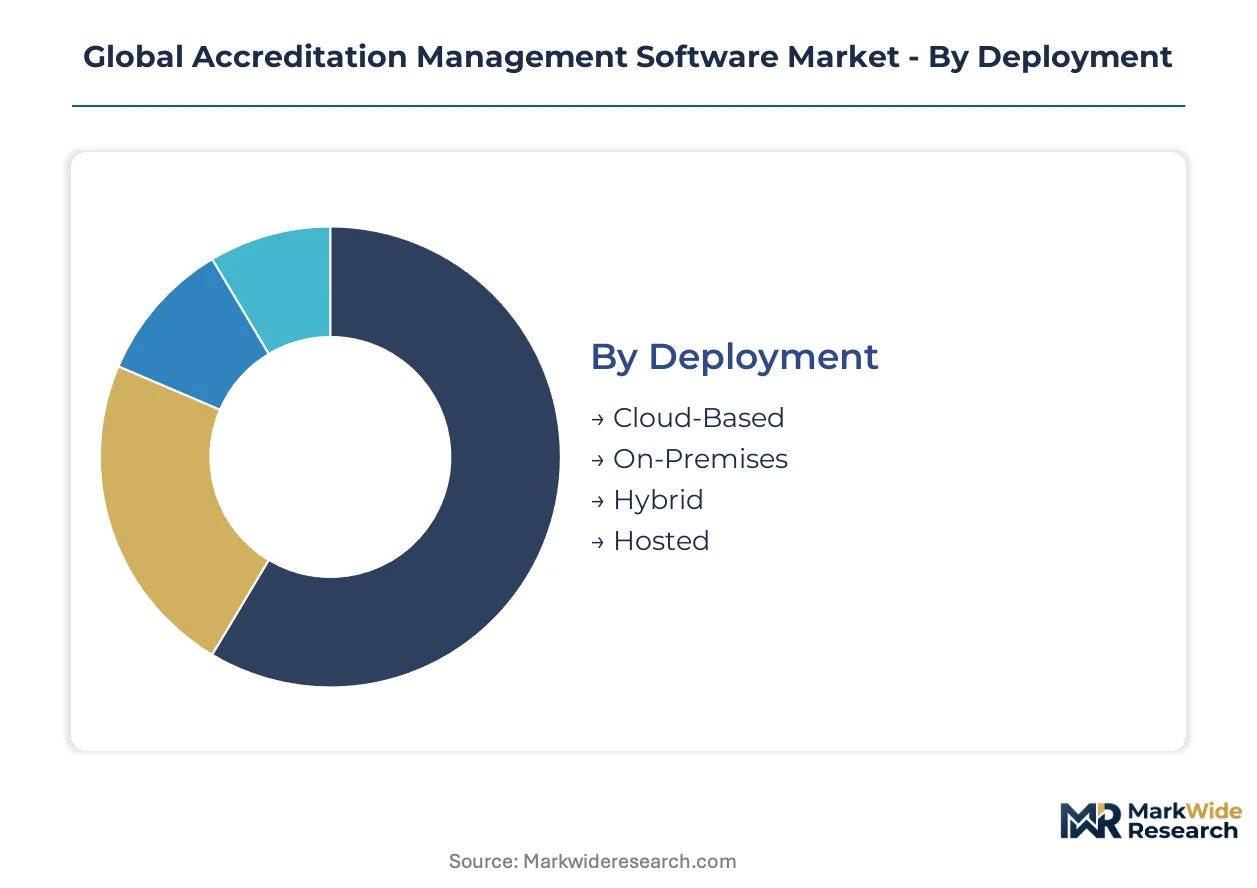
Accreditation management software segments reflect divergent technical requirements across deployment constraints, regulatory complexity, and user workflow integration. Vendors must align architecture decisions with customer IT maturity and compliance documentation intensity.
Deployment:
Cost tier determines infrastructure ownership and operational overhead for accreditation platforms.
- Cloud-Based:Multi-tenant SaaS architectures eliminate server maintenance burdens while enabling remote access for distributed peer review panels. Universities in the United States and Australia prioritize this model to reduce IT staffing overhead during accreditation cycles.
- On-Premises:Localized server installations with dedicated hardware stacks satisfy data sovereignty mandates from German federal agencies and Australian state governments. Procurement cycles extend due to security clearance requirements.
- Hybrid:Split workloads between private cloud instances and on-premise document repositories balance accessibility with sensitive audit trail protection.
- Hosted:Single-tenant managed deployments on vendor-controlled infrastructure serve mid-tier certification bodies seeking customization without capital expenditure.
Cloud-Based commands the established base. The steepest expansion runs through Hybrid configurations as regulated industries seek architectural flexibility.
Solution Type:
Application intensity varies by regulatory documentation volume and audit frequency across verticals.
- Document Control:Version-controlled repositories with granular permission matrices manage evidence artifacts against ISO 17011 and FDA 21 CFR Part 11 requirements. Certification bodies in Germany and France embed these modules for CE marking documentation.
- Compliance Tracking:Continuous monitoring dashboards map institutional performance against evolving CSRD disclosure mandates and EU AI Act risk classifications. European conformity assessment organizations drive feature expansion here.
- Audit Management:Automated scheduling engines coordinate peer reviewer assignments and site visit logistics for higher education accreditors.
- Training Management:Competency tracking modules align staff certifications with accreditation body personnel requirements.
- Risk Management:Predictive analytics flag compliance gaps before formal assessment cycles.
Document Control anchors vendor revenue through renewal stickiness. Compliance Tracking gains share fastest as regulatory disclosure obligations multiply.
Application:
Customer type dictates workflow complexity and integration requirements for accreditation platforms.
- Certification Bodies:Multi-client assessment frameworks manage concurrent accreditation programs across diverse industries. EU notified bodies serving medical device manufacturers under MDR requirements drive platform sophistication.
- Educational Institutions:Regional accreditor alignment tools coordinate self-study preparation and evidence collection for U.S. universities seeking regional recognition.
- Manufacturing Firms:ISO 9001 and ISO 13485 quality system documentation modules support supplier audit readiness.
- Healthcare Providers:Joint Commission and DNV accreditation workflows integrate with electronic health record systems.
- Government Agencies:Public sector procurement compliance with national standards bodies requires localized deployment architectures.
Certification Bodies represent the deepest implementation expertise. Educational Institutions expand most quickly as cloud migration accelerates among U.S. universities.
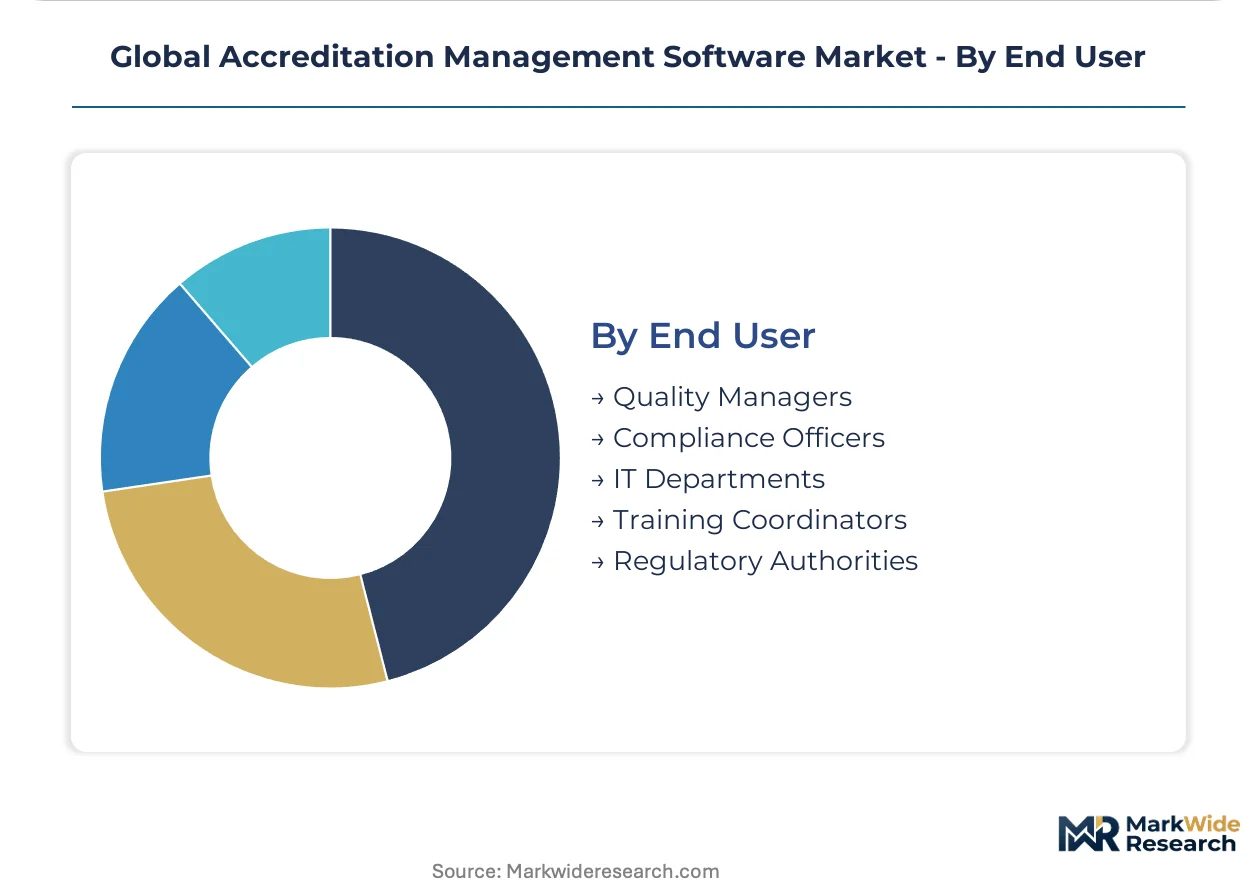
End User:
Functional role determines dashboard configuration and workflow automation priorities.
- Quality Managers:Cross-functional oversight tools coordinate corrective action tracking and management review preparation for ISO-certified organizations.
- Compliance Officers:Regulatory intelligence feeds and deadline alerting systems prioritize multi-jurisdictional obligation management.
- IT Departments:Integration middleware and API governance modules maintain system interoperability.
- Training Coordinators:Competency gap analysis and curriculum alignment tools support personnel qualification maintenance.
- Regulatory Authorities:Oversight dashboards for national accreditation bodies monitor certified entity performance.
Quality Managers retain the primary user base. Compliance Officers show the steepest adoption trajectory as regulatory fragmentation intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Accreditation management software consumption patterns diverge sharply between higher education institutions seeking cloud accessibility and certification bodies demanding audit trail granularity. The United States drives subscription model adoption through university consortium purchasing, while Germany enforces data sovereignty requirements that fragment deployment architectures.
United States
Higher education institutions dominate procurement volume as regional accreditor alignment tools replace legacy perpetual license systems. FDA 21 CFR Part 11 requirements for healthcare compliance audits elevate workflow automation thresholds among Joint Commission-accredited hospital networks. The Boston-Cambridge research corridor deploys predictive analytics modules to compress self-study preparation cycles for New England Association accreditation reviews.
Germany
Notified bodies serving medical device manufacturers under EU MDR requirements drive platform sophistication for CE marking documentation workflows. The EU AI Act risk classification framework forces certification bodies to embed explainability modules with granular audit trail architectures. Munich and Stuttgart industrial clusters concentrate procurement among TÜV and DEKRA affiliates managing ISO 17011 assessment frameworks for machinery exporters.
Australia
Technical and medical training institutes expand cloud-based platform adoption as BIS standards alignment opens procurement channels for Indian regulatory convergence. State government data sovereignty mandates in Victoria and New South Wales sustain hybrid deployment demand among public sector accreditation bodies. Sydney and Melbourne university consortiums consolidate vendor relationships through shared service agreements demanding API interoperability.
India
CDSCO regulatory alignment and BIS standards expansion create procurement channels for cloud-based platforms among pharmaceutical training institutes and medical device testing laboratories. The National Accreditation Board for Certification Bodies mandates ISO 17011 compliance documentation that elevates software feature requirements. Hyderabad and Bengaluru technology corridors drive adoption among software services exporters seeking CMMI and ISO 9001 quality system automation.
United Kingdom
GDPR consent management architectures coexist with post-Brexit regulatory divergence, complicating single-platform deployment for global certification bodies maintaining EU and UK operations. The Office for Students quality assessment framework drives evidence collection automation demand among Russell Group universities. London and Oxford-Cambridge research clusters prioritize continuous compliance monitoring integration with research data repositories.
Global Accreditation Management Software Market Competitive Landscape
Capability concentration sits with specialized workflow engine vendors; scale advantage sits with established learning management system integrators. The vendor base organizes around three strategic tiers: cloud-native platforms with deep LMS embedding, healthcare-focused compliance specialists with domain-specific assessment frameworks, and configurable assessment vendors serving multi-client certification bodies. Competitive moves center on SaaS migration acceleration and API-first architecture development to capture consortium purchasing consolidation.
Within the cloud-native tier, Watermark and SPOL occupy positions anchored to U.S. higher education renewal cycles. Qualtrax exemplifies the healthcare compliance specialist archetype with workflow engines calibrated to FDA quality system requirements. Armature Solutions represents the configurable framework approach that reduces implementation timelines for certification bodies managing concurrent accreditation programs across diverse industries.
| Leading Market Players |
|---|
| Watermark |
| Qualtrax |
| Armature Solutions |
| Liaison International |
| Accredible |
| SoftTech Health |
| WizeHive |
| SPOL |
| Dossier Solutions |
| Others |
Supply & Pricing Matrix
Undercapacity in European cloud infrastructure for GDPR-compliant hosting is forcing vendors to prioritize subscription renewals over new customer acquisition, compressing implementation margins while elevating switching costs for certification bodies managing multi-jurisdictional audit trails.
Pricing Analysis
Long-term offtake contracts dominate procurement between university consortiums and established SaaS vendors, though spot purchasing persists among mid-tier certification bodies seeking modular compliance tracking. Three-tier pricing structure across premium, standard, and economy levels differentiates by integration depth with learning management systems and document control granularity. Pricing pressure stems from compressed implementation timelines as cloud-native entrants undercut legacy vendors on deployment costs. Educational institutions exhibit highest price sensitivity due to constrained IT budgets, while healthcare compliance officers prioritize workflow reliability over license expenditure.
Supply Chain Analysis
Contract-manufacturing concentration for server infrastructure rests with facilities in Ireland, Germany, and the Netherlands serving European data residency requirements. Software development draws from specialized talent pools in India, Poland, and Portugal for workflow engine programming and regulatory compliance architecture. Single-source vulnerability in AI/ML inference chip supply complicates explainability module deployment for EU AI Act documentation. Distribution runs through direct enterprise sales teams for large certification bodies, supplemented by channel partners serving mid-market educational institutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics in accreditation management is tilting toward API-first ecosystems where interoperability with student information systems and research data repositories determines vendor survival, compressing standalone document control providers into acquisition targets.
For Market Incumbents: Insulate renewal revenue through deeper embedding with Canvas, Blackboard, and Moodle ecosystems, creating switching friction that delays competitive displacement. Accelerate SaaS migration for remaining on-premise installations before cloud-native challengers capture German and Australian government procurement cycles. Prioritize ISO 17011 pre-certification workflows to defend against healthcare-focused specialists encroaching on certification body accounts.
For New Entrants and Emerging Players: Build out API-first architectures targeting Australian and Canadian university consortiums consolidating vendor relationships through shared service agreements. Penetrate India's pharmaceutical training institutes as CDSCO regulatory alignment elevates documentation requirements for medical device testing laboratories. Pursue vertical-specific assessment frameworks for TÜV and DEKRA affiliates managing machinery exporter certifications under EU MDR.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among cloud-native platforms with established learning management system partnerships, positioning these archetypes for premium valuation multiples. Target vendors with configurable assessment frameworks reducing implementation cycles for multi-client certification bodies. Monitor procurement consolidation signals among Russell Group universities and U.S. regional accreditor alignment tool replacements as inflection indicators for platform economics shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Deep embedding with Canvas and Blackboard ecosystems creates switching friction that sustains renewal rates among U.S. universities. |
| Acquisition of Specialist Firm | Healthcare compliance workflow engines from FDA-calibrated vendors accelerate CE marking documentation for EU notified bodies. |
| Geographic Expansion | Indian pharmaceutical training institutes and medical device laboratories offer procurement channels as BIS standards expand. |
| Strategic Partnership | API interoperability agreements with student information system vendors enable continuous compliance monitoring revenue streams. |
| Product Launch | Explainability modules with granular audit trails address EU AI Act risk classification requirements for certification bodies. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with accreditation directors at U.S. regional universities, compliance officers at German notified bodies, IT procurement leads at Australian technical institutes, and platform engineers at cloud-native vendors. Secondary validation drew from FDA 21 CFR Part 11 guidance documents, EU AI Act implementation timelines, ISO 17011 accreditation body standards, CSRD disclosure mandate drafts, and SEC filings from publicly traded education technology providers. Bottom-up segmentation modeling triangulated against top-down market sizing from hyperscaler education vertical revenue disclosures.
Calibration across deployment model adoption curves, regulatory implementation timelines, and university procurement cycle phasing anchored volume and value outputs across the analysis window. Segmentation dimensions modeled include cloud versus on-premise infrastructure, solution type intensity by regulatory documentation volume, and vertical concentration across higher education, healthcare, and certification body end users. CAGRs were derived from fitted adoption curves against historical LMS integration penetration rates and EU regulatory compliance spending patterns.
Stress conditions across GDPR enforcement intensity, FDA audit frequency fluctuations, and university IT budget contraction scenarios were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding cloud migration velocity and regulatory disclosure mandate implementation timelines. Quarterly review of procurement consolidation announcements among university consortiums and EU notified body software vendor selections is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
School Timetable Software Market
Software & Services
Taxi Booking Software Market
Software & Services
Programming Language Market
Software & Services
Construction Jobsite Management Software Market
Software & Services
Java Integrated Development Environment (IDE) Market
Software & Services
Global Headless CMS Software Market
Software & Services
Financial Corporate Performance Management (FCPM) Software Market
Software & Services
Data Center Backup and Recovery Software Market
Software & Services
Global Customer Success Software Market
Software & Services
Global Investor Relationship Management Software Market
Software & Services
Advanced Product Quality Planning (APQP) Software Market
Software & Services
Document-Centric Collaboration Software Market
Software & Services
Smartphone Music Production Software Market
Software & Services
Lead-To-Account Matching and Routing Software Market
Software & Services
Skills Management Software Market
Software & Services
Cricket Analysis Software Market