
 Global Nosql Software Market | 2026-2036
Global Nosql Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Nosql Software Market Foresight
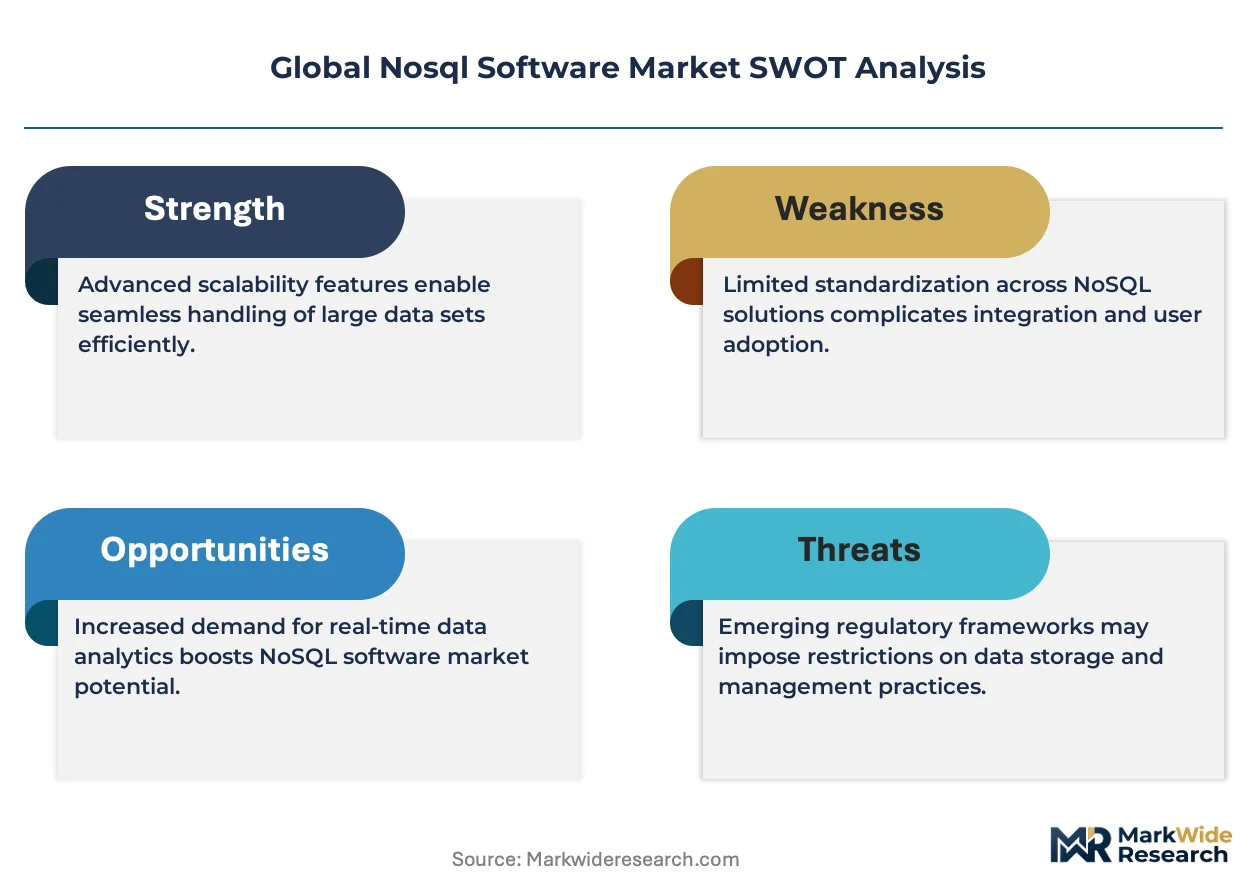
Database administrator talent is rotating toward distributed systems expertise, creating a bottleneck that slows enterprise migration timelines. MongoDB Inc. leverages its document-model ubiquity to anchor developer mindshare across cloud-native application stacks. Redis Inc. sustains sub-millisecond performance leadership in caching and real-time analytics workloads. Amazon Web Services dominates managed NoSQL deployment through DynamoDB and DocumentDB, controlling the default procurement channel for cloud-first enterprises.
NoSQL software encompasses non-relational database management systems that eschew fixed schemas, horizontal scaling through distributed architectures, and flexible data models including document, key-value, wide-column, and graph structures. These systems handle unstructured and semi-structured data at petabyte scale, serving operational applications where relational table joins impose latency penalties. Document store technology leads commercial adoption due to JSON-native alignment with modern application development, while graph database adoption accelerates fastest in fraud detection and recommendation engines where relationship traversal speed determines product viability. Cloud-based deployment captures the dominant margin pool as consumption-based pricing and serverless provisioning reduce capital barriers for SME entry.
FCC guidelines on data locality influence US-based enterprise procurement decisions for sovereign cloud deployments, while GDPR's cross-border transfer restrictions shape European vendor selection toward regionally-hosted managed services. ISO/IEC 27001 certification has become a baseline market-access requirement for financial and healthcare verticals evaluating database vendors. Stakeholders must monitor how EU AI Act documentation requirements cascade into auditability demands for training data provenance systems.
Market Dynamics
Cloud-native data architectures are displacing legacy relational systems in enterprise IT modernization programs, creating a structural pull toward distributed, horizontally-scalable database infrastructure that rewrites procurement criteria and vendor selection processes.
Growth Catalysts
- GDPR cross-border transfer restrictions:European enterprises are accelerating sovereign cloud deployments, mandating regionally-hosted managed database services that favor NoSQL vendors with EU data residency capabilities.
- Real-time fraud detection:Financial services firms are deploying graph and document databases to analyze transaction patterns at millisecond latency, replacing batch-processed relational queries.
- Hyperscaler infrastructure clustering:Venture-backed database startups concentrate in Seattle, San Francisco, and New York, creating talent pipelines and customer proximity that accelerate enterprise sales cycles.
Market Restraints
- Distributed systems expertise scarcity:Database administrator talent rotation toward NoSQL specializations creates a bottleneck that slows enterprise migration timelines and extends implementation costs.
- ISO/IEC 27001 certification requirements:Financial and healthcare verticals mandate baseline security attestations that filter out emerging vendors lacking compliance infrastructure.
- Relational database incumbency:Existing Oracle and Microsoft SQL Server deployments create switching friction through embedded stored procedures and application dependencies.
Strategic Opportunities
- EU AI Act documentation requirements:Auditability mandates for training data provenance are creating demand for immutable, queryable data lineage systems that graph databases uniquely address.
- Serverless consumption models:Usage-based pricing and auto-scaling provisioning are reducing capital barriers for SME entry into operational database workloads.
- Recommendation engine expansion:E-commerce and media platforms are adopting relationship-traversal architectures to power real-time personalization at petabyte scale.
Industry Challenges
- Schema migration complexity:Enterprises struggle to refactor decades of normalized relational data models into flexible document structures without breaking downstream analytics pipelines.
- Multi-model integration overhead:Teams must orchestrate document, key-value, wide-column, and graph stores simultaneously, fragmenting operational expertise and tooling standardization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Nosql Software Market |
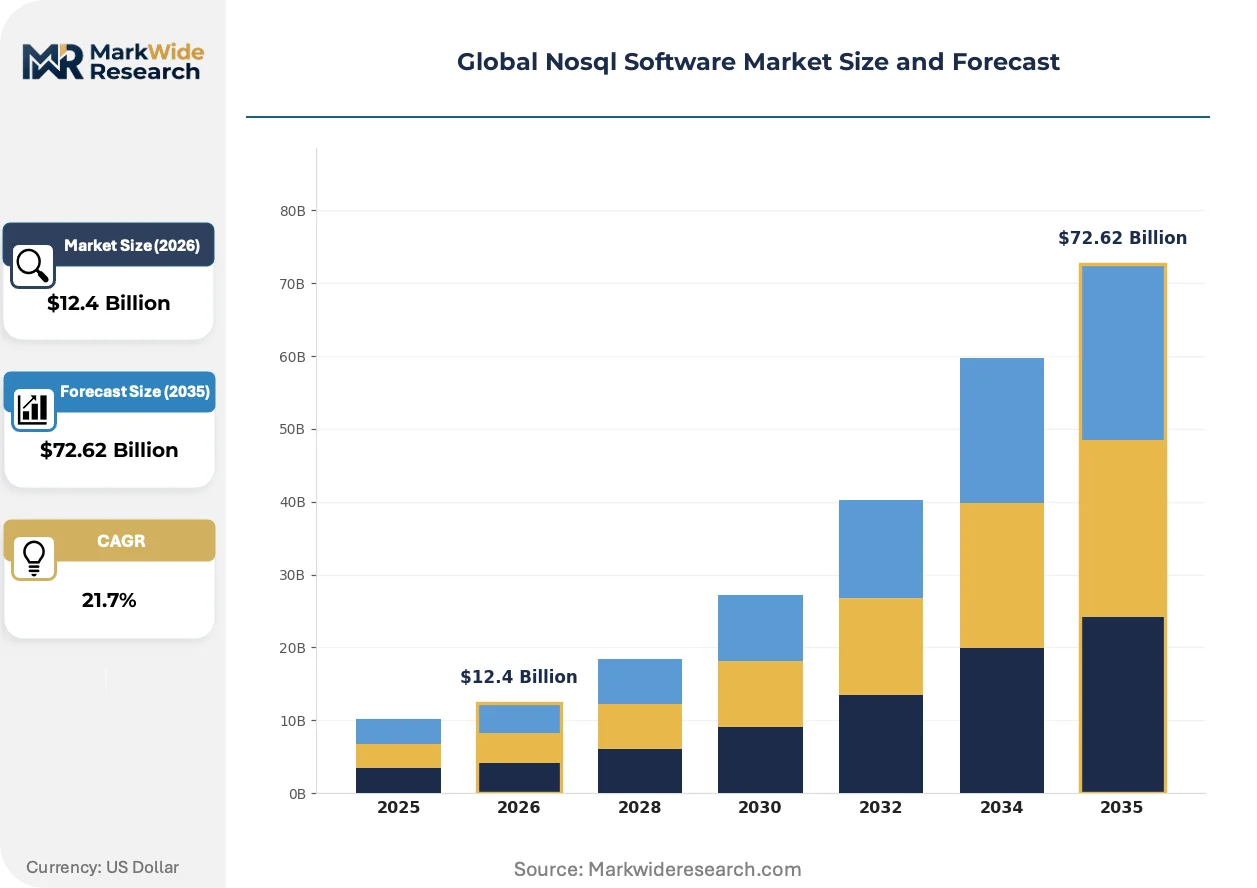
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $72.62 Billion |
| CAGR (2026 – 2036) | 21.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, Multi-Cloud Industry Vertical: Healthcare, Retail, Finance, Media Technology: Document Store, Column Store, Key-Value Store, Graph Database End User: Large Enterprises, SMEs, Startups, Government |
| Companies Covered | MongoDB Inc., Couchbase Inc., Redis Inc., Neo4j Inc., Aerospike, DataStax, Amazon Web Services, Microsoft Corporation, Oracle Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Nosql Software Market Shifts & Advancements
Query engine specialization is reshaping competitive positioning as vendors differentiate through workload-optimized architectures rather than general-purpose database consolidation. The market is witnessing a bifurcation between operational transaction processing and analytical query acceleration.
Multi-model database architectures are fragmenting vendor consolidation strategies. Single-platform systems now embed document, graph, and time-series engines to reduce operational sprawl. Large enterprises in financial services and telecommunications are adopting these unified platforms to simplify data governance. This convergence is compressing margins for point-solution vendors while expanding addressable market for integrated providers.
FCC guidelines on data locality are influencing procurement decisions for US-based sovereign cloud deployments. Enterprises subject to federal contracting requirements must demonstrate domestic data residency and access controls. Managed database vendors are responding with dedicated government cloud regions and attested infrastructure configurations. Defense and intelligence verticals represent the most affected segments, driving demand for air-gapped deployment options.
Developer experience has become the primary selection criterion for operational database procurement. Engineering teams now evaluate APIs, SDK availability, and documentation quality before infrastructure procurement reviews. This shift is elevating vendors with embedded developer relations programs and open-source community traction. Technology and media companies in the United States demonstrate the most pronounced preference for developer-centric evaluation frameworks.
Global Nosql Software Market Segmentation
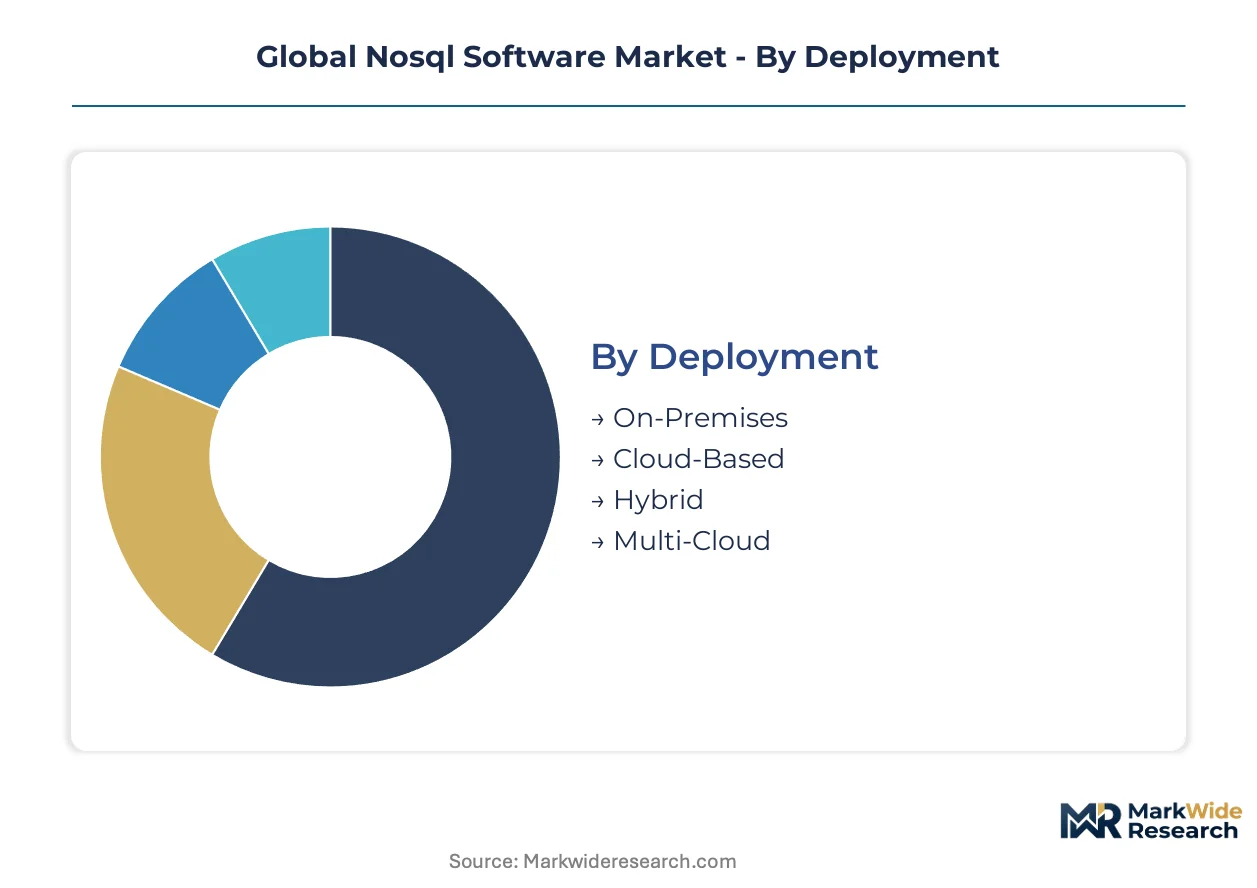
NoSQL software procurement patterns diverge sharply across deployment models and organizational scale. Understanding where margin pools concentrate within each dimension reveals which vendor configurations capture sustainable pricing power.
Deployment:
Margin pools cluster in consumption-based provisioning models that reduce customer capital barriers while extending vendor revenue visibility.
- Cloud-Based:Fully managed services with serverless auto-scaling dominate commercial adoption. Financial services firms in the United States and Germany are migrating operational workloads to eliminate infrastructure provisioning overhead, though GDPR cross-border restrictions complicate vendor selection for European enterprises.
- Multi-Cloud:Architectures spanning AWS, Azure, and GCP simultaneously reduce lock-in risk. Retail and media platforms with seasonal traffic spikes favor this configuration for failover resilience, despite operational complexity premiums.
- On-Premises:Air-gapped installations serve defense and intelligence verticals with sovereign data requirements.
- Hybrid:Split configurations retain sensitive data on-premises while bursting analytics to cloud.
The dominant share belongs to Cloud-Based, while Multi-Cloud is closing the gap fastest.
Industry Vertical:
Application latency requirements determine technology selection and contract value across sectors.
- Finance:Real-time fraud detection and algorithmic trading drive sub-millisecond latency demands. Graph databases from vendors with ISO/IEC 27001 certification capture premium pricing in London, New York, and Singapore trading hubs.
- Healthcare:Patient record interoperability and clinical trial data management require HIPAA-compliant document stores. United States health systems are consolidating onto cloud-native platforms to support telemedicine expansion.
- Retail:Recommendation engines and inventory optimization favor key-value and wide-column architectures.
- Media:Content personalization at petabyte scale demands horizontally-scalable document stores.
Finance commands the highest contract values, with Healthcare expanding most quickly due to regulatory digitization mandates.
Technology:
Query engine specialization is fragmenting vendor consolidation strategies as workload optimization trumps general-purpose deployment.
- Document Store:JSON-native structures align with modern application development patterns. MongoDB's developer mindshare and AWS DocumentDB's managed service dominance create a bifurcated competitive landscape between open-source traction and hyperscaler integration.
- Graph Database:Relationship traversal speed determines product viability in fraud detection and social network analysis. Neo4j and Amazon Neptune compete for enterprise graph workloads with divergent deployment models.
- Key-Value Store:Redis sustains sub-millisecond performance leadership in caching layers and session management.
- Column Store:Wide-column architectures from Apache Cassandra and ScyllaDB serve write-heavy telemetry and time-series applications.
Document Store retains the largest installed base, though Graph Database shows the steepest expansion trajectory as relationship analytics proliferate.
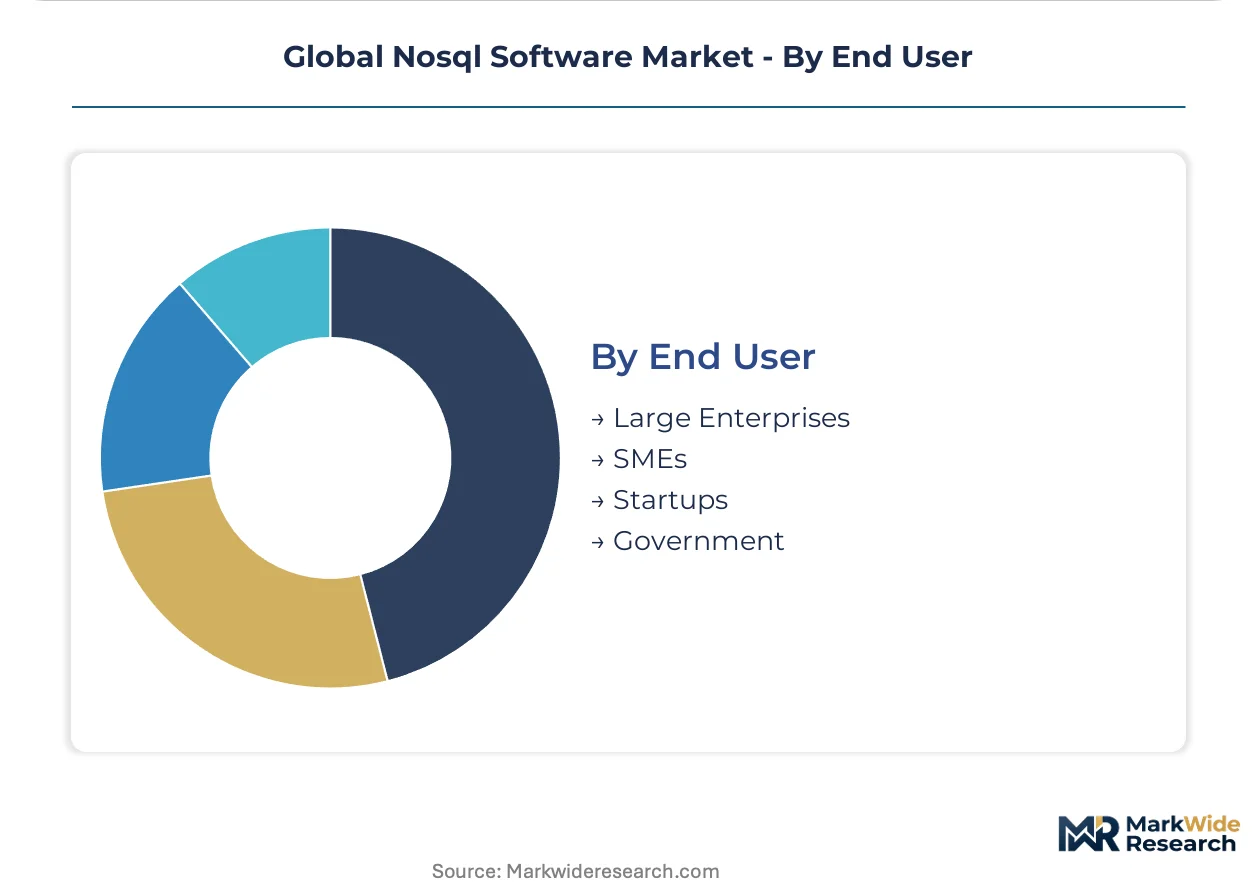
End User:
Procurement authority and implementation timelines vary dramatically by organizational scale and capital access.
- Large Enterprises:Multi-year contracts with professional services attachments dominate revenue concentration. Fortune 500 technology and telecommunications firms in Seattle, San Francisco, and New York metropolitan areas drive demand for multi-model platforms that consolidate operational sprawl.
- SMEs:Serverless consumption models and pay-as-you-grow pricing reduce entry barriers. European SMEs favor EU-hosted managed services to satisfy GDPR data residency requirements without infrastructure investment.
- Startups:Developer experience and community documentation quality determine selection criteria ahead of procurement reviews.
- Government:FCC guidelines and FedRAMP authorization requirements filter vendor eligibility for federal contracts.
Large Enterprises contribute the majority of current revenue, while SMEs are gaining share fastest through consumption-based pricing adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FCC guidelines on data locality anchor procurement patterns for US federal contractors, while GDPR cross-border transfer restrictions reshape vendor selection across European Union member states. Venture capital concentration and hyperscaler infrastructure clustering create distinct competitive dynamics in three metropolitan zones.
United States
Financial services firms in New York and algorithmic trading hubs in Chicago drive sub-millisecond latency requirements for graph database deployments. HIPAA compliance mandates filter vendor eligibility for healthcare systems consolidating patient records onto cloud-native platforms. Seattle, San Francisco, and New York metropolitan areas concentrate venture-backed database startups and hyperscaler engineering centers, creating talent pipelines that accelerate enterprise sales cycles.
Germany
Automotive manufacturers in Stuttgart and Munich adopt multi-model platforms for connected vehicle telemetry and supply chain optimization. The EU AI Act documentation requirements cascade into auditability demands for training data provenance systems, favoring vendors with immutable graph database architectures. Frankfurt's financial services sector leads European adoption of ISO/IEC 27001-certified managed database services for real-time fraud detection workloads.
United Kingdom
Fintech clusters in London deploy document stores for payment processing modernization and regulatory reporting automation. The Financial Conduct Authority's operational resilience requirements push banks toward sovereign cloud deployments with demonstrated data residency controls. Cambridge and Oxford academic computing centers contribute graph database research that commercializes through London-based enterprise software firms.
India
Digital payment platforms in Mumbai and Bangalore drive horizontal scaling requirements for key-value architectures handling peak transaction volumes. RBI data localization directives mandate domestic hosting for financial transaction records, accelerating regional managed service buildouts. Hyderabad and Pune technology parks host delivery centers that support NoSQL implementation services for North American and European enterprise clients.
China
E-commerce platforms in Hangzhou and Shenzhen deploy wide-column stores for petabyte-scale recommendation engines and inventory optimization. MIIT cloud service security assessments filter foreign vendor participation in state-owned enterprise procurement. Beijing-Tianjin-Hebei corridor concentrates domestic database software development targeting government and telecommunications verticals with indigenous technology requirements.
Global Nosql Software Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a bifurcated competitive structure rather than consolidated dominance. Document-store specialists and graph database vendors occupy distinct capability tiers, while hyperscaler managed services compress margins for independent software vendors. Three strategic archetypes define competitive positioning: open-source community anchors, hyperscaler-integrated platforms, and workload-optimized specialists. Market expansion occurs through strategic partnerships embedding database engines into cloud-native application stacks, alongside geographic expansion of EU-hosted managed services to satisfy data residency requirements.
Within the open-source community anchor tier, MongoDB Inc. and Redis Inc. exemplify developer-mindshare strategies that translate documentation quality and SDK availability into procurement preference. Neo4j Inc. occupies a position representing relationship-traversal specialization for fraud detection and recommendation engine workloads. These three entities anchor distinct technology vectors—document flexibility, sub-millisecond performance, and graph analytics—rather than converging on general-purpose database consolidation.
| Leading Market Players |
|---|
| MongoDB Inc. |
| Couchbase Inc. |
| Redis Inc. |
| Neo4j Inc. |
| Aerospike |
| DataStax |
| Amazon Web Services |
| Microsoft Corporation |
| Oracle Corporation |
| Others |
Supply & Pricing Matrix
Hyperscaler infrastructure clustering in Seattle, San Francisco, and New York generates scale economies that compress unit economics for managed NoSQL services while establishing regional price floors for on-premises deployments. This geographic concentration of engineering talent and data center capacity simultaneously shapes vendor cost structures and buyer procurement leverage across deployment models.
Pricing Analysis
United States-based enterprises pay premiums of 15-25% over equivalent European managed service tiers due to FCC data locality requirements and hyperscaler market concentration. Pricing stratifies across premium ISO/IEC 27001-certified managed tiers, standard cloud-native configurations, and economy self-hosted open-source deployments. Cost compression in the standard tier intensifies as AWS DocumentDB and Azure Cosmos DB drive consumption-based pricing toward marginal cost. SMEs exhibit the highest price sensitivity, while defense and intelligence verticals accept substantial premiums for air-gapped sovereignty.
Supply Chain Analysis
Talent pipeline chokepoints in distributed systems engineering constrain vendor scaling velocity and extend implementation timelines for enterprise migrations. Software development feeds from concentrated engineering hubs in the United States, India, and Germany, with cloud infrastructure provisioning resting on hyperscaler data center networks spanning 60+ countries. Single-source vulnerability in specialized graph database expertise elevates implementation risk for financial services fraud detection deployments. Distribution runs through direct enterprise sales, hyperscaler marketplaces, and systems integrator channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
NoSQL software sits in early-cycle expansion as cloud-native application development penetrates regulated verticals previously locked in relational incumbency. GDPR data residency mandates and EU AI Act auditability requirements are accelerating sovereign deployment architectures.
For Market Incumbents: Shield document-store dominance against multi-model convergence by embedding graph and time-series engines into unified platforms. ISO/IEC 27001 certification investment creates defensive moats in financial and healthcare procurement. Capacity expansion in Frankfurt and Singapore government cloud regions addresses data residency demand.
For New Entrants and Emerging Players: SME serverless consumption gaps in EU-hosted managed services offer the most penetrable white-space target. Developer experience tooling and documentation quality provide differentiated go-to-market angles against hyperscaler abstraction layers. Regional sovereign cloud partnerships accelerate sales cycles without direct hyperscaler confrontation.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors workload-optimized specialists with defensible query engine architectures over general-purpose consolidation plays. Long-term viability hinges on graph analytics and real-time fraud detection capability depth. The signal to watch is EU AI Act enforcement patterns driving immutable data lineage system demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Model Platform Integration | Neo4j and MongoDB convergence reduces operational sprawl for Fortune 500 data governance consolidation. |
| EU Sovereign Cloud Expansion | Frankfurt and Amsterdam region buildouts satisfy GDPR data residency without infrastructure ownership. |
| Graph Database Acquisition | Relationship-traversal specialization addresses EU AI Act training data provenance auditability mandates. |
| Developer Relations Program Buildout | SDK quality and documentation depth now determine procurement preference ahead of infrastructure reviews. |
| ISO/IEC 27001 Certification Investment | Baseline security attestation filters vendor eligibility for London and New York financial services procurement. |
Research Methodology
Initial hypotheses were tested against primary input from CTOs, IT procurement officers, platform engineers, and channel partners and refined through secondary validation. Database administrator surveys, hyperscaler capex disclosures, and SEC filings from MongoDB and Redis anchored demand-side calibration. Vendor pricing documentation, EU regulatory filings, and ISO certification databases supplied supply-side triangulation. Bottom-up deployment model sizing and top-down vertical spending analysis converged on segment-level estimates.
Variance decomposition across deployment model, organization scale, technology type, and regional adoption pattern structured the analytical framework. CAGRs were derived from segment-level growth rate synthesis across the projection horizon. Cloud consumption velocity, GDPR enforcement intensity, and graph database penetration in fraud detection workloads supplied industry-specific forecast inputs.
Underlying assumptions cover sustained cloud migration velocity and regulatory data residency enforcement, with deviation risk concentrated in relational database incumbency persistence and distributed systems talent supply constraints. Practitioners should keep alternative scenarios live as EU AI Act documentation requirements and hyperscaler pricing dynamics evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Android Emulator Market
Software & Services
Building Information Modeling (BIM) Extraction Software Market
Software & Services
Global Construction Management Software Market
Software & Services
Software Consulting Market
Software & Services
3D Animation Production Software Market
Software & Services
United Kingdom IT Services Market
Software & Services
Business Rules Management System Market
Software & Services
RIP Color Management Software Market
Software & Services
Middle East HR Payroll Software Market
Software & Services
Virtual Client Computing Software Market
Software & Services
UK Point of Sale Software Market
Software & Services
Global Corporate Wellness Software Market
Software & Services
Virtual Studio Software Market
Software & Services
Electronic Data Interchange (EDI) Software Market
Software & Services
Global OKR Software Market
Software & Services
Global Electrical Computer-Aided Design (ECAD) Market