
 Global Audit Software Market | 2026-2036
Global Audit Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Audit Software Market Foresight
Enterprise software procurement channels is reconfiguring around subscription-based delivery and direct vendor relationships, bypassing traditional value-added resellers. SAP SE leverages its embedded ERP customer base to cross-sell audit modules across Fortune 500 accounts. Wolters Kluwer NV sustains dominance in specialized compliance content through deep regulatory databases. MetricStream Inc. competes on risk-quantification capabilities that appeal to banking regulators.
Audit software encompasses platforms that automate evidence collection, control testing, and exception reporting across financial, operational, and IT domains, typically integrating with general ledger systems via standardized APIs and supporting real-time transaction sampling at throughput rates exceeding millions of records per hour. Cloud-Based deployment is capturing the fastest expansion as organizations abandon capital-intensive on-premises infrastructure. Compliance Management solutions command premium pricing due to mandatory jurisdictional updates. Financial Institutions represent the deepest end-user segment, driven by Basel III operational risk mandates and anti-money-laundering audit trails.
The US SEC, EU EBA guidelines, and ISO 27001 standards collectively mandate granular access logging and immutable record retention, forcing vendors to embed cryptographic verification and multi-tenant data segregation into core architectures. India's RBI and Germany's BaFin impose supplementary localization requirements that fragment product roadmaps. Stakeholders must evaluate whether to build jurisdiction-specific compliance layers or pursue modular platforms adaptable to regulator-specific rule engines.
Market Dynamics
The EU AI Act and ISO 27001 updates are compressing vendor roadmaps, forcing cryptographic verification and multi-tenant data segregation into core architectures ahead of traditional release cycles.
Growth Catalysts
- Basel III operational risk mandates:Financial institutions in Germany and the United States must maintain immutable audit trails, driving replacement of legacy sampling systems with continuous monitoring platforms.
- Cloud infrastructure abandonment:Organizations are shedding capital-intensive on-premises deployments, creating pull-through demand for API-native audit modules that integrate with general ledger systems.
- India's RBI localization requirements:Data sovereignty rules mandate in-country server deployment, fragmenting product roadmaps but opening dedicated revenue streams for compliant vendors.
Market Restraints
- Regulatory fragmentation:Germany's BaFin, India's RBI, and the US SEC impose non-overlapping technical standards, multiplying engineering costs for cross-border vendors.
- Legacy system entrenchment:Fortune 500 accounts running SAP ERP cores face high switching costs when migrating to standalone audit platforms.
- Talent scarcity in cryptographic engineering:Shortage of developers capable of implementing zero-knowledge proof architectures limits vendor differentiation.
Strategic Opportunities
- EU AI Act compliance layers:Automated evidence collection for algorithmic decision auditing represents an unpenetrated module category within European financial services.
- Real-time transaction sampling convergence:Integration of streaming analytics with blockchain verification creates new product architecture for high-frequency trading audits.
- Direct vendor relationships:Subscription-based delivery models bypass traditional value-added resellers, capturing margin previously lost to channel intermediaries.
Industry Challenges
- Multi-jurisdiction certification timelines:Vendors must sequence ISO 27001, SOC 2, and BaFin approvals, delaying market entry by 12-18 months.
- API integration complexity:Legacy general ledger systems lack standardized endpoints, requiring custom engineering for each Fortune 500 deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Audit Software Market |
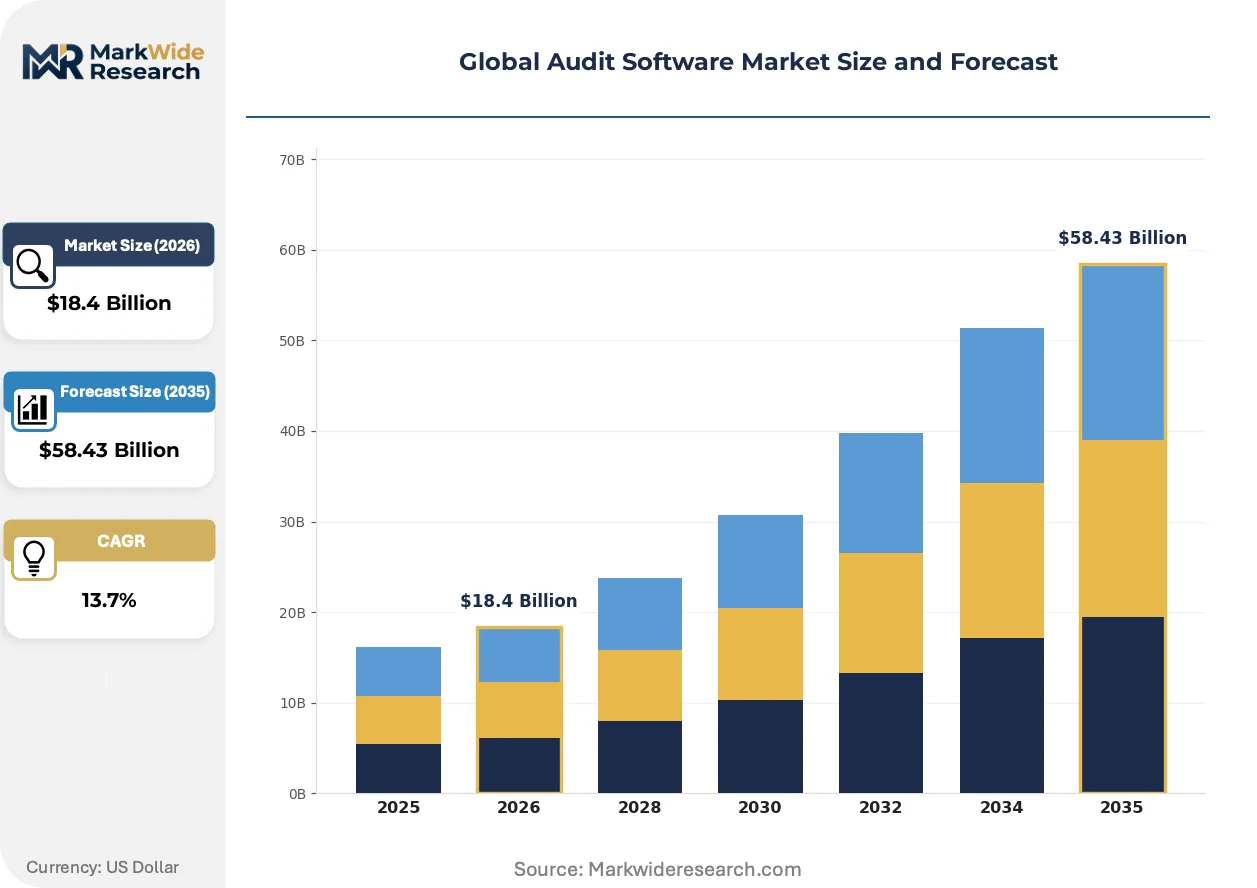
| Market Size in 2026 | $18.4 Billion |
| Market Size in 2035 | $58.43 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, SaaS, Web-Based Solution Offering: Risk Assessment, Compliance Management, Financial Auditing, IT Audit, Operational Audits Application: Enterprise Resource Planning, Fraud Detection, Regulatory Reporting, Internal Controls, Tax Auditing End User: Accounting Firms, Corporate Controllers, Government Agencies, Nonprofit Organizations, Financial Institutions |
| Companies Covered | IBM, Thomson Reuters Corporation, AuditBoard Inc., Ideagen PLC, MetricStream Inc., Wolters Kluwer NV, SAP SE, Resolver Inc., Workiva Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Audit Software Market Shifts & Advancements
Continuous auditing platforms are virtualizing evidence collection workflows, collapsing the latency between transaction execution and control verification. Three forces are compressing traditional audit cycles.
Distributed ledger verification is virtualizing the attestation layer that previously required manual third-party confirmation. Banking regulators in the United States and Germany are mandating cryptographic proof of reserve calculations, compressing reconciliation windows from quarterly to intraday. The technology is virtualizing the role of external audit firms in high-frequency verification scenarios.
The EU AI Act imposes granular logging requirements on automated decision systems used for credit scoring and fraud detection. Financial institutions must demonstrate algorithmic accountability through immutable audit trails. German BaFin and US SEC guidelines are converging on similar technical standards, forcing vendors to embed explainability modules into core architectures.
Enterprise buyers are unbundling after-sales implementation services from software licenses, preferring fixed-fee deployment contracts over time-and-materials arrangements. This pattern concentrates in US Fortune 500 accounts where procurement functions have centralized vendor management. Direct vendor relationships are displacing systems integrators for initial platform configuration.
Global Audit Software Market Segmentation
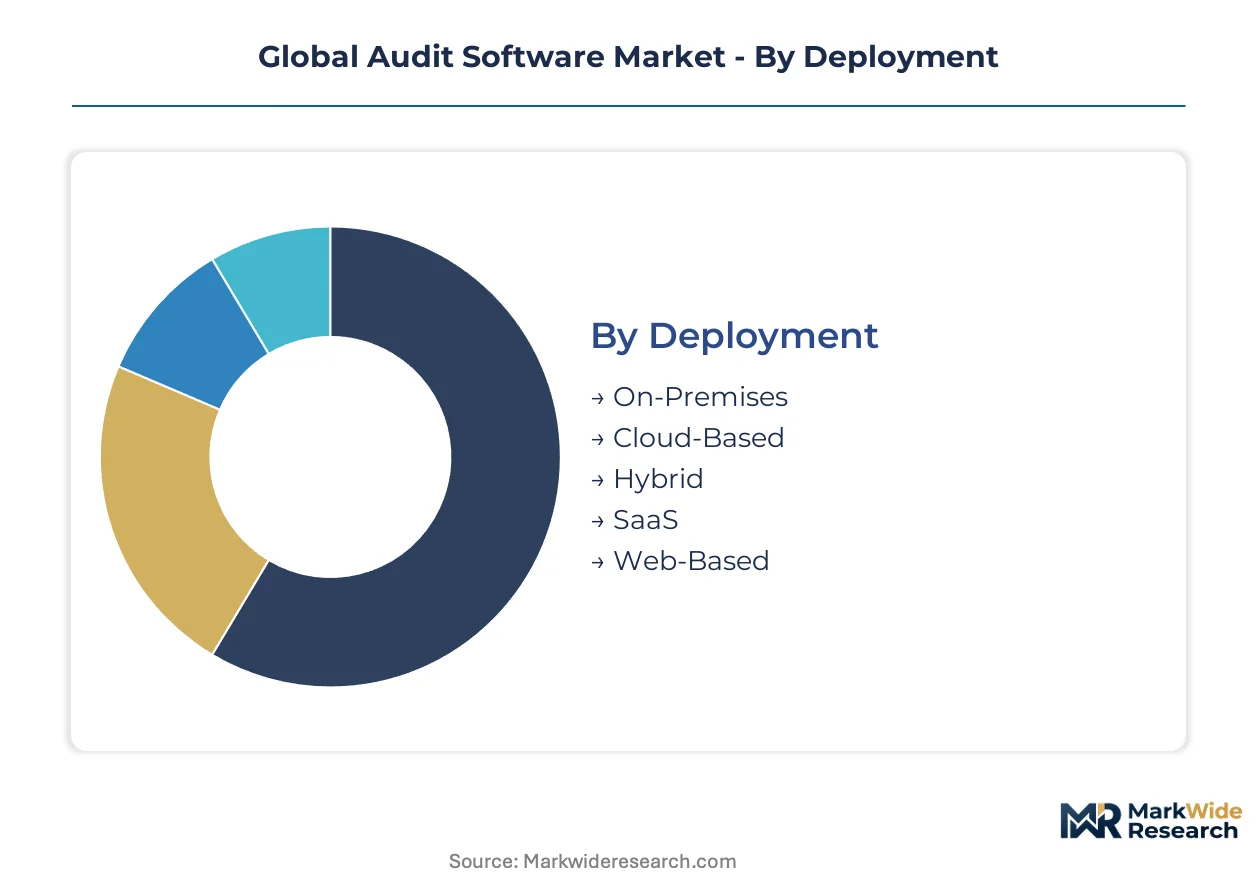
Audit software procurement patterns diverge sharply across deployment architectures and buyer sophistication. Vendors must architect modular pricing and service tiers that align with the technical maturity and regulatory exposure of each segment.
Deployment:
After-sales engineering intensity peaks in hybrid configurations, where vendors maintain dual infrastructure stacks across client premises and cloud regions.
- Cloud-Based:Multi-tenant architectures with API-native general ledger integration dominate new procurement in the United States and Germany. Financial institutions abandon capital-intensive infrastructure, pulling demand toward subscription models with automatic regulatory patch deployment.
- On-Premises:Immutable audit trail requirements from India's RBI and Germany's BaFin sustain demand among sovereign data custodians. Legacy ERP entrenchment at Fortune 500 accounts preserves this segment despite higher total cost of ownership.
- Hybrid:Split architectures serving sensitive workloads on-premises while pushing analytics to cloud regions.
- SaaS:Pre-configured compliance modules with jurisdiction-specific rule engines.
- Web-Based:Browser-accessible platforms targeting mid-market accounting firms with limited IT staffing.
Cloud-Based holds the largest share; momentum sits with Hybrid as regulatory fragmentation forces jurisdictional data partitioning.
Solution Offering:
Cost tier stratification separates premium compliance content from standardized risk quantification tools.
- Compliance Management:Granular regulatory databases with mandatory jurisdictional updates command premium pricing. Wolters Kluwer NV sustains dominance through deep EU AI Act and ISO 27001 content layers that refresh faster than competitor cycles.
- Risk Assessment:Quantification engines appealing to banking regulators in Germany and the United States. MetricStream Inc. competes here with stochastic modeling capabilities for Basel III operational risk calculations.
- Financial Auditing:General ledger reconciliation and sampling automation for external audit firms.
- IT Audit:Control testing across identity management and access logging systems.
- Operational Audits:Workflow efficiency and exception reporting for manufacturing and logistics operations.
Compliance Management captures the highest margins; Risk Assessment is expanding most quickly under regulatory pressure for forward-looking capital adequacy.
Application:
Volume concentration clusters around ERP integration projects, where audit modules attach to existing SAP SE deployments.
- Enterprise Resource Planning:Embedded audit trails within SAP, Oracle, and Workday environments. SAP SE leverages its installed base to cross-sell continuous monitoring modules across Fortune 500 accounts in the United States and Germany.
- Fraud Detection:Real-time transaction sampling with machine learning anomaly detection. EU AI Act logging mandates for algorithmic credit scoring are accelerating procurement among European financial institutions.
- Regulatory Reporting:Automated submission formatting for SEC, BaFin, and RBI templates.
- Internal Controls:Segregation of duties testing and approval workflow verification.
- Tax Auditing:Jurisdiction-specific calculation validation and documentation retention.
Enterprise Resource Planning anchors current revenue; Fraud Detection shows the steepest expansion trajectory as real-time verification replaces periodic sampling.
End User:
Customer type determines deployment complexity, with Financial Institutions demanding cryptographic verification and multi-tenant segregation that smaller buyers cannot resource.
- Financial Institutions:Banks, insurers, and asset managers subject to Basel III operational risk mandates and anti-money-laundering audit trail requirements. India's RBI localization rules and Germany's BaFin technical standards fragment vendor roadmaps but create dedicated revenue streams for compliant architectures.
- Accounting Firms:External auditors seeking efficiency tools for evidence collection and control testing. The Big Four dominate procurement, with mid-tier firms adopting SaaS alternatives to narrow the capability gap.
- Corporate Controllers:Internal audit functions at non-financial enterprises.
- Government Agencies:Public sector transparency and expenditure verification mandates.
- Nonprofit Organizations:Donor accountability and grant compliance requirements.
Financial Institutions generate the deepest revenue per account; Accounting Firms are gaining share fastest as audit quality standards tighten globally.

Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States and Germany, where Basel III mandates and EU AI Act compliance layers justify premium subscription tiers, while Indian vendors compete on localization-adapted cost structures.
United States
Financial institutions in New York and Chicago drive continuous auditing procurement to satisfy SEC granular access logging requirements. The US SEC mandates immutable record retention for operational risk calculations. Silicon Valley SaaS vendors embed cryptographic verification into multi-tenant architectures serving Fortune 500 accounts.
Germany
BaFin technical standards for banking supervision accelerate replacement of legacy sampling systems in Frankfurt and Munich. The EU AI Act imposes algorithmic accountability requirements on automated credit scoring. Bavaria's industrial clusters demand audit modules with real-time blockchain verification for supply chain finance.
India
RBI localization rules fragment product roadmaps but create dedicated revenue streams for compliant vendors in Mumbai and Bangalore. Data sovereignty mandates require in-country server deployment for financial audit trails. Hyderabad's technology corridor hosts development centers architecting jurisdiction-specific compliance layers.
United Kingdom
London's banking sector pulls demand for risk-quantification platforms aligned with Prudential Regulation Authority guidelines. The UK Financial Conduct Authority converges on EU AI Act technical standards for algorithmic decision logging. The City of London concentrates procurement of embedded ERP audit modules among asset managers.
Japan
METI guidelines on operational risk disclosure drive adoption of continuous monitoring platforms in Tokyo and Osaka. Japanese financial institutions integrate audit software with core banking systems under FSA supervisory expectations. The Kanto region's enterprise software market favors hybrid deployment architectures splitting sensitive workloads on-premises.
Global Audit Software Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with narrower functional scope. The vendor base consolidates around ERP-embedded suites and standalone risk-quantification engines. Three archetypes dominate: legacy ERP extenders, compliance content aggregators, and API-native challengers. M&A activity concentrates on acquiring cryptographic engineering talent; strategic partnerships focus on cloud infrastructure co-deployment.
Within the ERP-embedded tier, SAP SE and IBM represent platform consolidation strategies that leverage installed base relationships for audit module cross-selling. Wolters Kluwer NV sits within the compliance content archetype, anchoring premium pricing through regulatory database depth. MetricStream Inc. exemplifies the risk-quantification specialist position, occupying a niche serving banking regulators with stochastic modeling capabilities. These three anchors illustrate divergent competitive vectors: horizontal platform breadth, vertical content depth, and functional specialization.
| Leading Market Players |
|---|
| IBM |
| Thomson Reuters Corporation |
| AuditBoard Inc. |
| Ideagen PLC |
| MetricStream Inc. |
| Wolters Kluwer NV |
| SAP SE |
| Resolver Inc. |
| Workiva Inc. |
| Others |
Supply & Pricing Matrix
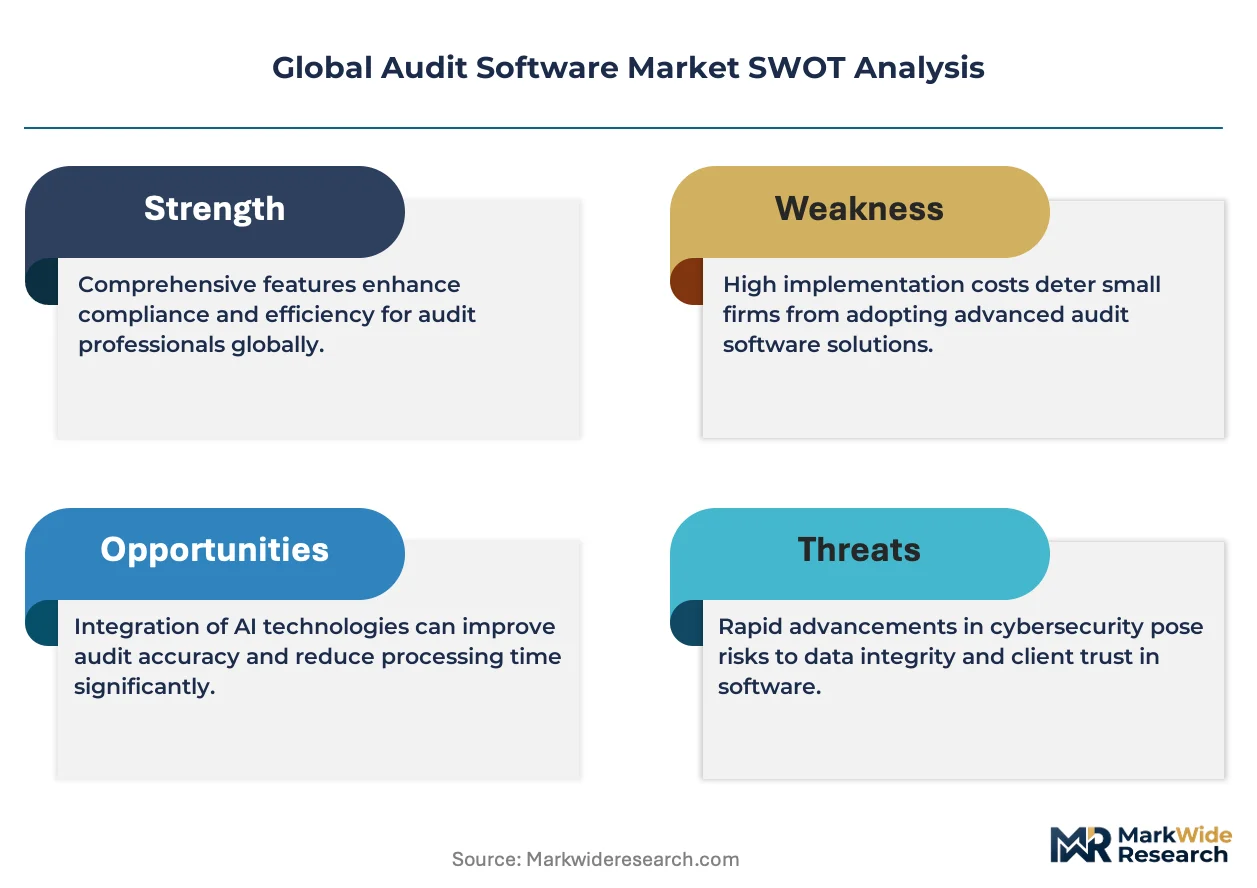
Regulatory fragmentation across Germany's BaFin, India's RBI, and the US SEC forces vendors to engineer jurisdiction-specific compliance layers, widening the spread between configured-to-order premium deployments and standard SaaS tiers while fragmenting supply chain sourcing across multiple certification regimes.
Pricing Analysis
The customization-premium spread separates Fortune 500 configured deployments from mid-market SaaS subscriptions. Subscription-based SaaS models dominate new procurement, with price differentiation anchored in certification grade—ISO 27001 and EU AI Act compliance tiers command substantial premiums—and customization depth for legacy ERP integration. Pricing pressure stems from cloud infrastructure commoditization compressing base platform margins. Corporate controllers at mid-tier accounting firms exhibit highest price sensitivity, while financial institutions under Basel III mandates absorb premium tiers without elasticity.
Supply Chain Analysis
Supplier-financing facilities have become critical as vendors extend payment terms to cloud infrastructure providers anchoring multi-tenant architectures. Engineering talent concentrates in the United States, Germany, and India, with cryptographic verification modules drawing from specialized developer pools in Silicon Valley and Bangalore. Raw material dependencies center on cloud compute capacity, enterprise-grade encryption hardware, and regulatory content databases. Single-source vulnerability sits with concentrated cryptographic engineering expertise. Distribution runs through direct vendor relationships displacing traditional value-added resellers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The audit software market sits in a cyclical recovery phase driven by the post-pandemic compliance investment wave as financial institutions replace deferred legacy system upgrades.
For Market Incumbents: Entrench embedded ERP relationships through deeper SAP and Oracle integration modules that raise switching costs for Fortune 500 accounts. Prioritize cryptographic engineering capacity additions in Germany and India to satisfy BaFin and RBI localization mandates before challengers achieve certification. Defend against API-native challengers by controlling channel access through direct subscription relationships that capture margin previously lost to systems integrators. For New Entrants and Emerging Players: Pursue white-space opportunities in EU AI Act algorithmic accountability modules for automated credit scoring, where established vendors lack pre-built explainability architectures. Target mid-tier accounting firms in the United States and United Kingdom with browser-accessible platforms that narrow the capability gap against Big Four procurement dominance. Lead with fixed-fee deployment contracts that unbundle after-sales services, appealing to centralized procurement functions at corporate controllers. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors risk-quantification specialists with stochastic modeling capabilities serving banking regulators. Long-term viability rests on vendors embedding cryptographic verification into core architectures rather than bolt-on compliance layers. Acquisition targets should demonstrate zero-knowledge proof engineering depth and multi-jurisdiction certification progress. The signal to watch is regulatory divergence between the US SEC and EU EBA on immutable record retention standards, which would fragment product roadmaps and favor modular platform architectures.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Content Layer Acquisition | Deep EU AI Act and ISO 27001 databases command recurring premium pricing from financial institutions. |
| Cloud-Native Platform Integration | API-native general ledger connectivity displaces on-premises infrastructure at Fortune 500 accounts. |
| Cryptographic Engineering Talent Acquisition | Zero-knowledge proof capabilities differentiate vendors for Basel III operational risk mandates. |
| Jurisdiction-Specific Compliance Buildout | In-country server deployment satisfies India's RBI data sovereignty requirements. |
| Direct Channel Relationship Expansion | Subscription delivery bypassing value-added resellers captures margin from channel intermediaries. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with chief technology officers, IT procurement officers at financial institutions, platform engineers, regulatory compliance leads, and channel integration specialists. Secondary validation drew from SEC filings, EBA guideline documentation, ISO certification registries, and cloud infrastructure capex disclosures. Bottom-up deployment estimates triangulated against top-down regulatory mandate timelines.
Calibration against historical compliance investment cycles and cloud migration patterns anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include deployment architecture, solution offering tier, ERP integration complexity, end-user regulatory exposure, and regional adoption pattern. CAGRs derived from regulatory mandate effective dates and legacy system replacement cycles. Industry-specific inputs encompassed Basel III operational risk calculation requirements and EU AI Act algorithmic logging specifications.
Sensitivities concentrate around regulatory timeline acceleration, cryptographic standard evolution, and cloud infrastructure pricing volatility. Forecasts reflect documented assumptions on compliance mandate enforcement intensity and enterprise SaaS procurement velocity. Macroeconomic deviation affecting financial institution IT budgets, regulatory standard divergence between jurisdictions, or breakthrough zero-knowledge proof commercialization would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Mobile Application Testing Services (MATS) Market
Software & Services
Sports League Management Software Market
Software & Services
Global Auto Dealer Software Market
Software & Services
Construction Estimating Software Market
Software & Services
Software Publishers Market
Software & Services
Neurodiverse Workforce Productivity Tools Market
Software & Services
Problem Management Software Market
Software & Services
Customs Declaration Software Market
Software & Services
Global Referral Software Market
Software & Services
Proxy Services and Software Market
Software & Services
Global Bill of Material Management Software Market
Software & Services
Global Polling Software Market
Software & Services
Procurement Software Market
Software & Services
Survey and Feedback Management Software Market
Software & Services
Global Archiving Software Market
Software & Services
Australia HR Payroll Software Market