
 Global Charity Accounting Software Market | 2026-2036
Global Charity Accounting Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Charity Accounting Software Market Foresight
Cloud-native microservices architecture is fragmenting the traditional monolithic charity accounting stack into modular, API-first components. Blackbaud leverages its entrenched presence in faith-based and educational segments to sustain recurring revenue depth. Xero anchors its position among small charities through intuitive interfaces and native bank feeds. Sage Intacct differentiates via multi-entity consolidation tools purpose-built for complex philanthropic foundations.
Charity accounting software denotes specialized financial management systems engineered to handle restricted fund accounting, donor-imposed purpose constraints, and FASB- or SORP-compliant reporting for tax-exempt entities. These platforms automate grant allocation tracking, generate Form 990 and Gift Aid documentation, and maintain audit trails that satisfy both board oversight and external regulator examination. Cloud-based deployment leads in net-new installations among organizations with under fifty staff, while fund accounting modules command the deepest integration budgets due to their role in restricted-versus-unrestricted balance sheet integrity. On-premises solutions persist in large philanthropic foundations where data residency policies and legacy ERP interconnectivity delay migration timelines.
FDA oversight of donor data handling intersects with HIPAA provisions when charities operate affiliated health clinics, while the EU AI Act imposes algorithmic transparency requirements on automated grant-scoring tools deployed in European markets. The UK's Charity Commission SORP and Australia's ACNC reporting standards mandate granular fund segregation that directly shapes software feature prioritization. Stakeholders must monitor how rapidly evolving AI disclosure mandates and cross-border data localization rules will force platform architecture decisions before the next procurement cycle.
Market Dynamics
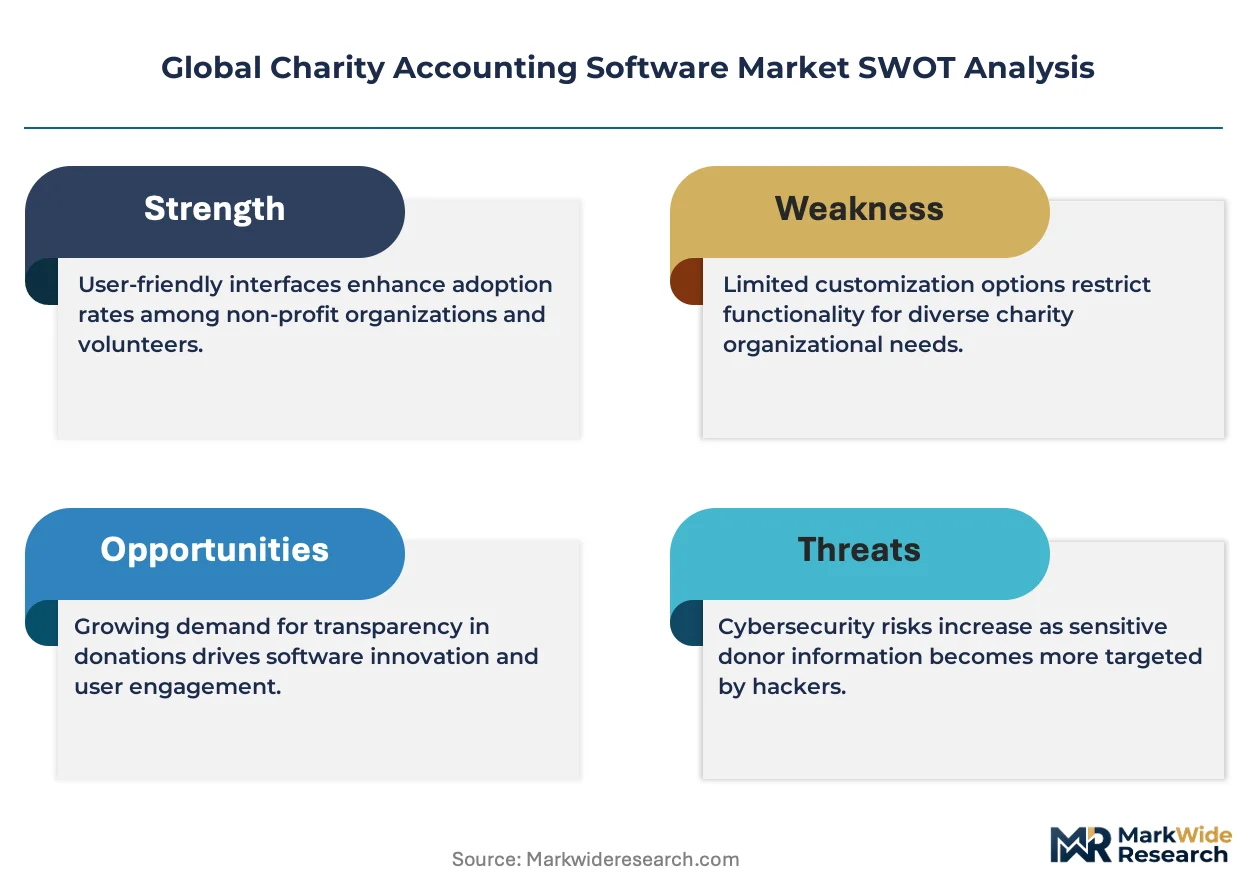
Cloud-native microservices architecture is fragmenting monolithic charity accounting stacks into modular, API-first components that vendors must assemble into cohesive platforms. This structural shift forces incumbents to rearchitect legacy codebases while challengers exploit composability to enter niche fund-accounting segments.
Growth Catalysts
- Australia's ACNC transparency mandates:The Australian Charities and Not-for-profits Commission has intensified financial disclosure requirements, compelling mid-sized nonprofits to upgrade from spreadsheet-based tracking to purpose-built fund accounting platforms.
- GDPR-EU AI Act convergence:European charities deploying automated grant-scoring tools face dual compliance pressure, creating demand for software with embedded algorithmic transparency and cross-border data governance features.
- Small charity cloud migration:Organizations with under fifty staff in the United Kingdom are abandoning on-premises installations for browser-based platforms with native bank feeds and real-time donor reporting.
Market Restraints
- Legacy ERP interconnectivity:Large philanthropic foundations in the United States maintain data residency policies and complex integrations with on-premises systems that delay cloud migration timelines by three to five years.
- Specialized accounting talent scarcity:The shallow labor pool for professionals trained in restricted fund accounting and SORP compliance limits implementation velocity for new platform deployments.
- Multi-jurisdiction compliance costs:Vendors must maintain parallel code branches for FASB, SORP, and ACNC standards, inflating R&D expenditure without proportional pricing power.
Strategic Opportunities
- AI-assisted audit preparation:Machine learning tools that auto-classify restricted versus unrestricted transactions and flag anomalies before external examination represent unclaimed white space.
- India's nonprofit formalization:The country's expanding NGO registration requirements and foreign contribution regulation enforcement create first-mover advantage for localized fund accounting solutions.
- Embedded fintech convergence:Integration of payment processing, donor-advised fund management, and automated Gift Aid reclamation within accounting platforms compresses vendor procurement cycles.
Industry Challenges
- API standardization delays:The absence of unified data exchange protocols between charity CRM systems and accounting platforms forces costly custom integration work for each deployment.
- Cross-border data localization friction:Conflicting requirements between GDPR, state-level US privacy laws, and emerging national data sovereignty rules complicate multi-entity consolidation architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Charity Accounting Software Market |
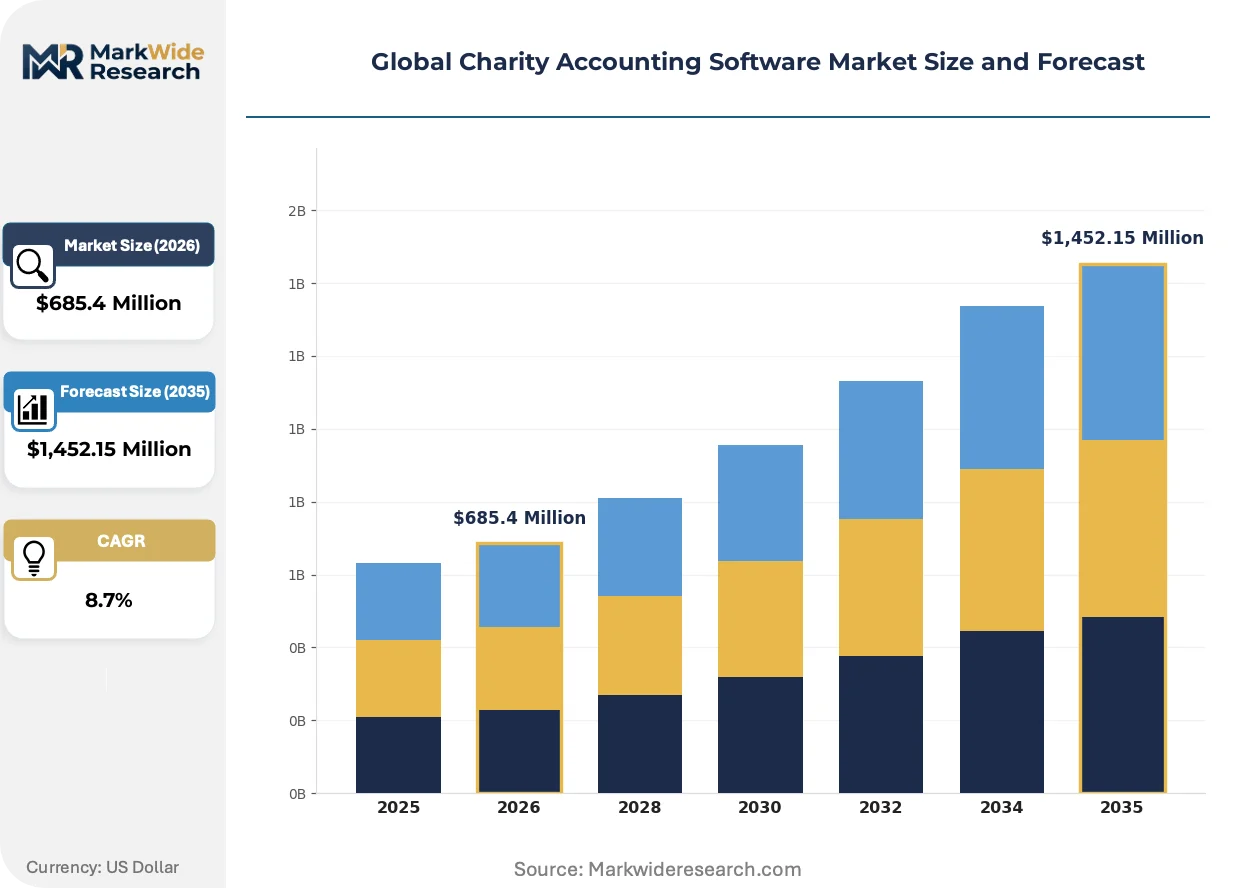
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,452.15 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, Hosted Solution Offering: Donation Management, Fund Accounting, Grant Tracking, Reporting & Compliance, Volunteer Management, CRM Integration Application: Non-Profit Organizations, Religious Institutions, Educational Foundations, Cultural Societies, Social Advocacy Groups, Environmental NGOs End User: Small Charities, Medium-Sized Charitable Trusts, Large Philanthropic Foundations, Community-Based Organizations, Research Institutes |
| Companies Covered | Aplos Software, Intuit, Blackbaud, Pushpay, Xero, NetSuite, QuickBooks, Community Brands, Sage Intacct, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Charity Accounting Software Market Shifts & Advancements
Artificial intelligence and modular architecture are compressing traditional software delivery models while regulatory complexity deepens feature differentiation requirements. These forces are reshaping how vendors build, sell, and maintain charity accounting platforms.
Embedded machine learning for transaction classification is collapsing the manual coding workflows that previously consumed finance staff hours. Small charities in the United Kingdom are adopting these tools fastest, driven by staff capacity constraints. The technology is collapsing the historical trade-off between audit-ready accuracy and operational efficiency that forced organizations to choose between depth and speed.
The EU AI Act imposes algorithmic transparency requirements on automated grant-scoring and donor-engagement tools deployed by European charities. Vendors must now document decision logic and enable human override capabilities that add development overhead. Faith-based and educational segments with complex donor segmentation are most affected, accelerating procurement of compliance-ready platforms ahead of enforcement deadlines.
Subscription pricing with usage-based tiers is displacing perpetual license models among mid-sized nonprofits in Australia and the United Kingdom. Finance directors prefer predictable operational expenditure over capital-intensive upfront commitments. This shift is most visible among organizations with volatile grant funding cycles who cannot forecast multi-year software amortization.
Global Charity Accounting Software Market Segmentation
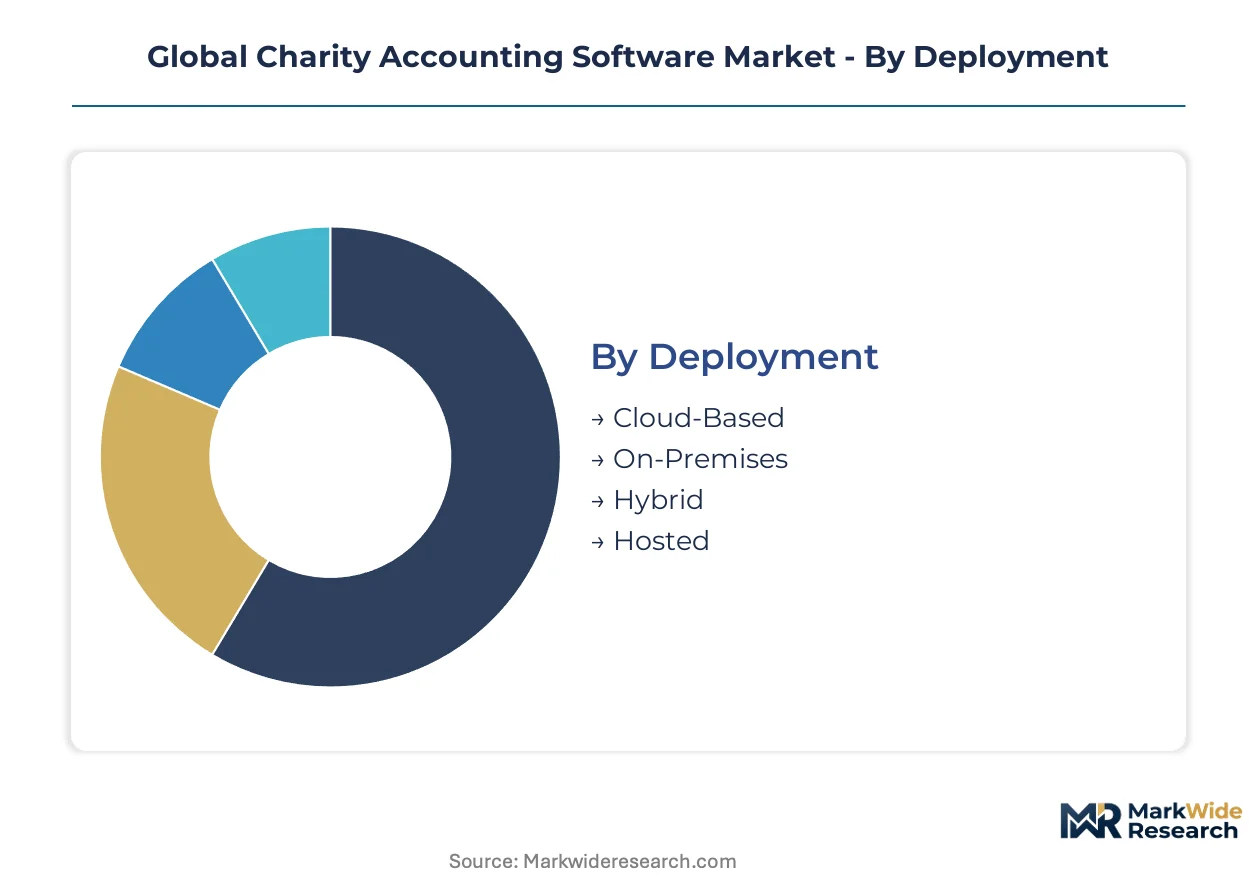
Charity accounting software segments reflect divergent compliance burdens, technical maturity, and procurement authority structures across the nonprofit sector. Deployment models determine integration architecture and data residency constraints. Solution offerings map directly to regulatory filing requirements in specific jurisdictions.
Deployment:
Cost tier separates organizations by capital availability and IT staffing depth, with cloud solutions dominating lean operations and on-premises systems preserving control in complex estates.
- Cloud-Based:Browser-accessible platforms with automatic updates and API-native connectivity to banking and donor systems. Demand concentrates among small charities in the United Kingdom and Australia, where ACNC and Charity Commission mandates accelerate replacement of spreadsheet workflows. Subscription economics align with volatile grant funding cycles.
- On-Premises:Locally installed software maintaining full data custody and custom ERP interconnectivity. Large philanthropic foundations in the United States retain these deployments to satisfy HIPAA-linked data residency policies when operating affiliated health clinics.
- Hybrid:Split architectures keeping sensitive donor records on local servers while pushing transactional processing to cloud instances.
- Hosted:Vendor-managed private cloud deployments offering dedicated infrastructure without capital expenditure.
Cloud-Based commands the established base. The steepest expansion runs through Hybrid configurations bridging legacy and modern architectures.
Solution Offering:
Application depth tracks regulatory complexity, with fund accounting modules absorbing the largest implementation budgets due to restricted-versus-unrestricted balance sheet integrity requirements.
- Fund Accounting:Purpose-built general ledger systems handling donor-imposed purpose constraints, net asset classification, and FASB or SORP-compliant reporting. Religious institutions and educational foundations deploy these most intensively, driven by multi-layered restriction tracking and endowment management needs.
- Donation Management:Platforms capturing donor data, pledge tracking, and automated receipt generation. Social advocacy groups in Australia adopt these rapidly under ACNC transparency pressure.
- Grant Tracking:Lifecycle management from application through reporting to funders.
- Reporting & Compliance:Automated generation of Form 990, Gift Aid documentation, and audit-ready financial statements.
- Volunteer Management:Scheduling, hour tracking, and background check integration for labor-intensive operations.
- CRM Integration:Bidirectional data flows between fundraising databases and financial systems.
Fund Accounting retains the deepest customer relationships. The fastest volume gains are occurring in Reporting & Compliance as GDPR-EU AI Act convergence forces platform replacements.
Application:
Customer type determines feature prioritization, with religious and educational segments driving complexity while environmental NGOs favor lean, mobile-first configurations.
- Non-Profit Organizations:General-purpose charities spanning human services, health, and community development. These organizations in the United Kingdom are migrating fastest to cloud-native platforms with real-time donor dashboards.
- Religious Institutions:Faith-based entities managing tithing, mission fund designations, and multi-campus consolidation. Complex donor segmentation and SORP compliance requirements in England and Wales sustain demand for sophisticated fund accounting modules.
- Educational Foundations:Scholarship funds and institutional endowments with restricted gift management.
- Cultural Societies:Museums, arts organizations, and heritage trusts with project-based funding cycles.
- Social Advocacy Groups:Campaign-focused nonprofits with rapid-response fundraising and volunteer mobilization needs.
- Environmental NGOs:Conservation and climate organizations with international program delivery and multi-currency requirements.
Religious Institutions anchor vendor recurring revenue. Environmental NGOs are climbing the fastest as international grant funding expands.
End User:
Organizational scale dictates procurement authority, implementation timelines, and integration complexity, with mid-sized trusts representing the most contested segment.
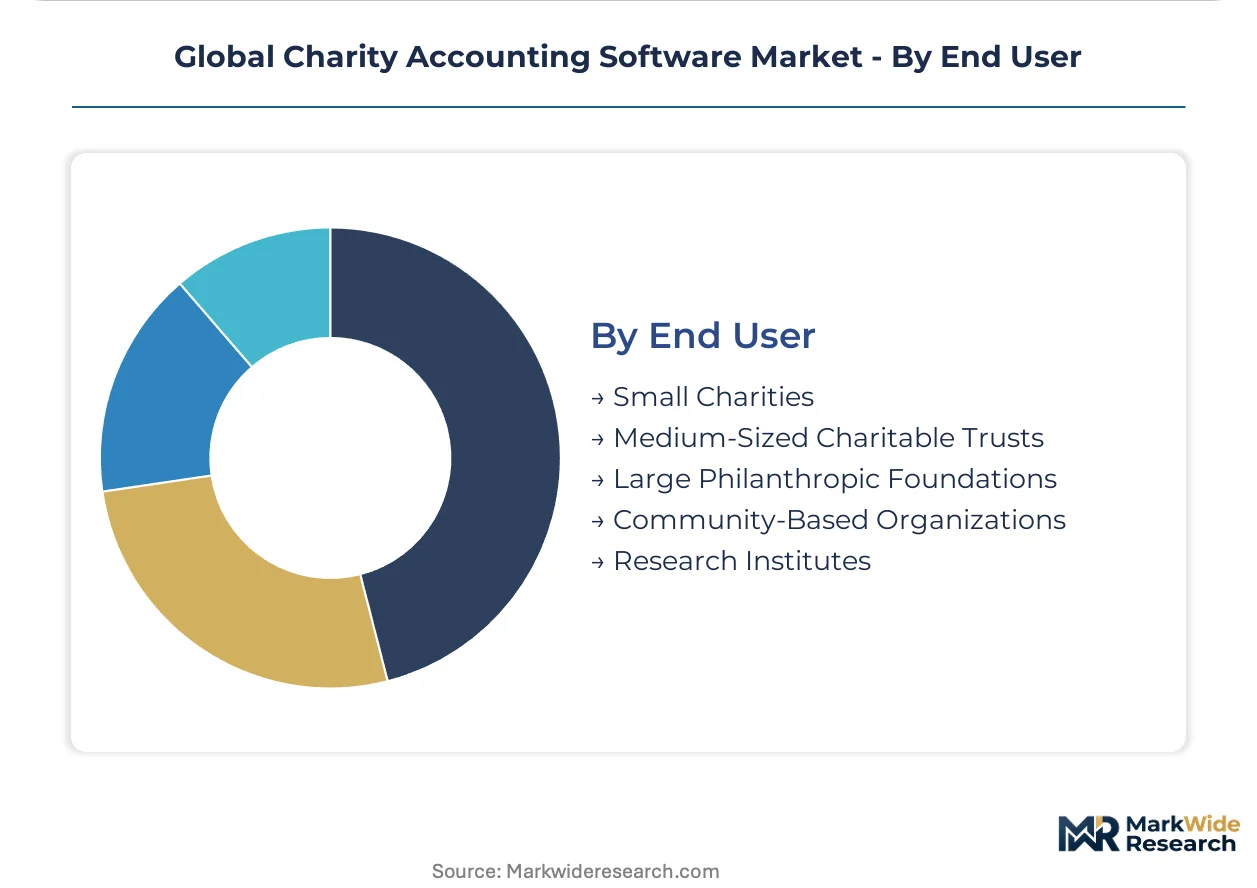
- Small Charities:Organizations with under fifty staff and limited dedicated finance personnel. These entities across Australia and the United Kingdom are abandoning spreadsheet-based tracking for browser platforms with native bank feeds and automated transaction classification.
- Large Philanthropic Foundations:Multi-billion-dollar endowed institutions with complex investment accounting and multi-entity consolidation. Data residency policies and legacy ERP interconnectivity in the United States delay their cloud migration timelines.
- Medium-Sized Charitable Trusts:Regional and national organizations with professionalized finance functions.
- Community-Based Organizations:Grassroots nonprofits with volunteer-led financial management.
- Research Institutes:Academic and scientific charities with federal grant compliance and indirect cost recovery requirements.
Small Charities represent the broadest installed base. Medium-Sized Charitable Trusts are gaining share fastest as subscription pricing displaces perpetual licenses.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United Kingdom software vendors export cloud-based fund accounting platforms to Australia and New Zealand as regulatory pressure intensifies across Commonwealth markets. Cross-border procurement concentrates in English-speaking jurisdictions sharing SORP-derived reporting standards.
United States
Large philanthropic foundations in New York and California sustain demand for on-premises fund accounting systems with HIPAA-compliant data residency. FDA oversight intersects with donor data handling when charities operate affiliated health clinics. The San Francisco Bay Area hosts clusters of cloud-native challengers targeting mid-sized nonprofits.
United Kingdom
Small charities across England and Wales are abandoning spreadsheet workflows for browser-based platforms with native bank feeds. The Charity Commission SORP mandates granular fund segregation that shapes vendor feature prioritization. London's fintech corridor accelerates embedded payment integration within accounting stacks.
Australia
Mid-sized nonprofits in Sydney and Melbourne upgrade to purpose-built fund accounting platforms under ACNC transparency mandates. The national regulator's disclosure requirements compel replacement of manual tracking systems. Melbourne's nonprofit technology cluster drives regional procurement authority.
Germany
Faith-based institutions in Bavaria and North Rhine-Westphalia deploy sophisticated fund accounting modules for multi-layered restriction tracking. GDPR compliance requirements reshape vendor product roadmaps for automated grant-scoring tools. Berlin's SaaS ecosystem incubates API-first accounting components.
India
Expanding NGO registration requirements and foreign contribution regulation enforcement create demand for localized fund accounting solutions. The country's central bank monitors cross-border donor flows that software platforms must track. Mumbai's nonprofit headquarters concentrate procurement decision-making.
Global Charity Accounting Software Market Competitive Landscape
Channel-controlling players compete with product-specialist players across deployment models and compliance depth. The market structure fragments between entrenched incumbents with legacy codebases and cloud-native challengers exploiting microservices composability. Two strategic archetypes dominate: horizontal accounting platforms extending into nonprofit verticals, and purpose-built fund accounting specialists. M&A activity concentrates on API-first components, while geographic expansion targets Commonwealth markets with aligned reporting standards.
Within the incumbent tier, Blackbaud and Sage Intacct occupy positions anchored in faith-based and educational segments with complex endowment management needs. Xero represents the horizontal-platform archetype among small charities seeking intuitive interfaces. Aplos Software exemplifies the specialist vector with purpose-built restricted fund capabilities. These three companies collectively illustrate how compliance depth and user experience simplicity define competitive positioning across organizational scale segments.
| Leading Market Players |
|---|
| Aplos Software |
| Intuit |
| Blackbaud |
| Pushpay |
| Xero |
| NetSuite |
| QuickBooks |
| Community Brands |
| Sage Intacct |
| Others |
Supply & Pricing Matrix
Cloud infrastructure concentration in the United States and Ireland concentrates margin capture among hyperscale providers, while downstream pricing power fragments across SaaS vendors competing for nonprofit procurement budgets. This upstream-downstream tension shapes how charity accounting platforms structure subscription tiers and where vendors absorb or pass through infrastructure cost volatility.
Pricing Analysis
Legacy perpetual-license systems command residual premiums among large US foundations with data residency constraints, while browser-native platforms price through three-tier subscription structures across premium, standard, and economy levels. Price differentiation rests on compliance depth—ACNC-ready reporting modules in Australia and SORP-automated workflows in the United Kingdom extract 40-60% premiums over baseline bookkeeping tiers. Cost compression in the small-charity segment intensifies as Xero and QuickBooks bundle fund accounting lite features into horizontal platforms at minimal incremental pricing. Finance directors at community-based organizations exhibit highest price sensitivity, deferring procurement until grant funding cycles stabilize.
Supply Chain Analysis
EU AI Act algorithmic transparency requirements restrict automated grant-scoring tool flows into European markets, forcing vendors to maintain parallel code branches. Core development concentrates in the United States, United Kingdom, and Australia, with Indian engineering centers supplying API-first component development. Cloud hosting dependencies on AWS, Azure, and Google Cloud create single-source vulnerability for data residency-compliant deployments. Distribution runs through direct SaaS self-service for small charities, value-added resellers for mid-sized trusts, and systems integrators for large foundation ERP interconnectivity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Charity accounting software sits in early-cycle expansion as Australia's ACNC mandates and India's NGO formalization create first-mover windows ahead of regulatory enforcement deadlines. Penetration remains below saturation across Commonwealth markets sharing SORP-derived standards.
For Market Incumbents: Pre-empt API standardization by embedding native connectors to Blackbaud and Salesforce nonprofit clouds before challenger microservices fragment integration budgets. Consolidate position through targeted acquisition of Gift Aid automation specialists in the United Kingdom, where compliance complexity sustains pricing power. Defend against horizontal-platform encroachment by Xero through deeper SORP workflow automation that generalist bookkeeping cannot replicate.
For New Entrants and Emerging Players: Build out AI-assisted audit preparation tools targeting medium-sized charitable trusts in Australia, where ACNC transparency pressure outpaces incumbent roadmap velocity. Capture share fastest through mobile-first configurations for environmental NGOs with international program delivery and multi-currency complexity. Lead go-to-market through Melbourne and Sydney nonprofit technology clusters where procurement authority concentrates regionally.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed horizontal accounting platforms seeking nonprofit vertical extension through tuck-in acquisitions. Long-term viability hinges on compliance automation moats deepening faster than regulatory convergence commoditizes features. Watch India's foreign contribution regulation enforcement intensity as the signal indicating when localized fund accounting solutions achieve scale viability.
| Strategic Initiative | Industry Significance |
|---|---|
| API-First Platform Integration | Enables modular assembly of fund accounting stacks without monolithic rewrites. |
| Acquisition of Compliance Specialists | Captures SORP and ACNC workflow expertise that accelerates time-to-market. |
| Embedded Fintech Convergence | Compresses procurement cycles by unifying payment processing with accounting. |
| Geographic Expansion to Commonwealth Markets | Leverages shared reporting standards across Australia, New Zealand, and Canada. |
| AI-Assisted Audit Preparation Development | Addresses talent scarcity in restricted fund accounting through machine learning automation. |
Research Methodology
Operator-level perspectives from nonprofit CFOs, charity commission auditors, SaaS procurement officers, and systems integration specialists anchored the qualitative base. Primary interviews combined with secondary validation against Charity Commission SORP guidance documents, ACNC disclosure templates, SEC filings from listed software vendors, and EU AI Act regulatory texts. Bottom-up sizing of cloud deployment volumes triangulated against top-down addressable nonprofit counts across jurisdictions.
Scenario-bracketing framed the analytical approach across the projection horizon, modeling deployment model shifts, organization size tier migrations, and vertical adoption patterns. CAGRs derived from segment-level growth rate assumptions calibrated to regulatory enforcement timelines and cloud migration velocity observed in comparable SaaS verticals. Forecast inputs incorporated grant funding cycle volatility and compliance automation penetration curves.
Sensitivities concentrate around EU AI Act enforcement timing, India's foreign contribution regulation implementation pace, and US foundation cloud migration acceleration. Forecasts reflect documented assumptions on regulatory convergence and vendor consolidation trajectories. Material shifts in GDPR-EU AI Act convergence stringency or Commonwealth market procurement centralization would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
UK Applicant Tracking System Market
Software & Services
Denmark Software As a Service (Saas) Market
Software & Services
Global Java Web Frameworks Software Market
Software & Services
Global Contract Lifecycle Management Software Market
Software & Services
Stock Footage Software Market
Software & Services
Search and Discovery Software Market
Software & Services
Nonconformance Management Software Market
Software & Services
Client Virtualization Software Market
Software & Services
Japan IT Services Market
Software & Services
Global Open API Market
Software & Services
Global Managed File Transfer (MFT) Software and Service Market
Software & Services
Oracle Services Market
Software & Services
Classified Platform Market
Software & Services
Cloud Business Process Management (BPM) Software Market
Software & Services
Global Job Evaluation Software Market
Software & Services
Mobile Tracking Software Market