
 Automotive Customization Software Market | 2026-2036
Automotive Customization Software Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Customization Software Market Outlook
ISO 26262 functional safety certification is rotating the competitive landscape by filtering out vendors lacking automotive-grade software validation. DXC Technology leverages its embedded systems heritage to sustain long-term contracts with tier-one suppliers. Luxoft anchors its position through deep integration with German OEM digital twin architectures. GlobalLogic competes by extending its Ukraine-based engineering centers into automotive HMI specialization.
Automotive customization software comprises digital tools that enable real-time vehicle specification, visual configuration, and engineering validation across exterior, interior, and powertrain parameters. These platforms integrate parametric 3D rendering with rules-based compatibility engines to prevent invalid build combinations before production commitment. Configuration Tools currently dominate transaction volumes as dealerships require intuitive interfaces for consumer-facing sales, while AI-Driven Solutions represent the fastest-expanding technology segment as machine learning accelerates option recommendation engines. Cloud-Based deployment captures the largest margin pools by converting perpetual licenses into recurring SaaS revenue streams across multinational OEM networks.
FDA cybersecurity guidance for connected vehicles, EPA emissions certification workflows, and ISO 27001 data security standards collectively shape product requirements and vendor qualification criteria. The EU AI Act specifically constrains automated decision-making in consumer-facing configurators, forcing platform redesigns for European market access. Stakeholders must monitor evolving type-approval linkages between software-defined vehicle features and homologation processes.
Market Dynamics
Build-to-order manufacturing strategies are compressing configuration cycle times and forcing software vendors to integrate real-time engineering validation with consumer-facing visualization tools.
Growth Catalysts
- OEM Configurator Mandates:Automakers in Germany, Japan, and the United States now require dealer-facing platforms that synchronize with manufacturing execution systems for order-to-delivery transparency.
- EU AI Act Compliance:European regulators are mandating explainable decision logic in automated recommendation engines, which accelerates platform modernization investments across the continent.
- Digital Twin Convergence:Engineering teams are merging vehicle simulation environments with sales configurators to validate build combinations before production commitment.
Market Restraints
- ISO 26262 Certification Burden:Functional safety validation for embedded configuration modules extends development timelines and excludes smaller software vendors from tier-one supply chains.
- Cloud Infrastructure Concentration:Hyperscale data center reliance in Ireland and Frankfurt creates single-point-of-failure exposure for SaaS-based customization platforms serving multinational OEM networks.
- Legacy System Entrenchment:Proprietary dealer management systems in North American dealership groups resist API integration with modern cloud-native configurators.
Strategic Opportunities
- India PLI Scheme Alignment:Production-linked incentives for automotive software development are attracting engineering centers to Bangalore and Pune for cost-optimized configuration tool development.
- Subscription Revenue Conversion:Perpetual license holders across German premium OEMs represent captive targets for SaaS migration and recurring service attachment.
- AR-VR Interface Convergence:Spatial computing headsets and mobile augmented reality are creating immersive configuration experiences that bypass traditional screen-based interaction limits.
Industry Challenges
- Functional Safety Engineering Scarcity:ISO 26262-certified software architects command premium compensation and remain concentrated within German automotive clusters.
- Cross-Border Data Sovereignty:GDPR-mandated data localization requirements conflict with centralized cloud architectures serving multi-country OEM deployments.
- Homologation Workflow Integration:Type-approval documentation systems in individual EU member states resist automated linkage with software-defined vehicle feature configurations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Customization Software Market |
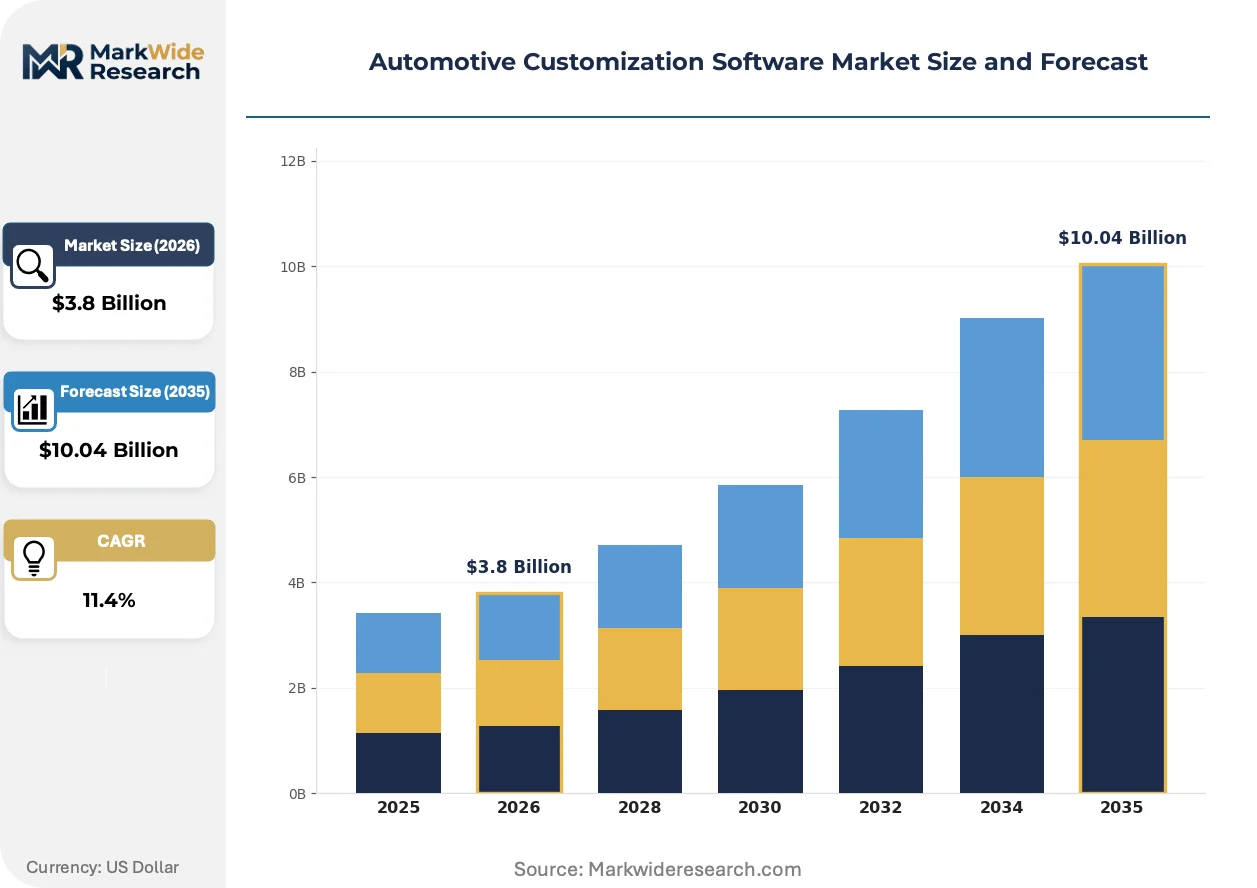
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Design Software, Configuration Tools, Simulation Software, Customer Relationship Management End User: Automotive OEMs, Aftermarket Retailers, Dealerships, Fleet Management Technology: Cloud-Based, On-Premises, Mobile Applications, AI-Driven Solutions Service Type: Implementation Services, Training Services, Support Services, Maintenance Services |
| Companies Covered | Zco Corporation, EPAM Systems, Devox Software, DXC Technology, Rightpoint, Inoxoft, Luxoft, GlobalLogic, Saritasa, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Customization Software Market Strategic Shifts
Generative AI is rewriting interface design norms while regulatory pressure on automated decision systems intensifies compliance engineering requirements.
Parametric 3D rendering engines are fragmenting the traditional monolithic configurator architecture into modular microservices. Tier-one suppliers in Stuttgart and Munich are adopting component-based visualization libraries that decouple exterior, interior, and powertrain configuration modules. This fragmentation enables faster feature rollout without platform-wide regression testing.
REACH substance restriction updates are forcing material database overhauls within configuration platforms. The European Chemicals Agency's expanded candidate list now requires real-time validation of interior trim options against restricted substance thresholds. Premium SUV and luxury sedan configurators in the EU market are deploying automated compliance flags that block invalid material combinations before consumer display.
Fleet procurement departments are consolidating vendor relationships and demanding API-first configuration tools that integrate with enterprise resource planning systems. Commercial vehicle buyers in the United States now expect direct-to-factory ordering portals that bypass traditional dealer negotiation. This concentration of buying authority is compressing configuration cycle times and elevating self-service platform requirements.
Automotive Customization Software Market Segmentation
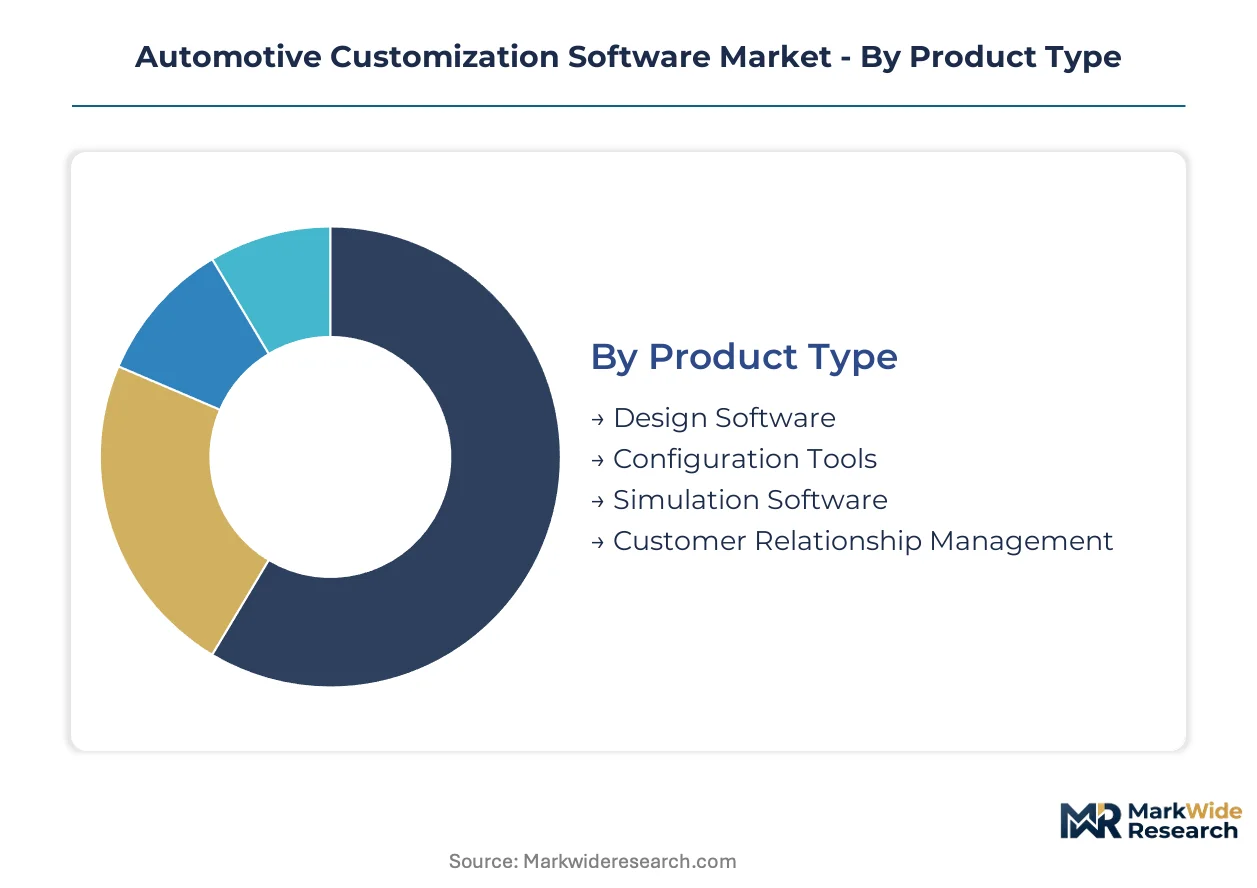
Segmentation in automotive customization software reveals distinct procurement patterns across channel types. OEMs pursue direct vendor relationships for engineering-grade platforms, while dealerships rely on distributor-mediated SaaS subscriptions. Fleet operators and aftermarket retailers occupy separate purchasing tiers with divergent integration requirements.
Product Type:
Channel flow varies sharply by product complexity. Configuration Tools move through OEM direct sales teams and tier-one system integrators, while Design Software and CRM modules often route through value-added resellers serving smaller dealership networks.
- Configuration Tools:These platforms integrate parametric 3D rendering with rules-based compatibility engines that prevent invalid build combinations before production commitment. German premium OEMs concentrate demand here as build-to-order strategies require real-time synchronization between consumer-facing interfaces and manufacturing execution systems. ISO 26262 functional safety certification filters vendor participation at this tier.
- Design Software:Advanced surfacing and visualization tools enable exterior and interior aesthetic customization with photorealistic output. Engineering teams in Stuttgart and Munich anchor demand for these modules as they merge vehicle simulation environments with sales configurators. The segment requires deep integration with OEM digital twin architectures.
- Simulation Software:Physics-based validation tools for powertrain and chassis configuration options.
- Customer Relationship Management:Lead tracking and preference analytics modules for dealership sales operations.
Configuration Tools dominate installed base. Design Software is where expansion concentrates.
End User:
Customer scale determines platform architecture and pricing models. Large-scale OEM deployments favor perpetual licenses with maintenance contracts, while smaller fleet operators and aftermarket retailers increasingly accept SaaS pricing with per-seat subscriptions.
- Automotive OEMs:Direct factory relationships require platforms that synchronize with manufacturing execution systems for order-to-delivery transparency. German, Japanese, and United States automakers mandate dealer-facing configurators with real-time engineering validation. These buyers command the largest contract values and longest sales cycles.
- Fleet Management:Commercial vehicle procurement departments consolidate vendor relationships and demand API-first tools that integrate with enterprise resource planning systems. United States fleet operators now expect direct-to-factory ordering portals that bypass traditional dealer negotiation, compressing configuration cycle times significantly.
- Dealerships:Consumer-facing sales operations requiring intuitive interfaces for vehicle specification.
- Aftermarket Retailers:Independent customization shops seeking modular tools for accessory and upgrade visualization.
Automotive OEMs capture the largest contract values. Fleet Management is climbing the fastest as commercial buyers consolidate purchasing authority.
Technology:
Deployment model shapes margin structure and vendor competitive position. Cloud architectures convert upfront license revenue into recurring streams, while on-premises installations retain higher initial recognition with lower long-term visibility.
- Cloud-Based:SaaS delivery captures the largest margin pools across multinational OEM networks by eliminating perpetual license capital expenditure. Hyperscale data center reliance in Ireland and Frankfurt creates operational concentration risk for European deployments. GDPR-mandated data localization requirements conflict with centralized architectures serving multi-country implementations.
- AI-Driven Solutions:Machine learning accelerates option recommendation engines and automates compatibility validation. The EU AI Act constrains automated decision-making in consumer-facing configurators, forcing platform redesigns for European market access with explainable decision logic mandates.
- On-Premises:Legacy installations in security-sensitive environments with dedicated infrastructure requirements.
- Mobile Applications:Smartphone and tablet interfaces for field sales and consumer self-service configuration.
Cloud-Based deployments command recurring revenue premiums. AI-Driven Solutions face regulatory headwinds in Europe while expanding elsewhere.
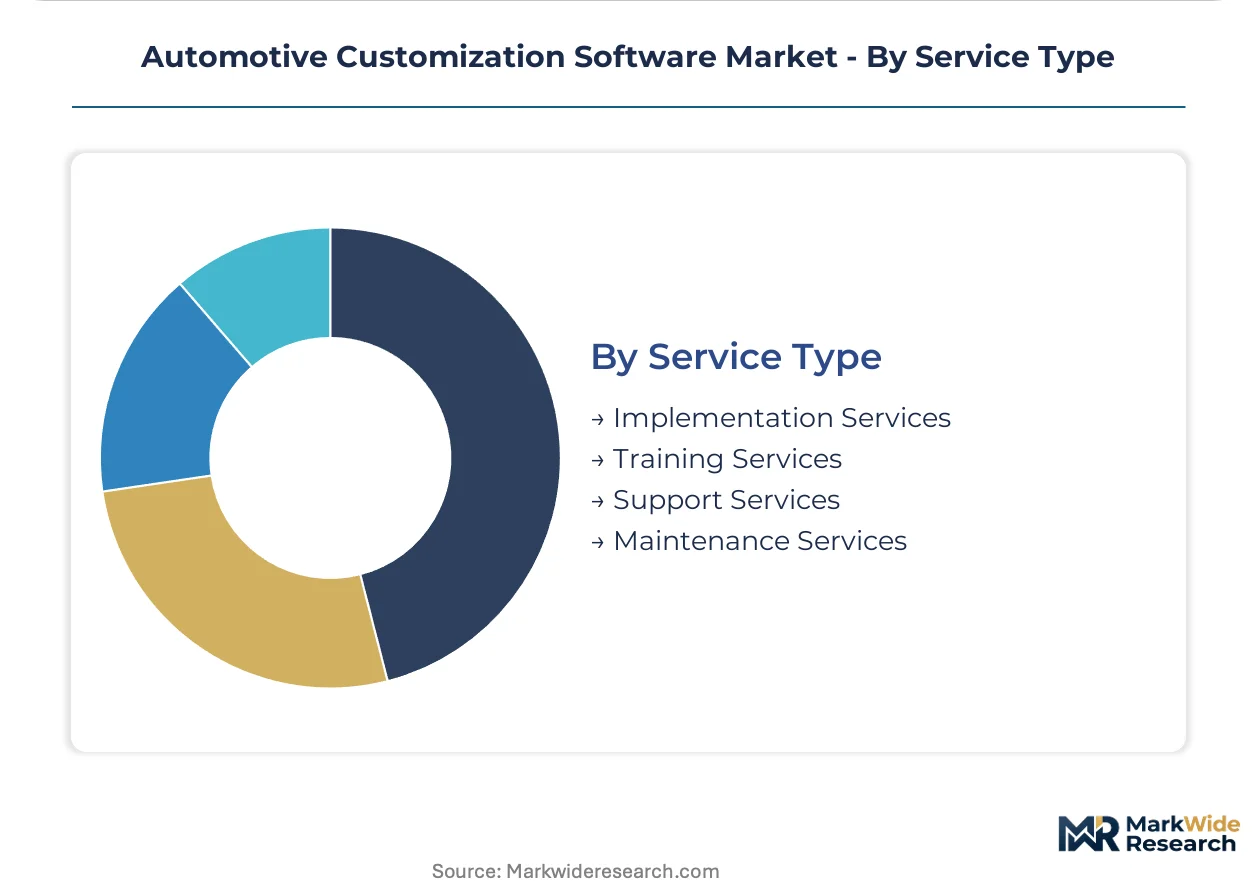
Service Type:
Service attachment rates correlate with product complexity and customer technical maturity. Implementation and training services concentrate at initial deployment, while maintenance and support extend across contract lifecycles.
- Implementation Services:System integration, data migration, and workflow configuration for new deployments. German OEM digital twin architectures require specialized integration expertise that concentrates delivery capacity within Stuttgart and Munich engineering clusters.
- Maintenance Services:Ongoing platform updates, security patching, and regulatory compliance management. REACH substance restriction updates and ISO 27001 data security standards drive recurring maintenance demand as platforms must validate interior trim options against restricted substance thresholds in real time.
- Training Services:User onboarding and administrator certification programs for dealership staff.
- Support Services:Technical helpdesk and troubleshooting operations for production configuration environments.
Implementation Services concentrate professional services revenue. Maintenance Services provide the steadiest expansion trajectory as regulatory compliance burdens accumulate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fleet procurement departments in the United States concentrate buying authority for commercial vehicle configurators, while German engineering clusters anchor premium OEM platform development. Japanese automakers drive standardization requirements for Asia-Pacific dealer networks.
United States
Commercial fleet operators demand API-first configuration tools that integrate with enterprise resource planning systems for direct-to-factory ordering. NHTSA cybersecurity guidance for connected vehicles shapes platform validation requirements. Engineering teams in Detroit and Austin anchor development centers for cloud-native configurators serving North American dealership groups.
Germany
Premium OEMs mandate real-time synchronization between consumer-facing interfaces and manufacturing execution systems for build-to-order transparency. The EU AI Act constrains automated decision-making in configurators, forcing platform redesigns for explainable decision logic. Stuttgart and Munich engineering clusters concentrate ISO 26262-certified software architects for functional safety validation.
Japan
Automakers pursue standardized dealer-facing platforms across domestic and export markets with rigorous quality assurance protocols. METI industrial policy supports digital transformation investments in automotive supply chains. Tokyo and Nagoya technology corridors host configuration tool development for Asian market localization.
India
Production-linked incentives for automotive software development attract engineering centers to cost-optimized configuration tool development. BIS standards compliance requirements shape platform architecture decisions for domestic market access. Bangalore and Pune technology hubs concentrate SaaS development capacity for international OEM vendor relationships.
United Kingdom
Fleet management companies consolidate vendor relationships for commercial vehicle specification platforms with Brexit-adjusted supply chain visibility. GDPR data localization requirements conflict with centralized cloud architectures serving European deployments. London fintech corridors and Midlands automotive clusters split development focus between financial services integration and manufacturing system connectivity.
Automotive Customization Software Market Competitive Environment
Player mix skews toward systems integrators with embedded automotive heritage. Tier-one technology service providers dominate contract values for OEM direct relationships, while specialized software boutiques capture niche implementation projects. Two strategic archetypes define competitive positioning: engineering-centric consultancies with functional safety certification and cloud-native developers with SaaS platform expertise. Dominant competitive moves include strategic partnerships with hyperscale cloud providers and portfolio diversification into adjacent digital twin services.
Among US-based technology service providers, DXC Technology occupies a position within the embedded systems heritage archetype, while EPAM Systems represents the engineering-scale tier. Luxoft anchors the European specialist segment with deep integration positioning. These three exemplify how vendor selection concentrates on demonstrated automotive software validation capabilities rather than generic enterprise platform experience.
| Leading Market Players |
|---|
| Zco Corporation |
| EPAM Systems |
| Devox Software |
| DXC Technology |
| Rightpoint |
| Inoxoft |
| Luxoft |
| GlobalLogic |
| Saritasa |
| Others |
Value Chain & Pricing Dynamics
Long-term SaaS subscription contracts with tiered capacity reservations lock in both cloud infrastructure access and predictable annual recurring revenue visibility for automotive software vendors serving German and Japanese OEM networks.
Pricing Analysis
Cost-plus contracts indexed to hyperscale cloud compute rates dominate enterprise deployments. Three-tier pricing structure across premium, standard, and economy levels separates ISO 26262-certified platforms from uncertified alternatives and open-source derivatives. Pricing pressure stems from India's PLI scheme attracting cost-optimized engineering centers to Bangalore and Pune. Fleet management buyers exhibit highest price sensitivity due to consolidated procurement authority, while premium OEMs prioritize functional safety certification over cost minimization.
Supply Chain Analysis
Port congestion at Rotterdam and Hamburg elevates inbound logistics costs for specialized rendering hardware sourced from Taiwan and South Korea. Software development capacity concentrates in Germany, India, and the United States, with cloud infrastructure dependencies on hyperscale data centers in Ireland and Frankfurt. The supply chain draws from semiconductor components, high-performance computing clusters, and certified engineering talent pools. Single-source vulnerability exists in ISO 26262-certified architect availability concentrated within Stuttgart and Munich clusters. Distribution runs through direct OEM vendor relationships and tier-one system integrator partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive customization software sits in early-cycle expansion as build-to-order manufacturing mandates penetrate beyond German premium OEMs into broader European and North American production networks.
For Market Incumbents: Shield market position by deepening ISO 26262 certification moats against cloud-native challengers lacking automotive-grade validation heritage. Prioritize captive engineering capacity expansion in Stuttgart and Munich clusters where functional safety architect scarcity creates recruitment bottlenecks for competitors. For New Entrants and Emerging Players: API integration services for legacy dealer management systems represent a service-layer gap where incumbents under-serve North American dealership groups resisting cloud-native migration. Fleet procurement departments in the United States offer the most penetrable entry point through direct-to-factory ordering portal specialization. Lead with ERP integration expertise rather than visualization feature differentiation. For Investors and Strategic Acquirers: Engineering-centric consultancies with embedded automotive heritage and existing Luxoft-style OEM digital twin relationships present the most defensible acquisition target archetype. Long-term viability hinges on SaaS revenue conversion velocity across German premium OEM perpetual license bases. Monitor EU AI Act implementation enforcement intensity as an inflection indicator for platform modernization demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 26262 Certification Investment | Functional safety validation filters vendor participation in tier-one supply chains serving German OEMs. |
| SaaS Migration Program | Recurring revenue conversion targets German premium OEM perpetual license holders for platform modernization. |
| Digital Twin Architecture Integration | Deep engineering ties with Stuttgart and Munich clusters anchor long-term OEM platform relationships. |
| AR-VR Interface Development | Spatial computing headsets bypass traditional screen-based configuration limits for immersive consumer experiences. |
| India Engineering Center Expansion | PLI scheme alignment attracts cost-optimized configuration tool development capacity to Bangalore and Pune. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of SEC filings, hyperscaler capex disclosures, and vehicle production databases. Primary interviews engaged CTOs at tier-one suppliers, OEM platform engineers, dealership operations managers, and automotive software integration specialists. Secondary validation drew from IHS Markit registration data, customs records for specialized rendering hardware, and EU regulatory filings. Bottom-up segment sizing triangulated against top-down market aggregation.
Segmentation dimensions modeled include deployment architecture, end-user scale, technology integration complexity, and regional production cluster concentration. Value projections derive from installed base expansion, SaaS pricing tier migration velocity, and attach rates for implementation and maintenance services across the analysis window. Forecast inputs incorporate OEM build-to-order adoption curves and regulatory compliance investment schedules.
Forecasts assume regulatory continuity in EU AI Act implementation and NHTSA cybersecurity guidance; material policy shifts would require re-modeling. REACH substance restriction updates and ISO 27001 data security standard revisions represent specific risk factors that could alter platform development cost assumptions. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Family Office Software Solutions Market
Software & Services
Europe Human Resource (HR) Technology Market
Software & Services
Global Diagram Software Market
Software & Services
Quality and Lifecycle Management Software Market
Software & Services
Artwork Management Software Market
Software & Services
Global Virtualization Software Market
Software & Services
Consignment Software Market
Software & Services
Global HMI Software Market
Software & Services
Enterprise Content Management Software Market
Software & Services
Global Business Software Market
Software & Services
Global Software Composition Analysis Market
Software & Services
Programmable Automation Controller Software Market
Software & Services
Event Management Software Market
Software & Services
CAD Modeling Software Market
Software & Services
Workflow Management Software (WMS) Market
Software & Services
Global Electronic Data Capture Software Market