
 Global DevOps Software Market | 2026-2036
Global DevOps Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global DevOps Software Market Foresight
India is narrowing its DevOps talent gap through specialized engineering institutes and government-backed cloud skilling programs. Microsoft Corporation leverages its Azure DevOps ecosystem to anchor enterprise pipelines across hybrid environments. Amazon Web Services sustains market presence through deep integration between its CI/CD tooling and native cloud infrastructure services.
DevOps software encompasses integrated toolchains that automate software build, test, deployment, and infrastructure provisioning workflows through APIs, agent-based runners, and declarative configuration formats such as YAML and HCL. The primary commercial purpose is collapsing release cycles from months to hours while maintaining audit trails and rollback capabilities for production systems. Cloud-based deployment dominates new procurement as enterprises exit capital-intensive data center commitments, while containerized delivery represents the fastest-expanding configuration due to Kubernetes standardization across vendor platforms. Security and compliance solutions command premium pricing as financial services and government agencies mandate software supply chain attestation.
ISO 27001 certification requirements and SOC 2 Type II audits shape vendor selection criteria for DevOps platforms handling sensitive build artifacts and deployment credentials. The EU AI Act and GDPR cross-cut automated decision pipelines, forcing European enterprises to embed explainability and data residency controls into their CI/CD orchestration layers. Stakeholders must evaluate how emerging sovereign cloud mandates and algorithmic accountability rules will reshape toolchain architecture and geographic data routing decisions.
Market Dynamics
Container orchestration standardization around Kubernetes is compressing vendor differentiation and forcing platform consolidation across enterprise toolchains. This technical convergence is redistributing value toward integrated security and compliance layers.
Growth Catalysts
- ISO 27001 Certification Mandates:Financial services firms in Germany and the United States now require attested software supply chains, driving procurement of compliance-embedded CI/CD platforms.
- India Cloud Skilling Programs:Government-backed workforce development is expanding the engineering talent pool available to multinational DevOps implementations.
- Infrastructure-as-Code:Declarative configuration formats such as HCL and YAML are automating provisioning workflows and collapsing deployment error rates in cloud-native architectures.
Market Restraints
- Credential Sprawl Risk:Secrets management complexity escalates with multi-cloud deployments, exposing enterprises to lateral movement attacks in hybrid environments.
- Specialized Talent Scarcity:Site reliability engineering expertise concentrates in technology hubs across the United States, Germany, and India, constraining rollout velocity elsewhere.
- Legacy System Entanglement:Mainframe and monolithic application estates in established enterprises resist containerization, fragmenting toolchain standardization efforts.
Strategic Opportunities
- EU AI Act Compliance Layer:Explainability and data residency requirements for automated decision pipelines create white space for European sovereign cloud DevOps vendors.
- Platform Engineering Convergence:Internal developer platforms integrating Kubernetes, policy-as-code, and observability are displacing point-tool procurement in large enterprises.
- South Korean Financial Sector:MFDS-aligned digital transformation mandates are accelerating cloud-native adoption among Seoul-based banking consortia.
Industry Challenges
- SOC 2 Type II Audit Timelines:Six to twelve month certification cycles delay market entry for emerging DevOps security vendors serving regulated industries.
- Agent-Based Runner Fragmentation:Incompatible execution environments across cloud providers complicate pipeline portability and inflate integration engineering costs.
- Supply Chain Attestation Complexity:SBOM generation and verification tooling remains immature, creating execution gaps between policy requirements and operational capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global DevOps Software Market |
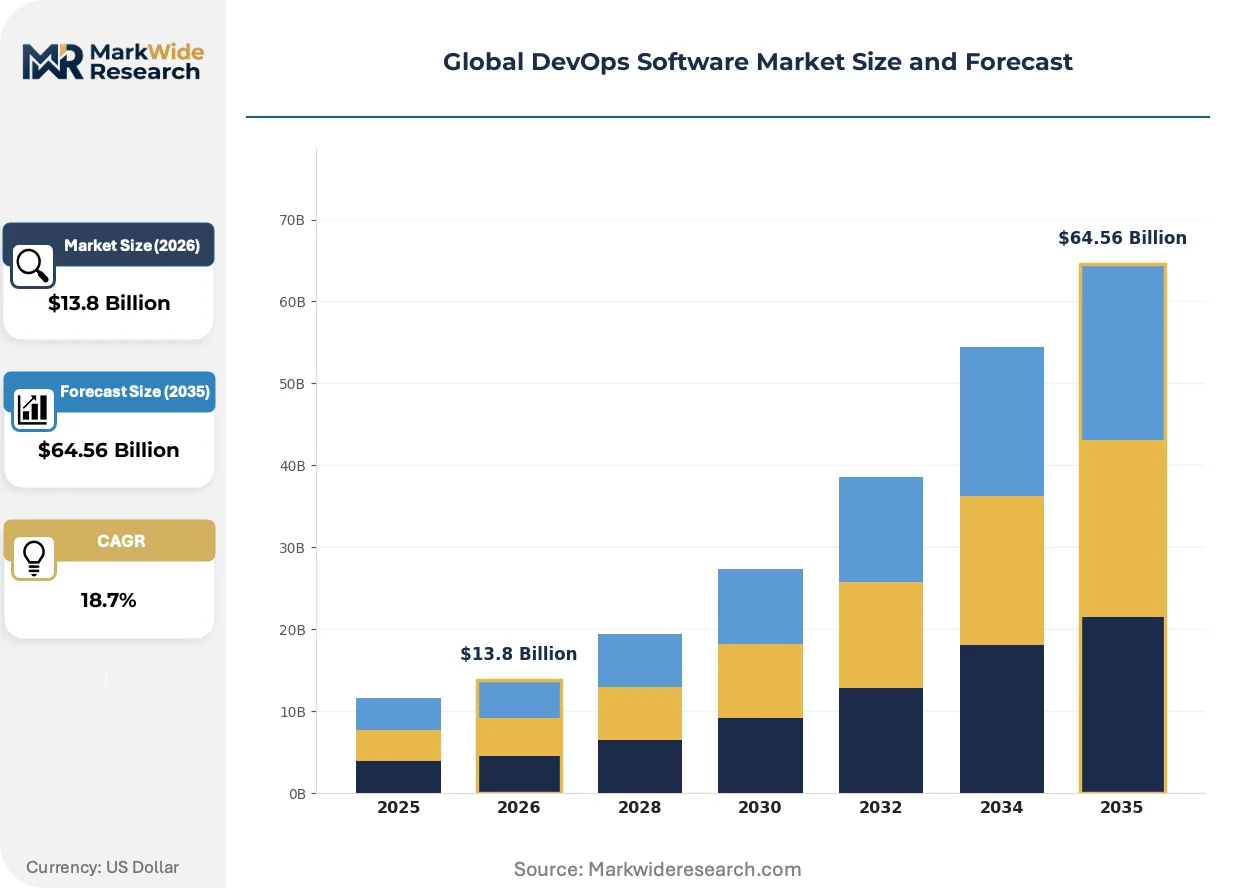
| Market Size in 2026 | $13.8 Billion |
| Market Size in 2035 | $64.56 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud-Based, Hybrid, Containerized Solution Type: Continuous Integration, Continuous Delivery, Infrastructure as Code, Monitoring & Logging, Security & Compliance Use Case: Application Development, Automation, Performance Management, Collaboration Enhancement End User Industry: Financial Services, Telecommunications, Government Agencies, Software Publishers |
| Companies Covered | Microsoft Corporation, IBM Corporation, Amazon Web Services, Google LLC, Atlassian Corporation, Broadcom Inc, GitLab Inc., Oracle Corporation, Red Hat Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global DevOps Software Market Shifts & Advancements
GitOps operational models are restructuring how infrastructure state is managed and reconciled, shifting control planes toward version-controlled declarative systems. This pattern is converging with policy-as-code frameworks to embed compliance verification directly into deployment automation.
Kubernetes-native continuous delivery controllers are collapsing the distinction between application packaging and infrastructure provisioning. Platform teams at financial services firms are adopting these controllers to unify deployment semantics across development and production environments. The structural consequence is compressing the traditional boundary between CI and CD tooling into single-plane orchestration layers.
The EU AI Act's algorithmic accountability requirements are forcing European enterprises to embed explainability checkpoints and data residency controls into CI/CD pipelines. Automated decision systems must now maintain audit trails from training data through production inference. DevOps vendors serving GDPR jurisdictions are responding by integrating lineage tracking and model registry capabilities directly into their orchestration platforms.
Buyer procurement patterns are gravitating toward consolidated platform subscriptions that subsume previously discrete point tools. Enterprise technology sourcing teams in the United States are negotiating multi-year agreements with single vendors rather than assembling best-of-breed toolchains. This concentration is most visible among Fortune 500 manufacturers modernizing operational technology software delivery.
Global DevOps Software Market Segmentation
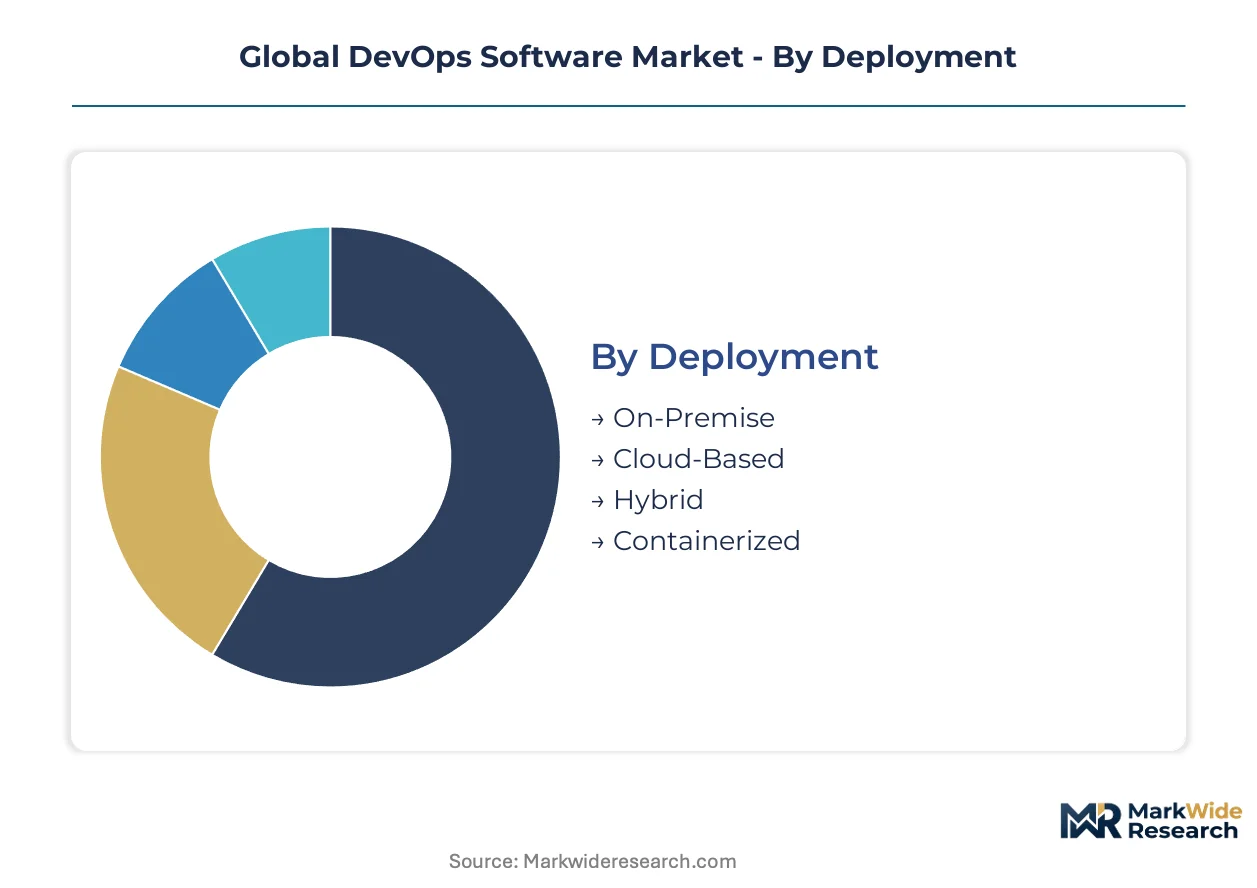
DevOps software segmentation reveals how deployment topology, solution architecture, and industry compliance requirements reshape procurement patterns across enterprise technology stacks. Understanding these dimensions exposes where vendor consolidation concentrates and where specialized tooling retains pricing power.
Deployment:
Cloud-native workloads span edge data centers to sovereign infrastructure zones, with each deployment model carrying distinct operational trade-offs in latency, control, and audit scope.
- Cloud-Based:Multi-tenant SaaS platforms eliminate capital expenditure for pipeline infrastructure while embedding automatic security patching. Financial services firms in Germany and the United States favor this model under ISO 27001 attestation requirements, though data residency clauses in GDPR jurisdictions constrain provider selection.
- Containerized:Kubernetes-orchestrated execution environments standardize build and runtime semantics across hybrid estates. Indian technology services exporters deploy this configuration most aggressively, leveraging government cloud skilling programs to staff platform engineering teams at scale.
- On-Premise:Air-gapped installations serve classified government workloads and defense contractors with mandatory physical control over build artifacts.
- Hybrid:Split orchestration across private data centers and public cloud regions accommodates phased migration of legacy monoliths.
Established volume favors Cloud-Based deployments; emerging adoption favors Containerized orchestration as Kubernetes standardization accelerates.
Solution Type:
Enterprise procurement gravitates toward integrated platforms that collapse previously discrete toolchain categories into unified control planes.
- Continuous Integration:Automated build and test pipelines triggered by version control commits. Software publishers in the United States deploy these most densely, driven by competitive pressure to compress release cadence from weeks to hours.
- Security & Compliance:Policy-as-code frameworks embedding SOC 2 and ISO 27001 verification into deployment gates. German financial institutions command premium pricing here, mandating software supply chain attestation for all third-party dependencies.
- Continuous Delivery:Release automation extending from artifact repository to production environment.
- Infrastructure as Code:Declarative provisioning through HCL and YAML replacing manual configuration.
- Monitoring & Logging:Observability pipelines aggregating metrics, traces, and audit logs for incident response.
Procurement concentration sits with Continuous Integration; steepest expansion trajectory belongs to Security & Compliance as regulatory mandates harden.
Use Case:
Functional applications of DevOps tooling track how enterprises prioritize velocity, reliability, or cross-functional coordination.
- Application Development:End-to-end automation from code commit through production deployment. Telecommunications operators in India invest most heavily here, modernizing customer-facing digital services under competitive pressure from over-the-top challengers.
- Automation:Repetitive task elimination across testing, provisioning, and configuration management. Government agencies in the United States adopt this use case to satisfy executive mandates for IT modernization with constrained staffing.
- Performance Management:Latency optimization and capacity planning through continuous observability.
- Collaboration Enhancement:Shared visibility across development, operations, and security functions.
Current spending clusters around Application Development; Automation use cases gain share fastest as public sector procurement accelerates.
End User Industry:
Regulatory intensity and digital maturity create divergent procurement patterns across vertical markets.
- Financial Services:Banks and insurers with mandatory audit trails for all production changes. German and US institutions lead deployment sophistication, embedding EU AI Act explainability requirements into automated decision pipelines.
- Government Agencies:Sovereign cloud mandates and classified workload constraints. Indian central and state governments expand procurement through digital infrastructure programs targeting citizen service delivery.
- Telecommunications:Network function virtualization and 5G service orchestration driving cloud-native adoption.
- Software Publishers:Pure-play technology vendors with highest CI/CD pipeline density per engineering headcount.
Financial Services anchors current revenue; Government Agencies represent the fastest-climbing vertical as sovereign cloud procurement frameworks mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SEC attestation requirements and FedRAMP authorization frameworks shape procurement patterns across the United States, while EU AI Act compliance mandates reshape European pipeline architecture. India's PLI scheme for IT hardware and cloud skilling programs accelerate talent formation for multinational DevOps implementations.
United States
Financial services firms in New York and San Francisco drive demand for SOC 2 Type II certified CI/CD platforms with software supply chain attestation. SEC cybersecurity disclosure rules mandate audit trails for all production system changes. The Boston-Washington corridor concentrates platform engineering talent for federal cloud modernization contracts.
Germany
Frankfurt-based banking consortia require ISO 27001 certification for all DevOps tooling handling payment infrastructure credentials. BaFin supervisory mandates enforce granular logging for automated decision systems in insurance underwriting pipelines. Bavarian automotive manufacturers embed compliance gates into Kubernetes-native delivery controllers for connected vehicle software.
India
Bengaluru and Hyderabad technology campuses supply platform engineering talent to global enterprises through government-backed cloud skilling initiatives. RBI data localization guidelines force domestic financial institutions to maintain sovereign pipeline infrastructure for core banking systems. Maharashtra-based IT services exporters deploy containerized orchestration most aggressively among Asia-Pacific delivery centers.
South Korea
Seoul banking groups accelerate cloud-native adoption under MFDS-aligned digital transformation mandates for financial infrastructure modernization. KISA cybersecurity frameworks require encrypted artifact repositories for critical financial system deployments. The Pangyo Techno Valley cluster hosts specialized DevOps consultancies serving chaebol-affiliated software subsidiaries.
United Kingdom
London financial institutions embed EU AI Act explainability requirements into automated trading pipeline checkpoints despite post-Brexit regulatory divergence. FCA operational resilience rules mandate recovery time objectives for CI/CD infrastructure serving retail banking platforms. The Manchester-Leeds corridor emerges as a secondary hub for government digital service delivery teams.
Global DevOps Software Market Competitive Landscape
Hyperscale cloud providers and independent DevOps specialists split the market into distinct capability tiers. Consolidation pressure intensifies as enterprise procurement teams favor integrated platform subscriptions over assembled toolchains. Three archetypes dominate: infrastructure-anchored suites, open-source-native challengers, and vertical compliance specialists. M&A activity concentrates on security and policy-as-code capabilities, while strategic partnerships bridge on-premise legacy estates with cloud-native orchestration layers.
Within the infrastructure-anchored tier, Microsoft Corporation and Amazon Web Services exemplify platform consolidation strategies that embed CI/CD tooling within broader cloud service ecosystems. GitLab Inc. occupies a position as the open-source-native archetype, representing the challenger model built on transparent codebase and community-driven feature development. IBM Corporation anchors the enterprise legacy bridge segment, exemplifying how established technology vendors reposition existing client relationships into modern pipeline contracts.
| Leading Market Players |
|---|
| Microsoft Corporation |
| IBM Corporation |
| Amazon Web Services |
| Google LLC |
| Atlassian Corporation |
| Broadcom Inc |
| GitLab Inc. |
| Oracle Corporation |
| Red Hat Inc. |
| Others |
Supply & Pricing Matrix
Bengaluru's technology campus concentration generates capacity elasticity that compresses SaaS subscription pricing for mid-market DevOps platforms across Asia-Pacific delivery centers. Indian IT services exporters leverage government cloud skilling programs to staff platform engineering teams at wage arbitrage, forcing global vendors to tier pricing geographically.
Pricing Analysis
North American enterprise buyers pay 40-60% premiums over Indian counterparts for identical ISO 27001-certified CI/CD platforms. Three-tier pricing structure across premium, standard, and economy levels segments by compliance depth, with SOC 2 Type II attestation commanding top tier. Cost compression in standard tiers intensifies as hyperscale cloud providers bundle CI/CD tooling with infrastructure commitments. Financial services firms in Germany exhibit lowest price sensitivity due to BaFin-mandated audit trail requirements.
Supply Chain Analysis
Tariff exposure between the United States and China dominates component sourcing for on-premise DevOps appliance vendors. Taiwan, South Korea, and the United States anchor semiconductor supply for pipeline infrastructure servers. Intel Xeon processors, Samsung NAND storage, and Broadcom networking silicon feed from concentrated foundry capacity. Single-source vulnerability in advanced node fabrication threatens delivery timelines for air-gapped government deployments. Distribution runs through hyperscale cloud marketplaces and direct enterprise sales teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as container orchestration standardization around Kubernetes penetrates Fortune 500 operational technology estates. Regulatory mandates for software supply chain attestation accelerate replacement of legacy toolchain assemblies.
For Market Incumbents: Harden compliance-embedded platform positioning against open-source-native challengers. Invest in SOC 2 Type II pre-certification for all new modules to compress six-to-twelve-month audit cycles. Acquire policy-as-code specialists to defend margin position as Kubernetes commoditizes core orchestration layers.
For New Entrants and Emerging Players: Build out EU sovereign cloud DevOps offerings targeting BaFin and ECB regulatory jurisdictions. The most penetrable white space sits in explainability-integrated CI/CD pipelines for automated decision systems under EU AI Act mandates. Lead with Kubernetes-native continuous delivery controllers that collapse CI/CD boundaries.
For Investors and Strategic Acquirers: Long-term, this sits as a compliance-layer consolidation play because ISO 27001 and SOC 2 certification requirements create durable moats around attested vendors. Target platform engineering specialists with existing financial services deployments. Watch for inflection when sovereign cloud procurement frameworks mature in Indian and South Korean government sectors.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies CI/CD, policy-as-code, and observability into single control planes for financial services. |
| Acquisition of Specialist Firm | Captures SBOM generation and software supply chain attestation capabilities under SEC cybersecurity rules. |
| Strategic Partnership | Bridges on-premise mainframe estates with cloud-native Kubernetes orchestration for phased modernization. |
| Product Launch | Introduces EU AI Act-compliant explainability checkpoints into automated decision pipelines for GDPR jurisdictions. |
| Geographic Expansion | Establishes sovereign pipeline infrastructure under RBI data localization guidelines for Indian banking. |
Research Methodology
The analysis maps continuous integration platforms, security and compliance layers, infrastructure-as-code tooling, and monitoring solutions, each validated through platform engineers, IT procurement officers, cloud architects, and integration specialists. Primary fieldwork combined structured interviews with secondary triangulation across SEC filings, hyperscaler capex disclosures, ISO certification databases, and government cloud skilling program records. Bottom-up deployment counts and top-down vendor revenue estimates converged through iterative reconciliation.
Assumptions held regulatory mandate timelines and Kubernetes standardization velocity fixed while varying enterprise cloud migration pace and sovereign cloud procurement intensity across the analysis window. Segmentation modeled deployment topology, solution architecture, organization size, vertical compliance intensity, and regional adoption pattern. CAGRs derived from S-curve penetration modeling against historical SaaS platform diffusion benchmarks, with inputs from hyperscale infrastructure spend trajectories and financial services technology budget surveys.
The forecast holds incumbent behavior within observed patterns; aggressive bundling moves by hyperscale cloud providers or accelerated EU AI Act enforcement would shift outcomes. Macroeconomic contraction in technology capital expenditure, regulatory delay in sovereign cloud mandates, or breakthrough standardization in open-source security tooling would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Office Software Market
Software & Services
Acoustic Simulation Software Market
Software & Services
Vacation Rental Software Market
Software & Services
Blogger Outreach Software Market
Software & Services
Lighting Control Software Market
Software & Services
AI Powered Software Testing Tool Market
Software & Services
UK Applicant Tracking System Market
Software & Services
Embedded Software Market
Software & Services
Sales Force Automation Software Market
Software & Services
Banking Team Collaboration Software Market
Software & Services
Construction Jobsite Management Software Market
Software & Services
Remote Desktop Software Market
Software & Services
Global Wedding Invitations Software Market
Software & Services
Enterprise Application Market
Software & Services
Africa Financial Services Software Market
Software & Services
Global Retail Inventory Management Software Market