
 High-Resolution 3D X-Ray Microscopy Market | 2026-2036
High-Resolution 3D X-Ray Microscopy Market Size, Share, and Industry Trends Forecast 2026-2036
High-Resolution 3D X-Ray Microscopy Market Outlook
Direct sales and specialized microscopy distributors is reshaping how high-resolution 3D X-ray systems reach end users, with fewer intermediaries handling installation and service contracts. Bruker Corporation leverages its established life sciences distribution footprint to sustain recurring revenue from academic customers. Carl Zeiss AG anchors its position through deep specialization in optical-to-X-ray hybrid workflows for semiconductor clients. Nikon Corporation competes aggressively in Asia-Pacific manufacturing hubs where industrial inspection standards are tightening.
High-resolution 3D X-ray microscopy employs X-ray computed tomography with sub-micron voxel resolution to reconstruct three-dimensional internal structures without destructive sample preparation, typically operating at accelerating voltages between 30 kV and 300 kV depending on material density and penetration requirements. The technique serves primarily non-destructive quality assurance, materials characterization, and biological specimen analysis where optical or electron microscopy cannot access buried features. Laboratory Systems dominate current procurement value given their flexibility across multiple research disciplines and end users, while Desktop Microscopes represent the fastest-expanding product category as manufacturing firms embed quality control closer to production lines. Phase Contrast technology leads in biological research applications where soft-tissue differentiation demands minimal radiation exposure, whereas Computed Tomography commands the largest installed base across industrial inspection workflows.
FDA 21 CFR Part 820 quality system regulations and ISO 13485 medical device standards shape product development cycles for healthcare-facing equipment, while REACH compliance in Europe constrains detector material sourcing and disposal protocols for manufacturers serving EU research laboratories. The EU AI Act's emerging requirements for automated image analysis software will likely extend certification burdens beyond hardware into embedded diagnostic algorithms. Stakeholders must monitor how regulatory divergence between FDA predicate device pathways and EU MDR conformity routes fragments product roadmaps and delays market entry for next-generation platforms.
Market Dynamics
Semiconductor packaging miniaturization is compressing inspection tolerances below optical microscopy limits, forcing fabs to adopt sub-micron X-ray systems for non-destructive failure analysis of 3D stacked architectures.
Growth Catalysts
- FDA 21 CFR Part 820:Medical device manufacturers face intensified imaging validation requirements, compelling healthcare facilities toward certified high-resolution platforms for implantable device quality assurance.
- Phase Contrast technology:Soft-tissue differentiation capabilities with minimal radiation exposure are accelerating biological specimen analysis workflows where electron microscopy risks sample damage.
- German materials science cluster:Fraunhofer institutes and Max Planck facilities anchor concentrated procurement volumes, creating demonstration effects that diffuse adoption patterns across European research networks.
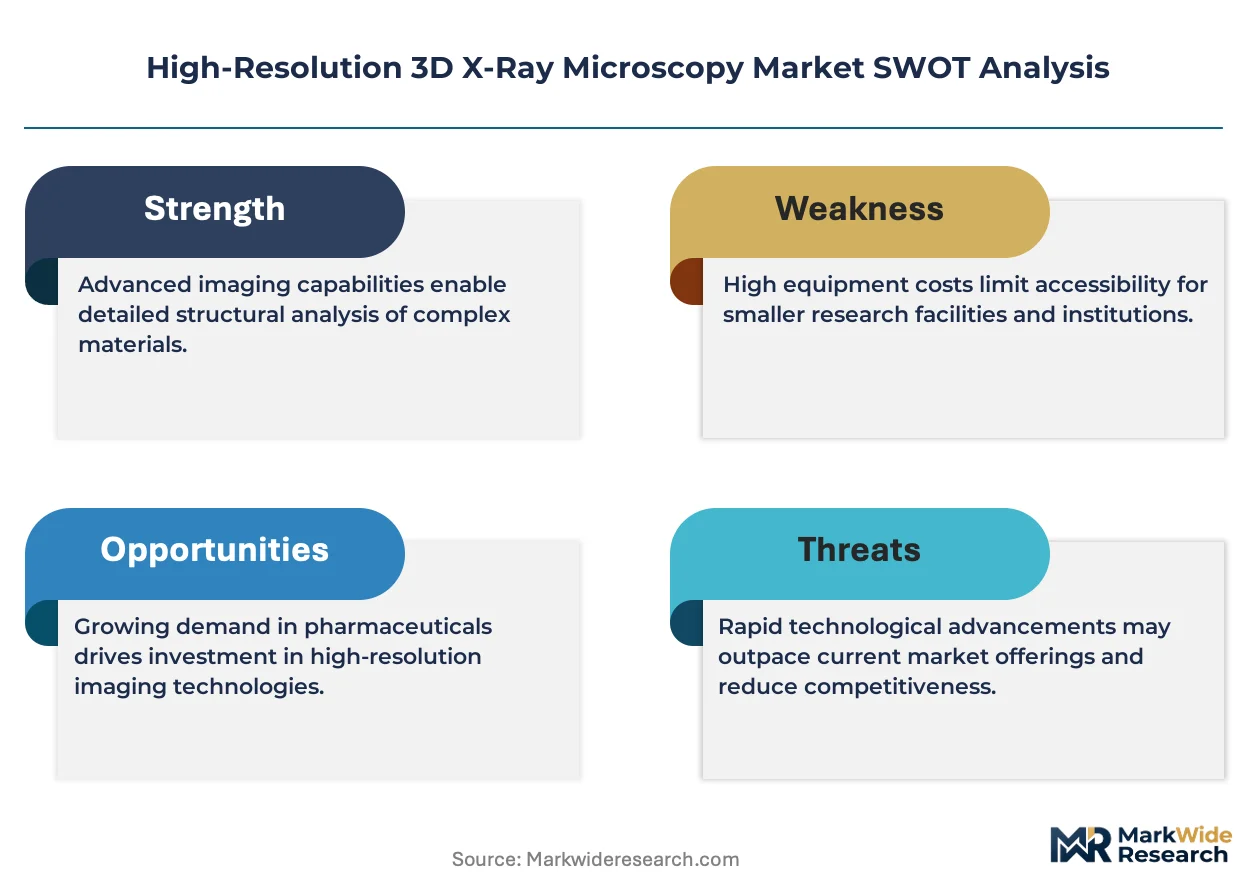
Market Restraints
- Detector material cost volatility:Scintillator crystal supply concentrates among limited specialty chemical suppliers, exposing system manufacturers to rare earth price swings that compress hardware margins.
- REACH compliance burden:European detector disposal protocols constrain material sourcing flexibility, forcing manufacturers to maintain parallel supply chains for EU and non-EU research laboratory customers.
- Electron microscopy substitution:Scanning electron microscopy maintains cost advantages for surface-level defect analysis, limiting X-ray penetration in routine quality control budgets.
Strategic Opportunities
- Desktop Microscope embedding:Manufacturing firms are relocating quality control closer to production lines, creating demand for compact systems that bypass centralized metrology lab bottlenecks.
- EU AI Act certification pathway:Automated image analysis software will require conformity assessment, extending vendor revenue streams from hardware into embedded diagnostic algorithm validation services.
- Optical-to-X-ray hybrid workflows:Convergence of correlative microscopy techniques enables seamless navigation between resolution regimes, opening integrated platform contracts with semiconductor failure analysis labs.
Industry Challenges
- Computational reconstruction expertise:Sparse availability of trained tomography algorithm specialists delays customer onboarding and extends installation-to-production timelines for complex industrial applications.
- ISO 13485 certification timelines:Medical device quality system documentation requirements extend product development cycles, compressing competitive windows against faster-moving industrial inspection segments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High-Resolution 3D X-Ray Microscopy Market |
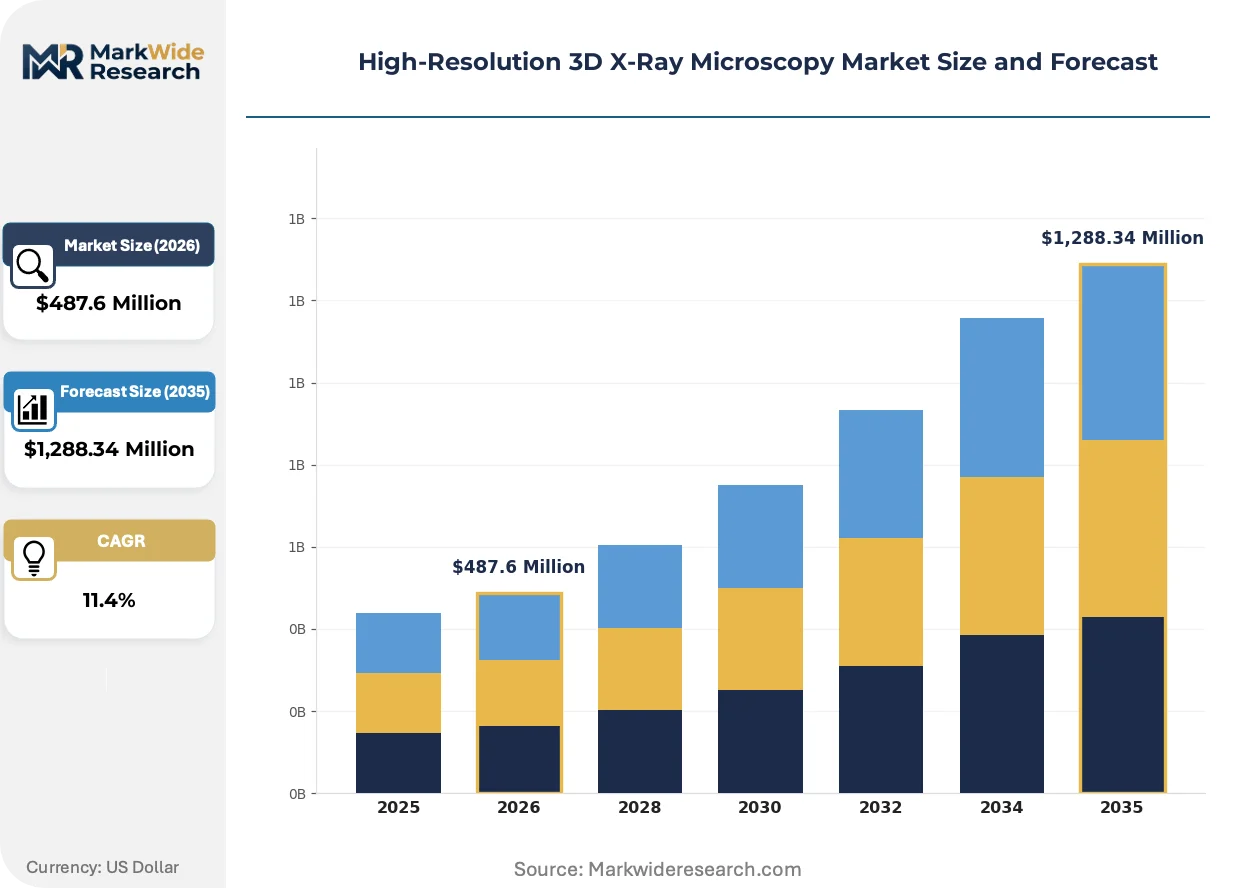
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,288.34 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Desktop Microscopes, Laboratory Systems, Portable Units, Advanced Imaging Systems Application: Material Science, Biological Research, Industrial Inspection, Semiconductor Analysis Technology: Phase Contrast, Differential Phase Contrast, Computed Tomography, Digital Holography End User: Academic Institutions, Research Laboratories, Manufacturing Firms, Healthcare Facilities |
| Companies Covered | TESCAN ORSAY HOLDING, JEOL Ltd., Carl Zeiss AG, Shimadzu Corporation, Rigaku Corporation, Bruker Corporation, Nikon Corporation, Scanco Medical AG, Thermo Fisher Scientific, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High-Resolution 3D X-Ray Microscopy Market Strategic Shifts
Artificial intelligence inference at the detector edge is compressing reconstruction times from hours to minutes, reshaping throughput economics for high-volume manufacturing inspection environments.
Phase-retrieval algorithms are digitizing raw X-ray intensity data into quantitative electron density maps without multiple-projection acquisition, eliminating mechanical rotation stages that constrain throughput in battery electrode inspection. Cell manufacturers in South Korea are deploying these systems for inline porosity mapping. The structural consequence is collapsing the cost-per-inspection metric that previously favored destructive cross-sectioning.
EU AI Act requirements for high-risk medical device software will mandate conformity assessment of automated defect classification algorithms before clinical deployment, extending vendor liability from hardware into embedded diagnostic logic. European notified bodies are developing specialized competencies for machine-learning-based image analysis validation. This regulatory expansion most directly affects laboratory system vendors serving hospital-based research pathology workflows.
Service contract unbundling is fragmenting traditional bundled maintenance agreements, with semiconductor fabs negotiating separate detector calibration subscriptions from core system warranties. Japanese foundries pioneered this disaggregation, pressuring vendors to price transparency across component lifecycle costs. The practice is diffusing through Taiwan and Singapore manufacturing hubs as capital expenditure scrutiny intensifies.
High-Resolution 3D X-Ray Microscopy Market Segmentation
High-resolution 3D X-ray microscopy serves divergent technical requirements across research and production environments, with product configurations, analytical methods, and institutional buyers each imposing distinct performance specifications and procurement patterns.
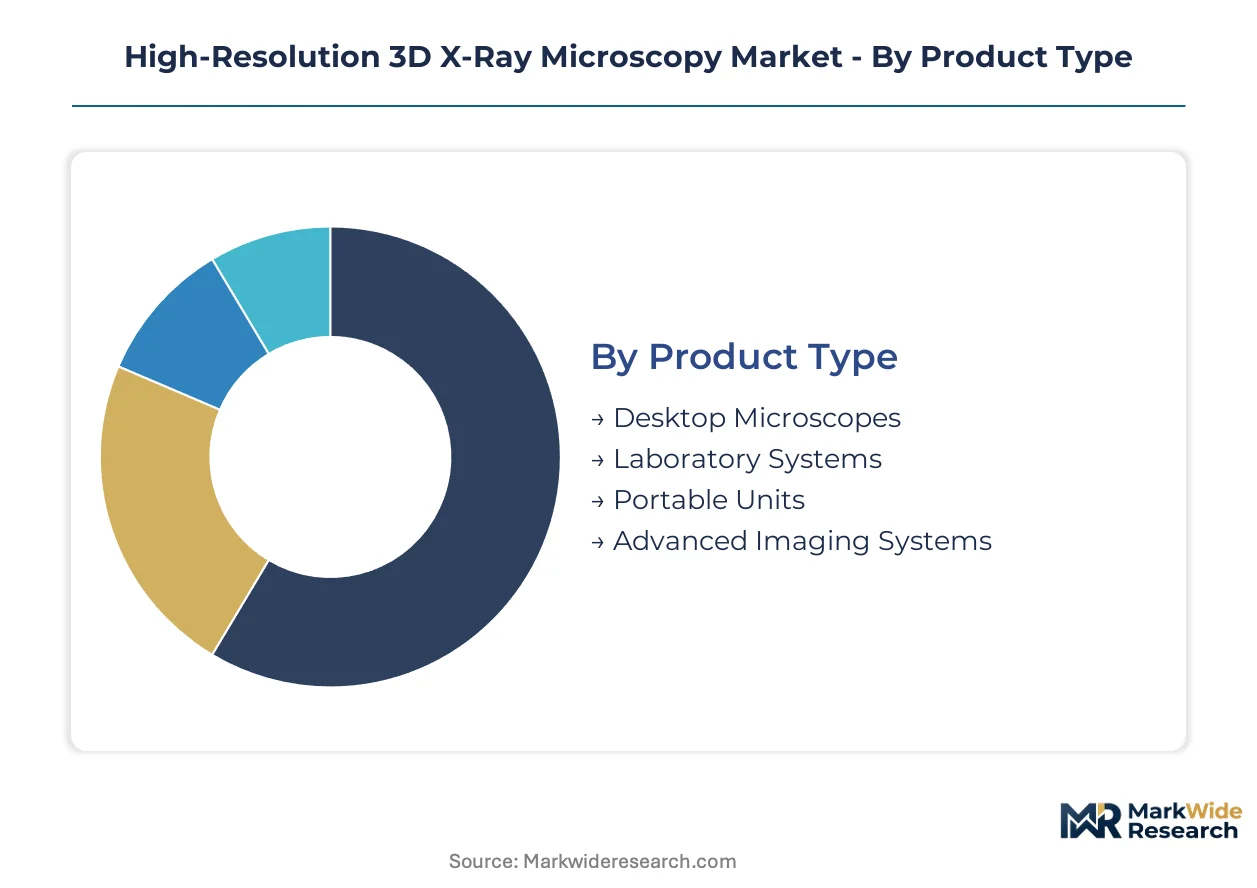
Product Type:
Equipment form factors span from benchtop units embedded on factory floors to multi-ton installations requiring dedicated radiation shielding and climate-controlled facilities.
- Laboratory Systems:Full-scale installations with 300 kV accelerating voltage capability and sub-100 nm voxel resolution serve multi-disciplinary research hubs requiring programmable scan protocols for heterogeneous sample types. Fraunhofer institutes in Germany anchor concentrated procurement for materials science workflows where sample throughput and resolution flexibility outweigh capital intensity.
- Desktop Microscopes:Compact 80-160 kV systems with automated sample handling occupy production-line footprints for inline quality control, with South Korean battery manufacturers deploying units for electrode porosity mapping. Manufacturing firms bypass centralized metrology bottlenecks by embedding inspection capacity adjacent to forming and coating operations.
- Portable Units:Battery-powered 50-90 kV systems with carbon-fiber enclosures enable field deployment for cultural heritage conservation and pipeline weld inspection.
- Advanced Imaging Systems:Synchrotron-coupled beamlines with cryogenic sample environments serve structural biology consortia requiring native-state protein complex visualization.
Established volume favors Laboratory Systems; emerging adoption favors Desktop Microscopes.
Application:
Resolution requirements and sample preparation constraints segment demand across scientific disciplines and industrial quality regimes.
- Semiconductor Analysis:Sub-micron voxel resolution enables non-destructive failure analysis of 3D stacked packaging architectures where optical microscopy fails. Taiwan foundries drive procurement volume for through-silicon via inspection and microbump void detection.
- Material Science:Quantitative phase retrieval maps internal strain distributions and crack propagation in additively manufactured alloys. Max Planck facilities in Germany demonstrate workflows that diffuse across European research networks.
- Industrial Inspection:High-throughput automated defect classification serves aerospace casting verification and automotive powertrain quality assurance.
- Biological Research:Soft-tissue phase contrast minimizes radiation damage to hydrated specimens, accelerating developmental biology and neuroscience specimen analysis where electron microscopy risks structural alteration.
Semiconductor Analysis commands premium pricing tiers; Biological Research exhibits steepest expansion trajectory as phase-retrieval algorithms mature.
Technology:
Contrast mechanisms differentiate capability for low-density biological structures versus high-attenuation industrial materials.
- Computed Tomography:Filtered back-projection and iterative reconstruction algorithms from multiple radiographic projections constitute the dominant installed base across industrial inspection workflows. Automotive and aerospace manufacturers standardize on CT for dimensional metrology and porosity quantification.
- Phase Contrast:Interferometric and propagation-based methods convert X-ray phase shifts into intensity modulation for soft-tissue differentiation at doses below absorption contrast thresholds. University medical centers deploy systems for preclinical imaging and ex vivo pathology.
- Differential Phase Contrast:Grating-based shearing interferometry enables quantitative phase mapping with conventional X-ray tubes, extending laboratory access to synchrotron-grade contrast.
- Digital Holography:Inline holographic recording with iterative phase retrieval reconstructs nanoscale morphology without mechanical rotation stages.
Computed Tomography retains the broadest installed base; Phase Contrast gains share fastest in clinical and preclinical translation.
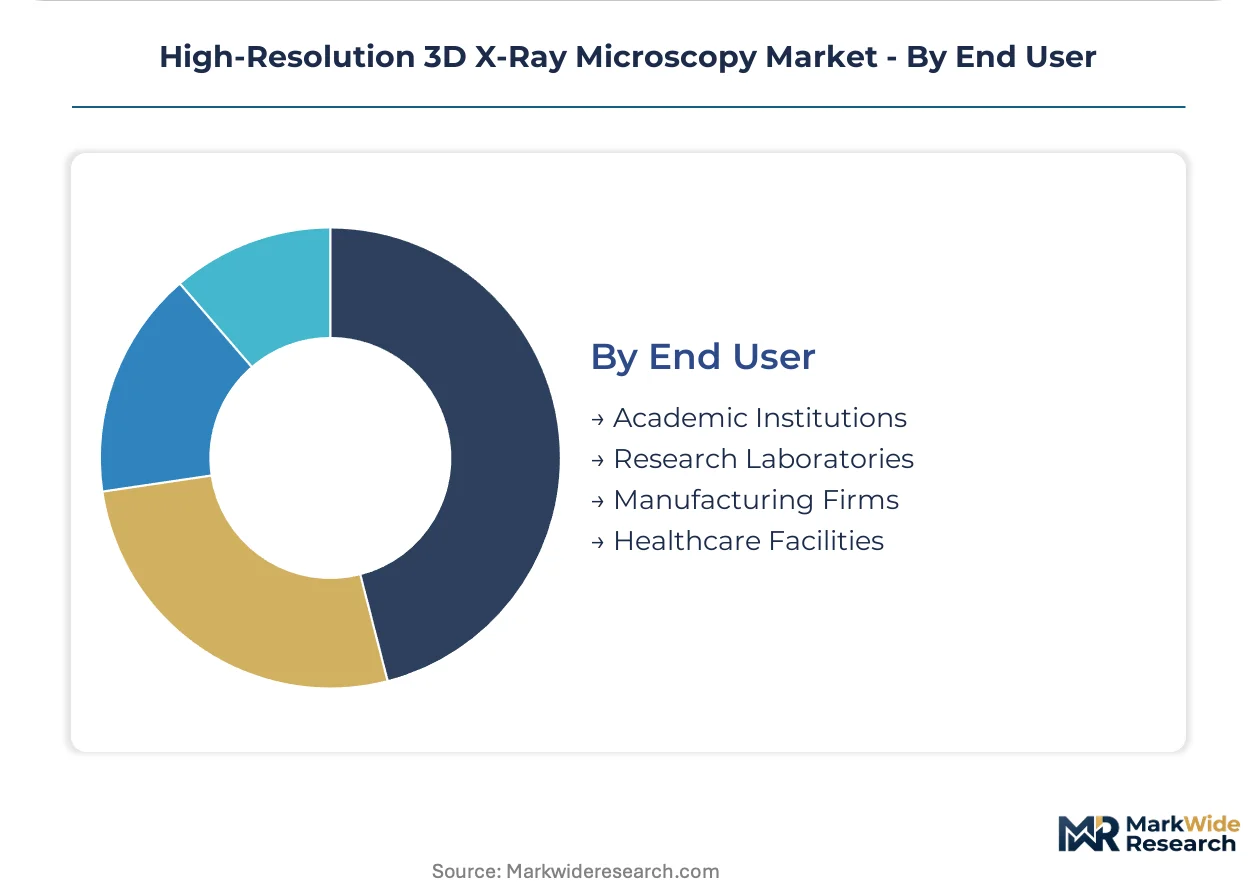
End User:
Procurement authority and funding mechanisms create distinct buying centers with divergent service contract expectations and upgrade cycles.
- Research Laboratories:National and corporate R&D facilities with multi-year capital budgets prioritize modularity and vendor service responsiveness. Helmholtz Association centers in Germany consolidate purchasing power for coordinated instrument networks.
- Manufacturing Firms:Semiconductor fabs and battery cell producers negotiate unbundled maintenance agreements with separate detector calibration subscriptions, a practice diffusing from Japanese foundries through Taiwan and Singapore.
- Academic Institutions:Shared instrumentation facilities balance disciplinary access demands against per-hour operational cost recovery models.
- Healthcare Facilities:Hospital-based pathology departments and medical device manufacturers face FDA 21 CFR Part 820 validation requirements for implantable device quality assurance.
Research Laboratories dominate absolute procurement value; Manufacturing Firms reshape contract structures toward component-level service transparency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Frankfurt-Milan rail freight corridor and Rhine-Danube waterway network underpin Central Europe's dominance in precision instrumentation logistics, while Pacific submarine cable systems anchor East Asian data-intensive microscopy workflows.
Germany
Fraunhofer institutes and Max Planck facilities drive concentrated procurement for materials science applications, with Helmholtz Association centers consolidating purchasing power across coordinated instrument networks. REACH compliance constrains detector material sourcing flexibility for EU-bound equipment. Munich and Stuttgart anchor manufacturing clusters where optical-to-X-ray hybrid workflows diffuse across European research networks.
United States
Semiconductor fabs in Arizona and Texas deploy sub-micron systems for 3D stacked packaging inspection as packaging miniaturization compresses tolerances below optical limits. FDA 21 CFR Part 820 quality system regulations shape product development cycles for healthcare-facing equipment. Boston and San Diego biotech corridors accelerate biological specimen analysis adoption where phase contrast minimizes radiation damage.
Japan
Foundries in the Kansai and Kyushu regions pioneered unbundled maintenance agreements with separate detector calibration subscriptions, a practice diffusing through Taiwan and Singapore manufacturing hubs. METI industrial standards govern precision equipment certification pathways. Nagoya automotive suppliers standardize on high-throughput CT for powertrain quality assurance.
South Korea
Battery cell manufacturers deploy compact desktop systems for inline electrode porosity mapping, bypassing centralized metrology bottlenecks. MFDS medical device regulations align with international quality system standards for clinical translation. Seoul-Gyeonggi semiconductor clusters drive premium-tier procurement for through-silicon via inspection.
China
Academic institutions in Beijing and Shanghai balance disciplinary access demands against per-hour operational cost recovery models for shared instrumentation facilities. NMPA medical device standards and GB technical regulations shape import substitution strategies. Yangtze River Delta manufacturing hubs tighten industrial inspection standards, intensifying competitive pressure from domestic equipment suppliers.
High-Resolution 3D X-Ray Microscopy Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in detector materials and precision motion stages. The vendor base organizes around three archetypes: diversified analytical instrumentation conglomerates with life sciences distribution footprints, optical heritage specialists leveraging hybrid microscopy workflows, and precision engineering houses with captive electron optics capabilities. Consolidation pressure intensifies as semiconductor fabs demand bundled service contracts spanning hardware, software, and algorithm validation. Geographic expansion into Asia-Pacific manufacturing hubs and backward integration into scintillator crystal supply represent dominant competitive vectors.
Among diversified analytical instrumentation conglomerates, Bruker Corporation and Thermo Fisher Scientific occupy positions sustained by recurring revenue from academic service contracts. Japanese precision engineering houses exemplified by JEOL Ltd., Rigaku Corporation, and Shimadzu Corporation anchor the electron optics heritage tier. Nikon Corporation represents optical-to-X-ray hybrid specialization targeting Asia-Pacific manufacturing quality control. Carl Zeiss AG sits within the premium-tier segment for semiconductor failure analysis workflows.
| Leading Market Players |
|---|
| TESCAN ORSAY HOLDING |
| JEOL Ltd. |
| Carl Zeiss AG |
| Shimadzu Corporation |
| Rigaku Corporation |
| Bruker Corporation |
| Nikon Corporation |
| Scanco Medical AG |
| Thermo Fisher Scientific |
| Others |
Value Chain & Pricing Dynamics
Munich-Stuttgart precision engineering clusters concentrate scintillator crystal production capacity, anchoring downstream pricing power for detector assemblies that constitute the dominant cost component in high-resolution 3D X-ray microscopy systems. German manufacturers leverage this geographic concentration to maintain margin structures even as semiconductor fabs intensify procurement negotiations for unbundled service contracts.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates synchrotron-coupled installations from laboratory systems and compact desktop units. Certification grade under FDA 21 CFR Part 820 and ISO 13485 medical device tiers commands substantial premiums over industrial inspection configurations. Pricing pressure stems from Japanese foundries pioneering detector calibration subscription unbundling, diffusing through Taiwan and Singapore manufacturing hubs. Academic institutions exhibit highest price sensitivity due to shared instrumentation facility cost-recovery constraints, while semiconductor fabs prioritize throughput metrics over capital expenditure minimization.
Supply Chain Analysis
Export control regimes restricting scintillator crystal and precision motion stage technologies limit material flows from Germany, Japan, and the United States to Chinese research laboratories and manufacturing facilities. System manufacturers draw from rare earth concentrate suppliers in China, specialized optical glass producers in Japan, and precision bearing fabricators in Germany. Single-source vulnerability concentrates in lutetium-based scintillator crystal supply, where two specialty chemical houses dominate global production. Distribution runs through direct sales organizations for semiconductor and battery manufacturing accounts, with academic and healthcare procurement flowing through specialized microscopy distributors handling installation and service contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue layers expand faster than hardware sales as semiconductor fabs negotiate unbundled detector calibration subscriptions and algorithm validation contracts separate from core system warranties. Software companion development for automated defect classification and EU AI Act conformity assessment services represent the fastest-expanding recurring revenue streams.
For Market Incumbents: Entrench position through backward integration into scintillator crystal supply and captive production of precision motion stages, neutralizing rare earth price volatility that compresses hardware margins. Deepen optical-to-X-ray hybrid workflow specialization to defend against electron microscopy substitution in surface-level defect analysis budgets. Prioritize EU AI Act certification pathway investment to extend liability coverage from hardware into embedded diagnostic algorithms before notified bodies finalize machine-learning validation competencies. For New Entrants and Emerging Players: Pursue white-space opportunity in portable unit deployment for cultural heritage conservation and pipeline weld inspection, segments where battery-powered 50-90 kV systems face limited incumbent competition. Target South Korean battery electrode porosity mapping applications where phase-retrieval algorithm deployment collapses cost-per-inspection metrics previously favoring destructive cross-sectioning. Lead with digital holography capability eliminating mechanical rotation stages to differentiate against established CT reconstruction workflows. For Investors and Strategic Acquirers: Long-term, this sits as a precision instrumentation consolidation play because semiconductor fabs increasingly demand bundled contracts spanning hardware, software, and algorithm validation that favor scaled platform integrators over component specialists. Acquisition target archetype: precision engineering houses with captive electron optics capabilities and established Asia-Pacific manufacturing hub presence. Signal to watch: diffusion of unbundled maintenance agreements from Japanese foundries through Taiwan and Singapore, indicating capital expenditure scrutiny intensity and service transparency expectations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Scintillator Supply | German and Japanese manufacturers secure captive lutetium crystal production against rare earth price volatility. |
| EU AI Act Algorithm Validation Services | European notified body partnerships extend vendor revenue streams into embedded diagnostic logic certification. |
| Desktop Microscope Production Line Embedding | South Korean battery manufacturers deploy compact systems adjacent to electrode forming operations. |
| Optical-to-X-ray Hybrid Workflow Development | Carl Zeiss and Nikon leverage correlative microscopy specialization for semiconductor failure analysis contracts. |
| Unbundled Service Contract Transparency | Japanese foundries negotiate separate detector calibration subscriptions, diffusing through Taiwan manufacturing hubs. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with semiconductor fab metrology directors, hospital pathology department heads, academic shared instrumentation facility managers, and microscopy distributor technical sales specialists; and secondary validation against SEC 10-K filings, EU MDR conformity assessment databases, Japanese METI industrial equipment certification records, and South Korean MFDS medical device registration data. Bottom-up triangulation across equipment procurement volumes and top-down reconciliation against end-user budget allocation patterns anchored segmentation-level estimates.
Forecast inputs incorporated accelerating voltage tier penetration, voxel resolution requirement trajectories by application, and regulatory certification burden evolution across the projection horizon. Segmentation dimensions modeled include product form factor, contrast mechanism technology, end-user institutional type, and geographic regulatory cluster. CAGRs derived from equipment replacement cycle analysis, research funding trajectory assessment, and manufacturing quality control automation adoption curves. Phase-retrieval algorithm maturation and AI inference at detector edge deployment timelines served as technology-specific forecast modifiers.
Sensitivities concentrate around scintillator crystal supply disruption, EU AI Act implementation timeline acceleration, and electron microscopy cost-performance improvement trajectories. Forecasts reflect assumptions regarding continued semiconductor packaging miniaturization and battery electrode inspection automation adoption. Material shifts in export control regime stringency or REACH compliance scope expansion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Global 3D Camera Market
Imaging
Chemiluminescence Imaging Market
Imaging
Uncooled Infrared Camera Market
Imaging
Sub-Micrometer Computed Tomography Market
Imaging
Middle East and Africa Image Sensors Market
Imaging
In Vivo Imaging Systems Market
Imaging
US Near Infrared Imaging Market
Imaging
Industrial Machine Vision Market
Imaging
Plenoptic Camera Market
Imaging
Asia Pacific Smartphone Camera Module Market
Imaging
Global Trail Camera Market
Imaging
Digital Camera Market
Imaging
Semiconductor Microscopes Market
Imaging
Computational Photography Market
Imaging
Industrial Computed Tomography Market
Imaging
Asia Pacific Industrial Computed Tomography Market