
 Virus-Induced Asthma Treatment Market | 2026-2036
Virus-Induced Asthma Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Virus-Induced Asthma Treatment Market Analysis
Biologics is restructuring product economics in virus-induced asthma care, displacing traditional small-molecule maintenance regimens with targeted anti-inflammatory proteins. GlaxoSmithKline leverages its respiratory franchise depth to sustain dominance in inhaled corticosteroid combinations. AstraZeneca anchors its position through biologic specialization in eosinophilic asthma phenotypes. Boehringer Ingelheim competes via device-therapy integration, controlling delivery format innovation across nebulizer and inhaler platforms.
Virus-induced asthma treatment encompasses pharmacological interventions designed to prevent or attenuate bronchoconstriction and airway inflammation triggered by viral respiratory infections, typically employing formulations with particle size distributions optimized for lower respiratory deposition and stability profiles suited to acute exacerbation settings. Its primary purpose centers on reducing hospitalization frequency and preventing progression to severe refractory disease in susceptible populations. Corticosteroids occupy the largest margin pool among product types, while leukotriene modifiers represent the fastest-growing category driven by pediatric prophylaxis protocols. Inhalers dominate delivery method volumes, though nebulizers retain structural importance in emergency room and home care settings where patient coordination limits breath-actuated device efficacy.
FDA accelerated approval pathways and EMA adaptive licensing frameworks shape product development timelines, compressing phase transition intervals for respiratory biologics while elevating post-market evidence requirements. The EPA's inhaler propellant regulations under Clean Air Act amendments are forcing formulation transitions from hydrofluoroalkane to dry powder and soft mist alternatives, altering device-therapy pairing strategies. Stakeholders must monitor how regulator convergence on real-world evidence standards reshapes competitive positioning between established pharmaceutical manufacturers and emerging biologic developers.
Market Dynamics
FDA accelerated approval pathways are compressing development timelines for respiratory biologics while EPA propellant regulations force wholesale reformulation of established inhaled therapies, creating simultaneous speed and compliance pressures.
Growth Catalysts
- Pediatric prophylaxis protocols:Specialist networks in the United States are expanding biologic therapy access for virus-susceptible children, driving leukotriene modifier volumes through structured care pathways.
- EMA adaptive licensing:European frameworks enable earlier market entry for eosinophil-targeting biologics, reducing phase transition intervals while maintaining safety surveillance.
- Emergency room biologic administration:Acute care settings are adopting rapid-onset monoclonal antibodies for post-viral exacerbation management, reshaping hospital pharmacy formularies.
Market Restraints
- Hydrofluoroalkane propellant phase-out:EPA Clean Air Act amendments are forcing costly transitions to dry powder and soft mist platforms, eroding margins on legacy inhaler portfolios.
- Biologic cold chain concentration:Temperature-controlled logistics for monoclonal antibodies concentrate supply vulnerability in third-party distribution networks across North America.
- Small-molecule substitution ceiling:Generic corticosteroid availability limits pricing power for maintenance therapy segments in Medicaid-dominated patient pools.
Strategic Opportunities
- Home nebulizer biologics:Device-therapy integration platforms enable subcutaneous-to-inhaled conversion for post-viral prophylaxis in United States home care settings.
- Real-world evidence mandates:FDA post-market surveillance requirements create data monetization pathways for registry-building specialists.
- Pediatric phenotype stratification:Eosinophil count testing expansion in German and French specialist clinics opens targeted therapy enrollment.
Industry Challenges
- Biologics manufacturing scale-up:Cell culture capacity constraints delay commercial launch timelines for post-approval respiratory monoclonals.
- Cross-platform device validation:Dry powder inhaler bioequivalence testing against hydrofluoroalkane references extends regulatory submission preparation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Virus-Induced Asthma Treatment Market |
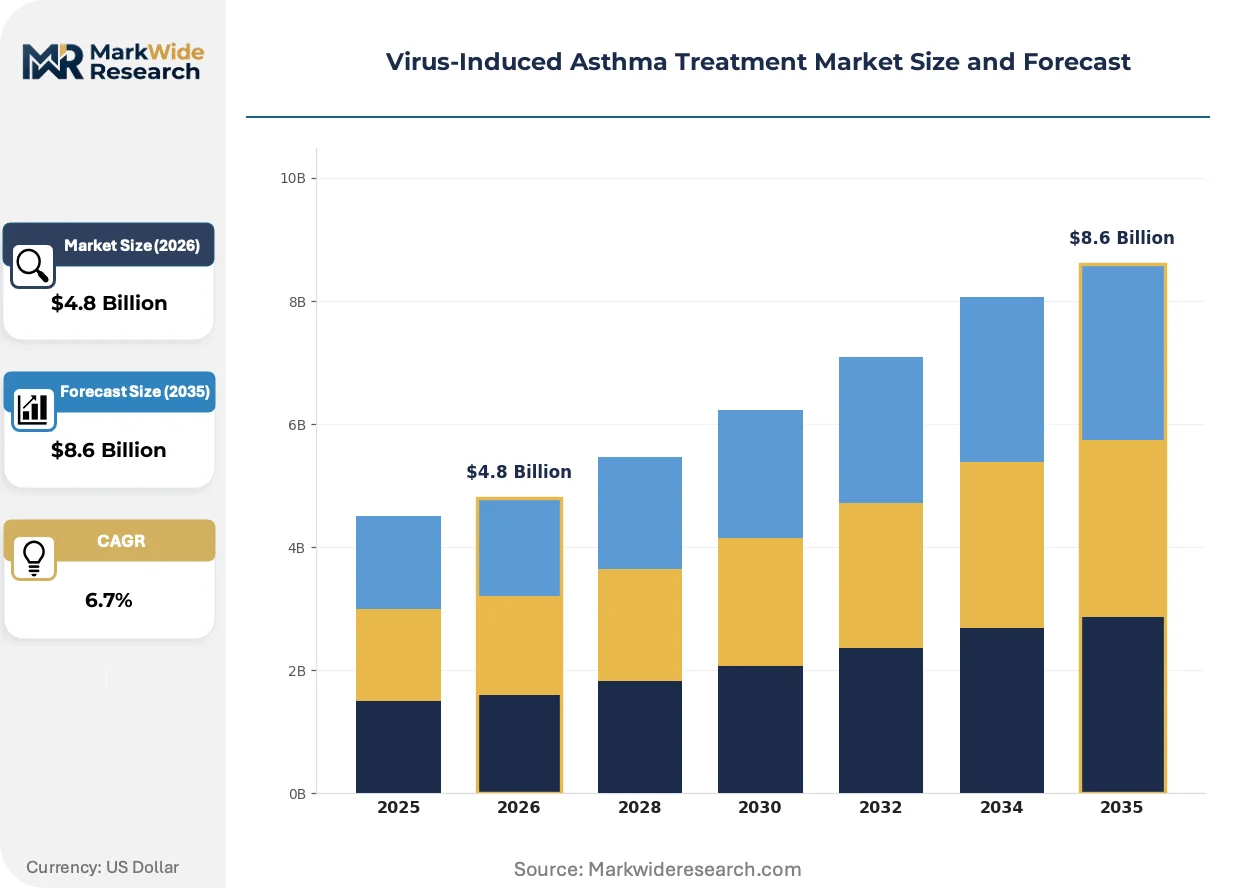
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bronchodilators, Corticosteroids, Antihistamines, Leukotriene Modifiers Delivery Method: Inhalers, Nebulizers, Oral Tablets, Injectables Patient Age Group: Pediatrics, Adults, Geriatrics, Adolescents Treatment Setting: Home Care, Outpatient Care, Emergency Room, Hospitals |
| Companies Covered | GlaxoSmithKline, AstraZeneca, Boehringer Ingelheim, Novartis, Sanofi, Teva Pharmaceutical Industries, Merck & Co., Chiesi Farmaceutici, Areteia Therapeutics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Virus-Induced Asthma Treatment Market Emerging Trajectories
Respiratory care is experiencing convergent pressures from biologic automation, environmental compliance mandates, and care setting decentralization that collectively redefine product development priorities.
Digital inhaler sensors paired with machine learning algorithms are automating adherence monitoring and exacerbation prediction for virus-triggered patients. United States pulmonology practices are deploying these connected devices at scale within value-based care contracts. The technology is automating clinical decision support, reducing specialist consultation frequency while capturing real-world efficacy data.
EPA enforcement of hydrofluoroalkane propellant restrictions under amended Clean Air Act provisions is mandating device platform transitions by 2028. Formulation scientists are reoptimizing particle size distributions for dry powder alternatives to match lung deposition profiles. United States manufacturers are responding by consolidating device-therapy development teams to accelerate platform substitution timelines.
Hospital-at-home programs are displacing traditional emergency department observation for moderate virus-induced exacerbations. United States health systems are contracting with specialty pharmacy infusion providers to administer biologics in residential settings. This channel expansion is most visible in Medicare Advantage populations where capitated payments incentivize admission avoidance.
Virus-Induced Asthma Treatment Market Segmentation
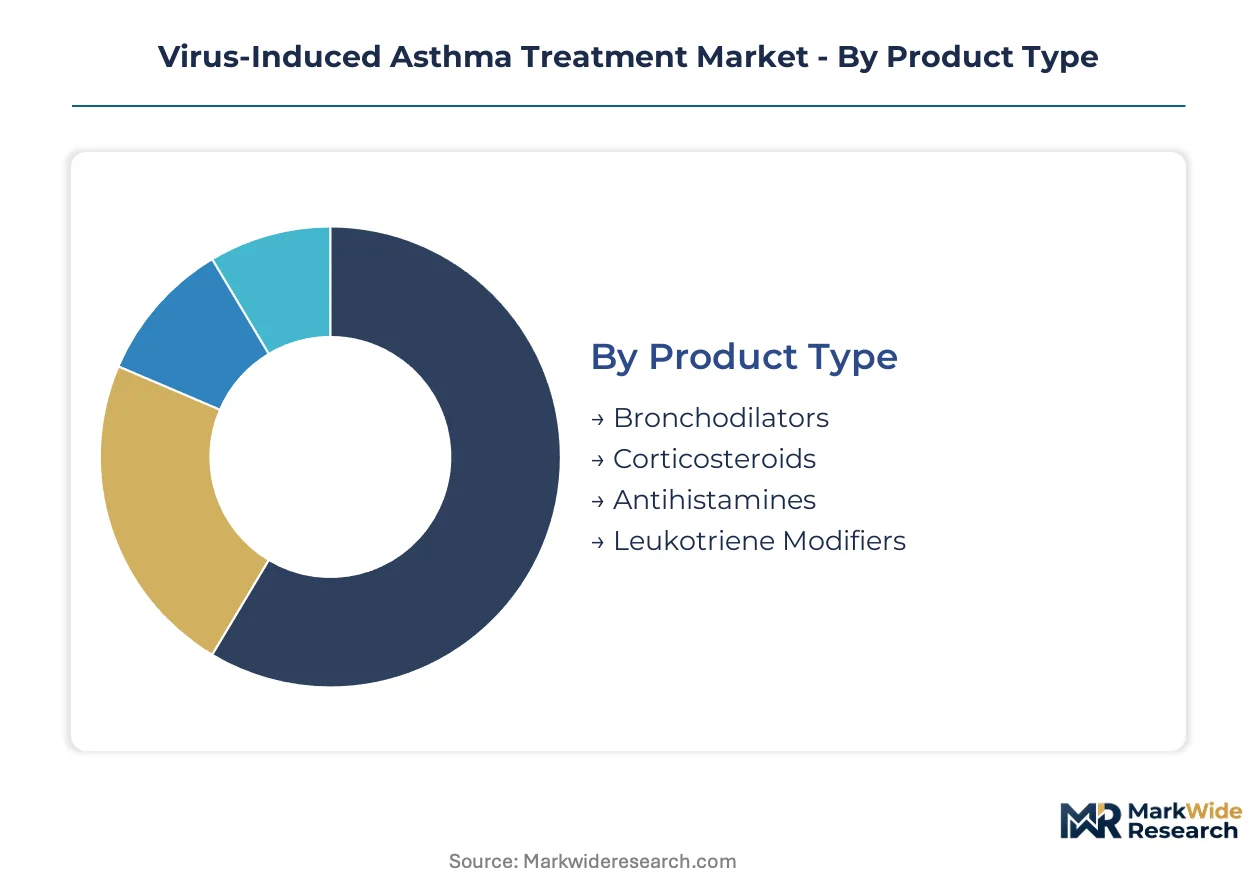
Segmentation in virus-induced asthma treatment reveals how capital allocation, reimbursement pathways, and clinical workflow constraints reshape competitive priorities across product formats and care settings. Manufacturers must align portfolio investments with the specific infrastructure requirements of each segment.
Product Type:
Capital intensity varies sharply across therapeutic modalities, with biologic manufacturing demanding cell culture facilities while small-molecule production leverages existing chemical synthesis infrastructure.
- Corticosteroids:Inhaled and oral formulations suppress airway inflammation through glucocorticoid receptor activation. United States hospital systems anchor demand through emergency department protocols for acute exacerbations. Generic competition limits pricing power in Medicaid populations.
- Leukotriene Modifiers:Montelukast and related compounds block cysteinyl leukotriene receptors to prevent bronchoconstriction. Pediatric prophylaxis protocols in United States specialist networks drive volume expansion. Structured care pathways accelerate enrollment for virus-susceptible children.
- Bronchodilators:Beta-agonist formulations provide rapid symptomatic relief through smooth muscle relaxation. Short-acting variants dominate rescue therapy.
- Antihistamines:H1-receptor antagonists address allergic components in mixed-trigger asthma phenotypes. Second-generation agents predominate in maintenance regimens.
Corticosteroids absorb the bulk of installed manufacturing capacity; leukotriene modifiers are expanding most quickly.
Delivery Method:
Device platform selection determines regulatory pathway complexity, with breath-actuated systems requiring extensive human factors validation compared to passive delivery formats.
- Inhalers:Metered-dose and dry powder devices optimize particle size distribution for lower respiratory deposition. EPA hydrofluoroalkane phase-out mandates are forcing wholesale platform transitions to dry powder alternatives by 2028. United States manufacturers are consolidating device-therapy development teams to accelerate substitution timelines.
- Nebulizers:Jet and mesh systems convert liquid formulations to respirable aerosols for patients with limited breath coordination. Home care settings and emergency departments retain structural demand where patient dexterity constrains inhaler efficacy. Medicare Advantage capitated payments are expanding hospital-at-home biologic administration through specialty pharmacy networks.
- Oral Tablets:Systemic delivery bypasses pulmonary deposition variability for maintenance therapy. Pediatric compliance challenges favor liquid formulations.
- Injectables:Subcutaneous and intravenous monoclonal antibodies target specific inflammatory pathways. Cold chain requirements concentrate supply vulnerability in third-party distribution networks.
Inhalers command the largest volume footprint; nebulizers are gaining share fastest through home care channel expansion.
Patient Age Group:
Developmental physiology and regulatory requirements fragment clinical trial design, with pediatric studies demanding age-stratified pharmacokinetic validation.
- Pediatrics:Children under twelve exhibit heightened viral susceptibility and airway hyperresponsiveness. United States pediatric respiratory clinics are expanding biologic therapy access through structured phenotype assessment protocols.
- Adolescents:Transition-age patients require adherence support as self-management responsibility shifts from caregivers. Digital inhaler sensors paired with machine learning algorithms are automating monitoring for this demographic.
- Adults:Working-age populations balance symptom control with cognitive and performance side effects of systemic therapy.
- Geriatrics:Comorbidity burden and polypharmacy complicate treatment selection in Medicare-dominated patient pools. Inhaler technique degradation drives nebulizer preference.
Adults represent the largest addressable population; pediatrics is climbing the fastest on biologic protocol expansion.
Treatment Setting:
Site-of-care economics determine reimbursement rates and product form selection, with facility fees and professional component billing creating margin dispersion across channels.
- Emergency Room:Acute care settings deploy rapid-onset bronchodilators and systemic corticosteroids for severe exacerbations. United States health systems are adopting monoclonal antibodies for post-viral management, reshaping hospital pharmacy formularies.
- Home Care:Residential settings enable chronic disease management through nebulizer and digital adherence platforms. Hospital-at-home programs are displacing traditional emergency department observation for moderate virus-induced exacerbations.
- Outpatient Care:Specialist pulmonology and allergy practices coordinate long-term maintenance therapy. Value-based care contracts are driving connected device deployment at scale.
- Hospitals:Inpatient units manage refractory cases requiring continuous monitoring and escalation to mechanical ventilation.
Outpatient care captures the majority of clinical encounters; home care is expanding most rapidly on hospital-at-home program growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialist care networks and reimbursement infrastructure concentrate demand in the United States, while European biologic adoption accelerates through adaptive licensing frameworks. Emerging markets present fragmented access patterns shaped by public procurement constraints.
United States
Pediatric respiratory clinics and Medicare Advantage capitated payments drive biologic therapy volumes. FDA accelerated approval pathways compress development timelines for respiratory monoclonals. The Greater Boston and Research Triangle Park clusters anchor clinical trial operations and post-market surveillance infrastructure.
Germany
Eosinophil count testing expansion in specialist clinics opens targeted therapy enrollment for pediatric phenotypes. EMA adaptive licensing frameworks enable earlier market entry while maintaining safety surveillance. The Munich and Heidelberg medical research corridors concentrate biologics manufacturing and respiratory clinical development.
United Kingdom
NHS specialist commissioning frameworks shape biologic access through structured care pathways for virus-susceptible populations. NICE technology appraisals determine reimbursement thresholds for novel respiratory interventions. The London and Cambridge life sciences clusters host digital inhaler sensor development and real-world evidence platform integration.
Japan
PMDA consultation pathways for respiratory biologics align with global development timelines through harmonized ICH guidelines. METI industrial policy supports domestic inhaler device manufacturing capacity. The Kanto region around Tokyo concentrates pharmaceutical distribution networks and hospital pharmacy formulary decision-making.
India
CDSCO regulatory harmonization efforts accelerate biosimilar entry for respiratory monoclonals in private hospital chains. Price control mechanisms under the National List of Essential Medicines constrain premium therapy access in public procurement channels. The Hyderabad and Ahmedabad pharmaceutical manufacturing belts supply active pharmaceutical ingredients for corticosteroid and leukotriene modifier formulations.
Virus-Induced Asthma Treatment Market Vendor Landscape
Strategic partnerships dominate the current landscape as established respiratory franchises seek biologic capabilities through external innovation channels. The market structure concentrates around three archetypes: integrated pharmaceutical conglomerates with device-therapy platforms, biologic specialists with phenotype-targeting pipelines, and generic manufacturers capturing maintenance therapy commoditization. Portfolio diversification and geographic expansion constitute the primary competitive vectors, with players rebalancing between small-molecule defense and biologic offense.
Within the integrated pharmaceutical tier, GlaxoSmithKline and AstraZeneca occupy positions exemplifying contrasting strategic emphases. GlaxoSmithKline represents the respiratory franchise depth archetype, while AstraZeneca anchors the biologic specialization vector in eosinophilic phenotypes. Boehringer Ingelheim sits within the device-therapy integration category, controlling delivery format innovation across nebulizer and inhaler platforms.
| Leading Market Players |
|---|
| GlaxoSmithKline |
| AstraZeneca |
| Boehringer Ingelheim |
| Novartis |
| Sanofi |
| Teva Pharmaceutical Industries |
| Merck & Co. |
| Chiesi Farmaceutici |
| Areteia Therapeutics |
| Others |
Supply Flow & Price Mechanics
Medicaid formulary restrictions in the United States are compressing reimbursement rates for maintenance corticosteroids, forcing manufacturers to absorb cost increases from EPA-mandated propellant transitions while preserving margin through dry powder platform consolidation.
Pricing Analysis
Volume concentrates in generic corticosteroid inhalers where Medicaid pricing caps limit margin expansion, while biologic monoclonals command premium positioning through specialist channel exclusivity and prior-authorization barriers. Price differentiation hinges on FDA approval pathway tier and pediatric indication breadth, with accelerated approval products sustaining higher net pricing through limited competition. Pricing pressure stems from generic leukotriene modifier entry in United States retail pharmacy channels. Medicaid-dominated patient pools exhibit highest price sensitivity; Medicare Advantage and commercial specialty tiers show lowest.
Supply Chain Analysis
Direct-to-specialty-pharmacy channels handle biologic monoclonal distribution, bypassing wholesale consolidation to preserve cold chain integrity. Active pharmaceutical ingredient production concentrates in India, China, and the United States, with corticosteroid synthesis anchored in Gujarat and Zhejiang manufacturing belts. Finished biologic production rests on mammalian cell culture capacity in Massachusetts, North Carolina, and Bavaria. Single-source vulnerability characterizes nebulizer device component supply from Taiwanese electronics manufacturers. Distribution runs through third-party logistics networks with temperature-validated warehousing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around biologic capabilities as EPA propellant mandates and cold chain infrastructure requirements force subscale inhaler manufacturers toward exit or acquisition.
For Market Incumbents: To counter generic corticosteroid commoditization in Medicaid channels, GlaxoSmithKline and AstraZeneca should deepen backward integration into dry powder inhaler device manufacturing and secure captive cell culture capacity for respiratory monoclonal expansion. Prioritize United States-based biologics manufacturing to reduce third-party logistics concentration risk. For New Entrants and Emerging Players: FDA accelerated approval pathways in the United States open a window for phenotype-targeting biologics in eosinophil-stratified pediatric populations underserved by current standard-of-care. Target German and French specialist clinics where EMA adaptive licensing compresses phase transition timelines. Pursue hospital-at-home infusion partnerships as the primary go-to-market angle for post-viral prophylaxis indications. For Investors and Strategic Acquirers: The window for entry favors device-therapy integration platforms with nebulizer-to-inhaler format flexibility and established specialty pharmacy relationships. Long-term viability centers on regulatory navigation capabilities across FDA and EMA parallel pathways. Monitor CDSCO biosimilar harmonization progress as the inflection signal for Indian market premiumization potential.| Strategic Initiative | Industry Significance |
|---|---|
| Biologics Manufacturing Scale-Up | Cell culture capacity additions in Massachusetts and North Carolina reduce monoclonal supply vulnerability. |
| Dry Powder Inhaler Platform Transition | Device-therapy consolidation accelerates EPA hydrofluoroalkane compliance timelines for United States portfolios. |
| Hospital-at-Home Partnership | Medicare Advantage capitated contracts expand biologic administration outside traditional emergency department settings. |
| Pediatric Phenotype Stratification | Eosinophil testing protocols in German specialist clinics open targeted therapy enrollment for virus-susceptible children. |
| Real-World Evidence Registry Building | FDA post-market surveillance mandates create data monetization pathways for connected inhaler sensor platforms. |
Methodological Framework
Document review covered FDA accelerated approval filings, EMA adaptive licensing decisions, EPA Clean Air Act amendment dockets, and ClinicalTrials.gov respiratory biologic protocols, complemented by interviews with drug development executives at established respiratory franchises, regulatory affairs leads navigating parallel FDA-EMA submissions, hospital formulary directors managing biologic prior authorization, and specialty pharmacy procurement managers contracting for hospital-at-home infusion services. Secondary validation drew from CMS Medicare Part B reimbursement data, United States hospital procurement databases, and European formulary access trackers. Bottom-up patient flow modeling and top-down pharmaceutical revenue triangulation anchored market size estimation.
Segment-level outputs across product type, delivery method, patient age group, and treatment setting were generated through multi-dimensional demand decomposition over the projection horizon. CAGRs were derived from fitted growth curves incorporating biologic adoption velocity, generic substitution rates, and regulatory pathway acceleration effects. Forecast inputs included pediatric respiratory clinic expansion rates in the United States, EMA adaptive licensing throughput timelines, and EPA hydrofluoroalkane phase-out enforcement schedules.
Caveats apply where FDA post-market surveillance requirement changes, EMA benefit-risk recalibrations, or EPA enforcement delays could materially shift the outlook. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Respiratory Therapy
Interventional Pulmonology Market
Respiratory Therapy
Asia-Pacific Topical Oxygen Therapy Market
Respiratory Therapy
Respiratory Disorders Treatment Market
Respiratory Therapy
Respiratory Inhaler Market
Respiratory Therapy
Pneumoconiosis Treatment Market
Respiratory Therapy
Human Respiratory Syncytial Virus (RSV) Treatment Market
Respiratory Therapy
Cough Systems Market
Respiratory Therapy
Brazil Therapeutic Respiratory Devices Market
Respiratory Therapy
Pediatric Respiratory Disease Treatment Market
Respiratory Therapy
Global Pneumonia Therapeutics Market
Respiratory Therapy
Healthcare Powered Air Purifying Respirator Market
Respiratory Therapy
Chronic Respiratory Diseases Treatment Market
Respiratory Therapy
Viral Pneumonia Treatment Market
Respiratory Therapy
Global Bronchitis Treatment Market
Respiratory Therapy
Idiopathic Pulmonary Fibrosis Management Market
Respiratory Therapy
Respiratory Antiviral Treatment Market