
 Chronic Respiratory Diseases Treatment Market | 2026-2036
Chronic Respiratory Diseases Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Chronic Respiratory Diseases Treatment Market Outlook
Biologic-grade inhaled therapies is bifurcating the competitive landscape into precision-molecule developers and legacy formulation houses. AstraZeneca leverages its respiratory biologics pipeline to sustain premium positioning in severe asthma and COPD segments. Boehringer Ingelheim anchors European market access through deep primary care relationships and nebulizer-compatible portfolios. GlaxoSmithKline competes via fixed-dose combination dominance across LAMA/LABA and ICS/LABA categories.
Chronic respiratory diseases treatment encompasses pharmaceutical and device-based interventions targeting persistent airway obstruction, inflammation, and remodeling, with inhaled corticosteroids typically formulated at 80-500 microgram doses for localized pulmonary action and systemic minimization. The primary purpose is to reduce exacerbation frequency, preserve lung function, and maintain patient mobility across progressive conditions. Combination therapy leads product type revenue pools due to adherence benefits and payer preference for simplified regimens, while inhalation delivery commands structural priority given its bioavailability advantages and the EU F-Gas Regulation's phase-down pressures on metered-dose propellants. Homecare end users represent the fastest-growing channel as remote monitoring technologies and reimbursement shifts enable ambulatory management of moderate disease.
The FDA's Breakthrough Therapy designation and the EMA's PRIME scheme accelerate development timelines for novel biologics targeting IL-5, IL-13, and TSLP pathways in eosinophilic asthma. The EU MDR and FDA's updated inhaler bioequivalence guidance raise barriers for generic entrants, concentrating margin pools among established developers with legacy clinical datasets. Stakeholders must monitor how the EPA's hydrofluoroalkane phase-down timelines and emerging dry-powder platforms reshape device supply chains and formulation partnerships.
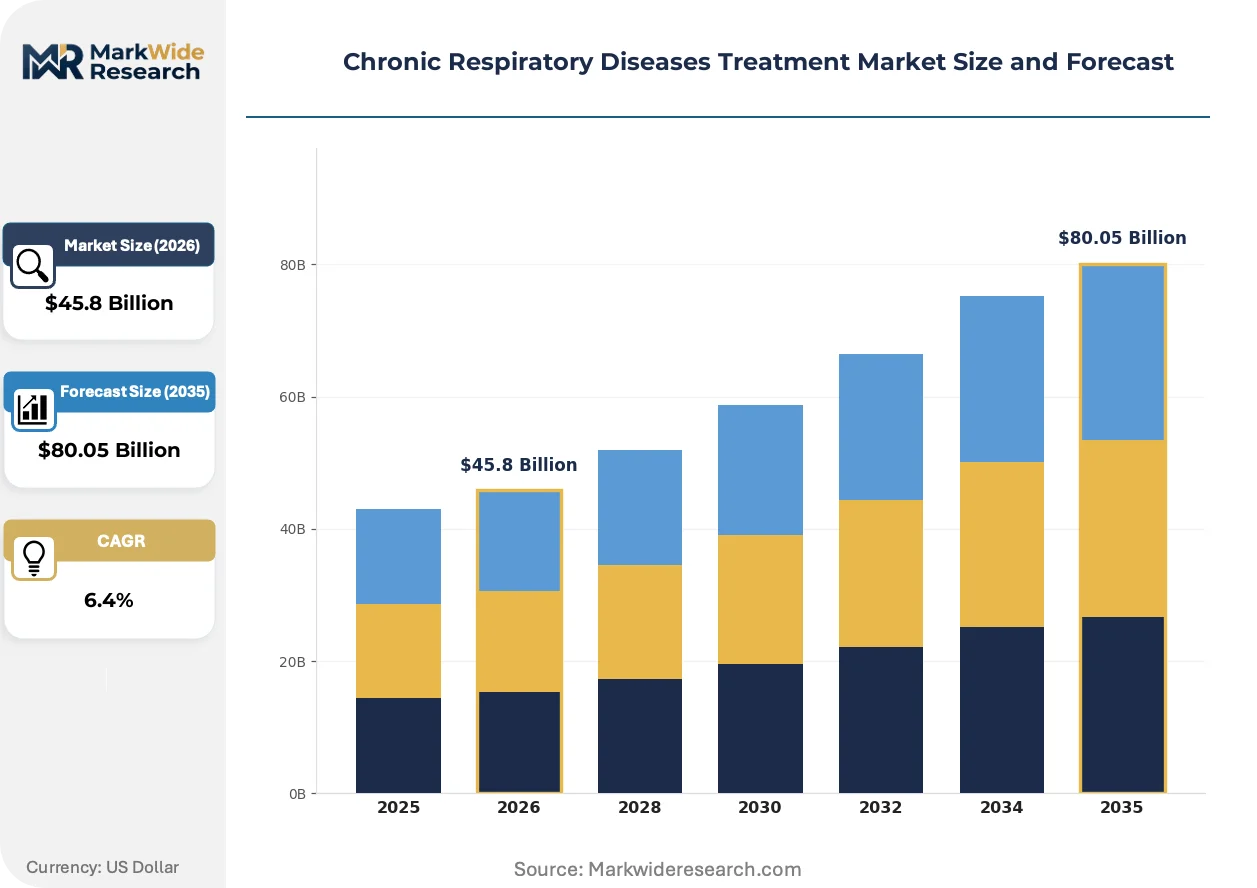
Market Dynamics
The EU F-Gas Regulation's hydrofluoroalkane phase-down is forcing wholesale device platform transitions, concentrating investment toward dry-powder inhaler architectures and reshaping formulation partnerships across the value chain.
Growth Catalysts
- Aging Demographics:Population cohorts over 65 in Germany, Japan, and the United States sustain elevated treatment volumes for COPD and severe asthma, expanding the addressable patient pool for maintenance therapies.
- EMA PRIME Scheme:Accelerated assessment pathways for biologics targeting IL-5 and TSLP pathways compress development timelines, enabling earlier commercialization of precision therapies for eosinophilic phenotypes.
- Remote Monitoring Integration:Bluetooth-enabled inhalers and connected spirometry devices are embedding into pulmonology workflows, improving adherence tracking and enabling proactive exacerbation management in homecare settings.
Market Restraints
- API Supply Concentration:Active pharmaceutical ingredient production for inhaled corticosteroids concentrates among Indian and Chinese contract manufacturers, creating vulnerability to geopolitical trade friction and quality enforcement actions.
- MDR Clinical Evidence Burden:The EU MDR's tightened requirements for legacy device recertification demand extensive clinical datasets, extending timelines and raising capital requirements for inhaler platform renewals.
- Generic Bioequivalence Barriers:FDA guidance on in vitro bioequivalence for complex generics requires specialized imaging and pharmacokinetic studies, limiting substitutability and preserving originator pricing power.
Strategic Opportunities
- Japan's Geriatric Infrastructure:METI-supported digital health integration and PMDA's streamlined biologics pathway create favorable conditions for connected inhaler launches targeting the world's oldest population.
- Pediatric Formulation Gaps:Underdeveloped nebulizer-compatible biologic options for severe asthma in patients under 12 represent an underserved segment with limited competitive entrants.
- Carbon-Neutral Propellant Platforms:Next-generation hydrofluoroolefin and propellant-free dry-powder systems align with EU Green Deal procurement criteria, opening preferential access channels for sustainability-certified suppliers.
Industry Challenges
- Inhaler Technique Standardization:Variability in patient coordination with pressurized metered-dose devices drives suboptimal lung deposition, requiring costly training infrastructure and adherence support programs.
- Legacy Device Integration:Hospital pharmacy information systems and electronic health record platforms fragment across vendor ecosystems, complicating connected device deployment and data interoperability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chronic Respiratory Diseases Treatment Market |
| Market Size in 2026 | $45.8 Billion |
| Market Size in 2035 | $80.05 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bronchodilators, Corticosteroids, Combination Therapy, Mucolytics Delivery Mode: Inhalation, Oral, Injectable, Nebulization Therapy Area: Asthma, COPD, Pulmonary Hypertension, Interstitial Lung Disease End User: Hospitals, Clinics, Homecare, Pharmacies |
| Companies Covered | GlaxoSmithKline, AstraZeneca, Boehringer Ingelheim, Novartis, Teva Pharmaceutical Industries, Sanofi, Roche, Merck & Co., Chiesi Farmaceutici, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chronic Respiratory Diseases Treatment Market Strategic Shifts
Device architecture and delivery mechanisms are undergoing fundamental redesign as environmental regulations and precision medicine requirements converge, compressing legacy platform lifecycles and opening new competitive vectors.
Smart inhaler technology is miniaturizing sensor arrays and wireless connectivity into palm-sized form factors without compromising aerosol performance. Pulmonology clinics and accountable care organizations are piloting these devices for remote patient monitoring, capturing real-world adherence data that pharmaceutical sponsors leverage for outcomes-based contracting with payers.
The EPA's hydrofluoroalkane phase-down timeline and the EU F-Gas Regulation's quota reductions are synchronizing to accelerate propellant transition roadmaps. Device manufacturers face compressed redesign cycles to validate hydrofluoroolefin alternatives or abandon pressurized systems entirely, with dry-powder platforms capturing structural priority in European tender processes.
Homecare channels are displacing hospital-based initiation for stable moderate disease, enabled by reimbursement codes that cover remote therapeutic monitoring and telehealth follow-up. Germany's DiGA fast-track and the United States' CMS remote patient monitoring billing categories are accelerating this behavioral shift, with pulmonology practices restructuring around ambulatory care models.
Chronic Respiratory Diseases Treatment Market Segmentation
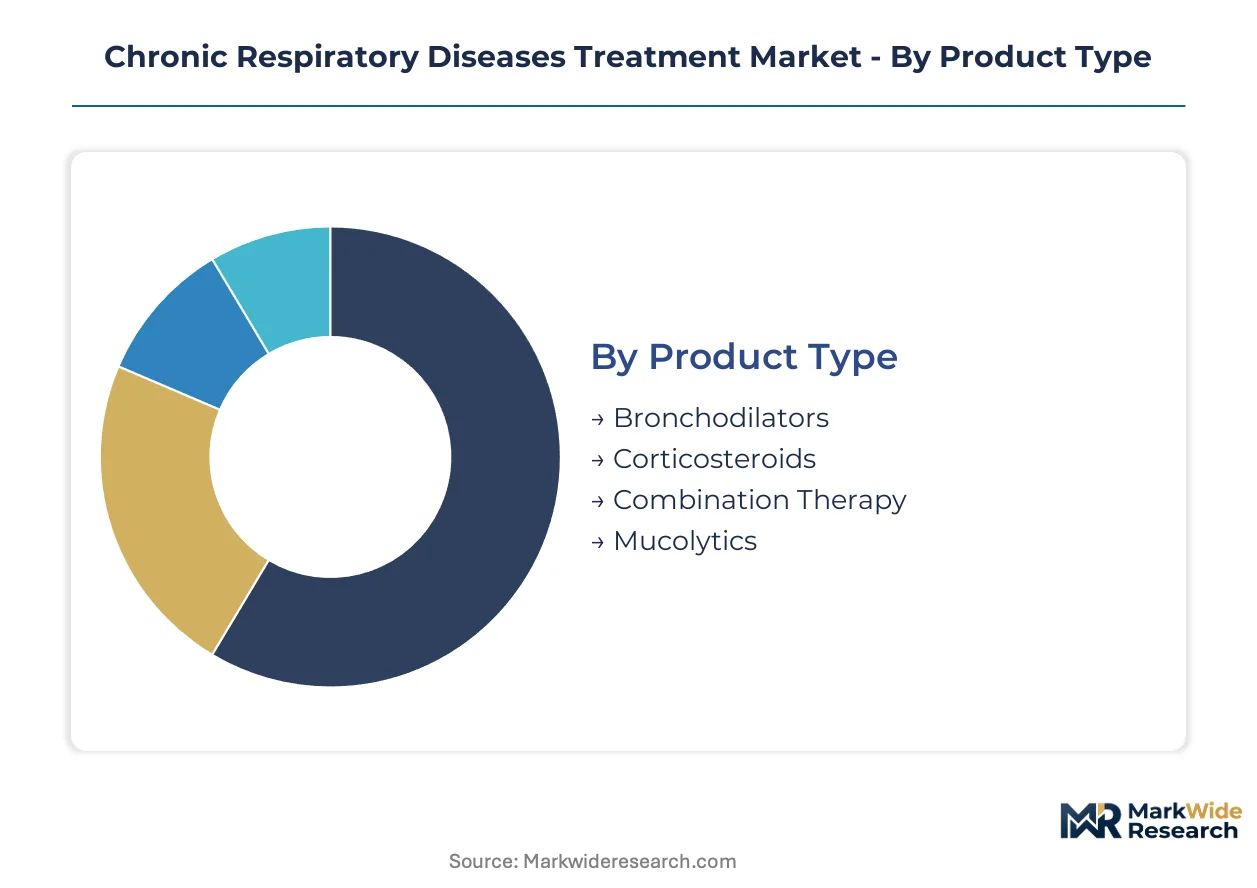
Regulatory differentiation across device platforms and therapy modalities creates distinct margin pools and competitive barriers. Segmentation reveals how formulation complexity, delivery technology, and care setting economics reshape strategic positioning for chronic respiratory interventions.
Product Type:
FDA bioequivalence guidance and EU MDR clinical evidence requirements stratify segments by development capital intensity and generic substitutability risk.
- Combination Therapy:Fixed-dose LAMA/LABA and ICS/LABA formulations integrate multiple mechanisms into single inhaler architectures. Hospital formularies in the United States and Germany prioritize these regimens for adherence benefits, with payer contracts favoring simplified maintenance protocols that reduce exacerbation-related admissions.
- Corticosteroids:Inhaled formulations at 80-500 microgram doses deliver localized pulmonary anti-inflammatory action with systemic minimization. Manufacturing concentrates among Indian and Chinese API suppliers, exposing supply chains to quality enforcement actions and trade friction that originators exploit for pricing defense.
- Bronchodilators:Short-acting beta-agonists and anticholinergics provide acute symptom relief through rapid airway smooth muscle relaxation.
- Mucolytics:Agents reducing sputum viscosity target specific phenotypes with excessive mucus production, particularly in bronchiectasis overlap syndromes.
Established volume favors corticosteroids; emerging adoption favors combination therapy.
Delivery Mode:
Environmental regulations and bioavailability requirements concentrate investment toward platforms with superior lung deposition and lower carbon intensity.
- Inhalation:Pressurized metered-dose and dry-powder devices dominate maintenance therapy for asthma and COPD. The EPA's hydrofluoroalkane phase-down and EU F-Gas Regulation quota reductions are accelerating transitions to hydrofluoroolefin propellants or propellant-free systems, with dry-powder architectures gaining structural priority in European procurement.
- Nebulization:Compressor and mesh-based systems enable biologic delivery and pediatric administration where coordination with handheld devices proves inadequate. Japan's geriatric infrastructure and homecare reimbursement codes are expanding ambulatory nebulizer utilization for severe disease management.
- Oral:Systemic corticosteroids and phosphodiesterase-4 inhibitors address maintenance gaps and acute exacerbations requiring hospital-level intervention.
- Injectable:Subcutaneous biologics targeting IL-5, IL-13, and TSLP pathways serve eosinophilic phenotypes with inadequate response to inhaled maintenance.
Device transition economics favor inhalation; patient access expansion favors nebulization.
Therapy Area:
Disease prevalence demographics and precision medicine penetration create divergent addressable patient pools across indications.
- COPD:Progressive airflow limitation driven by tobacco exposure and occupational particulates generates the largest maintenance therapy volume. Aging cohorts in Germany, Japan, and the United States sustain treatment intensity, with combination LAMA/LABA/ICS regimens displacing monotherapy in severe segments.
- Asthma:Heterogeneous inflammatory phenotypes enable biologic segmentation around eosinophil and allergic biomarkers. EMA PRIME and FDA Breakthrough Therapy designations are compressing development timelines for TSLP and IL-13 pathway inhibitors in severe, uncontrolled populations.
- Pulmonary Hypertension:Vascular remodeling targeted by endothelin receptor antagonists and prostacyclin analogs requires specialized cardiopulmonary infrastructure.
- Interstitial Lung Disease:Fibrotic progression in idiopathic and connective tissue-associated forms drives antifibrotic adoption with limited therapeutic alternatives.
Volume concentration favors COPD; precision therapy margins favor asthma.
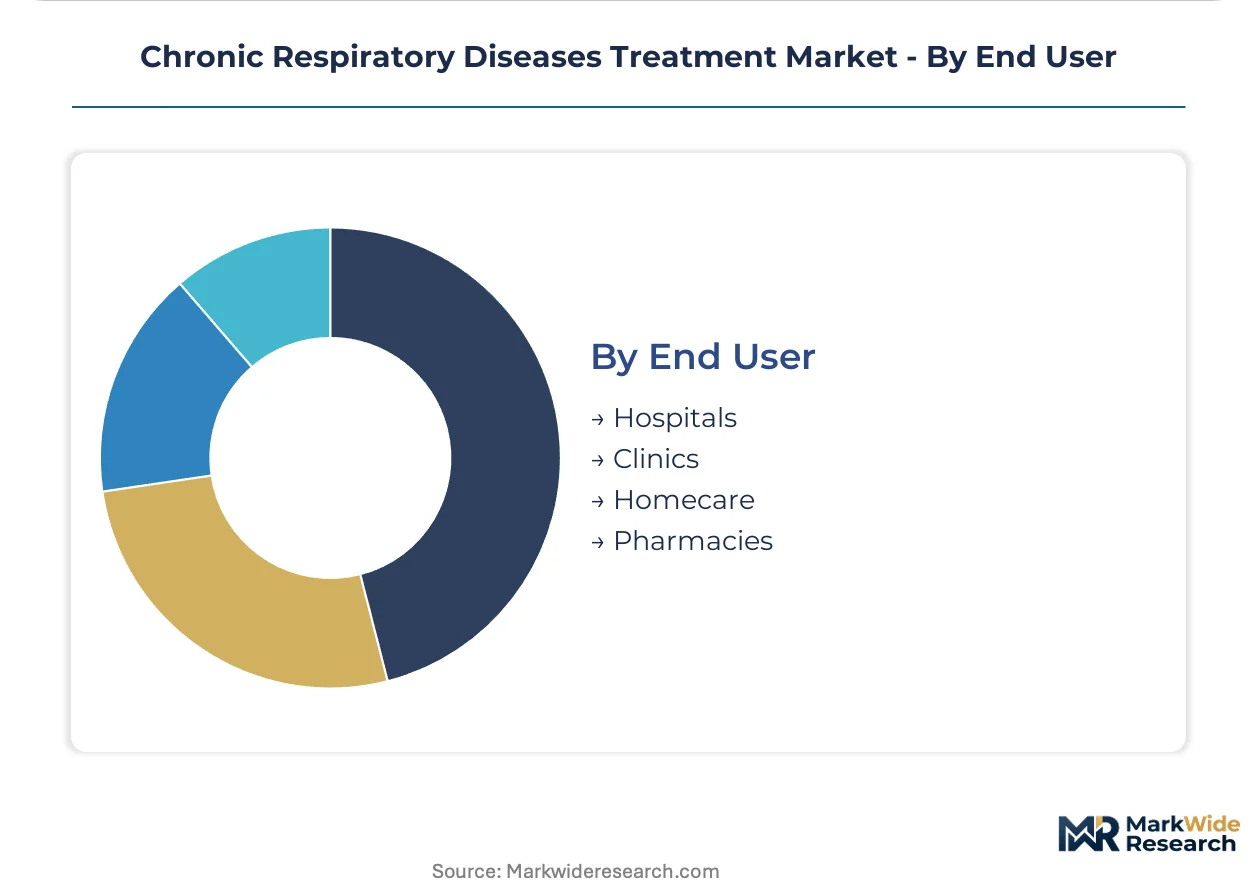
End User:
Reimbursement architecture and remote monitoring capability are redistributing care delivery across facility types.
- Homecare:Bluetooth-enabled inhalers and connected spirometry devices enable ambulatory management of stable moderate disease. Germany's DiGA fast-track and United States CMS remote patient monitoring billing categories are accelerating behavioral shifts away from hospital-based initiation.
- Hospitals:Acute exacerbation management and biologic initiation for severe phenotypes maintain institutional pharmacy concentration. EHR fragmentation and legacy device integration challenges complicate connected inhaler deployment in multi-vendor environments.
- Clinics:Pulmonology practices restructure around ambulatory models with telehealth follow-up and therapeutic monitoring reimbursement.
- Pharmacies:Retail dispensing channels capture maintenance prescription volume with adherence support programs and technique training infrastructure.
Reimbursement tailwinds favor homecare; acute intervention dependence favors hospitals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependence for inhaled corticosteroid APIs shapes trade flows across major consumption centers, with finished formulation exports from European and North American manufacturing hubs offsetting raw material inflows from Asian suppliers.
United States
Medicare reimbursement codes for remote therapeutic monitoring expand homecare channels for connected inhaler platforms. The FDA's Breakthrough Therapy designation accelerates timelines for biologics targeting TSLP and IL-13 pathways in severe eosinophilic asthma. The Research Triangle Park cluster in North Carolina concentrates respiratory clinical trial infrastructure and CRO capacity for Phase III respiratory studies.
Germany
Aging demographics sustain elevated COPD treatment volumes, with combination LAMA/LABA/ICS regimens displacing monotherapy in severe disease segments. The EU MDR's tightened clinical evidence requirements extend recertification timelines for legacy pressurized metered-dose inhalers. The Rhine-Main region around Frankfurt anchors pharmaceutical distribution networks serving Central and Eastern European markets.
Japan
The world's oldest population drives nebulizer-compatible biologic demand for severe asthma management in geriatric patients. METI-supported digital health integration and PMDA's streamlined biologics pathway accelerate connected inhaler launches. The Kanto region surrounding Tokyo concentrates pulmonology specialist practices and hospital pharmacy infrastructure for respiratory biologic initiation.
United Kingdom
NHS England's specialized commissioning frameworks concentrate biologic access in designated severe asthma centers, creating regional treatment hubs. The MHRA's post-Brexit regulatory autonomy enables accelerated assessment pathways for novel inhaled therapies. The Golden Triangle corridor between London, Cambridge, and Oxford anchors respiratory biologics R&D and early-phase clinical development.
India
Domestic API production for inhaled corticosteroids supplies contract manufacturing demand from European and North American originators. CDSCO's tightened quality enforcement actions reshape supplier qualification requirements for export-oriented facilities. The Hyderabad-Visakhapatnam corridor concentrates active pharmaceutical ingredient manufacturing and formulation development for respiratory generics.
Chronic Respiratory Diseases Treatment Market Competitive Environment
Listed leaders compete with private specialists across capital access and development timelines, with publicly traded pharmaceutical conglomerates leveraging equity markets to fund biologics pipeline expansion while family-owned European houses maintain primary care relationships. The competitive structure concentrates around respiratory biologics developers, fixed-dose combination specialists, and device-integrated formulation houses. Strategic moves center on portfolio diversification into precision-molecule pipelines and geographic expansion through emerging market licensing partnerships.
Within the biologics-focused tier, AstraZeneca and Roche exemplify developers leveraging respiratory immunology platforms for severe asthma and COPD positioning. Boehringer Ingelheim occupies a distinctive position as a private German pharmaceutical house with deep European primary care penetration and nebulizer-compatible portfolio breadth. These three anchors represent contrasting competitive models: listed biologics-led growth, private integrated care relationships, and family-controlled long-term market development.
| Leading Market Players |
|---|
| GlaxoSmithKline |
| AstraZeneca |
| Boehringer Ingelheim |
| Novartis |
| Teva Pharmaceutical Industries |
| Sanofi |
| Roche |
| Merck & Co. |
| Chiesi Farmaceutici |
| Others |
Value Chain & Pricing Dynamics
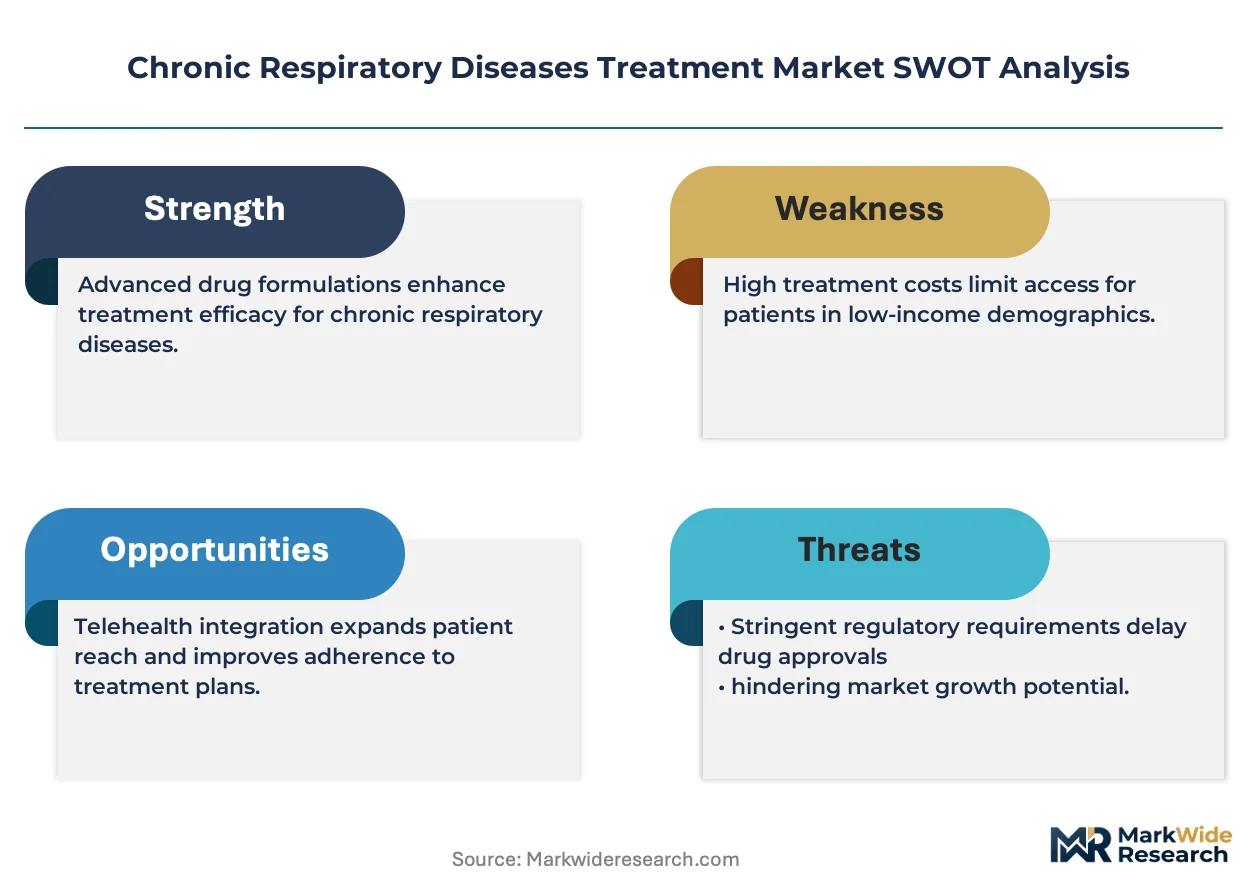
The EU F-Gas Regulation and FDA's updated inhaler bioequivalence guidance gate both API supplier qualification and originator price differentiation simultaneously, concentrating margin pools among developers with legacy clinical datasets while forcing generic entrants into costly specialized imaging studies. Price differentiation between biologic-grade precision therapies and commodity corticosteroid formulations reflects this dual certification burden.
Pricing Analysis
Hospital formularies and pharmacy benefit managers anchor three-tier pricing structure across premium, standard, and economy levels, with biologics commanding premium positioning based on biomarker-stratified efficacy data and originator brands defending share through outcome-based contracting. Price differentiation stems from FDA Breakthrough Therapy designation tier and EU MDR clinical evidence burden scale. Pricing pressure intensifies in the corticosteroid segment due to Indian and Chinese API oversupply. Generic manufacturers exhibit highest price sensitivity; biologics developers demonstrate lowest.
Supply Chain Analysis
Port congestion on Asia-Europe trade lanes and container availability constraints elevate inbound logistics costs for finished inhaler devices sourced from contract manufacturers, compressing working capital cycles for European distributors. Active pharmaceutical ingredient production concentrates in India and China, with formulation finishing in Germany and the United States. Supply chains draw from hydrofluoroalkane propellants, specialized polymer canisters, and electronic sensor components. Single-source vulnerability in Indian API manufacturing creates exposure to CDSCO quality enforcement actions. Distribution runs through hospital pharmacy systems, retail pharmacy chains, and direct-to-patient homecare channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The chronic respiratory diseases treatment market is accelerating through disruption as the EPA's hydrofluoroalkane phase-down and EU F-Gas Regulation quotas force wholesale device platform transitions toward dry-powder and hydrofluoroolefin architectures.
For Market Incumbents: Shield premium positioning in severe asthma and COPD segments by deepening backward integration into nebulizer-compatible biologic manufacturing and securing captive supply of carbon-neutral propellant alternatives. The FDA's tightened bioequivalence guidance for complex generics threatens originator pricing power in corticosteroid categories. Prioritize certification investment under EU MDR recertification pathways to extend legacy device platform lifecycles. For New Entrants and Emerging Players: Lead with pediatric formulation gaps in nebulizer-compatible biologics for severe asthma patients under 12, where competitive density remains lowest and regulatory pathways offer streamlined assessment. Japan's geriatric infrastructure and METI-supported digital health integration present the most penetrable geography for connected inhaler launches. Pursue hospital system partnership go-to-market models to bypass fragmented retail pharmacy distribution. For Investors and Strategic Acquirers: Carve-out targets emerge from large-cap pharmaceutical conglomerates seeking to divest respiratory maintenance portfolios amid biologics pivot strategies. Long-term viability centers on precision-molecule pipelines with biomarker-stratified positioning and device-integrated delivery platforms. Watch FDA Breakthrough Therapy designation velocity for TSLP and IL-13 pathway inhibitors as inflection indicator for biologics adoption curves.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | EMA PRIME scheme accelerates eosinophilic asthma biologics through Phase III respiratory studies. |
| Regulatory Approval Pathway | FDA Breakthrough Therapy designation compresses timelines for TSLP pathway inhibitors in severe populations. |
| Manufacturing Scale-Up | Dry-powder inhaler platform transitions align with EU F-Gas Regulation quota reduction timelines. |
| Pipeline Diversification | Carbon-neutral propellant development opens preferential access under EU Green Deal procurement criteria. |
| Strategic Partnership | Connected inhaler collaborations with telehealth platforms leverage CMS remote monitoring reimbursement codes. |
Study Parameters
Desk research of FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases preceded structured interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists across North America, Europe, and Asia-Pacific. Secondary validation drew from SEC 10-K respiratory segment disclosures, CMS Medicare Part D claims data, and EU customs trade flows for inhaled pharmaceutical devices. Bottom-up patient-volume modeling and top-down revenue triangulation converged on segment-level estimates.
Variance decomposition across therapy area, delivery mode, product type, and end-user channel informed the analytical framework over the projection horizon. CAGRs were derived from regression-based trend extrapolation adjusted for regulatory inflection points and demographic cohort shifts. Forecast inputs incorporated EPA hydrofluoroalkane phase-down timelines, EU MDR recertification completion rates, and Japan's geriatric population trajectories.
Forecasts assume regulatory continuity in FDA Breakthrough Therapy pathways, EMA PRIME schemes, and EU F-Gas Regulation implementation; material policy shifts would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Respiratory Therapy
China Topical Oxygen Therapy Market
Respiratory Therapy
Pneumoconiosis Treatment Market
Respiratory Therapy
Nitric Oxide Management Systems Market
Respiratory Therapy
Respiratory Trainer Market
Respiratory Therapy
Pneumonia Treatment Market
Respiratory Therapy
Virus-Induced Asthma Treatment Market
Respiratory Therapy
Oscillating Positive Expiratory Pressure (OPEP) Devices Market
Respiratory Therapy
Croup Treatment Market
Respiratory Therapy
Chronic Obstructive Pulmonary Disease Treatment Market
Respiratory Therapy
Global Hypoxia Treatment Market
Respiratory Therapy
Respiratory Biologics Market
Respiratory Therapy
Idiopathic Pulmonary Fibrosis (IPF) Treatment Market
Respiratory Therapy
Brazil Therapeutic Respiratory Devices Market
Respiratory Therapy
Global Positive Airway Pressure Market
Respiratory Therapy
Respiratory Antiviral Treatment Market
Respiratory Therapy
Asia-Pacific Topical Oxygen Therapy Market