
 Asthma Treatment Market | 2026-2036
Asthma Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Asthma Treatment Market Analysis
MDR compliance timelines in Europe are decoupling small-device manufacturers from large-scale hospital supply contracts. AstraZeneca leverages its biologics pipeline depth to sustain dominance in severe asthma indications. GlaxoSmithKline anchors its position through fixed-dose combination inhaler portfolios across multiple therapy lines. Teva Pharmaceutical Industries Ltd. competes aggressively in the generics inhaler segment, particularly in dry powder formats.
Asthma treatment encompasses pharmacological interventions and mechanical delivery systems designed to control bronchial inflammation, reverse airway obstruction, and prevent acute exacerbations through corticosteroid administration, beta-agonist bronchodilation, or monoclonal antibody targeting of IgE and IL-5 pathways. Metered-dose inhalers remain the backbone of maintenance therapy, though dry powder inhalers are gaining ground in pediatric and geriatric populations where hand-breath coordination challenges limit traditional device efficacy. Biologics now command disproportionate margin attention as allergen-specific and exercise-induced asthma subpopulations demonstrate durable response to targeted monoclonal therapy. The hospital-to-homecare shift in end-user distribution is redrawing fulfillment logistics, with pharmacies capturing incremental prescription volume as telehealth protocols expand.
FDA, EMA, and NMPA collectively enforce escalating standards for inhaler device equivalence, environmental propellant transition, and biologics manufacturing consistency that filter market participants by compliance capital. The EPA's phasedown of hydrofluoroalkane propellants under the AIM Act is forcing reformulation investments across the metered-dose inhaler installed base. Stakeholders must weigh propellant transition costs against biologics capacity expansion as the dual regulatory pressure on device chemistry and biologic purity intensifies capital allocation trade-offs.
Market Dynamics
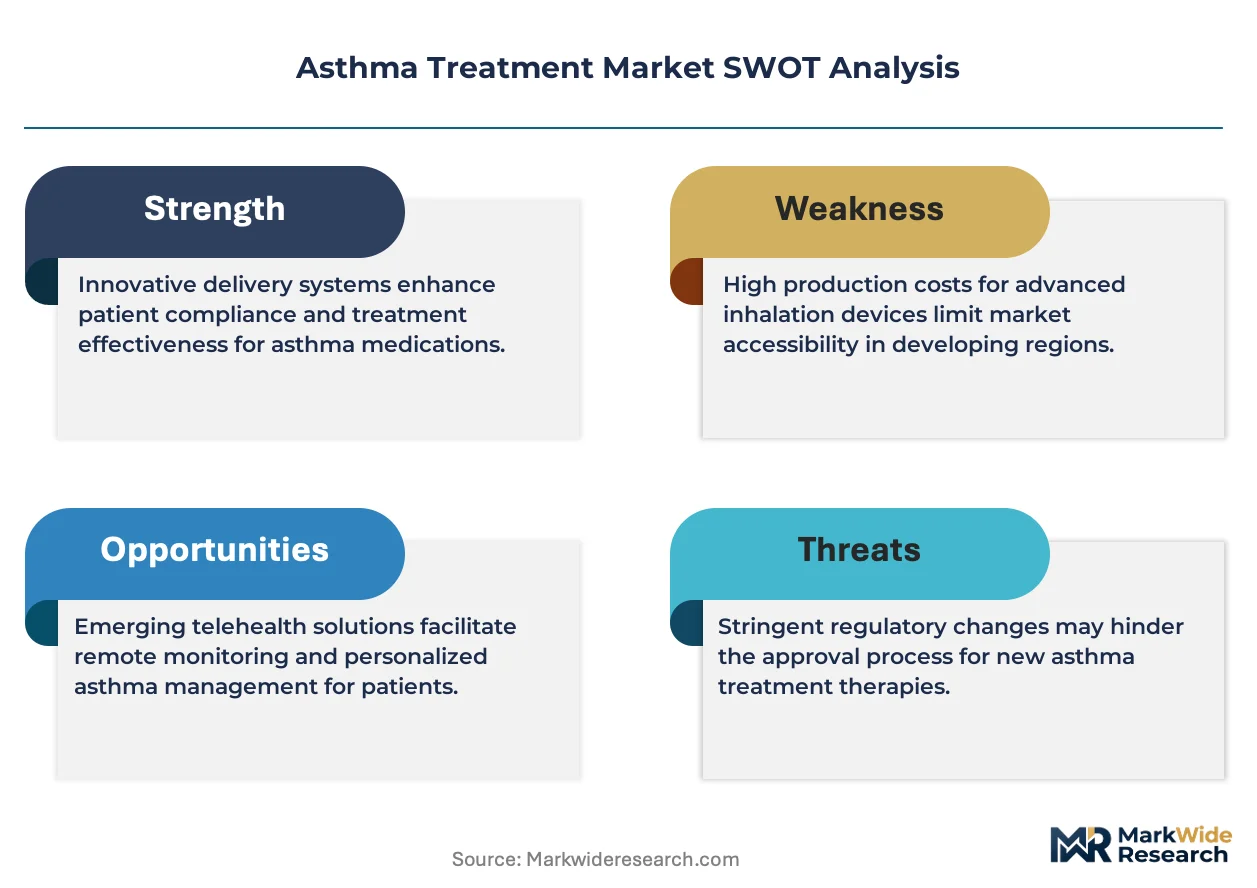
The EPA's hydrofluoroalkane propellant phasedown under the AIM Act is forcing metered-dose inhaler reformulation across the installed base, while biologics manufacturing scale-up demands compete for the same capital pools.
Growth Catalysts
- Telehealth protocol expansion:Remote patient monitoring platforms enable self-administered biologic dosing in homecare settings, reducing hospital dependency for severe asthma populations.
- EMA biosimilar approval framework evolution:Streamlined equivalence pathways for monoclonal antibodies accelerate competitor entry and expand patient access to IL-5 and IgE-targeted therapies.
- Pediatric dry powder inhaler adoption:Hand-breath coordination challenges in children and elderly patients drive device format switching from traditional metered-dose systems.
Market Restraints
- Propellant transition cost burden:Hydrofluoroalkane replacement chemistry requires complete device redesign and toxicology revalidation, compressing margins on established inhaler portfolios.
- Biologics manufacturing concentration:Fill-finish capacity for monoclonal antibodies clusters in Swissmedic-regulated Swiss facilities and select FDA-inspected US sites, creating supply vulnerability.
- Reimbursement fragmentation:Payer prior authorization requirements for biologics vary by US state Medicaid programs, delaying therapy initiation.
Strategic Opportunities
- Underpenetrated exercise-induced asthma segment:Pre-activity bronchodilator protocols remain inconsistently prescribed, creating white space for targeted patient education and device bundling.
- Smart inhaler connectivity convergence:Bluetooth-enabled dose counters integrated with electronic health records enable adherence tracking and outcomes-based contracting with US payers.
- Pharmacy fulfillment channel expansion:Specialty pharmacies capture incremental biologic prescription volume as homecare administration protocols displace infusion center visits.
Industry Challenges
- Inhaler device equivalence demonstration:FDA and EMA aerodynamic particle sizing requirements demand costly clinical bridging studies for generic substitution approval.
- Cold chain biologics distribution reconfiguration:Temperature-controlled last-mile logistics for monoclonal antibodies require infrastructure investment that strains regional pharmacy networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asthma Treatment Market |
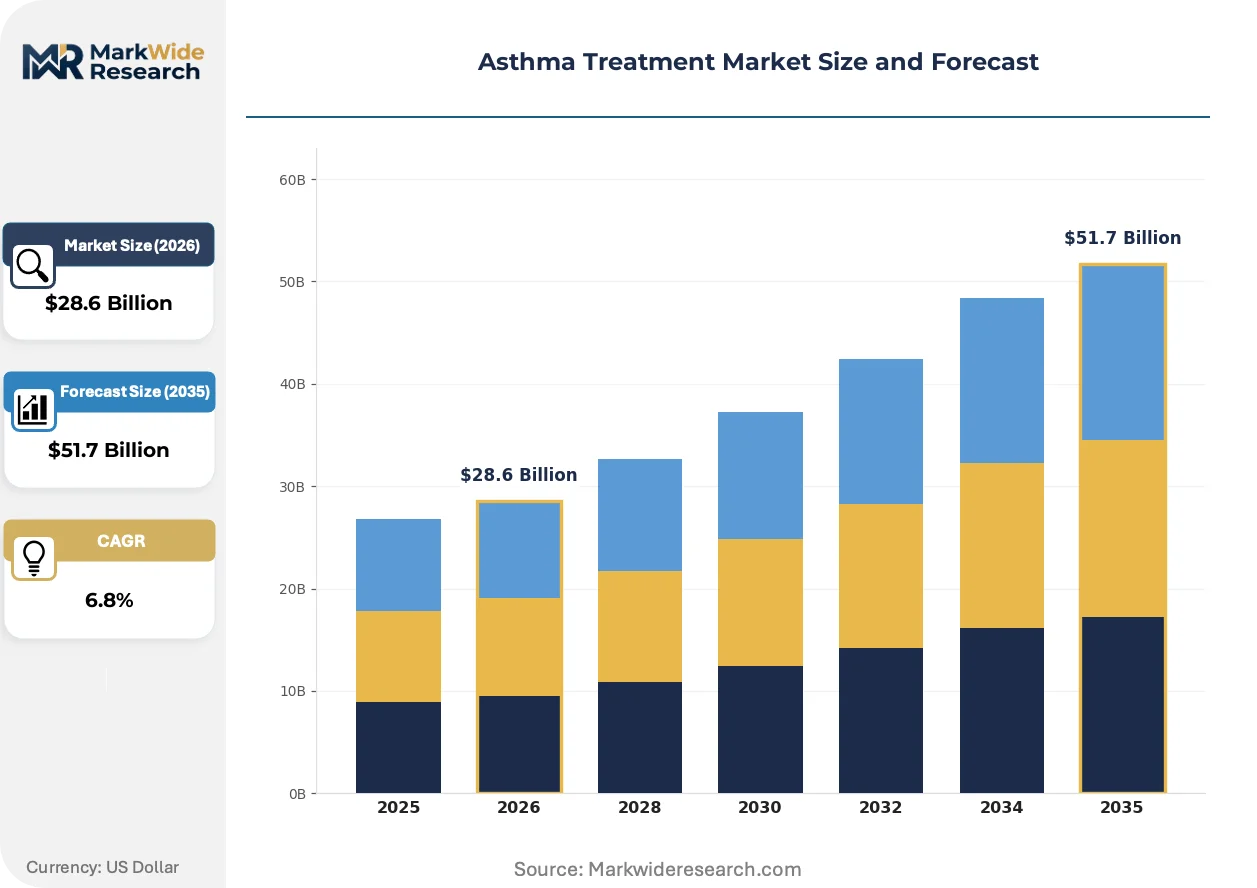
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inhalers, Nebulizers, Oral Medications, Biologics Delivery Mode: Metered-Dose Inhalers, Dry Powder Inhalers, Solutions, Tablets End User: Hospitals, Clinics, Homecare, Pharmacies Therapy Area: Allergic Asthma, Exercise-Induced Asthma, Severe Asthma, Occupational Asthma |
| Companies Covered | AstraZeneca, GlaxoSmithKline, Novartis AG, Boehringer Ingelheim International GmbH, Sanofi, Merck & Co., Inc., Teva Pharmaceutical Industries Ltd., F. Hoffmann-La Roche Ltd., Koninklijke Philips N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asthma Treatment Market Emerging Trajectories
Device digitization and biologics personalization are converging to reshape how asthma therapies are prescribed, monitored, and reimbursed across care settings.
Connected inhaler platforms with embedded sensors and real-time adherence feedback are rewriting the chronic disease management contract between patients and pulmonologists. Pediatric and adolescent populations in US integrated delivery networks show fastest uptake of Bluetooth-enabled dry powder devices. Pharmaceutical manufacturers now bundle hardware subsidies with biologic prescriptions to secure formulary placement and capture longitudinal usage data.
Europe's F-Gas Regulation and the US AIM Act are jointly accelerating hydrofluoroalkane propellant elimination timelines, forcing coordinated reformulation investments across multinational inhaler portfolios. Metered-dose device manufacturers face compressed R&D cycles to validate alternative propellant chemistries before 2028 supply deadlines. Generic competitors without legacy installed base burdens are gaining first-mover advantage in next-generation low-global-warming-potential device submissions.
Specialty pharmacy direct-to-patient distribution is displacing traditional wholesale-hospital channels for biologic asthma therapies, with US payers mandating home infusion alternatives to reduce site-of-care costs. Patient training and adverse event management responsibilities shift to telehealth nursing teams. This channel migration concentrates fulfillment volume with CVS Specialty, Accredo, and Walgreens-owned entities that can credential home health nursing networks.
Asthma Treatment Market Segmentation
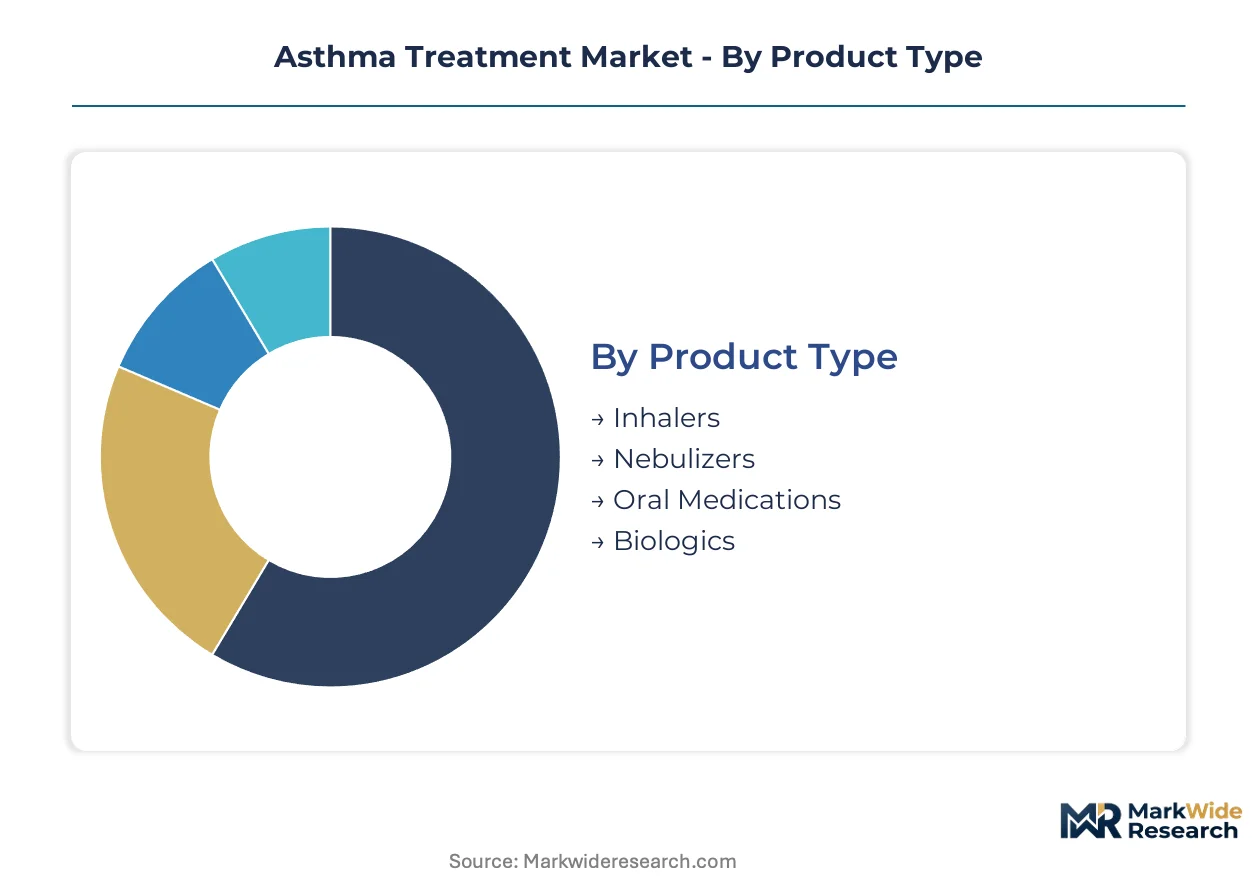
Asthma treatment segmentation reveals divergent capital requirements across device chemistry, biologics manufacturing, and distribution infrastructure. Product type and delivery mode categories demand the heaviest upfront investment, while end-user and therapy area splits reflect shifting reimbursement and patient acuity patterns.
Product Type:
Capital intensity peaks in biologics fill-finish capacity and inhaler propellant transition programs, with manufacturing scale-up competing for limited compliance capital.
- Inhalers:Pressurized metered-dose systems require complete reformulation as hydrofluoroalkane propellants face regulatory phaseout under the US AIM Act and Europe's F-Gas Regulation. Swissmedic-regulated facilities and FDA-inspected US sites concentrate toxicology revalidation investment for alternative propellant chemistries.
- Biologics:Monoclonal antibody production demands single-use bioreactor clusters and cold chain infrastructure for IgE and IL-5 pathway inhibitors. Fill-finish capacity constraints in Swiss and select US facilities create supply vulnerability as homecare administration protocols expand.
- Nebulizers:Compressor and vibrating mesh devices serve acute exacerbation management in hospital and homecare settings with lower regulatory barriers than inhaler propellant transitions.
- Oral Medications:Leukotriene modifiers and corticosteroid tablets occupy the generic-heavy maintenance therapy tier with minimal device R&D overhead.
Inhalers absorb the bulk of installed capacity; biologics is expanding most quickly.
Delivery Mode:
Device format selection hinges on patient coordination capability, with pediatric and geriatric populations driving format switching toward breath-actuated alternatives.
- Metered-Dose Inhalers:Hand-breath coordination requirements limit efficacy in children and elderly patients, though they remain the backbone of maintenance therapy across US and European formularies. EPA propellant phasedown timelines compress R&D cycles for alternative chemistry validation.
- Dry Powder Inhalers:Breath-actuated mechanisms bypass coordination challenges and gain fastest uptake in pediatric integrated delivery networks. Bluetooth-enabled dose counters integrated with electronic health records enable adherence tracking for outcomes-based contracting.
- Solutions:Nebulized formulations serve acute care and patients unable to master handheld device technique, concentrated in hospital and emergency settings.
- Tablets:Oral delivery occupies the maintenance therapy tier with minimal patient training requirements and broad pharmacy distribution.
Metered-dose inhalers retain the largest installed base; dry powder inhalers are climbing the fastest on pediatric and connected-device adoption.
End User:
Channel migration from infusion centers to homecare settings is redrawing fulfillment logistics and concentrating volume with credentialed specialty pharmacy networks.
- Homecare:Self-administered biologic dosing protocols displace hospital visits as telehealth nursing teams assume patient training responsibilities. US payers mandate home infusion alternatives to reduce site-of-care costs, concentrating volume with CVS Specialty, Accredo, and Walgreens-owned entities.
- Hospitals:Acute exacerbation management and initial biologic initiation remain anchored in inpatient and emergency settings, though length of stay compression limits volume growth.
- Clinics:Pulmonology and allergy specialist offices serve as the primary site for therapy selection and device training, with prescription fulfillment shifting to external channels.
- Pharmacies:Retail and specialty pharmacy networks capture incremental prescription volume as direct-to-patient distribution displaces traditional wholesale-hospital channels for biologics.
Hospitals retain the highest acuity concentration; homecare is gaining share fastest on payer cost containment and telehealth protocol expansion.
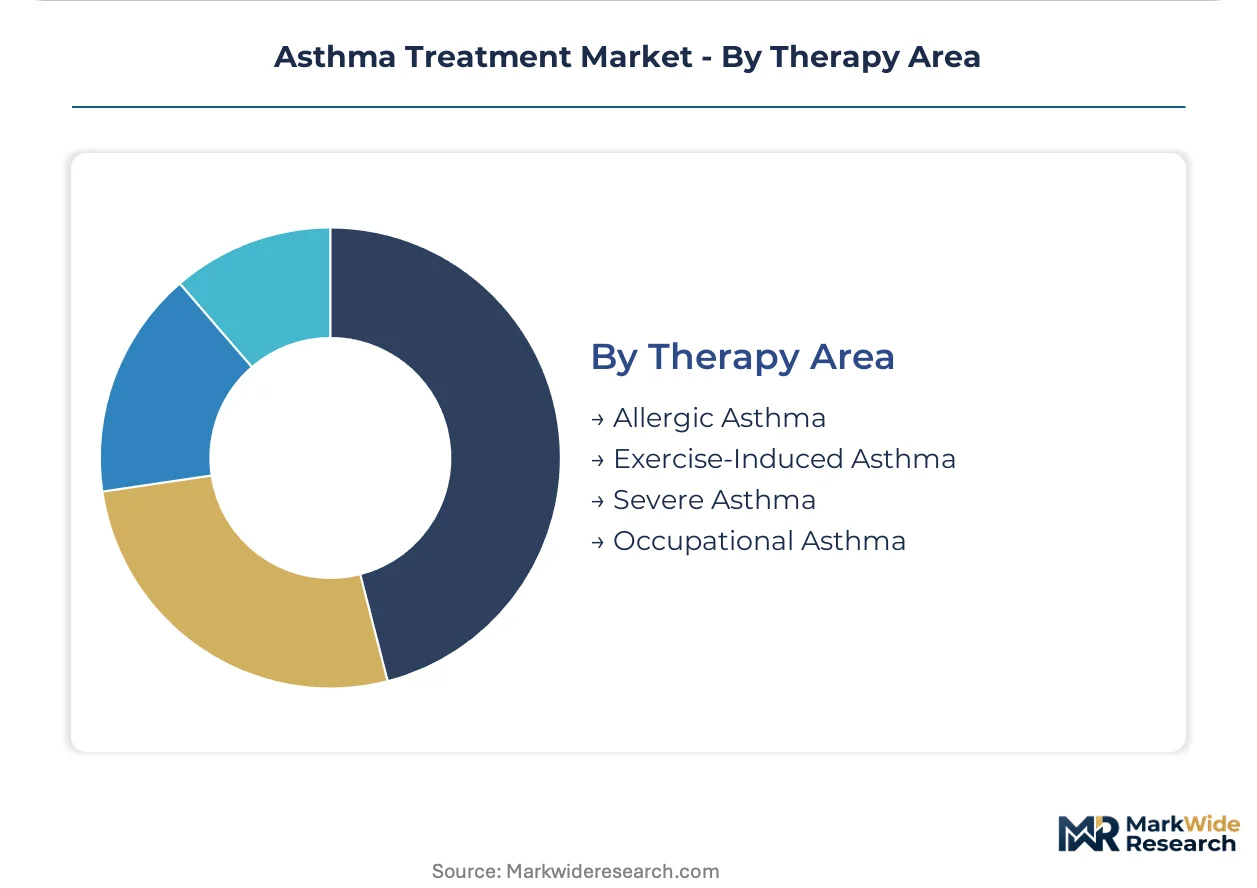
Therapy Area:
Patient phenotype stratification determines biologic eligibility and reimbursement intensity, with severe asthma commanding premium therapy investment.
- Severe Asthma:Eosinophilic and allergic subpopulations demonstrate durable response to IL-5 and IgE-targeted monoclonals, driving disproportionate margin attention. US state Medicaid prior authorization requirements create reimbursement fragmentation that delays therapy initiation.
- Allergic Asthma:IgE-mediated pathways support omalizumab and similar biologic targeting, with allergen-specific immunotherapy complementing pharmacological intervention.
- Exercise-Induced Asthma:Pre-activity bronchodilator protocols remain inconsistently prescribed, creating white space for targeted patient education and device bundling in athletic and school-based populations.
- Occupational Asthma:Workplace exposure-related phenotypes require environmental control alongside pharmacological management, with regulatory reporting obligations varying by national occupational health frameworks.
Severe asthma commands the premium therapy investment; exercise-induced asthma presents the steepest expansion trajectory on underpenetrated protocol adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialty pharmaceutical zones in Basel, Boston, and Hyderabad concentrate biologics manufacturing capacity for monoclonal antibody therapies. These tax-advantaged clusters anchor global supply chains for severe asthma treatments while regulatory divergence across FDA, EMA, and NMPA jurisdictions shapes market access timelines.
United States
Severe asthma prevalence and commercial reimbursement infrastructure sustain premium biologic uptake across integrated delivery networks. The EPA's AIM Act mandates hydrofluoroalkane propellant phasedown by 2028, forcing metered-dose inhaler reformulation investments. Massachusetts and North Carolina biomanufacturing clusters expand fill-finish capacity for IL-5 and IgE-targeted monoclonal antibodies serving homecare administration protocols.
Germany
Pediatric dry powder inhaler adoption accelerates within statutory health insurance formularies prioritizing breath-actuated devices. The F-Gas Regulation aligns with EU-wide propellant transition timelines, compressing R&D cycles for alternative chemistries. Bavaria's medical device manufacturing corridor concentrates connected inhaler sensor production for Bluetooth-enabled adherence tracking systems.
Switzerland
Swissmedic-regulated facilities command disproportionate share of global biologics fill-finish capacity for monoclonal antibody therapies. Cantonal tax incentives reinforce Basel's concentration of respiratory biologics manufacturing and toxicology validation infrastructure. The country's cold chain logistics networks serve as distribution hubs for temperature-sensitive asthma biologics across European homecare channels.
United Kingdom
NHS England's severe asthma pathway redesign expands biologic eligibility criteria for eosinophilic phenotypes. The MHRA's post-Brexit equivalence framework with FDA and EMA streamlines inhaler device approval submissions. Greater London's specialty pharmacy networks credential home health nursing teams for direct-to-patient biologic distribution displacing hospital infusion visits.
India
Domestic dry powder inhaler manufacturing scales to serve price-sensitive maintenance therapy demand across tier-2 and tier-3 cities. CDSCO's biosimilar approval guidelines for monoclonal antibodies accelerate competitor entry to IL-5 pathway inhibitors. Hyderabad's pharmaceutical special economic zone concentrates generic inhaler device production for export markets facing propellant transition deadlines.
Asthma Treatment Market Vendor Landscape
US and UK pharmaceutical conglomerates anchor the biologics tier; Swiss and German specialists hold device chemistry and manufacturing excellence positions. The market structure concentrates around respiratory-dedicated divisions within diversified health science groups, with three archetypes dominating: biologics pipeline owners, fixed-dose combination inhaler incumbents, and generic device challengers. Strategic moves center on biosimilar litigation defense and propellant transition partnerships with contract manufacturing organizations.
Within the biologics archetype, AstraZeneca and GlaxoSmithKline occupy positions defined by severe asthma indication depth and fixed-dose portfolio breadth respectively. Teva Pharmaceutical Industries Ltd. exemplifies the generic device specialist tier competing on dry powder inhaler cost positioning. F. Hoffmann-La Roche Ltd. represents the monoclonal antibody manufacturing scale archetype with Swiss-regulated fill-finish infrastructure. These three anchors illustrate how geographic regulatory clustering—UK commercial reach, Israeli generic manufacturing, Swiss biologics purity standards—shapes competitive differentiation without requiring proprietary technology claims.
| Leading Market Players |
|---|
| AstraZeneca |
| GlaxoSmithKline |
| Novartis AG |
| Boehringer Ingelheim International GmbH |
| Sanofi |
| Merck & Co., Inc. |
| Teva Pharmaceutical Industries Ltd. |
| F. Hoffmann-La Roche Ltd. |
| Koninklijke Philips N.V. |
| Others |
Supply Flow & Price Mechanics
Captive biologics manufacturing in Swissmedic-regulated Basel facilities and FDA-inspected Massachusetts sites anchors supply security and sustains premium pricing power for monoclonal antibody therapies. This vertical integration pattern concentrates fill-finish capacity control with incumbents while forcing price competition onto generic inhaler manufacturers lacking comparable upstream infrastructure.
Pricing Analysis
Short lead-time premiums apply to cold-chain biologics requiring temperature-controlled last-mile logistics, while spot inventory discounts emerge in generic dry powder inhaler categories. Three-tier pricing structure across premium biologics, standard fixed-dose combinations, and economy generic inhalers separates reimbursement tiers by patient acuity and prior authorization intensity. Cost compression in the metered-dose inhaler segment is intensifying because EPA propellant transition deadlines force toxicology revalidation investments. Medicaid programs exhibit highest price sensitivity due to state-level prior authorization fragmentation, while commercial integrated delivery networks show lowest sensitivity for severe asthma biologics with demonstrated outcomes data.
Supply Chain Analysis
Regional distribution centers in Switzerland, the United States, and Germany anchor hub-and-spoke patterns for temperature-sensitive biologics reaching homecare channels. Active pharmaceutical ingredient production draws from India and China for generic inhaler components, while monoclonal antibody cell lines rest on Swiss and US biomanufacturing clusters. Single-source vulnerability concentrates in Swissmedic-regulated fill-finish facilities for IL-5 and IgE-targeted therapies. Distribution runs through specialty pharmacy direct-to-patient networks displacing traditional wholesale-hospital channels for biologic asthma treatments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The asthma treatment sector sits in a device-chemistry transition phase as hydrofluoroalkane propellants face regulatory elimination and connected inhaler platforms replace legacy mechanical dose counters.
For Market Incumbents: Cement formulary positioning through Bluetooth-enabled adherence tracking bundled with biologic prescriptions, capturing longitudinal usage data that supports outcomes-based contracting with US payers. Expand fill-finish capacity in Massachusetts and North Carolina biomanufacturing clusters to offset Swiss supply concentration risk. Prioritize FDA toxicology revalidation timelines for alternative propellant chemistries ahead of AIM Act deadlines. For New Entrants and Emerging Players: Specialty pharmacy networks offer the most accessible channel partnership route for biosimilar monoclonal antibodies seeking rapid formulary placement. Target the underpenetrated exercise-induced asthma segment with pre-activity bronchodilator protocols and school-based athletic program partnerships. Pursue pediatric dry powder inhaler formats where hand-breath coordination advantages drive fastest device-switching velocity. For Investors and Strategic Acquirers: Exit pathways concentrate in biologics manufacturing specialists with Swissmedic or FDA-inspected fill-finish credentials and established cold chain logistics. Long-term viability favors assets with demonstrated IL-5 or IgE pathway inhibitor production scale and telehealth protocol integration capabilities. Watch FDA biosimilar approval velocity for monoclonal antibodies as the inflection indicator for competitive entry intensity and margin compression timing.| Strategic Initiative | Industry Significance |
|---|---|
| Propellant Reformulation Investment | AIM Act compliance secures metered-dose inhaler market access beyond 2028 EPA deadlines. |
| Smart Inhaler Platform Development | Bluetooth-enabled dose counters enable adherence tracking contracts with US integrated delivery networks. |
| Biologics Manufacturing Scale-Up | Single-use bioreactor clusters in Swiss and US facilities address fill-finish capacity constraints for homecare protocols. |
| Specialty Pharmacy Partnership | Direct-to-patient distribution with CVS Specialty or Accredo reduces site-of-care costs for payer mandates. |
| Biosimilar Approval Pathway Navigation | EMA streamlined equivalence protocols accelerate competitor entry to IL-5 and IgE-targeted therapy markets. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with regulatory affairs leads at biologics manufacturers, formulary directors at US integrated delivery networks, pulmonology clinicians, hospital procurement managers, and specialty pharmacy operations executives. FDA 510(k) submissions, EMA marketing authorization applications, EPA AIM Act implementation documents, and CMS Medicare Part B reimbursement data provided secondary validation. Bottom-up patient population modeling and top-down pharmaceutical revenue triangulation cross-checked segment-level outputs.
Data-stream reconciliation across prescription volume databases, biologics shipment records, and inhaler device production indices supported the analytical framework. Segmentation dimensions modeled include product type, delivery mode, end-user channel, and therapy area severity across the projection horizon. CAGRs were derived from patient prevalence trajectories, biologic penetration assumptions, and device replacement cycles. Forecast inputs incorporated EPA propellant phasedown timelines, EMA biosimilar approval velocity, and US payer homecare mandate expansion patterns.
Caveats apply where FDA propellant transition deadline extensions, Swiss biologics manufacturing disruptions, or state Medicaid reimbursement reconfigurations could materially shift the outlook. Forecasts reflect documented assumptions regarding patient phenotype stratification, biologic eligibility expansion, and telehealth protocol adoption rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Global Medication Management Market
Medical Treatment
Cephalic Disorders Treatment Market
Medical Treatment
Post-Operative Nausea and Vomiting (PONV) Market
Medical Treatment
Pelvic Organ Prolapse Repair Market
Medical Treatment
Babesiosis Treatment Market
Medical Treatment
Polycystic Ovary Syndrome (PCOS) Treatment Market
Medical Treatment
Cytokine Release Syndrome Management Market
Medical Treatment
Hyperkalemia Treatment Market
Medical Treatment
Global Von Willebrand Disease Treatment Market
Medical Treatment
North America Chronic Disease Management Market
Medical Treatment
Brazilian Hemorrhagic Fever (Bzhf) Treatment Market
Medical Treatment
Kidney Stones Management Market
Medical Treatment
Behcet's Disease Treatment Market
Medical Treatment
Burns Treatment Market
Medical Treatment
Systemic Inflammatory Response Syndrome Treatment Market
Medical Treatment
North America Breast Reconstruction Market