
 Respiratory Inhaler Market | 2026-2036
Respiratory Inhaler Market Size, Share, and Industry Trends Forecast 2026-2036
Respiratory Inhaler Market Outlook
Hospital procurement channels is reshaping how respiratory inhalers reach end users, with centralized purchasing now favoring suppliers that bundle device training with volume contracts. GSK plc leverages its manufacturing scale to secure multi-year hospital agreements across North America and Europe. AstraZeneca anchors its position through sustained R&D intensity in biologic-naïve patient populations. Boehringer Ingelheim differentiates via specialized soft mist technology that commands premium placement in pulmonology clinics.
A respiratory inhaler is a drug-device combination product that delivers measured doses of bronchodilators, corticosteroids, or combination therapies directly to the lungs through aerosolized particles typically sized between one and five microns for optimal alveolar deposition. The device serves the primary commercial purpose of enabling non-invasive, rapid-onset treatment for obstructive airway diseases while minimizing systemic side effects. Metered-dose inhalers dominate volume due to decades of clinical familiarity and low per-unit cost, though dry powder inhalers are gaining fastest in pediatric and geriatric segments where breath-actuation improves compliance. Nebulizers retain a concentrated margin pool in emergency services and intensive care settings where continuous medication delivery proves critical.
The FDA enforces strict bioequivalence protocols under its draft guidance for orally inhaled products, while the EMA's MDR framework reclassifies many inhalers as higher-risk devices requiring enhanced clinical evidence for CE marking. ISO 20072 standardizes dose uniformity testing, creating a technical barrier that favors established manufacturers with dedicated analytical laboratories. Stakeholders must monitor how emerging sustainability mandates from the EPA and EMA's F-Gas Regulation will alter propellant chemistry and device recyclability requirements.
Market Dynamics
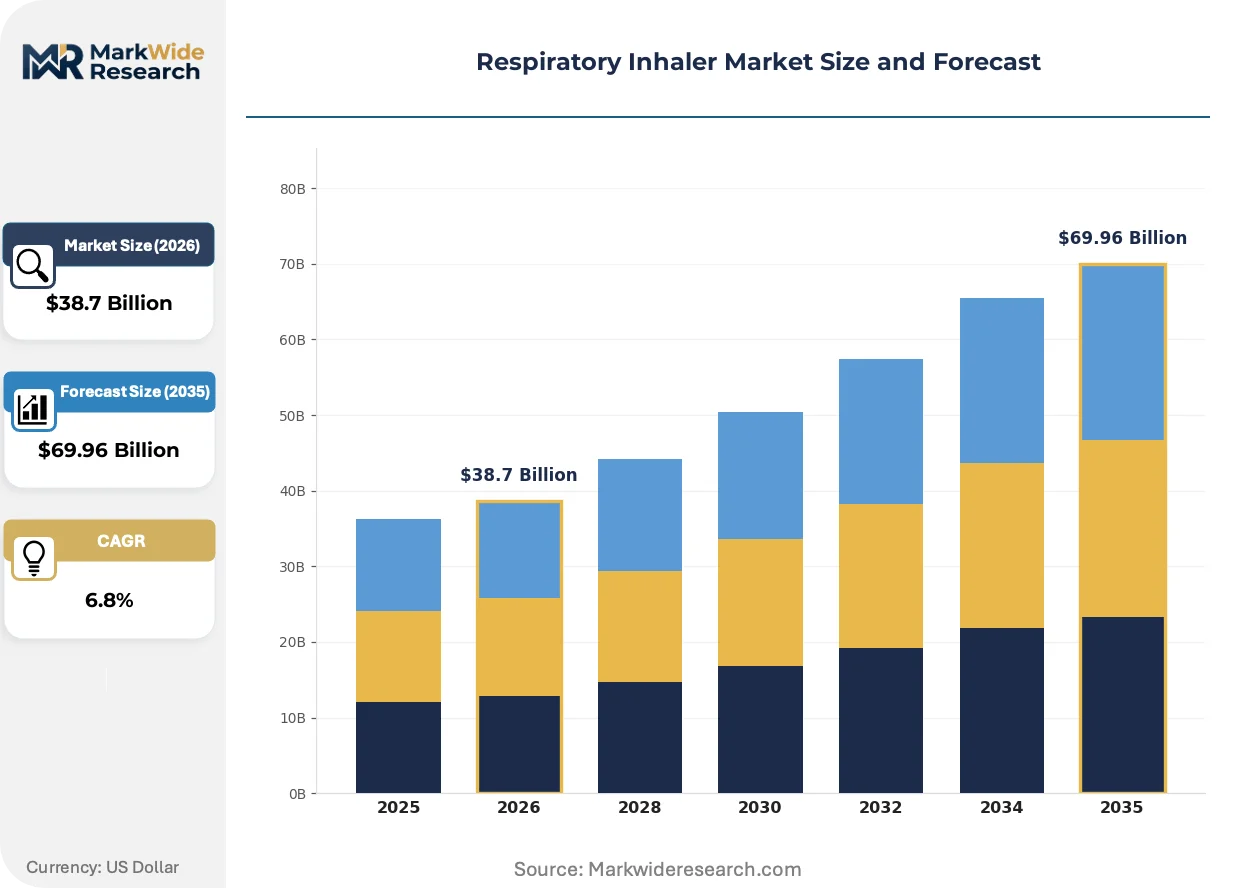
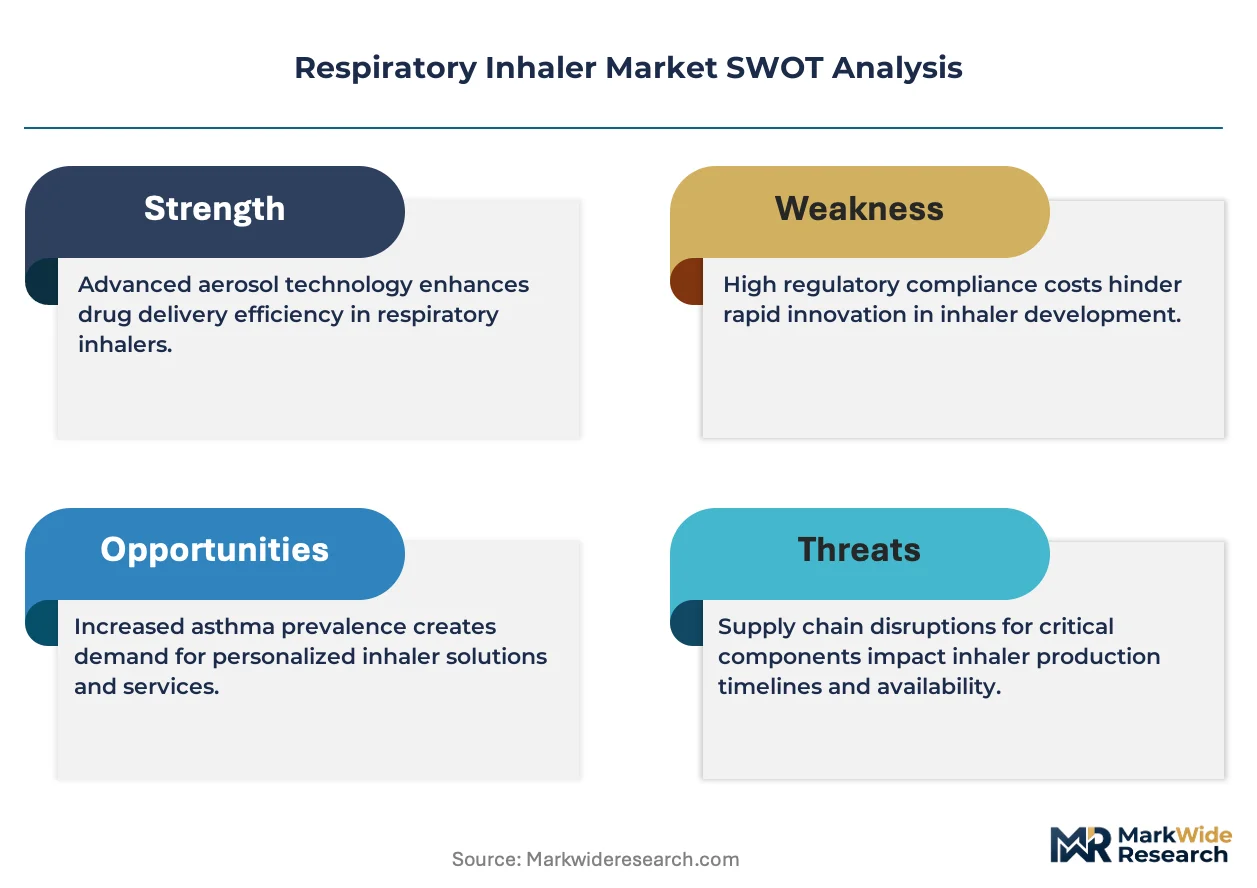
Hospital procurement consolidation and the FDA's tightened bioequivalence standards for generic inhalers are compressing margins while forcing manufacturers toward advanced formulation capabilities and bundled service contracts.
Growth Catalysts
- Home care migration:Patients with asthma and COPD are shifting from institutional settings to self-managed respiratory therapy, expanding addressable volume for portable metered-dose and dry powder devices.
- EMA MDR reclassification:The Medical Device Regulation's elevated risk tier for many inhalers mandates enhanced clinical evidence, creating competitive moats for established manufacturers with dedicated analytical infrastructure.
- Pediatric breath-actuation:Dry powder inhalers are capturing fastest adoption in pediatric and geriatric segments where coordinated inhalation technique proves difficult with pressurized devices.
Market Restraints
- Propellant chemistry constraints:The EPA and EMA's F-Gas Regulation are restricting hydrofluorocarbon propellants used in metered-dose inhalers, forcing costly reformulation of legacy products.
- Analytical laboratory scarcity:ISO 20072 dose uniformity testing requirements concentrate technical capability among a narrow set of established manufacturers with captive laboratory assets.
- Biologic substitution pressure:Injectable biologics for severe asthma are displacing high-dose inhaled corticosteroid combinations in specialist pulmonology practice.
Strategic Opportunities
- Soft mist technology convergence:Integration of aqueous formulation science with novel actuator mechanics commands premium placement in pulmonology clinics resistant to generic commoditization.
- Emerging market underpenetration:India's CDSCO pathway for abbreviated new drug applications creates first-mover potential for manufacturers with localized manufacturing and distribution partnerships.
- Device recyclability mandates:Anticipated EMA sustainability requirements for medical device circularity will reward early investment in aluminum canister recovery and polymer separation technologies.
Industry Challenges
- Inhalation toxicology expertise gap:The specialized skill set bridging pulmonary physiology, aerosol physics, and regulatory science commands premium compensation and constrains R&D expansion timelines.
- Legacy system integration friction:Digital connectivity features in next-generation inhalers face interoperability barriers with established hospital electronic health record architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Respiratory Inhaler Market |
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Metered-Dose Inhaler, Dry Powder Inhaler, Nebulizer, Soft Mist Inhaler End User: Hospitals, Clinics, Home Care, Emergency Services Distribution Channel: Pharmacies, Online Retail, Direct Sales, Medical Stores Formulation: Liquid, Powder, Spray, Aerosol |
| Companies Covered | GSK plc, AstraZeneca, Cipla, Novartis AG, Boehringer Ingelheim, Teva Pharmaceutical Industries Ltd., Chiesi Farmaceutici, Lupin, OMRON Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Respiratory Inhaler Market Strategic Shifts
Connected inhaler technology and sustainable propellant transitions are redrawing competitive boundaries, while procurement centralization reshapes how device manufacturers capture value across acute and chronic care settings.
Connected inhaler platforms with embedded sensors and Bluetooth telemetry are rendering obsolete the reliance on patient-reported adherence metrics in clinical trials and value-based contracts. Pulmonology clinics and integrated delivery networks in the United States are adopting these devices at accelerating pace for severe asthma populations. The shift is compressing differentiation based on mechanical reliability alone while elevating data infrastructure and analytics partnerships as competitive battlegrounds.
The EMA's F-Gas Regulation and parallel EPA restrictions on hydrofluorocarbon propellants are forcing wholesale chemistry transitions across metered-dose inhaler portfolios. Manufacturers face multi-year reformulation timelines and stability testing burdens that favor incumbents with integrated propellant supply chains. Generic challengers without backward integration into propellant production are most exposed to approval delays and cost pass-through volatility.
Hospital procurement coalitions are consolidating volume into multi-year agreements that bundle device training, adherence monitoring, and outcomes guarantees with unit supply. This displaces the traditional fee-for-product model that dominated acute care pharmacy channels. The phenomenon is most visible in United States integrated delivery networks and United Kingdom National Health Service trusts, where total-cost-of-therapy metrics now govern supplier selection.
Respiratory Inhaler Market Segmentation
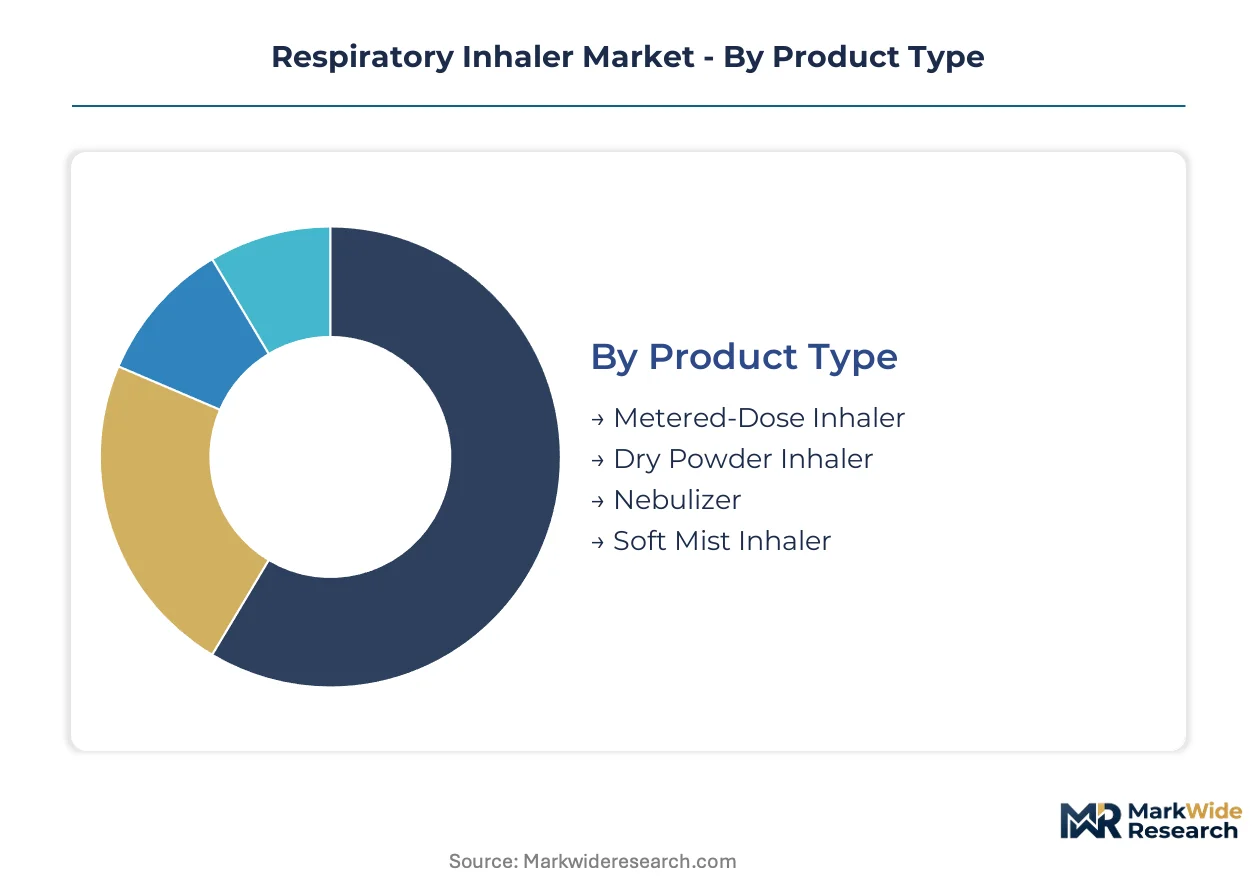
Segmentation in respiratory inhalers reveals divergent service intensity requirements across device categories, with hospital procurement demanding bundled training contracts while home care channels prioritize portability and ease of use. Understanding these structural differences illuminates where margin pools concentrate and which technical capabilities command premium positioning.
Product Type:
After-sales service intensity varies sharply across inhaler modalities, with nebulizers requiring preventive maintenance programs and soft mist devices demanding specialized training support that reshapes supplier economics.
- Metered-Dose Inhaler:Pressurized canisters deliver measured aerosol doses through hand-breath coordination, with hydrofluorocarbon propellant chemistry now facing EPA and EMA F-Gas regulatory pressure that forces multi-year reformulation cycles. Demand concentrates in United States pulmonology clinics where decades of clinical familiarity sustain high-volume procurement despite sustainability headwinds.
- Dry Powder Inhaler:Breath-actuated devices eliminate propellant dependence through micronized drug particles in lactose carrier matrices, capturing fastest adoption in pediatric and geriatric populations where inhalation coordination proves difficult. Germany's Kliniken and United Kingdom NHS trusts favor these devices for outpatient asthma management programs.
- Nebulizer:Compressor-driven or mesh-based systems enable continuous medication delivery for acute exacerbations, requiring calibration services and replacement part logistics that sustain recurring revenue streams.
- Soft Mist Inhaler:Aqueous formulations propelled through mechanical spring mechanisms generate slow-moving aerosol clouds optimized for lung deposition, commanding premium placement in specialist clinics resistant to generic substitution.
Metered-dose inhalers hold the largest share; momentum sits with dry powder devices gaining share fastest among breath-actuation-dependent populations.
End User:
Procurement centralization intensity distinguishes acute care channels from dispersed retail access, with integrated delivery networks consolidating volume through multi-year outcome-based agreements.
- Hospitals:Centralized pharmacy and respiratory therapy departments negotiate bundled contracts combining device supply with staff training and adherence monitoring infrastructure. United States IDNs and United Kingdom NHS trusts increasingly mandate digital connectivity features for severe asthma populations.
- Clinics:Pulmonology and allergy specialty practices select devices based on deposition efficiency data and patient education burden, with soft mist technology securing preferential placement in biologic-naïve patient management.
- Home Care:Self-managed respiratory therapy expansion drives demand for portable, intuitive devices with minimal cleaning requirements, favoring dry powder and metered-dose formats.
- Emergency Services:Pre-hospital and intensive care settings prioritize nebulizers for continuous bronchodilator delivery during acute respiratory failure, with mesh nebulizers displacing compressor systems in ambulance fleets.
Hospitals command the highest contract values; home care channels are expanding most quickly as institutional-to-home migration accelerates.
Distribution Channel:
Channel economics reflect divergent regulatory oversight intensity, with pharmacy and direct sales channels facing distinct compliance burdens for drug-device combination products.
- Pharmacies:Community and hospital outpatient dispensaries remain the dominant access point, with pharmacists providing technique verification that reduces emergency department utilization. Germany's Apotheken and France's officines maintain strict device counseling protocols under national pharmacy practice standards.
- Online Retail:E-commerce platforms capture growing share for maintenance medications, though FDA and EMA serialization requirements for drug-device combinations create compliance complexity that favors established pharmacy chains with verified cold-chain capabilities.
- Direct Sales:Manufacturer field forces engage hospital procurement coalitions and integrated delivery networks with customized adherence analytics platforms.
- Medical Stores:Durable medical equipment suppliers serve nebulizer and accessory demand with rental and preventive maintenance service models.
Pharmacies retain dominant volume; online retail is climbing the fastest as digital prescription fulfillment normalizes.
Formulation:
Formulation chemistry determines device compatibility and regulatory pathway complexity, with liquid and powder formats commanding distinct analytical testing requirements under ISO 20072.
- Liquid:Aqueous or ethanol-based solutions enable nebulizer and soft mist delivery, requiring stability testing for protein and peptide formulations that expands biologic compatibility.
- Powder:Micronized drug particles with excipient carriers optimize dry powder inhaler performance, with particle engineering expertise concentrating among established manufacturers with captive spray-drying capabilities.
- Spray:Pump-actuated aqueous formulations serve nasal and oropharyngeal indications with lower regulatory burden than pulmonary delivery systems.
- Aerosol:Suspension or solution formulations in pressurized metered-dose systems face propellant transition pressures from EPA and EMA F-Gas restrictions.
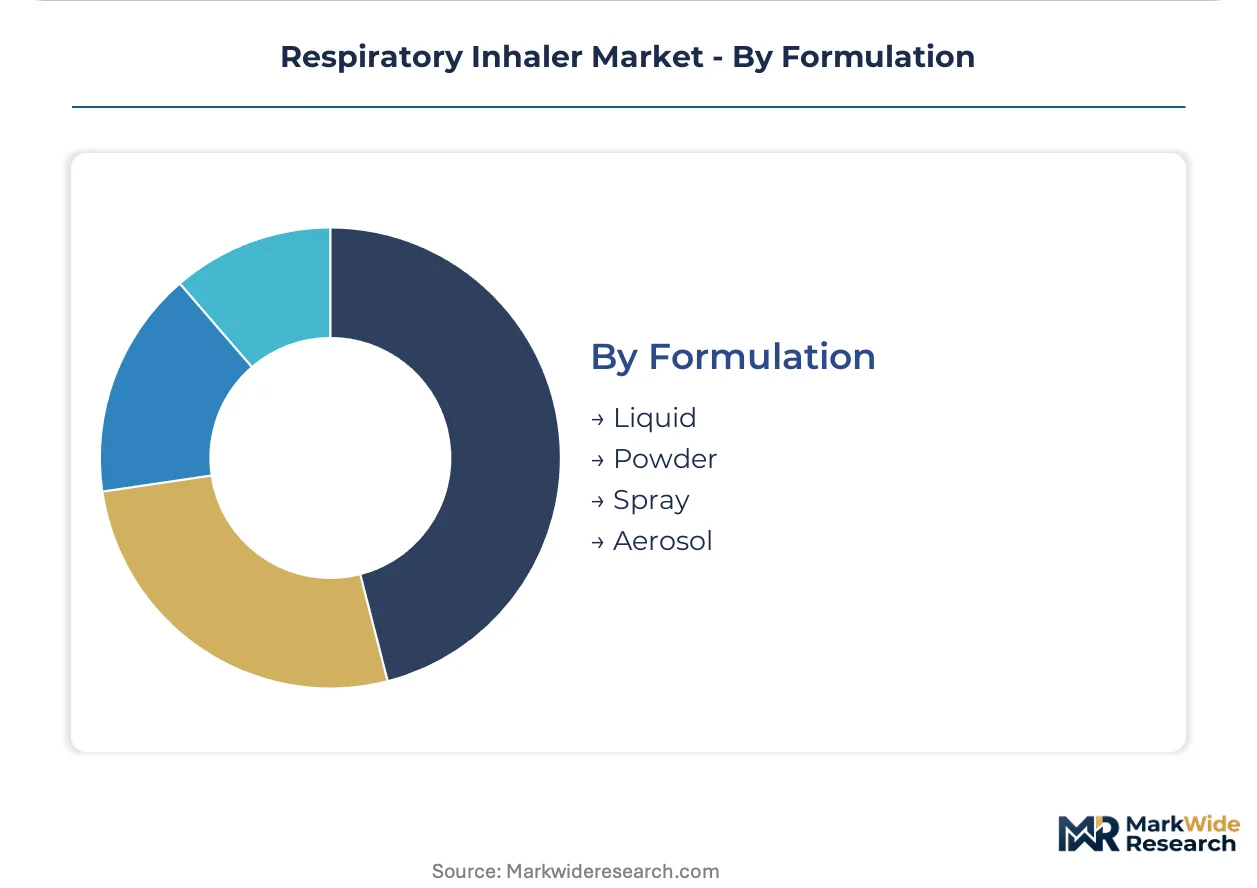
Powder formulations hold the largest share; liquid formulations show steepest expansion trajectory as biologic-naïve patient protocols evolve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
F-Gas Regulation implementation across Europe and FDA bioequivalence tightening in the United States are redrawing manufacturing investment patterns. National procurement centralization and local manufacturing incentives now determine where inhaler production capacity expands.
United States
Asthma and COPD prevalence sustains high-volume procurement of metered-dose and dry powder devices through integrated delivery networks. FDA draft guidance on orally inhaled products enforces strict bioequivalence protocols that favor manufacturers with dedicated analytical laboratories. Boston and Research Triangle Park host concentrated respiratory R&D clusters where connected inhaler platforms with embedded sensors gain traction in severe asthma populations.
Germany
Kliniken and university hospital networks favor dry powder inhalers for outpatient asthma management programs where breath-actuation improves compliance. EMA MDR reclassification mandates enhanced clinical evidence for CE marking, creating competitive moats for established manufacturers. Baden-Württemberg and Bavaria concentrate device engineering expertise alongside pharmaceutical formulation capabilities.
United Kingdom
NHS trusts increasingly mandate digital connectivity features for severe asthma populations through centralized pharmacy procurement. EMA F-Gas Regulation restricts hydrofluorocarbon propellants, forcing reformulation of legacy metered-dose products. London and the Southeast anchor adherence monitoring infrastructure partnerships between health systems and device suppliers.
India
CDSCO pathway for abbreviated new drug applications creates first-mover potential for manufacturers with localized manufacturing partnerships. Domestic production incentives under PLI schemes attract investment in metered-dose and dry powder device assembly. Maharashtra and Gujarat concentrate pharmaceutical manufacturing clusters where distribution partnerships with regional pharmacy chains accelerate market access.
Japan
Aging demographics expand geriatric demand for breath-actuated devices where inhalation coordination proves difficult with pressurized systems. PMDA maintains rigorous drug-device combination review standards that concentrate approval expertise among established players. Tokyo and Osaka metropolitan areas anchor pulmonology clinic networks adopting soft mist technology for biologic-naïve patient management.
Respiratory Inhaler Market Competitive Environment
On the supply side, the industry is consolidating around manufacturers with integrated propellant supply chains and captive analytical infrastructure. Three strategic archetypes dominate: diversified pharmaceutical conglomerates with device manufacturing scale, specialized respiratory-focused firms with formulation depth, and regional generic challengers leveraging abbreviated regulatory pathways. Competitive intensity centers on multi-year hospital procurement contracts and sustainability-driven propellant chemistry transitions.
Within the diversified pharmaceutical tier, GSK plc and AstraZeneca exemplify manufacturers securing multi-year agreements through bundled training and adherence monitoring services. Boehringer Ingelheim occupies a distinct position via specialized soft mist technology that commands premium placement in pulmonology clinics resistant to generic substitution. These three anchors represent contrasting strategic bets on device format differentiation versus service integration.
| Leading Market Players |
|---|
| GSK plc |
| AstraZeneca |
| Cipla |
| Novartis AG |
| Boehringer Ingelheim |
| Teva Pharmaceutical Industries Ltd. |
| Chiesi Farmaceutici |
| Lupin |
| OMRON Corporation |
| Others |
Value Chain & Pricing Dynamics
Air freight corridors linking Indian pharmaceutical clusters to European distribution hubs impose cost volatility that concentrates margin pressure on generic manufacturers lacking captive propellant supply, while ISO-certified incumbents extract premiums through bundled adherence analytics contracts with United States integrated delivery networks.
Pricing Analysis
Certification level under ISO 20072 and FDA bioequivalence tiers creates the primary spread between premium and economy positioning. Three-tier pricing structure across premium, standard, and economy levels dominates, with differentiation anchored in analytical laboratory accreditation and digital connectivity features. Cost compression in the generic tier intensifies because EMA F-Gas reformulation timelines strain manufacturers without backward integration. Hospital procurement coalitions exhibit lowest price sensitivity due to total-cost-of-therapy contracting, while retail pharmacy channels face acute margin pressure from online fulfillment competitors.
Supply Chain Analysis
Contract manufacturing for pressurized canister assembly concentrates among specialized European and North American facilities with validated hydrofluorocarbon handling capabilities. Active pharmaceutical ingredient production draws from India and China, while device molding and final assembly centers on Germany and the United States. Aluminum canister supply rests on single-source vulnerability given concentrated smelter capacity. Distribution runs through hospital procurement coalitions and pharmacy chains with cold-chain verification infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Connected inhaler platforms and EMA MDR reclassification are accelerating competitive disruption, compressing timelines for manufacturers to secure analytical infrastructure and digital partnerships before regulatory moats solidify.
For Market Incumbents: Harden analytical laboratory capacity under ISO 20072 to defend against generic challengers facing bioequivalence approval delays. Secure multi-year propellant supply agreements to neutralize cost pass-through volatility from EPA and EMA F-Gas restrictions. Expand adherence monitoring service bundles to deepen hospital procurement coalition relationships.
For New Entrants and Emerging Players: India's CDSCO abbreviated new drug application pathway for localized manufacturing partnerships represents the most penetrable entry point for volume-scale positioning. Pediatric breath-actuation devices in Southeast Asian markets offer secondary white-space opportunity. Pursue distribution partnerships with regional pharmacy chains rather than direct hospital procurement competition.
For Investors and Strategic Acquirers: EMA MDR implementation reshapes the acquisition landscape by elevating clinical evidence requirements that concentrate value in established CE-marked portfolios. Five-to-ten year viability favors manufacturers with integrated propellant chemistry and device engineering capabilities. Monitor FDA draft guidance finalization on orally inhaled products as the critical inflection signal for generic approval timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| ISO 20072 Analytical Laboratory Accreditation | FDA bioequivalence protocols favor manufacturers with dedicated dose uniformity testing infrastructure. |
| Propellant Chemistry Backward Integration | EMA F-Gas Regulation compliance requires captive hydrofluorocarbon supply chains to control reformulation costs. |
| Connected Inhaler Platform Development | Bluetooth telemetry features command premium placement in United States pulmonology clinic procurement. |
| Hospital Procurement Coalition Partnership | Bundled training and adherence monitoring contracts displace fee-for-product models in acute care channels. |
| India CDSCO Localized Manufacturing | Abbreviated new drug application pathways reward first-movers with regional distribution partnerships. |
Study Parameters
Operator-level perspectives from hospital procurement managers, respiratory therapy directors, pharmaceutical regulatory affairs leads, and GPO contracts specialists anchored the qualitative base. Primary interview findings triangulated against FDA filings, EMA MDR submission databases, hospital procurement contract repositories, and ISO certification registries. Bottom-up volume modeling across device categories and top-down market sizing converged through iterative stakeholder validation.
Scenario-bracketing around regulatory implementation timelines and propellant chemistry transition costs framed the analytical approach across the projection horizon. Segmentation dimensions modeled include device modality, end-user setting, formulation chemistry, and regional regulatory cluster. CAGRs derived from elasticity-adjusted demand curves incorporating asthma and COPD prevalence trajectories, with cross-validation against historical hospital procurement volume data.
Macroeconomic conditions sit as an overlay; deviation in healthcare reimbursement policy, propellant commodity pricing, or trade corridor logistics would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory implementation pacing and technology adoption curves. Quarterly review of FDA guidance finalization, EMA MDR enforcement patterns, and hospital procurement coalition contract awards is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Respiratory Therapy
Healthcare Powered Air Purifying Respirator Market
Respiratory Therapy
Asia-Pacific Topical Oxygen Therapy Market
Respiratory Therapy
Asthma and COPD Biomarkers Market
Respiratory Therapy
Respiratory Disorders Treatment Market
Respiratory Therapy
Nitric Oxide Management Systems Market
Respiratory Therapy
Respiratory Antiviral Treatment Market
Respiratory Therapy
Oscillating Positive Expiratory Pressure (OPEP) Devices Market
Respiratory Therapy
Pediatric Respiratory Disease Therapeutics Market
Respiratory Therapy
Oxygen Therapy Equipment Market
Respiratory Therapy
Chronic Respiratory Diseases Treatment Market
Respiratory Therapy
Global Pneumonia Therapeutics Market
Respiratory Therapy
Global Dyspnea Treatment Market
Respiratory Therapy
Diaphragm Pacing Therapy System Market
Respiratory Therapy
Home Respiratory Therapy Market
Respiratory Therapy
China Topical Oxygen Therapy Market
Respiratory Therapy
Pediatric Respiratory Syncytial Virus Infection Market