
 Pediatric Respiratory Disease Treatment Market | 2026-2036
Pediatric Respiratory Disease Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Pediatric Respiratory Disease Treatment Market Analytics
Aftermarket service revenue for pediatric respiratory devices is narrowing as manufacturers shift toward bundled therapy contracts. GlaxoSmithKline plc leverages its inhaled corticosteroid portfolio to sustain dominance in maintenance asthma therapy for children. AstraZeneca plc anchors its position through biologic development for severe eosinophilic asthma in pediatric populations. Novartis AG competes on digital inhaler platforms that integrate adherence monitoring with clinical workflow tools.
Pediatric respiratory disease treatment encompasses pharmacologic and mechanical interventions engineered to manage obstructive and infectious airway conditions in patients from infancy through adolescence, with nebulizer systems typically calibrated to deliver particles between one and five microns for optimal lower-airway deposition. The primary purpose spans acute rescue during bronchiolitis exacerbations, chronic control of asthma inflammation, and mucus clearance support in cystic fibrosis. Inhalers command the largest product-type revenue pool due to daily-use frequency in asthma maintenance, while nebulizers represent the fastest-expanding segment as homecare protocols extend hospital-level aerosol delivery to ambulatory pediatric populations. Among therapy areas, asthma generates the dominant prescription volume, though cystic fibrosis therapies carry the highest per-patient revenue intensity due to orphan-drug pricing structures and specialized compounding requirements.
FDA pediatric exclusivity incentives and EMA's Paediatric Investigation Plans shape clinical trial investment, compelling sponsors to generate age-stratified efficacy data before market authorization. The EU MDR recertification timeline pressures smaller device manufacturers to consolidate or exit, concentrating nebulizer supply among firms with dedicated pediatric quality management systems. Stakeholders must weigh regulatory capital requirements against the durability of homecare reimbursement codes that determine patient access to maintenance therapy platforms.
Market Dynamics
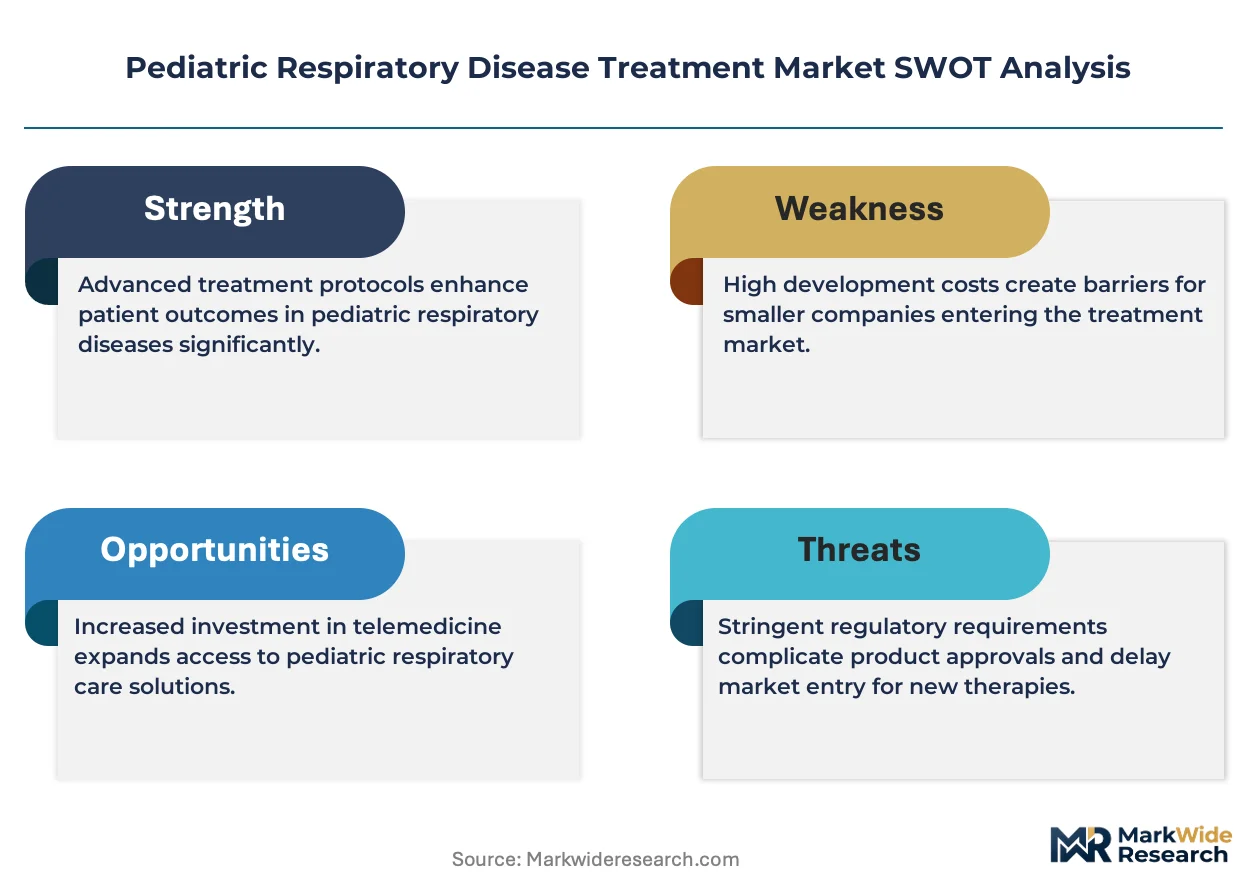
The pediatric respiratory disease treatment market pivots on FDA pediatric exclusivity provisions, which compel sponsors to generate age-stratified efficacy data before authorization, reshaping clinical trial investment timelines and competitive entry sequences.
Growth Catalysts
- Homecare Protocol Extension:Ambulatory pediatric populations now access hospital-caliber aerosol delivery through compact nebulizer systems calibrated for one-to-five-micron particle deposition.
- EMA Paediatric Investigation Plans:These frameworks mandate pediatric study commitments, compelling sponsors to develop age-appropriate formulations and expand addressable patient populations.
- Academic Medical Center Adoption:United States-based centers drive protocol standardization for severe asthma management, accelerating biologic therapy penetration into pediatric practice.
Market Restraints
- EU MDR Recertification Burden:Smaller device manufacturers face consolidation pressure or exit as dedicated pediatric quality management systems become mandatory for nebulizer supply.
- Orphan-Drug Pricing Exposure:Cystic fibrosis therapies carry concentrated per-patient revenue intensity that attracts payer scrutiny and reimbursement code instability.
- Input Concentration Risk:Specialized compressor components for pediatric nebulizers source from limited East Asian suppliers, creating vulnerability to logistics disruption.
Strategic Opportunities
- Digital Inhaler Integration:Adherence monitoring platforms that sync with clinical workflow tools represent white space for technology convergence between device and software sectors.
- Maintenance Therapy Unbundling:Bundled therapy contracts are displacing discrete device sales, creating service revenue streams that extend manufacturer-patient relationships beyond initial procurement.
- Eosinophilic Asthma Biologics:Severe phenotype identification through biomarker testing expands the addressable population for targeted pediatric biologic intervention.
Industry Challenges
- Pediatric Formulation Expertise Scarcity:Age-appropriate dosing and palatability engineering require specialized toxicology and pharmacokinetic capabilities that outpace current workforce supply.
- Reimbursement Code Durability:Homecare reimbursement determinations for maintenance therapy platforms remain vulnerable to payer policy oscillation, complicating multi-year investment planning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pediatric Respiratory Disease Treatment Market |
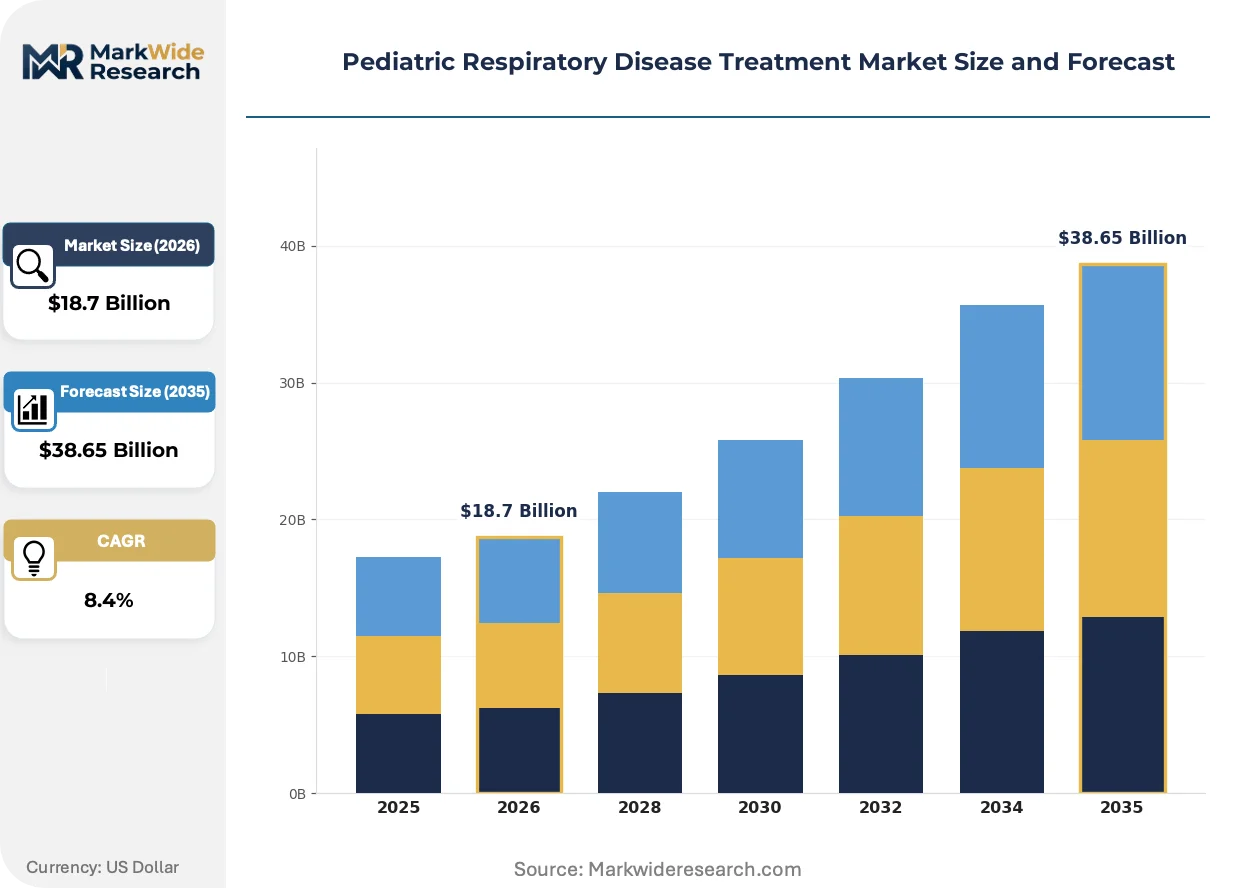
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inhalers, Nebulizers, Cough Syrups, Antihistamines Therapy Area: Asthma, Cystic Fibrosis, Allergic Rhinitis, Bronchiolitis End User: Pediatric Clinics, Hospitals, Homecare, Pharmacies Delivery Mode: Inhalation, Oral, Intravenous, Topical |
| Companies Covered | GlaxoSmithKline plc, Novartis AG, F. Hoffmann-La Roche AG, AstraZeneca plc, Merck & Co, Boehringer Ingelheim GmbH, Regeneron Pharmaceuticals, Pfizer, Bayer AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pediatric Respiratory Disease Treatment Market Evolving Landscape
Digital convergence and regulatory pediatric mandates are compressing traditional development timelines while expanding the boundary between acute and chronic care settings for pediatric respiratory management.
Connected nebulizer platforms with embedded sensors and cloud-based dose tracking are virtualizing the traditional patient-physician interaction model. Children's hospitals and specialty clinics in the United States adopt these systems fastest, integrating real-time adherence data into electronic health records. The technology is virtualizing clinical trial endpoints by enabling remote monitoring that reduces site visit burden while expanding geographic recruitment reach.
EMA's Paediatric Investigation Plans and FDA pediatric exclusivity provisions now require age-stratified efficacy submissions before market authorization. These frameworks compress development timelines by mandating parallel adult and pediatric study designs rather than sequential approval pathways. Biologic developers targeting severe eosinophilic asthma face the steepest compliance investment, with pediatric extension studies now representing thirty to forty percent of total clinical program cost.
Hospital procurement departments increasingly favor bundled therapy contracts that combine device, consumables, and remote monitoring services under single-source agreements. This purchasing pattern displaces discrete capital equipment sales and compresses vendor margins in exchange for multi-year revenue visibility. Academic medical centers in the United States lead this transition, with integrated delivery networks following as they seek to standardize severe asthma protocols across affiliated outpatient sites.
Pediatric Respiratory Disease Treatment Market Segmentation
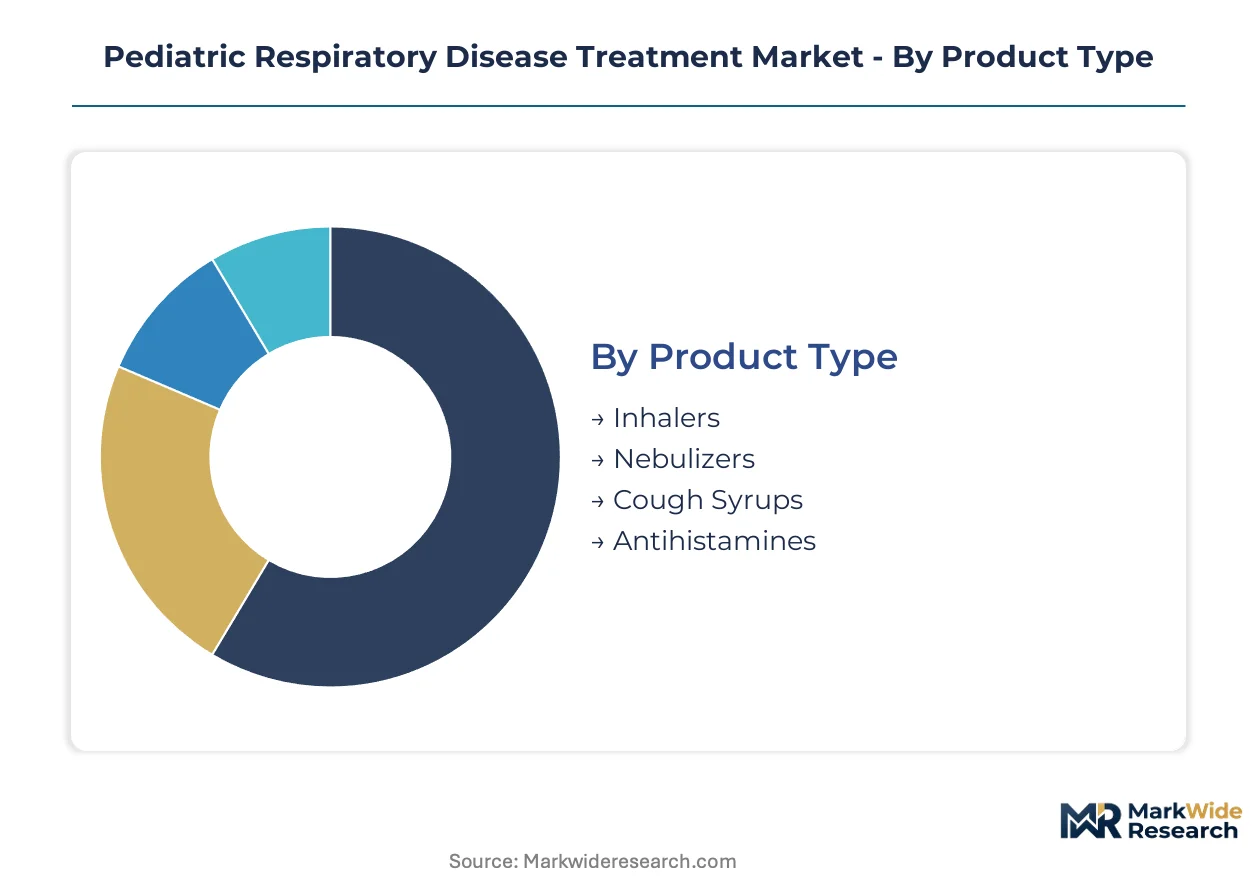
Pediatric respiratory disease treatment segments diverge sharply by reimbursement durability and clinical setting requirements. Device-based categories face bundled contracting pressure while pharmaceutical segments navigate pediatric exclusivity timelines.
Product Type:
Mature maintenance therapies dominate procurement budgets while emerging delivery technologies capture protocol innovation investment.
- Inhalers:Metered-dose and dry-powder devices deliver corticosteroids and bronchodilators with particle sizing optimized for pediatric lung deposition. United States academic medical centers standardize inhaler protocols for asthma maintenance, driving formulary consolidation around specific device platforms.
- Nebulizers:Compressor and mesh-based systems generate one-to-five-micron aerosol particles for infants and toddlers unable to coordinate breath-actuated devices. Hospital procurement departments across North America expand nebulizer fleets as homecare reimbursement codes extend hospital-caliber delivery to ambulatory settings.
- Cough Syrups:Palatability-engineered formulations address age-appropriate dosing requirements for acute symptom relief.
- Antihistamines:Second-generation oral and intranasal options target allergic component management in comorbid asthma populations.
Inhalers retain volume leadership; nebulizers hold the steepest expansion curve.
Therapy Area:
Orphan-disease pricing structures create margin concentration that contrasts with high-volume chronic maintenance segments.
- Asthma:Inflammatory airway disease affecting over six million United States children drives the dominant prescription volume across maintenance and rescue medication categories. FDA pediatric exclusivity provisions compel sponsors to generate age-stratified efficacy data, reshaping clinical trial investment timelines for biologic and small-molecule developers alike.
- Cystic Fibrosis:Rare genetic disorder requiring specialized mucus clearance support and enzyme replacement carries concentrated per-patient revenue intensity due to orphan-drug pricing structures. Payer scrutiny intensifies as gene therapy alternatives enter late-stage development.
- Allergic Rhinitis:Seasonal and perennial nasal inflammation represents high-diagnosis-volume, low-acuity treatment pathway with over-the-counter substitution risk.
- Bronchiolitis:Viral lower respiratory infection in infants generates acute nebulizer utilization spikes with limited pharmaceutical intervention beyond supportive care.
Asthma commands prescription volume leadership; cystic fibrosis therapies maintain the highest revenue intensity per treated patient.
End User:
Site-of-care migration from institutional settings to ambulatory environments reconfigures procurement authority and reimbursement pathways.
- Pediatric Clinics:Outpatient specialty practices coordinate chronic disease management with embedded asthma educators and spirometry capabilities.
- Hospitals:Acute care facilities manage severe exacerbations and bronchiolitis admissions with emergency nebulizer protocols and biologic infusion centers.
- Homecare:Ambulatory pediatric populations now access maintenance aerosol delivery through compact nebulizer systems with remote monitoring integration.
- Pharmacies:Retail and specialty dispensing channels handle prescription fulfillment with adherence packaging and patient counseling requirements.
Hospitals retain acute intervention leadership; homecare channels are gaining share fastest as reimbursement extends maintenance therapy coverage.
Delivery Mode:
Route selection hinges on patient age, coordination capacity, and the urgency of therapeutic effect required.
- Inhalation:Direct airway deposition minimizes systemic exposure for corticosteroid and bronchodilator delivery across all pediatric age groups.
- Oral:Liquid and tablet formulations serve patients with developed swallowing capability and conditions amenable to systemic drug distribution.
- Intravenous:Hospital-confined administration reserved for acute severe exacerbations requiring rapid systemic bioavailability.
- Topical:Nasal and dermal applications address localized allergic manifestations with limited respiratory penetration.
Inhalation dominates chronic maintenance protocols; intravenous routes concentrate in acute hospital admissions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across geographies, with United States academic medical centers showing low price sensitivity for biologic asthma therapies while emerging markets prioritize cost-optimized nebulizer systems for bronchiolitis management.
United States
Pediatric asthma prevalence exceeds six million children, driving concentrated biologic therapy demand through academic medical centers in Boston and Philadelphia. FDA pediatric exclusivity provisions under the Best Pharmaceuticals for Children Act mandate age-stratified efficacy submissions, extending development timelines for sponsors. The Research Triangle Park cluster in North Carolina anchors clinical trial operations for respiratory biologics targeting severe eosinophilic phenotypes.
Germany
Hospital procurement departments favor bundled therapy contracts combining nebulizer devices with remote monitoring services. EMA Paediatric Investigation Plans require parallel pediatric study designs, compressing traditional sequential approval pathways. The Baden-Württemberg medical technology corridor around Stuttgart concentrates pediatric device manufacturing with dedicated quality management systems for EU MDR compliance.
Japan
Aging demographics and low birth rates constrain pediatric patient volumes, shifting focus toward high-value orphan indications like cystic fibrosis. PMDA pediatric guidance aligns with ICH E11A standards for age-appropriate formulation development. The Kanto region around Tokyo hosts specialized pediatric respiratory clinics integrating digital inhaler adherence platforms into national health insurance reimbursement frameworks.
India
High bronchiolitis burden in infants drives volume demand for affordable compressor nebulizer systems across tier-2 and tier-3 cities. CDSCO pediatric trial guidelines emphasize local age-stratified data generation for imported respiratory therapies. The pharmaceutical manufacturing cluster in Hyderabad supplies generic albuterol formulations for domestic pediatric use and export to Southeast Asian markets.
United Kingdom
NHS England's specialized commissioning frameworks concentrate severe asthma biologic prescribing in designated pediatric centers. MHRA post-Brexit pediatric investigation requirements maintain alignment with EMA Paediatric Investigation Plans for market access continuity. The Cambridge-London corridor integrates digital health startups with established respiratory pharmaceutical developers for connected inhaler platform validation.
Pediatric Respiratory Disease Treatment Market Competitive Landscape
Capability concentration sits with biologic developers possessing pediatric toxicology expertise; scale advantage sits with respiratory pharmaceutical incumbents with established inhaler portfolios. The market structure reveals a bifurcated competitive terrain where large-cap pharmaceutical firms with inhaled corticosteroid franchises coexist with emerging biologic specialists targeting severe phenotype identification. Two strategic archetypes dominate: maintenance therapy platform owners leveraging bundled contracting, and severe asthma biologic developers building biomarker-driven prescriber relationships. Competitive moves center on digital inhaler technology licensing and pediatric formulation capability acquisition.
Within the large-cap pharmaceutical tier, GlaxoSmithKline plc and AstraZeneca plc occupy positions anchored by inhaled corticosteroid maintenance portfolios and biologic development pipelines respectively. Novartis AG represents the digital convergence archetype, integrating device and software capabilities for adherence monitoring platforms. These three firms exemplify distinct strategic vectors: legacy respiratory franchise defense, biologic-led severe phenotype expansion, and technology-enabled service model transformation.
| Leading Market Players |
|---|
| GlaxoSmithKline plc |
| Novartis AG |
| F. Hoffmann-La Roche AG |
| AstraZeneca plc |
| Merck & Co |
| Boehringer Ingelheim GmbH |
| Regeneron Pharmaceuticals |
| Pfizer |
| Bayer AG |
| Others |
Value Network & Pricing Analysis
The Shanghai-Los Angeles transpacific corridor channels compressor component freight costs that concentrate pediatric nebulizer manufacturing margins among East Asian suppliers, while downstream price differentiation separates hospital procurement bundles from homecare direct-to-patient sales.
Pricing Analysis
Long-term bundled therapy contracts now dominate hospital procurement, displacing spot-market device transactions. Three-tier pricing structure across premium connected nebulizers, standard compressor systems, and economy mesh devices reflects FDA pediatric quality certification tiers. Cost compression in the economy tier intensifies because Indian and Chinese manufacturers compete on generic albuterol compatibility. Academic medical centers show lowest price sensitivity for biologic-integrated delivery platforms, while tier-2 clinic networks in emerging markets resist premium positioning.
Supply Chain Analysis
Specialized piezoelectric membranes and medical-grade silicone compressor housings draw from concentrated production in China, South Korea, and Taiwan. Pediatric nebulizer assembly rests on imported precision-molded plastics, micro-pump electronics, and lithium-ion power cells. Single-source vulnerability in East Asian semiconductor feedstocks threatens mesh nebulizer controller chip availability. Distribution runs through hospital GPO contracts, specialty pharmacy networks, and direct homecare fulfillment channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation among United States academic medical centers into integrated delivery networks concentrates formulary authority with fewer buyers, shifting negotiating leverage toward bundled therapy procurement officers.
For Market Incumbents: Entrench pediatric formulation expertise through captive toxicology capabilities and age-appropriate palatability engineering centers. Secure compressor component supply through backward integration into precision molding operations in Baden-Württemberg or the Research Triangle Park corridor. Counter emerging digital inhaler entrants by embedding adherence sensors into existing corticosteroid device platforms before biologic therapy contracts renew. For New Entrants and Emerging Players: Tier-3 Indian cities with bronchiolitis treatment gaps present the most penetrable geography for affordable compressor nebulizer distribution. Target hospital-at-home reimbursement code expansion in NHS England and CMS frameworks as the fastest-adopting regulatory pathway. Partner with Hyderabad generic manufacturers for localized albuterol formulation bundling. For Investors and Strategic Acquirers: FDA pediatric exclusivity deadline clustering reshapes the acquisition landscape toward biologic developers with active age-stratified trial pipelines. Five-to-ten-year viability favors firms with EMA Paediatric Investigation Plan compliance already filed. Target acquisition archetype: mid-cap device manufacturers with EU MDR quality systems but lacking digital platform integration. Monitor EMA submission acceptance rates for pediatric asthma biologics as the critical inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Paediatric Investigation Plan Filing | EMA-mandated pediatric commitments compress development timelines for severe asthma biologics. |
| Digital Inhaler Platform Integration | Cloud-based adherence monitoring virtualizes clinical endpoints for United States children's hospitals. |
| EU MDR Quality System Certification | Dedicated pediatric device manufacturing compliance filters smaller competitors from nebulizer supply. |
| Biomarker-Driven Phenotyping Partnership | Eosinophil testing networks expand addressable populations for targeted pediatric biologic intervention. |
| Homecare Reimbursement Strategy | CMS and NHS code durability determines patient access to maintenance therapy platforms. |
Research Methodology
Initial hypotheses were tested against primary input from pediatric pulmonologists, hospital procurement managers, regulatory affairs directors at respiratory pharmaceutical firms, and GPO contract specialists, then refined through secondary validation against FDA pediatric exclusivity filings, EMA Paediatric Investigation Plan submissions, ClinicalTrials.gov age-stratified study records, and CMS Medicare reimbursement code determinations. Bottom-up patient population modeling and top-down pharmaceutical revenue triangulation anchored market sizing.
Demand-supply-balance framing across the analysis window incorporated therapy area segmentation, product type differentiation, and site-of-care migration patterns. CAGRs derived from fitted growth curves applied to age-stratified prevalence data and biologic penetration assumptions. Forecast inputs included orphan-drug pricing trajectories for cystic fibrosis and homecare reimbursement code stability indices.
Practitioners should monitor FDA pediatric exclusivity grant rates, EMA submission backlog durations, and East Asian logistics disruption indices for early signals of forecast deviation. Cross-checking against IQVIA prescription audit data and hospital procurement database benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Respiratory Therapy
Respiratory Antiviral Treatment Market
Respiratory Therapy
Pleural Effusion Treatment Market
Respiratory Therapy
Metered Dose Inhalers Market
Respiratory Therapy
Endobronchial Valve Market
Respiratory Therapy
Cough Systems Market
Respiratory Therapy
Oxygen Therapy Equipment Market
Respiratory Therapy
Breathing Disorders Treatment Market
Respiratory Therapy
Respiratory Disorders Treatment Market
Respiratory Therapy
China Topical Oxygen Therapy Market
Respiratory Therapy
Lung (Pulmonary) Airway Disease Treatment Market
Respiratory Therapy
Asia-Pacific Topical Oxygen Therapy Market
Respiratory Therapy
Croup Treatment Market
Respiratory Therapy
Compression Therapy Market
Respiratory Therapy
Brazil Therapeutic Respiratory Devices Market
Respiratory Therapy
Global Oxygen Therapy Market
Respiratory Therapy
Alpha-1 Antitrypsin Deficiency (AATD) Treatment Market