
 Programmable Logic Controller [PLC] Market | 2026-2036
Programmable Logic Controller [PLC] Market Size, Share, and Industry Trends Forecast 2026-2036
Programmable Logic Controller [PLC] Market Analytics
The EU Green Deal is realigning procurement criteria for industrial automation across European manufacturing plants. Siemens leverages its domestic engineering base to dominate safety PLC development for process industries. Rockwell Automation sustains its position through channel control over North American automotive OEMs. Mitsubishi Electric anchors its competitiveness in compact PLC designs for Asian electronics manufacturing.
A programmable logic controller is an industrial digital computer engineered for electromechanical process automation, typically operating across temperature ranges from minus 20 to plus 60 degrees Celsius with scan cycles measured in milliseconds. Its primary purpose is executing relay logic, motion control, and process sequencing in harsh factory environments. Modular PLC architectures capture the dominant share of margin pools due to scalability in large process control installations. Compact PLCs are gaining fastest in building automation where space constraints and cost sensitivity shape buyer decisions. Ethernet/IP connectivity is displacing legacy fieldbus protocols across new factory automation deployments.
The EU AI Act and CE marking requirements under the Machinery Directive are reshaping product certification pathways for safety-critical PLC applications in European markets. OSHA electrical safety standards and FDA 21 CFR Part 11 compliance obligations in the United States create parallel regulatory thresholds for pharmaceutical and food manufacturing automation buyers. Stakeholders must monitor divergence between European AI governance frameworks and American sectoral safety regulations when configuring transatlantic product roadmaps.
Market Dynamics
Ethernet/IP protocol migration is compressing fieldbus infrastructure replacement cycles across automotive and process manufacturing, forcing incumbent suppliers to reconfigure hardware-software bundling strategies.
Growth Catalysts
- EU Green Deal energy mandates:Industrial efficiency thresholds for motor control systems are accelerating PLC refresh rates in German and French process plants.
- Automotive assembly automation:Battery module welding and electric drivetrain assembly lines are expanding safety PLC deployment in Michigan and Stuttgart manufacturing corridors.
- Edge computing integration:Real-time analytics at the device level is reducing latency for predictive maintenance applications in semiconductor fabs.
Market Restraints
- Silicon supply concentration:Microcontroller wafer fabrication bottlenecks in Taiwan are extending PLC lead times for compact unit orders.
- Legacy protocol lock-in:Profibus and DeviceNet installed bases in German chemical plants create switching friction for Ethernet/IP migration.
- Functional safety certification costs:IEC 61508 SIL compliance expenses disproportionately burden mid-tier PLC vendors serving building automation.
Strategic Opportunities
- India manufacturing automation:PLI scheme incentives for electronics and automotive component production are opening greenfield PLC specification opportunities in Gujarat and Tamil Nadu.
- AI-driven process optimization:Machine learning inference at the PLC edge is converging with traditional ladder logic in food and beverage batch control.
- Remote service channel development:Cloud-connected diagnostics platforms are unbundling traditional distributor technical support models in North American machine builder segments.
Industry Challenges
- Embedded cybersecurity expertise:IEC 62443 compliance requirements are outpacing firmware engineering talent availability in European automation vendors.
- Multi-protocol integration complexity:Time-Sensitive Networking coexistence with legacy fieldbus is extending commissioning timelines for brownfield retrofits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Programmable Logic Controller [PLC] Market |
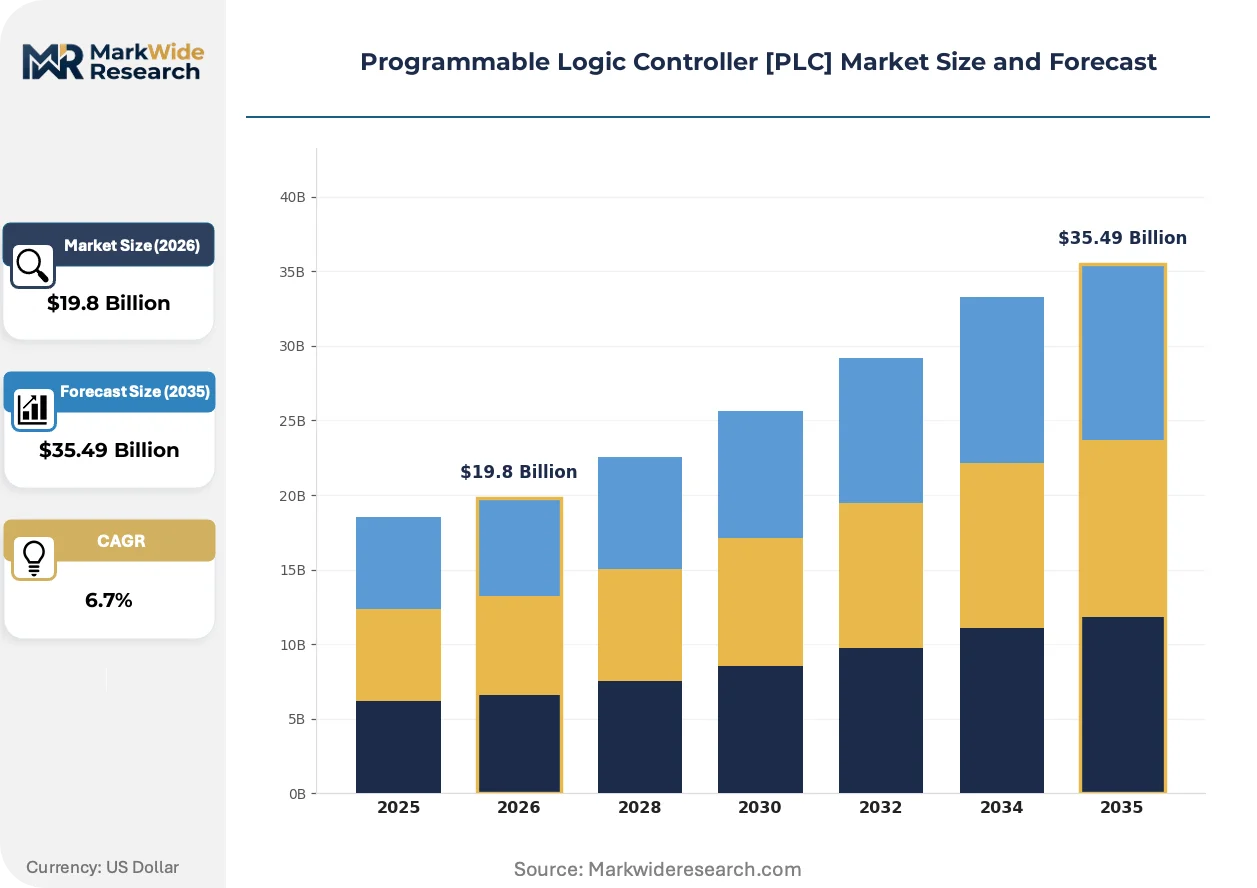
| Market Size in 2026 | $19.8 Billion |
| Market Size in 2035 | $35.49 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Compact PLC, Modular PLC, Rack-mounted PLC, Safety PLC Technology: Ethernet/IP, Modbus TCP, Profibus, DeviceNet End User: Manufacturing, Oil & Gas, Automotive, Utilities Application: Process Control, Factory Automation, Building Automation, Robotics |
| Companies Covered | Siemens, Rockwell Automation, Mitsubishi Electric, Schneider Electric, Omron, ABB, Honeywell, Emerson, Delta, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Programmable Logic Controller [PLC] Market Evolving Landscape
Operational technology-IT boundary dissolution is redefining PLC architecture requirements, with software-defined automation and cybersecurity hardening emerging as parallel development vectors.
Time-Sensitive Networking is converging with deterministic industrial Ethernet to enable microsecond-precision motion control across multi-vendor automation cells. Automotive OEMs in Germany and the United States are piloting TSN-enabled PLC backbones for synchronized robotic welding lines. This convergence is compressing the traditional separation between machine control and enterprise data layers.
The EU AI Act risk classification framework is mandating conformity assessments for AI-enabled PLCs deployed in safety-critical process applications. Machinery Directive harmonized standards are being revised to address neural network interpretability requirements. Pharmaceutical manufacturers in Ireland and Belgium are front-loading compliance investments ahead of notified body backlog accumulation.
Machine builder buyers are unbundling lifecycle service contracts from initial hardware procurement, compressing distributor margin pools and favoring direct manufacturer subscription models. System integrators in the US Midwest are consolidating specification influence through vertical expertise in battery manufacturing. This behavioral shift is most pronounced in automotive tier-one supplier relationships where total cost of ownership models dominate capital approval processes.
Programmable Logic Controller [PLC] Market Segmentation
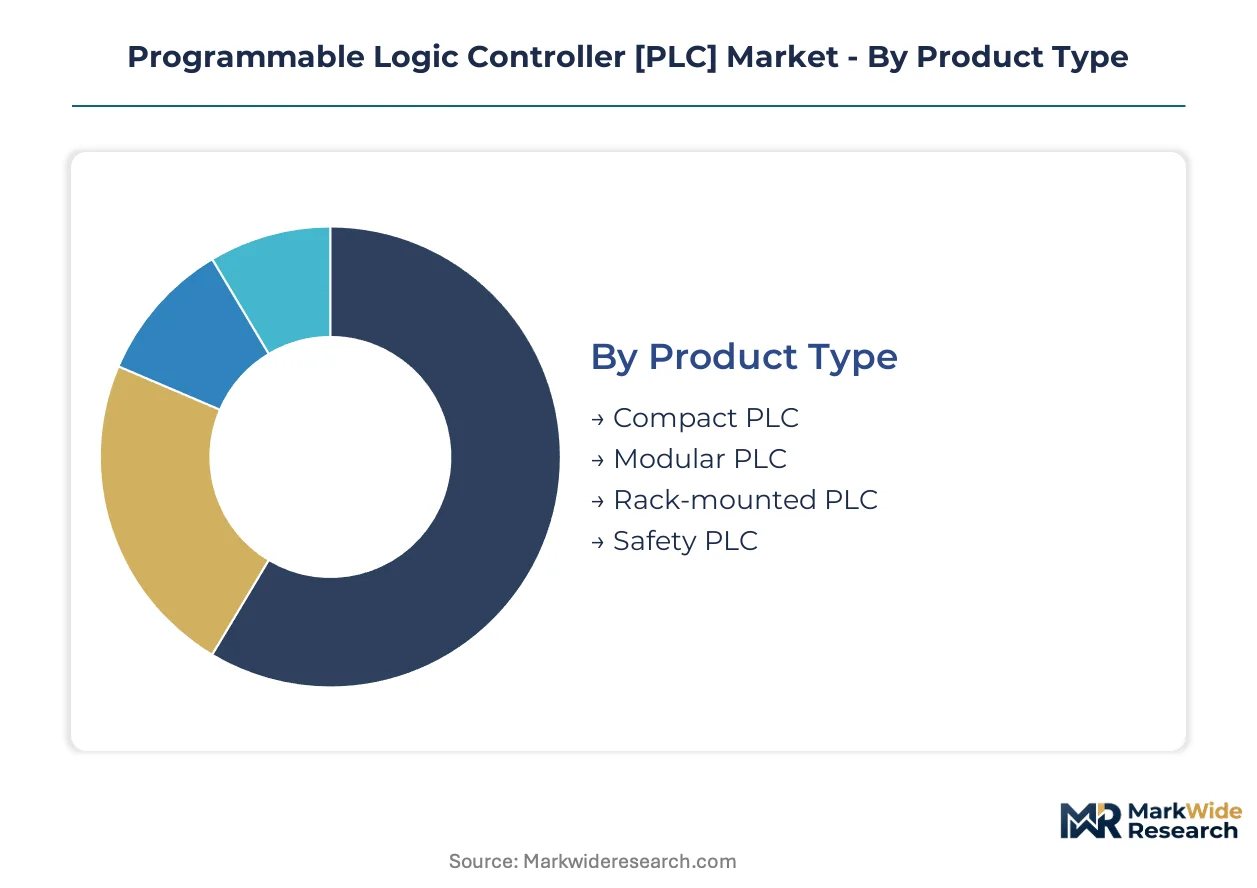
PLC procurement decisions hinge on balancing scalability requirements against capital constraints and operational environment demands. Engineers evaluate thermal tolerance, I/O density, and protocol compatibility before specifying hardware for specific automation tasks.
Product Type:
Capital intensity and facility scale determine whether buyers prioritize compact footprints or modular expansion capabilities.
- Compact PLC:Integrated CPU and I/O modules in fixed configurations suit machine-level control with limited expansion needs. Demand concentrates in Asian electronics manufacturing where space constraints and cost sensitivity dominate buyer criteria.
- Modular PLC:Separated processor, power supply, and I/O modules enable hot-swappable configuration changes during operation. Large process control installations in German chemical plants and US automotive assembly corridors drive specification volumes for this architecture.
- Rack-mounted PLC:Standardized 19-inch chassis mounting accommodates high-density I/O configurations in centralized control rooms.
- Safety PLC:Redundant processor architectures with certified fault detection serve SIL-rated applications in automotive welding lines and pharmaceutical batch operations.
Modular PLC leads on scale; Safety PLC leads on momentum.
Technology:
Protocol selection locks buyers into vendor ecosystems and determines integration complexity with existing fieldbus infrastructure.
- Ethernet/IP:CIP-based industrial Ethernet protocol delivers deterministic messaging over standard IEEE 802.3 physical layers. New factory automation deployments in Michigan and Stuttgart manufacturing corridors are displacing legacy fieldbus alternatives.
- Modbus TCP:Simplified register-based communication suits building automation and energy management systems where interoperability trues performance optimization.
- Profibus:Token-passing fieldbus protocol retains installed base dominance in German chemical processing and discrete manufacturing operations.
- DeviceNet:CAN-based physical layer serves cost-constrained material handling and packaging machinery in North American automotive tier-one supplier networks.
Ethernet/IP leads on momentum; Profibus retains scale through legacy lock-in.
End User:
Industry-specific regulatory burdens and operational uptime requirements shape PLC specification priorities across vertical markets.
- Manufacturing:Discrete assembly operations require high-speed sequencing and motion synchronization for conveyor systems and robotic workcells.
- Oil & Gas:Explosion-proof enclosures and extended temperature ratings address upstream drilling and downstream refining hazards.
- Automotive:Battery module welding and electric drivetrain assembly lines are expanding safety PLC deployment in Stuttgart and Michigan manufacturing corridors.
- Utilities:SCADA integration and cybersecurity hardening priorities dominate power generation and water treatment automation specifications.
Automotive leads on momentum; Manufacturing retains volume concentration.
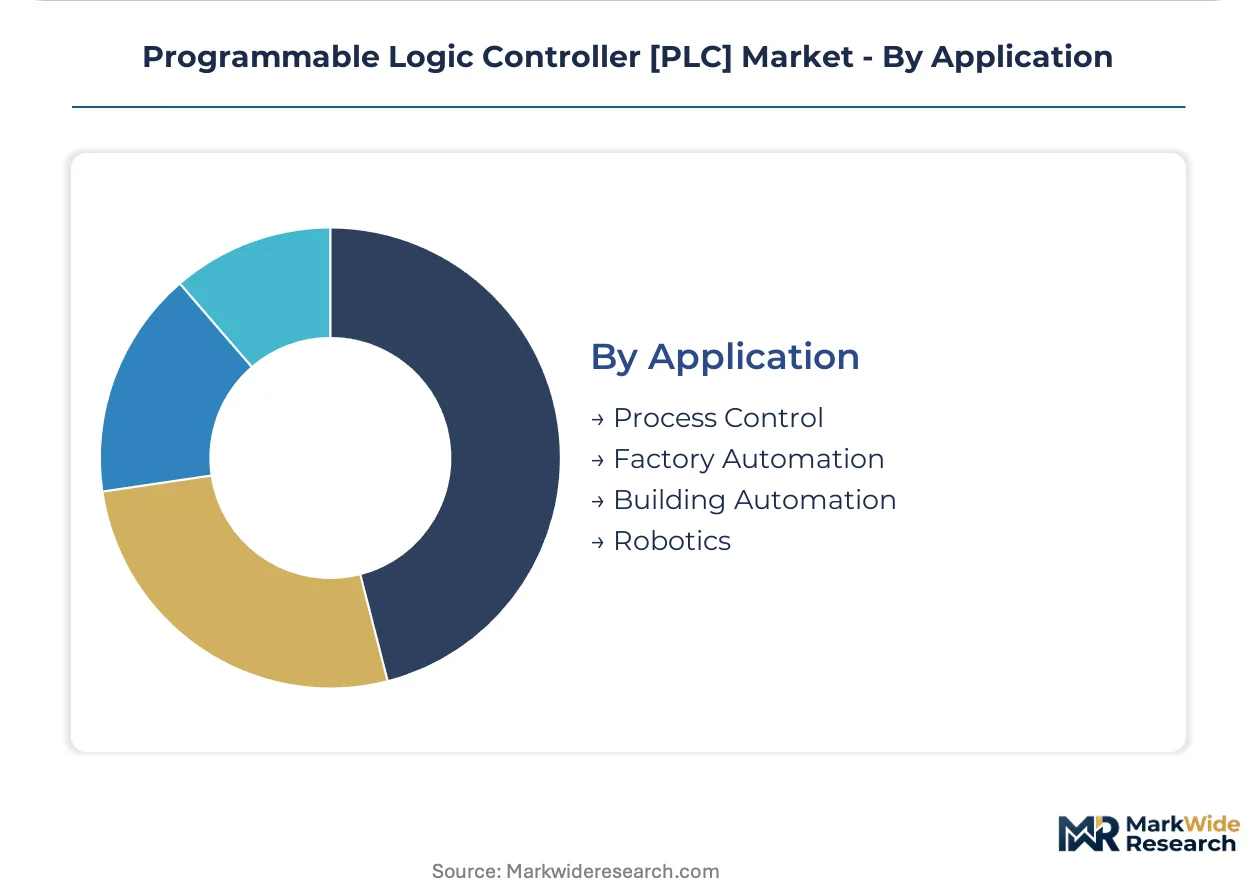
Application:
Control loop complexity and real-time determinism requirements separate process industries from discrete manufacturing automation needs.
- Process Control:Continuous feedback loops with PID regulation demand analog I/O precision and millisecond scan consistency. Chemical and pharmaceutical batch operations in Belgium and Ireland drive safety-certified PLC specifications under EU AI Act conformity requirements.
- Factory Automation:Discrete event sequencing and motion control coordination dominate automotive and consumer goods production lines.
- Building Automation:HVAC, lighting, and access control integration favors compact PLCs with BACnet compatibility over dedicated BMS controllers.
- Robotics:Multi-axis servo coordination and kinematic calculation offload requirements favor PLCs with embedded motion control coprocessors.
Process Control leads on specification value; Building Automation climbs fastest on cost-driven substitution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German engineering talent concentration anchors European PLC specification authority. Japanese mechatronics expertise sustains precision automation leadership. Chinese manufacturing scale drives cost-engineered compact unit volumes.
United States
Automotive battery manufacturing and pharmaceutical automation sustain demand. FDA 21 CFR Part 11 compliance obligations shape pharmaceutical and food manufacturing specifications. Michigan and Ohio manufacturing corridors deploy safety PLCs for electric drivetrain assembly lines.
Germany
Chemical process automation and automotive welding lines dominate procurement volumes. EU Green Deal energy efficiency mandates accelerate PLC refresh rates in motor control systems. Stuttgart and Bavarian industrial clusters lead safety PLC deployment for battery module production.
China
Electronics contract manufacturing and semiconductor fabrication drive compact PLC consumption. MIIT industrial digitalization policies accelerate smart factory retrofits. Yangtze River Delta and Pearl River Delta manufacturing hubs concentrate specification volumes for export-oriented production.
Japan
Robotics integration and precision electronics manufacturing sustain demand. METI manufacturing competitiveness programs subsidize automation upgrades. Kansai and Chubu industrial regions deploy motion-control-optimized PLCs for automotive component assembly.
India
Electronics manufacturing services and automotive component production expand specification opportunities. PLI scheme incentives for electronics and automotive sectors open greenfield automation investments. Gujarat and Tamil Nadu industrial corridors attract PLC vendors for smartphone and EV component assembly lines.
Programmable Logic Controller [PLC] Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the PLC value chain. Integrated electromechanical conglomerates with captive semiconductor fabrication dominate safety-critical and high-reliability segments. Pure-play automation specialists concentrate on software-defined control platforms and edge analytics integration. The competitive landscape reveals three strategic archetypes: diversified industrial technology groups, focused factory automation vendors, and emerging Asian cost-engineered suppliers. Consolidation activity concentrates on cybersecurity capability acquisition and vertical software stack integration.
Within the diversified industrial technology tier, Siemens AG and Schneider Electric SE exemplify European engineering heritage combined with process industry dominance. Rockwell Automation, Inc. occupies a position representing North American automotive OEM channel control. These three anchors demonstrate how geographic proximity to major manufacturing clusters confers specification influence in safety-critical applications.
| Leading Market Players |
|---|
| Siemens |
| Rockwell Automation |
| Mitsubishi Electric |
| Schneider Electric |
| Omron |
| ABB |
| Honeywell |
| Emerson |
| Delta |
| Others |
Value Network & Pricing Analysis
Ethernet/IP protocol migration is compressing hardware-software bundling economics while concentrating procurement leverage among automotive OEMs in Michigan and Stuttgart. This technology shift simultaneously erodes legacy fieldbus premium tiers and rewards vendors with captive semiconductor fabrication capabilities.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels reflects SIL certification grade and after-sales service bundling. Premium tiers attach to safety PLC architectures with IEC 61508 compliance, while economy tiers serve compact unit demand in Asian electronics manufacturing. Cost compression in standard tiers is intensifying because of microcontroller wafer fabrication bottlenecks in Taiwan. Building automation buyers exhibit highest price sensitivity; pharmaceutical batch operations show lowest.
Supply Chain Analysis
Microcontroller supply rests on Taiwanese wafer fabrication, German precision electromechanical components, and Chinese final assembly capacity. Critical inputs include ARM-based processors, industrial-grade capacitors, and Ethernet PHY chips. Single-source vulnerability concentrates in 300mm wafer production for safety-certified processors. Distribution runs through authorized distributor networks with technical support bundling in North American machine builder segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story. Battery module welding and electric drivetrain assembly lines are shifting procurement criteria toward SIL-rated safety specifications.
For Market Incumbents: Deepen firmware engineering capabilities for IEC 62443 cybersecurity compliance to counter embedded security talent scarcity. Expand safety PLC certification investments ahead of EU AI Act conformity backlog accumulation. Consolidate channel control over North American automotive OEMs through direct subscription diagnostics platforms.
For New Entrants and Emerging Players: Launch via cloud-connected remote service models targeting North American machine builder segments with unbundled lifecycle contracts. Penetrate India's Gujarat and Tamil Nadu industrial corridors where PLI scheme incentives create greenfield specification opportunities. Target compact PLC demand in building automation where BACnet compatibility gaps persist among established vendors.
For Investors and Strategic Acquirers: Valuations sit cheapest among pure-play automation specialists lacking captive semiconductor fabrication. Long-term viability over the next decade hinges on software-defined control platform differentiation. Acquisition targets should display vertical expertise in battery manufacturing automation. Watch Ethernet/IP migration velocity as inflection indicator for fieldbus incumbent displacement.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Microcontroller Supply | Captive wafer access insulates against Taiwan fabrication bottlenecks extending compact PLC lead times. |
| Safety Certification Pre-Investment | Early IEC 61508 SIL compliance ahead of EU AI Act deadlines secures pharmaceutical batch operation specifications. |
| Edge Analytics Platform Launch | Real-time machine learning inference at device level differentiates predictive maintenance offerings in semiconductor fabs. |
| Remote Diagnostics Channel Development | Cloud-connected technical support unbundles traditional distributor models in North American automotive tier-one networks. |
| Joint Venture in Indian Manufacturing Corridor | Local assembly partnerships in Gujarat capture PLI scheme benefits for smartphone and EV component automation. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combined with secondary validation. Interviews engaged automation system integrators, plant engineers at automotive OEMs, distributor technical sales leads, and pharmaceutical manufacturing compliance officers. Secondary sources included SEC 10-K filings from industrial technology groups, EU Machinery Directive harmonized standards documentation, and MIIT smart factory policy disclosures. Bottom-up unit demand estimates triangulated against top-down industrial automation capex projections.
Rate-of-change decomposition separated volume growth from price-mix effects across the analysis window. Segmentation dimensions modeled include product architecture type, protocol technology, end-use industry vertical, application control complexity, and regional regulatory cluster. CAGRs derived from polynomial trend fitting against historical industrial automation investment cycles. Industry-specific inputs incorporated semiconductor fab capacity utilization rates and automotive battery manufacturing facility announcement pipelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under Taiwan Strait logistics disruption or EU AI Act enforcement acceleration scenarios. Projections reflect assumptions about Ethernet/IP migration velocity and functional safety certification cost trajectories. A small set of triggers—including IEC 62443 compliance deadline shifts and India PLI scheme expansion—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
India Industrial Automation Market
Industrial Automation
Europe Automation Components Market
Industrial Automation
Global Motion Controller Market
Industrial Automation
Connected Worker Market
Industrial Automation
Europe Warehouse Automation Systems Market
Industrial Automation
Europe Process Automation Market
Industrial Automation
Machine Automation Controllers Market
Industrial Automation
Global Intelligent Process Automation Market
Industrial Automation
Parcel Sortation Systems Market
Industrial Automation
Europe Intralogistics Automation Market
Industrial Automation
Asia Industry 4.0 Market
Industrial Automation
North America Process Automation Market
Industrial Automation
Europe Sortation Systems Market
Industrial Automation
Industrial Embedded Systems Market
Industrial Automation
Embedded Automation Computers Market
Industrial Automation
North America and Europe Retail Automation Market