
 Colocation Edge Data Center Market | 2026-2036
Colocation Edge Data Center Market Size, Share, and Industry Trends Forecast 2026-2036
Colocation Edge Data Center Market Analysis
Market Context
Certified edge infrastructure engineering talent is collapsing across North America and Western Europe, forcing operators to automate deployment workflows and recruit from adjacent power systems disciplines. Equinix sustains geographic density through its metro-to-metro fiber strategy across dozens of global markets. Schneider Electric SE anchors the physical layer with integrated power and cooling portfolios purpose-built for constrained edge environments. Digital Realty Trust competes through hyperscale-adjacent edge nodes that bridge wholesale cloud on-ramps with local compute requirements.
Technical Definition and Structural Segments
Colocation edge data centers represent distributed facilities typically under 10 MW of critical IT load, positioned within 10-30 milliseconds of end users to host tenant-owned compute, storage, and networking equipment in shared environments with redundant power and precision cooling. These installations serve industrial automation, autonomous systems, and real-time analytics where centralized cloud latency violates application requirements. Wholesale colocation commands the dominant share of contracted MW as video streaming platforms and AI inference providers seek dedicated halls with operational control. Retail colocation retains margin strength in secondary metros where local enterprises require cabinet-scale presence without capital deployment. Hybrid colocation is gaining traction among financial services firms balancing legacy mainframe proximity with burst capacity to public cloud zones.
Regulatory Frame and Forward Outlook
The Federal Energy Regulatory Commission and state public utility commissions in the US shape interconnection queues and standby rate structures that directly impact edge site economics, while the EU F-Gas Regulation and national building codes in Germany and France constrain cooling technology selection and refrigerant choice. China's MIIT and NMPA administer data localization and cybersecurity review requirements that mandate domestic edge facility deployment for sensitive workloads. Stakeholders must monitor evolving carbon accounting rules under the EU CSRD and emerging state-level data center energy disclosure laws in the US, as these frameworks will increasingly determine where capital deploys and which cooling architectures qualify for permitting.
Market Dynamics
Telecommunications carriers are compressing interconnection distances to sub-10 millisecond thresholds for 5G network slicing and autonomous vehicle telemetry, forcing facility operators to secure real estate in metropolitan cores where power substations and dark fiber routes converge.
Growth Catalysts
- EU AI Act data residency mandates:France and Germany now require domestic processing for high-risk AI inference workloads, compelling cloud providers to establish certified edge nodes within national borders rather than routing through centralized hyperscale campuses.
- Industrial automation latency requirements:Manufacturing execution systems for precision robotics demand sub-5 millisecond response times that centralized cloud architectures cannot deliver, pulling compute capacity into plant-adjacent colocation facilities.
- Content delivery network densification:Video streaming platforms are contracting dedicated halls in secondary metros to cache 4K and emerging 8K content closer to subscriber concentrations, reducing transit costs and buffering incidents.
Market Restraints
- Copper and electrical steel input volatility:Switchgear and transformer lead times have extended to 52 weeks in some North American markets, constraining power infrastructure deployment timelines for greenfield edge sites.
- German F-Gas Regulation cooling constraints:The phasedown of hydrofluorocarbon refrigerants limits chiller technology selection in EU facilities, forcing operators toward higher-cost natural refrigerant systems with longer procurement cycles.
- Site acquisition competition:Data center operators, quick-service restaurant chains, and last-mile logistics firms are converging on identical urban infill parcels, inflating land premiums and zoning approval timelines.
Strategic Opportunities
- India data localization enforcement:The country's central bank and telecom regulator are tightening cross-border data flow restrictions for fintech and health-tech workloads, creating first-mover advantage for operators establishing Mumbai and Bengaluru presence.
- Liquid cooling convergence with AI inference:Direct-to-chip cooling architectures are penetrating sub-1 MW edge deployments previously served by air-cooled systems, opening premium pricing tiers for thermal management specialists.
- China MIIT cybersecurity review mandates:Domestic edge facility deployment is becoming compulsory for autonomous vehicle data and connected industrial equipment, insulating local operators from foreign competition.
Industry Challenges
- Certified edge infrastructure engineering scarcity:North American and Western European operators are recruiting power systems technicians from utility and renewable energy sectors to backfill collapsing talent pipelines for mission-critical facility operations.
- Utility interconnection queue congestion:Standby service agreements in Texas, Virginia, and California markets face 18-36 month delays, compressing project IRRs and forcing pre-leasing commitments before breaker closure.
Report Scope
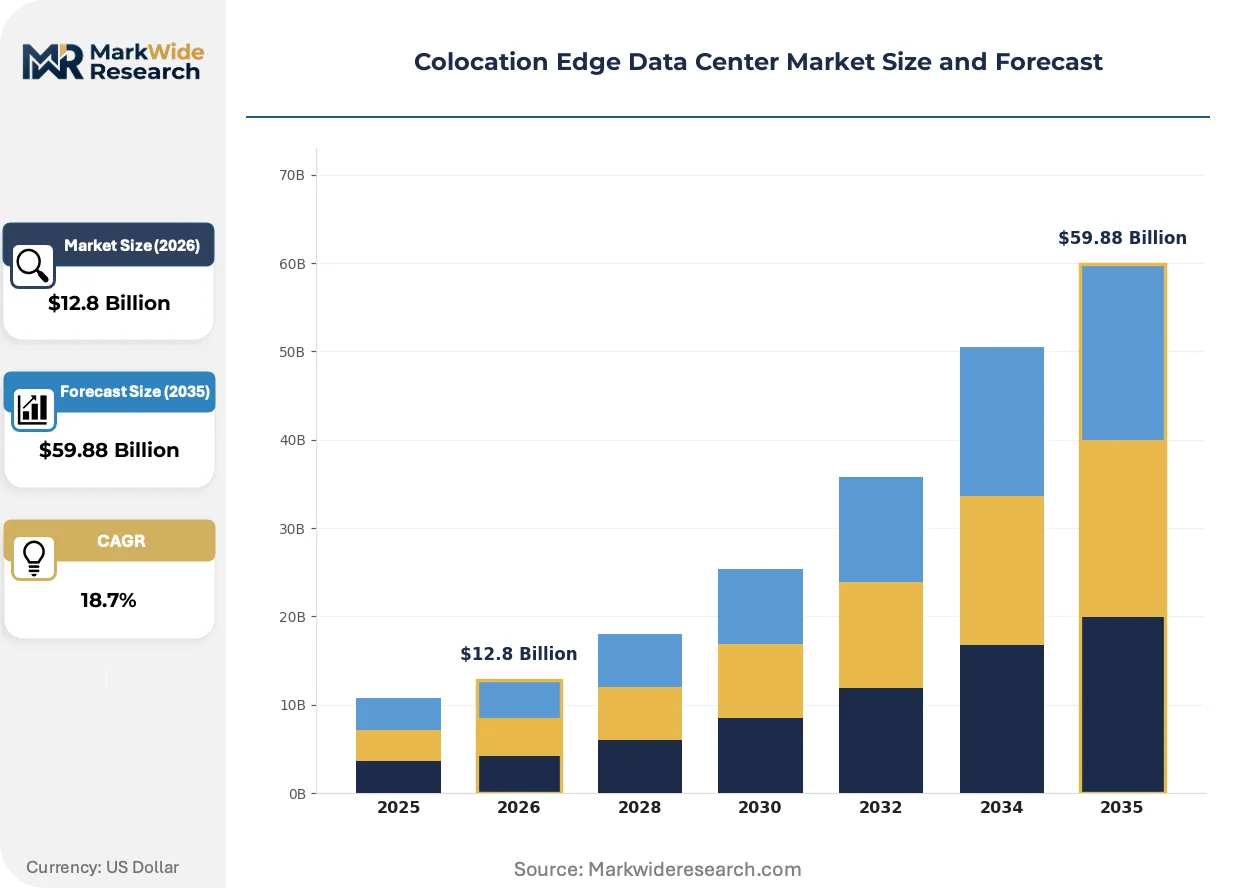
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Colocation Edge Data Center Market |
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $59.88 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Retail Colocation, Wholesale Colocation, Hybrid Colocation, Managed Hosting Deployment Model: On-Premises, Off-Premises, Multi-Cloud, Private Cloud End User: Telecommunications, Healthcare, Media & Entertainment, Government Technology: Hyper-Converged Infrastructure, Software-Defined Networking, Edge Computing, Network Function Virtualization |
| Companies Covered | Vertiv Group Corp, NTT Communications Corporation, Equinix, CyrusOne, KDDI Corporation, Digital Realty Trust, Schneider Electric SE, EdgeConneX, China Telecom Global Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Colocation Edge Data Center Market Emerging Trajectories
Physical infrastructure architectures are fragmenting into modular, factory-integrated systems that compress deployment timelines from months to weeks. Three developments are compressing conventional build methodologies.
Prefabricated modular data centers are displacing stick-built construction for sub-5 MW edge deployments. Telecommunications carriers and industrial automation firms are specifying skid-mounted power and cooling modules for 60-day installation cycles. The approach is displacing general contractor-led site construction in secondary metros where speed-to-revenue dominates total cost of ownership calculations.
The EU F-Gas Regulation is accelerating natural refrigerant adoption across cooling portfolios. The phasedown schedule for synthetic hydrofluorocarbons is forcing equipment refresh cycles earlier than technical obsolescence would dictate. Edge operators in Germany and France are responding with ammonia and CO2-based chiller specifications that require specialized maintenance protocols and safety zone expansions.
Consumption-based power contracting is altering tenant-operator relationships in multi-tenant facilities. Video streaming and AI inference providers are negotiating metered electricity pass-through structures rather than flat-rate cabinet pricing, transferring wholesale market volatility exposure while capturing demand response revenue streams. This restructuring is most visible in Texas and California markets where nodal pricing volatility creates arbitrage opportunities for flexible compute loads.
Colocation Edge Data Center Market Segmentation
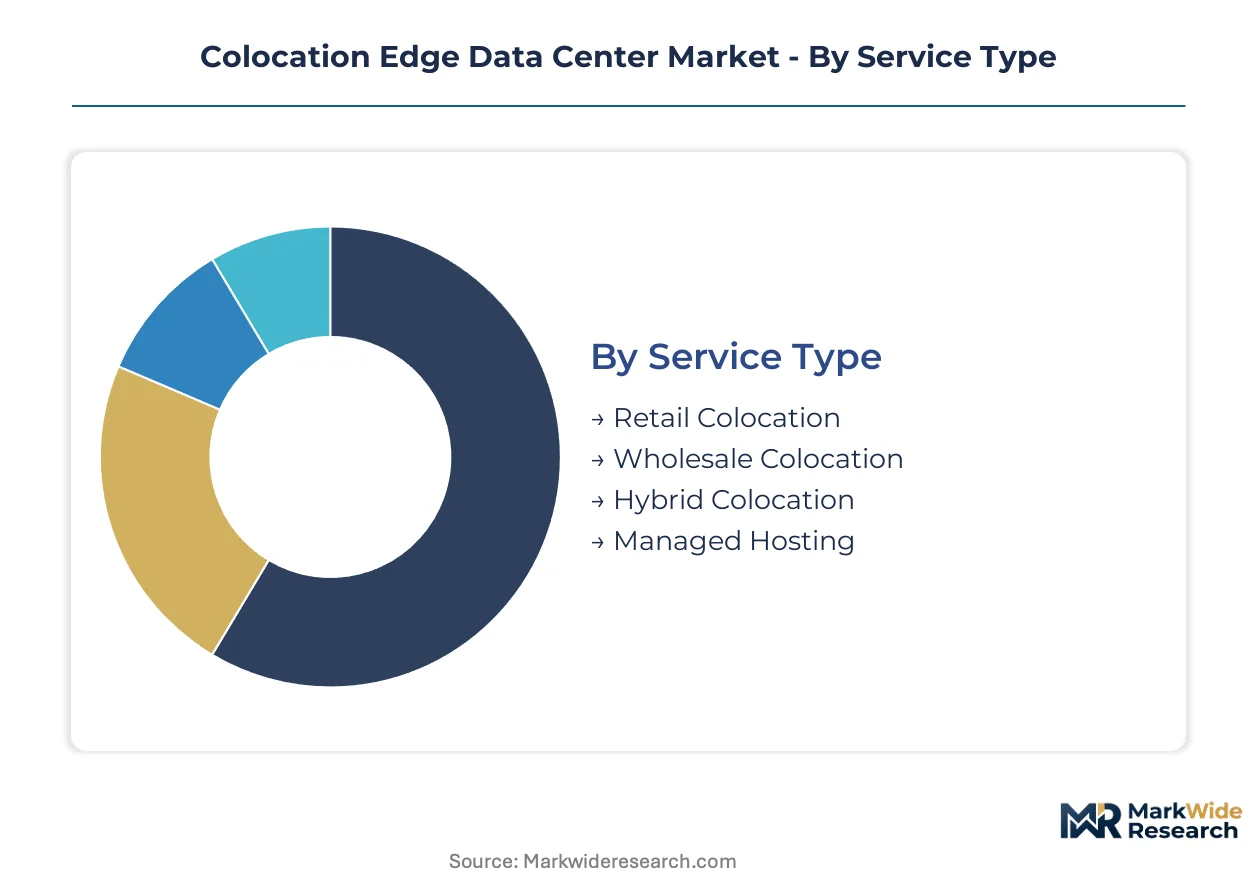
Edge data center segmentation reveals how facility economics, regulatory exposure, and workload latency requirements fragment the addressable market. Understanding these dimensions clarifies where capital deploys and which architectural approaches capture premium returns.
Service Type:
EU F-Gas Regulation refrigerant constraints and national data sovereignty rules in France, Germany, and India are reshaping service tier economics, with compliance costs concentrating differently across contract structures.
- Wholesale Colocation:Dedicated halls exceeding 500 kW per tenant with operational control retained by the customer. Video streaming platforms and AI inference providers in the United States and China are contracting these spaces to cache 4K content and process low-latency workloads where hyperscale cloud latency violates application requirements.
- Retail Colocation:Cabinet-scale deployments under 100 kW with shared infrastructure and standardized SLAs. Local enterprises in secondary German metros and Indian cities are adopting this model to satisfy RBI data localization mandates without capital deployment into owned facilities.
- Hybrid Colocation:Financial services firms in New York and London are balancing legacy mainframe proximity with burst capacity to public cloud zones through this architecture, navigating both SEC disclosure requirements and FCA operational resilience rules.
- Managed Hosting:Operator-managed server and storage infrastructure with full operational outsourcing. Healthcare providers facing HIPAA compliance complexity in Texas and California markets are gravitating toward this hands-off model.
Wholesale colocation handles the majority of throughput; hybrid colocation is climbing the fastest on share as financial services firms restructure legacy estates.
Deployment Model:
Cost tier differentiation separates capex-intensive owned infrastructure from opex-optimized consumption models, with utility interconnection queue delays in Texas and Virginia compressing returns for capital-heavy approaches.
- Off-Premises:Third-party colocation facilities where tenants lease space and power rather than owning real estate. Telecommunications carriers deploying 5G network slicing in Chicago and Atlanta are standardizing on this model to accelerate speed-to-market.
- Multi-Cloud:Architectures spanning AWS, Azure, and GCP with edge presence for latency-sensitive workloads. Industrial automation firms in Shenzhen and Shanghai are adopting this approach to satisfy MIIT data localization requirements while retaining cloud elasticity.
- On-Premises:Customer-owned facilities with full infrastructure control. Autonomous vehicle developers in Arizona and Nevada are maintaining these deployments for telemetry processing where sub-5 millisecond response times are non-negotiable.
- Private Cloud:Single-tenant virtualized environments within colocation facilities. Government agencies in Washington DC and Brussels are specifying this model to satisfy FedRAMP and EU cybersecurity certification requirements.
Off-premises deployments absorb the dominant share of new capacity; multi-cloud configurations are expanding most quickly as workload portability becomes a procurement priority.
End User:
Application-specific latency thresholds and data residency obligations are concentrating demand from sectors with the most stringent performance and compliance requirements.
- Telecommunications:Carriers compressing interconnection distances to sub-10 millisecond thresholds for 5G network slicing. Verizon and AT&T expansion in Dallas, Miami, and Seattle is driving demand for metro core facilities where dark fiber routes converge.
- Media & Entertainment:Video streaming platforms caching 4K and emerging 8K content closer to subscriber concentrations. Netflix and Disney+ deployments in São Paulo and Mexico City are reducing transit costs and buffering incidents in Latin American markets.
- Healthcare:Hospital systems and health-tech platforms processing patient data under HIPAA and GDPR constraints. Mayo Clinic and Cleveland Clinic networks in Minnesota and Ohio are establishing edge presence for real-time imaging analytics.
- Government:Federal, state, and municipal agencies with classified and sensitive workload requirements. Defense and intelligence community demand in Virginia and Maryland is insulating certain operators from commercial pricing pressure.
Telecommunications anchors volume commitment; media and entertainment is gaining share fastest as streaming bitrate escalation accelerates caching infrastructure deployment.
Technology:
Supply concentration among integrated infrastructure vendors is forcing rapid standardization decisions, with Schneider Electric and Vertiv portfolios dominating power and cooling specification.
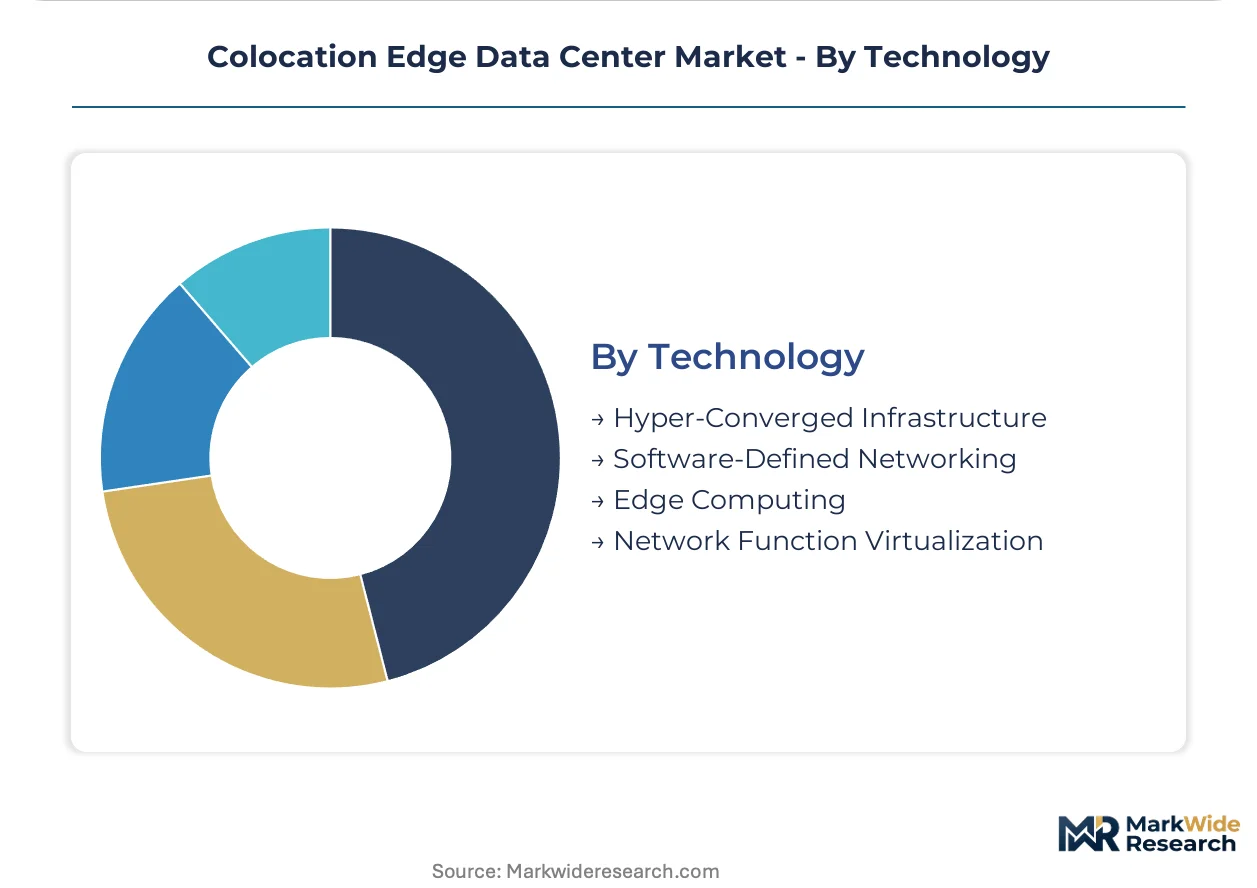
- Edge Computing:Distributed compute nodes positioned within 10-30 milliseconds of end users. Manufacturing execution systems for precision robotics in Stuttgart and Wolfsburg are pulling this capacity into plant-adjacent facilities.
- Hyper-Converged Infrastructure:Integrated compute, storage, and networking in single appliances. Mid-market enterprises in Sydney and Melbourne are adopting this approach to collapse deployment timelines without specialized engineering talent.
- Software-Defined Networking:Virtualized network control decoupled from physical hardware. Content delivery networks in Amsterdam and Frankfurt are leveraging this technology to optimize traffic routing across distributed edge nodes.
- Network Function Virtualization:Virtualized carrier network services replacing proprietary hardware. Telefónica and Deutsche Telekom deployments in Madrid and Munich are accelerating this transition for cost and agility advantages.
Edge computing infrastructure handles the majority of deployed capacity; hyper-converged systems are the fastest mover on share as talent scarcity forces architectural simplification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FERC interconnection queue management and state utility commission rate structures anchor United States edge deployment economics, while EU F-Gas Regulation and national data sovereignty rules reshape European facility specifications. Facility operators concentrate in metropolitan cores where power substations and dark fiber routes converge.
United States
Telecommunications carriers compress interconnection distances to sub-10 millisecond thresholds for 5G network slicing and autonomous vehicle telemetry. FERC and state public utility commissions shape standby rate structures and interconnection queues that directly impact site economics. Dallas, Miami, and Seattle metro cores attract Verizon and AT&T expansion where dark fiber routes converge with available substation capacity.
Germany
Industrial automation firms demand plant-adjacent facilities for manufacturing execution systems requiring sub-5 millisecond response times. The EU F-Gas Regulation phasedown of hydrofluorocarbon refrigerants constrains cooling technology selection, forcing operators toward ammonia and CO2-based systems. Stuttgart and Wolfsburg clusters pull compute capacity into precision robotics corridors with specialized maintenance protocols.
China
MIIT and NMPA administer data localization and cybersecurity review requirements mandating domestic edge facility deployment for sensitive workloads. Industrial automation firms in Shenzhen and Shanghai adopt multi-cloud architectures to satisfy data residency while retaining elasticity. Yangtze River Delta and Pearl River Delta corridors concentrate autonomous vehicle data and connected industrial equipment processing.
India
RBI and TRAI tighten cross-border data flow restrictions for fintech and health-tech workloads, creating first-mover advantage for Mumbai and Bengaluru presence. The central bank's data localization enforcement compels domestic processing for payment systems and patient records. Maharashtra and Karnataka sub-regions anchor initial operator deployments as compliance deadlines accelerate.
France
The EU AI Act now requires domestic processing for high-risk AI inference workloads, compelling cloud providers to establish certified edge nodes within national borders. ANSM and CNIL data governance frameworks layer additional compliance requirements onto facility specifications. Île-de-France and Auvergne-Rhône-Alpes clusters concentrate financial services and healthcare AI deployments seeking proximity to legacy mainframe infrastructure.
Colocation Edge Data Center Market Vendor Landscape
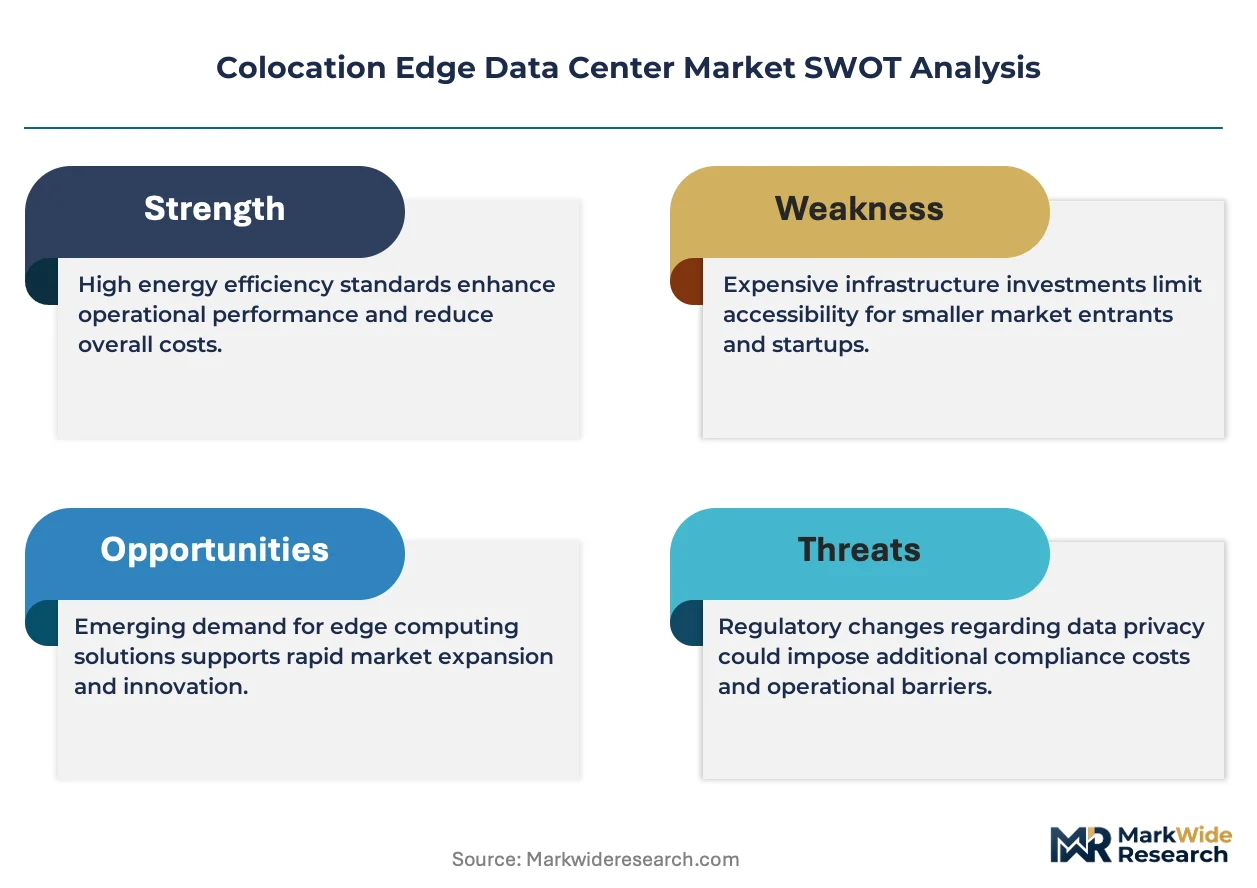
Technology leadership and cost leadership are held by different player archetypes across the colocation edge data center market. The vendor base organizes around three strategic groupings: integrated infrastructure specialists with power and cooling portfolios, facility operators with metro-to-metro fiber density, and telecommunications carriers with 5G network slicing requirements. Dominant competitive moves include geographic densification through pre-leased capacity commitments and modular deployment methodologies that compress installation cycles.
Among integrated infrastructure providers, Schneider Electric SE anchors the physical layer with factory-integrated power and cooling systems purpose-built for constrained edge environments. Vertiv Group Corp occupies a comparable position in thermal management and critical power distribution. Equinix represents the facility operator archetype with metro-to-metro fiber strategies spanning dozens of markets.
| Leading Market Players |
|---|
| Vertiv Group Corp |
| NTT Communications Corporation |
| Equinix |
| CyrusOne |
| KDDI Corporation |
| Digital Realty Trust |
| Schneider Electric SE |
| EdgeConneX |
| China Telecom Global Limited |
| Others |
Supply Flow & Price Mechanics
Fifty-two-week lead times for switchgear and transformers in North American markets compress deployment velocity and concentrate pricing power among integrated infrastructure vendors with captive component inventories. This supply constraint reshapes contract structures as operators absorb escalation risk or pass through material volatility via indexed power pricing.
Pricing Analysis
Texas and California nodal pricing spreads create three-tier contract differentiation across premium metered pass-through, standard flat-rate cabinet, and economy bulk power structures. Wholesale colocation buyers with flexible compute loads capture demand response arbitrage while retail tenants in secondary German metros face F-Gas Regulation compliance premiums embedded in cooling surcharges. Cost compression in air-cooled edge tiers intensifies as prefabricated modular systems displace stick-built construction timelines. Financial services firms in New York and London exhibit lowest price sensitivity given SEC and FCA operational resilience mandates, whereas mid-market enterprises in Sydney and Melbourne drive hardest bargain on standardized SLAs.
Supply Chain Analysis
Transformer and electrical steel inventories stretching to 52 weeks in Virginia and Texas markets expose procurement fragility across greenfield edge deployments. Manufacturing concentrates in China, South Korea, and Germany for power distribution equipment, with cooling systems drawing from ammonia and CO2 refrigeration specialists in France and Italy. Single-source vulnerability concentrates in semiconductor-based power conversion modules sourced from Taiwan and Japan. Distribution runs through direct OEM relationships for hyperscale-adjacent operators and tiered distributor networks serving secondary metro retail colocation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Edge data center infrastructure sits in early-cycle expansion as EU AI Act data residency mandates and 5G network slicing requirements accelerate facility deployment ahead of mature saturation curves.
For Market Incumbents: Shield metro-to-metro fiber density advantages through pre-leased capacity commitments in Dallas, Miami, and Seattle corridors before utility interconnection queues extend beyond 36 months. Acquire certified edge infrastructure engineering talent from utility and renewable energy sectors to backfill collapsing pipelines. Vertical integration into factory-integrated power and cooling modules compresses 60-day installation cycles that general contractor-led construction cannot match.
For New Entrants and Emerging Players: Anchor in Mumbai and Bengaluru sub-markets where RBI data localization enforcement creates first-mover advantage before compliance deadlines harden. Target plant-adjacent industrial automation corridors in Stuttgart and Wolfsburg where sub-5 millisecond manufacturing execution system requirements outpace incumbent facility footprints. Lead with liquid cooling convergence expertise for sub-1 MW AI inference deployments previously served by air-cooled systems.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across prefabricated modular sub-segments as factory-integrated systems displace site-built construction. Long-term viability centers on operators with utility interconnection queue priority in Texas, Virginia, and California markets. Acquisition target archetype: regional specialists with dark fiber route convergence and substation-proximate real estate in secondary metros. Signal to watch: standby service agreement execution timelines as leading indicator of project IRR compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Prefabricated Modular Deployment | Schneider Electric and Vertiv factory-integrated systems compress 60-day installation cycles in secondary metros. |
| Natural Refrigerant Cooling Transition | Ammonia and CO2-based chillers satisfy EU F-Gas Regulation phasedown in Germany and France facilities. |
| Metro-to-Metro Fiber Densification | Equinix strategy spans Dallas, Miami, and Seattle where dark fiber routes converge with substation capacity. |
| Consumption-Based Power Contracting | Metered electricity pass-through structures transfer wholesale market volatility to flexible compute loads in Texas. |
| Certified Edge Engineering Recruitment | Operators backfill talent pipelines recruiting power systems technicians from utility and renewable energy sectors. |
Methodological Framework
A spread of perspectives from data center facility operators, telecommunications carrier network planners, industrial automation procurement leads, and hyperscaler cloud infrastructure executives converged on the working assumptions. Primary interviews combined with secondary validation from FERC interconnection filings, EIA electricity market data, EU F-Gas Regulation implementation guidance, and MIIT cybersecurity review circulars. Bottom-up capacity deployment tracking triangulated against top-down capex disclosure analysis across the projection horizon.
Segmentation dimensions modeled span service type, deployment model, end user sector, and cooling technology architecture. CAGRs derived from facility construction pipeline analysis, tenant contract velocity, and power infrastructure procurement cycle data. Analytical framework incorporates utility interconnection queue dynamics, refrigerant phasedown compliance costs, and data localization enforcement timelines as industry-specific forecast inputs.
Material uncertainties — utility standby service agreement delays, copper and electrical steel input volatility, and evolving carbon accounting rules under EU CSRD — sit outside the modeled envelope. Forecasts reflect assumptions documented in facility operator interviews and regulatory filing analysis. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Blade Server Market
Data Center Infrastructure
Data Center Rack Power Distribution Unit Market
Data Center Infrastructure
Data Center Monitoring Systems Market
Data Center Infrastructure
Vietnam Data Center Physical Security Market
Data Center Infrastructure
Data Center Infrastructure Management Market
Data Center Infrastructure
United States Data Center Market
Data Center Infrastructure
North America Data Center Rack Market
Data Center Infrastructure
Germany Data Center Construction Market
Data Center Infrastructure
Server Station Market
Data Center Infrastructure
Converged Data Center Infrastructure Market
Data Center Infrastructure
Fiber Management Systems Market
Data Center Infrastructure
Russia Data Center Construction Market
Data Center Infrastructure
Water Leak Detection System for Server Rooms and Data Centers Market
Data Center Infrastructure
Sweden Data Center Power Market
Data Center Infrastructure
New York Data Center Market
Data Center Infrastructure
Asia-Pacific Data Center Infrastructure Management Market