
 GPON WIFI6 Home Gateway Market | 2026-2036
GPON WIFI6 Home Gateway Market Size, Share, and Industry Trends Forecast 2026-2036
GPON WIFI6 Home Gateway Market Insights
Subscription-based firmware management is hardening as the primary revenue layer beyond hardware shipments. Huawei leverages its integrated chip-to-cloud stack to control upgrade cycles across carrier contracts. Nokia anchors its position through R&D intensity in fiber-access silicon, while ZTE competes on manufacturing scale for emerging market tenders.
A GPON WIFI6 home gateway combines a Gigabit Passive Optical Network optical network terminal with an IEEE 802.11ax wireless access point, typically supporting 1024-QAM modulation and OFDMA scheduling across 2.4 GHz and 5 GHz bands to deliver symmetric gigabit throughput to residential subscribers. Residential deployments dominate volume, though commercial segments concentrate margin pools where managed service attach rates run higher. Hybrid connectivity configurations are gaining preference over pure wireless as ISPs seek deterministic latency for video and voice traffic.
FCC broadband labeling rules and EU CE marking requirements under the Radio Equipment Directive shape product certification timelines and RF power specifications for gateway manufacturers. China's MIIT enforces domestic encryption standards that influence chipset selection for vendors serving that market. Stakeholders must monitor spectrum reallocation proceedings and energy efficiency mandates as these will determine which hardware architectures remain compliant without costly redesigns.
Market Dynamics
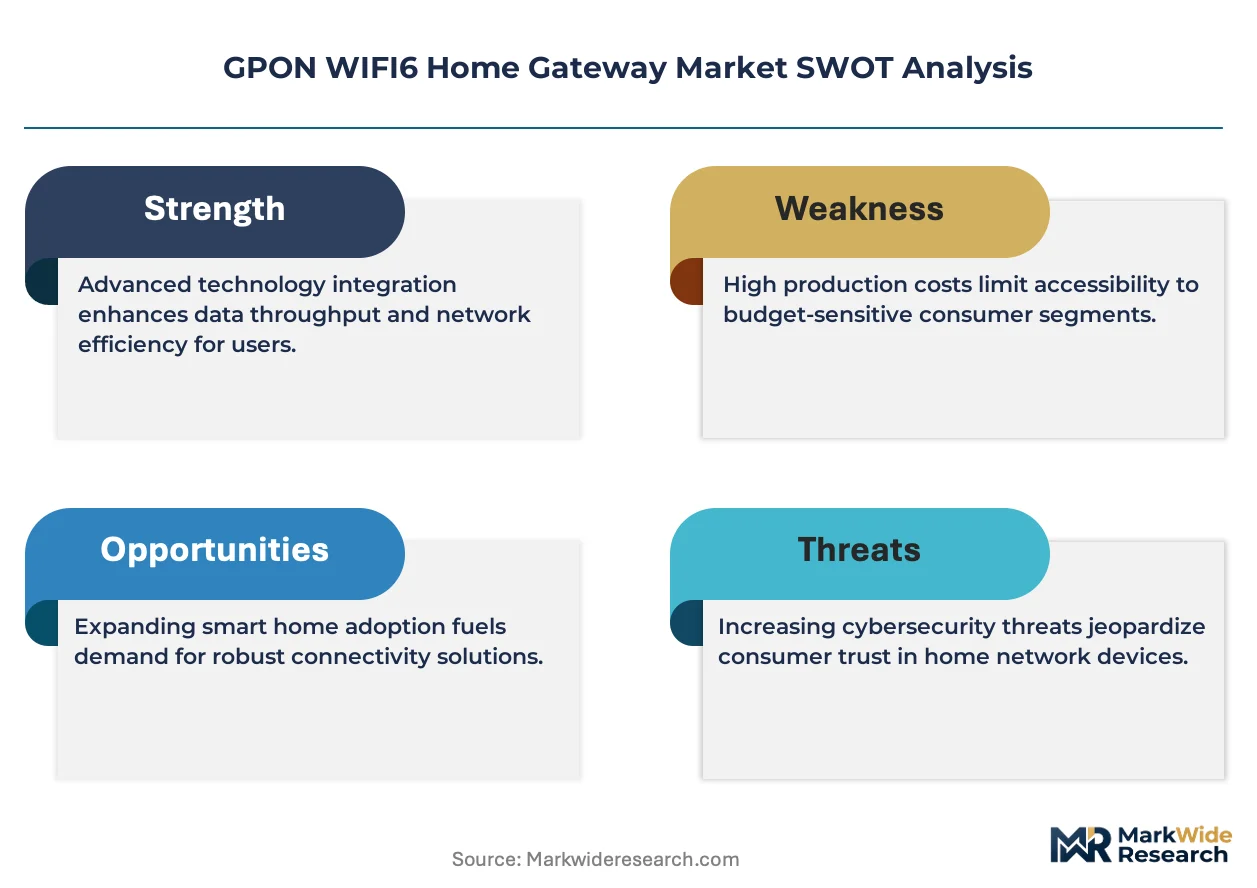
Subscription-based firmware management is hardening as the primary revenue layer beyond hardware shipments, with carriers locking upgrade cycles into multi-year service contracts that reshape vendor cash flow patterns.
Growth Catalysts
- FTTH Deployment Mandates:Government broadband programs in India, Brazil, and Indonesia are accelerating fiber-to-the-home rollouts that require gateway replacements at subscriber premises.
- WiFi 6 Spectrum Efficiency:OFDMA scheduling and 1024-QAM modulation enable gigabit symmetric throughput over existing copper infrastructure, reducing ISP capex per subscriber connection.
- Multi-Dwelling Unit Standards:China's MIIT encryption requirements and EU CE marking under the Radio Equipment Directive are mandating gateway refresh cycles in dense residential installations.
Market Restraints
- Optical Chip Supply Concentration:GPON MAC and laser driver silicon fabrication concentrates among three foundry sources in Taiwan and South Korea, creating single-source vulnerability for volume contracts.
- RF Component Cost Volatility:Gallium arsenide and silicon germanium substrate prices fluctuate with 5G base station demand, compressing gateway margin structures.
- Legacy GPON Interoperability:ITU-T G.984 standard equipment remains embedded in carrier networks, forcing dual-mode silicon that increases BOM complexity.
Strategic Opportunities
- Rural Broadband Subsidies:US FCC Rural Digital Opportunity Fund and EU Gigabit Infrastructure Act are unlocking tender volumes for cost-optimized gateway configurations.
- Managed WiFi Services:Cloud-based parental controls and security monitoring create attach-rate expansion beyond hardware shipment economics.
- WiFi 7 Pre-Positioning:Early 320 MHz channel support and 4K-QAM modulation capability in silicon designs are converging with carrier 10G-PON upgrade timelines to capture forward replacement cycles.
Industry Challenges
- Firmware Security Certification:Common Criteria EAL4+ and ISO/IEC 15408 evaluation timelines extend 14-18 months, delaying product launches for government and enterprise segments.
- Legacy HFC Integration:Cable operators deploying fiber overlays require hybrid gateway architectures that bridge DOCSIS and GPON signaling, complicating software stack maintenance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GPON WIFI6 Home Gateway Market |
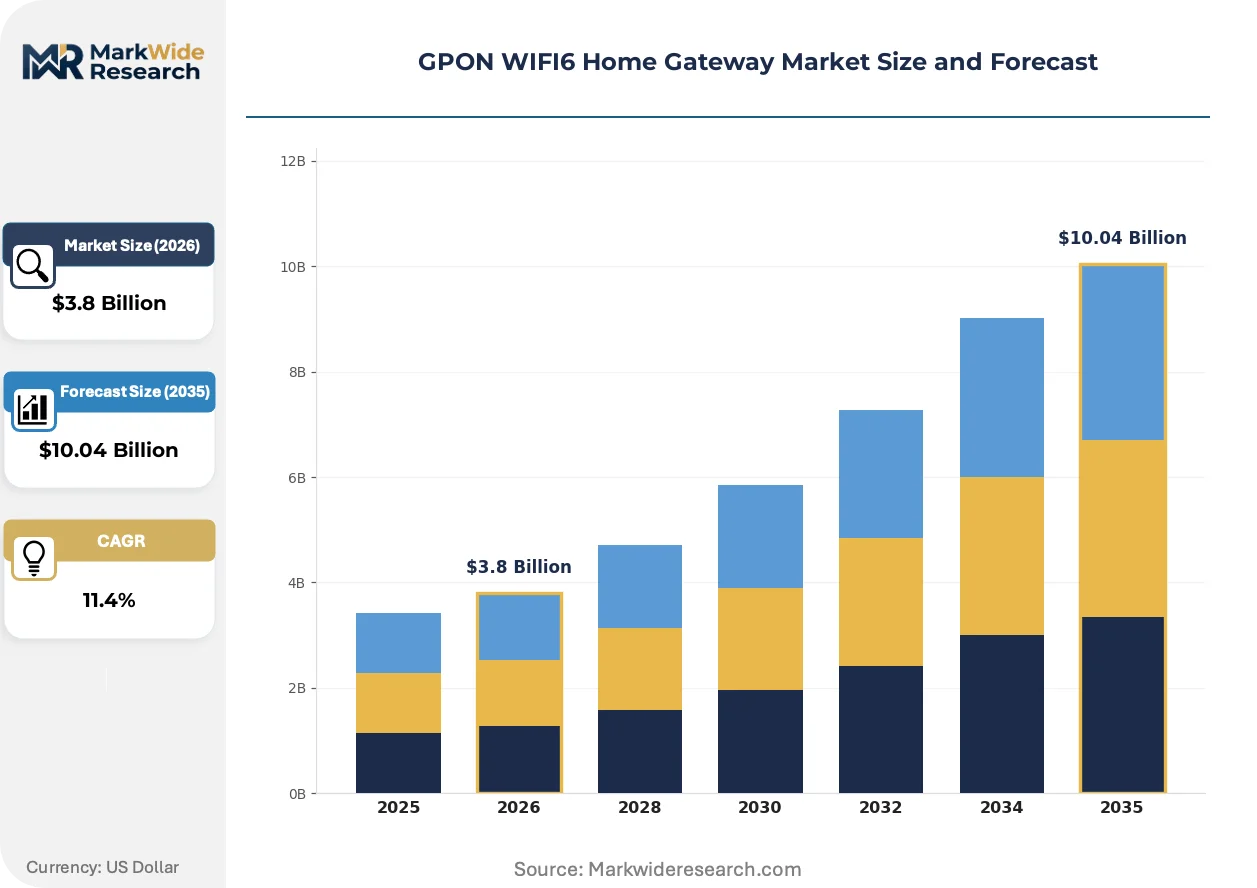
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Residential, Commercial, Industrial, SMB Connectivity: Wired, Wireless, Hybrid, Ethernet Deployment: On-Premise, Cloud-Based, Managed, SaaS Customer Type: End Users, ISPs, Enterprises, Retailers |
| Companies Covered | CommScope, AVM, Huawei, Actiontec Electronics, FiberHome Telecommunication Technologies, ZTE, Sercomm, Zyxel Communications, Nokia, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GPON WIFI6 Home Gateway Market Trends and Innovations
Open-source operating systems on gateway platforms are displacing proprietary firmware stacks, enabling carrier-specific feature differentiation without silicon redesigns.
Multi-AP mesh coordination is converging with GPON gateway baseband processing, allowing ISPs to manage whole-home coverage through a single subscriber-facing interface. Tier-1 carriers in Germany and Japan are deploying these integrated systems for premium tier subscribers. The architecture compresses customer support ticket volumes by eliminating handoff failures between router and extender units.
EU F-Gas Regulation restrictions on fluorinated greenhouse gases are forcing thermal design changes in gateway enclosures, with manufacturers shifting to vapor chamber and graphite sheet solutions. The mandate affects power dissipation specifications for 4x4 and 8x8 MIMO configurations. Asian ODMs serving European carrier brands are requalifying heatsink suppliers to maintain CE marking compliance.
Direct-to-consumer replacement channels are fragmenting traditional carrier-locked distribution, with retail availability of unlocked WiFi 6 gateways rising through electronics chains in Mexico and Southeast Asia. E-commerce platforms now carry certified units that bypass operator provisioning workflows. This pattern is most visible in markets where prepaid fiber services decouple connectivity from CPE procurement.
GPON WIFI6 Home Gateway Market Segmentation
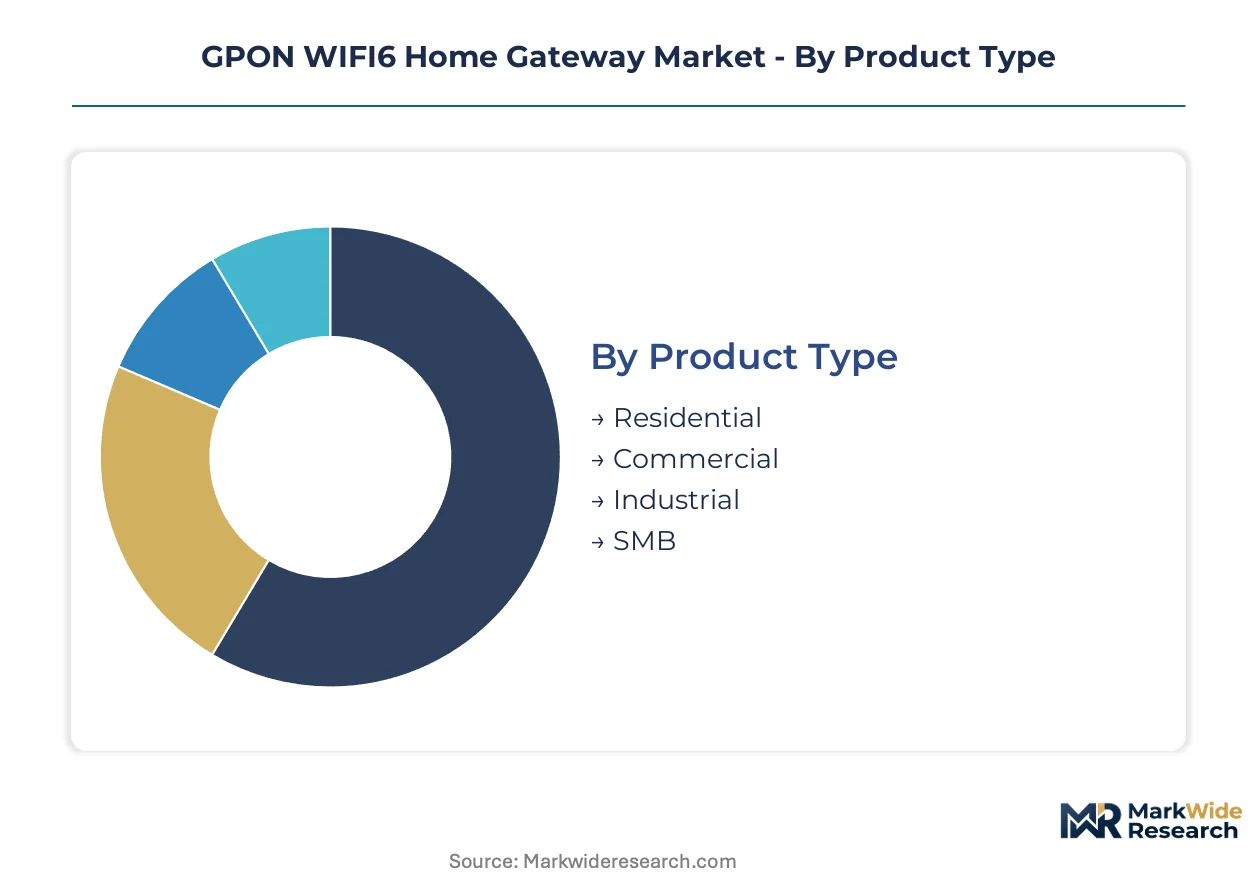
GPON WiFi6 gateway procurement patterns diverge sharply across installation environments, with carrier-managed bulk deployments operating on fundamentally different upgrade cycles than retail-direct or enterprise-customized configurations. Understanding these segment boundaries clarifies where silicon customization, firmware service attach rates, and certification requirements concentrate.
Product Type:
Replacement cycles vary dramatically between subscriber premises and commercial installations, shaping BOM optimization priorities and service contract structures.
- Residential:Units integrate 2.4 GHz and 5 GHz OFDMA basebands with GPON MAC silicon in single-enclosure designs. India's BharatNet tenders and Brazil's Fibra Ótica program are driving multi-million-unit annual volumes through state-backed carrier aggregation.
- Commercial:Managed WiFi overlays with cloud-based AP coordination dominate hospitality and retail deployments. These configurations prioritize deterministic latency for payment terminals and video surveillance backhaul over raw throughput metrics.
- Industrial:Hardened enclosures with extended temperature ratings serve factory automation and utility substation networks. China's MIIT mandates domestic encryption modules for critical infrastructure placements.
- SMB:Cost-optimized 2x2 MIMO variants balance port density against thermal constraints. Southeast Asian ISPs bundle these with prepaid fiber plans for small retail and food service subscribers.
Volume placements concentrate in Residential; the faster expansion belongs to Commercial.
Connectivity:
Physical layer configurations determine RF front-end complexity and thermal design requirements, with hybrid architectures gaining preference as ISPs hedge against pure-wireless congestion.
- Hybrid:Simultaneous GPON termination and 802.11ax mesh backhaul enable whole-home coverage without additional power outlets. German carriers Deutsche Telekom and Vodafone deploy these for premium tier subscribers seeking seamless handoffs.
- Wireless:Standalone WiFi 6 access points without fiber termination serve MDU extension scenarios and rural satellite backhaul installations. Indonesia's Palapa Ring fiber expansion is creating demand for wireless-only satellite gateway pairings.
- Wired:Ethernet-only configurations persist in data center out-of-band management and legacy enterprise wiring closet refreshes.
- Ethernet:Copper-based LAN aggregation ports support IPTV set-top box and IP phone tethering in European carrier bundles.
Hybrid architectures command the highest service attach rates; Wireless SKUs are climbing fastest in emerging market MDU overlays.
Deployment:
Delivery models reshape vendor cash flow timing, with cloud-orchestrated units converting hardware margins into recurring firmware subscription streams.
- Managed:Carrier-controlled provisioning and remote diagnostics dominate North American and Western European markets. These contracts lock upgrade cycles into 36-48 month refresh schedules with automatic security patch distribution.
- Cloud-Based:Zero-touch configuration via TR-069 and USP protocols enables ISP support cost reduction. Japanese carriers NTT and KDDI have standardized on cloud-first deployment for residential gateway fleets exceeding ten million units.
- On-Premise:Self-hosted controller installations persist in defense and financial services segments with data sovereignty requirements.
- SaaS:Per-subscriber licensing for parental controls and security monitoring is penetrating Latin American prepaid fiber markets.
Managed deployments capture the greatest firmware service value; Cloud-Based configurations are expanding most quickly in Asia-Pacific carrier consolidations.
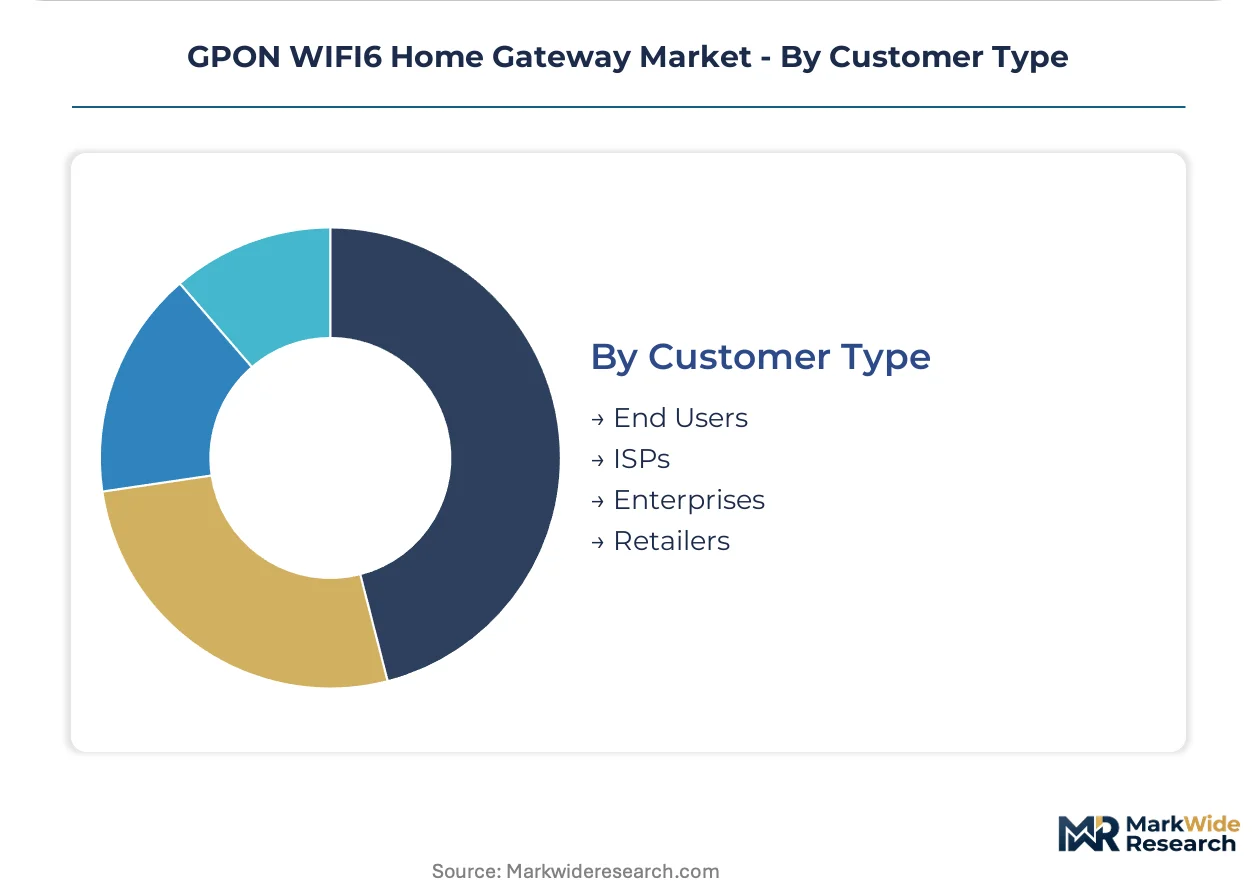
Customer Type:
Procurement authority fragmentation between connectivity providers and end users creates parallel distribution channels with divergent certification and pricing structures.
- ISPs:Volume tenders specify custom firmware builds, branded enclosures, and multi-year security update commitments. Brazil's Anatel certification requirements add 4-6 months to ISP-directed product qualification timelines.
- End Users:Retail-direct purchases through e-commerce platforms bypass operator provisioning workflows. Mexico's Mercado Libre and Southeast Asia's Shopee now carry CE-marked unlocked units for prepaid fiber subscribers.
- Enterprises:Custom security policy enforcement and captive portal integration drive higher-margin professional services attachment.
- Retailers:Electronics chains in India and Indonesia aggregate demand for unbranded white-label configurations serving local ISP partnerships.
ISP contracts anchor hardware volume; End User channels are gaining share fastest where prepaid fiber decouples CPE from subscription pricing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China manufactures the majority of GPON WiFi 6 gateway silicon and finished units, while India and Brazil absorb the largest subscriber deployment volumes through state-backed fiber programs. This production-consumption split shapes regional vendor strategies and certification priorities.
China
MIIT encryption mandates and domestic semiconductor subsidies accelerate gateway refresh cycles across state-owned carrier fleets. The Yangtze River Delta cluster around Shanghai and Suzhou concentrates ODM manufacturing for Huawei and ZTE export contracts. Shenzhen-based design houses are pre-positioning WiFi 7 silicon for 10G-PON upgrade timelines.
United States
FCC Rural Digital Opportunity Fund subsidies unlock tender volumes for cost-optimized gateway configurations in underserved counties. Broadband labeling rules under 47 CFR § 8.1 mandate standardized performance disclosure, extending product qualification timelines. Texas and California data centers drive demand for hardened gateway variants in fiber-backhaul edge deployments.
India
BharatNet Phase III tenders specify GPON WiFi 6 gateways for rural fiber-to-the-home expansion across 250,000 village blocks. TRAI's Wi-Fi Access Network Interface framework enables local entrepreneurs to resell carrier bandwidth through distributed gateway deployments. Tamil Nadu and Karnataka manufacturing corridors are qualifying domestic assembly partners for Make-in-India compliance.
Brazil
Anatel certification requirements add 4-6 months to gateway product qualification, favoring vendors with established São Paulo testing relationships. Fibra Ótica program targets 45 million fiber-connected households by 2028, driving multi-million-unit annual procurement volumes. Campinas and Manaus industrial parks host final assembly for regional carrier white-label contracts.
Germany
EU F-Gas Regulation thermal design mandates are forcing vapor chamber and graphite sheet adoption in gateway enclosures for CE marking compliance. Deutsche Telekom and Vodafone deploy hybrid mesh-GPON configurations for premium tier subscribers seeking seamless handoffs. Bavaria's automotive supplier ecosystem is cross-applying thermal management expertise to gateway industrial designs.
GPON WIFI6 Home Gateway Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the GPON WiFi 6 gateway value chain. Foundry-dependent silicon vendors face margin compression against integrated chip-to-cloud stacks. Three archetypes dominate: integrated telecommunications equipment suppliers with captive semiconductor divisions, contract manufacturing specialists serving carrier white-label programs, and ODMs pivoting toward retail-direct unlocked distribution. Consolidation concentrates around multi-year managed service contracts that lock firmware upgrade cycles. Geographic expansion into rural broadband subsidy programs and backward integration into optical MAC silicon represent the primary competitive vectors.
Among integrated telecommunications suppliers, Huawei, Nokia, and ZTE exemplify divergent strategic postures. Huawei leverages its Shenzhen-based semiconductor ecosystem to control upgrade cycles across carrier contracts spanning China, Southeast Asia, and Africa. Nokia anchors European and North American market presence through R&D intensity in fiber-access silicon and managed service attach rates. ZTE competes on manufacturing scale for emerging market tenders in India, Brazil, and Indonesia, optimizing BOM configurations for state-backed bulk procurement programs. These three occupy distinct geographic and contractual niches without direct overlap in core carrier relationships.
| Leading Market Players |
|---|
| CommScope |
| AVM |
| Huawei |
| Actiontec Electronics |
| FiberHome Telecommunication Technologies |
| ZTE |
| Sercomm |
| Zyxel Communications |
| Nokia |
| Others |
Pricing and Supply Chain Analysis
Gallium arsenide substrate costs cascade through GPON WiFi 6 gateway manufacturing, starting at Taiwan and South Korea foundries and compressing margins across carrier bulk contracts, retail-direct SKUs, and enterprise-managed deployments before reaching subscriber premises.
Pricing Analysis
Margin tightening in standard-tier residential gateways reflects gallium arsenide and silicon germanium substrate volatility tied to 5G base station demand. Three-tier pricing structure across premium, standard, and economy levels separates managed service bundles with firmware subscriptions from transactional hardware sales and white-label ODM configurations. Cost-down pressure on economy-tier units accelerates because India's BharatNet and Brazil's Fibra Ótica programs prioritize volume scale over feature depth. ISP procurement teams exhibit highest price sensitivity; hospitality and retail commercial segments tolerate premium positioning for deterministic latency guarantees.
Supply Chain Analysis
Refurbishment flows for carrier-returned gateways concentrate in Shenzhen and Suzhou industrial corridors, where ODMs reclaim optical MAC silicon and WiFi 6 baseband components for secondary market deployment. GPON laser drivers and RF front-end modules draw from Taiwan, South Korea, and domestic China fabrication. Single-source vulnerability in optical chip supply creates structural risk when foundry capacity shifts toward 5G infrastructure. Distribution runs through carrier-managed provisioning platforms in North America and Western Europe, while retail-direct e-commerce channels fragment traditional operator-locked pathways in Mexico and Southeast Asia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where captive semiconductor production and firmware subscription attach rates determine long-term margin capture across hardware refresh cycles.
For Market Incumbents: Anchor carrier relationships through multi-year managed service contracts that lock firmware upgrade cycles and preempt substitution by open-source gateway platforms. Defend against ZTE's manufacturing scale in emerging markets by deepening backward integration into optical MAC silicon design. Prioritize certification investment for Common Criteria EAL4+ evaluation to maintain government and enterprise segment access.
For New Entrants and Emerging Players: FCC Rural Digital Opportunity Fund subsidies in the United States open a window for cost-optimized gateway configurations targeting underserved counties with simplified BOM structures. Brazil's Anatel certification timeline creates white-space for vendors with established São Paulo testing relationships willing to absorb 4-6 month qualification delays. Pursue retail-direct distribution through Mercado Libre and Shopee platforms where prepaid fiber services decouple CPE procurement from operator subscriptions.
For Investors and Strategic Acquirers: Carrier announcements of 10G-PON upgrade timelines are the leading indicator that WiFi 7 pre-positioning in silicon designs will capture forward replacement cycles. Long-term viability over the next decade hinges on firmware service attach rates converting hardware shipments into recurring revenue streams. Monitor TRAI's Wi-Fi Access Network Interface framework expansion across Indian states as the signal for distributed gateway deployment models gaining regulatory traction.
| Strategic Initiative | Industry Significance |
|---|---|
| Optical MAC Silicon Backward Integration | Huawei's Shenzhen semiconductor ecosystem controls upgrade cycles across carrier contracts spanning Africa and Southeast Asia. |
| Managed WiFi Service Platform Launch | Cloud-based parental controls and security monitoring expand attach rates beyond hardware economics in Latin American prepaid markets. |
| WiFi 7 Pre-Positioning in Silicon Design | Early 320 MHz channel support aligns with Deutsche Telekom and Vodafone 10G-PON upgrade timelines for premium tier subscribers. |
| Rural Broadband Subsidy Tender Participation | FCC Rural Digital Opportunity Fund and EU Gigabit Infrastructure Act unlock volume placements for cost-optimized configurations. |
| Open-Source Firmware Stack Adoption | Carrier-specific feature differentiation without silicon redesigns displaces proprietary stacks in German and Japanese deployments. |
Research Methodology
Independent corroboration across carrier procurement executives, ODM engineering directors, semiconductor foundry account managers, and regulatory affairs specialists underwrites the qualitative findings. Primary fieldwork combined structured interviews with secondary validation through MIIT certification filings, Anatel approval databases, FCC broadband subsidy disclosures, and EU CE marking registries. Bottom-up unit shipment estimates triangulated against top-down carrier capex allocations across the analysis window.
Rate-of-change decomposition across product type, connectivity configuration, deployment model, and customer procurement authority shaped the analytical framework. CAGRs derived from logistic adoption curves for WiFi 6 penetration, FTTH subscriber growth trajectories, and firmware service attach rate expansion. Modeled inputs included optical chip foundry capacity utilization, gallium arsenide substrate pricing indices, and carrier-managed contract renewal patterns.
The model assumes a particular technology adoption path; alternative pathways for WiFi 7 silicon migration ahead of 10G-PON upgrade timelines would alter the outlook. Forecasts reflect assumptions regarding regulatory certification timelines, foundry capacity allocation, and carrier procurement cycle synchronization. Practitioners should monitor FCC spectrum reallocation proceedings, EU F-Gas Regulation thermal design enforcement, and MIIT encryption standard revisions for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Network Technology
Radio Modem Market
Network Technology
Smart Network Interface Card (Smartnic) Market
Network Technology
Global LWAN Market
Network Technology
Wi-Fi 6E Router Market
Network Technology
Dark Fiber Market
Network Technology
Home Wi-Fi Router and Extender Market
Network Technology
Global Network Monitoring Market
Network Technology
Global Carrier Wi-Fi Equipment Market
Network Technology
ISP Management Systems Market
Network Technology
Zero-Touch Provisioning Market
Network Technology
Global Network Management Market
Network Technology
IT Connector Market
Network Technology
Cloud Gateway Module Market
Network Technology
US Private LTE and 5G Network Market
Network Technology
WAN Optimization Controllers Market
Network Technology
Europe Video Conferencing Hardware Market