
 Virtual Reality in Education Market | 2026-2036
Virtual Reality in Education Market Size, Share, and Industry Trends Forecast 2026-2036
Virtual Reality in Education Market Intelligence
Buyer concentration among K-12 school districts and university systems is shifting from fragmented pilot programs toward consolidated multi-year district-wide deployments. Meta Platforms, Inc. leverages its Quest ecosystem to anchor hardware-software bundling for classroom-scale purchases. Microsoft Corporation competes through Teams-integrated Mesh environments that sustain enterprise-education crossover demand. EON Reality, Inc. differentiates through its proprietary EON-XR platform, which specializes in rapid content authoring for vocational modules.
Virtual Reality in Education denotes immersive digital environments rendered through head-mounted displays or spatial computing systems, typically operating at 90Hz refresh rates with six-degrees-of-freedom tracking to minimize motion sickness during extended instructional sessions. Its primary commercial purpose is to simulate inaccessible, dangerous, or cost-prohibitive learning scenarios at repeatable unit economics. Classroom Learning applications currently dominate installed base metrics, while Simulation-based Education captures disproportionate margin pools in medical and aviation training contracts. Software Solutions lead technology spending as institutions prioritize content libraries over hardware refresh cycles, though VR Headsets remain the visible procurement trigger for budget approvals.
FCC broadband subsidy rules and FERPA student privacy requirements in the United States shape procurement specifications, while EU GDPR and the EU AI Act constrain biometric data collection in immersive environments across European deployments. China's GB standards and NMPA device classifications add compliance layers for hardware vendors seeking access through MIIT-licensed distribution channels. Stakeholders must monitor how student data governance frameworks evolve alongside generative AI content generation tools before committing to platform architectures.
Market Dynamics
Procurement consolidation across United States K-12 districts and higher education systems is compressing vendor selection cycles from multi-year pilots to single-source district-wide contracts, privileging platforms with proven FERPA compliance architectures.
Growth Catalysts
- Federal stimulus infrastructure:United States Department of Education ESSER funds are underwriting hardware refresh cycles in under-resourced districts, converting deferred maintenance budgets into immersive technology procurement.
- EU AI Act biometric governance:Compliance frameworks for emotion recognition in learning analytics are creating first-mover advantages for European content providers with certified data architectures.
- Aviation and medical simulation:FAA-certified flight training modules and ACGME-accredited surgical simulations are displacing physical manikin inventories with repeatable virtual scenarios.
Market Restraints
- Display panel supply concentration:Micro-OLED fabrication capacity remains concentrated in South Korean and Taiwanese foundries, creating 12-16 week lead time volatility for headset manufacturers.
- GDPR biometric friction:Pupil dilation tracking and gaze heatmapping for attention analytics face Article 9 special-category data restrictions across German, French, and Italian deployments.
- Hardware refresh cadence:Three-year institutional depreciation schedules misalign with 18-month consumer headset release cycles, stranding educational buyers on unsupported firmware branches.
Strategic Opportunities
- Vocational apprenticeship convergence:Germany's dual education system and Austria's Pädagogische Hochschulen are piloting welding and electrical trade certifications in VR, reducing consumables costs for chamber of commerce training centers.
- Generative AI content pipelines:Text-to-3D mesh generation is compressing module development from months to days for anatomy and historical reconstruction curricula.
- India's National Education Policy 2020:CBSE-mandated experiential learning hours are creating procurement windows for state-level VR lab tenders in Maharashtra, Karnataka, and Tamil Nadu.
Industry Challenges
- Instructional design talent scarcity:Universities lack tenure-track pipelines for immersive pedagogy researchers, forcing platform vendors to internalize curriculum development costs.
- Cross-platform content portability:Proprietary authoring tools lock institutions into single-vendor ecosystems, complicating multi-year technology roadmap planning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Virtual Reality in Education Market |
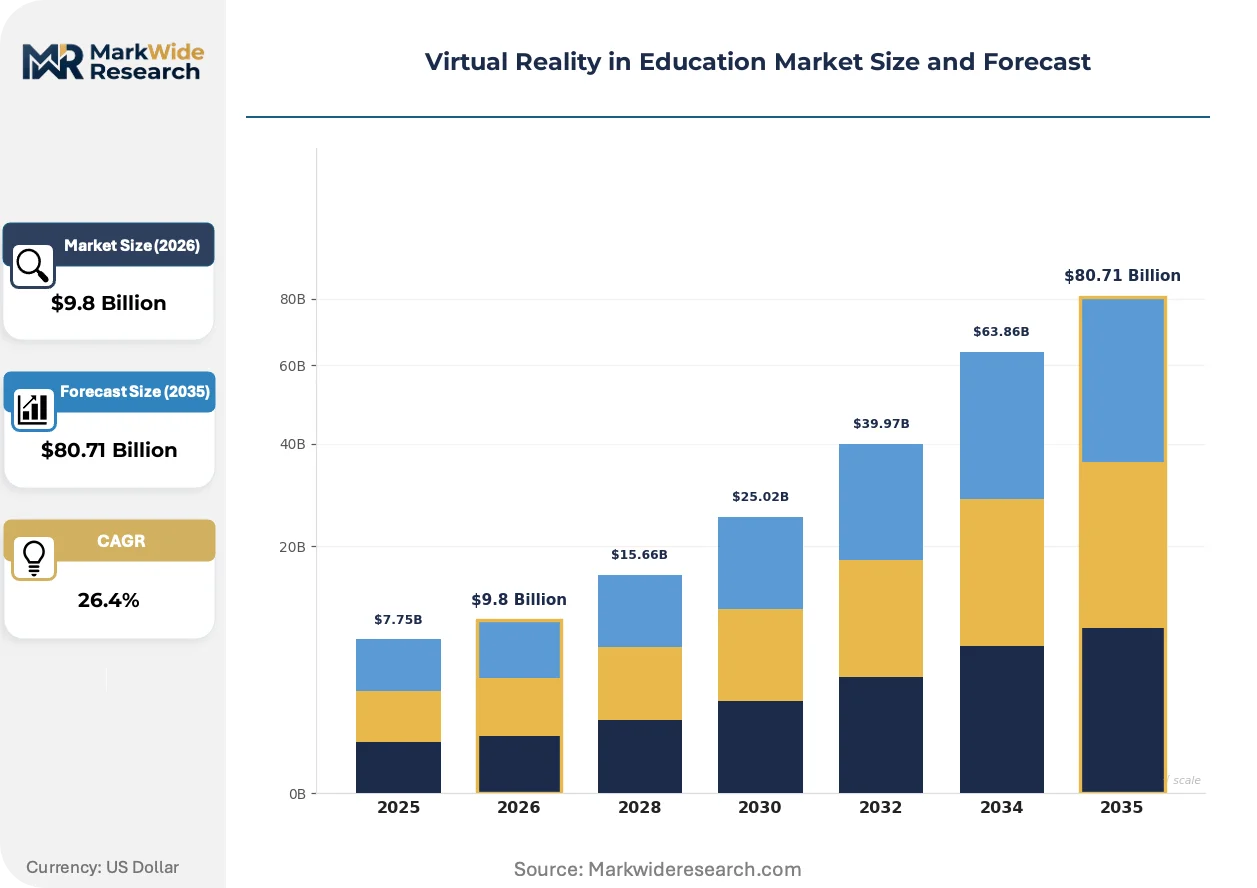
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $80.71 Billion |
| CAGR (2026 – 2036) | 26.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Classroom Learning, Remote Training, Simulation-based Education, Skill Development Technology: Software Solutions, VR Headsets, Augmented Reality, Interactive Platforms End User: K-12 Schools, Higher Education Institutions, Vocational Training Centers, Corporate Training Content Type: Educational Games, Virtual Tours, Interactive Lessons, 3D Models |
| Companies Covered | Meta Platforms, Inc., Microsoft Corporation, EON Reality, Inc., HTC Corporation, zSpace, Inc., Google LLC, VictoryXR, Inc., Schell Games, Avantis Systems Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Virtual Reality in Education Market Strategic Shifts & Innovations
Spatial computing architectures are displacing legacy screen-based learning management systems, with institutions prioritizing gesture-based interaction over controller-dependent navigation for younger learner cohorts.
Pass-through mixed reality is integrating physical classroom elements into virtual lesson plans, allowing K-12 instructors to maintain situational awareness while overlaying 3D molecular models or historical artifacts. Early adopters in Denmark and Singapore are deploying these hybrid environments for chemistry and archaeology modules. The technology is compressing the boundary between dedicated VR labs and general-purpose classrooms, reducing square-footage requirements for immersive infrastructure.
GDPR's Article 35 data protection impact assessments are mandating privacy-by-design architectures for biometric data collection in French and Dutch educational deployments. Vendors must now document lawful basis for processing gaze vectors and physiological responses before contract execution. Medical training programs in Rotterdam and Lyon are retrofitting existing installations with edge-computing anonymization layers to satisfy supervisory authority requirements.
Subscription-based content licensing is displacing perpetual software purchases in North American higher education, with procurement officers favoring annual per-student fees over capital expenditure approvals. Community college systems in Texas and California are consolidating multi-campus contracts through shared services agreements. This shift transfers technology obsolescence risk from institutional IT departments to platform operators, accelerating refresh cycles for instructional content libraries.
Virtual Reality in Education Market Segmentation
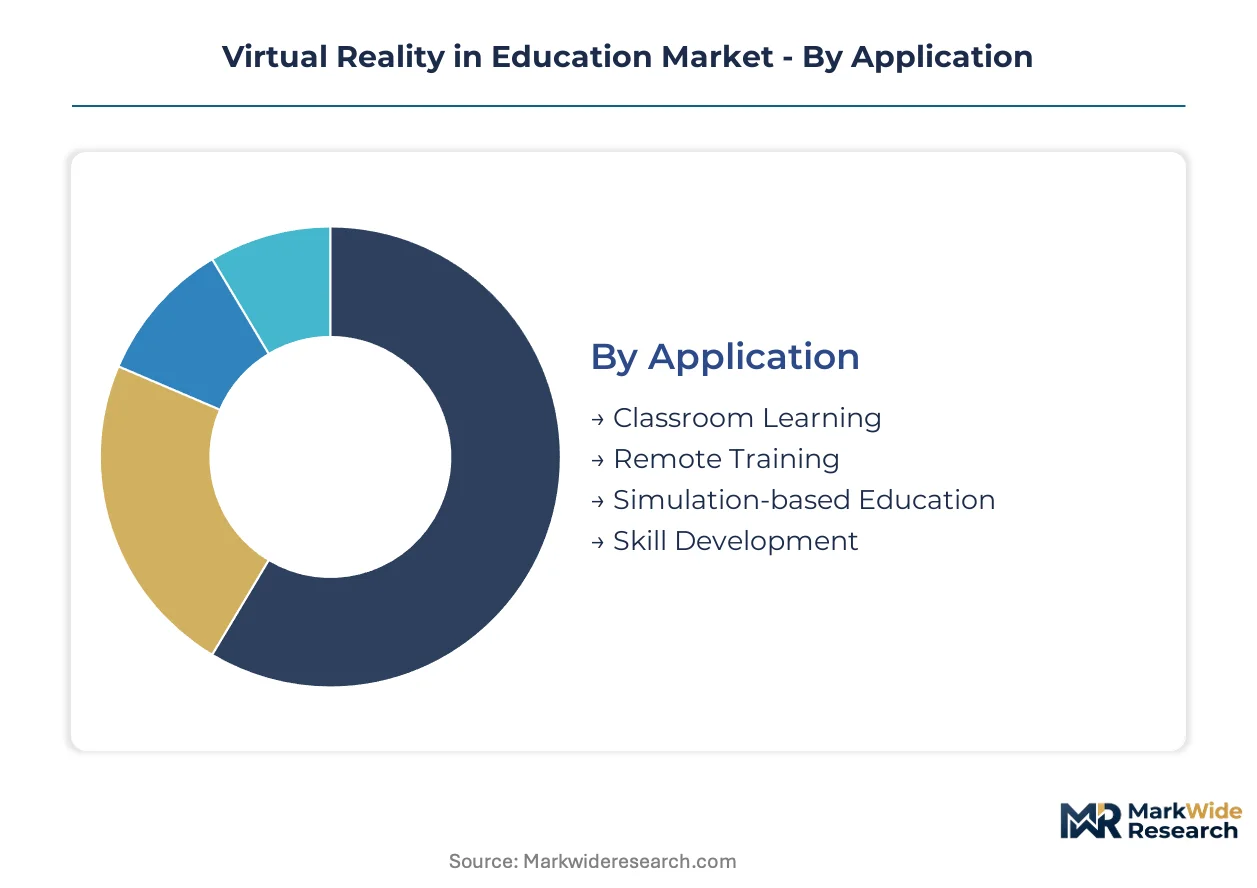
Segmentation in VR education reveals how procurement priorities diverge between capital-constrained K-12 districts and margin-rich medical training programs. Understanding these fault lines helps vendors align platform architectures with specific buyer economics and compliance requirements.
Application:
Buyer differentiation in this category hinges on whether institutions seek repeatable unit economics for high-risk scenarios or scalable content distribution for standard curricula.
- Classroom Learning:Deployments center on head-mounted displays with 90Hz refresh rates for extended instructional sessions without motion sickness. Demand concentrates in United States K-12 districts converting ESSER stimulus into district-wide hardware refresh cycles, though three-year depreciation schedules misalign with 18-month consumer headset release cadences.
- Simulation-based Education:FAA-certified flight modules and ACGME-accredited surgical scenarios displace physical manikin inventories with repeatable virtual environments. Medical schools in Rotterdam and Lyon are retrofitting installations with edge-computing anonymization layers to satisfy GDPR Article 35 data protection impact assessments for biometric data collection.
- Remote Training:Synchronous immersive sessions for distributed learner cohorts, typically delivered through cloud-rendered streaming to reduce local hardware requirements.
- Skill Development:Vocational modules for welding and electrical trades, piloted in Germany's dual education system and Austria's Pädagogische Hochschulen to reduce consumables costs for chamber of commerce training centers.
Volume sits with Classroom Learning; growth tilts toward Simulation-based Education.
Technology:
Procurement patterns in this dimension reflect institutional preference for content libraries over hardware refresh cycles, despite headsets remaining the visible budget trigger for approval workflows.
- Software Solutions:Subscription-based content licensing is displacing perpetual purchases in North American higher education, with Texas and California community college systems consolidating multi-campus contracts through shared services agreements. This transfers technology obsolescence risk from institutional IT departments to platform operators.
- VR Headsets:Micro-OLED fabrication capacity concentration in South Korean and Taiwanese foundries creates 12-16 week lead time volatility for manufacturers supplying institutional buyers.
- Augmented Reality:Pass-through mixed reality integrating physical classroom elements, deployed in Denmark and Singapore for chemistry and archaeology modules to compress boundaries between dedicated VR labs and general-purpose classrooms.
- Interactive Platforms:Gesture-based navigation systems prioritized for younger learner cohorts over controller-dependent interfaces.
Revenue concentrates in Software Solutions; steepest expansion trajectory belongs to Interactive Platforms.
End User:
Customer type determines compliance architecture requirements, with FERPA-governed United States deployments demanding different data governance than GDPR-constrained European installations.
- Higher Education Institutions:Universities in North America are expanding procurement of immersive learning labs through consolidated multi-year contracts rather than fragmented pilot programs. Tenure-track pipeline scarcity for immersive pedagogy researchers forces platform vendors to internalize curriculum development costs.
- K-12 Schools:Federal stimulus for digital infrastructure flows toward technology modernization, with procurement officers favoring annual per-student fees over capital expenditure approvals.
- Vocational Training Centers:India's National Education Policy 2020 mandates experiential learning hours, creating procurement windows for state-level VR lab tenders in Maharashtra, Karnataka, and Tamil Nadu.
- Corporate Training:Enterprise-education crossover demand sustained through Teams-integrated environments for professional development programs.
Deployment scale favors Higher Education Institutions; policy tailwinds are strongest for Vocational Training Centers.
Content Type:
Development economics in this category are compressing as generative AI text-to-3D mesh generation reduces module production timelines from months to days.
- 3D Models:Anatomy and historical reconstruction curricula benefit from accelerated authoring pipelines, with proprietary tools locking institutions into single-vendor ecosystems and complicating multi-year technology roadmap planning.
- Interactive Lessons:Spatial computing architectures displacing legacy screen-based learning management systems, with gesture-based interaction prioritized for younger cohorts.
- Educational Games:Gamification layers for engagement metrics in K-12 deployments.
- Virtual Tours:Cultural heritage and inaccessible site access for geography and history instruction.
Production volume clusters in 3D Models; engagement metrics favor Interactive Lessons.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates most acutely in the United States, where federal stimulus for digital infrastructure continues to flow toward K-12 technology modernization. European procurement is reshaping around GDPR Article 9 biometric restrictions and EU AI Act compliance timelines. Asia-Pacific markets are opening through national education policy mandates and state-level VR lab tenders.
United States
ESSER funds from the Department of Education are converting deferred maintenance budgets into immersive technology procurement across under-resourced districts. FERPA student privacy requirements and FCC broadband subsidy rules shape procurement specifications for hardware and content platforms. Texas and California community college systems are consolidating multi-campus contracts through shared services agreements for subscription-based content licensing.
Germany
The dual education system is piloting welding and electrical trade certifications in VR to reduce consumables costs for chamber of commerce training centers. GDPR Article 35 data protection impact assessments mandate privacy-by-design architectures for biometric data collection in educational deployments. Pädagogische Hochschulen in Baden-Württemberg and Bavaria are retrofitting installations with edge-computing anonymization layers to satisfy supervisory authority requirements.
India
The National Education Policy 2020 mandates experiential learning hours, creating procurement windows for state-level VR lab tenders. CBSE curriculum requirements are driving institutional adoption in Maharashtra, Karnataka, and Tamil Nadu. Vocational training centers in Telangana and Gujarat are integrating immersive modules for manufacturing and healthcare skill development under PLI scheme-linked workforce programs.
China
GB standards and NMPA device classifications add compliance layers for hardware vendors seeking access through MIIT-licensed distribution channels. Provincial education bureaus in Jiangsu and Guangdong are funding immersive learning lab deployments in tier-one city school districts. Yangtze River Delta universities are expanding procurement of simulation-based education platforms for medical and engineering training programs.
France
CNIL enforcement of GDPR Article 9 special-category data restrictions is constraining pupil dilation tracking and gaze heatmapping for attention analytics in educational deployments. Medical training programs in Lyon are retrofitting existing installations with edge-computing anonymization layers to satisfy supervisory authority requirements. Île-de-France higher education institutions are expanding procurement of immersive learning labs with certified data governance architectures.
Virtual Reality in Education Market Key Industry Players
United States producers anchor one tier; Asian hardware specialists and European content platforms hold differentiated positions. The vendor base stratifies across three tiers: consumer electronics conglomerates with education divisions, pure-play immersive learning platforms, and vocational simulation specialists. Consolidation pressure is compressing vendor selection cycles from multi-year pilots to single-source district-wide contracts. Dominant competitive moves include hardware-software bundling for classroom-scale purchases and strategic partnerships for FERPA-compliant data architectures.
Within the consumer electronics tier, Meta Platforms, Inc. and Microsoft Corporation exemplify divergent platform strategies. Meta leverages its Quest ecosystem to anchor hardware-software bundling for classroom-scale purchases. Microsoft competes through Teams-integrated Mesh environments that sustain enterprise-education crossover demand. EON Reality, Inc. occupies a position among pure-play immersive learning specialists, differentiating through proprietary rapid content authoring capabilities for vocational modules.
| Leading Market Players |
|---|
| Meta Platforms, Inc. |
| Microsoft Corporation |
| EON Reality, Inc. |
| HTC Corporation |
| zSpace, Inc. |
| Google LLC |
| VictoryXR, Inc. |
| Schell Games |
| Avantis Systems Ltd. |
| Others |
Cost & Logistics Intelligence
Immersive content developer talent pools in Eastern Europe and South Asia create labor-cost differentials that widen pricing-tier spreads between premium simulation modules and economy-grade classroom content. Subscription-based SaaS licensing transfers technology obsolescence risk from institutional IT departments to platform operators, compressing upfront capital expenditure thresholds while elongating total cost of ownership horizons.
Pricing Analysis
Volume concentrates in economy-tier classroom hardware bundles while margin pools accrue to premium simulation-based education contracts for medical and aviation certification. Three-tier pricing structure across premium, standard, and economy levels separates FAA-certified surgical modules from district-wide K-12 deployments from single-headset pilot programs. Price differentiation hinges on FERPA compliance certification grade and customization depth for institutional learning management system integration. Cost compression in hardware tiers is intensifying because Micro-OLED fabrication bottlenecks constrain supply elasticity. K-12 districts exhibit highest price sensitivity due to ESSER fund sunset timelines, while medical training programs demonstrate lowest sensitivity given manikin displacement economics.
Supply Chain Analysis
Specialized optical engineer availability in Taiwan and South Korea shapes headset manufacturer expansion timelines and yield rates for institutional-grade displays. Micro-OLED panel fabrication draws from South Korean and Taiwanese foundry capacity, while rare-earth magnet supply for six-degrees-of-freedom tracking sensors rests on Chinese processing infrastructure. Single-source vulnerability concentrates in display driver IC supply chains where fabless semiconductor design houses anchor to single foundry relationships. Distribution runs through education technology resellers with FERPA compliance certification, direct OEM relationships with large university systems, and shared services aggregators for community college networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Spatial computing architectures are displacing legacy screen-based learning management systems, with pass-through mixed reality integrating physical classroom elements into virtual lesson plans as the dominant transition vector.
For Market Incumbents: Lock in district-wide contract consolidation by accelerating FERPA-compliant data architecture certification ahead of procurement cycle compression. Deepen backward integration into rapid content authoring tools to offset instructional design talent scarcity forcing curriculum development cost internalization. Counter generative AI content pipeline threats by embedding proprietary 3D asset libraries into multi-year subscription lock-in structures. For New Entrants and Emerging Players: Generative AI text-to-3D mesh generation capabilities offer a technology-first wedge into vocational apprenticeship convergence segments where welding and electrical trade certification modules face compressed development timelines. India's state-level VR lab tenders under National Education Policy 2020 mandate represent the most penetrable geography-application intersection. Pursue chamber of commerce training center partnerships in Germany's dual education system as the optimal go-to-market angle. For Investors and Strategic Acquirers: Re-rating potential sits with pure-play immersive learning platforms with certified GDPR Article 35 data protection impact assessment architectures given EU AI Act biometric governance tailwinds. Long-term viability over the next decade favors vendors with demonstrated FERPA compliance and rapid vocational content authoring pipelines. Monitor ESSER fund utilization rates in United States K-12 districts as the primary inflection indicator for hardware refresh cycle sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| FERPA Compliance Certification Investment | Unlocks district-wide contract eligibility under compressed procurement timelines. |
| Generative AI Content Pipeline Development | Compresses anatomy module production from months to days for Rotterdam medical schools. |
| Edge-Computing Anonymization Layer Deployment | Satisfies CNIL enforcement of GDPR Article 9 restrictions in Lyon training programs. |
| Vocational Chamber of Commerce Partnership | Captures welding certification demand from Germany's dual education system pilots. |
| Shared Services Agreement Consolidation | Transfers obsolescence risk from Texas community college IT departments to operators. |
Research Approach
SEC filings from Meta Platforms and Microsoft, EON Reality investor presentations, and United States Department of Education ESSER fund disbursement records formed the secondary backbone. Primary interviews with immersive learning lab directors, K-12 district technology officers, FERPA compliance auditors, and vocational training center procurement managers combined with secondary validation. Bottom-up triangulation across hardware shipment data, content licensing contract values, and institutional deployment announcements anchored volume estimates.
Top-down analytical lens cross-referenced total addressable education technology spending against immersive technology penetration rates across the analysis window. Segmentation dimensions modeled include application type, technology category, end-user institution, and content development methodology. CAGRs derived from curve-fitting historical adoption patterns against policy mandate timelines. Forecast inputs incorporated FCC broadband subsidy rule evolution and EU AI Act implementation phase transitions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under ESSER fund extension or contraction scenarios and Micro-OLED fabrication capacity expansion delays. Projections reflect assumptions regarding institutional depreciation schedule alignment with headset release cadences and GDPR biometric friction resolution pathways. Material deviation in federal stimulus continuity or display panel supply concentration warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Educational Technology (EdTech)
Micro Learning Platform Market
Educational Technology (EdTech)
Higher Education Technology Market
Educational Technology (EdTech)
Student Response System Market
Educational Technology (EdTech)
Edutainment Market
Educational Technology (EdTech)
Education Apps Market
Educational Technology (EdTech)
Global Edutainment Centers Market
Educational Technology (EdTech)
Education Security Market
Educational Technology (EdTech)
Global Smart Classroom Market
Educational Technology (EdTech)
Game-Based Learning Market
Educational Technology (EdTech)
North America Digital Education Market
Educational Technology (EdTech)
Education Technology and Smart Classrooms Market
Educational Technology (EdTech)
Global K-12 Software Market
Educational Technology (EdTech)
Global AI in Education Market
Educational Technology (EdTech)
VR Education Market
Educational Technology (EdTech)
Child Care Software Market
Educational Technology (EdTech)
Education Technology Market