
 Global AI in Education Market | 2026-2036
Global AI in Education Market Size, Share, and Industry Trends Forecast 2026-2036
Global AI in Education Market Analysis
North American cloud infrastructure providers is repositioning AI education delivery toward scalable SaaS architectures. Microsoft leverages its Azure ecosystem to anchor institutional learning management deployments across university systems. Google competes through workspace-integrated tutoring tools that sustain engagement across K-12 environments. IBM differentiates via Watson-powered predictive analytics platforms designed for workforce credentialing programs.
Artificial intelligence in education encompasses machine learning algorithms, natural language processing engines, and adaptive assessment architectures that personalize content delivery, automate administrative workflows, and generate real-time performance diagnostics for learners and instructors. Intelligent Tutoring Systems currently occupy the highest-margin segment due to proprietary algorithm development costs and recurring content licensing structures, while Cloud-based deployment leads volume adoption as institutions abandon capital-intensive on-premises server maintenance. Higher Education Institutions represent the most concentrated end-user revenue pool, though Corporate Training demonstrates the fastest structural shift as enterprises replace conventional LMS subscriptions with AI-augmented skill-gap remediation platforms.
The EU AI Act imposes risk-classification obligations on educational algorithm providers, forcing vendors to document training data provenance and bias mitigation protocols before CE-marked deployment across European institutions. The FDA, while primarily a health regulator, influences AI education indirectly through oversight of clinical simulation training tools used in medical curricula, while China's SAMR enforces algorithmic transparency rules that constrain how adaptive learning platforms operate within its national education system. Stakeholders must monitor divergent regulatory timelines across jurisdictions to determine whether to architect single compliance frameworks or regionally segmented product variants.
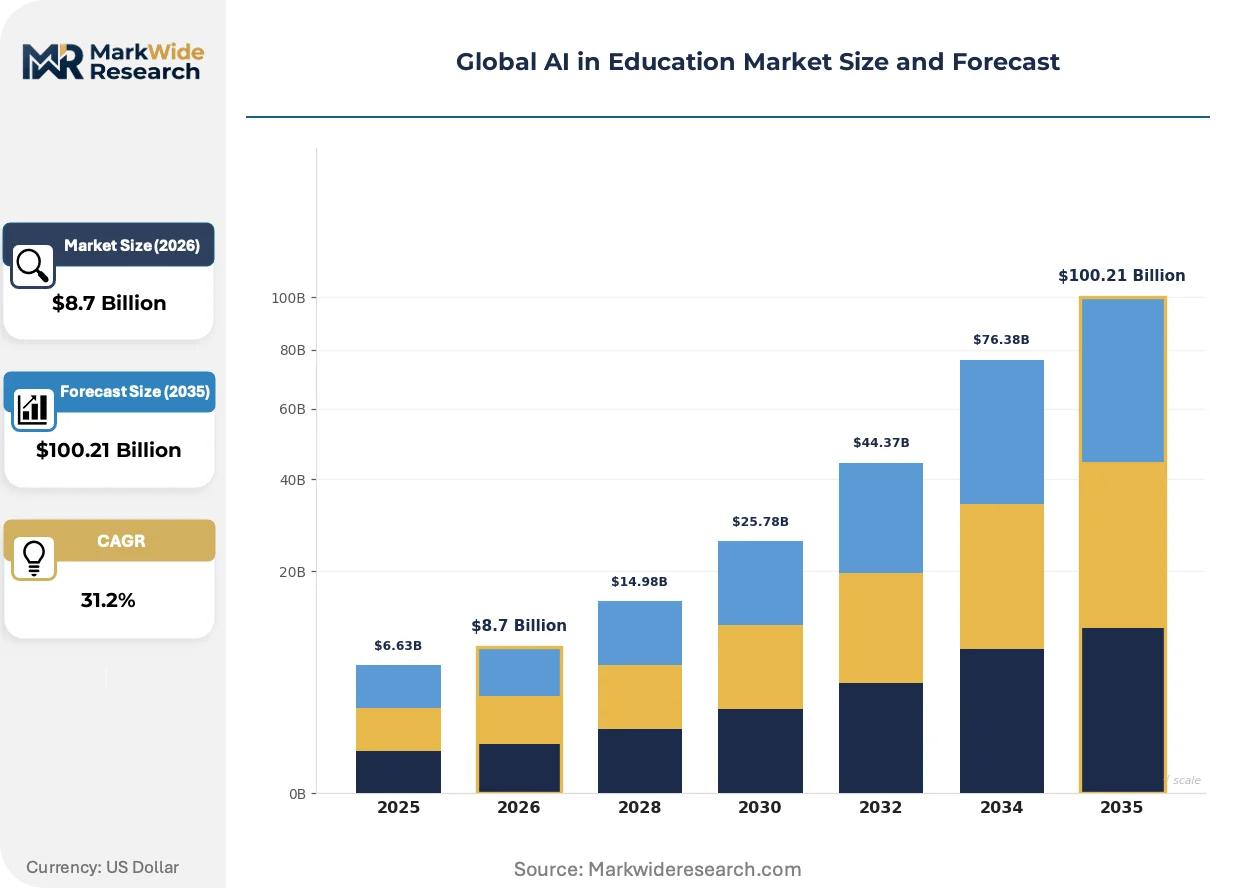
Market Dynamics
The EU AI Act's risk-classification framework is forcing educational technology vendors to rearchitect algorithmic transparency protocols before CE-marked deployment, compressing development timelines and elevating compliance costs across European institutional sales channels.
Growth Catalysts
- Federal R&D Funding Flows:United States government allocations toward personalized learning platforms are accelerating procurement cycles for adaptive assessment architectures in public university systems.
- Corporate Training Transformation:Enterprise workforce development departments are replacing conventional LMS subscriptions with AI-augmented skill-gap remediation platforms, creating sustained demand for predictive analytics engines.
- Natural Language Processing Maturation:Transformer-based tutoring engines are enabling real-time dialogue capabilities that sustain learner engagement across K-12 and higher education environments without human instructor intervention.
Market Restraints
- Training Data Provenance Requirements:The EU AI Act mandates exhaustive documentation of algorithmic training sources, extending compliance timelines and freezing vendor deployment schedules across European markets.
- Cloud Infrastructure Concentration:Dominance of hyperscale providers in North American data center geography creates single-point-of-failure risk for institutional learning management deployments.
- Proprietary Algorithm Lock-in:Intelligent Tutoring Systems depend on closed-source adaptive engines, limiting institutional ability to audit bias mitigation or port content across competing platforms.
Strategic Opportunities
- India's National Education Policy:Digital infrastructure mandates in Indian public school systems are opening procurement windows for multilingual adaptive learning platforms with offline synchronization capabilities.
- Clinical Simulation Convergence:FDA oversight of AI-enabled medical training tools is creating certified content demand that bridges education and healthcare regulatory frameworks.
- Workforce Credentialing Integration:China's SAMR algorithmic transparency rules are spurring development of blockchain-verified skill credentials that interoperate with adaptive assessment platforms.
Industry Challenges
- Learning Science Talent Scarcity:Shortage of specialists combining cognitive psychology expertise with machine learning engineering is constraining product development velocity for adaptive content providers.
- Legacy LMS Integration Friction:Institutional procurement cycles for AI-augmented tools are extending due to API incompatibility with entrenched campus-wide learning management infrastructures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global AI in Education Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $100.21 Billion |
| CAGR (2026 – 2036) | 31.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
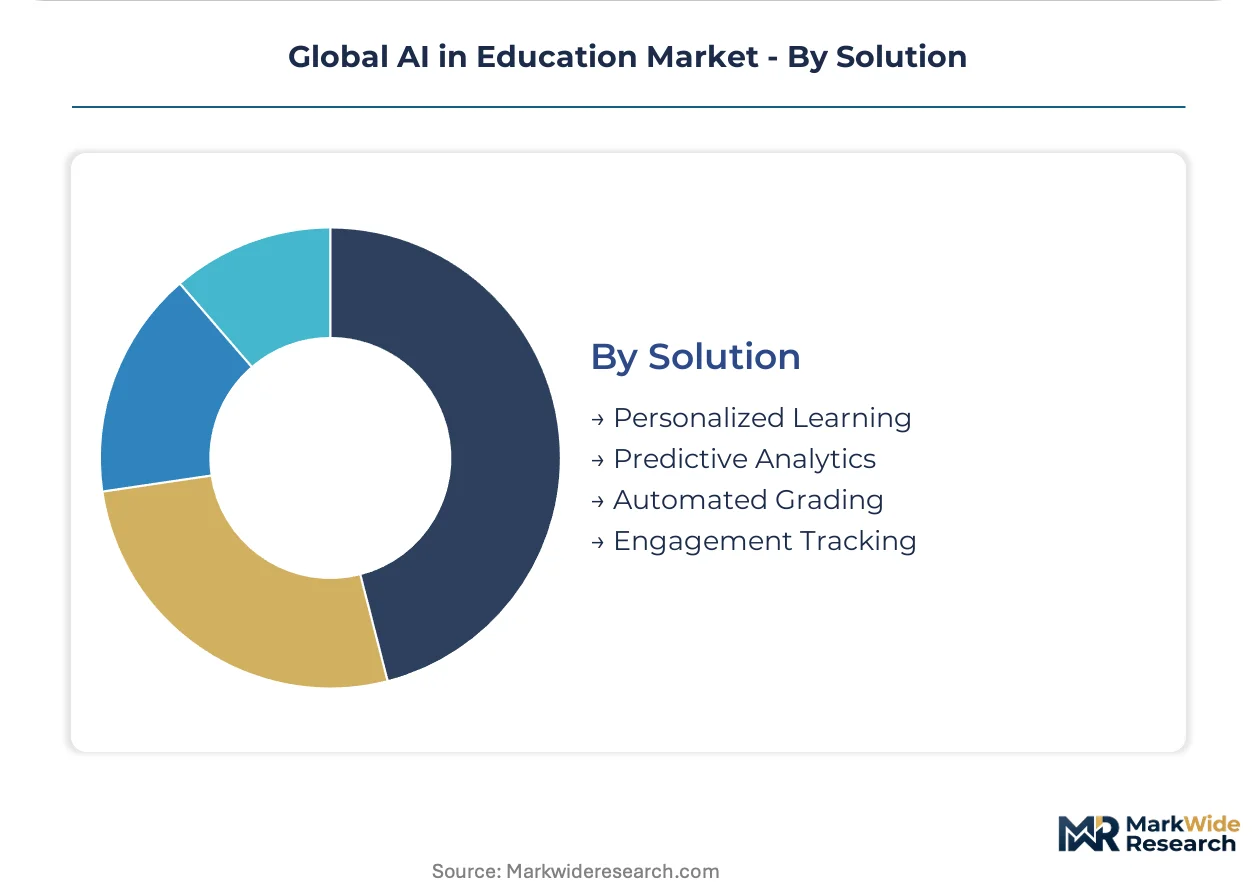
| Segmentation | Product Type: Learning Management Systems, Intelligent Tutoring Systems, Virtual Classrooms, Assessment Tools Deployment: Cloud-based, On-Premises, Hybrid, Blended Learning End User: Higher Education Institutions, K-12 Schools, Corporate Training, Educational NGOs Solution: Personalized Learning, Predictive Analytics, Automated Grading, Engagement Tracking |
| Companies Covered | Microsoft, Google, IBM, Pearson, Amazon Web Services, Duolingo, Carnegie Learning, DreamBox Learning, Blackboard, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global AI in Education Market Emerging Trajectories
Generative AI architectures are absorbing instructional design functions previously performed by human curriculum developers, compressing content production cycles and reshaping competitive positioning among educational publishers.
Multimodal large language models are absorbing text, voice, and visual tutoring interactions into unified conversational interfaces. University systems in the United States are piloting these engines for STEM remediation at scale. This convergence is absorbing the market share of single-modal intelligent tutoring systems that dominated the previous decade.
The EU AI Act's high-risk system classification for educational algorithms is mandating conformity assessment procedures before CE-marked deployment. European universities are delaying procurement decisions pending vendor compliance certification. This regulatory friction is absorbing smaller algorithm providers into larger platforms with dedicated compliance infrastructure.
Enterprise buyers are consolidating vendor relationships around integrated skill-gap assessment and remediation platforms. Corporate training departments in Germany and France are abandoning point-solution subscriptions for unified workforce analytics suites. This procurement concentration is absorbing standalone adaptive learning tools into broader human capital management ecosystems.
Global AI in Education Market Segmentation
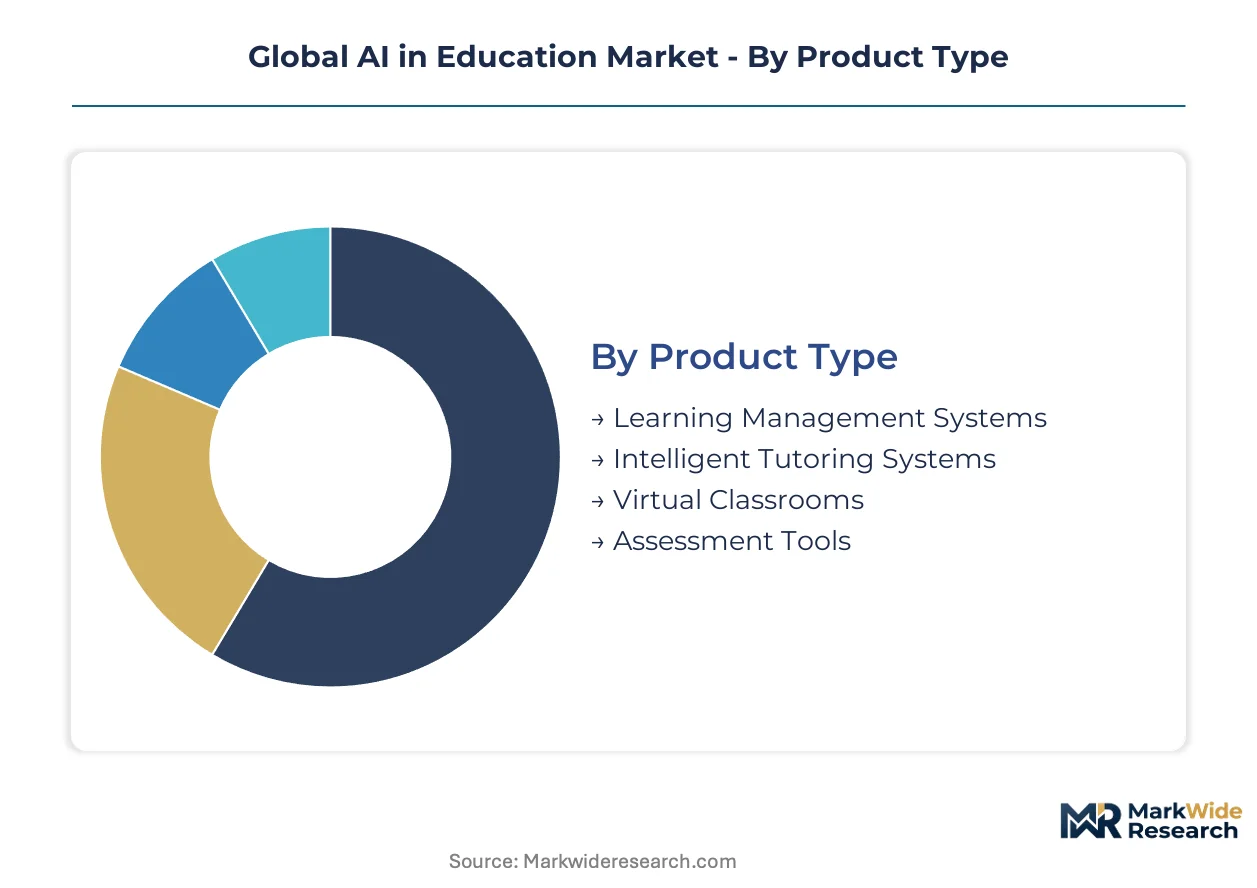
Segmentation in AI education reveals how procurement priorities diverge across institutional buyers. Cloud deployment preferences, regulatory compliance burdens, and end-user sophistication levels create distinct competitive battlegrounds that reshape vendor go-to-market strategies.
Product Type:
Institutional procurement teams prioritize integration depth with legacy campus infrastructure when evaluating product categories.
- Intelligent Tutoring Systems:Proprietary adaptive algorithms power one-on-one instruction simulations without human intervention. Demand concentrates in United States community college systems where STEM remediation backlogs strain instructor capacity and federal R&D funding accelerates pilot programs.
- Learning Management Systems:Unified platforms orchestrate content delivery, assessment scheduling, and learner progress tracking across distributed campuses. Higher education institutions in Germany and France delay procurement decisions pending EU AI Act compliance certification from vendors.
- Virtual Classrooms:Real-time video conferencing layers with AI attendance monitoring and engagement analytics.
- Assessment Tools:Automated essay scoring and plagiarism detection engines with natural language processing backends.
Learning Management Systems lead on scale; Intelligent Tutoring Systems lead on momentum.
Deployment:
Total cost of ownership calculations drive divergence between capital expenditure and operational expenditure models across institutional budgets.
- Cloud-based:Scalable SaaS architectures eliminate server maintenance overhead and enable automatic algorithm updates. United States public university systems dominate procurement volume as federal cloud-first mandates reshape IT infrastructure planning.
- Hybrid:Sensitive student data remains on-premises while compute-intensive AI workloads burst to public cloud resources. Corporate training departments in Japan favor this model under METI data sovereignty guidance for workforce credentialing platforms.
- On-Premises:Dedicated hardware installations for institutions with strict data residency requirements.
- Blended Learning:Synchronous online and asynchronous in-person modality switching with AI coordination.
Cloud-based deployment commands institutional volume; Hybrid architectures expand most quickly among compliance-sensitive buyers.
End User:
Budget authority and procurement cycle length separate enterprise buyers from public sector education customers.
- Corporate Training:Enterprise workforce development departments replace conventional LMS subscriptions with skill-gap remediation platforms. Demand concentrates in Germany automotive sector apprenticeship programs where predictive analytics engines identify competency deficiencies before production line deployment.
- Higher Education Institutions:Research universities and teaching colleges with multi-year technology refresh cycles. United States land-grant universities anchor revenue concentration as federal personalized learning grants accelerate adaptive assessment procurement.
- K-12 Schools:District-level purchasing with parent data privacy concerns constraining AI tutoring adoption.
- Educational NGOs:Nonprofit operators of supplemental education programs in emerging economies with offline synchronization requirements.
Higher Education Institutions anchor current revenue; Corporate Training climbs the fastest as enterprise learning budgets restructure around AI augmentation.
Solution:
Functional capability maturity determines price realization and renewal rates across solution categories.
- Personalized Learning:Adaptive content sequencing algorithms adjust difficulty and presentation format based on real-time learner performance signals. K-12 environments in India drive procurement under National Education Policy digital infrastructure mandates requiring multilingual offline-capable platforms.
- Predictive Analytics:Early warning systems flag at-risk students for intervention before course failure. United States community college systems deploy these engines to reduce dropout rates and protect tuition revenue.
- Automated Grading:Machine learning models score constructed responses and code submissions with consistency metrics.
- Engagement Tracking:Behavioral biometrics and attention proxies measure learner focus during digital instruction.
Personalized Learning leads on scale; Predictive Analytics leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting AI education platform development toward jurisdictions with clearer compliance pathways. Vendors are relocating algorithmic training operations from high-documentation regimes to markets with streamlined certification timelines.
United States
Federal R&D funding streams from the Department of Education and NSF accelerate adaptive learning procurement across public university systems. The FDA maintains indirect oversight through clinical simulation tools used in medical school curricula. Austin and Boston anchor development clusters where edtech startups concentrate near research university partnerships.
Germany
Automotive sector apprenticeship programs drive demand for predictive analytics engines that identify workforce competency gaps before production deployment. The EU AI Act mandates conformity assessments for educational algorithms, compressing vendor deployment timelines. Stuttgart and Munich host corporate training platform development centers serving DAX-listed manufacturers.
China
National education digitization mandates expand procurement windows for adaptive assessment platforms across provincial school systems. SAMR enforces algorithmic transparency rules that constrain how learning engines personalize content delivery. Beijing and Shanghai concentrate domestic platform development with state-backed cloud infrastructure support.
India
The National Education Policy creates procurement opportunities for multilingual adaptive learning platforms with offline synchronization capabilities. BIS standards for educational software quality provide certification frameworks for vendor market entry. Bangalore and Hyderabad anchor edtech development clusters serving both domestic and export markets.
United Kingdom
University system technology refresh cycles sustain demand for cloud-based learning management deployments. GDPR compliance requirements shape vendor data handling protocols for student information systems. London and Cambridge concentrate edtech venture activity near higher education institutional buyers.
Global AI in Education Market Vendor Landscape
United States technology conglomerates anchor one tier of the competitive structure; specialized adaptive learning developers hold differentiated positions in application-specific segments. The vendor landscape exhibits tiered consolidation around cloud infrastructure scale, with horizontal platform providers absorbing point-solution capabilities through strategic technology licensing. Three archetypes dominate: hyperscale cloud-integrated suites, proprietary algorithm specialists, and institutional legacy system modernizers. Competitive dynamics center on API ecosystem expansion and regulatory compliance infrastructure buildout.
Among United States-based technology platforms, Microsoft, Google, and IBM exemplify distinct competitive positioning archetypes. Microsoft represents the cloud-integrated ecosystem play through Azure-anchored institutional deployments. Google occupies the workspace-embedded engagement vector with productivity-tool tutoring integrations. IBM exemplifies the predictive analytics specialization for workforce credentialing applications.
| Leading Market Players |
|---|
| Microsoft |
| IBM |
| Pearson |
| Amazon Web Services |
| Duolingo |
| Carnegie Learning |
| DreamBox Learning |
| Blackboard |
| Others |
Supply Flow & Price Mechanics
The EU AI Act's high-risk system classification for educational algorithms gates both qualified supply and premium-tier pricing access. Vendors lacking conformity assessment infrastructure face exclusion from European institutional procurement, while compliance-certified platforms command pricing premiums across German and French university systems.
Pricing Analysis
Distributor margins in institutional learning management systems compress as hyperscale cloud providers bypass traditional channel layers through direct Azure and AWS enterprise contracts. SaaS-tiered subscription models dominate, with price differentiation resting on algorithmic transparency certification level and integration depth with legacy campus infrastructure. Cost compression in mid-tier adaptive learning tools is intensifying because open-source NLP frameworks erode proprietary engine premiums. K-12 school districts exhibit highest price sensitivity due to constrained district-level IT budgets, while corporate training departments in automotive and pharmaceutical sectors show lowest sensitivity when predictive analytics demonstrably reduce workforce competency gaps.
Supply Chain Analysis
Regional distribution centers for AI education platforms concentrate in the United States, Ireland, and Singapore to minimize latency for real-time adaptive assessment workloads. Cloud infrastructure hardware draws from Taiwan semiconductor foundries, South Korean memory fabricators, and United States GPU designers. Single-source vulnerability in NVIDIA AI chip supply creates procurement risk for vendors training large language models. Distribution runs through hyperscale cloud marketplaces and direct enterprise sales teams, with institutional buyers increasingly consolidating around integrated suites rather than point-solution procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global AI in Education Market functions as a geographic-arbitrage play where EU AI Act compliance costs in Europe diverge sharply from streamlined deployment pathways in India under National Education Policy digital infrastructure mandates.
For Market Incumbents: Deepen vertical integration into proprietary training data pipelines to defend against open-source model commoditization. Incumbent platforms should anchor compliance infrastructure in Ireland and Germany to capture EU AI Act certification premiums while expanding multilingual content licensing to serve India's offline-capable procurement requirements. Channel control through exclusive university system partnerships remains critical as enterprise buyers consolidate vendor relationships. For New Entrants and Emerging Players: The EU AI Act in Europe opens a window for specialized conformity assessment consultancies to embed within larger platform ecosystems. New entrants should target India's National Education Policy procurement windows for multilingual adaptive learning platforms, exploiting incumbent blind spots in offline synchronization capabilities. A direct-to-district sales model bypassing legacy LMS integration friction offers the cleanest go-to-market angle for K-12 environments. For Investors and Strategic Acquirers: Roll-up economics work for adaptive algorithm specialists because institutional procurement concentration is absorbing smaller vendors into integrated suites. Long-term viability favors platforms with dedicated compliance infrastructure spanning multiple jurisdictions. The signal to watch is FDA clinical simulation certification activity, as medical education AI tools bridge healthcare and education regulatory frameworks with premium pricing potential.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Compliance Infrastructure Buildout | Conformity assessment capabilities unlock CE-marked deployment across German and French institutional buyers. |
| Multilingual Adaptive Content Licensing | Offline-capable platforms capture National Education Policy procurement in India's public school systems. |
| Clinical Simulation FDA Certification Pathway | Medical education AI tools access healthcare-adjacent pricing premiums under FDA oversight frameworks. |
| Corporate Training Platform Integration | Predictive analytics engines displace conventional LMS subscriptions in German automotive apprenticeship programs. |
| Cloud Marketplace Distribution Expansion | Hyperscaler partnerships reduce customer acquisition costs for adaptive learning SaaS providers. |
Methodological Framework
Coverage spans North America, Europe, Asia-Pacific, and Middle East-Africa, with primary inputs from each region triangulated against secondary validation. The research combines structured interviews with chief learning officers, university procurement directors, corporate training executives, and edtech platform engineers alongside regulatory affairs specialists. Secondary sources include SEC filings from listed education technology vendors, EU AI Act implementation guidance documents, National Education Policy procurement circulars, and hyperscaler cloud infrastructure capex disclosures. Bottom-up demand modeling from institutional procurement cycles cross-validates against top-down market sizing from technology spending surveys.
Rate-of-change decomposition separates volume expansion from pricing evolution across the projection horizon. The analytical framework models segmentation dimensions including deployment architecture, end-user institution type, solution functional capability, and regional regulatory cluster. CAGRs derive from algorithmic adoption curves in comparable technology diffusion patterns, adjusted for education sector procurement cycle length and federal funding flow volatility. Forecast inputs incorporate transformer-based tutoring engine maturation timelines and workforce credentialing platform replacement rates.
Revisions become necessary when major jurisdiction regulatory timelines shift, federal R&D funding allocations change materially, or hyperscale cloud infrastructure concentration alters vendor economics. Forecasts reflect documented assumptions about algorithmic transparency requirement enforcement intensity and institutional IT refresh cycle synchronization. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Educational Technology (EdTech)
Edtech and Smart Classroom Market
Educational Technology (EdTech)
ASEAN Smart Education and Learning Market
Educational Technology (EdTech)
E Learning Virtual Reality Market
Educational Technology (EdTech)
Global Gamification in Education Market
Educational Technology (EdTech)
Asia Big Data Analytics in Education Market
Educational Technology (EdTech)
Game-Based Learning Market
Educational Technology (EdTech)
Higher Education Learning Systems Market
Educational Technology (EdTech)
Global K-12 Software Market
Educational Technology (EdTech)
Global Edutainment Centers Market
Educational Technology (EdTech)
Global Micro-Learning Market
Educational Technology (EdTech)
Smart Education System Market
Educational Technology (EdTech)
Global Social Learning Platforms Market
Educational Technology (EdTech)
Artificial Intelligence in the Education Sector Market
Educational Technology (EdTech)
Education Technology Market
Educational Technology (EdTech)
Child Care Software Market
Educational Technology (EdTech)
Student Response System Market