
 Higher Education Market | 2026-2036
Higher Education Market Size, Share, and Industry Trends Forecast 2026-2036
Higher Education Market Intelligence
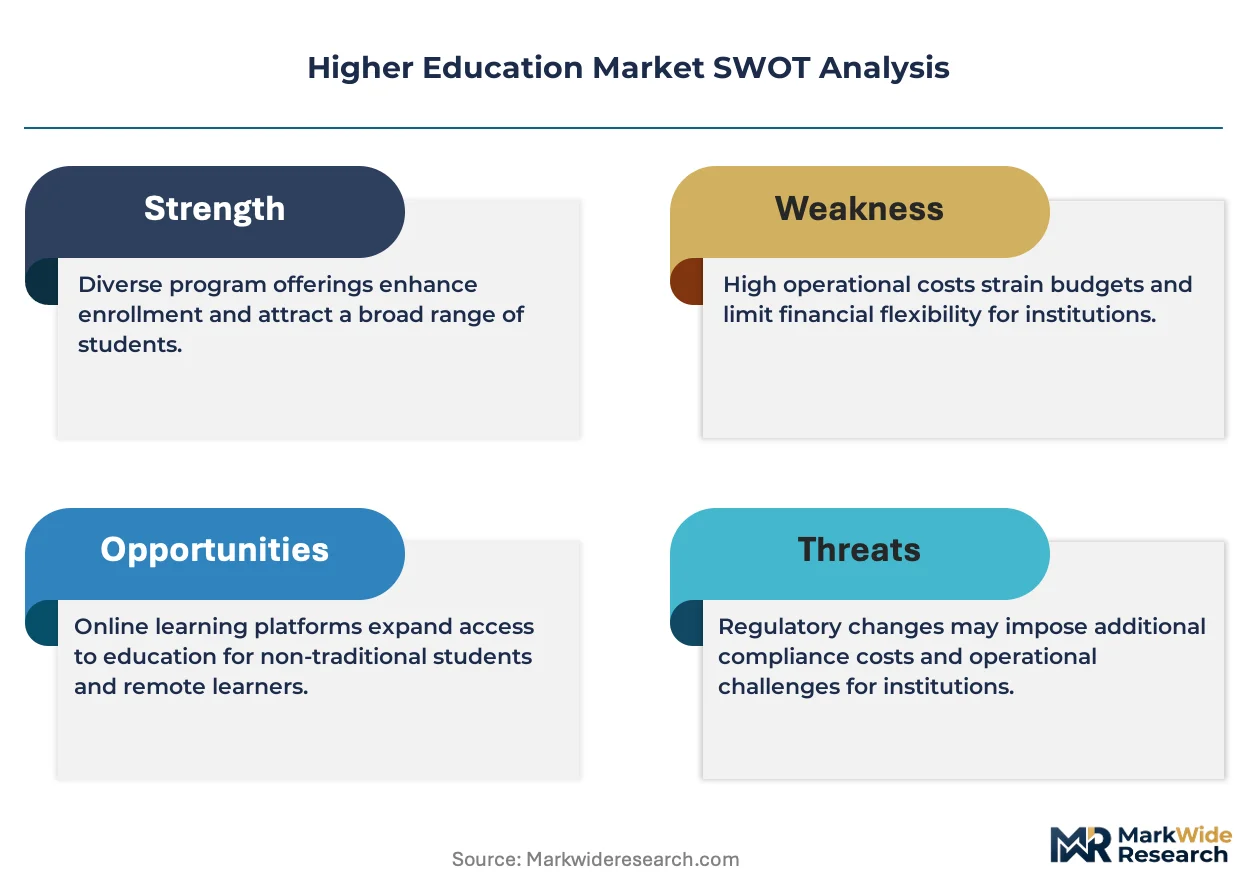
Accreditation frameworks, such as those governed by the Quality Assurance Agency for Higher Education in the UK and regional accreditors in the United States, are reorganizing the competitive landscape for universities. The University of Oxford leverages its historical brand and research output to attract top-tier faculty and students. In contrast, Massachusetts Institute of Technology specializes in science and technology programs, driving innovation through strong industry partnerships. Tsinghua University in China dominates its domestic market through state support and a focus on engineering disciplines.
Higher education encompasses structured, post-secondary learning provided by universities, colleges, and institutes. These programs are typically measured in credit hours or ECTS credits and culminate in the awarding of an academic degree or professional certificate. While Undergraduate programs form the volume base, Graduate and Doctoral programs represent significant value segments for institutions. The Online and Hybrid delivery modes are expanding rapidly, challenging the dominance of traditional On-Campus instruction, particularly for Continuing Education Learners.
Regulatory oversight from bodies like the US Department of Education, China's Ministry of Education, and principles from the European Higher Education Area (EHEA) dictate institutional eligibility for funding and student aid. These frameworks set standards for curriculum quality, faculty qualifications, and degree recognition, directly influencing market access. Institutions must now decide how to balance investments between traditional campus infrastructure and the digital platforms required for new delivery models.
Market Dynamics
The central structural force shaping higher education is the decoupling of credentials from traditional degree timelines. This shift is driven by corporate demand for specific skills and enabled by digital platforms, forcing institutions to re-evaluate their fundamental value proposition beyond campus-based experiences.
Growth Catalysts
- Post-Study Work Policies:Favorable visa regulations in countries like the United Kingdom and Australia act as a significant magnet for international students, directly stimulating enrollment in graduate and undergraduate programs from key source markets.
- Corporate Upskilling Demand:Employers are increasingly sponsoring employees for non-degree credentials, professional certificates, and specialized training modules to address critical skill gaps, particularly in technology and management disciplines.
- AI in Personalized Learning:The integration of artificial intelligence into learning management systems enables adaptive learning paths and personalized feedback at scale, improving engagement and outcomes for a diverse student body, especially online learners.
Market Restraints
- Tuition Affordability Crisis:Escalating tuition costs and associated student debt levels in markets like the United States present a significant barrier to access, prompting prospective students to question the return on investment of traditional degrees.
- Regulatory Fragmentation:Inconsistent cross-border recognition of academic credits and online degrees, despite frameworks like the European Higher Education Area, creates compliance burdens and limits the scalability of international online providers.
- Rise of Alternative Credentials:The proliferation of low-cost, skills-focused training from non-accredited providers and technology companies presents a direct substitution threat for segments of the professional and continuing education market.
Strategic Opportunities
- Unbundling and Stacking Credentials:Deconstructing traditional degrees into smaller, stackable micro-credentials allows institutions to serve lifelong learners who need to acquire skills on a flexible, as-needed basis throughout their careers.
- Immersive Learning Technologies:The convergence of virtual and augmented reality with pedagogical design opens new opportunities for delivering high-fidelity lab simulations and practical skills training in fields like medicine and engineering remotely.
- Emerging Market Penetration:A growing middle class and demographic expansion in regions across Southeast Asia and Africa create significant new demand for accessible and high-quality post-secondary education, both online and on-campus.
Industry Challenges
- Faculty Skill Gaps:A persistent challenge is the shortage of faculty trained in effective online pedagogy, instructional design, and the use of digital tools, which hampers the quality of hybrid and remote program delivery.
- Dual Infrastructure Investment:Institutions face the dual capital expenditure burden of maintaining and upgrading aging physical campus infrastructure while simultaneously investing heavily in the sophisticated digital platforms required for competitive online education.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Higher Education Market |
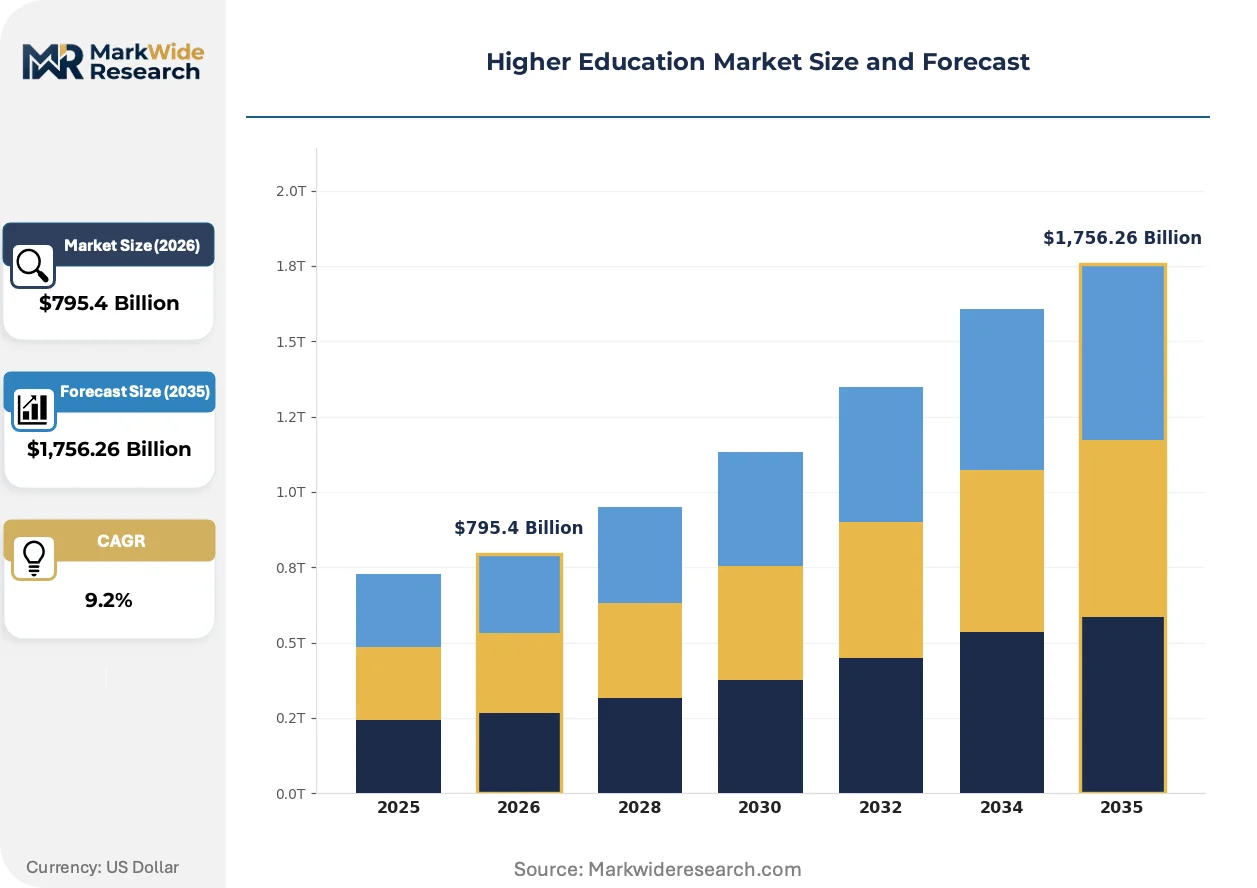
| Market Size in 2026 | $795.4 Billion |
| Market Size in 2035 | $1,756.26 Billion |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Program Type: Undergraduate, Graduate, Doctoral, Certificate, Diploma Delivery Mode: On-Campus, Online, Hybrid, Distance Learning, Blended Learning Institution Category: Public Universities, Private Colleges, Community Colleges, Technical Institutes, Vocational Schools End User Segment: Individual Learners, Corporate Trainees, Government Scholars, International Students, Continuing Education Learners |
| Companies Covered | Harvard University, Stanford University, Massachusetts Institute of Technology, California Institute of Technology, University of Oxford, Imperial College London, University College London, Tsinghua University, Peking University, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Higher Education Market Strategic Shifts & Innovations
The unbundling of the traditional university model defines the current era of higher education. Learner expectations for flexibility, combined with technological capabilities, are deconstructing established formats for content delivery, credentialing, and student services, creating new competitive pressures and opportunities for incumbents and new entrants alike.
Micro-credentials and digital badges are gaining traction as verifiable units of learning. Corporate learners and professionals adopt these formats to demonstrate specific, in-demand competencies without committing to a full degree program. This trend is miniaturizing the fundamental currency of education from the multi-year degree to the job-relevant skill, compressing the time and cost required for workforce development.
Regulatory frameworks governing online education are evolving, creating a complex compliance landscape. The US Department of Education's rules on distance learning and state authorization directly impact an institution's ability to enroll students from outside its home state. This oversight forces online providers to secure approvals on a state-by-state basis or through reciprocity agreements, affecting market access and operational costs.
A fundamental shift from a single, front-loaded educational event to a model of continuous, lifelong learning is underway. This disrupts the primacy of the residential, four-year undergraduate experience, which is increasingly supplemented or replaced by on-demand, hybrid modules for career-long skill acquisition. The pattern is most pronounced in the technology and healthcare sectors, where the half-life of professional skills is shortest.
Higher Education Market Segmentation
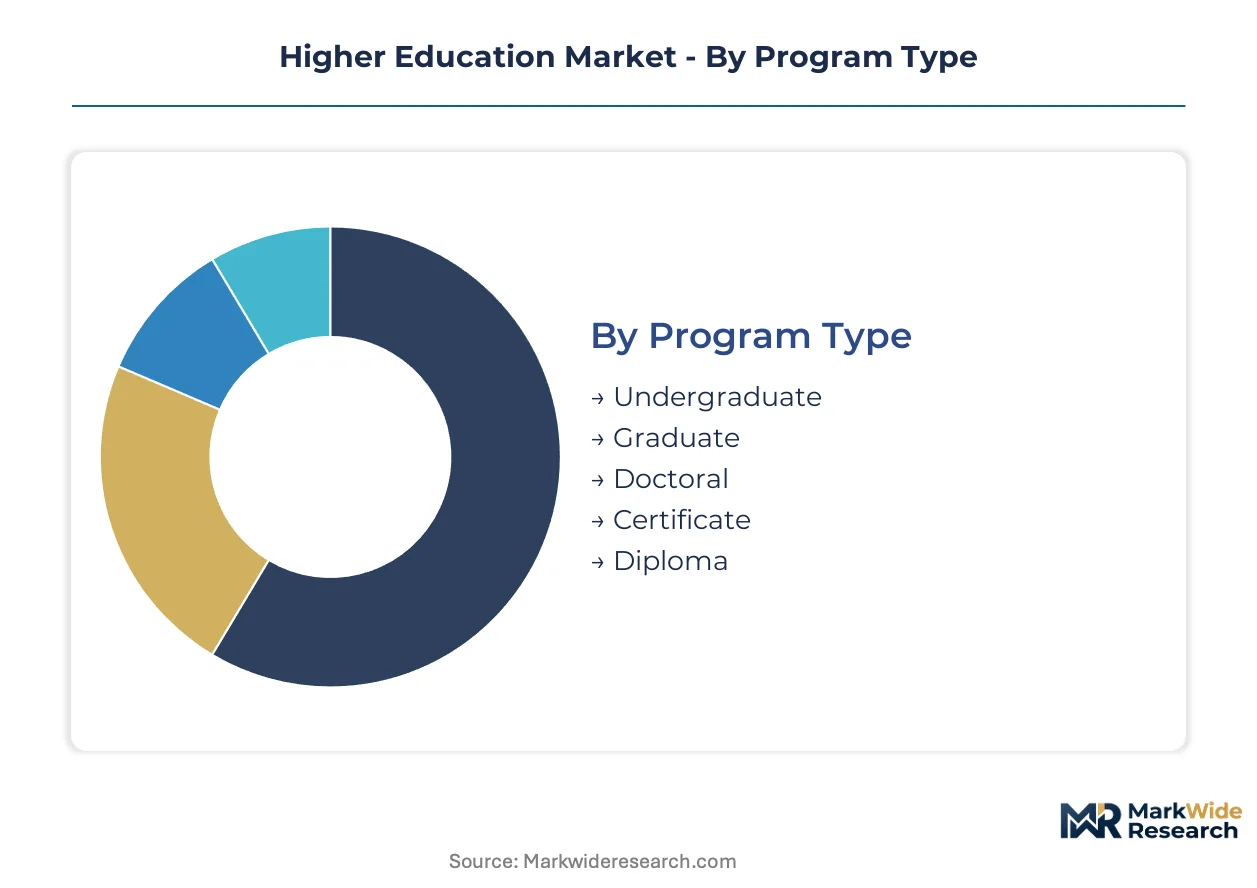
The Higher Education Market features distinct segments, driven by varied learner needs and evolving institutional structures. Understanding these distinctions helps institutions refine offerings and aids policymakers in addressing specific educational demands. Segmentation highlights growth areas and competitive dynamics across the sector.
Program Type:
Programs face distinct substitution pressures, particularly from alternative credentials challenging traditional degree pathways for workforce development.
- Undergraduate:These programs require a high school diploma, culminating in a bachelor's degree and forming the foundational volume base for most universities. Demand remains strong in established markets like the United States.
- Certificate:Shorter, focused programs providing specific skills, often without full degree commitment, serving professionals seeking rapid upskilling. Corporate demand for specialized credentials in technology fuels this segment.
- Graduate:Advanced programs, including master's degrees, focus on specialized knowledge and research, attracting students for career advancement.
- Doctoral:The highest academic degree, emphasizing original research and scholarship, preparing individuals for academic or leadership roles.
- Diploma:Often vocational, these programs offer practical skills training for specific occupations with shorter completion times than degrees.
Undergraduate retains volume leadership; Certificate holds the steepest expansion curve.
Delivery Mode:
Delivery modes differentiate by their capacity to reach diverse student populations and accommodate varying learner schedules and geographic locations.
- Online:Courses delivered entirely over the internet, providing significant flexibility in time and location, removing geographical barriers for learners. This mode attracts working professionals and international students.
- Hybrid:Combining online and on-campus instruction, this model blends digital flexibility with face-to-face interaction and practical experiences. Institutions leverage hybrid models to expand program accessibility.
- On-Campus:Traditional instruction delivered in physical classrooms, emphasizing direct interaction between faculty and students for immersive experiences.
- Distance Learning:Education delivered remotely, often through correspondence or early digital platforms, preceding modern online infrastructure.
- Blended Learning:A pedagogical approach integrating various learning experiences, including online and in-person, to optimize outcomes, often synonymous with hybrid.
The market observes a significant shift from traditional On-Campus models towards more flexible Online and Hybrid offerings.
Institution Category:
Institutional categories vary significantly in their cost structures, funding sources, and primary program offerings to student bodies.
- Public Universities:State-funded or government-subsidized institutions offering a wide range of academic programs, often at lower tuition rates. These attract large student volumes in China and the United States.
- Technical Institutes:Specialized institutions focused on vocational training and practical skills development for specific industries, leading to diplomas or certifications. Industry partnerships drive curriculum relevance.
- Private Colleges:Independently funded institutions, relying on tuition and endowments, offering diverse programs with varying selectivity and focus.
- Community Colleges:Primarily offering associate degrees, vocational training, and pathways to four-year institutions, serving local communities with affordable education.
- Vocational Schools:Institutions providing hands-on training for specific trades, preparing students for direct entry into the workforce.
Public Universities maintain broad accessibility, while Technical Institutes increasingly specialize in workforce-aligned skills provision.
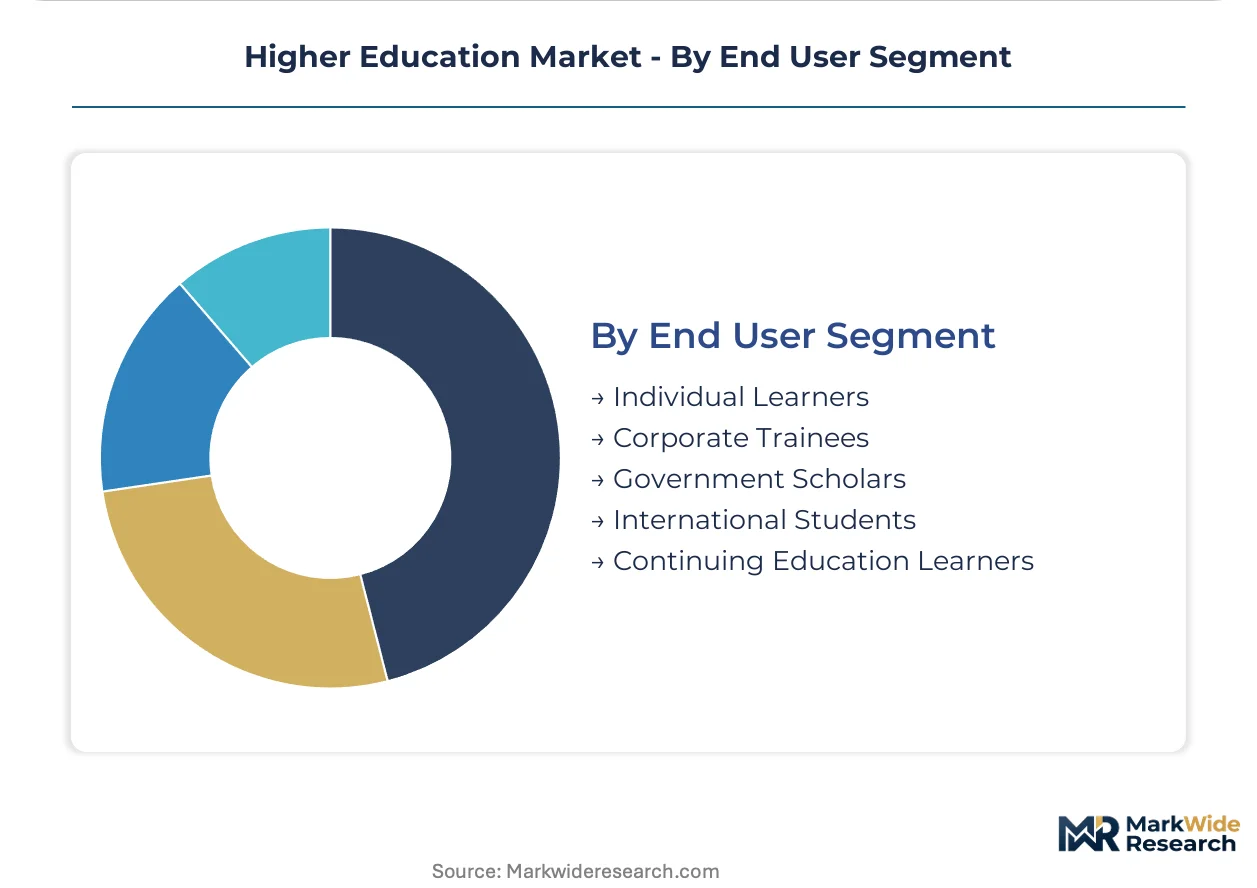
End User Segment:
Segmentation by end user reveals distinct motivations and funding mechanisms that shape demand for various higher education offerings.
- Corporate Trainees:Employees sponsored by companies for upskilling, reskilling, or professional development to address specific skill gaps. This segment shows pronounced growth in technology disciplines across Europe.
- International Students:Individuals pursuing education in a country other than their own, driven by academic reputation or post-study work opportunities. Favorable visa policies in Australia influence enrollment.
- Individual Learners:Self-funded students pursuing degrees or credentials for personal growth, career advancement, or intellectual enrichment.
- Continuing Education Learners:Adults seeking ongoing learning to update skills, change careers, or pursue personal interests outside traditional degree structures.
- Government Scholars:Students whose education is funded by government programs, often tied to national development goals or specific academic fields.
Individual Learners form the largest volume base, with Corporate Trainees and International Students representing strategic growth areas.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Favorable visa regulations and government initiatives significantly influence higher education enrollment across key global markets. Post-study work policies in countries like Australia and the United Kingdom attract a substantial influx of international students. Regulatory bodies worldwide dictate funding eligibility and curriculum standards, shaping institutional strategies.
United States
Demand for advanced degrees and specialized certifications drives enrollment in the United States. The US Department of Education sets stringent standards for federal funding and student aid. Silicon Valley and Boston serve as innovation hubs, concentrating demand for tech-focused graduate programs and research.
United Kingdom
Post-study work visa policies attract international students, particularly for graduate programs in the United Kingdom. The Quality Assurance Agency for Higher Education ensures academic standards and influences institutional competitiveness. London's diverse universities attract global talent, fostering research collaboration and specialized learning.
China
State support and a focus on engineering disciplines fuel domestic demand for higher education in China. China's Ministry of Education guides curriculum development and institutional expansion, particularly in STEM fields. Beijing and Shanghai host leading universities like Tsinghua, driving national innovation and talent development.
Australia
International student enrollment significantly boosts Australian universities, driven by attractive post-study work opportunities. The Tertiary Education Quality and Standards Agency (TEQSA) oversees quality assurance and regulatory compliance. Melbourne and Sydney are major education centers, drawing students for both undergraduate and graduate studies.
Canada
Government support for immigration and a strong reputation for quality education attract diverse learners to Canada. Immigration, Refugees and Citizenship Canada (IRCC) policies facilitate international student pathways to permanent residency. Toronto and Vancouver host a concentration of institutions offering technology and business programs.
Higher Education Market Key Industry Players
Player mix skews toward established academic institutions and specialized technical providers, creating a diverse educational landscape. The market exhibits a tiered structure, with globally recognized research universities at the top and vocational institutes serving specific skill needs. Strategic archetypes include comprehensive research institutions, specialized STEM universities, and agile online education platforms. Portfolio diversification into micro-credentials and strategic partnerships with industry are dominant competitive moves among these diverse players.
Within the established university archetype, institutions like Harvard University and the University of Oxford exemplify leveraging historical brand equity and extensive research output. These globally recognized entities often attract top-tier faculty and students, reinforcing their reputation for academic excellence and scholarly contributions. Massachusetts Institute of Technology (MIT) represents a specialized STEM-focused institution, driving innovation through strong industry collaboration and cutting-edge research. These institutions often define benchmarks for scientific and technological advancement, influencing curriculum design and global academic trends. Their distinct specializations and long-standing reputations contribute significantly to the competitive dynamics of the higher education market.
| Leading Market Players |
|---|
| Harvard University |
| Stanford University |
| Massachusetts Institute of Technology |
| California Institute of Technology |
| University of Oxford |
| Imperial College London |
| University College London |
| Tsinghua University |
| Peking University |
| Others |
Cost & Logistics Intelligence
Multi-year tuition agreements, often influenced by national funding models, lock in both student enrollment and institutional revenue visibility for extended periods. This structure helps stabilize financial planning against short-term market fluctuations.
Pricing Analysis
Cost-plus tuition structures, indexed to institutional operating expenses, dominate the higher education market. Pricing stratifies across public and private institutions, with brand premium driving differentiation for globally recognized universities. Pricing pressure stems from the escalating tuition affordability crisis in the United States. Individual learners, particularly undergraduates, are most price-sensitive, while corporate trainees exhibit lower sensitivity due to employer sponsorship.
Supply Chain Analysis
Instructional inventory, primarily faculty expertise and curriculum content, operates with long lead times for development and deployment. Geographic supply concentration for top-tier institutions centers on the United States, the United Kingdom, and China. Raw material dependencies include digital learning platforms and specialized research infrastructure. A key supply chain risk is the faculty skill gap in online pedagogy, which hampers digital program delivery. Distribution runs through direct-to-learner enrollment channels and institutional partnership networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Higher Education Market acts as a defensive moat, benefiting from strong regulatory entrenchment and deeply ingrained brand equity that creates significant switching costs for learners.
For Market Incumbents: Secure continued government funding and accreditation status through proactive engagement with bodies like the US Department of Education. Diversify revenue streams beyond traditional tuition by expanding into corporate upskilling programs. Invest heavily in digital infrastructure and faculty training for hybrid delivery models to counter the threat from agile online providers. Leverage existing brand strength to attract top research talent.
For New Entrants and Emerging Players: Unmet demand for flexible, skills-focused credentials presents a significant service-layer gap. Target continuing education learners and corporate trainees seeking rapid reskilling in technology disciplines. The most penetrable segment for new entrants involves specialized certificate programs delivered entirely online. A strong go-to-market angle involves direct partnerships with employers to co-create relevant curricula.
For Investors and Strategic Acquirers: Specialized online learning platforms with strong industry ties represent an attractive acquisition target archetype. The market remains robust over the next 5-10 years, driven by the shift towards lifelong learning. A signal to watch is the increasing corporate sponsorship for non-degree credentials, indicating a fundamental shift in workforce development priorities.
| Strategic Initiative | Industry Significance |
|---|---|
| Curriculum Digitization | Enhances accessibility and scalability for online and hybrid learning models, reaching a wider student demographic. |
| Micro-credential Portfolio Expansion | Addresses corporate demand for targeted skill development and flexible, stackable learning pathways. |
| Industry-Academic Partnerships | Ensures program relevance and provides practical experience, improving graduate employability outcomes. |
| International Student Recruitment | Diversifies revenue streams and enriches campus environments, particularly in countries with favorable visa policies. |
| AI-Powered Learning Platform Development | Enables personalized learning experiences and adaptive feedback at scale, boosting student engagement. |
Research Approach
The analysis maps undergraduate programs, graduate degrees, and certificate courses, each validated through academic deans, university administrators, and corporate HR managers. Primary interviews included faculty members, university presidents, and government education officials. Secondary data sources encompassed US Department of Education reports, QAA for Higher Education publications, and UNESCO statistics, ensuring comprehensive bottom-up and top-down triangulation.
Outputs underwent consistency checks against external benchmarks across the analysis window, integrating quantitative and qualitative models. Segmentation dimensions modeled include program type, delivery mode, institution category, end-user segment, and regional policy environment. CAGRs were derived from historical growth trends and projected market drivers, with student enrollment trends and government funding allocations serving as key forecast inputs.
Underlying assumptions cover regulatory stability and technological adoption rates, with deviation risk concentrated in unforeseen shifts in post-study work policies or global economic downturns. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Education & Training
United States Executive Education Program Market
Education & Training
Education Technology Market
Education & Training
Competency-Based Education Spending Market
Education & Training
Global Outplacement Services Market
Education & Training
Human Resource Professional Services Market
Education & Training
Digital Education Systems Market
Education & Training
Integrated Talent Management Market
Education & Training
United States HR Professional Service Market
Education & Training
School ERP Software Market
Education & Training
HR Professional Services Market
Education & Training
Global AI in Education Market
Education & Training
Massive Open Online Courses Market
Education & Training
Global Sales Training Market
Education & Training
E-Learning Market
Education & Training
English Learning for Children Market
Education & Training
Flipped Classroom Market