
 Higher Education Technology Market | 2026-2036
Higher Education Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Higher Education Technology Market Intelligence
Increased investment in digital infrastructure across Southeast Asian universities is fragmenting the supplier landscape for educational technology. Oracle Corporation leverages its enterprise resource planning expertise to offer integrated student information systems. Cisco Systems Inc. specializes in networking hardware and collaboration tools for hybrid learning models. Blackboard Inc. sustains its market position through its established Learning Management System platform.
Higher education technology refers to the array of software, hardware, and digital services designed for post-secondary institutions. These systems often incorporate cloud-based architectures and AI algorithms to deliver personalized learning paths and streamline operations. Learning Management Systems and Student Information Systems constitute the core product segments, with SaaS deployment models dominating new installations. Online learning applications show significant momentum, particularly among universities and vocational institutions.
Data privacy regulations like Europe's GDPR and the United States' FERPA heavily shape product development. These frameworks mandate strict controls over the collection, storage, and use of student information. Consequently, institutions must decide between adopting comprehensive, integrated platforms or pursuing a best-of-breed strategy with multiple specialized vendors.
Market Dynamics
The central tension shaping the higher education technology market is the strategic choice institutions face between adopting single-vendor integrated platforms and curating a portfolio of specialized, best-of-breed applications, a decision heavily influenced by data governance requirements.
Growth Catalysts
- Government Initiatives:National digital transformation policies, particularly in India, provide direct funding and regulatory support for universities to build out digital learning infrastructure and adopt new educational technologies.
- Administrative Automation:Universities are implementing advanced software to automate administrative tasks such as admissions, enrollment, and financial aid processing, which improves operational efficiency and reduces staff workload.
- Personalized Learning Demand:The adoption of AI and machine learning algorithms within Learning Management Systems allows for the creation of adaptive learning paths tailored to individual student needs and progress.
Market Restraints
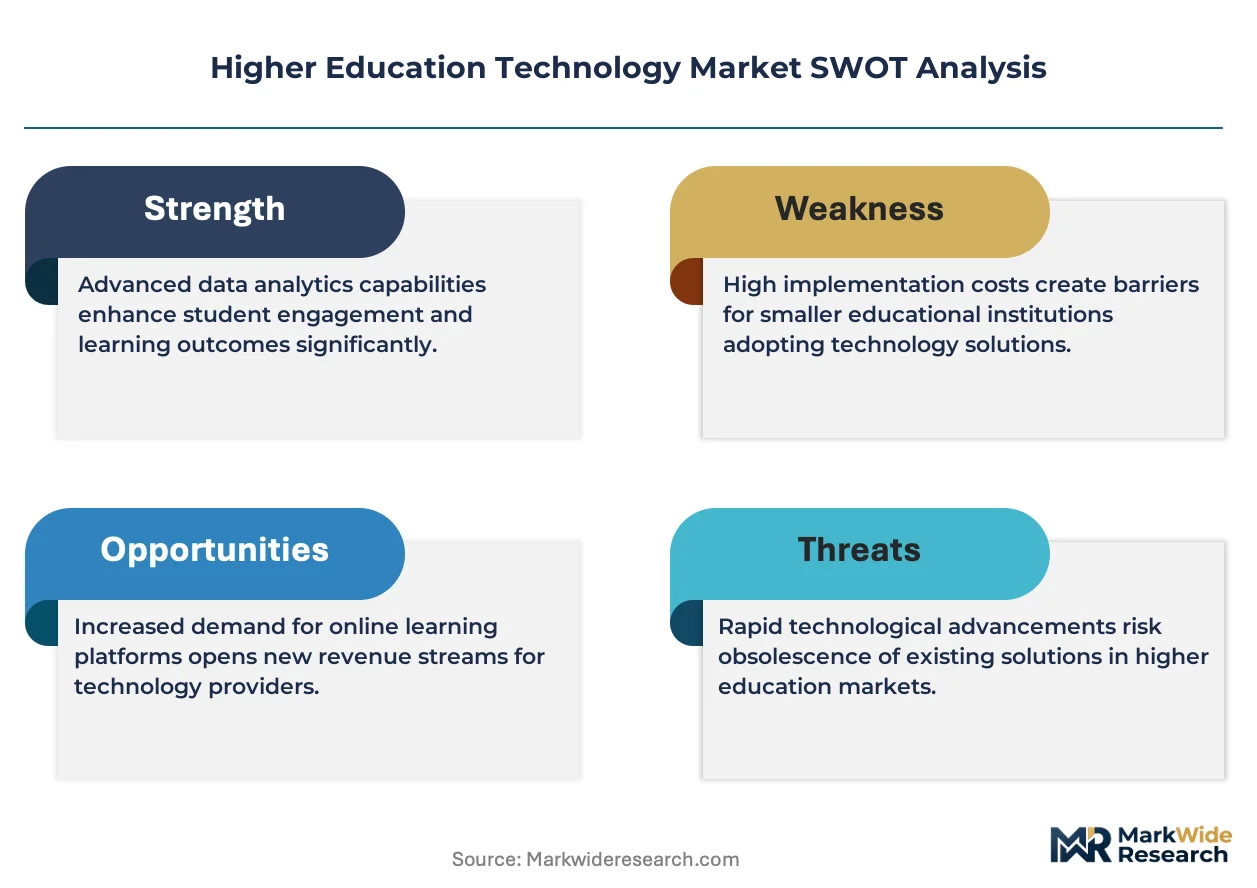
- High Implementation Costs:The significant upfront investment and recurring subscription fees associated with comprehensive Student Information Systems and enterprise resource planning platforms can be prohibitive for smaller institutions or those with limited budgets.
- Legacy System Integration:New technology solutions often face significant hurdles when integrating with decades-old, highly customized legacy IT systems prevalent in established universities, causing delays and compatibility issues.
- Regulatory Compliance Burden:Adhering to stringent data privacy regulations like Europe's GDPR and the US's FERPA requires substantial legal and technical resources, complicating product development and cross-border data flows.
Strategic Opportunities
- Southeast Asian Expansion:A growing number of universities across Southeast Asia are investing in digital infrastructure for the first time, creating significant greenfield opportunities for educational technology vendors.
- AI-Driven Assessment Tools:There is an opportunity to develop sophisticated AI-powered tools that go beyond simple grading to provide nuanced, formative feedback on complex assignments like essays and research projects.
- Vocational Training Platforms:The expansion of skills-based and vocational education programs creates a distinct market for specialized platforms focused on credentialing, hands-on simulation, and industry-specific training modules.
Industry Challenges
- Interoperability Standards:A lack of universally accepted data and interoperability standards makes it difficult for institutions to seamlessly connect different applications from multiple vendors, leading to data silos and inefficiencies.
- Cybersecurity Threats:Educational institutions are high-value targets for cyberattacks, challenging vendors to continuously update security protocols to protect sensitive student data and intellectual property from sophisticated threats.
- Faculty Training and Adoption:The effective use of advanced educational technology depends on faculty buy-in and proficiency, creating a constant need for comprehensive training and ongoing support to overcome resistance to change.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Higher Education Technology Market |
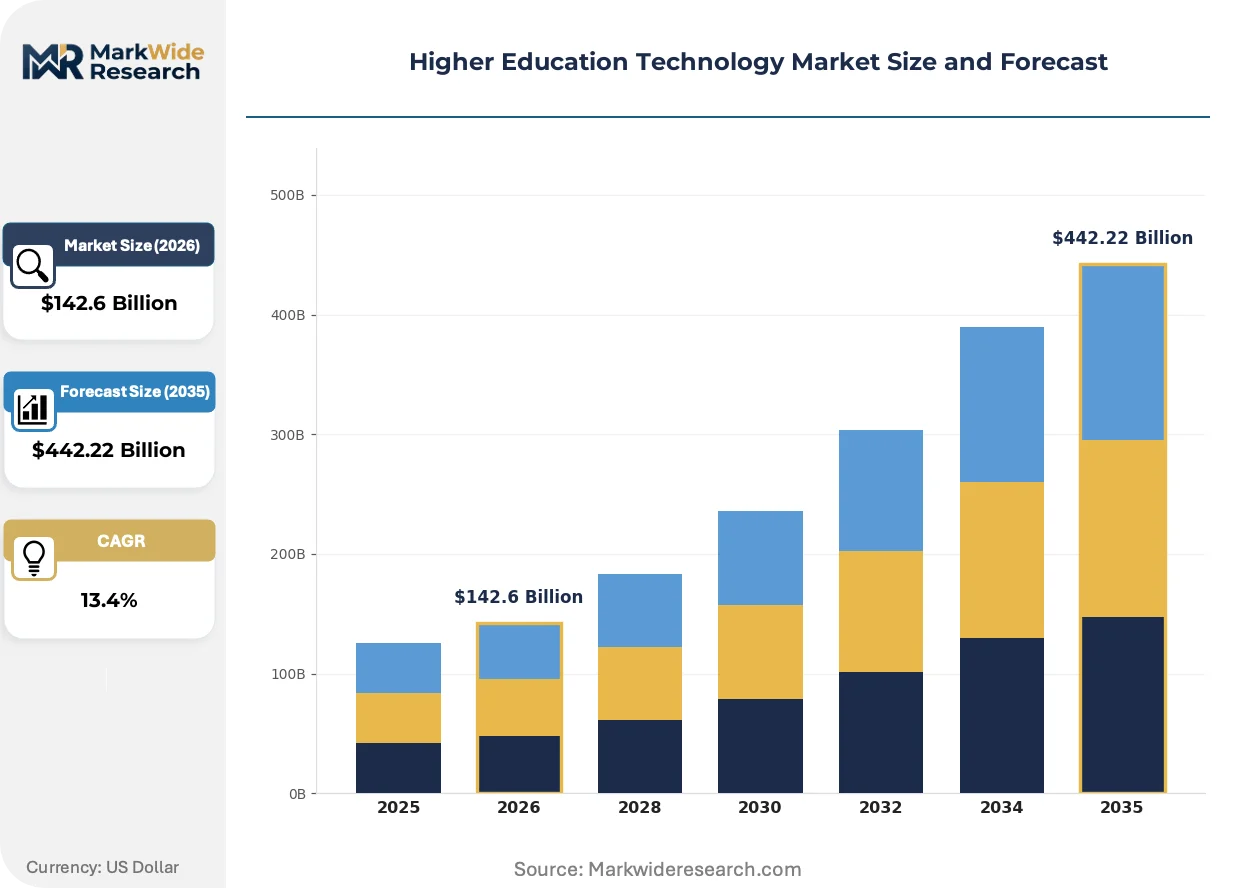
| Market Size in 2026 | $142.6 Billion |
| Market Size in 2035 | $442.22 Billion |
| CAGR (2026 – 2036) | 13.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Learning Management Systems, Virtual Labs, Classroom Response Systems, Student Information Systems, E-Books Application: Online Learning, Campus Management, Student Assessment, Content Delivery, Administrative Automation Deployment: Cloud-Based, On-Premise, Hybrid, SaaS, Mobile Applications End User: Universities, Community Colleges, Vocational Institutions, Research Institutes, Distance Learning Centers |
| Companies Covered | Oracle Corporation, Blackboard Inc., Cisco Systems Inc., Dell Inc., VMware Inc., ServiceNow Inc., CDW LLC, Astera Software, Unifyed, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Higher Education Technology Market Strategic Shifts & Innovations
Ethical considerations and data governance are becoming foundational elements of platform design. The development of trustworthy AI, as framed by regulations like the EU AI Act, is influencing how vendors architect systems for transparency and student data privacy.
Artificial intelligence engines embedded within learning platforms analyze student interaction data to identify patterns and predict academic risk. Universities are adopting these analytics tools to power early-alert systems and guide intervention strategies. This technology is hybridizing the instructional model, enabling a partnership where software manages personalized pacing while instructors focus on complex conceptual guidance.
The EU AI Act introduces a risk-based framework that directly impacts educational technology. It classifies AI systems used for student assessment or admission as high-risk, imposing strict requirements for fairness, transparency, and human oversight. Consequently, developers selling into the European market must re-architect platforms to ensure compliance, affecting global product roadmaps for Student Information Systems.
A notable behavioral shift involves universities moving from single-vendor, long-term contracts to a more agile, multi-vendor procurement approach. This "best-of-breed" strategy disrupts the market for monolithic platforms by allowing institutions to select specialized tools for specific needs, such as a dedicated application for career services. This trend is most prominent in large North American universities with robust IT departments capable of managing integration complexity.
Higher Education Technology Market Segmentation
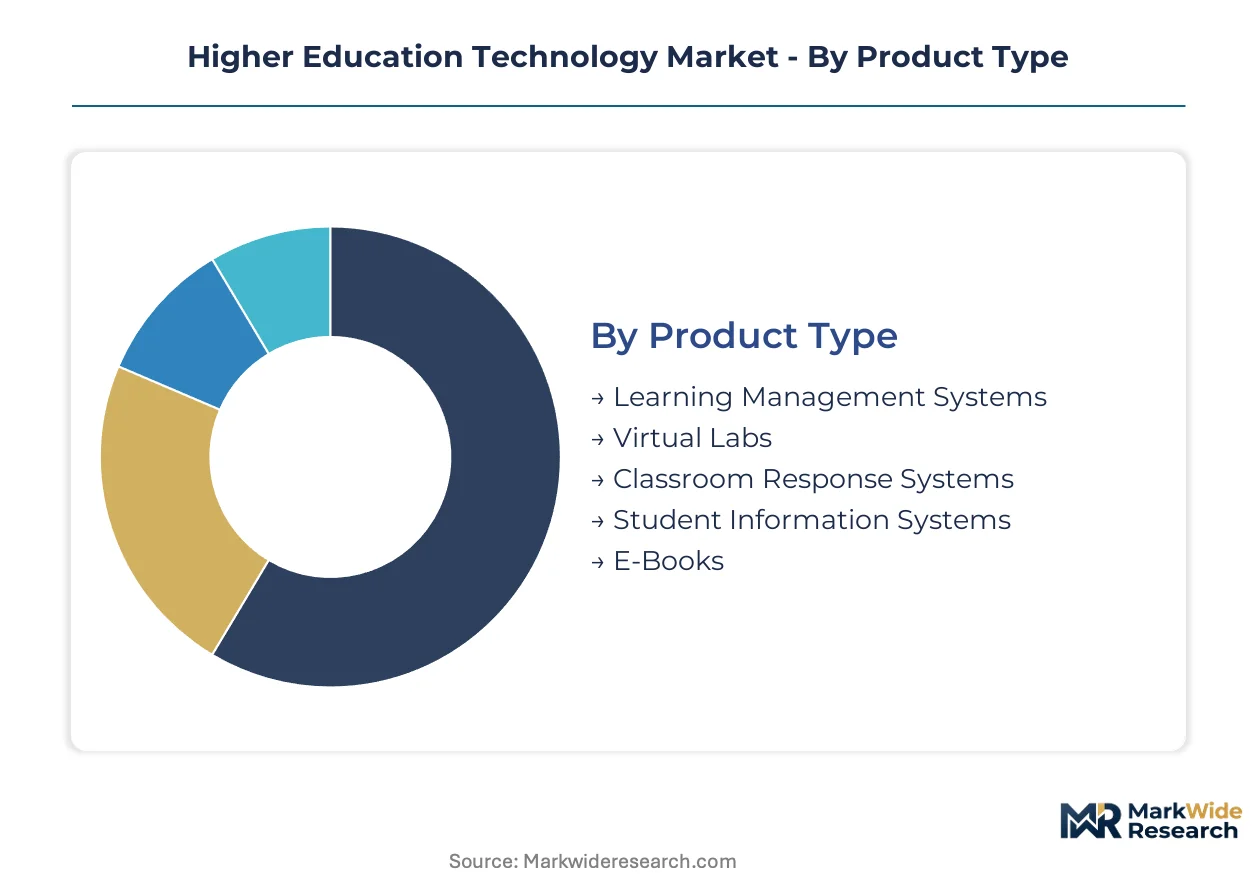
Higher education technology market segmentation provides a granular view of distinct product offerings and their adoption across various institutional settings. This detailed breakdown helps stakeholders understand where investment flows and which solutions address specific operational or pedagogical needs. Analyzing these segments reveals underlying demand patterns and technological preferences across the global landscape.
Product Type:
Product type segmentation in higher education technology identifies distinct software and hardware solutions tailored for post-secondary institutions.
- Learning Management Systems:These platforms provide a digital environment for course delivery, content sharing, and student interaction, often incorporating AI algorithms for personalized learning paths. Demand concentrates in universities seeking to hybridize instructional models and provide adaptive learning experiences.
- Student Information Systems:These comprehensive platforms manage core student data, including admissions, enrollment, grades, and financial aid, often leveraging cloud-based architectures for streamlined operations. Universities globally prioritize these systems for administrative automation and improved operational efficiency.
- Virtual Labs:Digital simulations offer hands-on experimental learning experiences, particularly in STEM fields for remote students.
- Classroom Response Systems:Interactive tools facilitate real-time polling and feedback during lectures, enhancing student engagement.
- E-Books:Digital textbooks and academic resources provide flexible access to learning materials for students.
Learning Management Systems holds installed capacity. Student Information Systems is rotating up the share rankings.
Application:
The functional application of higher education technology defines how institutions leverage digital tools to achieve pedagogical and operational objectives.
- Online Learning:This application segment encompasses platforms and tools designed for remote course delivery, virtual classrooms, and asynchronous learning, showing significant momentum among universities. Vocational institutions increasingly adopt these solutions for skills-based training and credentialing across India.
- Administrative Automation:This involves software solutions that streamline non-academic operations such as admissions, financial aid, and campus services, reducing manual workloads for university staff. Universities globally implement these tools to enhance operational efficiency and resource allocation.
- Campus Management:Integrated systems optimize facility scheduling, security, and resource allocation across university campuses.
- Student Assessment:Tools for evaluating student performance, including AI-driven feedback mechanisms for complex assignments.
- Content Delivery:Digital platforms distribute educational materials, lectures, and multimedia resources to students effectively.
Online Learning applications demonstrate substantial market traction. Administrative Automation is gaining momentum due to efficiency demands.
Deployment:
Deployment models for higher education technology dictate infrastructure requirements and accessibility for institutions.
- Cloud-Based:Solutions hosted on remote servers and accessed over the internet, offering scalability, flexibility, and reduced on-premise IT burden for institutions. Universities in Southeast Asia increasingly favor these architectures for new digital infrastructure investments.
- SaaS:Software-as-a-Service models provide subscription-based access to applications, eliminating the need for local installation and maintenance, dominating new installations. This model reduces upfront investment for smaller institutions and vocational centers.
- On-Premise:Software installed and run on local servers, offering greater control but higher maintenance costs for established universities.
- Hybrid:A combination of cloud-based and on-premise solutions, balancing data control with scalability for complex university environments.
- Mobile Applications:Dedicated apps provide access to learning content, campus services, and administrative functions on smartphones and tablets.
Cloud-Based deployments offer scalability and flexibility. SaaS models are becoming the preferred choice for new technology implementations.
End User:
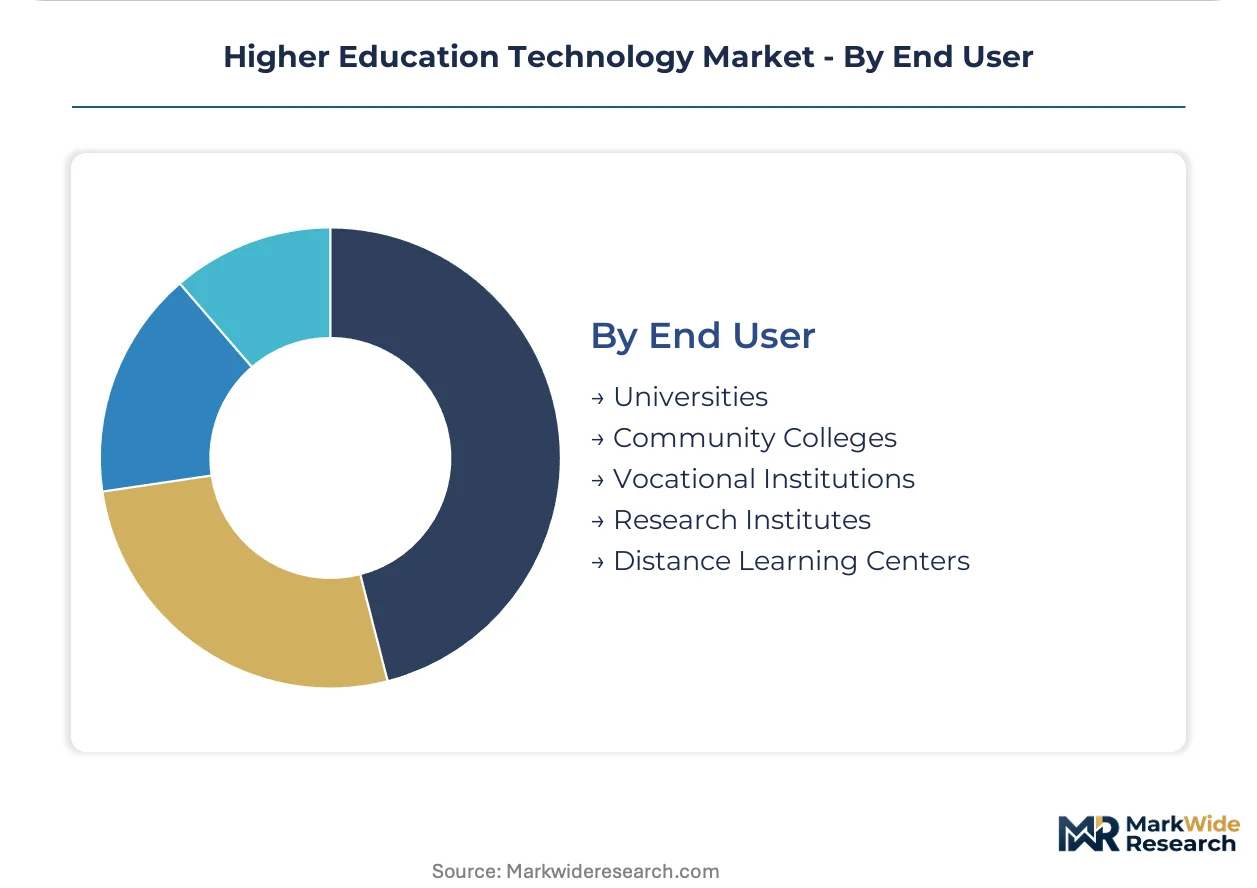
The end-user landscape for higher education technology encompasses diverse institutional types, each with unique needs and adoption patterns.
- Universities:Large, comprehensive institutions adopting advanced administrative automation tools and integrated platforms for extensive student populations and research activities. North American and European universities represent a significant segment for integrated SIS and LMS platforms.
- Vocational Institutions:Specialized centers providing skills-based training and professional certifications, increasingly investing in online learning platforms and simulation tools. Demand concentrates in India, supported by government initiatives for digital learning infrastructure.
- Community Colleges:Institutions offering associate degrees and workforce development programs, often seeking cost-effective and scalable technology solutions.
- Research Institutes:Organizations focused on advanced scientific inquiry, requiring specialized software for data analysis, collaboration, and knowledge management.
- Distance Learning Centers:Dedicated entities providing entirely remote education, heavily reliant on robust online learning platforms and content delivery systems.
Universities represent the largest installed base of technology solutions. Vocational Institutions exhibit a robust expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU AI Act significantly influences how educational platforms develop ethical AI, impacting global product roadmaps for Student Information Systems. This regulatory framework drives fundamental shifts in platform design, particularly for systems involved in student assessment or admissions. Governments in various regions, including India, are simultaneously investing heavily in digital learning infrastructure, creating distinct demand patterns for higher education technology.
United States
Universities in the United States prioritize both comprehensive, integrated platforms and best-of-breed specialized applications to meet diverse institutional needs. Data privacy regulations like FERPA heavily influence product development, mandating strict controls over student information. Major academic hubs such as Boston and Silicon Valley continue to drive innovation in ed-tech startups and adoption of advanced learning tools.
India
Government initiatives in India directly support universities in building out digital learning infrastructure and adopting new educational technologies. The national digital transformation policies stimulate demand for online learning applications, particularly among vocational institutions for skills-based training. Cities like Bangalore and Hyderabad are emerging as centers for ed-tech development, fueled by government support and a large student population.
Germany
The EU AI Act classifies AI systems used for student assessment as high-risk, imposing strict requirements on developers selling into the European market, including Germany. This regulation mandates transparency and human oversight in educational AI, influencing how German universities procure and implement new technologies. University cities such as Munich and Berlin are adapting their digital strategies to ensure compliance and ethical AI integration.
Singapore
A growing number of universities across Southeast Asia, including Singapore, are investing in digital infrastructure for the first time. Institutions increasingly favor cloud-based architectures for new digital infrastructure investments due to their scalability and flexibility. Singapore serves as a regional hub for technology adoption, with its universities actively exploring advanced administrative automation tools and personalized learning solutions.
United Kingdom
Established universities in the United Kingdom focus on administrative automation to improve operational efficiency and reduce staff workload. The UK's robust data protection framework, influenced by principles similar to GDPR, shapes product development and data governance practices within educational technology. London and other university cities are seeing a strong demand for integrated Student Information Systems and advanced Learning Management Systems.
Higher Education Technology Market Key Industry Players
Capability concentration sits with one tier; scale advantage sits with another, reflecting a fragmented supplier landscape for educational technology. This market structure features a mix of established enterprise solution providers, specialized educational software developers, and infrastructure specialists. Strategic archetypes include integrated platform vendors, niche application providers, and foundational hardware/networking companies. Competitive moves center on portfolio diversification to meet varied institutional needs and strategic partnerships to offer comprehensive solutions.
Integrated platform vendors, such as Oracle Corporation, leverage their enterprise resource planning expertise to offer comprehensive student information systems. Blackboard Inc. exemplifies the established Learning Management System specialists, sustaining market position through its widely adopted platform. Cisco Systems Inc. represents the infrastructure and collaboration tool providers, specializing in networking hardware and tools crucial for hybrid learning models.
| Leading Market Players |
|---|
| Oracle Corporation |
| Blackboard Inc. |
| Cisco Systems Inc. |
| Dell Inc. |
| VMware Inc. |
| ServiceNow Inc. |
| CDW LLC |
| Astera Software |
| Unifyed |
| Others |
Cost & Logistics Intelligence
Silicon Valley's concentration of software development talent and cloud infrastructure capacity strongly influences downstream pricing power for educational technology solutions. This geographic hub drives innovation cycles and sets cost benchmarks within the global market.
Pricing Analysis
Geographic price spreads exist, reflecting regional regulatory compliance costs and varying institutional budget capacities. SaaS-tiered subscription models dominate the market, offering institutions flexible access to educational technology platforms. Price differentiation stems from customization levels for specific university needs and the depth of after-sales technical support. Pricing softness reflects budget constraints among smaller institutions and vocational centers, often leading to competitive bidding. Large North American universities, however, exhibit less price sensitivity for comprehensive, integrated solutions.
Supply Chain Analysis
Upstream, the supply chain for higher education technology draws from cloud infrastructure services provided by global hyperscalers and specialized AI algorithm development talent. Geographic supply concentrations include the United States (Silicon Valley), India (Bangalore), and Germany for specialized software engineering. Raw material dependencies center on robust cloud computing resources and highly skilled cybersecurity expertise. Data privacy regulatory fragmentation across regions presents a structural supply chain risk. Distribution runs through direct sales channels, strategic channel partners, and cloud marketplaces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The higher education technology market exhibits a significant shift in buyer power, driven by universities increasingly adopting a best-of-breed procurement strategy that fragments demand from monolithic platform providers.
For Market Incumbents:Build an interoperability moat by developing open APIs and robust integration frameworks with third-party applications. Deepen platform capabilities in ethical AI and data governance, securing certifications that address regulations like the EU AI Act and FERPA. This strategy mitigates the threat from niche specialized vendors and evolving data privacy requirements. Investment in AI-driven assessment tools and strategic partnerships for localized content delivery represent a key lever.
For New Entrants and Emerging Players:Specialized vocational training platforms targeting skills-based education in emerging markets, particularly India, represent a highly penetrable entry point. AI-driven assessment tools offering nuanced, formative feedback on complex assignments also present significant white space. Focus go-to-market efforts on delivering highly specialized, compliant solutions for specific pedagogical needs within smaller institutions or distinct university departments.
For Investors and Strategic Acquirers:Long-term, this sits as a regulatory-driven innovation play because compliance with evolving data privacy and AI ethics frameworks will become a core competitive advantage. Target acquisition archetypes include companies with proven data privacy frameworks, niche AI assessment capabilities, or robust interoperability solutions. A significant signal to watch is increased M&A activity for specific compliance-focused technology providers or regional expansion into Southeast Asia's greenfield opportunities.
| Strategic Initiative | Industry Significance |
|---|---|
| Deepen Platform Integration | This enhances ecosystem compatibility, addressing university demand for best-of-breed solutions and reducing data silos. |
| Invest in AI Ethics Certification | This ensures compliance with regulations like the EU AI Act, building trust in high-risk AI applications for education. |
| Expand into Southeast Asia | This capitalizes on greenfield opportunities where universities are investing in digital infrastructure for the first time. |
| Launch Specialized Vocational Modules | This captures demand from skills-based training programs and government initiatives in regions like India. |
| Form Strategic Partnerships | This extends market reach and offers comprehensive solutions by combining core platforms with niche specialized tools. |
Research Approach
A standing panel of university CIOs, academic deans, IT procurement officers, and educational technology developers provided ongoing calibration for market assumptions. This primary research combined with extensive secondary validation from SEC filings of public ed-tech companies, government education policy documents, and university IT budget reports. Bottom-up and top-down triangulation ensured robust data integrity.
Multiple scenario analyses bracketed the forecast across the analysis window, accounting for various adoption rates and technological advancements. Segmentation dimensions modeled included product type, application, deployment model, end-user, and regional regulatory compliance. Compound annual growth rates were derived from historical data analysis and projected market shifts, incorporating university enrollment trends and government digital education funding as key inputs.
Macroeconomic conditions sit as an overlay; deviation in education funding levels or global economic stability would shift the trajectory of market expansion. Forecasts reflect documented assumptions regarding technology adoption and regulatory evolution. Cross-checking against national education spending reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Educational Technology (EdTech)
Virtual Reality in Education Market
Educational Technology (EdTech)
Flipped Classroom Market
Educational Technology (EdTech)
Blockchain in Edutech Market
Educational Technology (EdTech)
Smart Education and Learning Market
Educational Technology (EdTech)
Global Gamification in Education Market
Educational Technology (EdTech)
Global AI in Education Market
Educational Technology (EdTech)
Education Technology and Smart Classrooms Market
Educational Technology (EdTech)
Global Micro-Learning Market
Educational Technology (EdTech)
Artificial Intelligence (AI) in Education Market
Educational Technology (EdTech)
Asia-Pacific Digital Education Market
Educational Technology (EdTech)
Student Response System Market
Educational Technology (EdTech)
VR Education Market
Educational Technology (EdTech)
Specific Gravity Bench Apparatus Market
Educational Technology (EdTech)
Global Social Learning Platforms Market
Educational Technology (EdTech)
M-Education Market
Educational Technology (EdTech)
Artificial Intelligence in the Education Sector Market