
 Student Response System Market | 2026-2036
Student Response System Market Size, Share, and Industry Trends Forecast 2026-2036
Student Response System Market Analytics
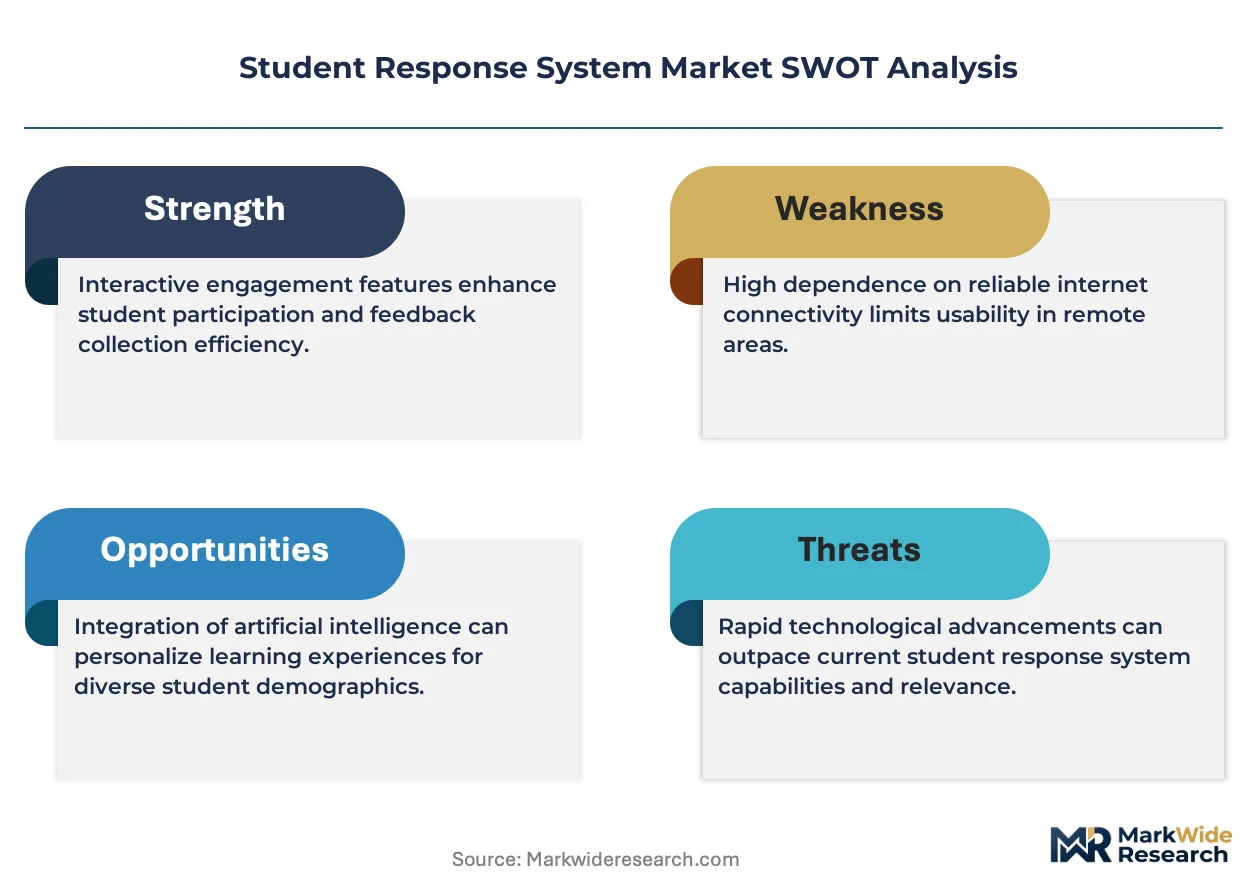
Cloud-native architecture is tilting the competitive landscape away from legacy hardware clickers toward browser-based and mobile-first platforms. Turning Technologies leverages its established institutional relationships to sustain recurring revenue from large university contracts. Kahoot! anchors its position through brand recognition in K-12 environments, while Mentimeter differentiates through enterprise-grade presentation tools that extend beyond education into corporate training.
A student response system comprises hardware or software interfaces that capture participant input during instruction, typically operating over Wi-Fi, cellular, or proprietary radio frequencies with latency thresholds below two seconds for real-time aggregation. These systems serve the primary commercial purpose of measuring comprehension, driving engagement, and generating actionable analytics for instructors or facilitators. Mobile apps now lead product type adoption as bring-your-own-device policies eliminate hardware procurement cycles, while cloud-based deployment captures the fastest growth by offloading infrastructure costs from school IT budgets. Higher education end users represent the most mature segment with established procurement frameworks, whereas corporate training offers emerging margin pools as enterprises seek interactive webinar solutions.
The Federal Communications Commission governs radio spectrum allocation for legacy clicker hardware in the United States, while the Family Educational Rights and Privacy Act constrains how student response data may be stored and shared. European deployments face additional compliance requirements under GDPR for cross-border data processing in cloud-based platforms. Stakeholders must monitor evolving accessibility standards from the Web Content Accessibility Guidelines and procurement mandates from the U.S. Department of Education's Office for Civil Rights as these frameworks increasingly influence platform selection criteria.
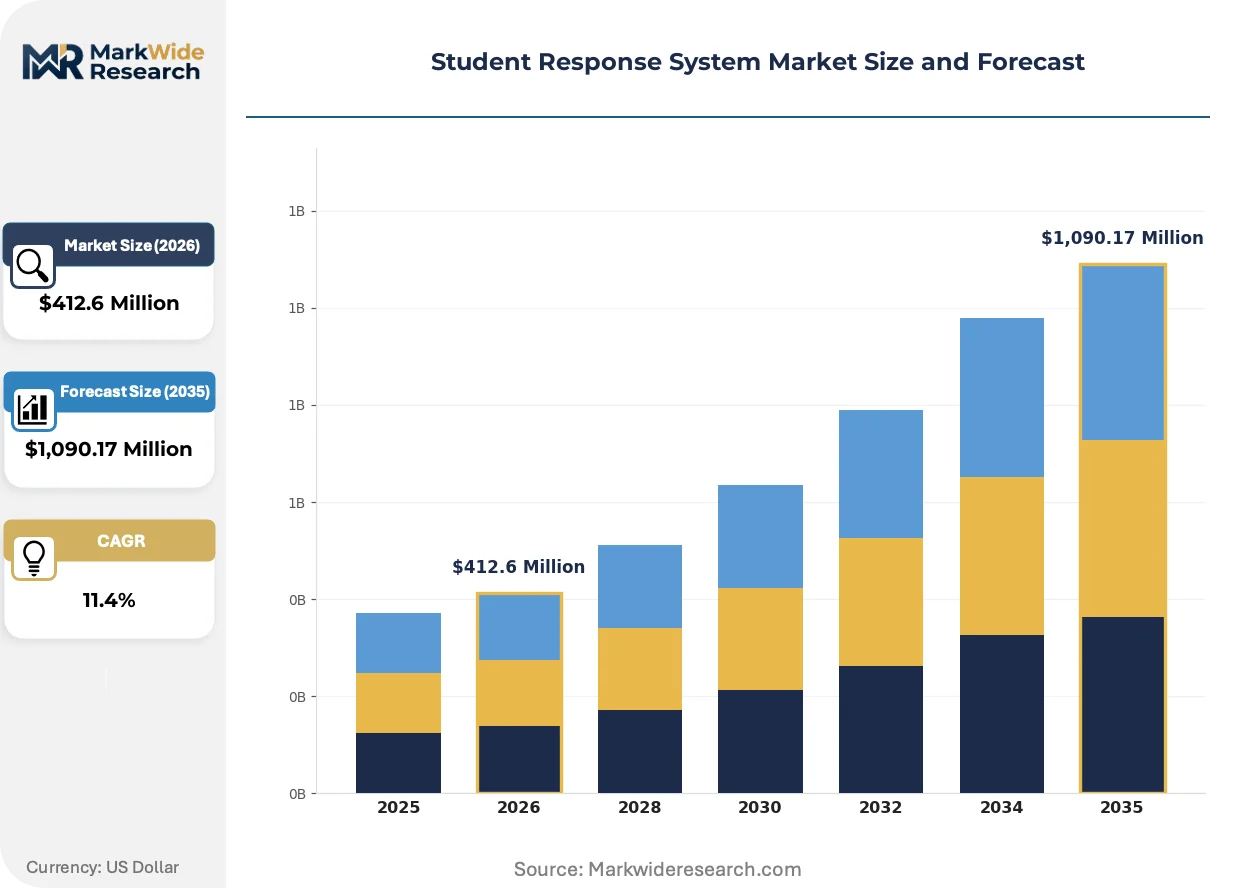
Market Dynamics
The migration from proprietary radio-frequency clickers to browser-based polling platforms is compressing hardware replacement cycles and redirecting institutional IT budgets toward recurring SaaS licensing arrangements.
Growth Catalysts
- Bring-your-own-device policies:Universities across the United States are eliminating capital expenditure on physical clicker hardware, accelerating subscription revenue for cloud-native platforms. Campus IT departments favor solutions that offload device management to students.
- Federal accessibility mandates:The U.S. Department of Education's Office for Civil Rights enforcement of Web Content Accessibility Guidelines standards is disqualifying non-compliant legacy systems from procurement shortlists.
- Real-time learning analytics:Instructors demand immediate comprehension feedback during lectures, driving integration of polling data with learning management systems like Canvas and Blackboard.
Market Restraints
- Cross-border data processing constraints:GDPR compliance requirements for European deployments impose architectural costs on cloud providers storing response data outside the European Economic Area.
- Network infrastructure dependency:Campus Wi-Fi density variations create performance inconsistency for mobile-first platforms in older university buildings with outdated access point coverage.
- Faculty adoption friction:Tenured instructors at research-intensive institutions exhibit persistent preference for established lecture formats, slowing platform rollout beyond early-adopter departments.
Strategic Opportunities
- Corporate training expansion:Enterprise learning and development departments are adopting academic engagement tools for interactive webinar delivery, opening margin pools outside education budgets.
- Artificial intelligence integration:Convergence of natural language processing with response systems enables automated comprehension gap detection and personalized content recommendation engines.
- K-12 district consolidation:State-level purchasing cooperatives in Texas and California are negotiating enterprise-wide licenses that reduce customer acquisition costs for platform vendors.
Industry Challenges
- Learning management system integration complexity:Proprietary API limitations from established LMS incumbents create friction for response system vendors seeking seamless gradebook synchronization.
- Instructional designer talent scarcity:Universities lack sufficient staff trained in pedagogical technology implementation, delaying effective deployment of advanced polling features.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Student Response System Market |
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $1,090.17 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Clickers, Mobile Apps, Web-based Solutions, Interactive Displays Deployment: Cloud-based, On-premise, Hybrid, Mobile End User: Educational Institutions, Corporate Training, K-12 Schools, Higher Education Feature: Real-time Feedback, Analytics Dashboard, Multi-language Support, Gamification |
| Companies Covered | Turning Technologies, iClicker, Poll Everywhere, Kahoot!, Top Hat, Socrative, Vevox, Mentimeter, ClassPoint, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Student Response System Market Evolving Landscape
Artificial intelligence and machine learning capabilities are embedding directly into student response platforms, transforming raw polling data into predictive intervention signals for instructors.
Browser-based polling architectures leveraging WebRTC and responsive design are rendering obsolete dedicated hardware clicker ecosystems that require proprietary base stations and radio-frequency spectrum allocation. Large public universities in the United States are completing full hardware retirement within single fiscal cycles. The shift eliminates FCC licensing burdens while enabling instantaneous feature deployment without campus infrastructure visits.
The European Union's General Data Protection Regulation enforcement against cross-border educational data transfers is compelling platform providers to establish regional data residency options. Vendors must now maintain separate cloud instances within European Economic Area boundaries. Higher education procurement committees in Germany and France are prioritizing GDPR-compliant solutions in competitive evaluations.
University purchasing committees are consolidating previously fragmented departmental software subscriptions into centralized campus-wide agreements. This concentration shifts negotiation leverage toward institutional buyers demanding volume discounts and standardized support tiers. The pattern is most pronounced among state university systems in the United States managing multi-campus technology contracts.
Student Response System Market Segmentation
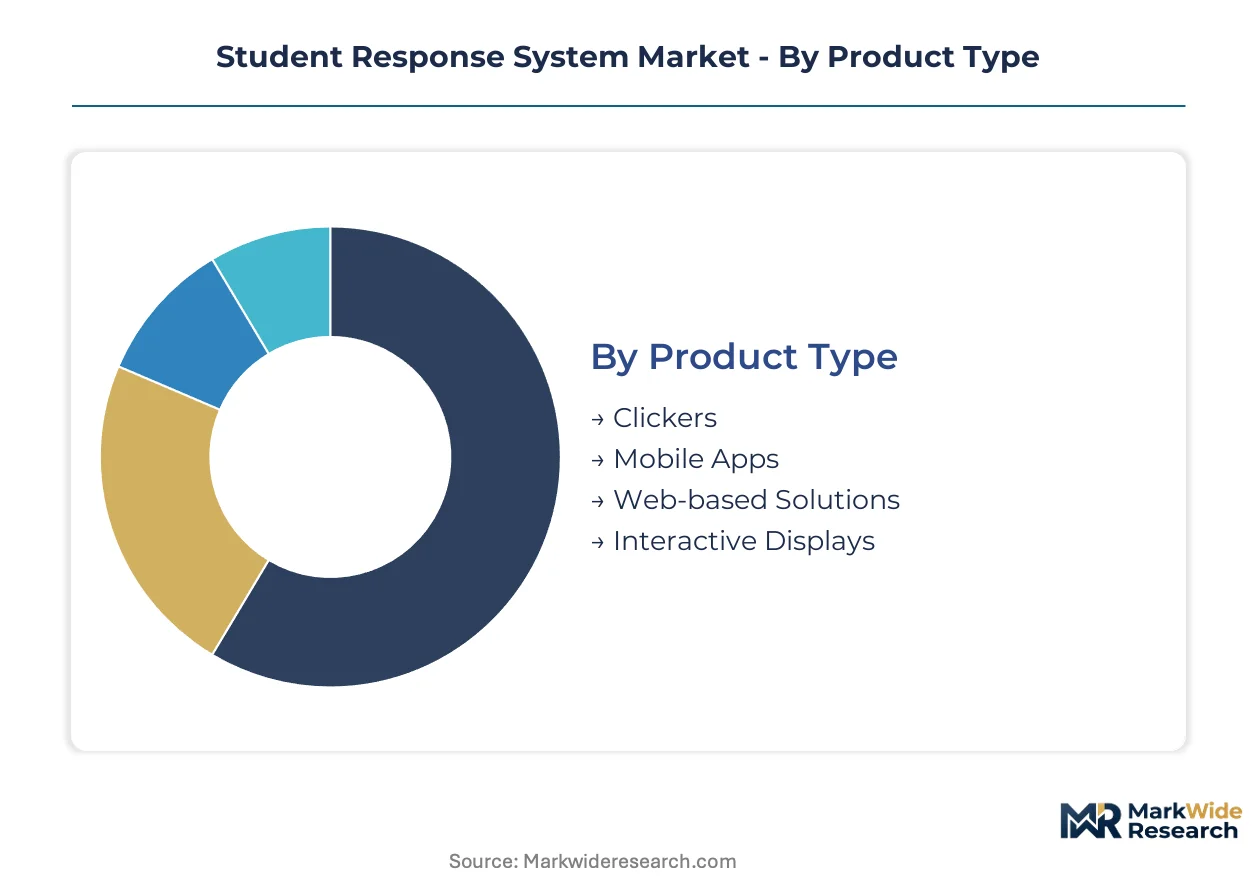
Segmentation in student response systems reveals how procurement priorities diverge across institutional contexts. Product architecture, deployment model, end-user category, and feature sophistication each create distinct competitive battlegrounds with different margin structures and switching costs.
Product Type:
Physical hardware and software interfaces span a use-case spectrum from large lecture halls requiring anonymous participation to collaborative classrooms prioritizing peer visibility.
- Mobile Apps:Browser-native and native iOS/Android applications leverage student-owned smartphones, eliminating capital expenditure cycles for campus IT departments. Demand concentrates most visibly in United States public universities implementing bring-your-own-device mandates, driven by FCC spectrum deregulation pressures that disadvantage legacy hardware. BYOD policies accelerate subscription revenue models.
- Web-based Solutions:Responsive web platforms utilizing WebRTC deliver real-time polling without installation requirements, operating across any network-connected device. Higher education institutions in Germany and France prioritize these architectures for GDPR-compliant data residency, constrained by cross-border processing restrictions under European Union enforcement. Cloud infrastructure offloads compliance liability.
- Clickers:Proprietary radio-frequency hardware with dedicated base stations requires FCC spectrum licensing in United States deployments. K-12 districts with restricted smartphone policies sustain residual demand.
- Interactive Displays:Touchscreen-integrated response interfaces combine visualization with input capture. Corporate training environments in Japan adopt these for hybrid webinar delivery.
The dominant share belongs to Mobile Apps, while Web-based Solutions are closing the gap fastest.
Deployment:
Cost tier differentiation separates institutions with mature cloud procurement frameworks from those maintaining captive data centers.
- Cloud-based:Multi-tenant SaaS architectures distribute infrastructure costs across subscriber bases, enabling instantaneous feature deployment without campus visits. United States higher education procurement committees favor these for operational expenditure predictability.
- Hybrid:Split architectures process sensitive response data on-premise while leveraging cloud analytics engines. German universities adopt these configurations to satisfy GDPR data residency requirements without sacrificing computational scalability.
- On-premise:Self-hosted installations within institutional data centers persist in defense and government-affiliated training programs with classified information handling mandates.
- Mobile:Edge-computed deployments utilizing cellular networks bypass campus Wi-Fi dependency. Rural community colleges in Texas deploy these where infrastructure density lags.
Cloud-based deployment captures institutional preference, though Hybrid architectures are expanding most quickly in European markets.
End User:
Customer type determines pricing tolerance and feature complexity requirements across education and enterprise verticals.
- Higher Education:Research-intensive universities with established learning management system integrations demand enterprise-grade analytics and gradebook synchronization. United States state university systems negotiate centralized campus-wide licenses, compressing vendor margins through volume concentration.
- Corporate Training:Enterprise learning and development departments repurpose academic engagement tools for interactive webinar delivery. Technology sector employers in California and Washington state drive adoption of AI-integrated comprehension tracking.
- K-12 Schools:District-level purchasing cooperatives in Texas and California negotiate enterprise agreements, reducing customer acquisition costs for platform vendors.
- Educational Institutions:Broad category encompassing vocational and continuing education programs with fragmented procurement authority.
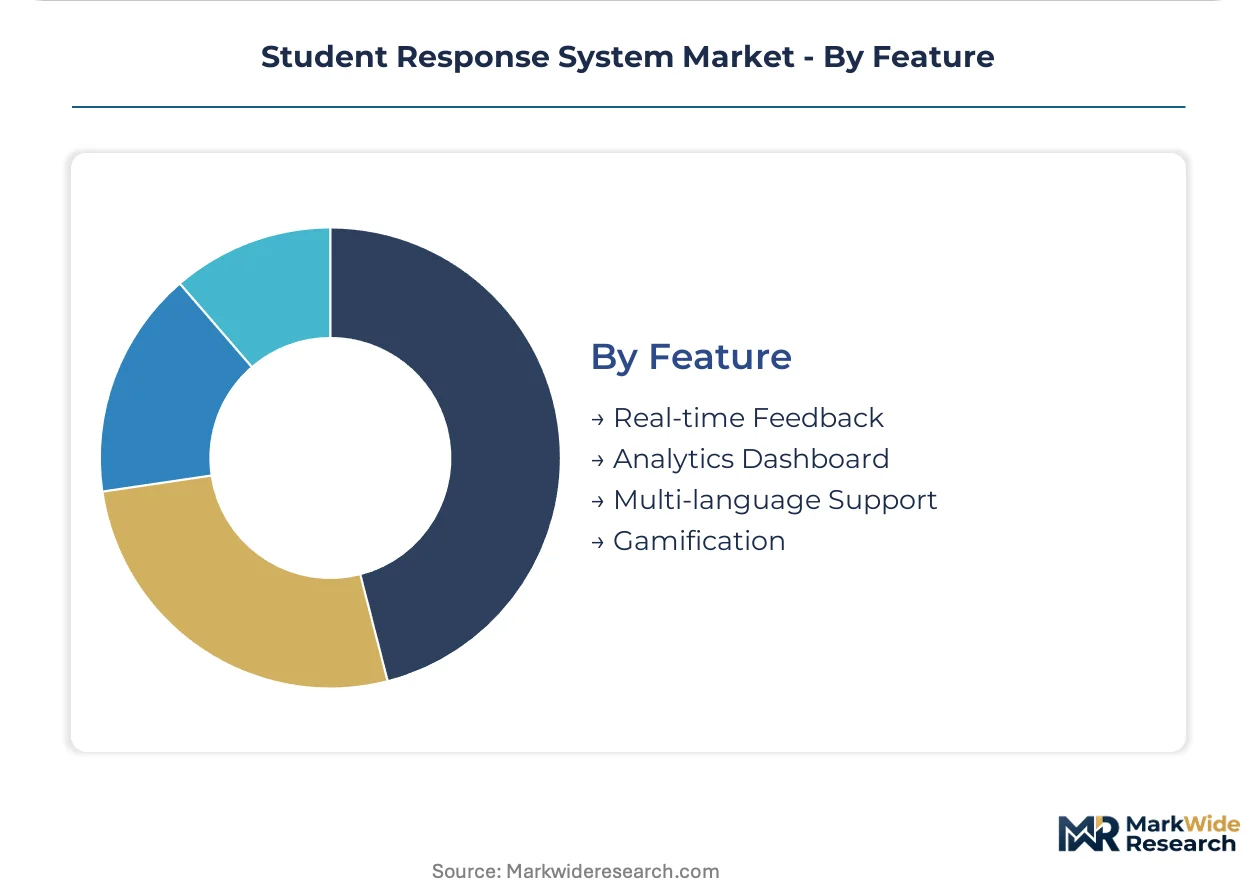
Higher Education commands the largest revenue pool, while Corporate Training is climbing the fastest as enterprises seek interactive webinar solutions.
Feature:
Maturity gradients separate baseline participation tools from advanced pedagogical intelligence layers.
- Real-time Feedback:Sub-two-second latency aggregation enables immediate instructor intervention during lectures. Canvas and Blackboard integration requirements dominate United States procurement specifications.
- Analytics Dashboard:Predictive comprehension gap detection using natural language processing transforms raw polling into actionable intervention signals. Japanese universities pilot these for personalized content recommendation engines.
- Gamification:Points, leaderboards, and competitive mechanics drive engagement in K-12 environments where intrinsic motivation requires external reinforcement.
- Multi-language Support:Interface localization and simultaneous translation accommodate international student populations and cross-border corporate training deployments.
Real-time Feedback retains foundational status, though Analytics Dashboard capabilities are gaining share fastest as AI integration deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
University IT departments in the United States, Germany, Japan, the United Kingdom, and Australia concentrate procurement authority for student response systems. These buyers prioritize cloud-native architectures, accessibility compliance, and learning management system integration.
United States
State university systems negotiate centralized campus-wide licenses, compressing vendor margins through volume concentration. The FCC governs radio spectrum allocation for legacy clicker hardware while FERPA constrains student response data storage and sharing protocols. Large public universities in California and Texas are completing full hardware retirement within single fiscal cycles.
Germany
Higher education procurement committees prioritize GDPR-compliant web-based solutions with regional data residency options. The CNIL enforces cross-border data processing restrictions under European Union frameworks. Universities in Bavaria and Baden-Württemberg adopt hybrid architectures to satisfy data residency requirements without sacrificing computational scalability.
Japan
Corporate training environments drive adoption of interactive displays for hybrid webinar delivery while universities pilot AI-integrated analytics dashboards. METI oversees technology procurement standards for educational institutions. Technology sector employers in Tokyo and Osaka anchor demand for comprehension tracking tools.
United Kingdom
Research-intensive universities demand enterprise-grade analytics and gradebook synchronization with established learning management systems. The Information Commissioner's Office enforces GDPR compliance for cloud-based educational platforms. Higher education clusters in London and the Southeast lead procurement of browser-native polling architectures.
Australia
Universities leverage responsive web platforms to eliminate hardware procurement cycles and reduce IT infrastructure burdens. The Office of the Australian Information Commissioner governs privacy requirements for student data processing. Institutions in New South Wales and Victoria concentrate adoption of mobile-first engagement tools.
Student Response System Market Competitive Landscape
Channel-controlling players compete with product-specialist players across deployment models and end-user segments. The market exhibits tiered consolidation with established institutional relationships sustaining recurring revenue against agile cloud-native entrants. Three archetypes dominate: legacy hardware vendors transitioning to SaaS, mobile-first platform specialists, and presentation-software incumbents extending into education. Competitive moves center on learning management system integration partnerships and geographic expansion through regional data residency infrastructure.
Within the established institutional tier, Turning Technologies and iClicker occupy positions anchored by large university contract relationships. Kahoot! exemplifies the brand-recognition archetype originating in K-12 environments. Mentimeter represents the enterprise-presentation extension model, differentiating through tools that serve corporate training verticals beyond education.
| Leading Market Players |
|---|
| Turning Technologies |
| iClicker |
| Poll Everywhere |
| Kahoot! |
| Top Hat |
| Socrative |
| Vevox |
| Mentimeter |
| ClassPoint |
| Others |
Value Network & Pricing Analysis
Overcapacity in cloud infrastructure provisioning across United States hyperscaler regions is compressing marginal hosting costs for student response system vendors while simultaneously intensifying pricing competition for campus-wide SaaS contracts. This utilization dynamic redirects supplier investment toward differentiation layers above raw compute and shapes institutional procurement leverage.
Pricing Analysis
Annual subscription contracts with higher education procurement committees typically index to campus full-time equivalent enrollment tiers rather than per-seat activation. Pricing stratifies across enterprise analytics, standard polling, and basic participation tiers, with differentiation anchored in LMS integration depth and AI-enabled comprehension tracking. Cost compression in the standard tier is intensifying because browser-native architectures eliminate proprietary hardware margins. K-12 district purchasing cooperatives exhibit the highest price sensitivity, while research-intensive universities prioritize feature completeness over per-license economics.
Supply Chain Analysis
Contract manufacturing for legacy clicker hardware concentrates with electronics manufacturing services in Shenzhen and Dongguan, while cloud-native platform development draws from engineering talent clusters in Bangalore and Berlin. Critical inputs span WebRTC signaling infrastructure, natural language processing APIs, and regional data residency server farms. Single-source vulnerability in proprietary radio-frequency chipset supply chains for remaining hardware deployments creates discontinuity risk as FCC spectrum reallocation accelerates. Distribution runs through direct enterprise sales teams for large university systems and value-added resellers for fragmented K-12 markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in switching costs: institutional learning management system integrations and multi-year campus-wide contracts create substantial friction against platform displacement.
For Market Incumbents: Harden institutional relationships through deeper Canvas and Blackboard gradebook synchronization while accelerating AI feature deployment to widen capability gaps against emerging browser-native entrants. Threat substitution from mobile-first challengers with superior user experience demands preemptive capability investment. Vertical integration into instructional design consulting services captures procurement committee attention and extends contract renewal cycles. For New Entrants and Emerging Players: Corporate training verticals in Japan and Australia show geographic underpenetration by established education-focused vendors, presenting white-space acquisition opportunities outside saturated North American higher education markets. Mid-sized enterprises with hybrid webinar requirements represent the most penetrable segment due to lower procurement formality. A channel partnership strategy through learning and development consultancies bypasses direct competition with entrenched academic sales teams. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-native deployment models as multi-tenant architectures achieve scale efficiencies, improving cash conversion profiles for SaaS-native targets. Viable acquisition archetypes include regional platform specialists with GDPR-compliant infrastructure and established European university relationships. The signal to watch is campus-wide license consolidation velocity within United States state university systems as an indicator of pricing power erosion or concentration opportunity.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Native Canvas and Blackboard synchronization satisfies procurement committee technical requirements. |
| Regional Data Residency | GDPR-compliant cloud instances in Frankfurt and Paris unlock German and French university tenders. |
| AI Feature Development | Automated comprehension gap detection differentiates enterprise-tier subscriptions from standard polling. |
| Channel Partnership | Learning and development consultancies extend reach into underpenetrated corporate training verticals. |
| Hardware Retirement Acceleration | FCC spectrum deregulation pressures force legacy clicker vendors toward SaaS transition or exit. |
Research Methodology
A spread of perspectives from chief technology officers at state university systems, learning management system integration specialists, campus procurement committee chairs, and instructional technology directors converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation against SEC filings from publicly traded platform vendors, United States Department of Education Office for Civil Rights enforcement documentation, and European Data Protection Board GDPR guidance for educational data processing. Bottom-up enrollment-driven modeling and top-down addressable market sizing were triangulated against observed contract values.
Demand-supply balance framing anchored the analytical framework across the projection horizon, with segmentation modeled across deployment architecture, end-user institutional type, and feature sophistication tier. CAGRs were derived from enrollment growth projections, SaaS pricing trend analysis, and technology substitution curves for hardware-to-software transitions. Industry-specific forecast inputs included FCC spectrum policy trajectories and European Union cross-border data transfer enforcement patterns.
The forecast holds incumbent behavior within observed patterns; aggressive pricing moves by well-capitalized presentation-software incumbents or accelerated AI capability deployment by emerging challengers would shift outcomes beyond modeled ranges. Quarterly review of campus-wide contract renewal rates and instructional designer hiring velocity at research-intensive universities is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Educational Technology (EdTech)
M-Education Market
Educational Technology (EdTech)
Game-Based Learning Market
Educational Technology (EdTech)
Global Social Learning Platforms Market
Educational Technology (EdTech)
Edutainment Market
Educational Technology (EdTech)
Edtech Market
Educational Technology (EdTech)
North America Digital Education Market
Educational Technology (EdTech)
SETM Education Market
Educational Technology (EdTech)
Education Apps Market
Educational Technology (EdTech)
Higher Education Technology Market
Educational Technology (EdTech)
Global Smart Learning Market
Educational Technology (EdTech)
Asia-Pacific Digital Education Market
Educational Technology (EdTech)
Flipped Classroom Market
Educational Technology (EdTech)
Smart Education and Learning Market
Educational Technology (EdTech)
Education Security Market
Educational Technology (EdTech)
AI in K-12 Education Market
Educational Technology (EdTech)
Education Technology Market