
 Global Smart Learning Market | 2026-2036
Global Smart Learning Market Size, Share, and Industry Trends Forecast 2026-2036
Global Smart Learning Market Foresight
Subscription-based software licensing is rebalancing how educational technology vendors monetize platform access. Microsoft Corporation leverages its Azure cloud infrastructure to anchor institutional deployments across K-12 and higher education segments. Google LLC competes through workspace-integrated learning tools that sustain engagement across distributed classrooms. Adobe Inc. specializes in creative-skills credentialing that differentiates its offering from generalist platforms.
Smart learning encompasses digitally delivered education systems that employ adaptive algorithms, real-time analytics dashboards, and multimodal content delivery to personalize instruction pathways. These platforms typically integrate learning management system architectures with artificial intelligence engines that adjust difficulty curves based on learner performance telemetry. Learning Management Systems capture the largest installed base among technology segments, while Artificial Intelligence integration commands the fastest expansion trajectory as vendors embed generative tutoring and automated assessment capabilities. Corporate Training applications generate the highest per-seat margins, whereas K-12 Education represents the deepest volume pool shaped by government procurement cycles.
The EU AI Act imposes algorithmic transparency requirements on adaptive learning systems deployed across European member states, while GDPR restricts how student behavioral data may be retained and processed. The FDA regulates certain clinical-education and medical-training smart learning modules in the United States, and China's SAMR oversees content compliance for platforms operating under national GB standards. Stakeholders must monitor how divergent data-localization mandates between jurisdictions reshape platform architecture decisions and cross-border service delivery models.
Market Dynamics
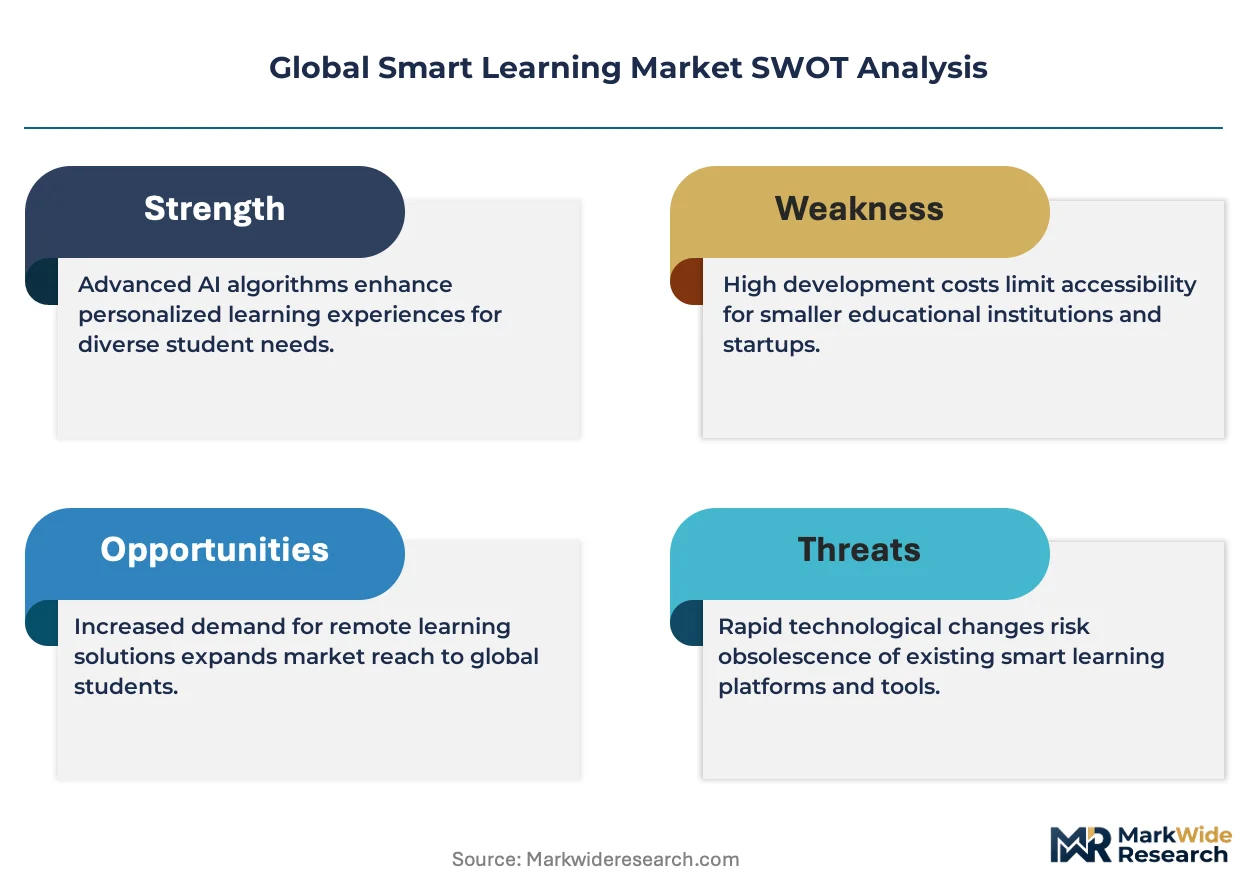
Adaptive algorithm deployment is restructuring competitive positioning across the smart learning ecosystem, forcing vendors to rebuild architectures around real-time performance telemetry and automated content personalization rather than static course libraries.
Growth Catalysts
- EU AI Act transparency mandates:European procurement specifications now require explainable adaptive systems, creating first-mover advantages for vendors with auditable algorithmic architectures.
- Corporate training digitization:Multinational employers are consolidating learning budgets onto integrated platforms that unify skills credentialing with workforce analytics.
- China's national digital education infrastructure:Provincial governments under SAMR oversight are standardizing smart classroom deployments across tier-2 and tier-3 cities.
Market Restraints
- Cloud infrastructure cost concentration:Platform economics depend on hyperscaler pricing from US-based providers, exposing margins to currency and capacity volatility.
- GDPR data localization friction:Cross-border student telemetry storage requires jurisdictional server segmentation that fragments operational scale.
- Legacy LMS substitution inertia:Institutional procurement cycles extend replacement timelines for established learning management systems.
Strategic Opportunities
- India's National Education Policy implementation:State-level digital infrastructure tenders are opening procurement channels for adaptive assessment platforms.
- Generative tutoring convergence:Large language model integration with multimodal content engines is creating new product categories beyond traditional courseware.
- Skills-based hiring mandates:Employer credential verification requirements are expanding addressable markets for micro-certification and competency tracking modules.
Industry Challenges
- Algorithmic audit talent scarcity:Vendors struggle to recruit machine learning engineers with cross-functional expertise in educational psychology and regulatory compliance.
- Interoperability standard delays:Fragmented data exchange protocols between learning management systems and third-party assessment tools increase integration costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Smart Learning Market |
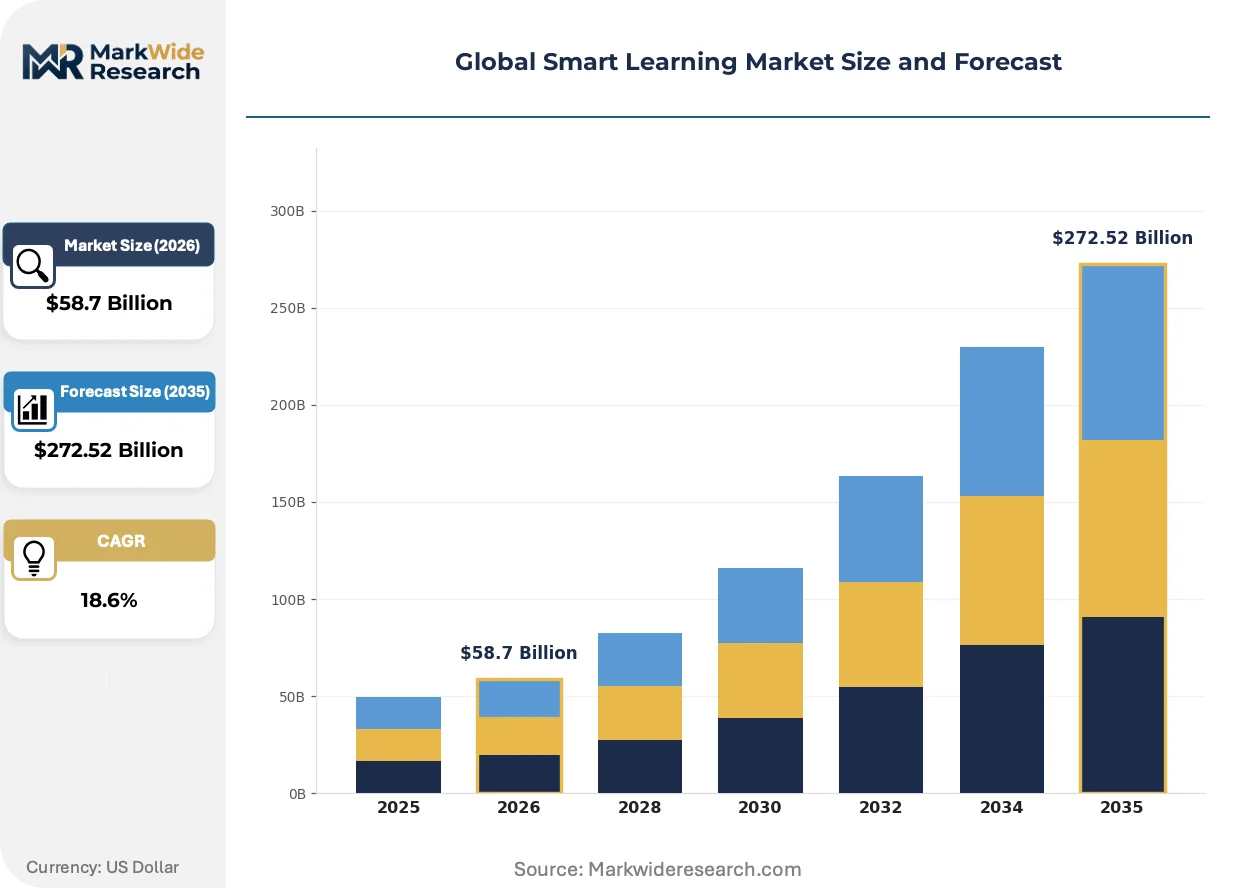
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $272.52 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Artificial Intelligence, Virtual Reality, Augmented Reality, Machine Learning, Natural Language Processing, Learning Management Systems Application: K-12 Education, Corporate Training, Higher Education, Skill Development, Language Learning, Professional Certification Deployment: Cloud-based, On-Premises, Hybrid, Web-based, Mobile Platform, Desktop Application End User: Students, Corporates, Educational Institutions, Training Providers, Government Organizations, Non-profit Organizations |
| Companies Covered | Microsoft Corporation, Google LLC, Adobe Inc., Cisco Systems Inc., Pearson plc, IBM, Samsung, Coursera Inc., Instructure Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Smart Learning Market Shifts & Advancements
Generative content engines are compressing production timelines for personalized learning materials, while regulatory pressure on algorithmic accountability is forcing architectural redesigns across vendor portfolios.
Multimodal adaptive tutoring systems that synthesize text, voice, and visual interaction channels are overtaking single-format delivery platforms in institutional procurement evaluations. Higher education technology committees are prioritizing these systems for first-year gateway courses with high attrition rates. The shift is compressing addressable markets for legacy video-based courseware providers.
The EU AI Act's risk-classification framework for educational algorithms is mandating documentation burdens that favor established vendors with compliance infrastructure. European member state procurement authorities are embedding these requirements into tender specifications before formal enforcement dates. K-12 platform vendors serving Germany, France, and the Netherlands are restructuring product roadmaps around algorithmic explainability features.
Enterprise learning buyers are consolidating vendor relationships around outcome-verified subscription models that tie contract renewals to measured skills acquisition metrics. Corporate training departments are displacing seat-based licensing with competency-outcome structures. This pattern is most visible in United States financial services and healthcare employer segments where regulatory continuing education requirements create predictable procurement cycles.
Global Smart Learning Market Segmentation
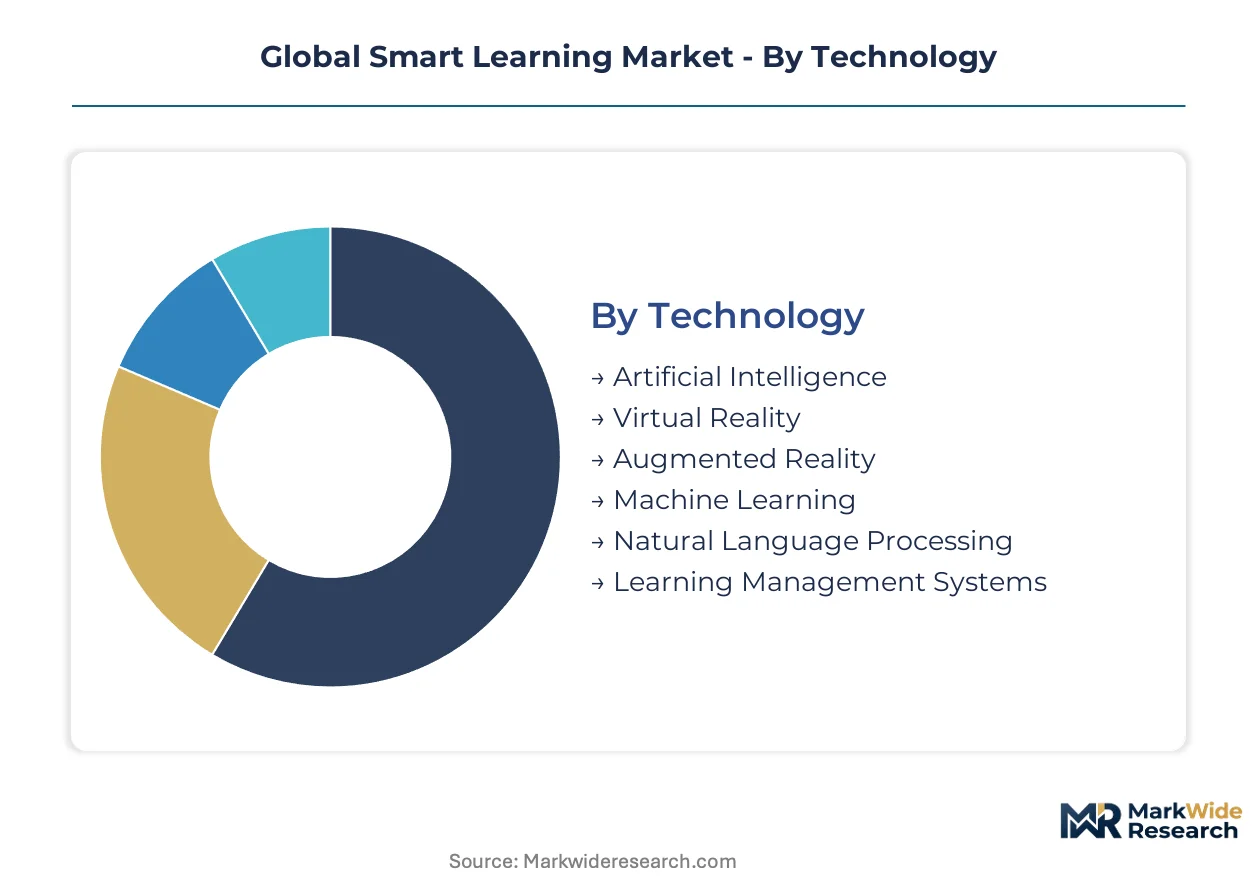
Smart learning vendors structure product portfolios across four intersecting dimensions that determine pricing architecture and customer acquisition costs. Technology selection dictates R&D capitalization requirements, while deployment mode shapes ongoing infrastructure economics.
Technology:
Capital intensity varies sharply across technology segments, with AI engines demanding the heaviest upfront investment in specialized machine learning talent and compute infrastructure.
- Artificial Intelligence:Adaptive algorithms process real-time learner telemetry to adjust difficulty curves and content sequencing automatically. Corporate training departments in United States financial services firms are prioritizing AI-powered platforms that demonstrate measurable skills acquisition outcomes.
- Learning Management Systems:Institutional-grade LMS architectures integrate gradebooks, attendance tracking, and third-party content libraries through standardized APIs. K-12 procurement cycles in India and China are consolidating around LMS-first deployments that accommodate low-bandwidth environments.
- Virtual Reality:Immersive simulation environments require substantial content production investment and specialized hardware partnerships.
- Augmented Reality:Overlay systems blend physical classroom elements with digital annotations for STEM visualization.
- Machine Learning:Predictive models identify at-risk learners before attrition events occur.
- Natural Language Processing:Automated essay scoring and conversational tutoring interfaces reduce instructor grading burden.
Learning Management Systems absorb the bulk of installed capacity; Artificial Intelligence is expanding most quickly.
Application:
Per-seat margins diverge substantially across application types, with corporate buyers tolerating premium pricing for outcome-verified credentialing.
- Corporate Training:Workforce analytics integration unifies skills gap assessment with personalized learning pathways. Multinational employers in Germany and France are consolidating learning budgets onto platforms that satisfy EU AI Act algorithmic transparency requirements.
- K-12 Education:Government procurement cycles drive volume concentration, with national digital infrastructure programs in China and India standardizing platform specifications across provincial school systems.
- Higher Education:University technology committees evaluate platforms for gateway course retention improvement.
- Skill Development:Micro-credentialing modules address specific competency gaps for career transitioners.
- Language Learning:Speech recognition engines enable pronunciation feedback at scale.
- Professional Certification:Regulatory continuing education mandates create predictable renewal revenue streams in healthcare and accounting sectors.
K-12 Education dominates volume deployment; Corporate Training commands the steepest expansion trajectory in revenue terms.
Deployment:
Operational scale economics favor cloud-native architectures, though data localization mandates fragment infrastructure decisions.
- Cloud-based:Hyperscaler-hosted platforms achieve operational leverage through shared infrastructure pools. GDPR compliance requirements in European deployments necessitate EU-region server segmentation that increases cost complexity.
- On-Premises:Institutions with sensitive research data or classified training content maintain physical infrastructure control.
- Hybrid:Split architectures keep core student records local while offloading compute-intensive analytics to cloud instances.
- Web-based:Browser-delivered experiences minimize client-side installation friction.
- Mobile Platform:Smartphone-optimized interfaces dominate skill development and language learning in India.
- Desktop Application:Resource-intensive creative software training requires local GPU access.
Cloud-based deployment captures the majority of new implementations; Mobile Platform is climbing the fastest in emerging market penetration.
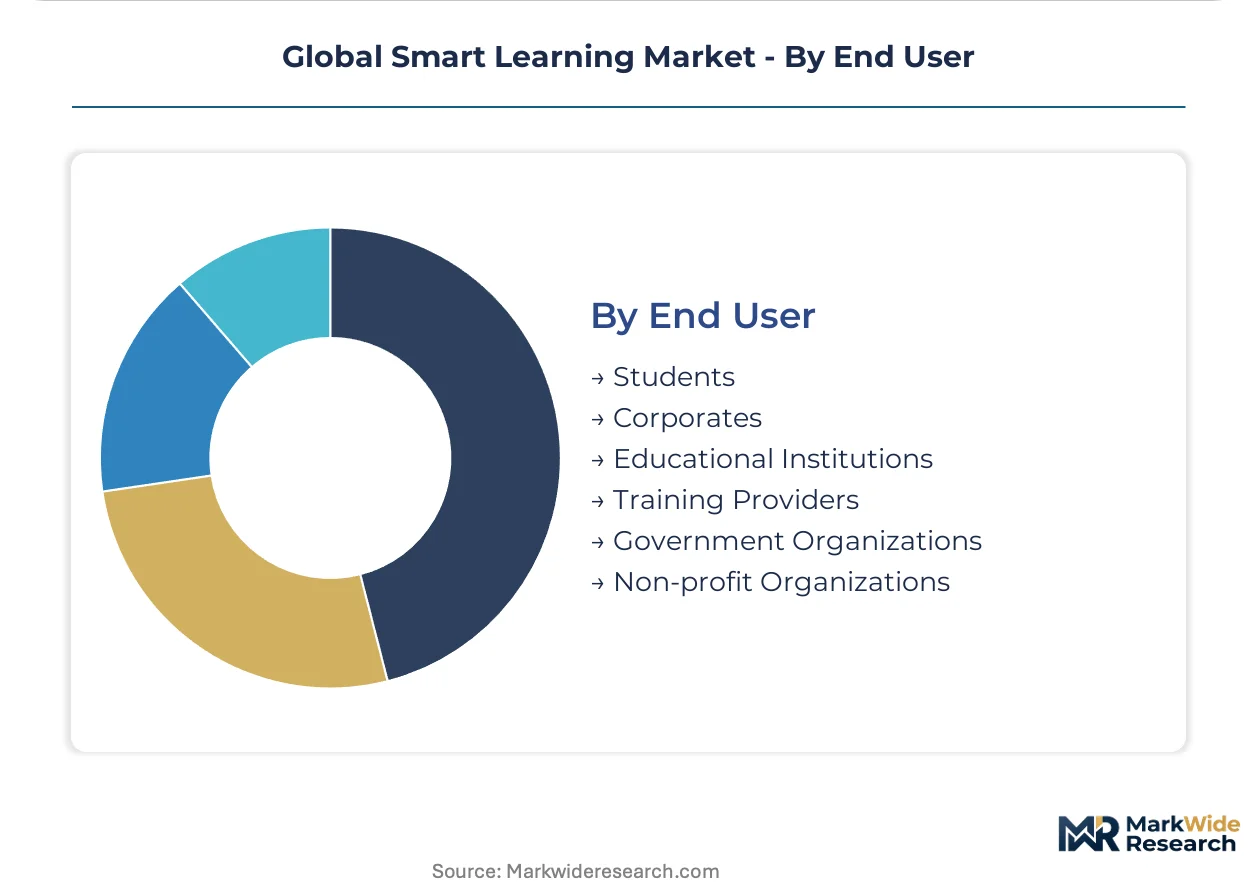
End User:
Budget authority concentration shapes sales cycle duration, with government tenders extending procurement timelines substantially.
- Students:Individual subscription purchases respond to direct-to-consumer marketing and peer recommendation networks. Chinese provincial scholarship programs subsidize platform access for rural students under SAMR content compliance oversight.
- Corporates:Centralized learning and development budgets enable enterprise-wide licensing negotiations.
- Educational Institutions:University and school district IT committees evaluate interoperability with existing authentication systems.
- Training Providers:Commercial education businesses resell platform access bundled with instructor services.
- Government Organizations:National digital education initiatives in India and China issue multi-year framework agreements.
- Non-profit Organizations:Foundation-funded programs target underserved learner populations with subsidized access models.
Educational Institutions hold the deepest installed base; Corporates are gaining share fastest as skills-based hiring mandates expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon Valley anchors the highest concentration of smart learning platform engineering talent, with venture-backed adaptive algorithm startups clustering around Stanford University and San Francisco enterprise software corridors.
United States
Corporate training digitization drives platform procurement across financial services and healthcare employers. FDA oversight of clinical-education modules shapes compliance architecture for medical-training vendors. Boston's edtech corridor hosts established learning management system providers serving higher education institutions with gateway course retention mandates.
China
Provincial governments under SAMR oversight standardize smart classroom deployments across tier-2 and tier-3 cities. National GB standards for educational content compliance reshape platform localization requirements. The Yangtze River Delta concentration of technology infrastructure providers supplies cloud-native deployment architectures for state digital education tenders.
India
State-level National Education Policy implementation opens procurement channels for adaptive assessment platforms. BIS certification requirements influence hardware-software integration specifications for government school deployments. Bangalore's technology corridor hosts platform engineering centers serving both domestic K-12 tenders and export markets.
Germany
Industrial employer apprenticeship digitization creates demand for outcome-verified credentialing systems. KBA and federal data protection authorities enforce GDPR-compliant student telemetry handling across Länder education ministries. Munich's enterprise software cluster anchors vendor compliance engineering for EU AI Act algorithmic transparency mandates.
United Kingdom
Higher education technology committees prioritize multimodal adaptive tutoring for first-year retention improvement. The Information Commissioner's Office enforces GDPR restrictions on cross-border student data flows. London's financial services learning and development departments consolidate vendor relationships around skills-based hiring verification platforms.
Global Smart Learning Market Competitive Landscape
Capital-heavy cloud infrastructure providers compete with asset-light adaptive algorithm specialists for institutional procurement contracts. The vendor landscape organizes into three tiers: hyperscaler-backed platform suites, specialized learning management system architects, and vertical-focused credentialing providers. Strategic differentiation centers on compliance-ready algorithmic transparency features and outcome-verified subscription structures. Competitive moves concentrate on M&A consolidation of assessment engine capabilities and strategic partnerships with national digital education infrastructure programs.
Within the hyperscaler tier, Microsoft Corporation and Google LLC anchor cloud-native deployment architectures across K-12 and higher education segments. Adobe Inc. occupies a specialist position in creative-skills credentialing that differentiates its offering from generalist platforms. IBM represents the enterprise analytics convergence archetype, integrating workforce intelligence with learning pathway optimization.
| Leading Market Players |
|---|
| Microsoft Corporation |
| Google LLC |
| Adobe Inc. |
| Cisco Systems Inc. |
| Pearson plc |
| IBM |
| Samsung |
| Coursera Inc. |
| Instructure Inc. |
| Others |
Supply & Pricing Matrix
Hyperscaler compute pricing indices cascade through smart learning platform economics, compressing margins for vendors tethered to AWS, Azure, and Google Cloud infrastructure while enabling SaaS-tiered subscription models that segment buyers by institutional scale and compliance sophistication.
Pricing Analysis
Margin tightening in cloud-hosted tiers reflects hyperscaler pass-through cost volatility and EU GDPR server-segmentation requirements. Three-tier pricing structure across enterprise, academic, and individual levels stratifies by volume commitment and algorithmic audit documentation depth. Cost-down pressure on mid-market offerings accelerates because Indian and Chinese government tenders prioritize low-bandwidth optimization over premium AI features. K-12 procurement committees exhibit highest price sensitivity; corporate training departments in financial services tolerate premium positioning for outcome-verified credentialing.
Supply Chain Analysis
Cross-border data transfer costs and jurisdictional server fragmentation inflate operational overhead for vendors serving European and Chinese markets simultaneously. Engineering talent concentrates in the United States, India, and China, with Bangalore and Shenzhen anchoring adaptive algorithm development centers. Platform architecture rests on GPU hardware from Taiwan and South Korea, content delivery networks from hyperscaler edge locations, and specialized machine learning frameworks from open-source repositories. Single-source vulnerability in NVIDIA GPU supply chains threatens scaling timelines. Distribution runs through direct enterprise sales teams for corporate training, government tender processes for K-12, and channel partnerships for higher education.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized machine learning engineering talent scarcity props pricing power for vendors with compliant algorithmic architectures, constraining supply expansion faster than demand growth across EU-regulated deployments.
For Market Incumbents: Deploy algorithmic explainability certification investments to lock in European procurement advantages before EU AI Act enforcement hardens. Acquire assessment engine capabilities to consolidate corporate training budgets around unified skills credentialing. Counter emerging generative tutoring specialists by embedding large language model features into existing LMS architectures.
For New Entrants and Emerging Players: Enter via India's state-level National Education Policy implementation tenders, where adaptive assessment platform specifications remain fluid and incumbent lock-in is weakest. Target tier-2 and tier-3 Chinese cities under SAMR standardization programs for smart classroom hardware-software bundles. Pursue white-label partnerships with established content publishers seeking AI personalization layers.
For Investors and Strategic Acquirers: Distressed-cycle entries favor compliance-ready mid-cap specialists in Germany and France with existing EU AI Act documentation infrastructure and Länder education ministry relationships. Long-term viability hinges on outcome-verified subscription model conversion rates displacing seat-based licensing. Watch corporate training procurement committee consolidation patterns as the inflection signal for platform vendor winner-take-most dynamics.
| Strategic Initiative | Industry Significance |
|---|---|
| Algorithmic Explainability Certification | EU AI Act compliance creates procurement moats for auditable adaptive systems in member states. |
| Assessment Engine Acquisition | Consolidated skills credentialing unifies corporate training budgets onto single-vendor platforms. |
| Generative Tutoring Integration | Large language model convergence creates new product categories beyond traditional courseware libraries. |
| State-Level Tender Participation | India's National Education Policy implementation opens procurement channels for adaptive assessment vendors. |
| Outcome-Verified Subscription Conversion | Competency-based contract structures displace seat-based licensing in financial services and healthcare. |
Research Methodology
SEC filings, hyperscaler capex disclosures, and EU regulatory documentation formed the secondary backbone, supplemented by customs records tracking educational technology hardware flows. Primary interviews with chief learning officers, government procurement officers, platform engineering leads, and regulatory compliance specialists validated demand assumptions and pricing dynamics. Bottom-up vendor revenue aggregation and top-down education spending allocation triangulated market sizing across the analysis window.
Historical trendline analysis of LMS adoption curves and AI integration penetration informed projection modeling across technology, application, deployment, and end-user segmentation dimensions. CAGRs derived from regression-weighted growth rate convergence over the projection horizon. Forecast inputs incorporated government digital education budget appropriations, corporate training spend elasticity to skills verification mandates, and hyperscaler infrastructure pricing trajectories.
Revisions become necessary when GDPR enforcement actions fragment cross-border service delivery, EU AI Act risk classifications escalate documentation burdens, or hyperscaler capacity constraints throttle platform scaling. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Educational Technology (EdTech)
Global Gamification in Education Market
Educational Technology (EdTech)
Flipped Classroom Market
Educational Technology (EdTech)
Global Social Learning Platforms Market
Educational Technology (EdTech)
Augmented and Virtual Reality in Education Market
Educational Technology (EdTech)
Smart Education and Learning Market
Educational Technology (EdTech)
Blockchain in Edutech Market
Educational Technology (EdTech)
SETM Education Market
Educational Technology (EdTech)
Game-Based Learning Market
Educational Technology (EdTech)
Education Security Market
Educational Technology (EdTech)
Global Smart Classroom Market
Educational Technology (EdTech)
Global AI in Education Market
Educational Technology (EdTech)
Digital Badges Market
Educational Technology (EdTech)
Asia Big Data Analytics in Education Market
Educational Technology (EdTech)
Global K-12 Software Market
Educational Technology (EdTech)
Education Apps Market
Educational Technology (EdTech)
Specific Gravity Bench Apparatus Market