
 Global K-12 Software Market | 2026-2036
Global K-12 Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global K-12 Software Market Foresight
The capital-intensity divergence between hyperscale platform providers and specialized learning management vendors is redrawing competitive boundaries in K-12 software. Microsoft Corporation leverages its Azure cloud infrastructure and Office 365 Education bundling to dominate district-level procurement in North America. Google LLC anchors its position through Chromebook ecosystem integration and free Workspace for Education tiers that lock in long-term user bases. Instructure Inc. specializes in higher-functionality learning management systems that compete on pedagogical depth rather than price.
K-12 software encompasses digital platforms, applications, and administrative systems designed to manage student data, deliver instructional content, and assess learning outcomes across primary and secondary education institutions. These systems typically operate through multi-tenant cloud architectures with API interoperability standards such as LTI 1.3 Advantage and OneRoster for seamless data exchange between student information systems and learning tools. Cloud-based deployment leads volume adoption as districts abandon on-premise server maintenance, while learning management systems capture the fastest growth trajectory due to hybrid classroom normalization. Subscription-based pricing now dominates vendor revenue models, though freemium entry tiers remain critical for penetrating underfunded public school segments.
The EU AI Act and GDPR impose strict algorithmic transparency and data minimization requirements on adaptive learning platforms sold into European schools. The US Department of Education and state-level student privacy laws such as California's SOPIPA create a fragmented compliance landscape that favors vendors with dedicated policy teams. India's BIS certification and DPDP Act are emerging as gatekeepers for foreign edtech market access. Stakeholders must monitor how AI safety regulations evolve from voluntary guidance to binding procurement mandates.
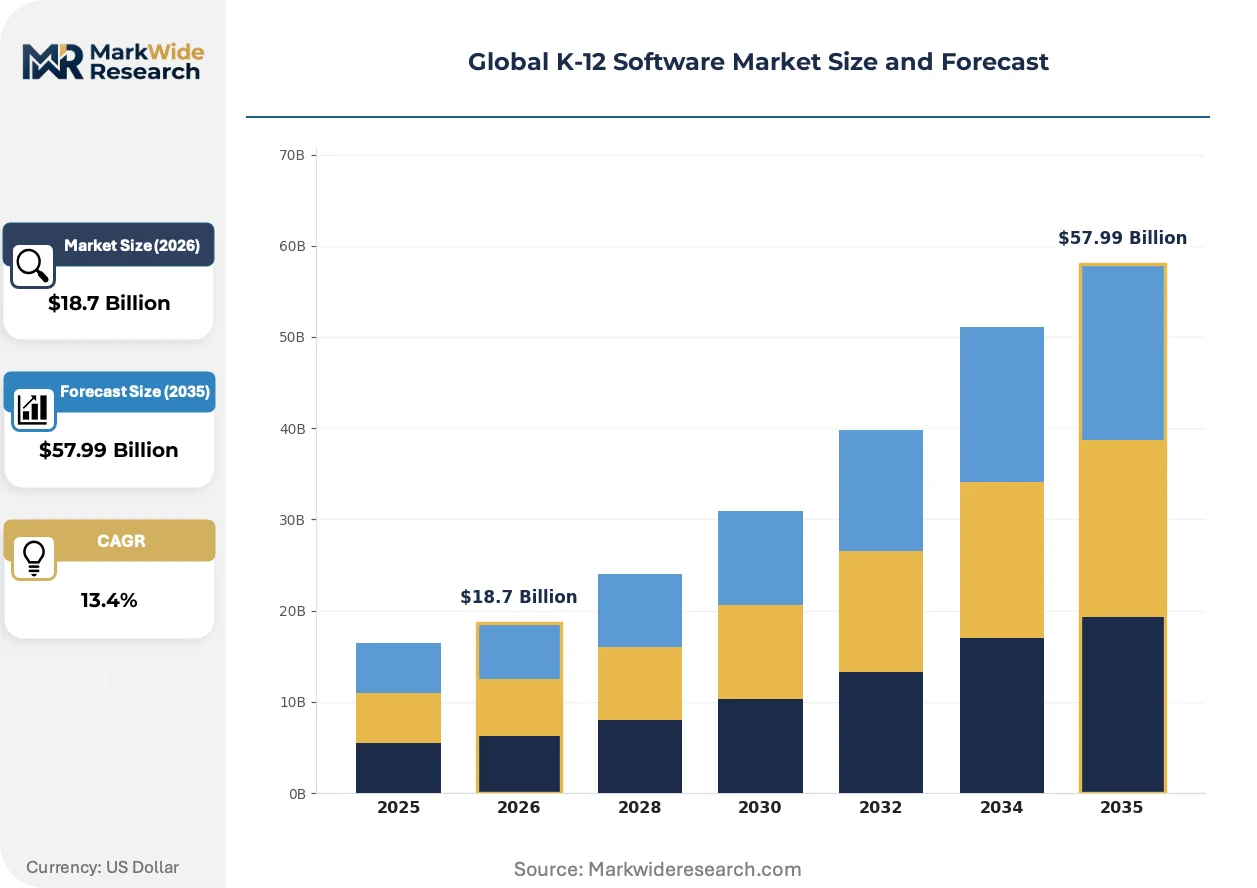
Market Dynamics
Cloud migration mandates from education ministries are compressing procurement cycles while simultaneously fragmenting vendor landscapes as districts abandon multi-year enterprise licenses for modular best-of-breed stacks.
Growth Catalysts
- EU AI Act compliance deadlines:European procurement authorities now require algorithmic transparency documentation for adaptive learning platforms, creating replacement demand for legacy systems lacking audit trails.
- India's DPDP Act implementation:Data localization requirements are forcing foreign edtech vendors to establish domestic cloud infrastructure, opening partnership opportunities for local system integrators.
- Hybrid classroom normalization:Synchronous-asynchronous blended instruction models require LMS-embedded video conferencing and asynchronous assignment workflows that on-premise legacy platforms cannot support.
Market Restraints
- Interoperability protocol fragmentation:Competing standards between LTI 1.3 Advantage, OneRoster, and proprietary APIs force districts to maintain expensive middleware layers or accept vendor lock-in.
- Public sector budget volatility:State-level education funding in the United States fluctuates with property tax cycles, creating unpredictable procurement windows that compress vendor sales pipelines.
- Substitute platform threat:Free consumer-grade collaboration tools from hyperscale technology providers satisfy basic instructional needs for underfunded rural districts, capping pricing power for specialized vendors.
Strategic Opportunities
- Brazil's national connectivity program:Federal broadband expansion into Amazonas and Northeast regions creates first-mover advantage for cloud-native platforms with low-bandwidth optimization.
- Special education mandate convergence:IEP management modules integrated with mainstream LMS workflows address compliance requirements under the United States IDEA reauthorization.
- AI-powered formative assessment:Real-time learning analytics that adjust content difficulty without human intervention capture premium pricing in affluent suburban United States districts.
Industry Challenges
- Specialized pedagogical engineering talent scarcity:Vendors struggle to hire learning scientists capable of translating educational research into algorithmic decision trees for adaptive systems.
- Legacy SIS integration complexity:Decades-old student information systems in large urban United States districts require expensive custom API development for real-time grade passback.
- GDPR Article 35 DPIA timelines:European data protection impact assessments for AI-enabled tutoring tools extend sales cycles by 6-12 months and require dedicated compliance personnel.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global K-12 Software Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $57.99 Billion |
| CAGR (2026 – 2036) | 13.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, Web-Based Learning Platforms Application: Student Information Systems, Learning Management Systems, Assessment Tools, Curriculum Management End User: Public Schools, Private Schools, Charter Schools, Homeschool Organizations Pricing Model: Subscription-Based, License Fee, Freemium, Pay-Per-Use |
| Companies Covered | Microsoft Corporation, Google LLC, Pearson PLC, IBM Corporation, Apple Inc., Instructure Inc., Blackboard Inc., D2L Corporation, McGraw-Hill Education, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global K-12 Software Market Shifts & Advancements
Generative AI capabilities are embedding into core instructional workflows faster than procurement frameworks can adapt, creating a competitive race between compliance-first and functionality-first vendor strategies.
Microlearning content formats are fragmenting traditional semester-long course structures into competency-based modules. District curriculum directors in Texas and Florida are piloting these atomic learning objects for credit recovery programs. The shift is fragmenting publisher content licensing models and enabling direct teacher-to-teacher marketplace transactions.
The EU AI Act's risk classification system for educational applications is forcing vendors to reengineer adaptive algorithms for explainability. Systems scoring above "limited risk" thresholds must provide human-readable logic traces for each content recommendation. German and French education authorities are now requiring these disclosures in RFP technical specifications, filtering out black-box machine learning approaches.
District technology directors are consolidating vendor relationships through platform bundling rather than point solutions. Single-sign-on fatigue and data synchronization failures between siloed applications are driving preference for integrated suites. This concentration is most visible in California and New York, where large unified districts have issued explicit "preferred platform" policies limiting approved vendor lists to three or fewer ecosystem providers.
Global K-12 Software Market Segmentation
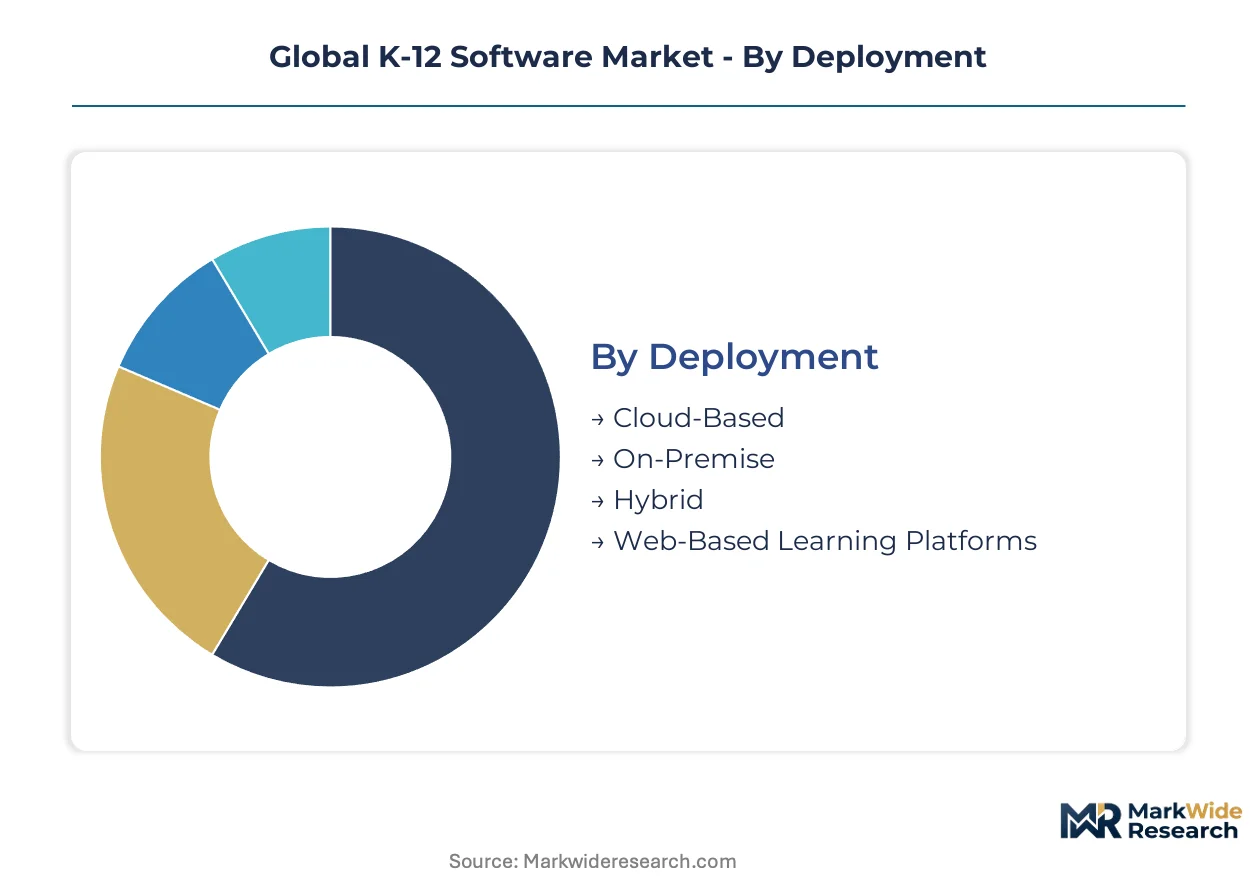
Segmentation in K-12 software reveals how procurement authority, technical architecture, and funding mechanisms fragment demand across institution types. Cloud-native vendors compete differently against legacy on-premise incumbents depending on district size and regulatory environment.
Deployment:
Cloud-based platforms dominate procurement in export-led education technology markets, while hybrid and on-premise solutions persist in domestically regulated environments with strict data sovereignty requirements.
- Cloud-Based:Multi-tenant SaaS architectures with automatic scaling eliminate district IT maintenance burdens. Demand concentrates in United States suburban districts pursuing 1:1 device initiatives where Microsoft Azure and Google Cloud infrastructure underpins procurement decisions.
- On-Premise:Locally hosted servers with dedicated hardware installations retain preference in German and French districts where GDPR Article 35 data protection impact assessments mandate physical data control. Compliance complexity slows replacement cycles.
- Hybrid:Split architectures keep sensitive student records on local servers while pushing instructional content to cloud edge nodes. Indian state education boards under BIS certification requirements favor this model for balancing cost with localization mandates.
- Web-Based Learning Platforms:Browser-delivered applications requiring no local installation beyond standard browsers. Brazilian federal connectivity programs in Amazonas regions prioritize these for low-bandwidth optimization.
Cloud-based deployment commands the established base. The steepest expansion runs through hybrid configurations as data localization laws proliferate.
Application:
Functional specialization determines pricing power, with administrative systems trading at cost-plus margins while adaptive instructional tools capture value-based premiums.
- Student Information Systems:Centralized databases managing enrollment, attendance, and transcript records across multi-year student lifecycles. United States urban districts with decades-old legacy SIS installations face expensive API integration projects for real-time grade passback to newer platforms.
- Learning Management Systems:Platforms orchestrating content delivery, assignment workflows, and synchronous-asynchronous communication. Affluent United States suburban districts pay premium pricing for AI-powered formative assessment modules that adjust difficulty without human intervention.
- Assessment Tools:Standardized testing platforms with proctoring and analytics capabilities. State-level accountability mandates in Texas and Florida drive replacement demand as paper-based exams phase out.
- Curriculum Management:District-level content repositories aligning instructional materials to state standards. Microlearning fragmentation into competency-based modules is disrupting traditional semester-long publisher licensing models.
Student Information Systems command the established base. The steepest expansion runs through Learning Management Systems as hybrid classroom normalization accelerates.
End User:
Funding stability and procurement autonomy create three distinct customer tiers with diverging vendor sales cycles and contract structures.
- Public Schools:Tax-funded districts with elected board oversight and multi-year budget cycles. State-level funding volatility in United States property-tax-dependent systems compresses vendor sales pipelines into unpredictable windows.
- Private Schools:Tuition-dependent institutions with faster procurement decisions and higher price tolerance. India's independent school networks under CBSE and ICSE boards represent concentrated demand for premium international curriculum platforms.
- Charter Schools:Publicly funded but independently operated schools with waivers from district procurement rules. United States authorizer requirements for academic accountability drive demand for integrated assessment-data systems.
- Homeschool Organizations:Parent-led cooperatives and state-registered home education networks. Freemium entry tiers from Google Workspace for Education dominate this price-sensitive segment, capping specialized vendor pricing power.
Public Schools command the established base. The steepest expansion runs through Charter Schools as authorizer accountability mandates intensify data system requirements.
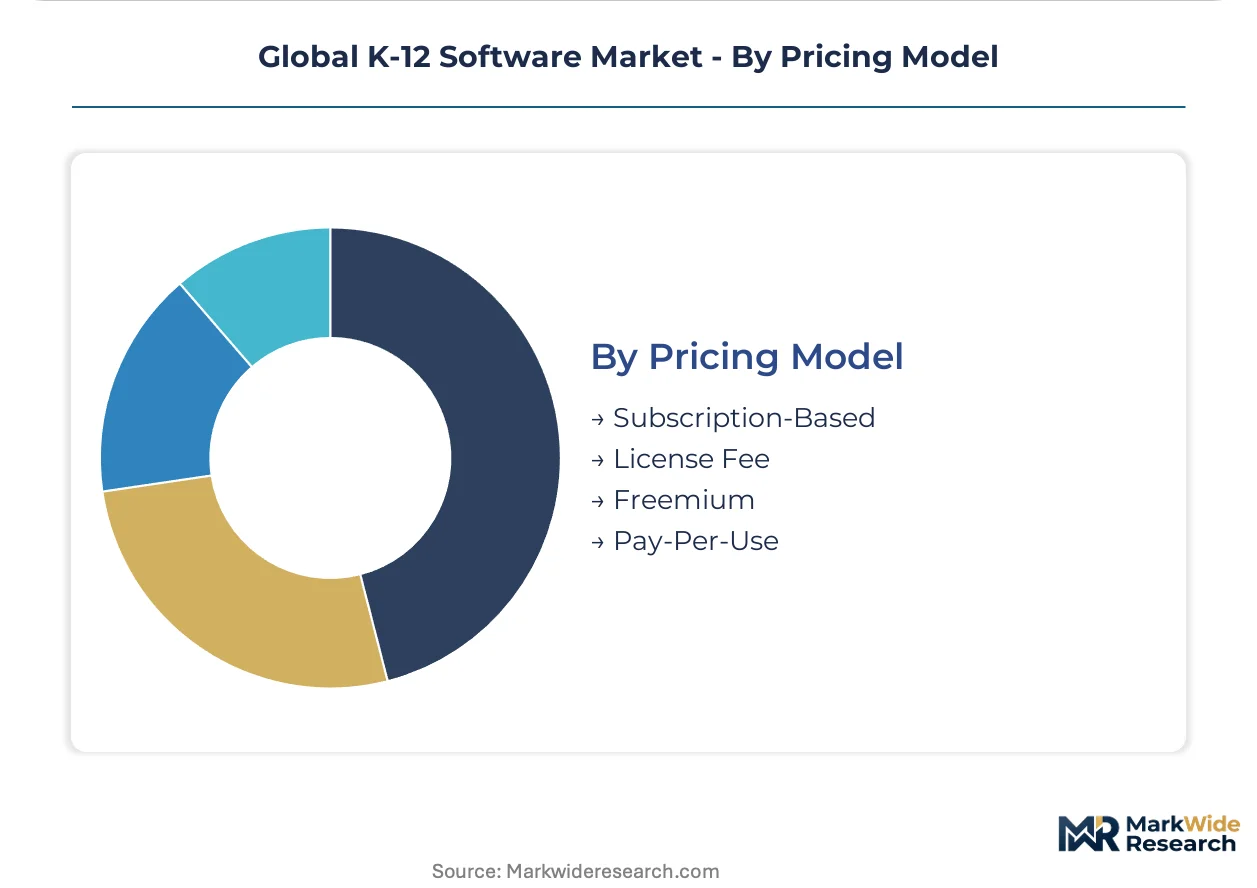
Pricing Model:
Revenue predictability and customer acquisition economics trade off across models, with enterprise subscription contracts funding R&D while freemium tiers build installed base for upsell conversion.
- Subscription-Based:Recurring annual or multi-year per-student or per-teacher fees. United States large unified districts in California and New York prefer this model for budget predictability within multi-year technology plans.
- License Fee:Perpetual software ownership with optional maintenance contracts. On-premise SIS vendors in legacy-dependent European districts retain this structure for customers resisting operational expenditure accounting shifts.
- Freemium:Zero-cost entry tiers with feature-gated premium upgrades. Google's Workspace for Education locks in long-term user bases that convert to paid tiers as institutional sophistication grows.
- Pay-Per-Use:Consumption-based billing tied to specific transactions like assessments delivered or storage utilized. Emerging in Indian state pilot programs where unpredictable scale makes fixed commitments risky.
Subscription-Based pricing commands the established base. The steepest expansion runs through Freemium models as vendor competition for district mindshare intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States generates substantial net exports in K-12 software licensing while importing specialized assessment content from European publishers. India's domestic vendors increasingly supply neighboring South Asian markets under BIS certification frameworks.
United States
Suburban districts in Texas and Florida drive procurement volume through state accountability mandates replacing paper-based exams. California's SOPIPA student privacy law creates compliance complexity that favors vendors with dedicated policy teams. The Greater Boston corridor hosts concentrated clusters of learning science engineering talent developing adaptive algorithmic systems.
Germany
German education ministries mandate physical data control through GDPR Article 35 assessments, slowing cloud migration in Bavaria and North Rhine-Westphalia. The KBA does not regulate this sector; instead, state-level data protection authorities enforce localization requirements. Berlin-Brandenburg districts maintain hybrid architectures keeping sensitive records on-premise while pushing instructional content to edge nodes.
India
CBSE and ICSE board schools in Maharashtra and Karnataka represent concentrated demand for premium international curriculum platforms. The DPDP Act forces foreign edtech vendors to establish domestic cloud infrastructure, opening partnership opportunities for Mumbai and Bengaluru system integrators. National digital education infrastructure scaling concentrates procurement authority at the state education board level.
Brazil
Federal broadband expansion into Amazonas and Northeast regions creates first-mover advantage for cloud-native platforms with low-bandwidth optimization. ANVISA does not regulate educational software; procurement falls under federal education ministry connectivity programs. São Paulo state districts lead adoption of web-based learning platforms requiring minimal local installation.
United Kingdom
Multi-academy trusts in London and the Southeast consolidate vendor relationships through platform bundling policies limiting approved lists. The Department for Education's data protection guidance shapes procurement criteria without binding statutory force. Manchester and Birmingham urban districts face expensive legacy student information system integration projects for real-time grade passback.
Global K-12 Software Market Competitive Landscape
Concentration sits with hyperscale cloud infrastructure providers bundling education tiers into broader enterprise relationships. The vendor landscape fragments across three strategic tiers: platform-integrated suites, specialized learning management systems, and legacy on-premise incumbents. Dominant competitive moves include strategic partnerships with system integrators for data localization compliance and portfolio diversification into AI-powered formative assessment modules.
Among the hyperscale platform providers, Microsoft Corporation and Google LLC exemplify the cloud-infrastructure-anchored archetype competing on ecosystem lock-in rather than pedagogical functionality. Instructure Inc. occupies a position within the specialized tier competing on instructional depth. Pearson PLC represents the legacy content publisher archetype adapting licensing models to microlearning fragmentation.
| Leading Market Players |
|---|
| Microsoft Corporation |
| Google LLC |
| Pearson PLC |
| IBM Corporation |
| Apple Inc. |
| Instructure Inc. |
| Blackboard Inc. |
| D2L Corporation |
| McGraw-Hill Education |
| Others |
Supply & Pricing Matrix
Hyperscale cloud infrastructure utilization rates above 70% in North American data centers compress marginal delivery costs for SaaS platforms while establishing price floors that specialized vendors cannot match without ecosystem subsidies. This scale asymmetry concentrates procurement power among Microsoft Azure and Google Cloud-anchored providers, forcing mid-tier learning management vendors toward niche pedagogical differentiation or freemium user acquisition strategies that defer monetization.
Pricing Analysis
Public school district procurement officers anchor K-12 software pricing through multi-year subscription negotiations that trade feature depth for per-student cost predictability. Three-tier pricing structure across premium, standard, and economy levels segments by administrative functionality, AI-powered assessment modules, and interoperability certification grade. Cost compression in standard tiers intensifies because free consumer-grade collaboration tools from hyperscale providers cap pricing power for specialized vendors. Rural districts with property-tax-constrained budgets exhibit highest price sensitivity, while affluent suburban United States districts tolerate premium pricing for adaptive learning analytics.
Supply Chain Analysis
API interoperability standard fragmentation between LTI 1.3 Advantage, OneRoster, and proprietary protocols creates integration chokepoints that inflate implementation costs for district IT departments. Cloud infrastructure supply concentrates in United States, Ireland, and Singapore regions where Microsoft, Google, and Amazon maintain education-specific data residency certifications. Software development draws from specialized learning science engineering talent pools in Greater Boston, Bengaluru, and Berlin. Single-source vulnerability runs through legacy student information system vendors whose decades-old architectures require expensive custom middleware. Distribution runs through direct enterprise sales teams for large unified districts and value-added resellers for fragmented rural markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now govern K-12 software competitive dynamics as district technology directors consolidate vendor relationships through ecosystem bundling that privileges integrated suites over point solutions. The shift from best-of-breed procurement toward preferred platform policies in California and New York exemplifies this interoperability-driven concentration.
For Market Incumbents: Fortify ecosystem lock-in through deeper Chromebook and Azure infrastructure integration while acquiring specialized assessment analytics firms to fill pedagogical functionality gaps. The substitute threat from free hyperscale collaboration tools demands defensive bundling of premium features into base education tiers. Backward integration into learning science engineering talent pools in Greater Boston and Bengaluru protects adaptive algorithm differentiation. For New Entrants and Emerging Players: Anchor in Brazil's Amazonas and Northeast federal connectivity expansion where low-bandwidth-optimized web platforms face minimal incumbent saturation. Charter school authorizer accountability mandates in United States urban centers create penetrable demand for integrated assessment-data systems with faster procurement cycles than public district bureaucracies. Freemium entry tiers with IEP management module upsells address special education compliance white space. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among cloud-native learning management vendors with established API interoperability certifications and state-level procurement approvals. Long-term viability hinges on compliance infrastructure for evolving AI safety regulations from voluntary guidance to binding mandates. Acquisition targets should demonstrate GDPR Article 35 assessment completion and domestic cloud infrastructure in India under DPDP Act requirements. The signal to watch is European procurement authority algorithmic transparency documentation requirements filtering into United States state-level RFP specifications.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Consolidates vendor relationships through single-sign-on ecosystems that reduce district IT fatigue. |
| Geographic Expansion | Captures Brazil federal broadband expansion into bandwidth-constrained Amazonas regions. |
| Strategic Partnership | Enables foreign vendors to satisfy India's DPDP Act data localization through Mumbai system integrators. |
| Product Launch | Addresses United States IDEA reauthorization with IEP management modules embedded in mainstream LMS workflows. |
| Acquisition of Specialist Firm | Secures learning science engineering talent for explainable adaptive algorithms under EU AI Act risk classification. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with chief technology officers at United States large unified districts, learning management platform engineers, state education procurement officers, and European data protection compliance leads; alongside secondary validation through SEC filings from hyperscale cloud providers, EDUCAUSE infrastructure survey data, and EU AI Act implementation guidance documents. Bottom-up triangulation against top-down market sizing cross-validated deployment model penetration rates and pricing tier distributions.
Across the projection horizon, the analytical framework modeled segmentation by deployment architecture, institution type, application functionality, and regional regulatory cluster to capture divergence between cloud-native and legacy on-premise competitive dynamics. CAGRs were derived from installed base growth rates, replacement cycle compression, and new module attach rates. Forecast inputs incorporated state-level funding volatility patterns in United States property-tax-dependent systems and data localization mandate timelines under India's DPDP Act.
Decision-makers should treat outputs as directional under assumptions of continued hybrid classroom normalization and stable hyperscale cloud infrastructure pricing; material deviation in public sector budget allocation or AI safety regulation enforcement velocity would warrant model refresh. Practitioners should keep alternative scenarios live as European algorithmic transparency requirements propagate into United States federal procurement guidelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Educational Technology (EdTech)
Global Micro-Learning Market
Educational Technology (EdTech)
Specific Gravity Bench Apparatus Market
Educational Technology (EdTech)
Higher Education Technology Market
Educational Technology (EdTech)
Child Care Software Market
Educational Technology (EdTech)
AI in K-12 Education Market
Educational Technology (EdTech)
Global Adaptive Learning Market
Educational Technology (EdTech)
Global Social Learning Platforms Market
Educational Technology (EdTech)
Artificial Intelligence (AI) in Education Market
Educational Technology (EdTech)
Digital Badges Market
Educational Technology (EdTech)
Global Smart Classroom Market
Educational Technology (EdTech)
Asia Big Data Analytics in Education Market
Educational Technology (EdTech)
Artificial Intelligence in the Education Sector Market
Educational Technology (EdTech)
Global Edutainment Centers Market
Educational Technology (EdTech)
VR Education Market
Educational Technology (EdTech)
Edtech Market
Educational Technology (EdTech)
Virtual Schools Market