
 Global Smart Classroom Market | 2026-2036
Global Smart Classroom Market Size, Share, and Industry Trends Forecast 2026-2036
Global Smart Classroom Market Foresight
ISO 21001 certification for educational organizations is unwinding competitive access across the smart classroom value chain, favoring vendors with documented quality management systems. Microsoft Corporation leverages its Azure cloud backbone to anchor institutional contracts in North American higher education. Cisco Systems, Inc. sustains dominance in network infrastructure for hybrid learning environments through its Webex-integrated hardware portfolio. Google LLC competes aggressively on price in the K-12 segment with Chrome OS ecosystem lock-in.
Smart classrooms integrate interactive displays, audio-visual networks, learning management software, and IoT sensors to deliver real-time content distribution and student analytics in educational or training settings. The architecture typically requires sub-50ms latency for synchronous video and API interoperability between hardware and cloud platforms. Learning Management Systems occupy the deepest margin pools due to recurring SaaS revenue and high switching costs. Interactive Whiteboards remain the most mature hardware category with slowing replacement cycles. Cloud-Based deployment is expanding fastest as districts and universities shed on-premises data center burdens.
FCC E-Rate funding rules in the United States, EU GDPR and AI Act provisions in Europe, and BIS electronic equipment standards in India collectively shape procurement eligibility and data governance obligations for classroom technology vendors. The EU AI Act specifically restricts automated assessment algorithms in educational settings, forcing product redesigns. Stakeholders must monitor how divergent national data localization laws fragment platform architectures and inflate compliance costs.
Market Dynamics
Cloud migration is compressing infrastructure procurement cycles as K-12 districts and universities abandon on-premises data centers for SaaS-delivered learning management platforms. This shift concentrates vendor selection authority at central IT procurement offices and elevates API interoperability above hardware specifications in evaluation criteria.
Growth Catalysts
- EU AI Act compliance mandates:Educational institutions across Germany, France, and Italy face algorithmic assessment restrictions that force platform upgrades, creating replacement demand for compliant learning analytics systems.
- India BIS certification requirements:National digital education missions in Maharashtra, Karnataka, and Uttar Pradesh mandate certified interactive hardware for public school procurement, accelerating standardization.
- Interactive display technology maturation:Zero-bonding manufacturing processes reduce panel weight and shipping costs, enabling ceiling-mounted deployments in aging school buildings with structural load constraints.
Market Restraints
- Semiconductor supply concentration:GPU and edge-computing chip fabrication concentrates in Taiwan and South Korea, exposing interactive display and AI-enabled camera vendors to geopolitical disruption risks.
- GDPR data localization friction:EU member states enforce divergent student data storage requirements, fragmenting cloud architecture designs and inflating vendor compliance engineering overhead.
- Projector-to-display substitution:Lamp-based projection systems retain installed-base presence in budget-constrained districts, slowing full conversion to solid-state interactive panels despite total-cost advantages.
Strategic Opportunities
- Vietnam and Indonesia public education digitization:National broadband expansion programs in Hanoi, Ho Chi Minh City, Jakarta, and Surabaya create first-mover advantages for hardware vendors establishing local assembly partnerships.
- ISO 21001 certification differentiation:Quality management documentation becomes a scored criterion in Brazilian and Mexican federal education technology tenders, favoring prepared vendors.
- LMS-IoT convergence:Environmental sensors feeding occupancy and air-quality data into learning platforms enable wellness-based classroom scheduling, opening recurring SaaS revenue streams.
Industry Challenges
- EdTech-IT skill bifurcation:School technology coordinators lack cloud architecture expertise to manage hybrid on-premises and SaaS environments, forcing vendors to absorb professional services costs.
- Legacy audio-visual infrastructure integration:Existing ceiling speaker and microphone installations in US and UK campuses require analog-to-digital bridge hardware, complicating retrofit sales cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Smart Classroom Market |
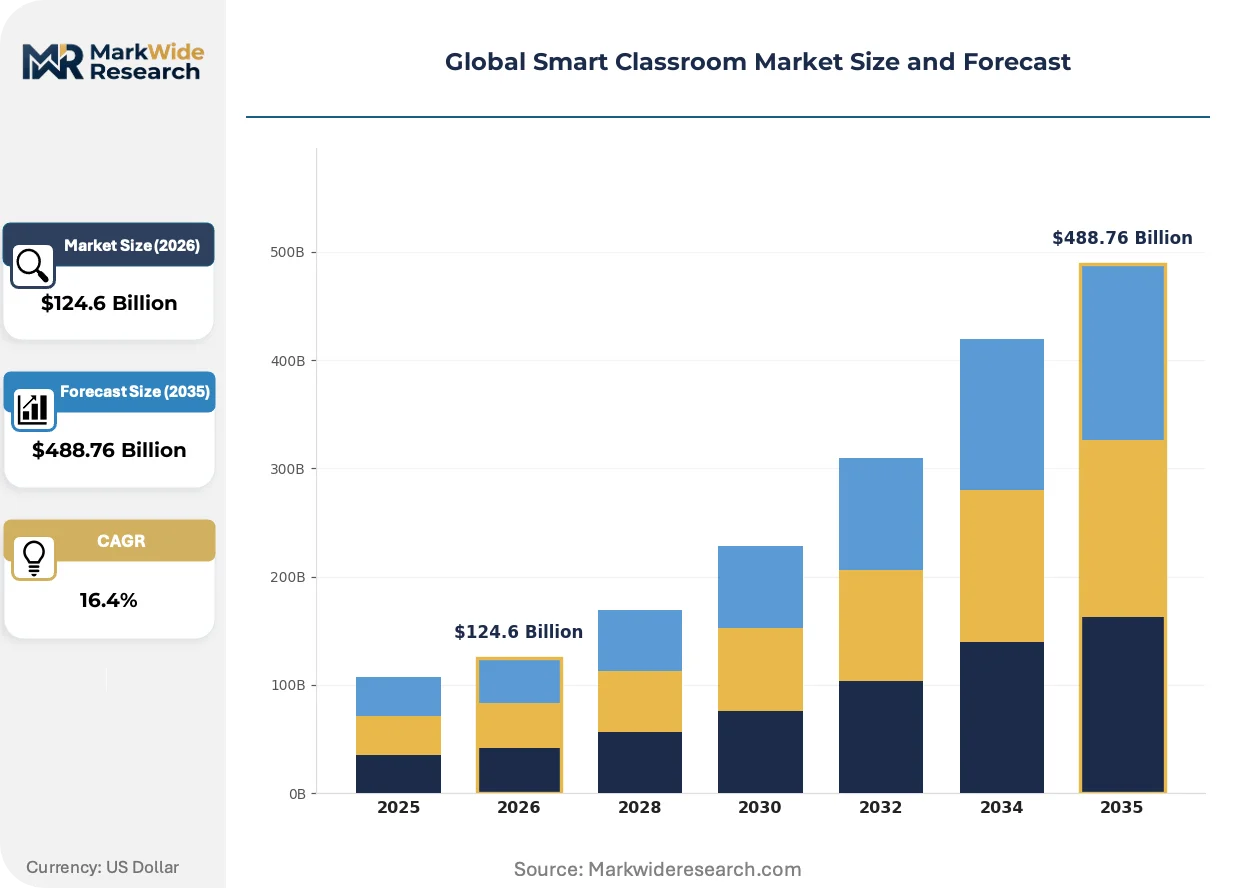
| Market Size in 2026 | $124.6 Billion |
| Market Size in 2035 | $488.76 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Interactive Whiteboards, Student Response Systems, Digital Projectors, Virtual Reality Kits, Learning Management Systems Application: K-12 Schools, Higher Education Institutions, Corporate Training, Skill Development Centers, Language Learning Institutes End User: Teachers, Educational Administrators, Corporate Trainers, Students, Instructional Designers Deployment: On-Premises, Cloud-Based, Hybrid, Mobile-Enabled, SaaS Platforms |
| Companies Covered | Microsoft Corporation, Cisco Systems, Inc., Google LLC, Apple Inc., IBM Corporation, Dell Inc., Pearson, SAP SE, SMART Technologies ULC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Smart Classroom Market Shifts & Advancements
Real-time student analytics is reconfiguring classroom technology from content-display hardware into data-capture infrastructure. This transformation elevates software architecture and API design above traditional audio-visual engineering in vendor capability requirements.
Edge-based AI inference engines embedded directly within interactive displays are displacing cloud-dependent processing for facial-attention and gesture-recognition workloads. K-12 districts in Texas, Florida, and Ohio prioritize these on-device architectures to minimize bandwidth consumption and satisfy parental data-privacy concerns. The displacement compresses latency below the 50-millisecond threshold required for synchronous feedback loops in adaptive learning applications.
The EU AI Act's prohibitions on emotion-recognition systems in educational settings are forcing learning analytics vendors to strip biometric inference modules from European product configurations. Compliance engineering teams must maintain parallel codebases for EU and non-EU deployments, fragmenting development resources. German and French procurement authorities now require algorithmic impact assessments as scored tender components, advantaging vendors with established documentation workflows.
District-level buying consortia in the United States are consolidating vendor evaluation authority away from individual schools toward centralized procurement offices in state capitals. California, New York, and Illinois education departments now mandate multi-year total-cost-of-ownership analyses that include cybersecurity audit fees and data-migration expenses. This concentration favors established platform vendors with documented compliance histories over point-solution specialists lacking enterprise sales infrastructure.
Global Smart Classroom Market Segmentation
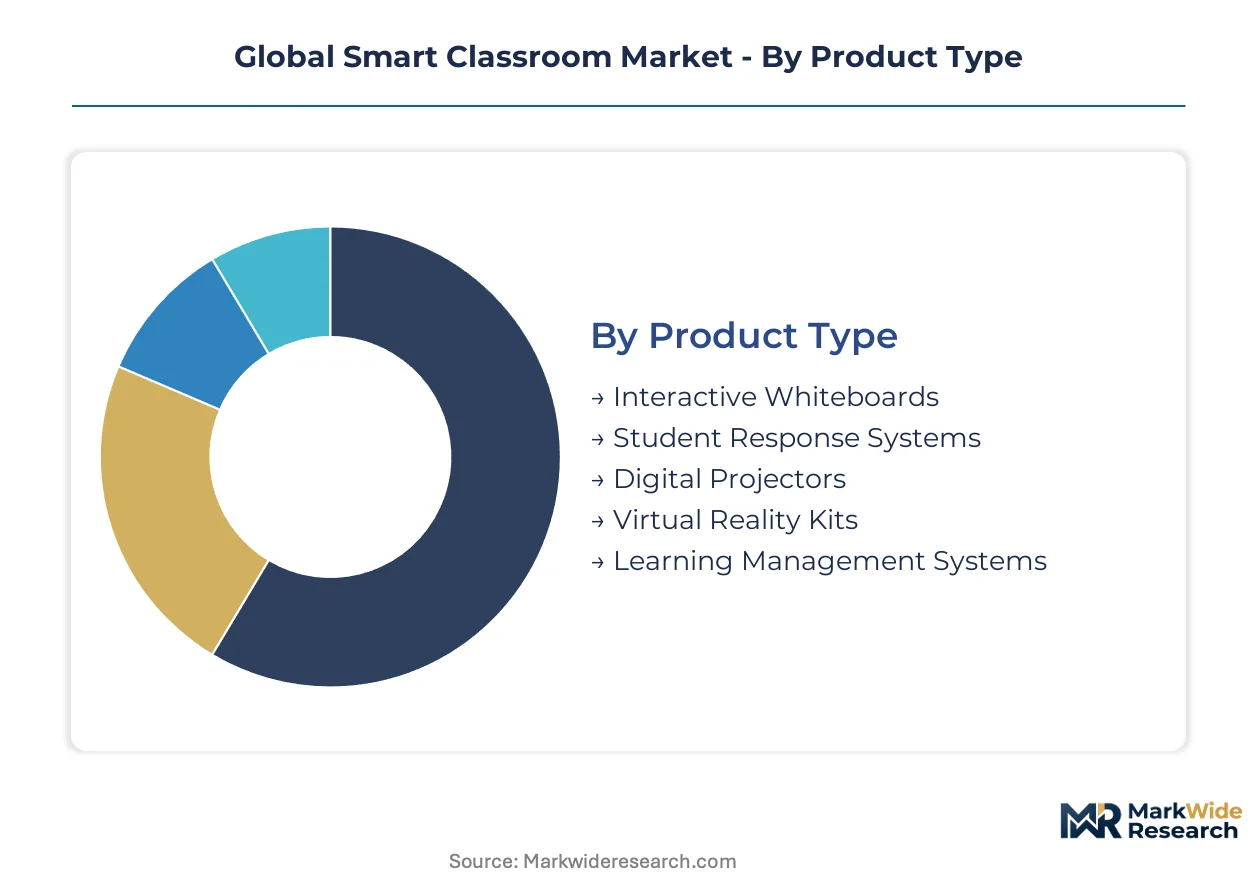
Segmentation reveals how procurement authority, technical requirements, and compliance obligations vary across buyer types and deployment models. Channel strategies must align with these structural differences to capture margin pools effectively.
Product Type:
Channel mix varies sharply: interactive hardware flows through AV integrators and direct education distributors, while software platforms concentrate procurement at central IT offices through SaaS marketplaces.
- Interactive Whiteboards:Zero-bonding panel manufacturing reduces weight for ceiling mounting in aging school infrastructure across India, Germany, and Texas. Public school districts in Maharashtra and Karnataka prioritize BIS-certified units under national digital education mandates.
- Learning Management Systems:Recurring SaaS revenue models dominate margin capture, with API interoperability now outweighing hardware specs in RFP evaluation criteria. Higher education institutions in North America and Europe consolidate procurement authority at central IT offices.
- Student Response Systems:Handheld clickers and mobile-enabled polling tools serve formative assessment needs in K-12 classrooms.
- Digital Projectors:Lamp-based systems retain installed-base presence in budget-constrained districts despite solid-state panel advantages.
- Virtual Reality Kits:Specialized hardware for immersive STEM and vocational training applications in corporate and higher education settings.
By volume, Interactive Whiteboards leads. By growth pace, Learning Management Systems is expanding most quickly.
Application:
Cost tier differentiation separates premium enterprise deployments from economy-scale public school rollouts, with compliance engineering overhead concentrated in regulated institutional segments.
- K-12 Schools:Developing economies represent the fastest-expanding buyer segment, with India accelerating deployments through state-level digital education missions. GDPR and EU AI Act compliance reshape procurement criteria for algorithmic assessment tools.
- Higher Education Institutions:Cloud migration compresses infrastructure procurement cycles as universities abandon on-premises data centers. Microsoft Azure anchors institutional contracts in North America through bundled collaboration licensing.
- Corporate Training:Enterprise learning departments prioritize measurable skill outcomes and integration with HR systems.
- Skill Development Centers:Government-funded vocational facilities in Vietnam and Indonesia drive hardware demand through national broadband expansion programs.
- Language Learning Institutes:Specialized pronunciation and conversation practice applications favor mobile-enabled deployment models.
By revenue concentration, Higher Education Institutions dominates. By expansion velocity, K-12 Schools in developing markets is climbing the fastest.
End User:
Volume concentration sits with classroom-facing roles, while margin capture concentrates in administrative purchasing authorities with multi-year budget authority.
- Teachers:Frontline classroom technology users driving adoption of real-time student analytics and adaptive content delivery. Edge-based AI inference in interactive displays addresses parental data-privacy concerns in Texas, Florida, and Ohio districts.
- Educational Administrators:Central procurement authority for district-wide and university-system contracts, mandating ISO 21001 certification and total-cost-of-ownership analyses including cybersecurity audit fees.
- Corporate Trainers:Enterprise learning departments with integration requirements into talent management platforms.
- Students:End-beneficiaries of analytics-driven personalization, with EU AI Act restrictions limiting biometric inference in European deployments.
- Instructional Designers:Content authoring specialists requiring LMS interoperability and learning object repositories.
By headcount, Teachers represents the largest user base. By contract value, Educational Administrators controls the steepest expansion trajectory.
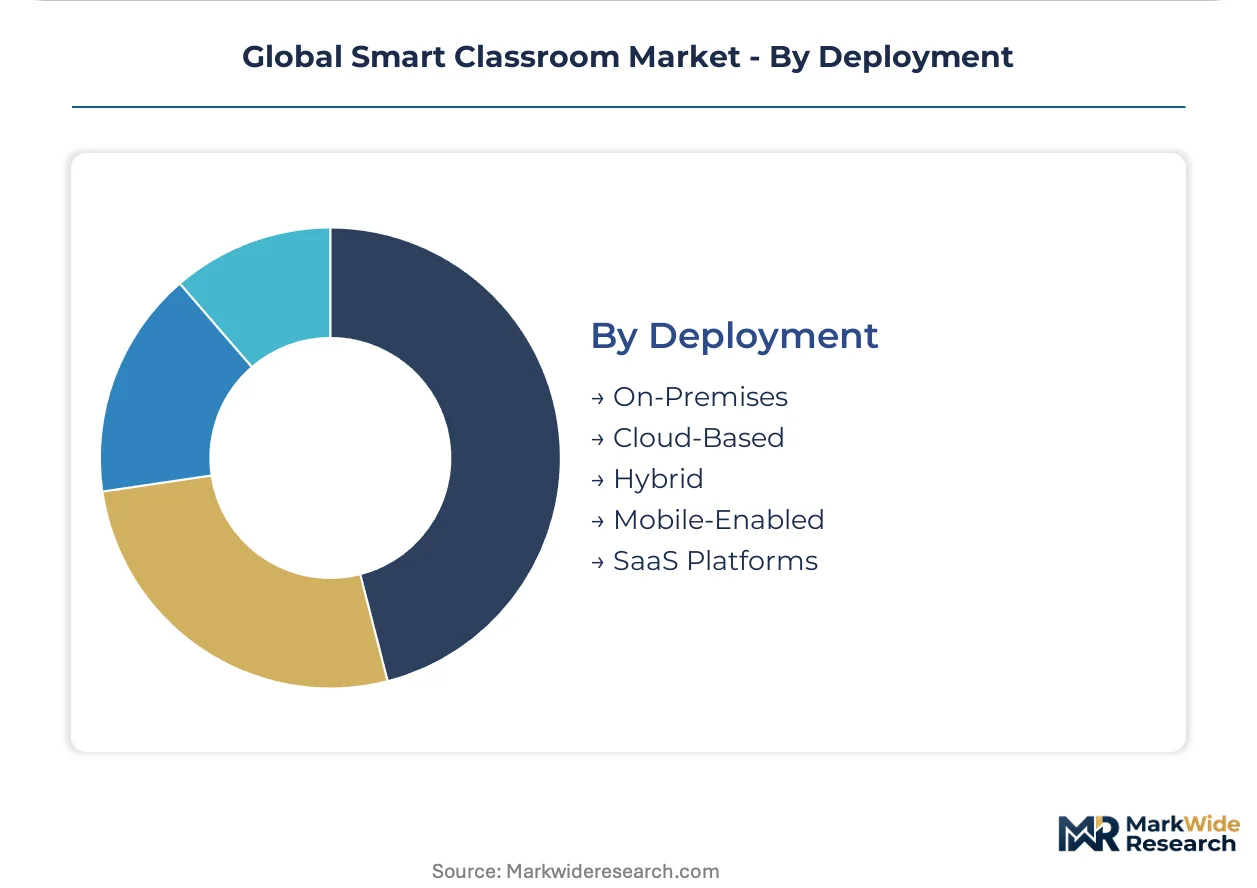
Deployment:
Supply concentration in cloud infrastructure providers shapes vendor partnership requirements, while data localization mandates fragment architecture designs across national boundaries.
- Cloud-Based:Fastest-expanding deployment mode as districts and universities shed on-premises data center burdens. GDPR data localization requirements in EU member states fragment platform architectures and inflate compliance engineering overhead.
- Hybrid:Bridge architectures accommodating legacy audio-visual infrastructure in US and UK campuses requiring analog-to-digital conversion hardware.
- On-Premises:Declining share in education, retained primarily in defense and sensitive government training environments with air-gapped security requirements.
- Mobile-Enabled:BYOD and tablet-centric models for language institutes and informal learning contexts with intermittent connectivity.
- SaaS Platforms:Recurring revenue models with API-first architectures enabling LMS-IoT convergence for environmental sensor integration.
By installed base, On-Premises retains legacy presence. By growth pace, Cloud-Based deployment is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
National digital education missions and data localization mandates are redrawing procurement geography for classroom technology vendors. Government-funded deployment programs in India, EU AI Act compliance requirements in Germany and France, and FCC E-Rate subsidies in the United States collectively determine where infrastructure investments concentrate.
United States
FCC E-Rate funding rules subsidize broadband infrastructure for K-12 districts, compressing procurement cycles toward centralized state-level buying consortia in California, New York, and Illinois. Edge-based AI inference in interactive displays addresses parental data-privacy concerns in Texas, Florida, and Ohio districts. Microsoft Azure anchors institutional contracts in North American higher education through bundled collaboration licensing.
India
National digital education missions in Maharashtra, Karnataka, and Uttar Pradesh mandate BIS-certified interactive hardware for public school procurement, accelerating standardization across state education departments. BIS electronic equipment standards reshape vendor eligibility criteria for classroom technology tenders. Zero-bonding panel manufacturing reduces weight for ceiling mounting in aging school infrastructure across Mumbai and Bangalore metropolitan clusters.
Germany
EU AI Act algorithmic assessment restrictions force platform upgrades across educational institutions, creating replacement demand for compliant learning analytics systems. German procurement authorities require algorithmic impact assessments as scored tender components. Berlin and Munich education technology clusters concentrate vendor documentation workflows for federal compliance engineering.
France
GDPR data localization requirements fragment cloud architecture designs for student data storage, inflating vendor compliance engineering overhead across EU member states. French procurement authorities mandate algorithmic impact assessments alongside German counterparts. Paris and Lyon metropolitan areas concentrate higher education institutions consolidating procurement authority at central IT offices.
Vietnam
National broadband expansion programs in Hanoi and Ho Chi Minh City create first-mover advantages for hardware vendors establishing local assembly partnerships. Government-funded vocational facilities drive interactive display demand through skill development center digitization initiatives. Northern and southern urban corridors concentrate public education infrastructure deployment timelines.
Global Smart Classroom Market Competitive Landscape
Player mix skews toward diversified technology conglomerates with cloud infrastructure and enterprise software portfolios. Market structure concentrates procurement authority at central IT offices, elevating platform vendors with documented compliance histories over point-solution specialists. Three archetypes dominate: cloud infrastructure providers bundling collaboration tools, network hardware specialists with hybrid learning integration capabilities, and interactive display manufacturers with zero-bonding panel expertise. Competitive moves center on API interoperability investments and ISO 21001 certification acquisition for tender eligibility.
Within the cloud-platform tier, Microsoft Corporation and Google LLC exemplify divergent pricing strategies for institutional lock-in. Microsoft leverages its Azure backbone for North American higher education contracts, while Google competes aggressively on price in the K-12 segment. Cisco Systems, Inc. occupies a position in network infrastructure for hybrid learning environments. These three anchors illustrate how procurement concentration favors vendors with enterprise sales infrastructure and documented compliance workflows across GDPR, EU AI Act, and FCC regulatory frameworks.
| Leading Market Players |
|---|
| Microsoft Corporation |
| Cisco Systems, Inc. |
| Google LLC |
| Apple Inc. |
| IBM Corporation |
| Dell Inc. |
| Pearson |
| SAP SE |
| SMART Technologies ULC |
| Others |
Supply & Pricing Matrix
Ninety-day panel procurement lead times from Taiwanese display fabs compress margin windows for interactive whiteboard vendors while amplifying pricing power for GPU and edge-AI chip suppliers in South Korea. This inventory-to-delivery gap concentrates cost pressure on mid-tier hardware assemblers lacking forward contracts with semiconductor foundries, forcing tiered pricing stratification across certification grades.
Pricing Analysis
Certification level creates the primary spread between BIS-compliant hardware for Indian public tenders and uncertified alternatives serving informal channels. Three-tier pricing structure across premium, standard, and economy levels anchors on ISO 21001 documentation, EU AI Act algorithmic impact assessments, and bare-metal hardware respectively. Cost compression in economy-tier projectors intensifies because lamp-based systems face solid-state substitution despite retention in budget-constrained US districts. K-12 procurement offices in developing markets exhibit highest price sensitivity, while North American higher education IT departments prioritize total-cost-of-ownership over unit economics.
Supply Chain Analysis
Container availability fluctuations on Asia-Europe trade lanes disrupt ceiling-mount hardware deliveries to German and French education clusters during peak procurement windows. Interactive display manufacturing draws from Taiwan for LCD/OLED panels, South Korea for memory and logic semiconductors, and China for structural components and final assembly. Single-source vulnerability concentrates in GPU supply for edge-AI inference engines embedded in Texas and Florida school deployments. Distribution runs through AV integrators for hardware and direct SaaS marketplaces for learning management platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hardware margins flatten as recurring SaaS revenue from learning analytics and IoT-enabled environmental monitoring expands faster than device sales. This service-attach dynamic elevates platform vendors with embedded professional services capabilities above pure-play equipment suppliers.
For Market Incumbents: Consolidate API interoperability investments to defend against Google and Microsoft's ecosystem lock-in strategies in K-12 and higher education respectively. Acquire ISO 21001-certified regional specialists in Brazil and Mexico before federal tender scoring mandates take effect. Deepen backward integration into zero-bonding panel manufacturing to offset Taiwanese fab pricing volatility.
For New Entrants and Emerging Players: BIS certification fast-track programs in Maharashtra and Karnataka open first-mover positioning before national digital education missions saturate procurement pipelines. Target Vietnam's government-funded vocational facilities through local assembly partnerships in Hanoi industrial zones. Lead with mobile-enabled deployment models bypassing legacy projector installed bases in Indonesian secondary cities.
For Investors and Strategic Acquirers: Long-term, this sits as a compliance-arbitrage play because divergent data localization mandates across EU member states fragment vendor cost structures and inflate acquisition premiums for multi-jurisdictional platform operators. Focus on learning management systems with established GDPR documentation workflows and EU AI Act algorithmic impact assessment capabilities. Monitor BIS certification backlog clearance rates as inflection indicator for Indian public sector deployment velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| ISO 21001 Certification Acquisition | Unlocks scored tender eligibility in Brazilian and Mexican federal education technology procurements. |
| Edge-AI Inference Engine Integration | Addresses Texas and Ohio parental data-privacy concerns while compressing synchronous feedback latency below 50 milliseconds. |
| Local Assembly Partnership Formation | Captures Vietnam and Indonesia government-funded vocational facility demand through national broadband expansion programs. |
| API-First Architecture Investment | Enables LMS-IoT convergence for environmental sensor data feeding wellness-based classroom scheduling. |
| EU AI Act Compliance Engineering | Maintains market access as German and French procurement authorities mandate algorithmic impact assessments. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of vendor RFP documentation, national procurement databases, and regulatory filing archives. Primary interviews engaged chief technology officers at K-12 districts and universities, education technology procurement officers, AV integration specialists, and cloud platform engineering leads. Secondary validation drew from FCC E-Rate disbursement records, EU AI Act implementation guidance, BIS certification registries, and hyperscaler education vertical revenue disclosures. Bottom-up unit shipment estimates triangulate against top-down education budget allocation analyses.
Segmentation dimensions modeled span product type, application tier, deployment architecture, and regional regulatory cluster across the analysis window. Deployment mode segmentation captures cloud-based, hybrid, on-premises, and mobile-enabled configurations. End-user stratification separates classroom-facing teachers from central procurement administrators. CAGRs derive from trend extrapolation of documented procurement volumes, pricing trajectories, and technology substitution elasticities. Inputs include semiconductor supply lead times, certification processing durations, and national broadband deployment timelines.
Underlying assumptions cover sustained public education digitization funding in India, stable EU AI Act enforcement interpretation, and continued FCC E-Rate appropriations, with deviation risk concentrated in geopolitical semiconductor supply disruption and divergent GDPR data localization rulings across member states. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Educational Technology (EdTech)
Specific Gravity Bench Apparatus Market
Educational Technology (EdTech)
Education Security Market
Educational Technology (EdTech)
Digital Classroom Market
Educational Technology (EdTech)
Child Care Software Market
Educational Technology (EdTech)
Education Technology and Smart Classrooms Market
Educational Technology (EdTech)
Higher Education Technology Market
Educational Technology (EdTech)
AI in K-12 Education Market
Educational Technology (EdTech)
Global IoT in Education Market
Educational Technology (EdTech)
Virtual Schools Market
Educational Technology (EdTech)
Artificial Intelligence in the Education Sector Market
Educational Technology (EdTech)
Global Social Learning Platforms Market
Educational Technology (EdTech)
Education Apps Market
Educational Technology (EdTech)
Augmented and Virtual Reality in Education Market
Educational Technology (EdTech)
Artificial Intelligence (AI) in Education Market
Educational Technology (EdTech)
Game-Based Learning Market
Educational Technology (EdTech)
VR Education Market