
 Child Care Software Market | 2026-2036
Child Care Software Market Size, Share, and Industry Trends Forecast 2026-2036
Child Care Software Market Analysis
North American SaaS infrastructure is pivoting toward early childhood education verticals as institutional buyers demand integrated operational stacks. Brightwheel leverages its parent engagement architecture to anchor premium positioning in multi-site child care chains. Procare Software sustains geographic dominance through decades of localized billing compliance across US states. HiMama competes on assessment tool specialization, differentiating its developmental portfolio tracking against generic competitors.
Child care software denotes integrated digital platforms that automate enrollment, attendance, billing, and developmental reporting for licensed early childhood providers, typically operating on cloud-native architectures with API connectivity to state subsidy systems. These systems serve the commercial purpose of reducing administrative overhead while generating audit-ready documentation for regulatory reimbursement. Management software and billing software together capture the dominant share of current revenue, though communication tools represent the fastest-expanding margin pool as parent expectations shift toward real-time visibility. Cloud-based deployment leads absolute adoption while hybrid architectures retain traction among nonprofits with intermittent connectivity constraints.
FCC guidelines shape data transmission standards for platforms serving federally subsidized providers, while HIPAA-adjacent state privacy frameworks govern health record integration in multi-function systems. The US Department of Health and Human Services subsidy compliance rules create procurement gatekeeping that favors vendors with pre-built state certification modules. Stakeholders must monitor evolving state-level reimbursement digitization timelines to align product roadmaps with procurement windows.
Market Dynamics
US Department of Health and Human Services subsidy compliance rules are restructuring procurement gatekeeping, forcing vendors to pre-certify state reimbursement modules before platform deployment.
Growth Catalysts
- CCDF Reauthorization Requirements:Federal child care subsidy digitization mandates compel state agencies to modernize reimbursement infrastructure, accelerating vendor certification cycles.
- Dual-Income Household Density:Metropolitan clusters in California and Texas generate concentrated demand for real-time parent engagement platforms that reduce administrative friction.
- Cloud-Native Architecture Migration:Multi-site child care chains abandon on-premise legacy systems to achieve centralized billing compliance across fragmented state regulatory environments.
Market Restraints
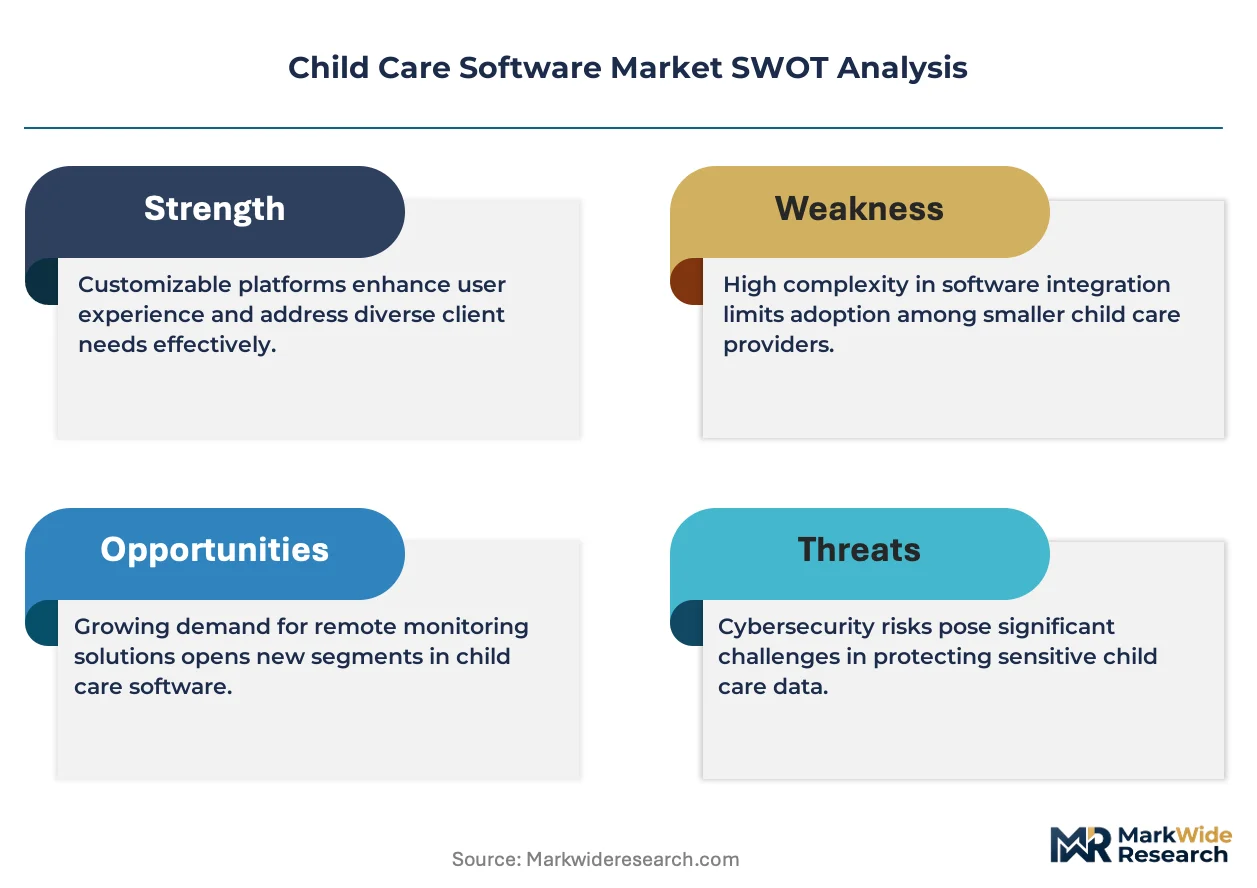
- State-by-State Certification Fragmentation:US subsidy compliance rules vary at the state level, forcing vendors to rebuild modules for each jurisdiction and compressing margin structures.
- Intermittent Connectivity in Rural Zones:Nonprofit providers in remote geographies cannot sustain pure cloud architectures, limiting addressable market expansion.
- HIPAA-Adjacent Privacy Liability:Health record integration within multi-function platforms exposes operators to state-level enforcement actions and insurance cost inflation.
Strategic Opportunities
- Assessment Tool Specialization:Developmental portfolio tracking capabilities remain underdeveloped relative to generic operational modules, creating differentiation white space.
- API Connectivity to State Systems:Pre-built certification modules that automate subsidy reimbursement workflows command procurement preference among institutional buyers.
- Parent Engagement Architecture:Real-time visibility tools that shift consumer expectations toward continuous communication represent the fastest-expanding margin pool.
Industry Challenges
- Legacy System Integration Complexity:Hybrid deployment architectures require specialized engineering talent to bridge intermittent connectivity constraints with cloud-native functionality.
- Localized Billing Compliance Expertise:Decades of state-specific regulatory knowledge concentration creates talent scarcity for vendors attempting geographic expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Child Care Software Market |
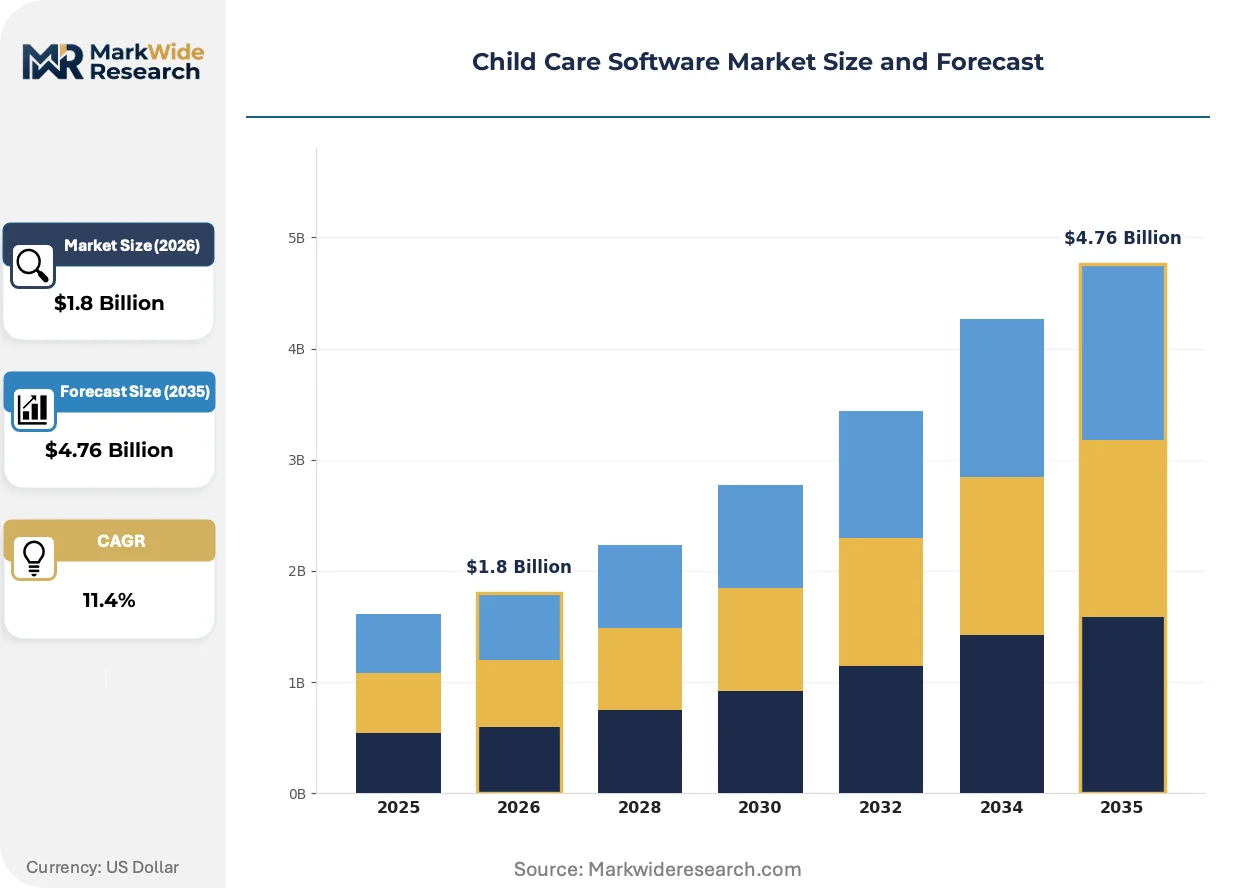
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Management Software, Billing Software, Communication Tools, Enrollment Software End User: Child Care Centers, Family Daycares, Preschools, Nonprofits Deployment: Cloud-Based, On-Premises, Hybrid, Mobile Applications Functionality: Attendance Tracking, Reporting Features, Parent Engagement, Assessment Tools |
| Companies Covered | Procare Software, Brightwheel, HiMama, EZChildTrack, Jackrabbit Technologies, LifeCubby, Childcare Sage, Bloomz, SofterWare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Child Care Software Market Emerging Trajectories
Child care software architecture is pivoting from operational automation toward developmental intelligence, embedding assessment capabilities that satisfy parent expectations and regulatory documentation requirements simultaneously.
Real-time parent communication platforms are rewriting competitive positioning in the child care software sector. These systems consolidate attendance alerts, billing notifications, and developmental milestone sharing into unified mobile interfaces. Multi-site chains in Texas and California deploy these tools aggressively to reduce parent churn. The technology is rewriting how centers justify premium tuition rates through transparency differentiation.
The US Department of Health and Human Services subsidy compliance rules are mandating audit-ready documentation standards for federally reimbursed providers. This regulatory pressure forces vendors to embed automated reporting workflows that pre-populate state reimbursement forms. Platforms lacking pre-built certification modules face procurement exclusion. Small independent centers in subsidized segments respond by consolidating vendor relationships toward compliant specialists.
Subscription-based pricing for parent-facing engagement tools is displacing perpetual licensing for core operational software. Child care chains now unbundle communication capabilities from management stacks, purchasing real-time visibility as standalone monthly services. Channel partners and reseller networks are capturing this transition by specializing in parent-app distribution. This behavioral shift concentrates most visibly in metropolitan markets with high dual-income household density where parent expectations for continuous updates have become baseline.
Child Care Software Market Segmentation
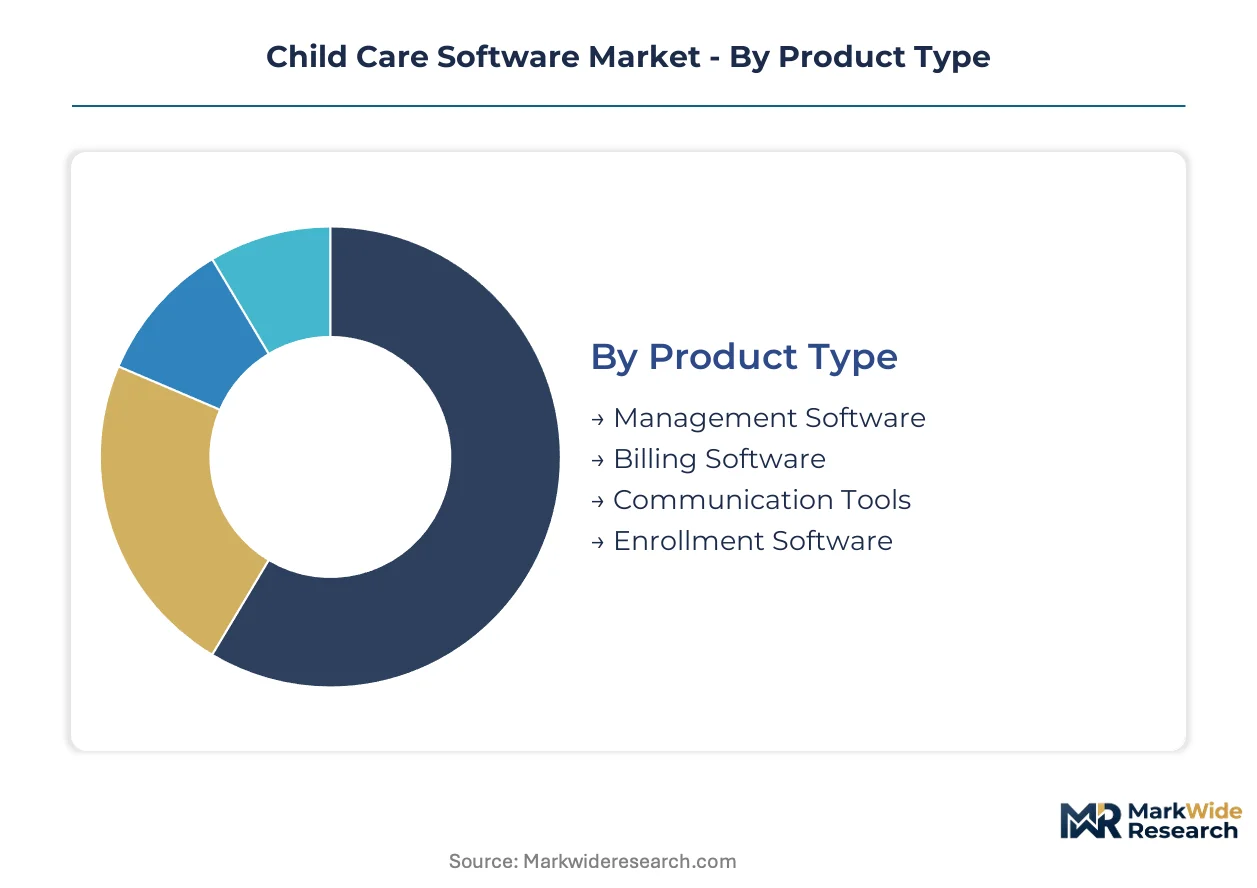
Child care software procurement follows distinct upgrade cycles across product categories, with institutional buyers prioritizing compliance-ready modules over point solutions. Segmentation reveals how vendor specialization aligns with operational maturity and regulatory exposure.
Product Type:
Replacement cycles accelerate where federal subsidy digitization mandates force legacy system obsolescence, compressing procurement windows for integrated platforms.
- Management Software:Centralized operational platforms automate enrollment, staff scheduling, and facility resource allocation across multi-site chains. Demand clusters in Texas and California metropolitan corridors where dual-income household density justifies premium operational stacks.
- Billing Software:State-specific reimbursement modules automate subsidy claim generation and audit-ready documentation. Procurement concentrates among federally subsidized providers facing US Department of Health and Human Services compliance deadlines.
- Communication Tools:Real-time parent engagement interfaces command standalone subscription pricing.
- Enrollment Software:Digital intake workflows reduce administrative overhead during peak registration periods.
Volume placements concentrate in Management Software; the faster expansion belongs to Communication Tools.
End User:
Cost tier segmentation separates enterprise-grade procurement by multi-site chains from constrained budgets of independent operators.
- Child Care Centers:Licensed commercial facilities with 50+ enrolled children drive demand for cloud-native architectures with API connectivity to state subsidy systems. California and Texas chains prioritize parent engagement differentiation to reduce churn.
- Family Daycares:Small licensed home-based operations require lightweight mobile-first solutions.
- Preschools:Academic-year programs emphasize developmental assessment documentation.
- Nonprofits:Federally subsidized community providers face intermittent connectivity constraints favoring hybrid deployment.
Revenue concentrates in Child Care Centers; Preschools are expanding most quickly on assessment specialization demand.
Deployment:
Application context determines architecture choice, with connectivity reliability and data sovereignty requirements driving configuration decisions.
- Cloud-Based:Fully hosted SaaS platforms enable centralized compliance management across fragmented state regulatory environments. Multi-site chains in metropolitan markets abandon on-premise legacy systems for this architecture.
- On-Premises:Local server installations persist where data residency requirements or legacy hardware investments block migration.
- Hybrid:Synchronized local-cloud architectures bridge intermittent rural connectivity gaps.
- Mobile Applications:Native smartphone interfaces serve parent-facing engagement and educator field data capture.
Deployment volume concentrates in Cloud-Based; Mobile Applications gain share fastest on parent expectation shifts.
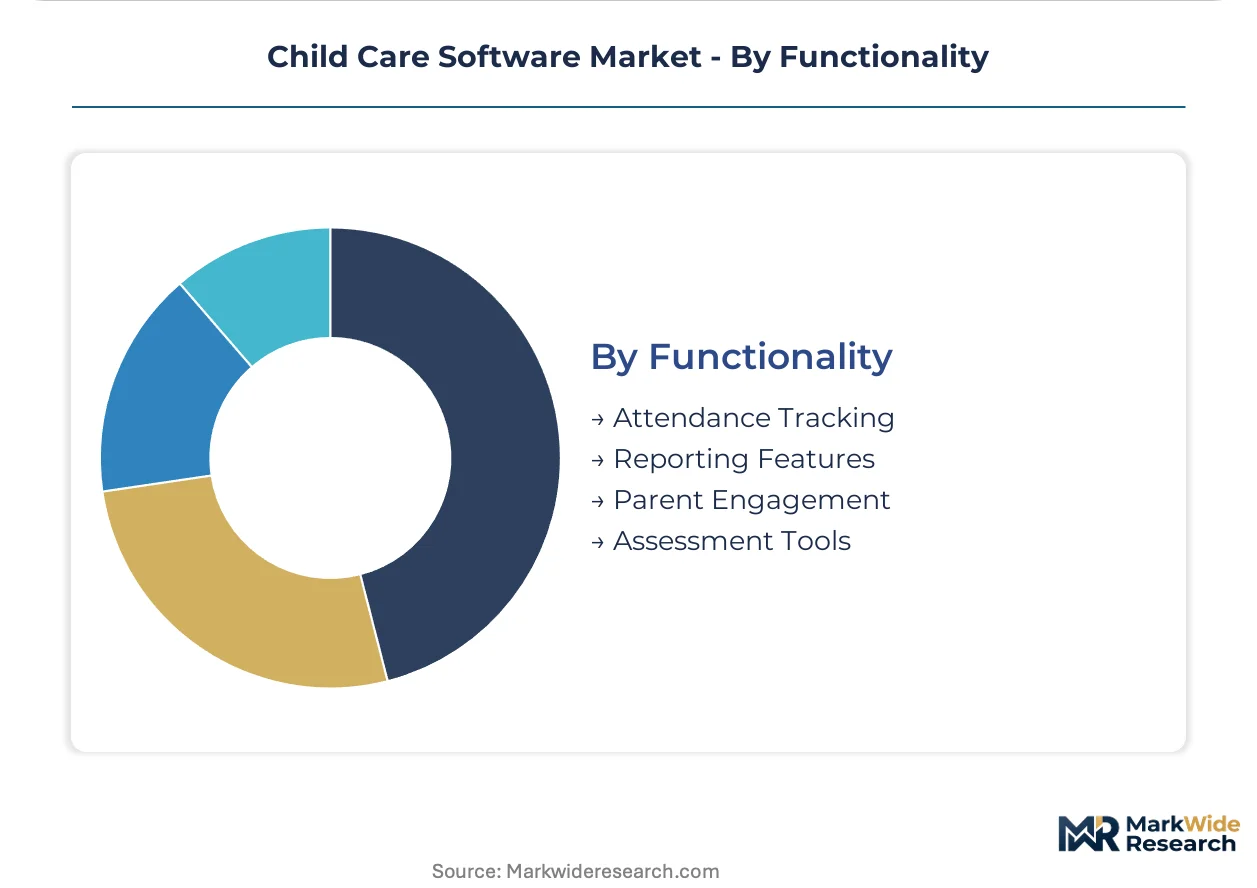
Functionality:
Margin structure varies sharply by capability depth, with documentation-intensive features commanding premium pricing over commoditized tracking modules.
- Attendance Tracking:Biometric and digital check-in systems automate regulatory ratio compliance and billing accuracy. This foundational capability saturates quickly, compressing vendor differentiation.
- Assessment Tools:Developmental portfolio tracking embeds pedagogical frameworks and milestone documentation for parent reporting. Demand from preschools and premium centers creates white space against generic competitors.
- Reporting Features:Automated state form population and audit trail generation.
- Parent Engagement:Real-time visibility into activities, meals, and milestones via unified mobile interfaces.
Functional volume concentrates in Attendance Tracking; Assessment Tools show the steepest expansion trajectory on differentiation demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon Valley's cloud infrastructure anchors North American child care software deployment. Dual-income household density in metropolitan corridors drives concentrated demand for parent engagement platforms.
United States
California and Texas metropolitan clusters generate the highest platform adoption rates among multi-site child care chains. The US Department of Health and Human Services subsidy compliance rules mandate audit-ready documentation standards for federally reimbursed providers. Dallas-Fort Worth chains deploy real-time parent engagement tools aggressively to reduce administrative friction and justify premium tuition rates.
Canada
Provincial childcare funding frameworks in Ontario and British Columbia accelerate cloud-native procurement among licensed providers. Health Canada guidelines shape data transmission standards for platforms serving subsidized nonprofit operators. Toronto's dense dual-income neighborhoods concentrate demand for integrated billing and developmental reporting systems.
United Kingdom
Ofsted inspection requirements drive demand for automated assessment documentation among early years providers. GDPR compliance frameworks govern parent data handling in multi-function platforms serving nursery chains. London's premium childcare market leads adoption of subscription-based parent communication tools.
Germany
Kitaplatz shortage pressures municipal providers toward operational efficiency software in Bavaria and North Rhine-Westphalia. Federal youth welfare regulations mandate structured developmental tracking for subsidized facilities. Berlin's Kita chains prioritize hybrid deployment architectures to bridge connectivity gaps in eastern boroughs.
Australia
Child Care Subsidy digitization mandates from the Department of Education accelerate vendor certification cycles across New South Wales and Victoria. The Australian Children's Education and Care Quality Authority sets documentation standards that favor integrated assessment platforms. Sydney's corporate childcare centers lead cloud migration away from legacy on-premise systems.
Child Care Software Market Vendor Landscape
Global majors compete with regional champions across state certification expertise and parent engagement architecture. The vendor base organizes into three tiers: established platforms with decades of localized billing compliance, cloud-native entrants competing on mobile-first design, and specialized assessment tool providers. Strategic moves concentrate on pre-building state reimbursement modules and unbundling communication capabilities into standalone subscription services.
Within the cloud-native tier, Brightwheel and HiMama occupy positions defined by parent-facing engagement specialization versus developmental portfolio tracking. Procare Software exemplifies the legacy-compliant archetype through sustained geographic dominance across fragmented US state regulatory environments. These three companies represent the competitive vectors reshaping procurement preferences among institutional buyers.
| Leading Market Players |
|---|
| Procare Software |
| Brightwheel |
| HiMama |
| EZChildTrack |
| Jackrabbit Technologies |
| LifeCubby |
| Childcare Sage |
| Bloomz |
| SofterWare |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up specialists dominate vendor ownership across North American child care software, concentrating development resources in California and Texas while enforcing subscription pricing discipline through portfolio-wide margin targets. This ownership pattern compresses supply-side innovation cycles and hardens annual contract value minimums for multi-site chains seeking integrated compliance modules.
Pricing Analysis
Service-bundling separates state certification support from core platform fees, with vendors unbundling parent engagement tools into standalone monthly subscriptions while embedding compliance consulting into enterprise tiers. Three-tier pricing structure across premium, standard, and economy levels aligns with center size and subsidy dependency, with federally reimbursed providers facing mandatory premium tiers for audit-ready documentation. Cost compression in standard tiers intensifies because cloud-native entrants compete on per-seat rates without legacy compliance depth. Independent family daycares exhibit highest price sensitivity, while multi-site chains in metropolitan California absorb premium positioning for parent retention differentiation.
Supply Chain Analysis
Freight costs for on-premise server hardware and edge computing equipment concentrate supply dependencies on Taiwan, China, and Mexico for semiconductor components and assembly. Cloud infrastructure draws from hyperscaler data centers in Virginia, Oregon, and Ohio, with API connectivity modules resting on third-party authentication services from Ireland and Singapore. Single-source vulnerability in state subsidy system integrations creates procurement bottlenecks where vendors await jurisdictional certification approvals. Distribution runs through direct enterprise sales teams for multi-site chains, with channel partners and reseller networks serving independent operators and family daycare segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates under supply-constrained conditions where state certification module development capacity props pricing power for compliant vendors. Talent scarcity in localized billing compliance expertise limits rapid vendor expansion and sustains incumbent margin structures.
For Market Incumbents: Acquire specialized assessment tool providers to anchor developmental portfolio capabilities against HiMama's differentiation. Consolidate channel partner networks in Texas and California to block cloud-native entrants from securing multi-site chain procurement decisions. State-by-state certification fragmentation threatens geographic expansion margins; preemptive hiring of former state agency reimbursement specialists defends this moat.
For New Entrants and Emerging Players: Capture nonprofit segments in rural zones with intermittent connectivity constraints through hybrid deployment architectures that legacy cloud-native platforms underserve. Target family daycares in subsidized segments with mobile-first, lightweight solutions priced below incumbent per-seat minimums. Partner with state reseller networks to bypass direct enterprise sales cost structures.
For Investors and Strategic Acquirers: Distressed-cycle entries favor assessment tool specialists with pre-built developmental frameworks in California and Texas metropolitan corridors. Long-term viability hinges on API connectivity depth to evolving state subsidy digitization timelines. Watch US Department of Health and Human Services reauthorization schedules as inflection indicators for procurement window acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| State Certification Module Expansion | Pre-built reimbursement workflows lock out non-compliant vendors from federally subsidized provider procurement. |
| Parent Engagement Platform Unbundling | Standalone subscription pricing captures margin expansion in metropolitan dual-income household clusters. |
| Hybrid Architecture Development | Synchronized local-cloud deployment bridges rural nonprofit connectivity gaps and expands addressable market. |
| Assessment Tool Specialization | Developmental portfolio tracking differentiates against generic operational modules in preschool segments. |
| Channel Partner Network Consolidation | Reseller specialization in parent-app distribution captures behavioral shift toward real-time visibility tools. |
Methodological Framework
Multi-period observation of state subsidy digitization timelines, vendor certification cycles, and parent engagement platform adoption anchored the trend analysis, supplemented by interviews with child care center operations directors, state agency reimbursement administrators, early childhood education technology procurement officers, and SaaS platform product managers. Secondary validation drew from US Department of Health and Human Services policy filings, state child care development fund plans, SEC disclosures from publicly traded education technology holdings, and hyperscaler cloud infrastructure expansion announcements. Bottom-up sizing of provider segments triangulated against top-down market value estimates from institutional buyer spending patterns.
Input-output matrices mapped deployment model adoption curves against regulatory compliance requirements across the projection horizon. Segmentation dimensions modeled include product type, end user category, deployment architecture, and functionality depth, with regional adoption patterns capturing metropolitan versus rural divergence. CAGRs derived from fitted growth curves applied to verified base-year estimates, incorporating CCDF reauthorization schedules and cloud migration velocity among multi-site chains as industry-specific forecast inputs.
The model holds under sustained federal subsidy digitization mandates and stable cloud infrastructure pricing; deviation in state-level reimbursement system procurement delays or hyperscaler cost inflation would shift vendor margin structures and adoption timelines. Stakeholders should weight assumptions against their own operating context and state-specific regulatory exposure.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Educational Technology (EdTech)
Asia Big Data Analytics in Education Market
Educational Technology (EdTech)
Global Edutainment Centers Market
Educational Technology (EdTech)
ASEAN Smart Education and Learning Market
Educational Technology (EdTech)
Education Technology and Smart Classrooms Market
Educational Technology (EdTech)
AI in K-12 Education Market
Educational Technology (EdTech)
Virtual Schools Market
Educational Technology (EdTech)
Higher Education Learning Systems Market
Educational Technology (EdTech)
Digital Classroom Market
Educational Technology (EdTech)
Smart Education System Market
Educational Technology (EdTech)
SETM Education Market
Educational Technology (EdTech)
Edutainment Market
Educational Technology (EdTech)
Global K-12 Software Market
Educational Technology (EdTech)
Global IoT in Education Market
Educational Technology (EdTech)
Edtech and Smart Classroom Market
Educational Technology (EdTech)
Global Micro-Learning Market
Educational Technology (EdTech)
Micro Learning Platform Market