
 Game-Based Learning Market | 2026-2036
Game-Based Learning Market Size, Share, and Industry Trends Forecast 2026-2036
Game-Based Learning Market Analysis
Multi-source content partnerships between specialized studios and platform distributors is recalibrating how game-based learning modules reach end users. Kahoot! leverages its freemium classroom footprint to upsell institutional licenses across K-12 districts. Strivr anchors enterprise VR training through exclusive content deals with Fortune 500 safety programs. Mursion differentiates via actor-driven simulation pods for soft-skills coaching in healthcare and customer service verticals.
Game-based learning denotes pedagogical systems that embed curriculum objectives within interactive rule-based environments, typically employing real-time feedback loops, adaptive difficulty algorithms, and progress analytics dashboards to sustain learner engagement. Its primary commercial purpose centers on improving knowledge retention rates and reducing training time-to-competency versus passive e-learning formats. Mobile games capture the largest addressable user base among product type segments, though simulation games command premium pricing in corporate and clinical certification use cases. Cloud gaming technology is expanding fastest among technology segments by eliminating hardware barriers for AR and VR deployments in under-resourced school districts.
GDPR shapes how European EdTech platforms collect learner analytics, while the EU AI Act imposes risk-classification requirements on adaptive tutoring algorithms that personalize difficulty in real time. In the United States, FERPA restricts cross-border data flows for student records, complicating multi-tenant platform architectures that serve both domestic and international institutions. Stakeholders must monitor how divergent privacy frameworks fragment cloud infrastructure decisions and content localization roadmaps.
Market Dynamics
Cloud gaming infrastructure is compressing hardware procurement cycles for immersive learning deployments, forcing platform vendors to re-architect delivery models around streaming latency rather than local processing power.
Growth Catalysts
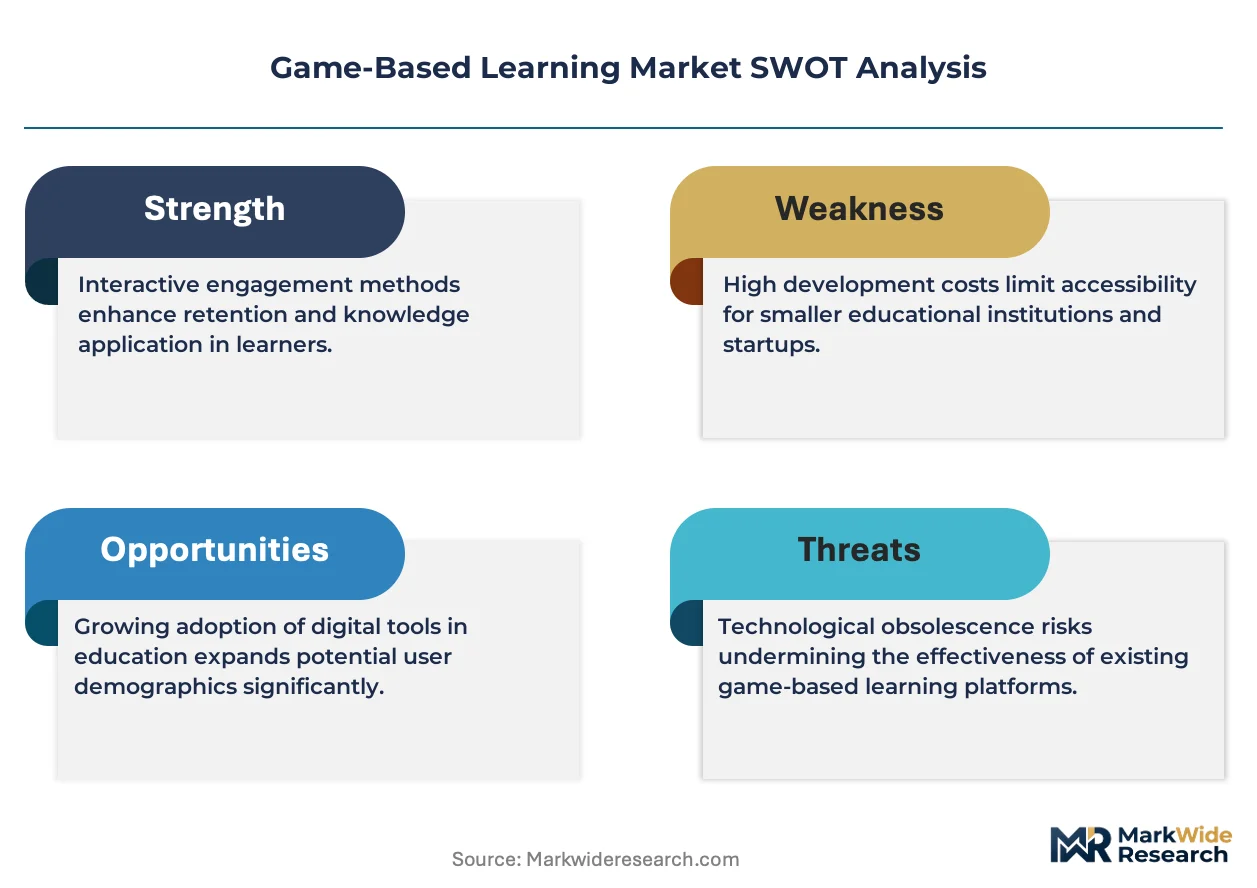
- EU AI Act risk-classification framework:Adaptive tutoring algorithms now face mandated transparency requirements, prompting European EdTech platforms to invest in explainable AI architectures that build institutional trust.
- Corporate safety training verticals:Scenario-based simulations for hazardous environment preparation are replacing classroom instruction at energy and manufacturing firms seeking OSHA compliance documentation.
- 5G network densification:Ultra-low latency connectivity in South Korean and Japanese urban corridors is enabling real-time multiplayer educational experiences previously impossible on 4G infrastructure.
Market Restraints
- GDPR Article 17 right-to-erasure:Learner analytics retention conflicts with progress-tracking requirements, forcing European platforms to maintain parallel data architectures with truncated historical datasets.
- GPU supply concentration:Cloud rendering capacity for AR/VR modules depends on TSMC-fabricated chips, exposing pricing volatility to Taiwan Strait logistics disruptions.
- Substitution by passive video:Microlearning platforms offering Netflix-style content libraries capture budget-constrained K-12 districts unwilling to fund interactive development.
Strategic Opportunities
- Brazilian vocational certification gap:ANVISA-aligned healthcare simulation modules remain underdeveloped for Latin America's largest clinical training market.
- Generative AI-NPC convergence:Large language models powering dynamic dialogue trees are creating personalized narrative branches without scripted content costs.
- India's National Education Policy 2020:Competency-based assessment mandates are opening procurement channels for formative assessment-embedded games in BIS-regulated curricula.
Industry Challenges
- Instructional design-specialized developer scarcity:Platforms struggle to hire talent bridging pedagogy and game engine proficiency, particularly for Unreal Engine 5 optimization.
- FERPA-compliant multi-tenant architecture:US student record restrictions complicate SaaS platforms serving both domestic and international institutions from shared infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Game-Based Learning Market |
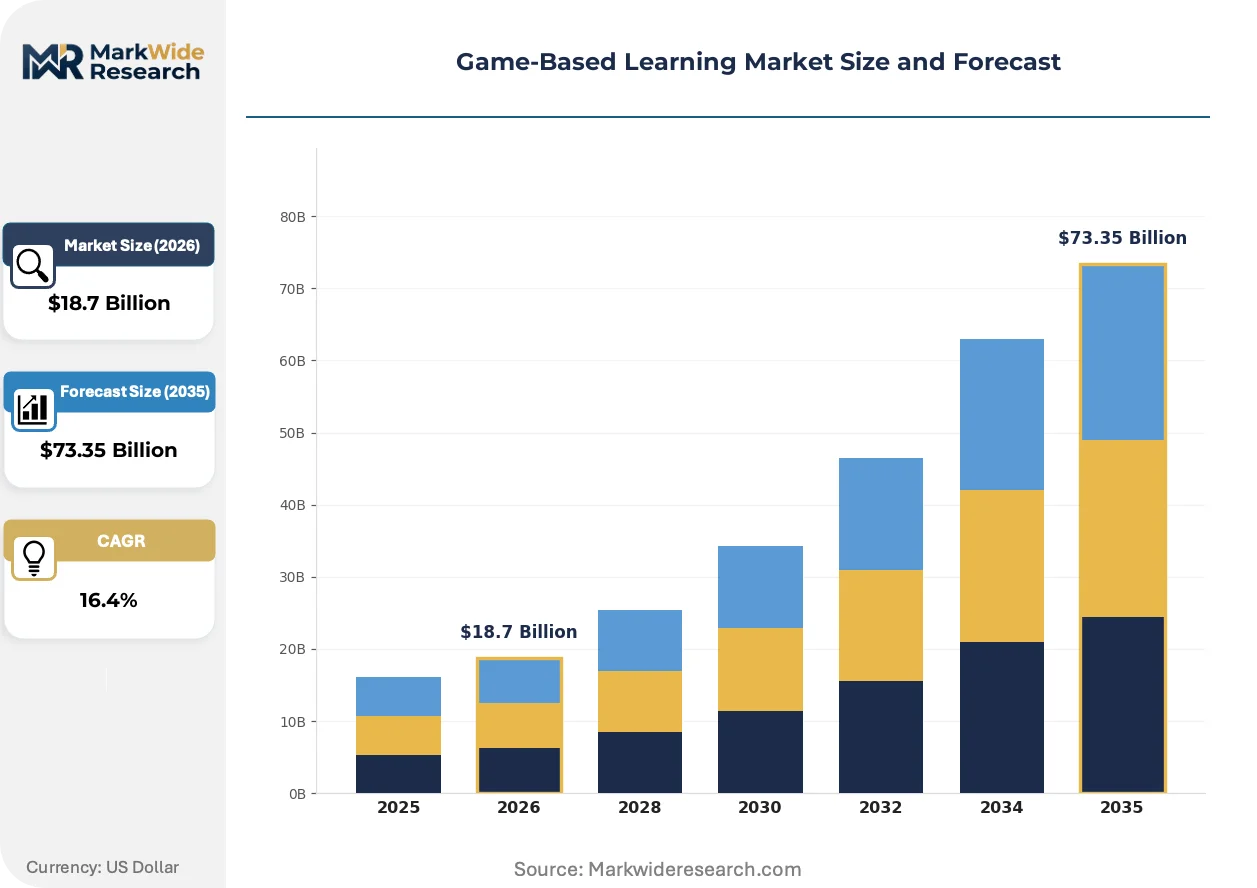
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $73.35 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mobile Games, Online Platforms, Simulation Games, Educational Board Games Technology: Virtual Reality, Augmented Reality, Cloud Gaming, Gamification Tools End User: K-12 Schools, Higher Education, Corporate Training, Non-Profits Delivery Mode: Self-Paced Learning, Instructor-Led Training, Blended Learning, Remote Learning |
| Companies Covered | Mursion, CenarioVR, Playware Studios, G-Cube, Gamelearn, Axonify, Strivr, Qstream, Kahoot!, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Game-Based Learning Market Emerging Trajectories
Real-time rendering and generative content pipelines are collapsing production timelines for immersive learning modules, enabling rapid scenario customization previously requiring months of scripted development.
Spatial computing headsets are electrifying clinical skills training by overlaying holographic patient anatomy onto physical manikins. Medical schools in the United States and United Kingdom are deploying these systems for surgical procedure rehearsal. The technology is electrifying credential pathways by compressing supervised practice hours while maintaining procedural fidelity standards.
GDPR's Article 35 data protection impact assessments are mandating privacy-by-design architectures for European EdTech platforms collecting biometric engagement metrics. Publishers must now document algorithmic decision-making logic before deploying adaptive difficulty systems. K-12 procurement frameworks in Germany and France are prioritizing vendors with pre-certified DPIA documentation, creating compliance-based vendor selection criteria.
Enterprise L&D departments are consolidating vendor relationships around integrated platform ecosystems rather than point solutions for discrete training modalities. Fortune 500 safety programs are replacing standalone VR modules with suites offering progress analytics across desktop, mobile, and immersive formats. This consolidation is most visible in United States corporate budgets where procurement teams seek unified data lakes for competency tracking across blended learning journeys.
Game-Based Learning Market Segmentation
Game-based learning modules carry divergent certification burdens across education and enterprise verticals, with K-12 procurement frameworks demanding FERPA-compliant architectures while corporate safety simulations require OSHA documentation trails. Understanding how regulatory requirements map to segment boundaries enables vendors to prioritize development roadmaps and localization investments.
Product Type:
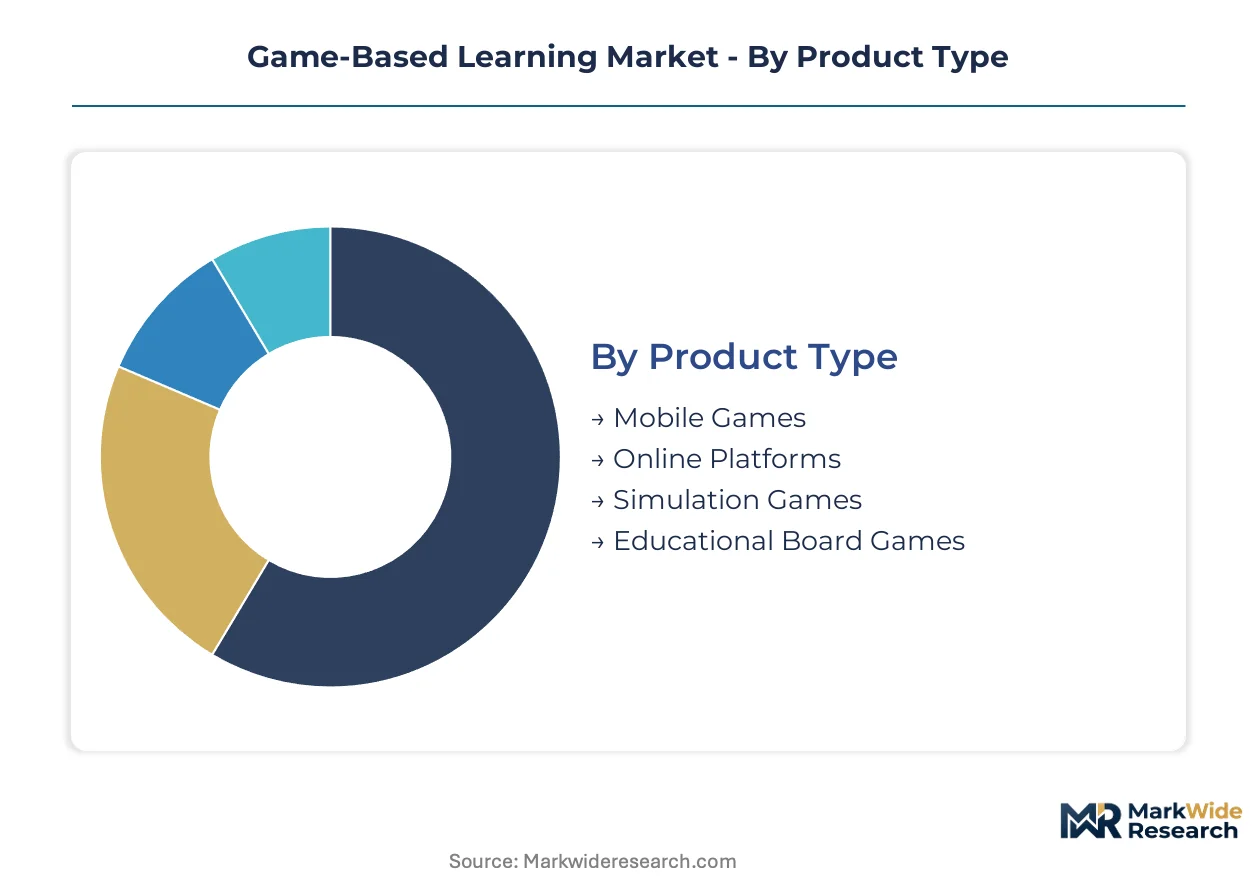
Mobile games face minimal certification overhead in consumer-facing deployments, while simulation games trigger clinical and safety compliance protocols depending on end-use context.
- Mobile Games:Touch-optimized modules deploy through iOS and Android storefronts with lightweight institutional provisioning. Demand concentrates in United States K-12 districts purchasing district-wide licenses for math and literacy remediation, constrained by procurement cycles tied to ESSER fund expiration deadlines.
- Simulation Games:Physics-based environments replicate hazardous equipment operation, surgical procedures, or emergency response scenarios with procedural fidelity requirements. Corporate training departments at energy and manufacturing firms anchor demand, driven by OSHA compliance documentation needs and insurance premium reduction incentives.
- Online Platforms:Browser-delivered ecosystems integrate assessment engines and progress dashboards for institutional deployment.
- Educational Board Games:Physical-digital hybrid products target early childhood motor skill development and social-emotional learning curricula.
Leading the category by volume: Mobile Games. Growing fastest: Simulation Games.
Technology:
Cost tiers separate hardware-dependent immersive modalities from software-layer gamification overlays, with capital expenditure thresholds determining adoption sequencing across customer types.
- Cloud Gaming:Streaming infrastructure eliminates GPU procurement for end users, enabling AR and VR module delivery to under-resourced school districts via 5G connectivity. South Korean and Japanese urban corridors demonstrate concentrated adoption where network densification supports ultra-low latency educational multiplayer experiences.
- Gamification Tools:Points, badges, and leaderboard layers integrate atop existing LMS deployments without hardware replacement. Higher education institutions in the United States represent the densest adoption cluster, pressured by enrollment competition to demonstrate engagement metrics to accreditation bodies.
- Virtual Reality:Headset-dependent immersion requires dedicated lab space and technical support staffing for deployment.
- Augmented Reality:Smartphone camera-overlay experiences bridge accessibility and spatial computing for clinical anatomy visualization.
Cloud Gaming commands the premium tier on total cost of ownership. Gamification Tools scale most broadly across budget-constrained institutions.
End User:
Customer type determines pricing architecture elasticity, with corporate training budgets accommodating per-seat premiums that K-12 procurement frameworks cannot sustain.
- Corporate Training:Fortune 500 safety programs and healthcare systems purchase scenario-based simulations with competency-tracking analytics. United States enterprise L&D spending anchors regional volume, with procurement teams consolidating vendor relationships around unified data lakes for blended learning journeys.
- K-12 Schools:District-level purchasing frameworks prioritize interoperability with existing SIS and LMS infrastructure, constrained by ESSER fund timelines and state-level curriculum alignment requirements.
- Higher Education:Competency-based assessment mandates under India's National Education Policy 2020 are opening procurement channels for formative assessment-embedded games in BIS-regulated curricula.
- Non-Profits:Grant-funded deployments target literacy and numeracy interventions in underserved communities with offline-capable mobile modules.
Corporate Training generates the highest per-seat revenue. K-12 Schools represent the largest addressable user base.
Delivery Mode:
Maturity curves separate established synchronous formats from emerging hybrid architectures, with pandemic-era infrastructure investments now constraining migration pathways.
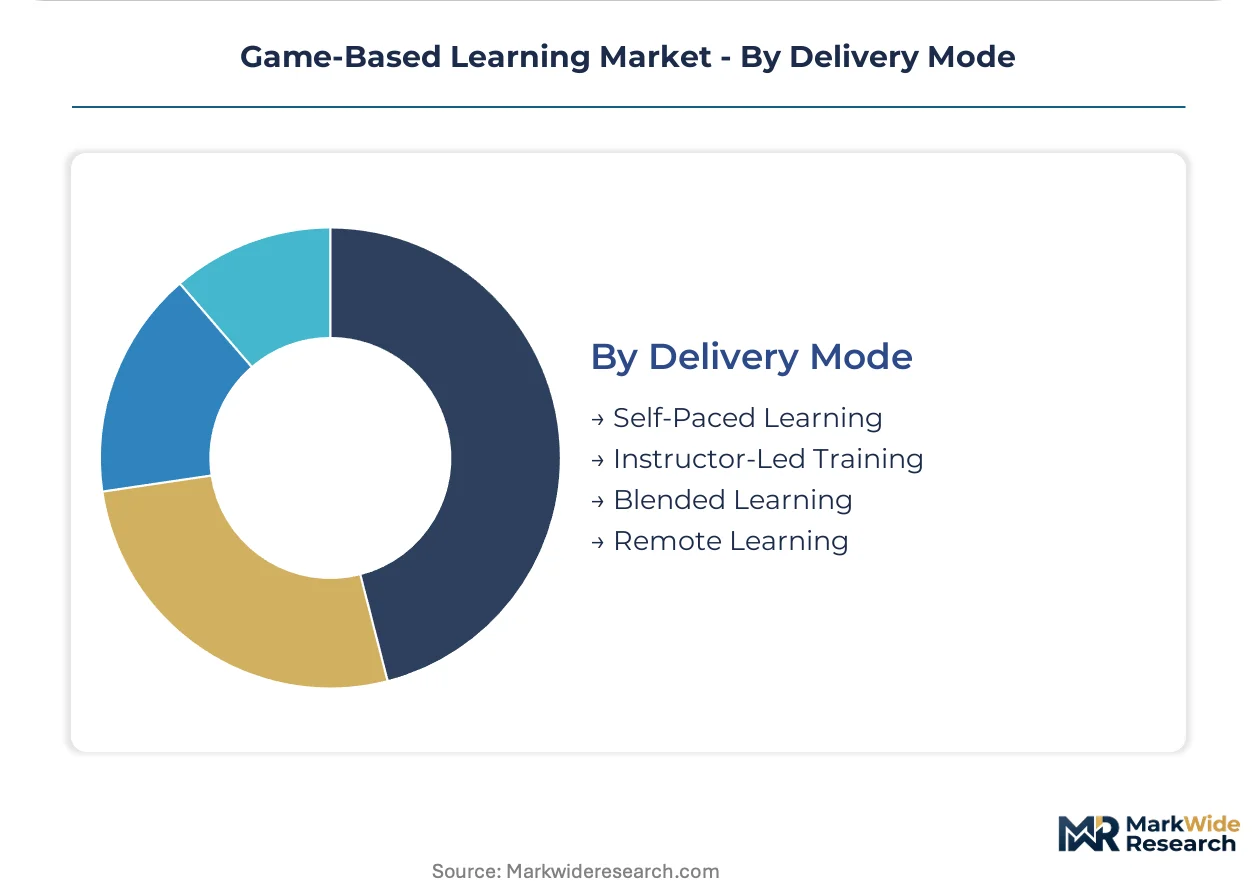
- Blended Learning:Rotational models combining in-person instruction with self-paced digital modules dominate post-pandemic institutional planning. United States K-12 districts with 1:1 device programs anchor demand, driven by federal connectivity subsidies and teacher professional development investments.
- Remote Learning:Fully asynchronous platforms with automated progress tracking serve geographically dispersed corporate workforces and rural education markets. Cloud gaming infrastructure enables this segment by eliminating hardware uniformity requirements across distributed learner populations.
- Self-Paced Learning:Individual progress tracking with adaptive difficulty algorithms supports competency-based credentialing pathways.
- Instructor-Led Training:Synchronous virtual classrooms with real-time facilitator dashboards persist in soft-skills and leadership development verticals.
Blended Learning holds the dominant installed base. Remote Learning is climbing the fastest as enterprise distributed workforce training normalizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Corporate L&D spending and K-12 procurement frameworks concentrate demand in the United States, while cloud gaming infrastructure adoption accelerates fastest in East Asian urban corridors with advanced 5G densification.
United States
Fortune 500 safety programs and healthcare systems drive enterprise demand for scenario-based simulations with OSHA compliance documentation. FERPA restricts cross-border data flows for student records, complicating multi-tenant platform architectures. Boston and San Francisco anchor medical school deployments of spatial computing headsets for surgical procedure rehearsal.
Germany
K-12 procurement frameworks prioritize vendors with pre-certified GDPR Article 35 data protection impact assessments. The EU AI Act imposes risk-classification requirements on adaptive tutoring algorithms that personalize difficulty in real time. Berlin and Munich concentrate EdTech platform development for explainable AI architectures.
South Korea
Ultra-low latency 5G connectivity enables real-time multiplayer educational experiences previously impossible on 4G infrastructure. The country's national education technology regulator aligns procurement with network densification milestones. Seoul anchors concentrated adoption of cloud gaming infrastructure for AR and VR module delivery to under-resourced districts.
India
The National Education Policy 2020 mandates competency-based assessment, opening procurement channels for formative assessment-embedded games in BIS-regulated curricula. State-level digital infrastructure investments accelerate blended learning adoption. Maharashtra and Karnataka concentrate higher education procurement for browser-delivered assessment ecosystems.
Brazil
ANVISA-aligned healthcare simulation modules remain underdeveloped for Latin America's largest clinical training market. Federal vocational certification gaps create procurement opportunities for scenario-based safety training. São Paulo anchors corporate demand for Portuguese-localized enterprise simulation content.
Game-Based Learning Market Vendor Landscape
Strategic partnerships dominate the current landscape as specialized studios and platform distributors recalibrate content distribution channels. The vendor base spans freemium classroom platforms, enterprise VR training specialists, and actor-driven simulation providers. Three archetypes define competitive positioning: freemium upsell platforms, immersive hardware-anchored specialists, and content-agnostic distribution layers. M&A activity and exclusive content licensing represent the dominant competitive moves for market access.
Within the immersive training tier, Strivr and Mursion occupy distinct positions—Strivr exemplifies hardware-anchored enterprise deployment through exclusive content deals, while Mursion represents actor-driven simulation pods for soft-skills coaching. Kahoot! sits within the freemium platform archetype, leveraging classroom footprint to upsell institutional licenses across district-level procurement frameworks.
| Leading Market Players |
|---|
| Mursion |
| CenarioVR |
| Playware Studios |
| G-Cube |
| Gamelearn |
| Axonify |
| Strivr |
| Qstream |
| Kahoot! |
| Others |
Supply Flow & Price Mechanics
GPU spot pricing volatility from TSMC-fabricated chips cascades through cloud gaming infrastructure costs into tiered SaaS subscription models, compressing margins for AR/VR module providers serving under-resourced school districts while inflating premiums for enterprise safety simulations with OSHA documentation requirements.
Pricing Analysis
Volume concentrates in mobile game licenses with thin per-seat margins, while simulation games capture premium pricing through compliance documentation value. SaaS-tiered subscriptions dominate, with price differentiation driven by certification grade and customization level. Cost compression in cloud rendering tiers is intensifying due to GPU supply concentration. K-12 procurement frameworks exhibit highest price sensitivity; corporate training departments accommodate per-seat premiums for competency-tracking analytics.
Supply Chain Analysis
Freight cost spikes for headset hardware from China, Taiwan, and South Korea are elevating total cost of ownership for immersive learning deployments. Cloud gaming infrastructure draws from concentrated semiconductor fabrication in Taiwan and South Korea, with software-layer content development anchored in the United States and Germany. Single-source vulnerability in TSMC chip supply exposes pricing volatility to Taiwan Strait logistics disruptions. Distribution runs through platform distributors and specialized studios with exclusive content licensing arrangements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud gaming infrastructure is displacing on-premise delivery architectures, forcing stakeholders to recalibrate around streaming latency optimization rather than local GPU procurement cycles.
For Market Incumbents: Lock in exclusive content partnerships with Fortune 500 safety programs and K-12 district procurement frameworks to defend against generative AI-NPC entrants offering dynamic dialogue without scripted development costs. Deepen backward integration into cloud rendering capacity to secure GPU supply allocation from TSMC-fabricated chip vendors. Prioritize FERPA-compliant multi-tenant architecture investments to maintain SaaS platform access to United States student record datasets.
For New Entrants and Emerging Players: The mid-market pricing gap between premium enterprise VR simulations and economy-tier mobile remediation modules offers white-space entry for browser-delivered assessment ecosystems with adaptive difficulty algorithms. Target India's higher education sector under National Education Policy 2020 competency-based assessment mandates, where BIS-regulated curriculum gaps remain underdeveloped. Pursue grant-funded non-profit deployments for offline-capable literacy interventions as proof-of-concept traction.
For Investors and Strategic Acquirers: Distressed-cycle entries favor actor-driven simulation pod specialists with healthcare and customer service vertical traction in United States metropolitan clusters. Long-term viability hinges on explainable AI architecture investments ahead of EU AI Act risk-classification enforcement. Watch for 5G network densification milestones in South Korean and Japanese urban corridors as inflection indicators for real-time multiplayer educational experience adoption.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies progress analytics across desktop, mobile, and immersive formats for Fortune 500 safety programs. |
| Strategic Partnership | Exclusive content licensing with specialized studios secures OSHA-compliant scenario libraries. |
| Acquisition of Specialist Firm | Actor-driven simulation pods add soft-skills coaching depth to healthcare vertical offerings. |
| Geographic Expansion | Portuguese-localized content captures ANVISA-aligned healthcare simulation gaps in São Paulo. |
| Product Launch | Generative AI-NPC modules reduce scripted content costs for personalized narrative branches. |
Methodological Framework
Multi-period observation of ESSER fund procurement cycles, 5G network densification milestones, and GDPR Article 35 certification trends anchored the trend analysis, supplemented by interviews with corporate L&D directors, K-12 district procurement officers, EdTech platform engineers, and instructional design specialists. Secondary validation drew from SEC filings, hyperscaler capex disclosures, FDA OSHA compliance documentation, and EU AI Act regulatory filings. Bottom-up segment sizing triangulated against top-down education technology budget forecasts.
Input-output matrices modeled deployment model, organization size, vertical application, and regional adoption pattern across the projection horizon. CAGRs derived from segment-level growth rate reconciliation with macroeconomic education spending indicators. Cloud gaming infrastructure penetration curves and adaptive algorithm explainability investment timelines served as industry-specific forecast inputs.
Inputs from corporate training budget disclosures and K-12 procurement databases were available through the study window; gaps in real-time biometric engagement metric standardization introduce uncertainty bands around spatial computing headset adoption curves. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Educational Technology (EdTech)
Global Smart Classroom Market
Educational Technology (EdTech)
Augmented and Virtual Reality in Education Market
Educational Technology (EdTech)
Virtual Reality in Education Market
Educational Technology (EdTech)
Asia-Pacific Digital Education Market
Educational Technology (EdTech)
E Learning Virtual Reality Market
Educational Technology (EdTech)
Asia Big Data Analytics in Education Market
Educational Technology (EdTech)
Edtech and Smart Classroom Market
Educational Technology (EdTech)
North America Digital Education Market
Educational Technology (EdTech)
Higher Education Learning Systems Market
Educational Technology (EdTech)
Edtech Market
Educational Technology (EdTech)
Child Care Software Market
Educational Technology (EdTech)
M-Education Market
Educational Technology (EdTech)
Global Edutainment Centers Market
Educational Technology (EdTech)
Global Micro-Learning Market
Educational Technology (EdTech)
Global Smart Learning Market
Educational Technology (EdTech)
ASEAN Smart Education and Learning Market