
 Education Technology and Smart Classrooms Market | 2026-2036
Education Technology and Smart Classrooms Market Size, Share, and Industry Trends Forecast 2026-2036
Education Technology and Smart Classrooms Market Intelligence
Modular bundling of hardware-software classroom suites is expanding buyer choice across district-level procurement offices. Coursera leverages its enterprise partnerships to anchor corporate training modules within institutional learning stacks. Duolingo competes through gamification-driven user retention models that sustain engagement metrics for language acquisition platforms.
Education technology and smart classrooms encompass integrated digital infrastructure combining interactive displays, learning management systems, and AI-driven adaptive content delivery with bandwidth requirements typically exceeding 100 Mbps per classroom node; the primary commercial purpose centers on measurable learning outcome improvement through real-time analytics and personalized pacing. Learning Management Systems dominate institutional spending as the backbone of gradebook integration and content distribution, while Artificial Intelligence segments capture expanding margin pools through predictive dropout alerts and automated assessment generation. Cloud-Based deployment models lead new installations given scalability advantages for multi-campus districts managing thousands of concurrent users.
The EU AI Act and GDPR constrain algorithmic transparency requirements for student-facing adaptive systems in European deployments, while India's BIS certification mandates electromagnetic compatibility standards for imported interactive hardware. The US Department of Education's guidance on student data privacy shapes procurement specifications that district IT directors must verify before vendor selection. Stakeholders must monitor evolving interoperability standards between competing LMS platforms as districts resist vendor lock-in through renewed emphasis on open data protocols.
Market Dynamics
Cloud-based deployment models are compressing district procurement cycles as K-12 administrators prioritize scalable infrastructure over capital-intensive hardware refresh programs. The EU AI Act and India's BIS certification regime are simultaneously reshaping vendor compliance roadmaps across two of the largest addressable education markets.
Growth Catalysts
- Federal connectivity subsidies:US Department of Education E-Rate program expansions are accelerating fiber-to-classroom mandates in underserved rural districts.
- Adaptive assessment algorithms:AI-driven personalized pacing engines are penetrating state procurement frameworks as measurable learning outcome guarantees replace seat-time metrics.
- Tier-1 municipal funding:India's central education ministry allocations through state governments are concentrating smart classroom infrastructure deployment in Delhi, Mumbai, and Bangalore.
Market Restraints
- Semiconductor input volatility:Interactive display panel production depends on concentrated GPU and memory chip supply from Taiwan and South Korea foundries.
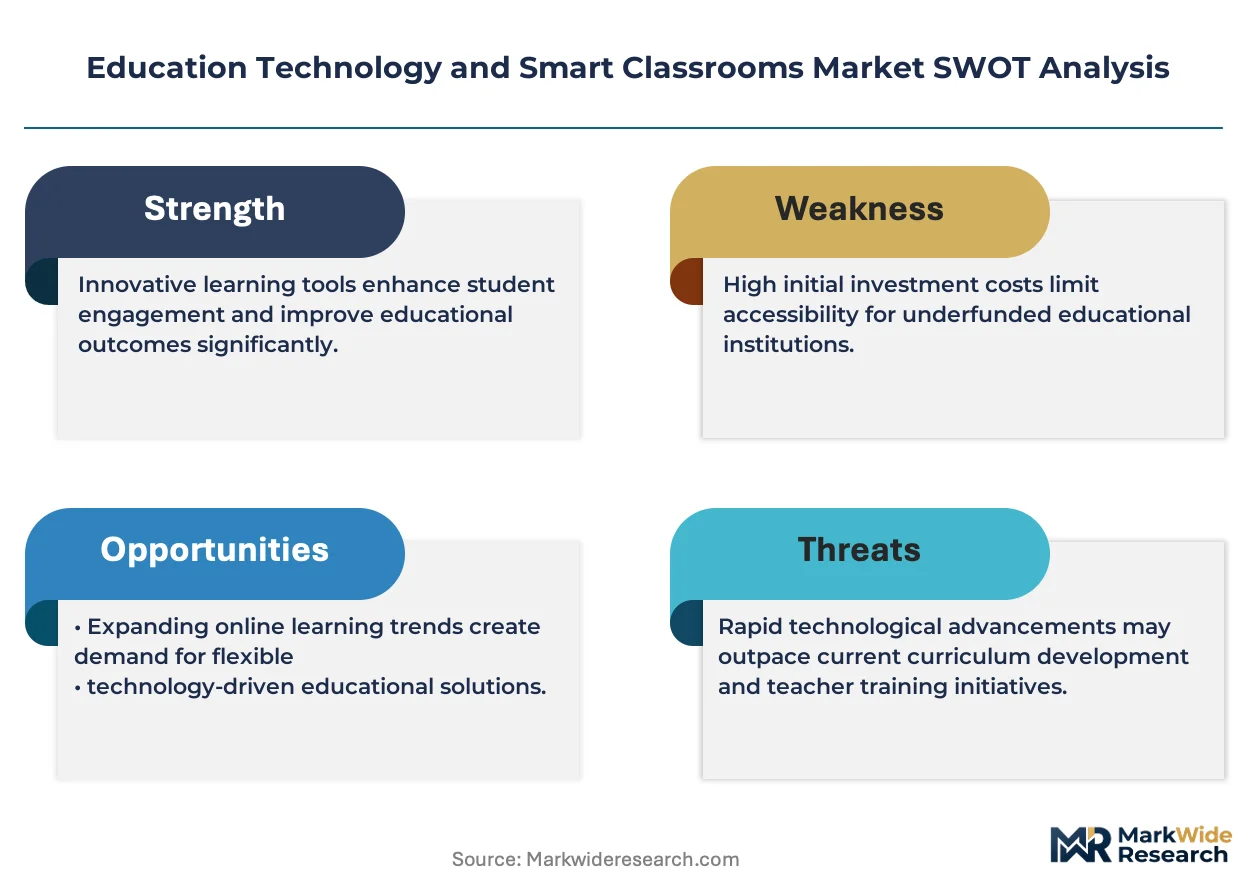
- GDPR algorithmic transparency mandates:European student-facing adaptive systems face documentation burdens that extend sales cycles by 8-14 months.
- Legacy LMS substitution threat:Districts with sunk costs in entrenched platforms resist full-stack replacements despite superior interoperability claims.
Strategic Opportunities
- Rural broadband convergence:5G fixed-wireless and low-earth-orbit satellite hybrids are opening last-mile connectivity for remote school clusters in Brazil and Indonesia.
- Corporate training channel integration:Enterprise learning stacks are absorbing institutional credential pathways through subscription bundling models.
- Open data protocol mandates:US state-level interoperability standards are forcing vendor cooperation on gradebook and roster data portability.
Industry Challenges
- Certification timeline compression:BIS electromagnetic compatibility testing for imported interactive hardware creates 4-6 month deployment delays in Indian tender processes.
- Cross-platform integration complexity:District IT directors face staff skill gaps in configuring SSO bridges between competing LMS and SIS environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Education Technology and Smart Classrooms Market |
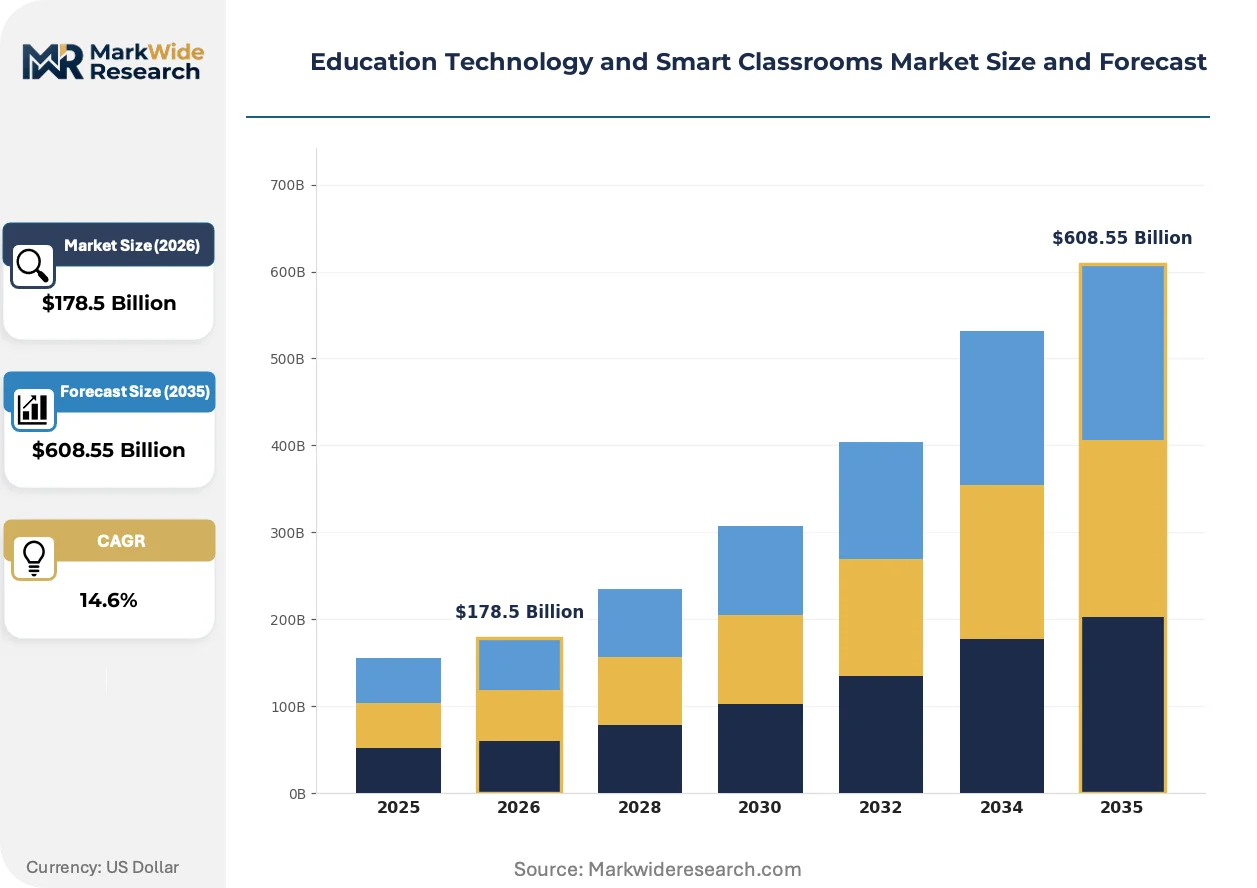
| Market Size in 2026 | $178.5 Billion |
| Market Size in 2035 | $608.55 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Interactive Displays, Learning Management Systems, Cloud Storage Solutions, Smart Projectors Technology: Artificial Intelligence, Augmented Reality, Virtual Reality, Gamification End User: K-12 Schools, Higher Education Institutions, Corporate Training Centers, Educational Nonprofits Deployment: On-Premise, Cloud-Based, Hybrid Models, Mobile Solutions |
| Companies Covered | Chegg, Pear Deck Tutor, Blackboard/Anthology, MasterClass, GoGuardian, Coursera, Course Hero, Udacity, Duolingo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Education Technology and Smart Classrooms Market Strategic Shifts & Innovations
Generative AI content engines and immersive hardware form factors are converging to displace static digital textbook repositories. Regulatory pressure on algorithmic accountability is forcing transparency disclosures that reshape product development priorities.
Multimodal large language models are rewriting how adaptive tutoring systems generate contextually relevant explanations and feedback loops. US K-12 districts with 1:1 device programs are piloting these engines for math and literacy remediation. The technology is compressing content development cycles from months to days while raising new demands for human-in-the-loop oversight protocols.
The EU AI Act's risk classification framework for educational algorithms is mandating conformity assessments and CE marking for adaptive systems deployed in European classrooms. Vendors must now document training data provenance and bias mitigation procedures before market entry. France and Germany's national education ministries are requiring algorithmic impact assessments as standard procurement checklist items.
District purchasing offices are consolidating vendor relationships through multi-year enterprise agreements that bundle hardware, software, and professional development. The traditional discrete RFP for interactive displays is giving way to comprehensive platform contracts. This pattern is most visible in Texas and California where state purchasing cooperatives negotiate volume pricing for member districts.
Education Technology and Smart Classrooms Market Segmentation
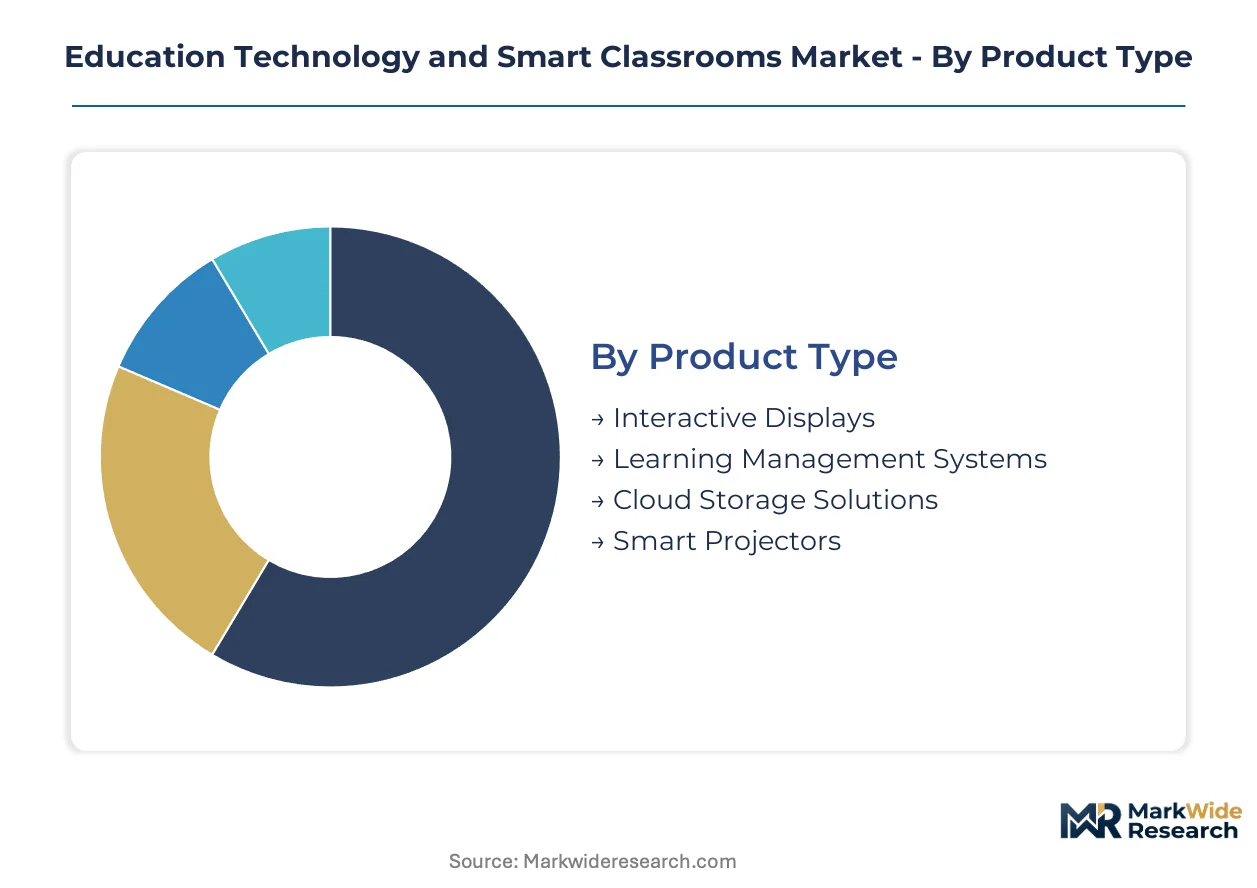
Segmentation in education technology reveals how procurement priorities diverge between institutional buyers seeking infrastructure backbone and those chasing engagement innovation. Hardware-software bundling decisions and compliance requirements reshape competitive positioning across each category boundary.
Product Type:
Volume concentrates in display hardware while premium margin pools form around software platforms that embed recurring revenue.
- Learning Management Systems:These platforms integrate gradebook functionality, content distribution, and roster management into unified administrative dashboards. K-12 districts in Texas and California consolidate multi-year enterprise agreements around LMS backbone procurement. District purchasing cooperatives negotiate volume pricing that displaces discrete RFP patterns for standalone hardware.
- Interactive Displays:Large-format touch panels with embedded computing modules serve as classroom nerve centers requiring 100+ Mbps bandwidth per node. India's tier-1 municipal funding through Delhi, Mumbai, and Bangalore state allocations concentrates smart classroom infrastructure deployment where BIS electromagnetic compatibility certification creates procurement delays.
- Cloud Storage Solutions:Scalable repository architectures support multi-campus districts managing thousands of concurrent users with automatic backup protocols.
- Smart Projectors:Portable projection units with wireless casting capabilities address retrofit budgets in legacy classroom conversions.
Today's leader: Learning Management Systems. Tomorrow's challenger: Cloud Storage Solutions.
Technology:
Application intensity separates experimental pilots from scaled deployment as algorithmic accountability requirements harden.
- Artificial Intelligence:Adaptive pacing engines generate predictive dropout alerts and automated assessment items through multimodal large language models. US K-12 districts with 1:1 device programs pilot these systems for math and literacy remediation while EU AI Act conformity assessments extend European sales cycles. France and Germany's national education ministries mandate algorithmic impact assessments as standard procurement checklist items.
- Gamification:Achievement systems, streak mechanics, and progress visualization sustain user retention metrics for language acquisition and skills training platforms. Corporate training centers absorb institutional credential pathways through subscription bundling models that embed gamified progress tracking.
- Augmented Reality:Overlay interfaces project 3D manipulatives onto physical classroom surfaces for science and geometry visualization.
- Virtual Reality:Immersive headset deployments create simulated environments for vocational training and historical reconstructions.
Artificial Intelligence captures expanding margin pools; Gamification climbs fastest in corporate channel integration.
End User:
Customer type dictates pricing architecture from municipal bulk tenders to per-seat SaaS subscriptions.
- K-12 Schools:District-level procurement offices manage E-Rate subsidy compliance and fiber-to-classroom mandates in underserved rural US markets. Federal connectivity programs accelerate scalable infrastructure priorities over capital-intensive hardware refresh cycles.
- Higher Education Institutions:University IT departments configure SSO bridges between competing LMS and SIS environments while facing staff skill gaps in cross-platform integration.
- Corporate Training Centers:Enterprise learning stacks anchor credential pathways through modular bundling with institutional partnerships.
- Educational Nonprofits:Grant-funded deployments prioritize open data protocol compliance and interoperability standards to resist vendor lock-in.
K-12 Schools dominate procurement volume; Corporate Training Centers gain share fastest in subscription bundling expansion.
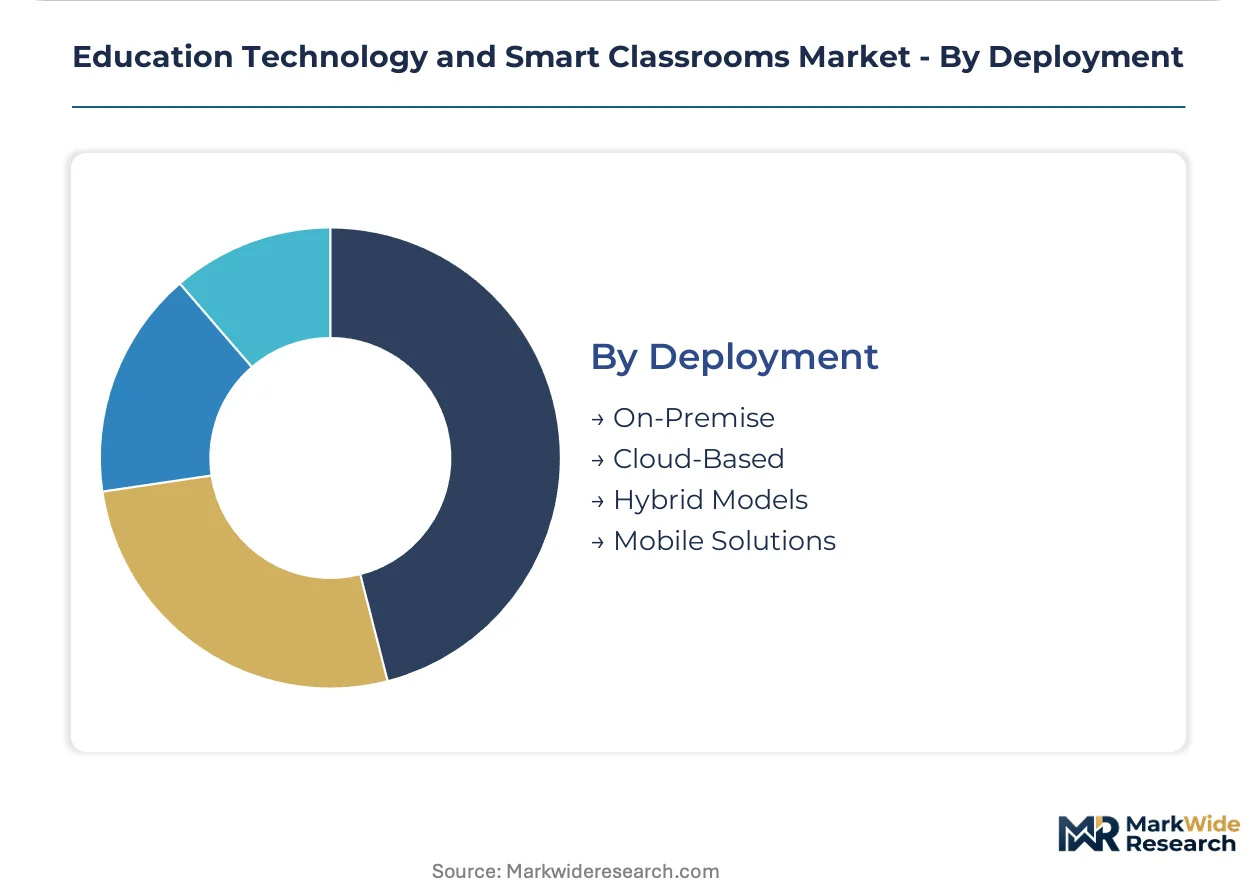
Deployment:
Maturity gradients separate legacy on-premise installations from cloud-native architectures.
- Cloud-Based:Scalable multi-tenant architectures support thousands of concurrent users across distributed campus networks without local server maintenance. India's state governments fund smart classroom infrastructure through central education ministry allocations that prioritize rapid deployment over capital expenditure control.
- Hybrid Models:Split architectures retain sensitive student data on local servers while pushing content delivery to cloud edge nodes. District IT directors verify US Department of Education student data privacy guidance before vendor selection in mixed deployment scenarios.
- On-Premise:Local server installations persist in regions with bandwidth constraints or strict data sovereignty requirements.
- Mobile Solutions:Smartphone-optimized interfaces address bring-your-own-device policies and last-mile connectivity gaps.
Cloud-Based leads new installations; Hybrid Models emerge as compliance complexity intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Education technology and smart classrooms trace their commercial origins to Silicon Valley's 1990s software incubators and Massachusetts Institute of Technology's early digital learning labs. The industry now distributes across distinct national regulatory environments that reshape vendor compliance roadmaps and procurement specifications.
United States
K-12 districts accelerate cloud-based learning platform procurement through E-Rate federal connectivity subsidies. The Department of Education's student data privacy guidance shapes district IT verification requirements before vendor selection. Texas and California purchasing cooperatives negotiate volume pricing for member districts, consolidating multi-year enterprise agreements that bundle hardware, software, and professional development.
India
State governments channel central education ministry allocations toward smart classroom infrastructure in Delhi, Mumbai, and Bangalore. BIS electromagnetic compatibility certification mandates create 4-6 month deployment delays for imported interactive hardware in tender processes. Tier-1 municipal funding concentrates deployment where bandwidth requirements exceed 100 Mbps per classroom node.
Germany
The national education ministry mandates algorithmic impact assessments as standard procurement checklist items for adaptive tutoring systems. EU AI Act conformity assessments and CE marking requirements extend sales cycles for student-facing adaptive platforms. France and Germany jointly enforce documentation burdens for training data provenance and bias mitigation procedures.
United Kingdom
Higher education institutions configure SSO bridges between competing LMS and SIS environments while facing staff skill gaps in cross-platform integration. GDPR algorithmic transparency mandates constrain European student-facing adaptive systems with documentation burdens. University IT departments prioritize interoperability standards to resist vendor lock-in through open data protocols.
China
MIIT standards and GB certification requirements govern interactive display hardware production for domestic and export markets. Yangtze River Delta and Pearl River Delta manufacturing clusters concentrate GPU and memory chip supply dependencies from Taiwan and South Korean foundries. State-directed education informatization policies accelerate provincial-level smart classroom deployment targets.
Education Technology and Smart Classrooms Market Key Industry Players
Premium-margin players sit above commodity-margin players across software platform differentiation, with AI-driven adaptive engines commanding recurring revenue multiples against hardware-integrated suite vendors. The vendor base stratifies between full-stack platform providers, specialized assessment engine developers, and hardware-software bundlers serving district procurement offices. Three archetypes dominate: enterprise SaaS platforms with institutional credential pathways, gamification-driven consumer retention specialists, and compliance-heavy European adaptive system vendors. Competitive moves concentrate on multi-year enterprise agreement consolidation and open data protocol certification to reduce district switching costs.
Within the enterprise SaaS tier, Coursera and Chegg occupy positions anchoring corporate training modules within institutional learning stacks. Duolingo exemplifies the gamification-driven archetype through retention mechanics that sustain engagement metrics. Blackboard/Anthology sits within the compliance-heavy institutional segment where gradebook integration and roster management form procurement backbones. These three company types collectively represent the strategic positioning spectrum that vendors must navigate across divergent national regulatory requirements.
| Leading Market Players |
|---|
| Chegg |
| Pear Deck Tutor |
| Blackboard/Anthology |
| MasterClass |
| GoGuardian |
| Coursera |
| Course Hero |
| Udacity |
| Duolingo |
| Others |
Cost & Logistics Intelligence
Generative AI content engines are compressing content development cycles from months to days while simultaneously shifting cost economics toward cloud compute consumption models and away from perpetual licensing. This production-method transition concentrates margin capture among hyperscaler-backed platform vendors while fragmenting hardware-software bundling decisions across district procurement offices.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates institutional procurement, with premium tiers commanding recurring SaaS multiples for AI-driven adaptive engines and economy tiers competing on per-seat hardware refresh cycles. Price differentiation hinges on certification grade—EU AI Act conformity assessments and BIS electromagnetic compatibility—and volume scale negotiated through state purchasing cooperatives. Cost compression in economy-tier interactive displays is intensifying because GPU and memory chip supply constraints from Taiwan and South Korean foundries squeeze component costs. K-12 district procurement offices exhibit highest price sensitivity, while corporate training centers absorb premium pricing for credential pathway integration.
Supply Chain Analysis
GPU and memory chip supply rests on Taiwan and South Korean semiconductor foundries, with Yangtze River Delta and Pearl River Delta manufacturing clusters assembling finished interactive display hardware for domestic Chinese and export markets. Raw material dependencies span indium tin oxide for touch panels, rare earth elements for display phosphors, and high-bandwidth memory modules for embedded computing. Single-source vulnerability in Taiwan Strait logistics corridors threatens just-in-time delivery schedules for North American district procurement cycles. Distribution runs through OEM-direct enterprise agreements and state purchasing cooperative frameworks that consolidate multi-campus demand into volume tenders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Education Technology and Smart Classrooms Market functions as a stable compounder anchored by federal connectivity subsidy programs that institutionalize recurring procurement cycles across K-12 infrastructure budgets.
For Market Incumbents: Lock in multi-year enterprise agreements with state purchasing cooperatives in Texas and California before open data protocol mandates erode switching costs. Deepen backward integration into cloud infrastructure to capture margin pools shifting from hardware to AI-driven adaptive engines. Counter emerging gamification-driven entrants by embedding professional development bundles that increase replacement friction. For New Entrants and Emerging Players: District IT directors with staff skill gaps in cross-platform integration represent the most penetrable channel partner type for SSO bridge solutions that reduce deployment friction. Target rural broadband convergence zones in Brazil and Indonesia where 5G fixed-wireless and low-earth-orbit satellite hybrids create greenfield infrastructure opportunities. Lead with hybrid deployment architectures that address GDPR algorithmic transparency burdens through local data retention with cloud edge delivery. For Investors and Strategic Acquirers: Valuations sit cheapest among compliance-heavy European adaptive system vendors facing extended sales cycles from EU AI Act documentation burdens. Long-term viability over a five-to-ten year window favors platforms with institutional credential pathway integration rather than pure engagement-retention plays. Watch federal E-Rate program expansion decisions as the inflection signal for rural district procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | SSO bridge development reduces district IT staff skill gaps in cross-platform environments. |
| Strategic Partnership | Enterprise learning stack bundling anchors corporate training modules within institutional pathways. |
| Acquisition of Specialist Firm | Adaptive assessment algorithm targets expand AI-driven personalized pacing engine capabilities. |
| Geographic Expansion | Rural broadband convergence zones in Brazil and Indonesia open last-mile connectivity markets. |
| Product Launch | Multimodal large language model deployment compresses content development cycles for math remediation. |
Research Approach
Bottom-up K-12 district and higher education institution modeling reconciled against top-down cloud infrastructure and hardware shipment tracking forms the analytical core of this study. Primary interviews with district IT directors, state procurement officers, LMS platform engineers, and corporate training center administrators combined with secondary validation against US Department of Education E-Rate disbursement records, EU AI Act regulatory filings, BIS certification databases, and SEC 10-K disclosures from publicly traded edtech vendors. Triangulation between demand-side procurement cycle analysis and supply-side semiconductor foundry output data ensures cross-verified volume and value estimates.
Input-output matrices map deployment model adoption rates against bandwidth infrastructure readiness scores across geographic clusters, with segmentation dimensions spanning product type, technology application intensity, end-user procurement architecture, and deployment maturity gradients. CAGRs derive from logistic diffusion curves fitted to historical procurement velocity data, with AI-driven adaptive system penetration rates and federal connectivity subsidy allocation trajectories serving as key forecast inputs across the projection horizon.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Taiwan Strait logistics disruptions, EU AI Act enforcement intensity variations, and E-Rate program legislative reauthorization cycles. These forecasts reflect documented assumptions about procurement cycle continuity and regulatory implementation timelines. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Educational Technology (EdTech)
AI in K-12 Education Market
Educational Technology (EdTech)
Child Care Software Market
Educational Technology (EdTech)
Digital Education Systems Market
Educational Technology (EdTech)
Global Smart Learning Market
Educational Technology (EdTech)
Global Smart Classroom Market
Educational Technology (EdTech)
Micro Learning Platform Market
Educational Technology (EdTech)
Specific Gravity Bench Apparatus Market
Educational Technology (EdTech)
Student Response System Market
Educational Technology (EdTech)
Augmented and Virtual Reality in Education Market
Educational Technology (EdTech)
Asia-Pacific Digital Education Market
Educational Technology (EdTech)
Virtual Reality in Education Market
Educational Technology (EdTech)
Digital Classroom Market
Educational Technology (EdTech)
Global Adaptive Learning Market
Educational Technology (EdTech)
M-Education Market
Educational Technology (EdTech)
Edtech Market
Educational Technology (EdTech)
Flipped Classroom Market