
 Global Sales Training Market | 2026-2036
Global Sales Training Market Size, Share, and Industry Trends Forecast 2026-2036
Global Sales Training Market Foresight
Enterprise-grade certification tiers is redrawing competitive positioning in sales training. Force Management leverages its Command of the Message methodology to anchor premium engagements with technology firms. Richardson Sales Performance competes through its conceptual selling framework, while Sandler Training dominates the subscription-based coaching segment with recurring revenue models.
Sales training encompasses structured curriculum delivery designed to improve quota attainment, deal velocity, and customer lifetime value through behavioral conditioning and methodology adoption. Programs typically integrate role-play simulations, CRM-embedded coaching triggers, and competency assessments tied to revenue outcomes. Virtual instructor-led delivery is expanding fastest as pharmaceutical and technology firms seek to train distributed field forces without travel overhead, while blended learning captures the deepest margin pools by combining self-paced modules with live coaching reinforcement. E-learning modules serve as the scalable entry tier for FMCG companies managing high-turnover retail sales teams.
The EU AI Act and GDPR constrain how European providers deploy automated coaching analytics and learner data profiling, pushing curriculum designers toward privacy-preserving assessment architectures. In the United States, OSHA guidelines on remote worker ergonomics and SEC disclosure rules around sales performance claims shape how virtual training vendors structure their delivery platforms and outcome marketing. Stakeholders must monitor how generative AI tooling reshapes certification credibility and whether buyers shift procurement toward providers with auditable human-in-the-loop coaching protocols.
Market Dynamics
Generative AI tooling is bifurcating the sales training value chain, compressing content production timelines while elevating human-in-the-loop coaching premiums. The EU AI Act and OSHA guidelines are forcing curriculum architects to redesign delivery architectures around automated assessment governance and remote worker ergonomics compliance.
Growth Catalysts
- Enterprise SaaS captive academies:Technology firms in the United States are building internal certification ecosystems to shorten complex sales cycles and reduce external vendor dependency.
- EU AI Act curriculum redesign:European providers are investing in privacy-preserving assessment architectures to maintain automated coaching deployment under tightened algorithmic governance.
- Pharmaceutical virtual delivery:Distributed field force training without travel overhead is accelerating adoption of virtual instructor-led platforms across life sciences organizations.
Market Restraints
- GDPR data profiling constraints:European learner analytics capabilities face structural limits on behavioral data capture and predictive coaching personalization.
- Blended learning margin pressure:The cost structure of combining self-paced modules with live coaching reinforcement compresses provider profitability at scale.
- High-turnover retail substitution:FMCG companies default to low-touch e-learning modules rather than methodology-intensive programs, capping premium pricing.
Strategic Opportunities
- India PLI scheme alignment:Manufacturing-linked incentive beneficiaries require consultative selling capabilities to penetrate export markets, creating white space for methodology providers.
- ISO 30414 human capital disclosure:Certification-driven procurement is emerging as European buyers prioritize auditable coaching protocols for ESG reporting.
- CRM-embedded trigger convergence:Integration of real-time performance data with just-in-time coaching recommendations opens new channel economics for platform vendors.
Industry Challenges
- Competency assessment standardization delays:Lack of cross-provider credential interoperability complicates enterprise procurement and talent mobility.
- Legacy LMS integration friction:Incumbent learning infrastructure resists API-based coaching trigger deployment, extending implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Sales Training Market |
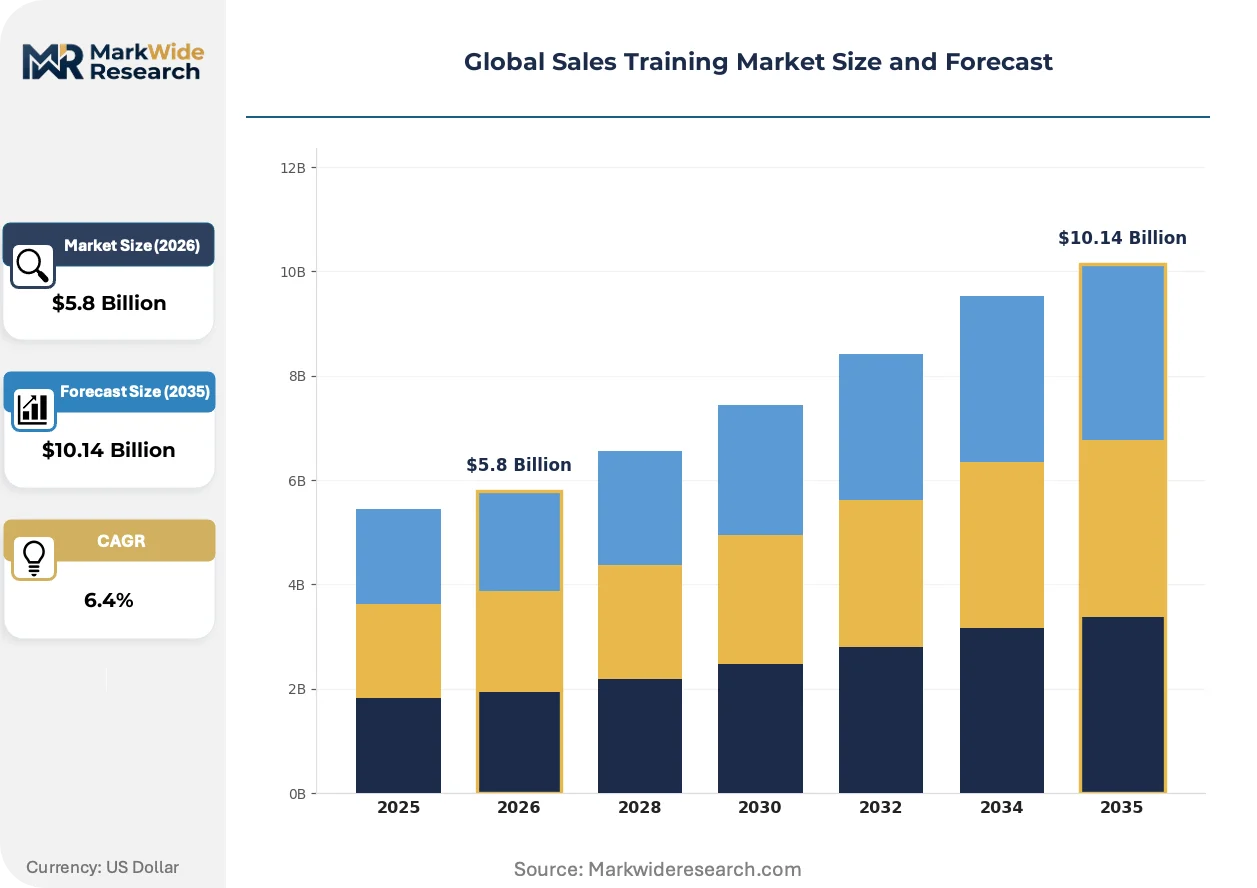
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $10.14 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Training Type: In-Person Workshops, Virtual Instructor-Led, E-Learning Modules, Blended Learning, Coaching Sessions Delivery Channel: Corporate Programs, Online Platforms, Third-Party Providers, Internal Training Teams, Consulting Firms End User Industry: Technology Firms, FMCG Companies, Financial Services, Telecommunications, Pharmaceuticals Skill Focus: Consultative Selling, Negotiation Techniques, Product Knowledge, Relationship Building, Closing Strategies |
| Companies Covered | Force Management, Richardson Sales Performance, pclub.io, Mercuri International, Dale Carnegie, Winning by Design, Sandler Training, Korn Ferry, Factor 8, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Sales Training Market Shifts & Advancements
Adaptive learning engines and regulatory compliance tooling are compressing traditional curriculum development cycles while elevating outcome-verification requirements. Three forces are actively restructuring how sales capabilities are built, certified, and deployed across enterprise environments.
Generative AI content synthesis is bifurcating the market between automated module production and premium human coaching validation. Pharmaceutical and technology firms are adopting AI-assisted role-play scenarios at accelerating pace. This technology is compressing baseline content costs while inflating premiums for certified facilitator oversight.
The EU AI Act algorithmic accountability requirements are mandating explainability standards for automated coaching recommendations. European curriculum designers must now embed audit trails into learner progression logic. Blended learning providers serving Germany and France are restructuring assessment architectures to preserve deployment eligibility.
Buyer procurement patterns are rotating toward outcome-verified engagements with clawback provisions for failed quota attainment. Subscription-based coaching vendors face displacement by performance-guaranteed contracts in United States technology verticals. SaaS procurement teams in California and Texas are piloting certification-efficacy escrow arrangements.
Global Sales Training Market Segmentation
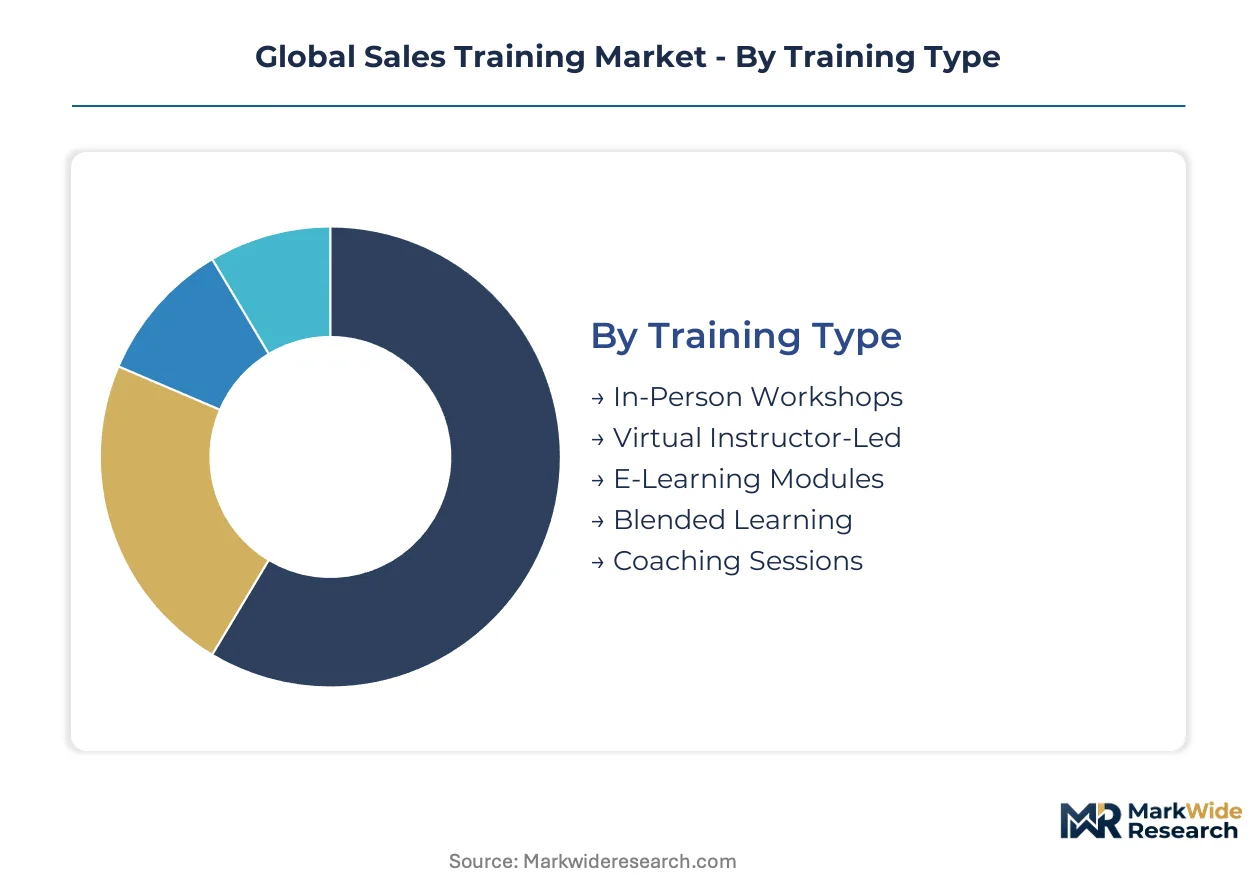
Sales training procurement splits across modality preferences, governance structures, and performance measurement frameworks. Understanding how these dimensions intersect reveals where providers can capture premium pricing versus commoditized volume.
Training Type:
Channel economics vary sharply by modality, with high-touch formats commanding enterprise premiums and scalable formats serving high-turnover segments.
- Virtual Instructor-Led:Synchronous digital delivery with live facilitator oversight enables distributed field force training without travel overhead. Pharmaceutical organizations in the United States and Germany are accelerating adoption to maintain compliance coverage across dispersed territories.
- Blended Learning:Combines self-paced digital modules with scheduled live coaching reinforcement, creating the deepest margin pools through tiered engagement models. Technology firms building captive academies favor this architecture for its scalability with retained human validation.
- In-Person Workshops:Intensive face-to-face immersion for executive sales teams and complex methodology certification.
- E-Learning Modules:On-demand digital content serving as entry-tier scalable delivery for high-turnover retail sales environments.
- Coaching Sessions:One-to-one or small-group sustained development, typically subscription-based with recurring revenue structures.
Blended learning dominates installed base. Virtual instructor-led is where expansion concentrates.
Delivery Channel:
Cost tier stratification separates integrated internal programs from outsourced specialist engagements, with hybrid models emerging at the boundary.
- Corporate Programs:Enterprise-designed curricula aligned to specific quota attainment metrics and proprietary sales methodologies. United States SaaS companies are scaling captive academies to reduce external vendor dependency and shorten complex sales cycles.
- Consulting Firms:Premium engagements embedding methodology certification with organizational change management. Technology firms in California and Texas are piloting performance-guaranteed contracts with clawback provisions for failed quota outcomes.
- Internal Training Teams:Company-employed L&D staff delivering standardized curriculum across regional offices.
- Online Platforms:Self-service digital marketplaces with modular content libraries and automated progress tracking.
- Third-Party Providers:Specialist sales training vendors delivering outsourced program design and facilitation.
Corporate programs capture the highest contract values. Consulting firms are climbing the fastest.
End User Industry:
Application intensity varies by sales cycle complexity, with consultative selling requirements driving methodology investment and transactional volume favoring modular approaches.
- Technology Firms:Enterprise SaaS and infrastructure vendors requiring sophisticated consultative selling capabilities to navigate multi-stakeholder procurement processes. Captive academy construction is concentrating in the United States, with California and Texas clusters leading investment.
- Pharmaceuticals:Life sciences organizations with distributed field forces facing strict regulatory compliance requirements. Virtual instructor-led adoption is accelerating to maintain training coverage without travel overhead.
- Financial Services:Banking and insurance sectors with relationship-intensive sales models and regulatory disclosure constraints.
- FMCG Companies:High-turnover retail sales environments defaulting to low-touch e-learning modules rather than methodology-intensive programs.
- Telecommunications:Subscription-based consumer and enterprise sales with standardized product portfolios and scripted engagement protocols.
Technology firms dominate methodology investment. Pharmaceuticals are expanding most quickly.
Skill Focus:
Maturity gradients separate foundational competencies from advanced specializations, with certification credibility becoming a procurement differentiator.
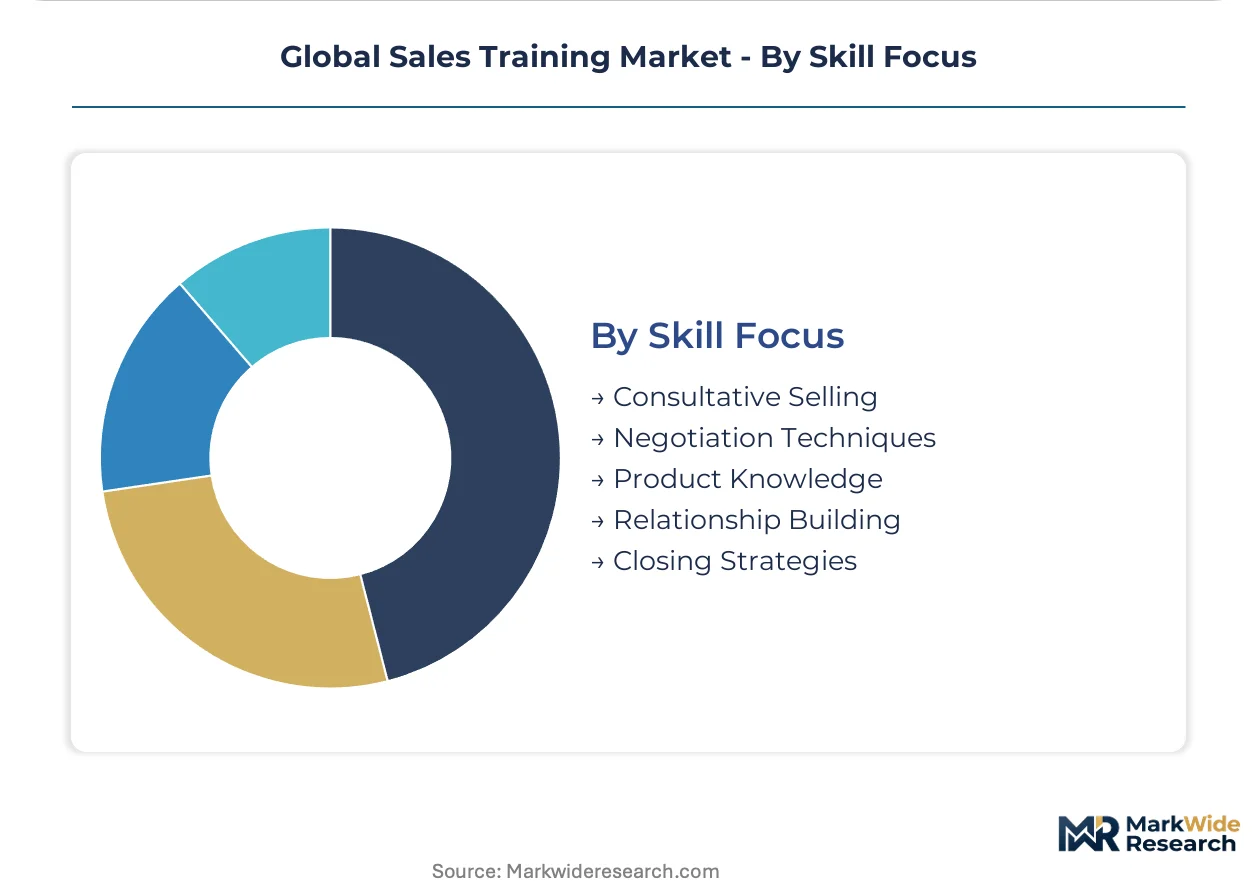
- Consultative Selling:Diagnostic discovery and value articulation methodologies for complex B2B environments. EU AI Act constraints on automated coaching are pushing European providers toward auditable human-in-the-loop validation protocols.
- Closing Strategies:Final-stage negotiation and commitment acceleration techniques tied directly to revenue outcome measurement.
- Negotiation Techniques:Structured frameworks for multi-party deal construction and concession management.
- Relationship Building:Long-term account development and customer lifetime value expansion capabilities.
- Product Knowledge:Technical specification fluency and competitive positioning expertise.
Consultative selling anchors premium pricing. Closing strategies are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in the United States exhibit the lowest price sensitivity, accepting premium methodology certification for complex enterprise sales cycles, while FMCG-driven markets in India and Brazil default to commoditized e-learning modules. European procurement teams occupy the middle ground, prioritizing GDPR-compliant automated coaching architectures over cost minimization. This elasticity gradient shapes where providers can sustain margin versus competing on volume.
United States
Enterprise SaaS vendors in California and Texas are constructing captive sales academies to compress multi-stakeholder procurement cycles and reduce external vendor dependency. OSHA guidelines on remote worker ergonomics constrain how virtual training platforms structure their delivery architectures for distributed workforces. The San Francisco Bay Area and Austin metro clusters anchor the highest concentration of methodology-intensive consultative selling programs.
Germany
Industrial machinery and automotive exporters demand sophisticated negotiation frameworks to navigate complex international procurement processes. The EU AI Act mandates explainability standards for automated coaching recommendations, forcing curriculum designers to embed audit trails into learner progression logic. Bavaria and Baden-Württemberg host the densest concentration of blended learning providers restructuring assessment architectures for algorithmic accountability compliance.
India
Manufacturing-linked incentive beneficiaries under the PLI scheme require consultative selling capabilities to penetrate European and North American export markets. The central bank's priority sector lending guidelines indirectly shape how financial services firms invest in relationship-building sales competencies. Maharashtra and Gujarat industrial corridors are emerging as demand centers for methodology providers serving pharmaceutical and engineering export sectors.
United Kingdom
Financial services and professional services firms prioritize closing strategy certification tied to measurable revenue outcome improvement. The Financial Conduct Authority's conduct rules influence how sales performance claims are marketed and validated by training vendors. London's Square Mile and Canary Wharf clusters concentrate subscription-based coaching demand from banking and insurance relationship managers.
Japan
Precision manufacturing and semiconductor equipment vendors invest heavily in product knowledge fluency for technical specification selling. METI's human capital development initiatives support corporate investment in structured competency assessment frameworks. The Kanto region around Tokyo anchors demand for CRM-embedded coaching trigger integration among enterprise technology distributors.
Global Sales Training Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the sales training value chain, creating a tiered competitive structure rather than consolidated dominance. Premium methodology providers anchor enterprise engagements with certified facilitator networks, while scalable platform vendors capture high-turnover retail segments through automated module delivery. Three archetypes define the competitive set: consultative methodology specialists, subscription coaching operators, and integrated corporate academy builders. Strategic moves concentrate on performance-guaranteed contract structures with quota-attainment clawback provisions, alongside API-based CRM integration partnerships that embed coaching triggers into live sales workflows.
Within the methodology specialist tier, Force Management and Richardson Sales Performance exemplify premium positioning through proprietary certification frameworks. Sandler Training occupies a distinct position in the recurring revenue segment with its subscription-based coaching architecture. These three entities represent the dominant competitive archetypes: consultative selling methodology owners, conceptual selling framework licensors, and scaled coaching subscription operators.
| Leading Market Players |
|---|
| Force Management |
| Richardson Sales Performance |
| pclub.io |
| Mercuri International |
| Dale Carnegie |
| Winning by Design |
| Sandler Training |
| Korn Ferry |
| Factor 8 |
| Others |
Supply & Pricing Matrix
Generative AI content synthesis replacing traditional facilitator-led curriculum development is redrawing supply geography toward algorithmic tooling clusters in the United States and India while compressing pricing economics for baseline modules and inflating premiums for human-validated coaching tiers.
Pricing Analysis
Subscription renewals and extended coaching engagements drive lifetime value capture across the sales training value chain. The dominant pricing structure runs on tiered SaaS licensing with volume-based certification discounts. Price differentiation rests on facilitator certification grade and CRM integration depth. Pricing pressure stems from FMCG buyers defaulting to low-touch e-learning modules rather than methodology-intensive programs. United States technology firms exhibit the lowest price sensitivity, while Indian manufacturing-linked incentive beneficiaries prioritize cost minimization.
Supply Chain Analysis
Facilitator certification bottlenecks in the United States, United Kingdom, and Germany constrain premium tier capacity expansion. Raw material dependencies center on proprietary methodology IP, cloud infrastructure, and qualified coaching talent pools. Supply chain risk concentrates in single-source vulnerability for certified facilitator networks. Distribution runs through direct enterprise sales teams and API-embedded platform partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The sales training market functions as a service-attach opportunity where recurring coaching subscriptions and certification renewal revenue expand faster than one-time curriculum licensing.
For Market Incumbents: Shield methodology IP through accelerated facilitator certification pipeline investment and exclusive CRM integration partnerships. Vertical integration into captive academy construction for United States SaaS clients counters displacement by performance-guaranteed contract structures. ISO 30414-compliant audit trail capabilities anchor retention among European ESG-reporting buyers. For New Entrants and Emerging Players: Differentiate on privacy-preserving assessment architectures compliant with EU AI Act algorithmic accountability requirements. White space concentrates in India PLI scheme-aligned consultative selling programs for pharmaceutical and engineering export sectors. Go-to-market leverage rests on outcome-verified engagements with quota-attainment clawback provisions. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors platform vendors with API-based coaching trigger capabilities and established facilitator networks. Long-term viability hinges on generative AI tooling adoption without eroding human-in-the-loop coaching premiums. Watch procurement rotation toward auditable human-in-the-loop protocols as the inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| CRM-Embedded Coaching Trigger Integration | Real-time performance data convergence with just-in-time recommendations opens new channel economics for platform vendors. |
| Privacy-Preserving Assessment Architecture Development | EU AI Act compliance enables continued automated coaching deployment across German and French enterprise markets. |
| Captive Academy Construction Partnership | United States SaaS clusters in California and Texas seek reduced vendor dependency through internal certification ecosystems. |
| Outcome-Verified Contract Structuring | Performance-guaranteed engagements with clawback provisions displace subscription-based coaching in technology verticals. |
| ISO 30414 Human Capital Disclosure Alignment | Auditable coaching protocols capture procurement preference from European buyers prioritizing ESG reporting compliance. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC filings, EU regulatory databases, and hyperscaler training expenditure disclosures through structured interviews with chief revenue officers, sales enablement directors, L&D procurement leads, and CRM platform integration specialists. Bottom-up demand modeling triangulates against top-down market sizing from certification volume data and vendor revenue disclosures.
Segmentation dimensions modeled include training modality, delivery channel architecture, end-user industry vertical, and skill focus tier across the projection horizon. CAGRs derive from regression analysis of historical certification volume growth against quota attainment outcome correlations. Forecast inputs incorporate EU AI Act implementation timelines and OSHA remote worker guideline adoption curves.
The analysis sits within stated boundaries; outcomes outside sustained enterprise SaaS expansion and regulatory enforcement intensity would require recalibration. Practitioners should keep alternative scenarios live as generative AI tooling adoption rates and algorithmic governance frameworks evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Corporate Training and Talent Development
Asia Pacific Strategic Consulting Services Market
Corporate Training and Talent Development
Corporate Workforce Development Training Market
Corporate Training and Talent Development
Corporate Training Software Market
Corporate Training and Talent Development
Corporate eLearning Market
Corporate Training and Talent Development
Middle East and Africa Management Consulting Services Market
Corporate Training and Talent Development
Corporate Training Market
Corporate Training and Talent Development
Global Outplacement Services Market
Corporate Training and Talent Development
United States HR Professional Service Market
Corporate Training and Talent Development
France Outplacement Services Market
Corporate Training and Talent Development
Asia Pacific HR Professional Services Market
Corporate Training and Talent Development
Asia-Pacific Corporate Training Market
Corporate Training and Talent Development
Europe Corporate Training Market
Corporate Training and Talent Development
IT Training Market
Corporate Training and Talent Development
Corporate Leadership Training Market
Corporate Training and Talent Development
Talent As a Service Market
Corporate Training and Talent Development
Competency-Based Education Spending Market