
 Global Edutainment Centers Market | 2026-2036
Global Edutainment Centers Market Size, Share, and Industry Trends Forecast 2026-2036
Global Edutainment Centers Market Foresight
ISO 9001 quality management certification is redrawing vendor eligibility for institutional procurement contracts in the edutainment sector. KidZania Operations leverages its city-scaled role-play infrastructure to anchor presence across fourteen countries. Science Museum Group sustains R&D intensity through university partnerships that refresh exhibit content. LEGOLAND Discovery Centres dominates the branded indoor format with tight channel control over mall-anchor placements.
Edutainment centers blend structured educational content with entertainment mechanics, typically incorporating interactive digital displays, tactile learning stations, and guided facilitator protocols to achieve curriculum-aligned learning outcomes. The primary commercial purpose is converting discretionary family spending into repeat-visit revenue while satisfying institutional procurement standards for field-trip destinations. Theme parks and interactive exhibits capture the deepest margin pools through premium ticket tiering and ancillary spend per visit. Science museums compete on grant-funded capital cycles that limit pricing flexibility but secure stable visitor flows. Virtual reality lounges represent the fastest-growing facility type as hardware costs decline and school VR budgets expand.
FDA guidelines on child-safe materials govern interactive exhibit surfaces in US venues, while China's GB standards for amusement facility safety dictate structural engineering requirements for climbing and kinetic installations. The EU's GDPR framework constrains biometric data collection from visitor tracking systems, pushing operators toward anonymized analytics. Stakeholders must monitor how AI content personalization tools navigate emerging regulatory boundaries around child data privacy across multiple jurisdictions.
Market Dynamics
Curriculum-mandated experiential learning requirements across multiple education systems are forcing rapid facility buildouts and technology refresh cycles. China's Ministry of Education reforms and similar state-level STEM initiatives in the US and Germany are creating synchronized procurement waves that favor vendors with certified content libraries and scalable deployment capabilities.
Growth Catalysts
- China's GB Standards for Amusement Facility Safety:National curriculum reforms now mandate experiential STEM exposure, creating institutional demand for compliant venues. Tier-one cities are building integrated edutainment complexes at scale.
- Declining VR Hardware Costs:School VR budgets are expanding as equipment prices fall, enabling widespread adoption of immersive learning installations previously limited to premium venues.
- ISO 9001 Quality Management Certification:Institutional procurement contracts increasingly require certified vendors, redrawing eligibility for field-trip destination contracts and favoring established operators.
Market Restraints
- Grant-Funded Capital Cycles:Science museums depend on unstable grant funding that limits pricing flexibility and compresses margin pools compared to commercial operators.
- Biometric Data Collection Constraints:GDPR frameworks across the EU constrain visitor tracking systems, pushing operators toward costlier anonymized analytics infrastructure.
- Content Refresh Intensity:University partnerships required for exhibit R&D create dependency on academic calendars and unpredictable research output timelines.
Strategic Opportunities
- Metropolitan China Expansion:Tier-two and tier-three cities lack integrated edutainment infrastructure, presenting first-mover advantages for scalable format operators.
- AI Content Personalization:Machine learning tools enabling adaptive learning paths are navigating emerging child data privacy boundaries across multiple jurisdictions.
- Mall-Anchor Channel Innovation:Branded indoor formats with tight channel control are securing premium retail real estate previously unavailable to educational venues.
Industry Challenges
- Facilitator Training Bottlenecks:Guided learning protocols require certified staff capable of managing both educational outcomes and safety compliance simultaneously.
- Multi-Jurisdictional Privacy Compliance:Operators must maintain parallel data governance systems for GDPR, China's Personal Information Protection Law, and emerging US state privacy frameworks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Edutainment Centers Market |
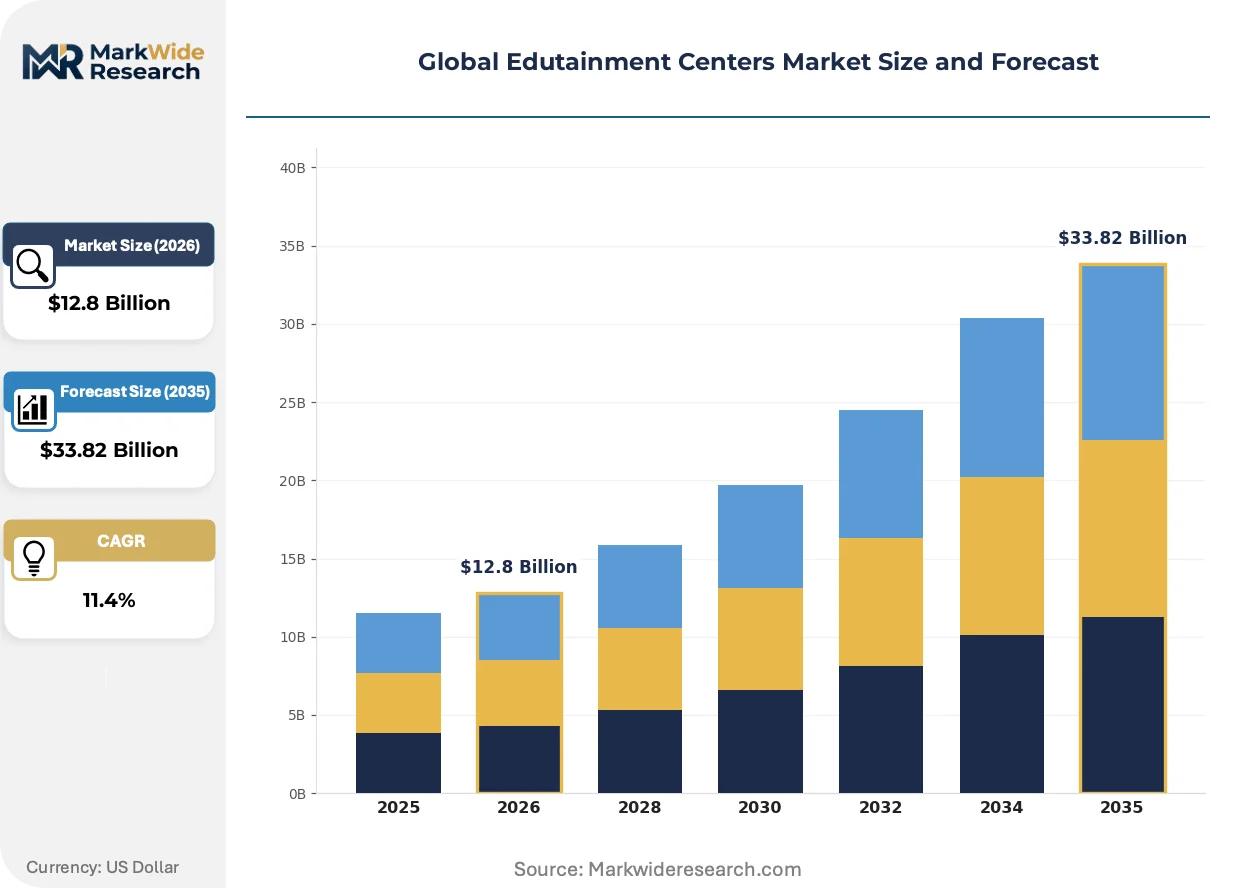
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $33.82 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Facility Type: Theme Parks, Science Museums, Kid Zones, Interactive Exhibits, Virtual Reality Lounges Target Age Group: Preschool, Primary School, Teenagers, Adults, Seniors Revenue Model: Admission Fees, Membership Plans, Event Hosting, Merchandise Sales, Food & Beverage Consumer Segment: Families, Educational Institutions, Corporate Clients, Tourists, Special Needs Groups |
| Companies Covered | Crayola Experience, Science Museum Group, KidZania Operations, Boston Children's Museum, Ontario Science Centre, LEGOLAND Discovery Centres (Merlin Entertainments Group), Discovery Cube Foundation, Exploratorium, Pororo Park, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Edutainment Centers Market Shifts & Advancements
Interactive digital infrastructure is fragmenting traditional exhibit design paradigms. Operators are deploying mixed-reality installations that compress the distinction between physical tactile stations and fully virtual environments, creating new capital allocation tensions between hardware refresh cycles and content development.
Spatial computing hardware is fragmenting the capital deployment models of edutainment venues. School districts with dedicated VR budgets are adopting immersive learning pods faster than museum-grade projection systems. This adoption curve is compressing the payback periods for mixed-reality installations while extending obsolescence risk for static exhibit formats.
The EU's GDPR framework is constraining biometric visitor tracking systems. Operators are redirecting analytics budgets toward anonymized movement-pattern sensors and privacy-preserving computer vision. Science museums in Germany and France are most affected, with several venues delaying AI personalization rollouts pending regulatory clarity on child data processing.
Field-trip procurement is consolidating around outcome-based vendor selection. School administrators in Texas and California are requiring documented learning outcome metrics before contract renewal. This behavioral shift favors operators with embedded assessment tools and disadvantages legacy venues relying on entertainment value alone.
Global Edutainment Centers Market Segmentation
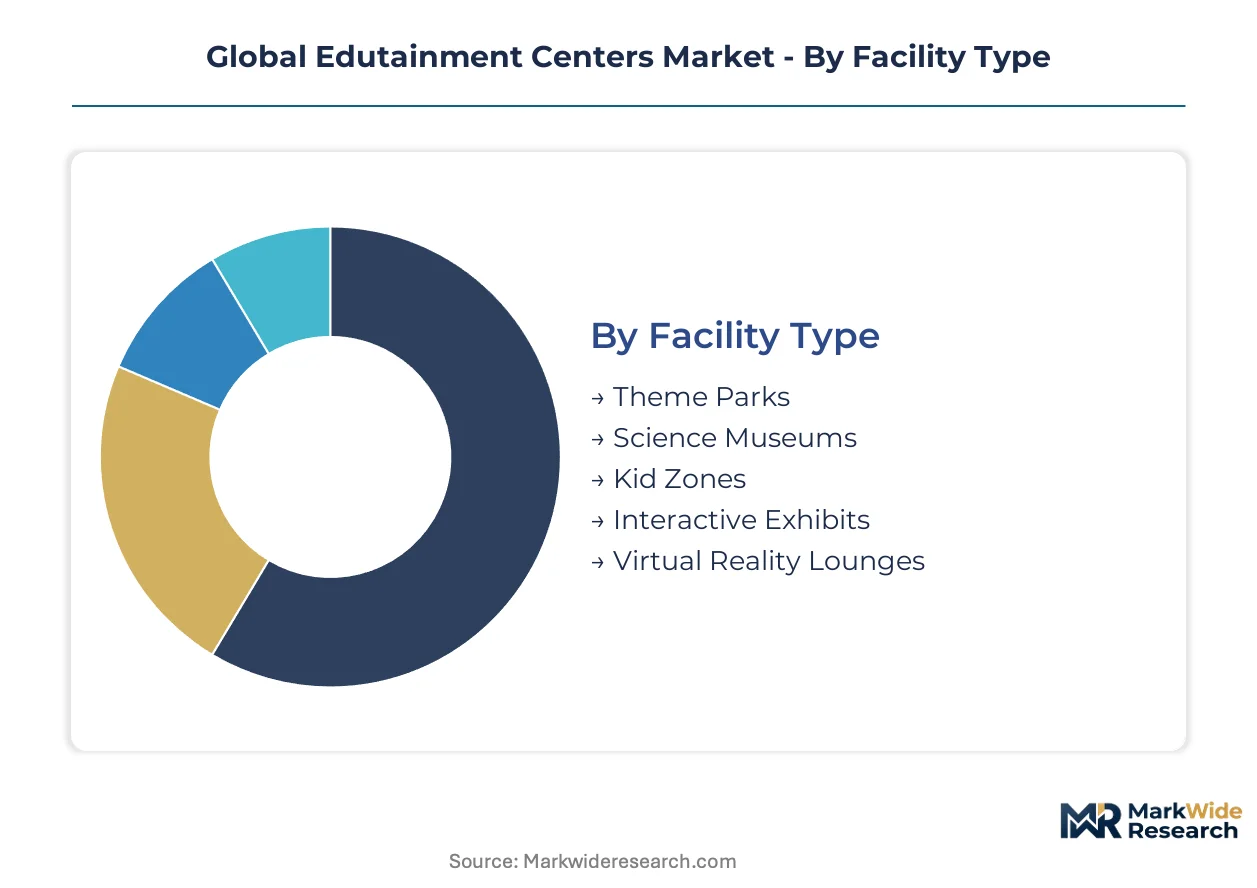
Edutainment center operators configure their physical and digital infrastructure around distinct facility formats, age cohorts, and revenue streams. Procurement patterns from school districts and family spending behavior differ sharply across these boundaries, forcing vendors to specialize rather than generalize.
Facility Type:
Channel mix varies dramatically: theme parks and science museums anchor institutional field-trip contracts, while VR lounges and kid zones dominate mall-based discretionary visits.
- Theme Parks:Large-format outdoor or hybrid venues combining rides with curriculum-aligned educational zones. School districts in Texas and California concentrate procurement here for multi-class excursion capacity.
- Science Museums:Grant-funded institutions with university partnerships refreshing exhibit content. German and French venues face compressed margin pools from GDPR-constrained visitor analytics.
- Kid Zones:Indoor soft-play and role-play formats targeting repeat family visits. Mall-anchor placements in tier-one Chinese cities are expanding fastest.
- Interactive Exhibits:Modular tactile and digital installations deployed across museums, libraries, and retail footprints. Hardware refresh cycles compress payback periods as mixed-reality adoption accelerates.
- Virtual Reality Lounges:Immersive learning pods with declining hardware costs enabling school budget adoption. This segment is climbing the fastest as spatial computing hardware fragments traditional capital deployment models.
By volume, interactive exhibits lead through modular deployment across multiple venue types. By growth pace, virtual reality lounges are ahead.
Target Age Group:
Cost tier stratification drives facility design: premium immersive installations target teenagers and adults, while standardized tactile stations serve preschool and primary cohorts at lower per-capita buildout cost.
- Preschool:Sensory-motor focused installations with strict FDA material safety requirements in US venues. Demand clusters in metropolitan China where dual-income households prioritize early experiential exposure.
- Primary School:Curriculum-mandated STEM alignment creates institutional procurement concentration. China's Ministry of Education reforms synchronize demand waves across tier-one and tier-two cities.
- Teenagers:Mixed-reality and competitive gaming integrations with higher per-visit spend. US school VR budgets are expanding fastest for this cohort.
- Adults:Corporate team-building and date-night positioning with evening-hour revenue optimization. European GDPR constraints limit biometric personalization rollouts.
- Seniors:Cognitive maintenance and intergenerational programming with lower throughput but higher ancillary attachment rates.
Primary school captures the deepest institutional revenue pools. Teenagers show the steepest expansion trajectory as VR hardware costs decline.
Revenue Model:
Application focus determines margin architecture: admission-dependent venues compete on volume, while membership and event models amortize fixed costs across predictable recurring commitments.
- Admission Fees:Single-visit ticketing with premium tiering for peak periods and special exhibitions. Science museums face pricing rigidity from grant-funded operating constraints.
- Membership Plans:Annual subscriptions converting discretionary spend into predictable recurring revenue. KidZania Operations leverages city-scaled infrastructure to maximize renewal rates across fourteen countries.
- Event Hosting:Birthday packages and corporate bookings with high ancillary attachment. Tier-one Chinese cities show strongest volume concentration.
- Merchandise Sales:Branded educational toys and collectibles with LEGOLAND Discovery Centres exercising tight channel control over retail placement.
- Food & Beverage:Captive dining with curriculum-aligned nutritional positioning in some institutional contracts. Margin contribution varies sharply by venue format.
Membership plans anchor the most stable cash flow profiles. Event hosting is gaining share fastest as post-pandemic gathering behavior normalizes.
Consumer Segment:
Customer type dictates sales cycle length and outcome documentation requirements: educational institutions demand certified learning metrics, while family segments prioritize entertainment value and convenience.
- Families:Discretionary weekend and holiday spending with repeat-visit cultivation through membership conversion. Mall-anchor formats in China optimize for this segment.
- Educational Institutions:Field-trip procurement with ISO 9001 certification increasingly mandatory for contract eligibility. Texas and California administrators now require documented learning outcomes.
- Corporate Clients:Team-building and training outsourcing with B2B sales cycles and customized content development. German venues are most advanced in this application.
- Tourists:One-time high-yield visits with location dependency on gateway city positioning. Science Museum Group sustains destination appeal through university partnership content refresh.
- Special Needs Groups:Accessibility-compliant programming with facilitator-intensive protocols and grant-subsidized pricing in some jurisdictions.
Families generate the highest visit frequency. Educational institutions are expanding procurement fastest as curriculum mandates harden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Shanghai-Nanjing high-speed rail corridor underwrites China's dominance in edutainment infrastructure deployment, connecting tier-one and tier-two metropolitan clusters where experiential learning complexes concentrate. This transport backbone enables synchronized procurement waves across provincial education systems.
United States
School district field-trip budgets in Texas and California are expanding toward immersive learning venues with documented outcome metrics. FDA guidelines on child-safe materials govern interactive exhibit surfaces nationwide. Science museums in Greater Boston and the San Francisco Bay Area sustain R&D partnerships with MIT and Stanford to refresh exhibit content.
China
Ministry of Education curriculum reforms mandate experiential STEM exposure across primary and secondary systems. GB standards for amusement facility safety dictate structural engineering requirements for climbing and kinetic installations. Tier-one cities including Shanghai, Beijing, and Shenzhen are building integrated edutainment complexes at scale with state-backed financing.
Germany
State-level STEM initiatives in Bavaria and North Rhine-Westphalia synchronize demand for certified field-trip destinations. GDPR frameworks constrain biometric visitor tracking systems, pushing operators toward anonymized movement-pattern sensors. Science museums in Munich and Cologne leverage university partnerships with TU Munich and RWTH Aachen for exhibit development.
United Kingdom
ISO 9001 quality management certification is redrawing vendor eligibility for institutional procurement contracts across England and Scotland. The Science Museum Group anchors national presence through London, Manchester, and Bradford locations with grant-funded capital cycles. Birmingham and Leeds are emerging as secondary hubs for mall-anchor indoor formats.
Japan
METI industrial policy supports experiential learning infrastructure as part of broader human capital development goals. JIS standards govern safety specifications for interactive installations in public venues. Tokyo and Osaka metropolitan areas concentrate premium immersive learning pods with corporate training and family entertainment positioning.
Global Edutainment Centers Market Competitive Landscape
Listed leaders compete with private specialists across capital access and operational flexibility, creating a tiered structure where scale advantages clash with niche customization capabilities. The vendor base spans multinational entertainment conglomerates, museum consortiums, and regional indoor-format operators. Three archetypes dominate: branded IP licensors with tight channel control, grant-funded institutional networks with university R&D pipelines, and scalable role-play city operators with membership-heavy revenue models. Competitive moves concentrate on mall-anchor real estate securing and outcome-based certification acquisition for school procurement eligibility.
Within the branded indoor format tier, LEGOLAND Discovery Centres and Crayola Experience exemplify IP-driven positioning with tight retail placement discipline. KidZania Operations occupies a distinctive scale-driven position across fourteen countries through city-scaled role-play infrastructure. Science Museum Group represents the institutional archetype, sustaining presence through grant-funded capital cycles and academic partnership networks rather than commercial ticket optimization.
| Leading Market Players |
|---|
| Crayola Experience |
| Science Museum Group |
| KidZania Operations |
| Boston Children's Museum |
| Ontario Science Centre |
| LEGOLAND Discovery Centres (Merlin Entertainments Group) |
| Discovery Cube Foundation |
| Exploratorium |
| Pororo Park |
| Others |
Supply & Pricing Matrix
ISO 9001 certification gates both vendor eligibility and price tiering simultaneously, as institutional procurement contracts in Texas and California now mandate documented learning outcomes alongside certified quality management systems. This regulatory overlay creates dual qualification barriers that compress margin pools for uncertified operators while enabling premium positioning for compliant venues.
Pricing Analysis
Volume-discount tiering structures dominate institutional field-trip contracting, with school districts negotiating sliding scales based on class-size minimums and repeat-visit commitments. Three-tier pricing structure across premium, standard, and economy levels separates venues with embedded assessment tools from legacy entertainment-focused competitors. Cost compression in the standard tier is intensifying because hardware refresh cycles for mixed-reality installations are shortening. Educational institutions exhibit the sharpest price sensitivity, while corporate training clients absorb premium positioning with minimal negotiation.
Supply Chain Analysis
Shenzhen electronics corridors underwrite the hardware procurement chokepoint for immersive learning pods, with component sourcing concentrated in Guangdong province and final assembly distributed across Vietnam and Mexico. Spatial computing hardware draws from Taiwanese semiconductor foundries, Korean display panel manufacturers, and Chinese lithium-ion battery suppliers. Single-source vulnerability runs through specialized motion-tracking sensors with limited qualified vendors. Distribution runs through mall-anchor developers in tier-one Chinese cities and school district procurement cooperatives in the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in tier-two Chinese cities and European mall-anchor formats, as curriculum-mandated experiential learning requirements splinter procurement across jurisdictions with divergent certification standards.
For Market Incumbents: Compound channel control advantages by securing exclusive mall-anchor placements ahead of retail real estate competition, and deepen backward integration into content development to reduce dependency on university partnership timelines. KidZania Operations demonstrates scalable format replication across fourteen countries through city-scaled infrastructure standardization. For New Entrants and Emerging Players: Anchor in tier-two and tier-three Chinese metropolitan clusters where integrated edutainment infrastructure remains underdeveloped, targeting primary school STEM alignment as the most penetrable procurement segment. Mall-anchor indoor formats with tight retail placement discipline offer the clearest go-to-market angle against established theme park incumbents. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across virtual reality lounge deployments as hardware costs decline and school VR budgets expand. Long-term viability favors operators with outcome-based certification and scalable content libraries over grant-dependent museum networks. Acquisition targets should demonstrate ISO 9001 compliance and embedded assessment tool capabilities. The signal to watch is regulatory clarity on child data privacy frameworks across GDPR, China's Personal Information Protection Law, and emerging US state regimes.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Investment | ISO 9001 acquisition unlocks institutional procurement eligibility in Texas and California school districts. |
| Mall-Anchor Expansion | Premium retail real estate in Shanghai and Shenzhen secures captive family discretionary spend. |
| Content Refresh Partnership | University R&D pipelines sustain exhibit relevance against hardware obsolescence cycles. |
| Privacy-Preserving Analytics | Anonymized movement-pattern sensors navigate GDPR constraints in German and French venues. |
| Membership Model Conversion | Annual subscriptions amortize fixed costs across predictable recurring commitments. |
Research Methodology
Cross-validation between facility operator interviews and school district procurement data anchors the qualitative findings. Primary fieldwork engaged edutainment center operations directors, district field-trip coordinators, mall development leasing managers, and exhibit technology procurement leads. Secondary sources included Ministry of Education curriculum reform documents, GB standards filings, FDA material safety guidance, and institutional membership databases. Bottom-up venue capacity modeling and top-down education budget allocation analysis provided triangulation.
Sensitivity analysis tested hardware cost decline trajectories and curriculum mandate implementation timelines across the projection horizon. Segmentation dimensions incorporated facility format, target age cohort, revenue model architecture, and regional regulatory cluster. CAGRs derived from facility buildout pipelines, institutional procurement wave synchronization, and discretionary family spending elasticity. VR hardware adoption curves and school technology budget expansion rates served as industry-specific forecast inputs.
Decision-makers should treat outputs as directional under stable curriculum reform implementation and hardware cost decline assumptions; material deviation would warrant model refresh. Forecasts reflect documented procurement patterns and capital deployment timelines. Practitioners should keep alternative scenarios live as child data privacy regulatory boundaries evolve across multiple jurisdictions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Educational Technology (EdTech)
Virtual Reality in Education Market
Educational Technology (EdTech)
Artificial Intelligence (AI) in Education Market
Educational Technology (EdTech)
Education Apps Market
Educational Technology (EdTech)
Digital Education Systems Market
Educational Technology (EdTech)
Asia-Pacific Digital Education Market
Educational Technology (EdTech)
Global AI in Education Market
Educational Technology (EdTech)
Global Social Learning Platforms Market
Educational Technology (EdTech)
Global Smart Learning Market
Educational Technology (EdTech)
Student Response System Market
Educational Technology (EdTech)
Education Technology Market
Educational Technology (EdTech)
Higher Education Learning Systems Market
Educational Technology (EdTech)
Global IoT in Education Market
Educational Technology (EdTech)
Global Micro-Learning Market
Educational Technology (EdTech)
Global Adaptive Learning Market
Educational Technology (EdTech)
AI in K-12 Education Market
Educational Technology (EdTech)
Digital Badges Market