
 Education Technology Market | 2026-2036
Education Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Education Technology Market Intelligence
Subscription-based software licensing is consolidating as the dominant revenue architecture in education technology, replacing perpetual licenses with recurring models that embed continuous content refresh and analytics services. Coursera leverages its university partnerships to sustain premium credentialing programs across professional domains. Duolingo anchors consumer language acquisition through freemium mechanics and gamified retention algorithms. Byju's competes aggressively in emerging markets through localized curriculum adaptation and direct-to-student mobile distribution.
Education technology encompasses hardware, software, and service platforms designed to deliver, administer, or assess learning experiences through digital interfaces, typically requiring interoperability standards such as LTI 1.3 Advantage and xAPI for learning record exchange across systems. Its primary commercial purpose centers on improving knowledge transfer efficiency while generating measurable outcome data for institutional buyers and individual learners. Learning Management Systems occupy the most mature margin pool as enterprise and university procurement standardizes around incumbent platforms. Adaptive Learning represents the fastest-expanding segment as AI-driven personalization engines reduce instructor-to-student ratios in scale environments. Virtual Classrooms retain structural importance in hybrid delivery models but face margin compression from commoditized video infrastructure.
The EU AI Act and GDPR impose algorithmic transparency and minor data protection obligations on adaptive learning platforms operating across member states, while India's BIS standards for educational software interoperability shape procurement criteria for government-funded digital classrooms. India's CDSCO and TRAI frameworks indirectly influence EdTech through data localization expectations and telecommunications quality standards that determine platform accessibility. Stakeholders must monitor how divergent regulatory timelines across jurisdictions will fragment compliance costs and create first-mover advantages for platforms architected with modular privacy and explainability features.
Market Dynamics
Adaptive learning engines powered by generative AI are compressing instructor-to-student ratios across scale environments, forcing incumbent Learning Management System providers to rebuild personalization stacks or cede margin to specialized AI-native platforms.
Growth Catalysts
- EU AI Act transparency mandates:Algorithmic explainability requirements accelerate procurement of modular privacy-compliant platforms across German and French higher education systems.
- Corporate reskilling mandates:Enterprise training departments expand budgets for credentialing programs as workforce automation intensifies skills gaps in data analytics and cloud architecture.
- India's national digital education missions:Government-funded classroom deployments in tier-two and tier-three cities create concentrated demand for localized curriculum software and low-bandwidth delivery infrastructure.
Market Restraints
- Cloud infrastructure cost volatility:GPU compute pricing for AI model training constrains adaptive learning platform margins, particularly for mid-scale providers without hyperscaler volume commitments.
- Data localization requirements:India's TRAI frameworks and EU GDPR sovereignty rules fragment platform architecture, forcing redundant infrastructure deployment that dilutes R&D investment.
- Interoperability standard gaps:Incomplete LTI 1.3 Advantage adoption across legacy university systems limits seamless learning record exchange, trapping institutions in incumbent vendor relationships.
Strategic Opportunities
- Vocational credentialing in Brazil:ANVISA-aligned healthcare training modules and technical certification programs remain underpenetrated by adaptive learning platforms serving Portuguese-speaking markets.
- AI-human tutoring convergence:Large language model integration with synchronous video coaching creates premium service tiers for executive education and specialized professional domains.
- Direct-to-student mobile channels:Bypassing institutional procurement cycles through app store distribution captures lifetime value in emerging markets where school-level purchasing authority remains fragmented.
Industry Challenges
- Instructional design talent scarcity:Platforms competing for learning scientists capable of structuring pedagogical content for AI personalization engines face wage inflation and recruitment bottlenecks.
- Legacy LMS integration complexity:Enterprise and university procurement teams demand seamless data migration from decades-old on-premise systems, extending sales cycles and implementation costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Education Technology Market |
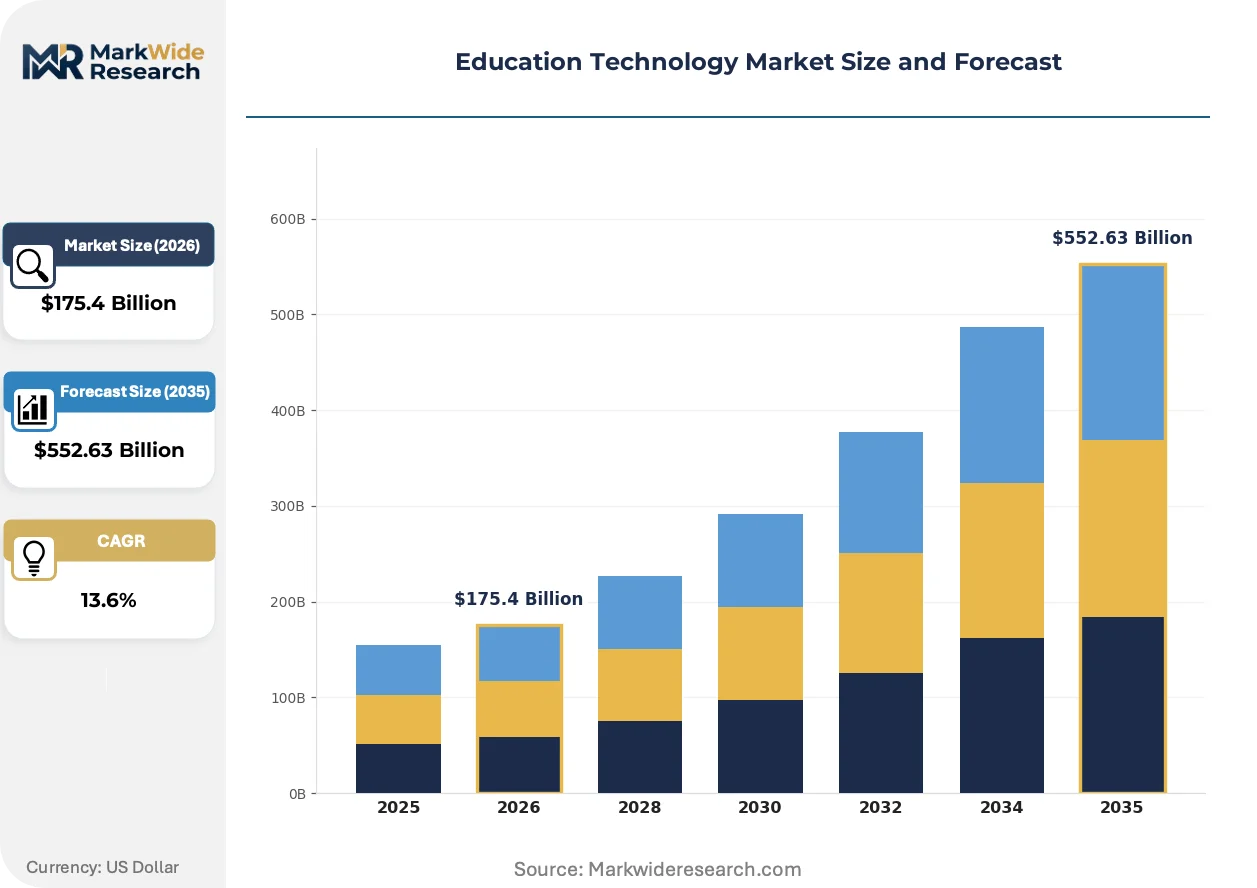
| Market Size in 2026 | $175.4 Billion |
| Market Size in 2035 | $552.63 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Learning Management Systems, Virtual Classrooms, Assessment Tools, Adaptive Learning End User: K-12 Institutions, Higher Education, Corporate Training, EdTech Startups Deployment: Cloud-Based, On-Premises, Hybrid Solutions, Mobile Applications Customer Type: Students, Educators, Administrators, Parents |
| Companies Covered | Udemy, MasterClass, Byju's, Udacity, GoStudent, Coursera, Outschool, Chegg, Duolingo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Education Technology Market Strategic Shifts & Innovations
Generative AI is fragmenting the traditional content production pipeline, enabling real-time curriculum adaptation while compressing the timeline from concept to deployed learning module from quarters to weeks.
Micro-credentialing infrastructure is modularizing around stackable digital badges that verify discrete competencies rather than degree completion. Community colleges and workforce development boards in Texas and Ohio are piloting these frameworks for healthcare and manufacturing certifications. This architecture is compressing the dominance of multi-year degree programs by enabling employer-verified skill signaling at granular proficiency levels.
GDPR and the EU AI Act are mandating algorithmic impact assessments for adaptive learning platforms operating across member states. France's CNIL and Germany's state data protection authorities are enforcing documentation requirements that extend procurement timelines by four to eight months. Vocational training platforms serving cross-border corporate clients are responding by establishing separate EU data residency instances with dedicated compliance engineering teams.
Enterprise training procurement is consolidating around subscription bundles that embed continuous content refresh, analytics dashboards, and human coaching touchpoints. Chief Learning Officers at Fortune 500 manufacturers are displacing standalone course libraries with integrated talent development platforms. This pattern is most visible in automotive and aerospace supply chains where reskilling velocity directly correlates with production line retooling cycles.
Education Technology Market Segmentation
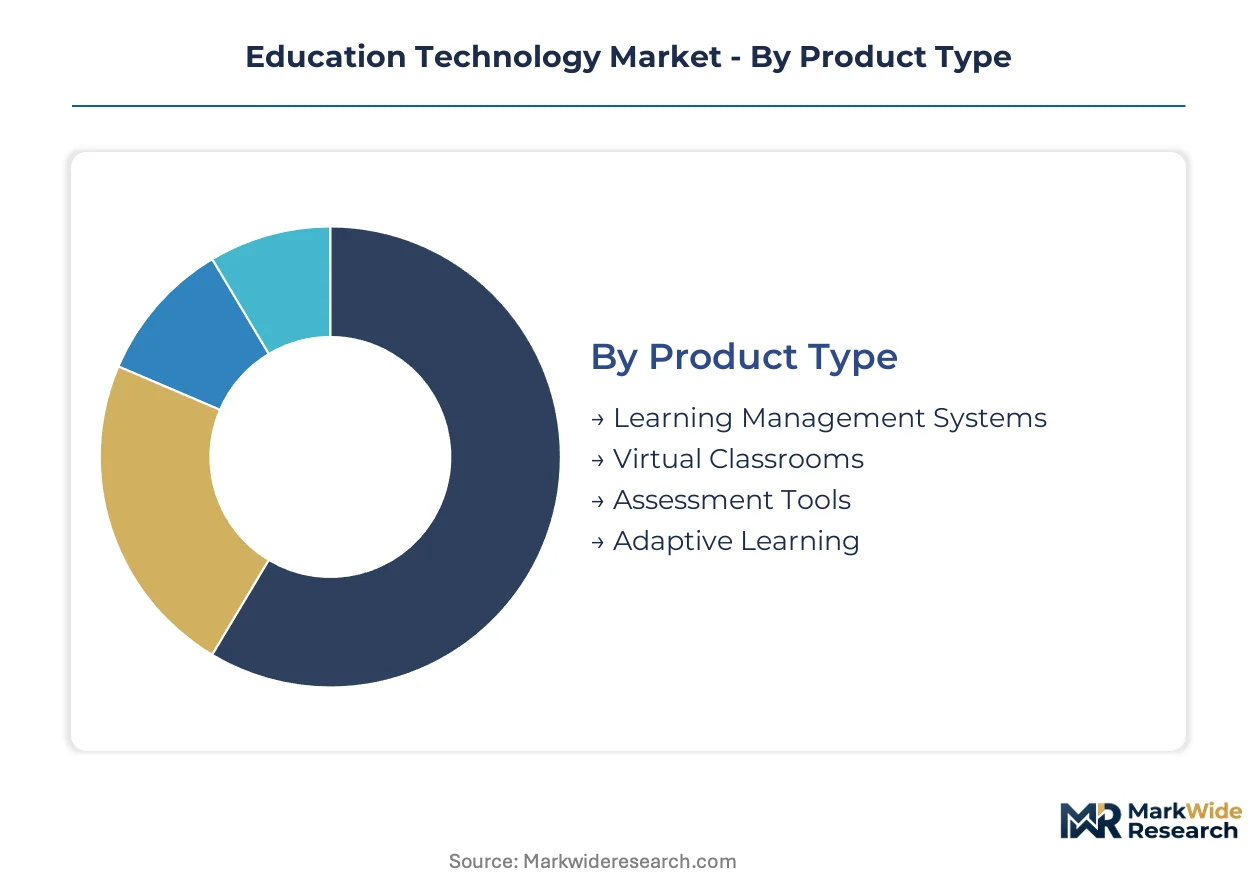
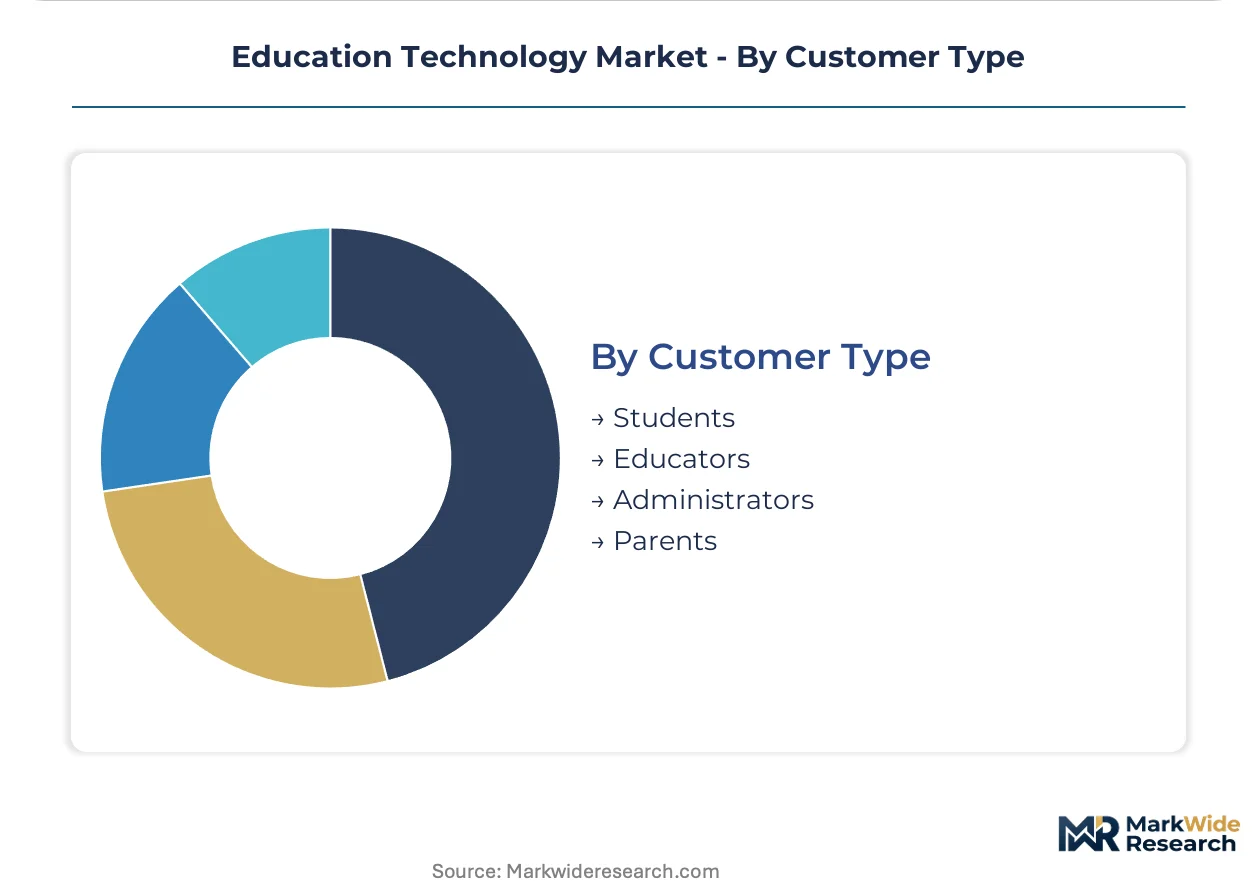
Segmentation in education technology reveals how procurement authority, technical infrastructure, and learner demographics fragment purchasing decisions across incompatible buying centers. Understanding these divisions enables platform providers to align product architecture with the specific integration requirements and budget cycles of each buyer type.
Product Type:
Standalone platforms dominate procurement in institutional settings where interoperability mandates force modular purchasing, while embedded systems penetrate corporate environments seeking unified talent stacks.
- Learning Management Systems:Enterprise-grade platforms orchestrate course delivery, grading workflows, and learning record storage through SCORM and xAPI protocols. University procurement in Germany and France standardizes around these systems as EU AI Act transparency requirements elevate auditability demands.
- Adaptive Learning:AI-driven personalization engines adjust content difficulty and pacing in real-time based on learner performance telemetry. Corporate training departments in automotive and aerospace supply chains deploy these systems to compress reskilling timelines during production line retooling cycles.
- Virtual Classrooms:Synchronous video infrastructure with breakout rooms and collaborative whiteboards supports hybrid delivery models. Margin compression from commoditized streaming technology limits differentiation.
- Assessment Tools:Proctoring software and automated grading systems verify competency attainment. India's national digital education missions drive procurement for standardized testing at scale.
Learning Management Systems lead volumes today; Adaptive Learning is gaining share fastest.
End User:
Procurement complexity escalates with organizational scale, from fragmented individual purchases to centralized enterprise contracts with multi-year implementation horizons.
- Corporate Training:Enterprise learning and development departments purchase credentialing programs and skills analytics platforms. Fortune 500 manufacturers displace standalone libraries with integrated talent development systems.
- K-12 Institutions:School districts and government education ministries procure curriculum-aligned software with parental oversight features. India's tier-two and tier-three cities concentrate demand for localized content and low-bandwidth delivery.
- Higher Education:Universities and community colleges license platforms supporting degree completion and micro-credentialing. Texas and Ohio workforce development boards pilot stackable digital badge frameworks.
- EdTech Startups:Venture-backed challengers build direct-to-student channels bypassing institutional procurement cycles. Mobile-first distribution captures lifetime value in emerging markets with fragmented school-level purchasing authority.
Corporate Training commands premium pricing; K-12 Institutions show the steepest expansion trajectory in emerging markets.
Deployment:
Architecture choices reflect data sovereignty constraints, with regulatory fragmentation forcing redundant infrastructure investment across jurisdictions.
- Cloud-Based:Scalable SaaS platforms enable continuous content refresh and analytics services through subscription licensing. GDPR and EU AI Act mandates require separate EU data residency instances with dedicated compliance engineering.
- Mobile Applications:Native iOS and Android distribution reaches learners without institutional device provisioning. Direct-to-student channels in India leverage low-cost smartphone penetration.
- Hybrid Solutions:Mixed cloud-edge architectures balance real-time personalization with offline functionality for bandwidth-constrained environments.
- On-Premises:Self-hosted installations persist in defense and healthcare training contexts with classified or protected health information requirements.
Cloud-Based deployments dominate new procurement; Mobile Applications are climbing the fastest in emerging market consumer segments.
Customer Type:
User role determines feature prioritization, from administrative compliance dashboards to learner-facing gamification mechanics.
- Students:Individual learners drive freemium conversion through achievement systems and social progression mechanics. Retention algorithms optimize daily engagement streaks in language acquisition contexts.
- Administrators:Procurement officers and compliance officers demand audit trails, learning outcome dashboards, and vendor risk assessments. EU AI Act documentation requirements extend their evaluation timelines.
- Educators:Instructors require content authoring tools and real-time learner progress visibility. Instructional design talent scarcity constrains platform adoption velocity.
- Parents:Guardians purchase supplementary tutoring and monitoring tools in markets with high private education expenditure. Usage analytics and screen time controls feature prominently.
Students generate the highest transaction volumes; Administrators control the largest contract values.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's tier-two and tier-three cities accelerate EdTech adoption through national digital education missions, while the United States concentrates corporate training procurement around Fortune 500 reskilling mandates. Regulatory fragmentation between GDPR-driven European requirements and India's data localization frameworks reshapes platform architecture across jurisdictions.
United States
Corporate learning and development departments drive demand for credentialing platforms as workforce automation intensifies skills gaps. OSHA and state-level professional licensing boards influence training content standards for healthcare and technical certifications. Austin and Seattle tech corridors host adaptive learning startups building AI personalization engines for enterprise clients.
India
National digital education missions and low-cost internet penetration accelerate platform adoption across secondary cities. TRAI frameworks and BIS standards for educational software interoperability shape government-funded classroom procurement criteria. Bangalore and Hyderabad clusters concentrate engineering talent developing localized curriculum software for vernacular language markets.
Germany
Dual vocational training systems create institutional demand for stackable credentialing platforms aligned with manufacturing reskilling cycles. GDPR and EU AI Act transparency mandates extend procurement timelines for adaptive learning systems across state education ministries. Munich and Stuttgart industrial regions pilot AI-human tutoring convergence for automotive supply chain technical certifications.
Brazil
ANVISA-aligned healthcare training modules and technical certification programs attract adaptive learning platform investment in Portuguese-speaking markets. National education ministry digitization initiatives expand procurement for low-bandwidth delivery infrastructure in northeastern states. São Paulo anchors corporate training demand from financial services and industrial conglomerates.
United Kingdom
University procurement standardizes around auditability-compliant platforms as GDPR documentation requirements elevate vendor assessment rigor. Apprenticeship levy reforms redirect employer training budgets toward modular digital credentialing systems. London and Manchester EdTech clusters focus on executive education platforms serving financial services reskilling mandates.
Education Technology Market Key Industry Players
Top-tier vendors anchor enterprise and university procurement through established interoperability standards, while mid-scale challengers compete on AI-native personalization stacks and direct-to-student mobile distribution. Market structure stratifies across three archetypes: incumbent learning management systems, adaptive learning specialists, and direct-to-consumer mobile platforms. Dominant competitive moves include strategic university partnerships for credentialing authority and geographic expansion into emerging markets with localized curriculum adaptation.
Within the direct-to-consumer tier, Duolingo and Byju's exemplify contrasting geographic strategies—Duolingo anchors freemium language acquisition through gamified retention algorithms, while Byju's concentrates on emerging market penetration through mobile-first distribution. Coursera occupies a position bridging institutional and individual demand through university partnership networks. Udemy and Udacity represent the skills-based credentialing archetype targeting corporate reskilling budgets.
| Leading Market Players |
|---|
| Udemy |
| MasterClass |
| Byju's |
| Udacity |
| GoStudent |
| Coursera |
| Outschool |
| Chegg |
| Duolingo |
| Others |
Cost & Logistics Intelligence
GPU compute costs for AI model training cascade through adaptive learning platform pricing tiers, with hyperscaler volume commitments separating enterprise-grade personalization engines from margin-constrained mid-scale providers serving K-12 institutions and vocational training programs.
Pricing Analysis
Capacity additions in India's engineering talent pools are reshaping price floors for curriculum localization services, compressing development premiums previously commanded by Western platforms. Three-tier pricing structure across premium, standard, and economy levels stratifies by integration depth and compliance certification, with EU AI Act-aligned transparency documentation driving premium tier valuations. Pricing pressure stems from commoditized video infrastructure eroding virtual classroom margins. Corporate training departments show lowest price sensitivity due to reskilling mandate urgency, while individual learners in emerging markets exhibit highest elasticity.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan and South Korea for advanced GPU silicon feeding adaptive learning personalization engines, with NVIDIA's datacenter architecture dominating training workloads for generative AI content adaptation. Cloud infrastructure draws from hyperscaler regions in the United States, Ireland, and Singapore, while instructional design talent concentrates in Bangalore, Berlin, and Austin. Supply chain risk centers on data localization requirements fragmenting platform architecture across GDPR and India's TRAI frameworks. Distribution runs through direct-to-student mobile channels and institutional procurement cycles with diverging sales velocity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The education technology market compounds steadily as workforce automation perpetuates corporate reskilling mandates across manufacturing and services sectors.
For Market Incumbents: Lock in interoperability dominance by accelerating LTI 1.3 Advantage certification across legacy university systems before AI-native challengers displace margin through superior personalization stacks. Deepen backward integration into proprietary assessment content libraries to defend against specialized credentialing platforms eroding enterprise training market share. For New Entrants and Emerging Players: Direct-to-student mobile channels in India's tier-two and tier-three cities offer the most penetrable white-space, bypassing fragmented school-level purchasing authority through app store distribution. Target vocational credentialing in Portuguese-speaking markets where ANVISA-aligned healthcare training modules remain underpenetrated by adaptive learning platforms. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-scale adaptive learning providers face GPU compute pricing constraints without hyperscaler volume commitments, creating acquisition opportunities for platforms with modular compliance architecture spanning EU and Indian regulatory frameworks. Target acquisition archetypes include AI-native personalization engines with vernacular language capabilities and established university partnership networks. The signal to watch is enterprise procurement consolidation around integrated talent development platforms displacing standalone course libraries.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Embedding adaptive learning engines within incumbent LMS architectures captures procurement cycles at German and French universities. |
| Geographic Expansion | Localized curriculum adaptation for India's vernacular language markets leverages national digital education mission funding. |
| Strategic Partnership | University credentialing authority partnerships enable premium pricing for professional domain certifications in data analytics and cloud architecture. |
| Acquisition of Specialist Firm | Instructional design talent scarcity makes learning science teams with AI personalization expertise high-priority targets. |
| Product Launch | AI-human tutoring convergence products capture executive education budgets through synchronous video coaching premiums. |
Research Approach
Multiple input streams — primary interviews with chief learning officers and university procurement directors, secondary validation through SEC filings and hyperscaler capex disclosures, and regulatory documentation from EU AI Act implementation guidance — were reconciled through bottom-up and top-down triangulation. EdTech platform engineering leads, instructional design directors, and government education ministry officials provided operational perspective on deployment constraints and procurement criteria.
Historical enrollment trajectories and panel-based growth assumptions were cross-referenced across the analysis window, with segmentation modeling spanning deployment architecture, end-user organization scale, curriculum vertical, and regional regulatory cluster. CAGRs were derived from enrollment velocity projections and average revenue per learner trends, incorporating AI adoption curves and interoperability standard penetration as industry-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for generative AI integration would alter the outlook if regulatory timelines for algorithmic transparency diverge significantly from current EU and Indian implementation schedules. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Educational Technology (EdTech)
Micro Learning Platform Market
Educational Technology (EdTech)
AI in K-12 Education Market
Educational Technology (EdTech)
Artificial Intelligence (AI) in Education Market
Educational Technology (EdTech)
Global Smart Learning Market
Educational Technology (EdTech)
Higher Education Technology Market
Educational Technology (EdTech)
Edutainment Market
Educational Technology (EdTech)
M-Education Market
Educational Technology (EdTech)
Virtual Schools Market
Educational Technology (EdTech)
Digital Badges Market
Educational Technology (EdTech)
ASEAN Smart Education and Learning Market
Educational Technology (EdTech)
VR Education Market
Educational Technology (EdTech)
Child Care Software Market
Educational Technology (EdTech)
E Learning Virtual Reality Market
Educational Technology (EdTech)
Edtech Market
Educational Technology (EdTech)
Global AI in Education Market
Educational Technology (EdTech)
Education Apps Market