
 Education Security Market | 2026-2036
Education Security Market Size, Share, and Industry Trends Forecast 2026-2036
Education Security Market Foresight
Higher education is pivoting toward converged physical-cybersecurity platforms as campus environments digitize. Cisco Systems Inc. leverages its networking heritage to dominate unified threat management for university networks. Honeywell International Inc. anchors its position through building automation systems that integrate access control with environmental monitoring. Motorola Solutions Inc. specializes in mission-critical communications infrastructure for large campus deployments.
Education security encompasses the integrated systems, protocols, and technologies designed to protect students, staff, and institutional assets across physical and digital domains, typically incorporating video analytics with sub-100ms latency, encrypted access credentials, and AI-driven threat detection operating at 99.5% accuracy thresholds for perimeter breach identification. The solution dimension shows cybersecurity outpacing physical security in revenue growth as ransomware attacks against school districts escalate, while access control remains the margin pool where proprietary biometric integration commands premium pricing. Deployment patterns reveal cloud-based architectures displacing on-premise legacy systems fastest among online education providers, though hybrid configurations sustain dominance in K-12 due to bandwidth constraints and data sovereignty requirements.
The US Department of Education collaborates with CISA to mandate K-12 cyber hygiene standards, while the EU AI Act constrains facial recognition deployment in European campuses, forcing vendors to redesign biometric offerings for compliance. India's BIS certification requirements for electronic safety equipment create non-tariff barriers that favor domestic assembly partnerships. Stakeholders must monitor evolving data localization mandates and their cascading impact on cloud service architecture decisions.
Market Dynamics
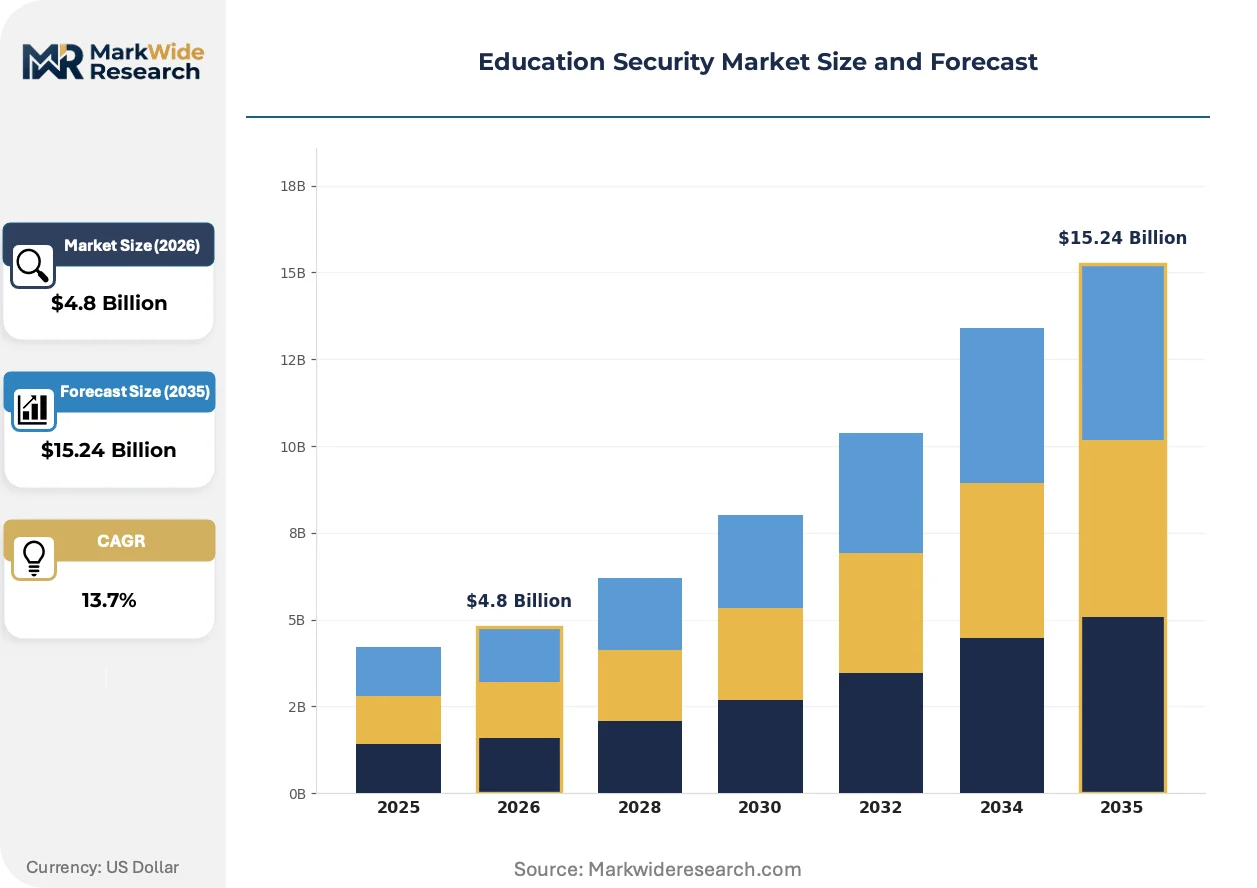
The convergence of physical and cybersecurity systems is compressing procurement cycles as K-12 districts and universities consolidate vendor relationships under unified threat management frameworks. This structural shift favors integrated platform providers over point-solution specialists, reshaping competitive positioning across both hardware and software layers.
Growth Catalysts
- US Department of Education mandates:Federal grant programs for school hardening accelerate capital expenditure timelines for integrated security platforms across public K-12 systems.
- Cloud migration among online education providers:India's Ministry of Education digital infrastructure guidelines drive preference for cloud-based deployment models over legacy on-premise architectures.
- Ransomware escalation against school districts:Cyberattack frequency forces cybersecurity budget allocation to outpace physical security spending in district technology planning cycles.
Market Restraints
- Semiconductor supply concentration:Video analytics hardware remains exposed to Taiwan-based foundry capacity constraints, creating 16-24 week lead time volatility for edge computing devices.
- EU AI Act facial recognition constraints:European campus deployments face redesign requirements for biometric access systems, extending product development timelines by 8-14 months.
- Hybrid configuration lock-in:K-12 bandwidth limitations and data sovereignty requirements perpetuate on-premise server maintenance costs that cloud-native competitors avoid.
Strategic Opportunities
- India BIS certification pathways:Domestic assembly partnerships for electronic safety equipment unlock public procurement access under preferential market access policies.
- Converged physical-cyber platforms:Higher education institutions seek unified dashboards integrating access control, network monitoring, and environmental sensors through single-pane management.
- AI-driven perimeter analytics:Sub-100ms latency threat detection with 99.5% accuracy thresholds creates premium pricing power for vendors with proprietary edge inference architectures.
Industry Challenges
- Interoperability with legacy access control:Wiegand protocol systems in aging K-12 facilities resist integration with modern encrypted credential platforms without full infrastructure replacement.
- Cyber-physical security talent scarcity:District IT departments lack personnel trained in both network defense and building automation system hardening, forcing reliance on outsourced managed security services.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Education Security Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $15.24 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution: Physical Security, Cybersecurity, Access Control, Surveillance Systems End User: K-12 Institutions, Higher Education, Online Education Providers, Training Centers Component: Hardware, Software, Services, Network Infrastructure Deployment: On-Premise, Cloud-Based, Hybrid, Managed Services |
| Companies Covered | Cisco Systems Inc., Honeywell International Inc., Fortinet Inc., Motorola Solutions Inc., Palo Alto Networks Inc., Hangzhou Hikvision Digital Technology Co., Ltd., IBM Corporation, Microsoft, Axis Communications AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Education Security Market Shifts & Advancements
Edge computing architectures are redistributing processing load from centralized data centers to campus perimeter devices, enabling real-time threat response without cloud latency dependencies. This shift is compressing the traditional security operations center model toward distributed autonomous decision-making.
Computer vision with on-device inference is expanding into perimeter monitoring applications, processing video feeds locally to eliminate bandwidth costs and privacy risks of cloud transmission. University campuses in the United States deploy these systems for automated intrusion detection across research facility boundaries. The technology is compressing response times from minutes to seconds while reducing recurring cloud service expenditures.
The EU AI Act's prohibition on remote biometric identification in publicly accessible spaces forces European campus security vendors to redesign facial recognition offerings around opt-in credentialing models. German universities now deploy palm-vein authentication as a compliant alternative for laboratory access control. This regulatory friction is fragmenting product roadmaps between privacy-sensitive European markets and surveillance-permissive jurisdictions.
K-12 technology directors increasingly unbundle security system procurement from facilities maintenance contracts, creating direct vendor relationships that bypass traditional mechanical-electrical contractor channels. Texas and Florida school districts lead this disintermediation, issuing separate RFPs for hardware specification and installation services. The pattern compresses margin capture for integrators while expanding addressable market access for specialized security technology vendors.
Education Security Market Segmentation
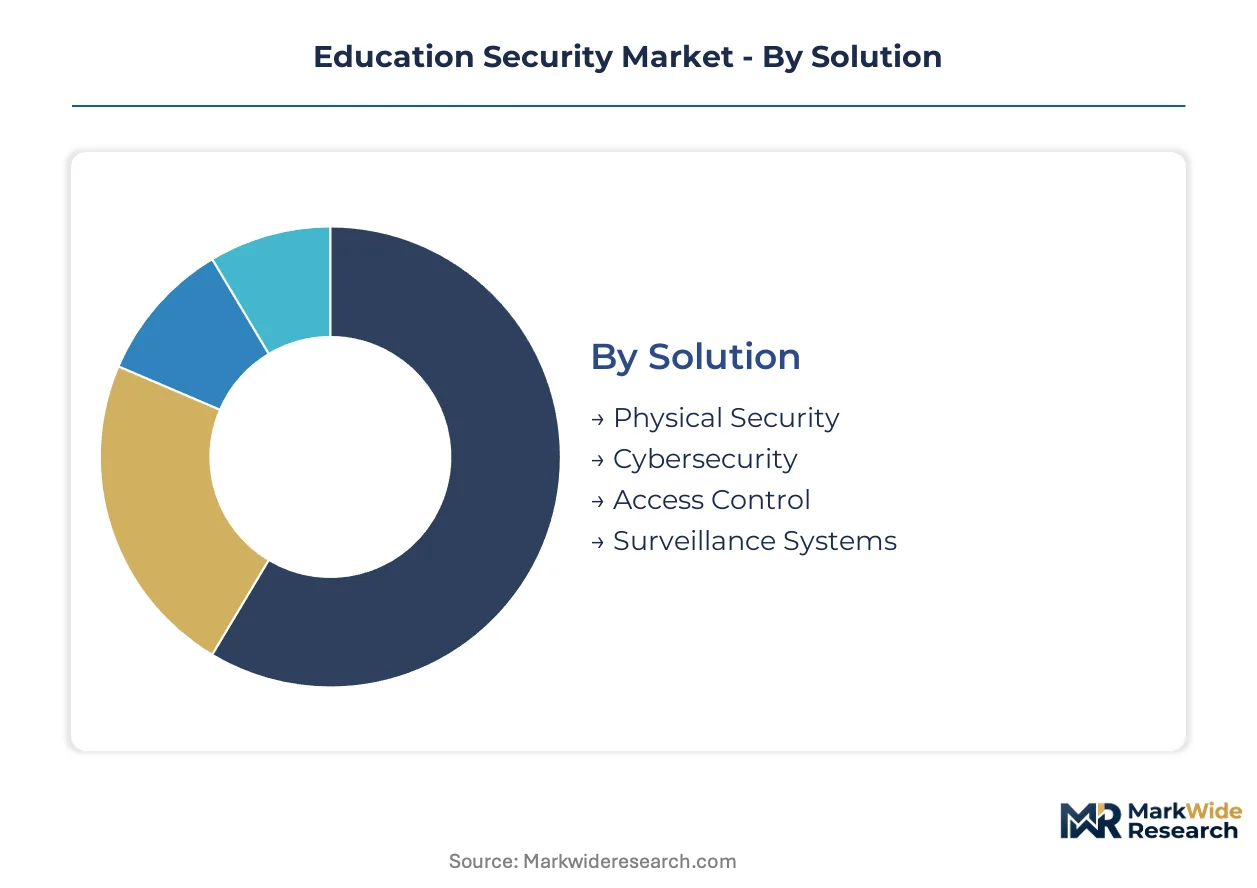
Education security procurement fragments across distinct operational layers, with integration depth determining whether solutions operate as standalone installations or embedded within unified platforms. Vendors must map segment interdependencies to capture cross-selling opportunities across hardware, software, and service bundles.
Solution:
Standalone point solutions dominate legacy installations, while embedded systems within converged platforms accelerate replacement cycles among institutions consolidating vendor relationships.
- Cybersecurity:Encompasses network defense, endpoint protection, and cloud security posture management for institutional data assets. K-12 districts in the United States allocate accelerated budgets here following CISA cyber hygiene mandates, displacing physical security spending in technology planning cycles.
- Access Control:Biometric and encrypted credential systems governing entry to facilities, laboratories, and restricted zones. Premium pricing persists where proprietary biometric integration—particularly palm-vein and facial recognition variants—commands compliance-driven redesigns under EU AI Act constraints.
- Physical Security:Perimeter barriers, intrusion detection, and environmental monitoring for campus infrastructure. Aging Wiegand protocol installations in United States public schools resist modernization without full infrastructure replacement.
- Surveillance Systems:Video analytics with edge inference capabilities for real-time threat detection. Sub-100ms latency requirements favor vendors with proprietary on-device processing architectures.
Cybersecurity leads volumes today; access control is gaining share fastest through biometric premiumization.
End User:
Procurement authority varies sharply across institution types, with public funding cycles and private capital availability creating divergent sales motion requirements.
- K-12 Institutions:Public school districts and private primary-secondary systems with federally influenced capital expenditure timelines. United States Department of Education grant programs compress decision windows for integrated platform adoption.
- Higher Education:Universities and colleges pursuing converged physical-cybersecurity dashboards. Large research campuses in Germany and the United States deploy mission-critical communications infrastructure with single-pane management requirements.
- Online Education Providers:Virtual learning platforms with cloud-native security architectures. India's Ministry of Education digital infrastructure guidelines accelerate migration from on-premise legacy systems.
- Training Centers:Vocational and corporate education facilities with standardized, replicable security specifications across distributed locations.
K-12 institutions anchor current procurement volumes; online education providers are expanding most quickly through cloud migration mandates.
Component:
Margin concentration shifts upstream toward software and services as hardware commoditization intensifies across camera and sensor categories.
- Software:AI-driven analytics platforms, identity management systems, and unified threat management consoles. License models are displacing perpetual sales as cloud-based deployment preferences harden among Indian online education providers.
- Services:Managed security operations, system integration, and compliance consulting. Cyber-physical talent scarcity across United States district IT departments forces reliance on outsourced monitoring and hardening expertise.
- Hardware:Cameras, biometric readers, edge computing devices, and environmental sensors. Taiwan-based foundry capacity constraints create 16-24 week lead time volatility for video analytics equipment.
- Network Infrastructure:Cabling, switches, and wireless access points enabling security system connectivity. Hybrid configurations perpetuate on-premise server maintenance costs that bandwidth-limited K-12 districts cannot escape.
Hardware dominates installed base value; software is climbing the fastest through recurring revenue conversion.
Deployment:
Architecture choices reflect data sovereignty requirements, bandwidth constraints, and institutional risk tolerance for third-party cloud custody.
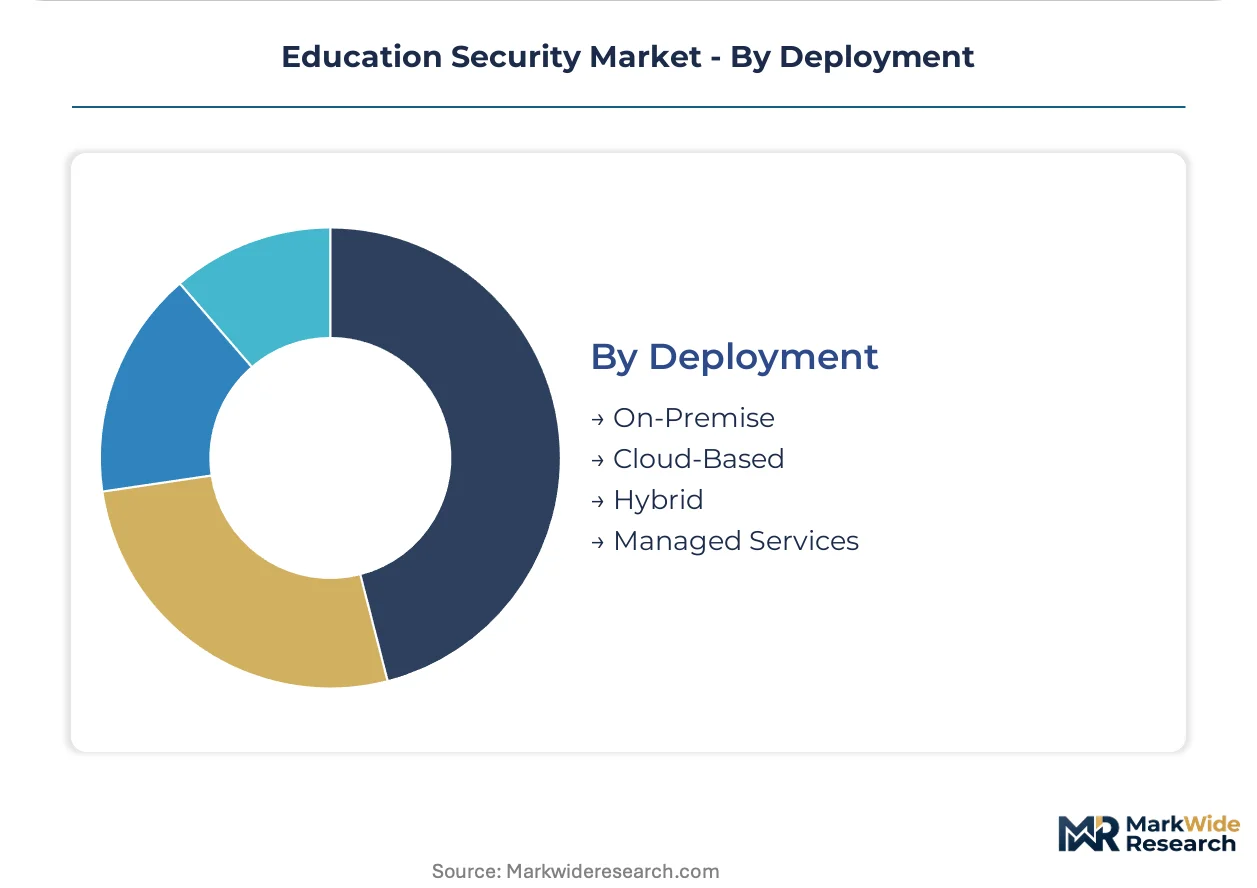
- Hybrid:Combines on-premise processing for latency-sensitive functions with cloud analytics for archival and advanced AI workloads. Dominates K-12 due to FERPA compliance requirements and unreliable rural bandwidth in United States districts.
- Cloud-Based:Fully outsourced security operations with browser-accessible management interfaces. India's Ministry of Education guidelines explicitly favor this model for online education providers seeking rapid scalability.
- On-Premise:Legacy architectures with localized data storage and processing. Declining share except where air-gapped networks serve research facilities with classified or export-controlled information.
- Managed Services:Third-party operation of security infrastructure under long-term service agreements. Expanding among United States community colleges lacking internal cyber-physical expertise.
Hybrid configurations lead installed volumes today; cloud-based deployment is gaining share fastest through vendor platform consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage between privacy-sensitive and surveillance-permissive jurisdictions is reshaping vendor product roadmaps and assembly location decisions. Compliance cost differentials drive domestic partnership strategies in markets with preferential procurement policies.
United States
Federal grant programs for school hardening and CISA cyber hygiene mandates accelerate K-12 capital expenditure timelines. The Department of Education collaborates with CISA to mandate district-level security standards. Texas and Florida school districts lead procurement disintermediation, issuing separate RFPs for hardware and installation services.
Germany
Research universities deploy mission-critical communications infrastructure with single-pane management requirements for large campus environments. The EU AI Act forces redesign of biometric access systems around opt-in credentialing models. German universities in Bavaria now deploy palm-vein authentication as a compliant alternative for laboratory access control.
India
Cloud migration among online education providers accelerates following Ministry of Education digital infrastructure guidelines. BIS certification requirements for electronic safety equipment create non-tariff barriers favoring domestic assembly partnerships. Karnataka-based system integrators capture public procurement access under preferential market access policies.
United Kingdom
Higher education institutions pursue converged physical-cybersecurity dashboards as campus environments digitize. GDPR constraints limit cloud transmission of video analytics data, favoring edge computing architectures. London and Southeast research facilities deploy air-gapped networks for export-controlled information protection.
Japan
University networks prioritize encrypted credential platforms with sub-100ms latency specifications for perimeter monitoring. METI standards influence building automation system integration requirements. Kanto region campuses anchor demand for unified threat management consoles with local language support.
Education Security Market Competitive Landscape
Platform consolidation dominates the current landscape as K-12 districts and universities compress procurement cycles under unified threat management frameworks. The vendor base separates into three tiers: integrated platform providers with networking heritage, building automation specialists with environmental monitoring capabilities, and mission-critical communications fabricators. Strategic archetypes include converged physical-cybersecurity platform builders, edge inference architecture developers, and managed security service operators. M&A activity and strategic partnerships represent the dominant competitive moves as point-solution specialists face margin compression.
Among networking-heritage platform builders, Cisco Systems Inc. and Palo Alto Networks Inc. occupy positions exemplifying the shift toward unified threat management for institutional networks. Honeywell International Inc. represents the building automation archetype, while Motorola Solutions Inc. anchors mission-critical communications specialization for large campus deployments. Microsoft and IBM Corporation sit within the cloud-native security services tier, serving online education providers with browser-accessible management interfaces. Hangzhou Hikvision Digital Technology Co., Ltd. and Axis Communications AB exemplify video analytics hardware specialists adapting to edge computing migration patterns.
| Leading Market Players |
|---|
| Cisco Systems Inc. |
| Honeywell International Inc. |
| Fortinet Inc. |
| Motorola Solutions Inc. |
| Palo Alto Networks Inc. |
| Hangzhou Hikvision Digital Technology Co., Ltd. |
| IBM Corporation |
| Microsoft |
| Axis Communications AB |
| Others |
Supply & Pricing Matrix
K-12 procurement disintermediation in Texas and Florida districts strips integrator margins and forces direct vendor relationships that compress pricing power for hardware specialists while elevating software license premiums. This buyer-side restructuring compels suppliers to absorb installation service costs or surrender margin to cloud-native competitors with leaner cost structures.
Pricing Analysis
Distributor margin capture has collapsed as Texas and Florida school districts issue separate RFPs for hardware specification and installation services. Three-tier pricing structure across premium, standard, and economy levels stratifies around biometric certification tiers, with EU AI Act-compliant palm-vein systems commanding substantial premiums over facial recognition alternatives. Cost compression in edge computing hardware intensifies because Taiwan foundry capacity constraints limit supply elasticity. Online education providers in India exhibit highest price sensitivity due to Ministry of Education procurement guidelines favoring cloud-native SaaS tiers.
Supply Chain Analysis
Reverse-logistics flows for Wiegand protocol retrofit kits and aging access control infrastructure create secondary market refurbishment channels that extend equipment lifecycles and dampen replacement demand. Manufacturing concentrates in Taiwan for video analytics semiconductors, China for camera assembly, and Mexico for North American distribution fulfillment. Component sourcing draws from South Korean memory suppliers, Japanese sensor fabricators, and German precision optics specialists. Single-source vulnerability around Taiwan-based foundry capacity exposes 16-24 week lead time volatility. Distribution runs through authorized security integrators, direct OEM relationships, and cloud service marketplaces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Education security has entered a late-cycle quality phase where procurement consolidation favors integrated platform providers over point-solution vendors. District technology directors now mandate unified threat management specifications that privilege vendors with converged physical-cyber capabilities.
For Market Incumbents: Anticipate margin compression from cloud-native entrants by deepening backward integration into edge computing hardware and securing BIS certification partnerships for Indian market access. Defensive consolidation through managed security service acquisitions addresses cyber-physical talent scarcity across United States district IT departments. Priority investment in sub-100ms latency inference architectures preserves premium pricing power.
For New Entrants and Emerging Players: System integrators in Karnataka, India represent the most penetrable channel partner type for cloud-based deployment models under Ministry of Education guidelines. White-space targets include online education providers migrating from on-premise legacy systems and United States community colleges lacking internal security operations expertise. Go-to-market execution should emphasize browser-accessible unified dashboards with rapid deployment timelines.
For Investors and Strategic Acquirers: Asymmetric upside sits with managed security service operators possessing cyber-physical hybrid expertise across K-12 and higher education verticals. Long-term viability hinges on recurring revenue conversion and platform consolidation tailwinds. Acquisition target archetype: regional managed security providers with established CISA compliance consulting capabilities. Monitor federal grant program allocation shifts as early inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Converged physical-cyber dashboards capture procurement consolidation among universities seeking single-pane management. |
| Domestic Assembly Partnership | BIS certification pathways unlock Indian public procurement access under preferential market access policies. |
| Edge Inference Architecture Development | Sub-100ms latency threat detection commands premium pricing for perimeter analytics with on-device processing. |
| Managed Security Service Expansion | Cyber-physical talent scarcity forces United States districts toward outsourced monitoring and system hardening expertise. |
| Compliance-Driven Biometric Redesign | EU AI Act constraints require palm-vein alternatives that fragment product roadmaps between privacy-sensitive and surveillance-permissive jurisdictions. |
Research Methodology
Direct dialogue with K-12 technology directors, university CIOs, security system integrators, and Ministry of Education procurement officials grounded qualitative findings in operational reality. Secondary validation drew from CISA cyber hygiene guidelines, Department of Education grant program disclosures, EU AI Act regulatory texts, and BIS certification databases. Bottom-up demand modeling triangulated against top-down market sizing across solution, end-user, component, and deployment dimensions.
Segmented outputs across cybersecurity, access control, physical security, and surveillance systems enabled granular demand decomposition over the projection horizon. Modeled dimensions included K-12 versus higher education procurement authority, hybrid versus cloud-native deployment preferences, and biometric versus encrypted credential authentication tiers. CAGRs derived from historical replacement cycle analysis, federal funding trajectory assessment, and ransomware incident frequency correlation with budget allocation shifts.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to semiconductor supply normalization, EU AI Act enforcement interpretation, and federal grant program continuity. Practitioners should monitor Taiwan foundry capacity utilization, BIS certification processing timelines, and CISA mandate expansion scope for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Educational Technology (EdTech)
VR Education Market
Educational Technology (EdTech)
Micro Learning Platform Market
Educational Technology (EdTech)
Global Adaptive Learning Market
Educational Technology (EdTech)
E Learning Virtual Reality Market
Educational Technology (EdTech)
Education Apps Market
Educational Technology (EdTech)
Global Smart Learning Market
Educational Technology (EdTech)
Virtual Schools Market
Educational Technology (EdTech)
Education Technology and Smart Classrooms Market
Educational Technology (EdTech)
Global IoT in Education Market
Educational Technology (EdTech)
Asia Big Data Analytics in Education Market
Educational Technology (EdTech)
Edtech and Smart Classroom Market
Educational Technology (EdTech)
Global Micro-Learning Market
Educational Technology (EdTech)
Smart Education System Market
Educational Technology (EdTech)
Augmented and Virtual Reality in Education Market
Educational Technology (EdTech)
Digital Badges Market
Educational Technology (EdTech)
M-Education Market