
 North America Digital Education Market | 2026-2036
North America Digital Education Market Size, Share, and Industry Trends Forecast 2026-2036
North America Digital Education Market Analytics
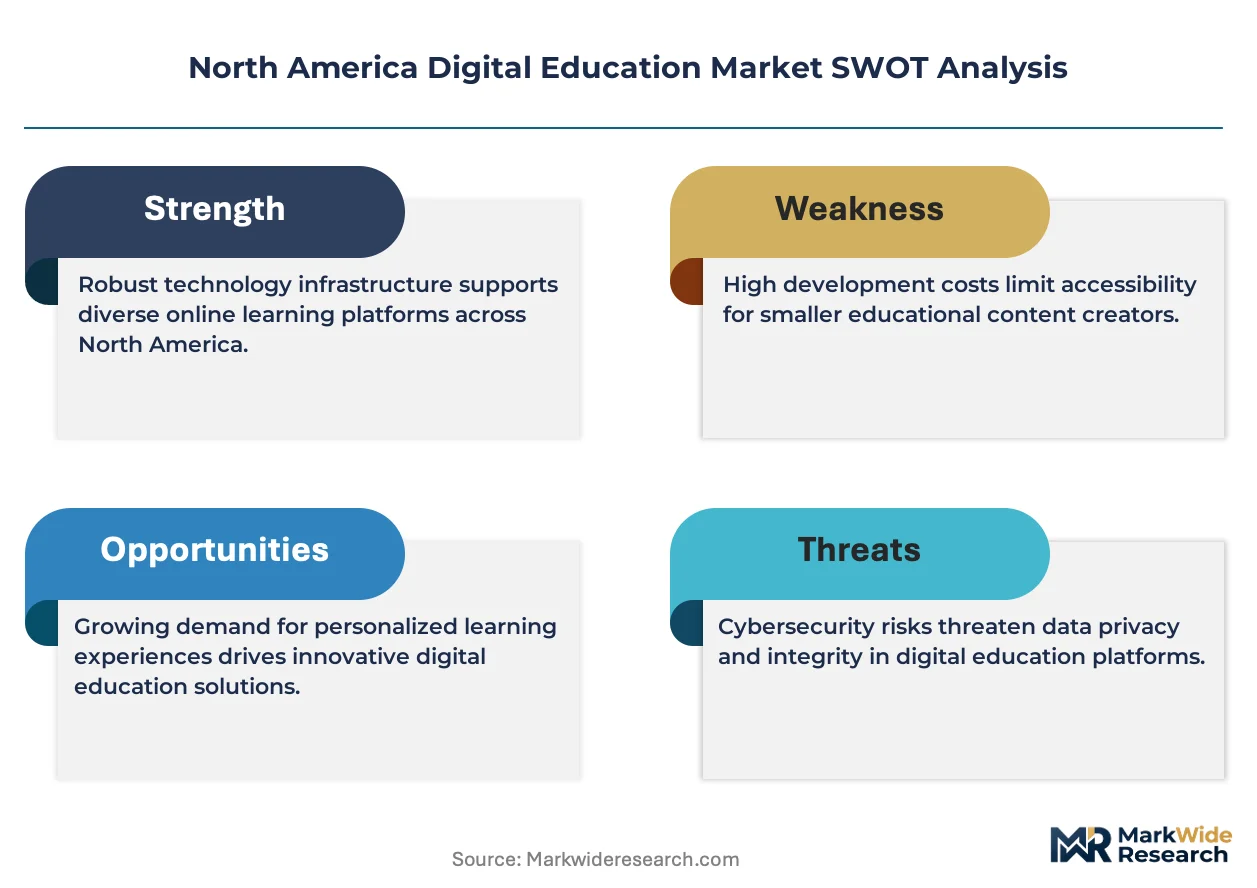
WCAG 2.1 AA accessibility certification is collapsing as a baseline requirement for platform procurement across US state university systems. Coursera Inc. leverages its university partnership network to sustain content credentialing pipelines. Chegg Inc. anchors its position through direct-to-student homework assistance tools. 2U Inc. differentiates via bundled online degree programs with tier-one institutions.
North America digital education encompasses software platforms, content delivery infrastructure, and analytics tools that enable remote instruction, skills assessment, and credential verification through internet-connected devices. Cloud-based architectures with sub-100ms latency thresholds dominate real-time virtual classroom performance. Learning Management Systems occupy the largest installed base across K-12 and higher education deployments, while Artificial Intelligence segments attract the fastest development spend for personalized tutoring engines. Corporate Training end users generate premium margin pools due to measurable ROI requirements and bulk licensing structures.
FCC broadband mapping mandates, US Department of Education Title IV rules, and state-level student data privacy laws collectively shape platform compliance costs and market access thresholds. The FERPA framework restricts how vendors process academic records, forcing architecture redesigns for AI-driven analytics. Stakeholders must monitor pending state legislation on algorithmic transparency in admissions and grading tools.
Market Dynamics
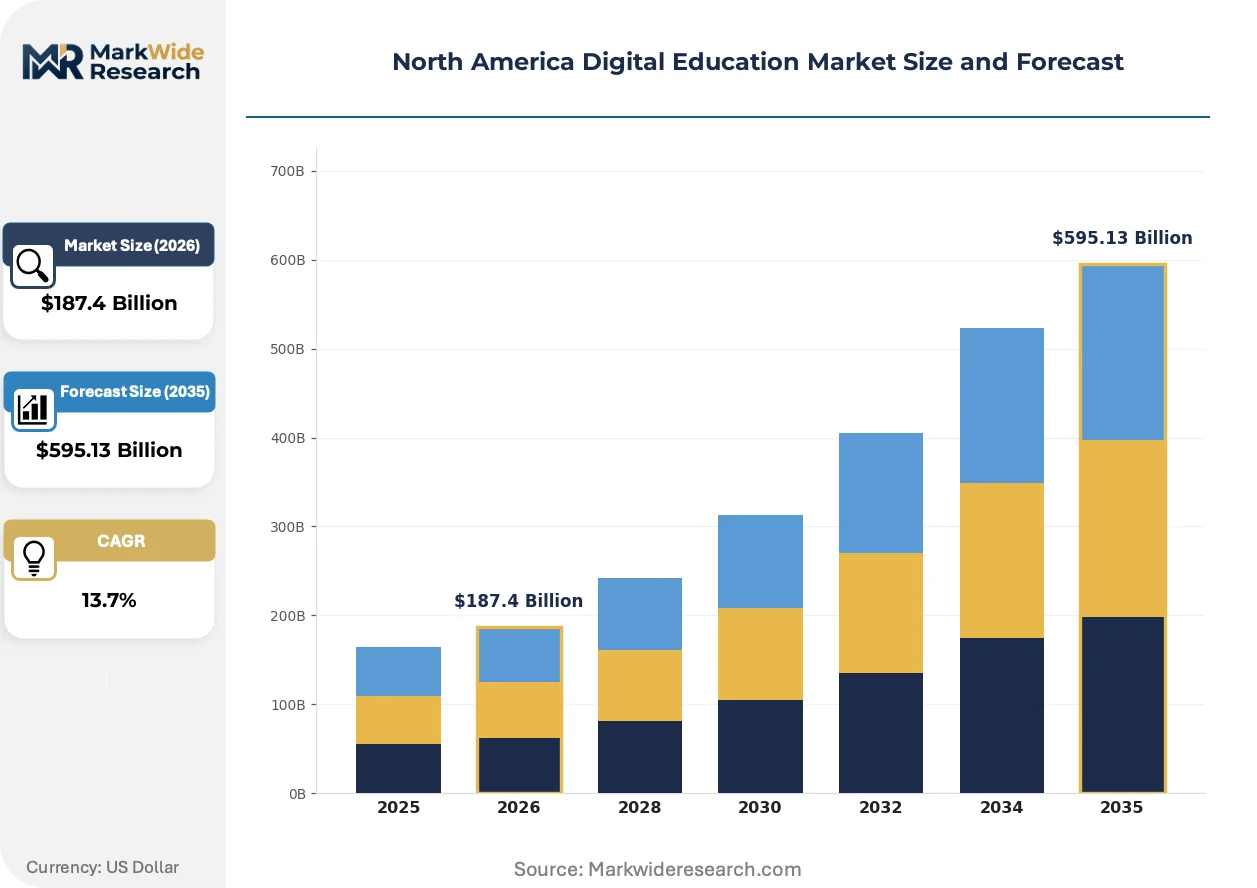
Cloud-based credentialing platforms are compressing procurement cycles across US state university systems as Title IV eligibility expansion forces legacy Learning Management System vendors to re-architect compliance frameworks. This structural pressure cascades through vendor pricing, integration timelines, and partnership terms with tier-one research institutions.
Growth Catalysts
- US Department of Education Title IV expansion:Federal eligibility rules for online degree programs unlock enrollment growth at accredited institutions. Platform providers capture recurring licensing revenue from expanded student pools.
- Fortune 500 corporate training mandates:Manufacturers in Michigan and Ohio now require cloud-based skills verification for workforce reskilling. Bulk enterprise contracts deliver premium margin structures absent in K-12 deployments.
- Silicon Valley-to-Los Angeles corridor concentration:Edtech startups cluster near Stanford, Caltech, and USC research parks. Proximity to university technology transfer offices accelerates AI tutoring engine development cycles.
Market Restraints
- FERPA compliance architecture costs:Student data privacy restrictions force vendors to redesign AI-driven analytics pipelines. Engineering overhead compresses gross margins for mid-tier platform providers.
- Broadband infrastructure gaps:Rural districts in Montana and Mississippi lack sub-100ms latency connectivity required for real-time virtual classrooms. FCC mapping mandates expose addressable market limitations.
- WCAG 2.1 AA certification timelines:Accessibility baseline requirements delay platform procurement approvals. State university system RFP cycles extend 8-14 months pending compliance verification.
Strategic Opportunities
- Texas and Florida K-12 underpenetration:District-level procurement centralization in these states creates consolidated sales channels. Vendors with state-level master service agreements capture multi-year recurring revenue.
- Artificial Intelligence and Learning Management System convergence:Personalized tutoring engines integrated with existing institutional deployments reduce switching friction. Early movers secure exclusive data-sharing terms with research universities.
- California algorithmic transparency legislation:Pending state bills on admissions and grading tools create first-mover advantage for vendors with explainable AI architectures. Compliance-ready platforms command procurement preference.
Industry Challenges
- WCAG 2.1 AA engineering talent scarcity:Accessibility-specialized developers command 40% salary premiums. Vendors compete for limited talent pools in Boston and Seattle technology corridors.
- Legacy Learning Management System integration complexity:State university systems operate heterogeneous technology stacks. API standardization delays prolong implementation timelines and inflate professional services costs.
- State-level student data privacy law fragmentation:California, New York, and Illinois maintain distinct compliance frameworks. Multi-state operators face duplicated legal review and architecture certification expenses.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Digital Education Market |
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $595.13 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Learning Management Systems, E-Learning Tools, Virtual Classrooms, Mobile Learning Applications End User: K-12 Schools, Higher Education Institutions, Corporate Training, Government Agencies Technology: Cloud-Based Solutions, Artificial Intelligence, Augmented Reality, Video Conferencing Distribution Channel: Online Platforms, Direct Sales, Resellers, Educational Partnerships |
| Companies Covered | Coursera Inc., Chegg Inc., 2U Inc., Instructure Holdings Inc., Udemy Inc., Pluralsight LLC, Anthology Inc., D2L Corp., Blackboard Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Digital Education Market Evolving Landscape
Generative AI is compressing content production timelines while regulatory pressure on algorithmic decision-making forces transparency investments. These dual pressures reshape competitive positioning between incumbent platform providers and specialized AI-native entrants.
Adaptive assessment engines are bifurcating the skills verification market. Corporate training departments at automotive and aerospace manufacturers adopt these tools for real-time competency mapping. The technology compresses traditional certification timelines from quarters to weeks, enabling just-in-time workforce deployment.
FCC broadband mapping mandates are reshaping platform go-to-market strategies. Infrastructure data disclosure exposes addressable market boundaries with precision. Vendors now concentrate direct sales resources on metropolitan statistical areas with verified sub-100ms latency, abandoning prior nationwide coverage assumptions.
Enterprise procurement teams are consolidating vendor relationships under outcome-based credentialing contracts. Fortune 500 manufacturers now tie platform fees to measurable skills acquisition rather than seat licenses. This shift concentrates spending with providers offering integrated assessment-to-placement analytics, marginalizing point-solution homework assistance tools.
North America Digital Education Market Segmentation
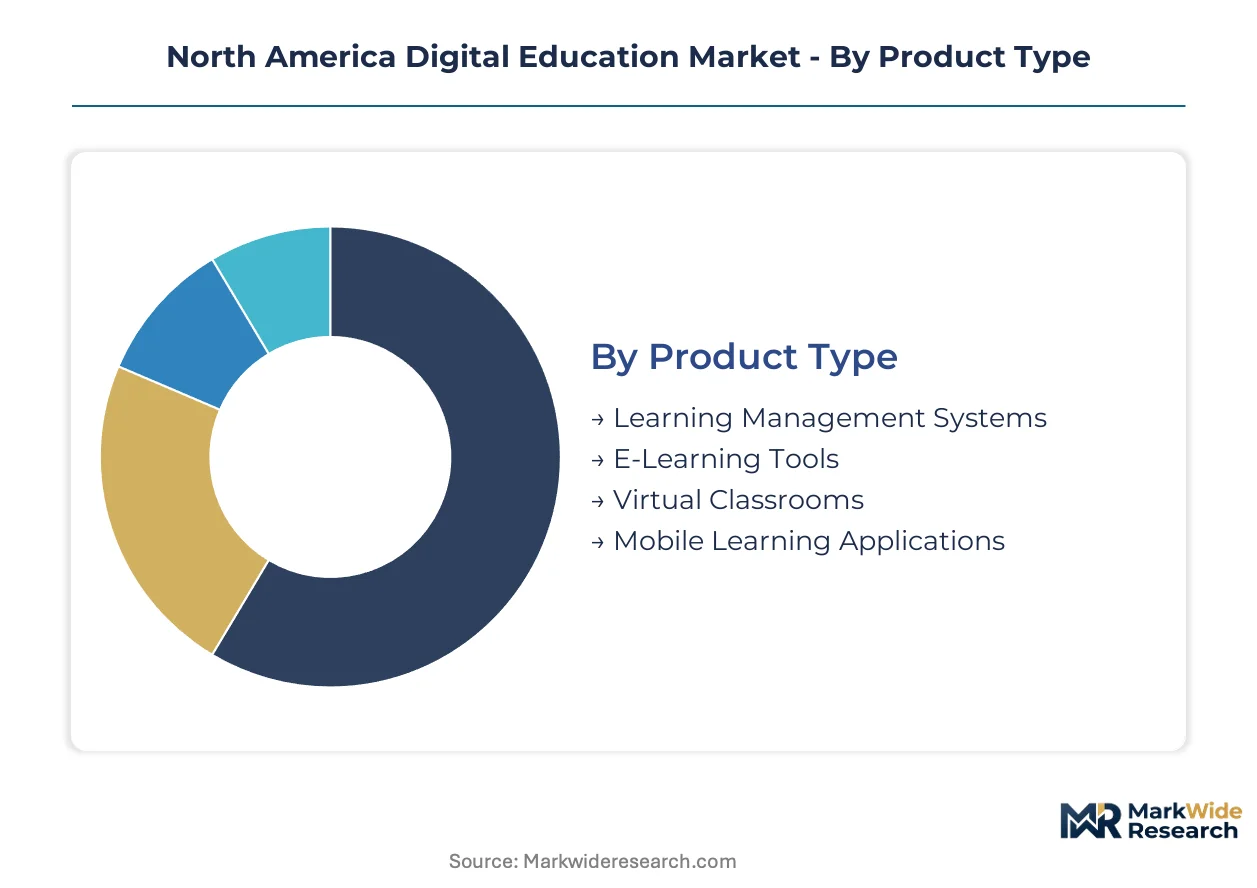
Segmentation in the North America Digital Education Market reveals how procurement authority and infrastructure requirements fragment revenue capture across institutional buyers. Cloud architecture investments and compliance mandates create divergent margin profiles between enterprise-scale deployments and district-level K-12 contracts.
Product Type:
Substitution pressure from AI-native tutoring platforms threatens legacy Learning Management System incumbents most severely, forcing established vendors to re-architect around real-time personalization engines.
- Learning Management Systems:These platforms integrate gradebook, content repository, and user administration functions into unified institutional deployments. Procurement concentrates in California and Texas state university systems where Title IV compliance requirements favor established vendors with FERPA-certified architectures.
- E-Learning Tools:Modular assessment, plagiarism detection, and content authoring applications that plug into larger institutional stacks. Demand clusters near Boston and Seattle technology corridors where accessibility engineering talent commands premium compensation.
- Virtual Classrooms:Real-time video infrastructure with sub-100ms latency thresholds for synchronous instruction.
- Mobile Learning Applications:Smartphone-optimized microlearning modules targeting commuter corporate training segments.
Learning Management Systems anchor the volume base while Artificial Intelligence-integrated E-Learning Tools gain share at the steepest rate.
End User:
Cost tier stratification separates premium-margin corporate contracts from price-sensitive K-12 procurement cycles, with higher education occupying an intermediate position on both dimensions.
- Corporate Training:Fortune 500 manufacturers in Michigan and Ohio mandate cloud-based credentialing with measurable skills verification. Bulk enterprise contracts deliver premium pricing structures tied to outcome-based fee arrangements rather than per-seat licensing.
- Higher Education Institutions:Accredited colleges and universities purchasing bundled online degree program infrastructure. Procurement centralizes in California's Silicon Valley-to-Los Angeles corridor where proximity to research parks accelerates technology transfer partnerships.
- K-12 Schools:District-level deployments constrained by federal Title I funding formulas and state-level student data privacy law fragmentation.
- Government Agencies:Federal and state workforce development programs with specialized security clearance requirements.
Corporate Training commands the highest margin tier while K-12 Schools generate the largest absolute seat volume across the installed base.
Technology:
Application maturity separates production-ready cloud deployments from experimental Augmented Reality implementations still seeking scalable instructional use cases.
- Cloud-Based Solutions:Distributed server architectures enabling real-time content delivery and centralized credential verification. FCC broadband mapping mandates now concentrate vendor sales resources on metropolitan statistical areas with verified sub-100ms latency, abandoning prior nationwide coverage assumptions.
- Artificial Intelligence:Personalized tutoring engines and adaptive assessment algorithms attracting the fastest development spend. Pending California algorithmic transparency legislation creates first-mover advantage for vendors with explainable AI architectures in admissions and grading tools.
- Augmented Reality:Immersive simulation environments for vocational and medical training applications.
- Video Conferencing:Commoditized real-time communication infrastructure facing margin compression from free-tier consumer alternatives.
Cloud-Based Solutions constitute the dominant deployment mode while Artificial Intelligence segments expand most quickly through research university partnerships.
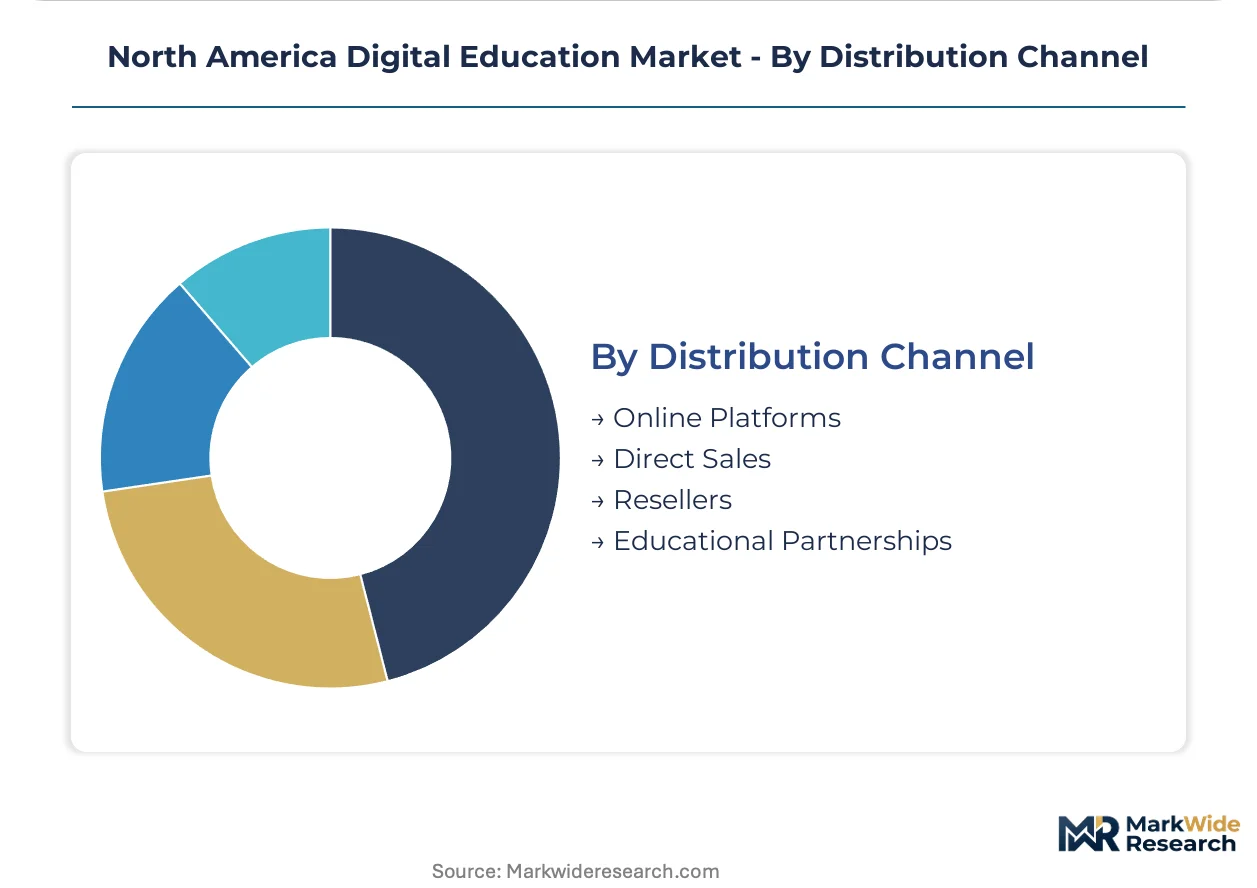
Distribution Channel:
Customer type concentration drives channel selection, with institutional procurement teams favoring direct relationships while smaller districts default to aggregator platforms.
- Direct Sales:Enterprise field teams targeting Fortune 500 training departments and state university system central procurement offices. These relationships enable multi-year master service agreements with customized integration timelines and dedicated support tiers.
- Educational Partnerships:Exclusive technology transfer arrangements with Stanford, Caltech, and USC research parks. Proximity to university innovation offices accelerates AI tutoring engine development cycles and provides preferred access to pilot deployments.
- Online Platforms:Self-service marketplaces capturing mid-tier institutional and individual learner transactions.
- Resellers:Regional systems integrators bundling hardware, connectivity, and software for rural district deployments.
Direct Sales captures the premium contract value while Educational Partnerships deliver the steepest technology access trajectory through research collaboration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fortune 500 training departments and state university procurement offices concentrate demand across three national markets. Federal Title IV expansion and FCC broadband infrastructure mandates reshape addressable boundaries differently in each jurisdiction.
United States
Corporate training mandates at Michigan and Ohio manufacturers drive cloud-based credentialing procurement. The US Department of Education's Title IV eligibility rules for online programs accelerate platform enrollment at accredited institutions. Silicon Valley-to-Los Angeles corridor clustering concentrates edtech startup formation near Stanford, Caltech, and USC research parks.
Canada
Provincial education ministries in Ontario and Quebec centralize K-12 platform procurement through master service agreements. Health Canada coordinates with the Canadian Radio-television and Telecommunications Commission on rural broadband mapping for remote learning infrastructure. Toronto-Waterloo corridor proximity to University of Toronto and McGill research offices accelerates AI tutoring engine commercialization.
Mexico
Federal workforce development programs through the Secretariat of Public Education expand digital credentialing for manufacturing reskilling in Nuevo León and Jalisco. The Federal Telecommunications Institute mandates broadband infrastructure disclosure for platform market access. Mexico City metropolitan area clustering concentrates edtech deployment near Tecnológico de Monterrey and UNAM technology transfer offices.
North America Digital Education Market Competitive Landscape
Player mix skews toward platform-integrated specialists with university partnership networks. Consolidation pressure intensifies as Title IV compliance requirements and FERPA-certified architectures raise fixed-cost barriers. Three archetypes dominate: university-affiliated degree bundlers, direct-to-student homework assistance providers, and corporate training outcome-based credentialing platforms. M&A activity concentrates on AI tutoring engine acquisitions and state-level procurement channel consolidation.
Within the university partnership tier, Coursera Inc. and 2U Inc. exemplify divergent approaches to institutional credentialing pipelines. Chegg Inc. anchors the direct-to-student assistance segment. These three entities collectively represent how platform providers navigate the tension between scalable content delivery and compliance-heavy institutional sales cycles.
| Leading Market Players |
|---|
| Coursera Inc. |
| Chegg Inc. |
| 2U Inc. |
| Instructure Holdings Inc. |
| Udemy Inc. |
| Pluralsight LLC |
| Anthology Inc. |
| D2L Corp. |
| Blackboard Inc. |
| Others |
Value Network & Pricing Analysis
Generative AI content engines displacing traditional instructional design labor pools simultaneously concentrates development cost advantages in Silicon Valley-to-Los Angeles corridor vendor clusters and compresses per-course production pricing across tier-two platform providers. This substitution dynamic redistributes margin capture toward AI-native entrants while forcing legacy Learning Management System vendors into defensive pricing postures.
Pricing Analysis
Cost-plus contracts with cloud infrastructure indexation dominate Fortune 500 corporate training procurement, tying platform fees to AWS and Azure compute pricing bands. Three-tier pricing structure across premium, standard, and economy levels separates outcome-based credentialing bundles from seat-license homework assistance tools. Cost compression in mid-tier K-12 deployments intensifies because state procurement centralization mandates volume discounts. District-level buyers exhibit highest price sensitivity; enterprise training departments show lowest, accepting premium pricing for measurable skills verification.
Supply Chain Analysis
Just-in-time content deployment preferences dominate edtech vendor inventory strategies, minimizing pre-produced course asset stockpiles in favor of on-demand generative assembly. Geographic supply concentrates in the United States, Canada, and Mexico, with cloud infrastructure provisioning drawing from hyperscaler data center networks across these jurisdictions. Raw material dependencies center on GPU compute capacity, broadband latency infrastructure, and accessibility engineering talent pools. Single-source vulnerability runs through NVIDIA chip supply chains for AI tutoring engine development. Distribution runs through direct enterprise field teams and educational partnership channels with university technology transfer offices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face existential substitution pressure from AI-native tutoring platforms that compress content production economics and erode traditional Learning Management System switching costs.
For Market Incumbents: Consolidate AI tutoring engine capabilities through targeted capability acquisitions in Boston and Seattle technology corridors. Lock in exclusive data-sharing terms with Stanford, Caltech, and USC research parks before explainable AI legislation crystallizes procurement preferences. Vertical integration into cloud infrastructure provisioning reduces hyperscaler dependency exposure. For New Entrants and Emerging Players: Lead with algorithmic transparency compliance as a wedge against FERPA-certified legacy architectures. Texas and Florida K-12 district centralization offers the most penetrable procurement channel for state-level master service agreements. Direct sales teams targeting underpenetrated rural districts in Montana and Mississippi bypass incumbent relationship moats. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed corporate training platforms holding Fortune 500 outcome-based contracts but lacking AI-native personalization engines. Five-to-ten year viability hinges on successful technology transfer from research university partnerships. The signal to watch is California algorithmic transparency bill passage timing as a demand inflection trigger.| Strategic Initiative | Industry Significance |
|---|---|
| AI Tutoring Engine Acquisition | Captures explainable AI capabilities ahead of California procurement mandates. |
| University Partnership Expansion | Secures exclusive data-sharing terms with Stanford and Caltech research parks. |
| State-Level Master Service Agreement | Locks in multi-year recurring revenue through Texas and Florida procurement centralization. |
| FERPA-Certified Architecture Investment | Eliminates compliance barriers for Title IV-eligible online degree program deployments. |
| Corporate Training Outcome-Based Contracting | Ties platform fees to measurable skills verification at Michigan and Ohio manufacturers. |
Research Methodology
Cross-validation between primary interviews with edtech platform CTOs, state university system procurement officers, corporate training directors, and accessibility engineering specialists and secondary validation through FCC broadband mapping data, US Department of Education Title IV enrollment disclosures, and SEC filings from publicly traded platform providers anchors the qualitative findings. Bottom-up triangulation aggregates district-level contract values while top-down validation cross-checks against federal funding allocation patterns.
Sensitivity analysis across deployment model, institutional size, vertical application, and regional regulatory cluster dimensions shapes the analytical framework. Growth projections derive from cohort-based adoption curves segmented by end-user type and technology maturity tier across the analysis window. Forecast inputs incorporate cloud infrastructure latency thresholds, WCAG 2.1 AA certification timelines, and AI tutoring engine development cycle acceleration from research university partnerships.
Forecasts assume regulatory continuity in US Department of Education Title IV rules and California algorithmic transparency frameworks; material policy shifts would require re-modeling enrollment eligibility and procurement preference structures. Revision becomes warranted when FCC broadband infrastructure disclosure thresholds cross latency benchmarks that invalidate real-time virtual classroom deployment assumptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Educational Technology (EdTech)
Blockchain in Edutech Market
Educational Technology (EdTech)
Artificial Intelligence (AI) in Education Market
Educational Technology (EdTech)
Digital Education Systems Market
Educational Technology (EdTech)
Flipped Classroom Market
Educational Technology (EdTech)
Edtech and Smart Classroom Market
Educational Technology (EdTech)
Higher Education Learning Systems Market
Educational Technology (EdTech)
Global Smart Learning Market
Educational Technology (EdTech)
ASEAN Smart Education and Learning Market
Educational Technology (EdTech)
Augmented and Virtual Reality in Education Market
Educational Technology (EdTech)
Global Edutainment Centers Market
Educational Technology (EdTech)
Education Technology and Smart Classrooms Market
Educational Technology (EdTech)
Asia-Pacific Digital Education Market
Educational Technology (EdTech)
Child Care Software Market
Educational Technology (EdTech)
VR Education Market
Educational Technology (EdTech)
Smart Education System Market
Educational Technology (EdTech)
Student Response System Market