
 VR Education Market | 2026-2036
VR Education Market Size, Share, and Industry Trends Forecast 2026-2036
VR Education Market Insights
The VR education landscape is restructuring around a sharp split between enterprise-grade immersive labs and low-cost mobile VR deployments for mass classrooms. Meta Platforms, Inc. dominates consumer-accessible hardware ecosystems for K-12 distribution. Microsoft Corporation anchors institutional trust through Azure-backed mixed-reality services for universities. zSpace, Inc. specializes in stereoscopic desktop solutions that circumvent headset barriers in budget-constrained districts.
Virtual reality education encompasses hardware, software platforms, and simulation tools that generate interactive three-dimensional learning environments with refresh rates typically exceeding 90 Hz to prevent motion sickness. These systems serve industrial and commercial purposes by enabling risk-free skill repetition, spatial concept visualization, and remote collaborative instruction. Headsets and software platforms capture the dominant share of value, while simulation tools for vocational training represent the fastest-expanding margin pool. Corporate training and higher education verticals outpace K-12 adoption due to direct return-on-investment measurability and autonomous procurement authority.
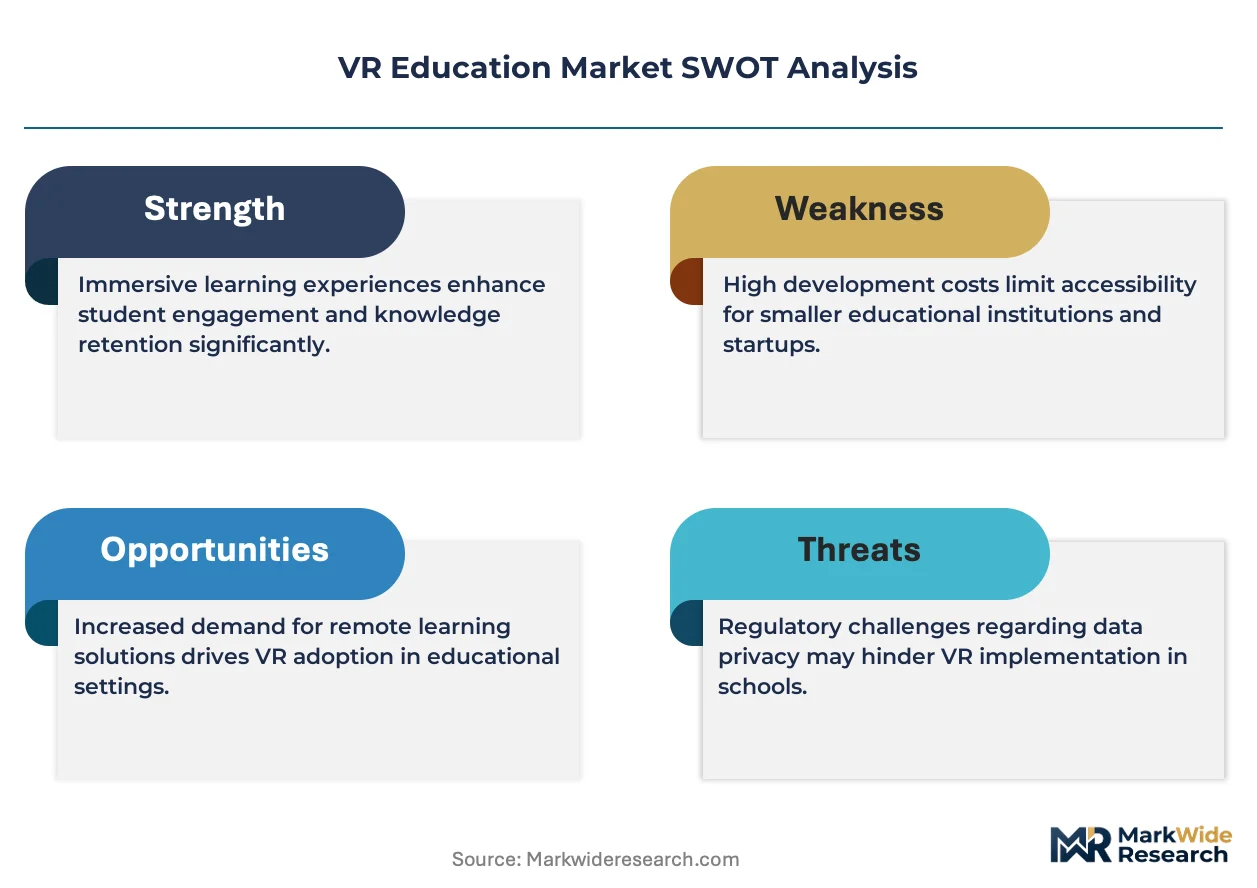
The U.S. Federal Communications Commission shapes broadband subsidy eligibility that determines which schools can sustain remote VR delivery, while the EU AI Act imposes algorithmic transparency requirements on adaptive tutoring software sold across Europe. China's Ministry of Industry and Information Technology enforces GB standards for hardware electromagnetic compatibility that foreign vendors must satisfy for market access. Stakeholders must monitor which regulatory framework—data privacy, content certification, or infrastructure subsidy—becomes the binding constraint in their target geography.
Market Dynamics
Medical schools and surgical training programs are accelerating procurement of enterprise-grade immersive labs, compressing hardware refresh cycles from five years to eighteen months as competency-based curricula replace lecture-based instruction.
Growth Catalysts
- EU AI Act:Algorithmic transparency mandates for adaptive tutoring software sold across Europe are forcing vendors to document decision pathways, which ironically builds institutional buyer confidence and accelerates procurement approvals for AI-integrated VR platforms.
- Spatial computing:Hand-tracking and eye-tracking sensors embedded in next-generation headsets eliminate controller-based friction for younger learners, expanding addressable K-12 age bands downward into early elementary.
- United States:University procurement budgets for immersive learning infrastructure continue expanding as trustees demand measurable return-on-investment metrics that VR simulations deliver through repeatable skill assessment.
Market Restraints
- Display panel concentration:Micro-OLED supply for high-refresh headsets remains captive to Korean and Japanese component fabs, creating six-month lead time volatility for hardware vendors outside East Asian supply chains.
- Motion sickness thresholds:Sub-90 Hz refresh rates in budget mobile VR deployments trigger user dropout in 15-20% of first-time adolescent users, capping low-end market penetration regardless of price compression.
- FCC broadband subsidy eligibility:Schools in rural U.S. counties lacking gigabit infrastructure cannot sustain synchronous remote VR delivery, excluding approximately one-third of American school districts from cloud-rendered immersive content.
Strategic Opportunities
- Vocational training:Industrial maintenance and hazardous materials handling simulations represent underpenetrated white space where union apprenticeship programs lack capital for physical mock-ups but possess training budgets for software licenses.
- China GB standards compliance:Foreign hardware vendors who pre-certify electromagnetic compatibility with MIIT requirements unlock direct-to-district sales channels previously blocked by procurement preference for domestic equipment.
- Haptic feedback convergence:Force-feedback gloves integrated with surgical training software enable tactile skill transfer previously impossible in screen-based simulation, commanding premium pricing in medical residency programs.
Industry Challenges
- Instructional design talent scarcity:VR content studios cannot hire sufficient learning scientists who bridge pedagogical theory with 3D environment design, delaying curriculum deployment timelines by 8-12 months.
- LMS integration complexity:Proprietary VR platforms require custom API development to feed assessment data into existing student information systems, inflating implementation costs and frustrating IT departments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | VR Education Market |
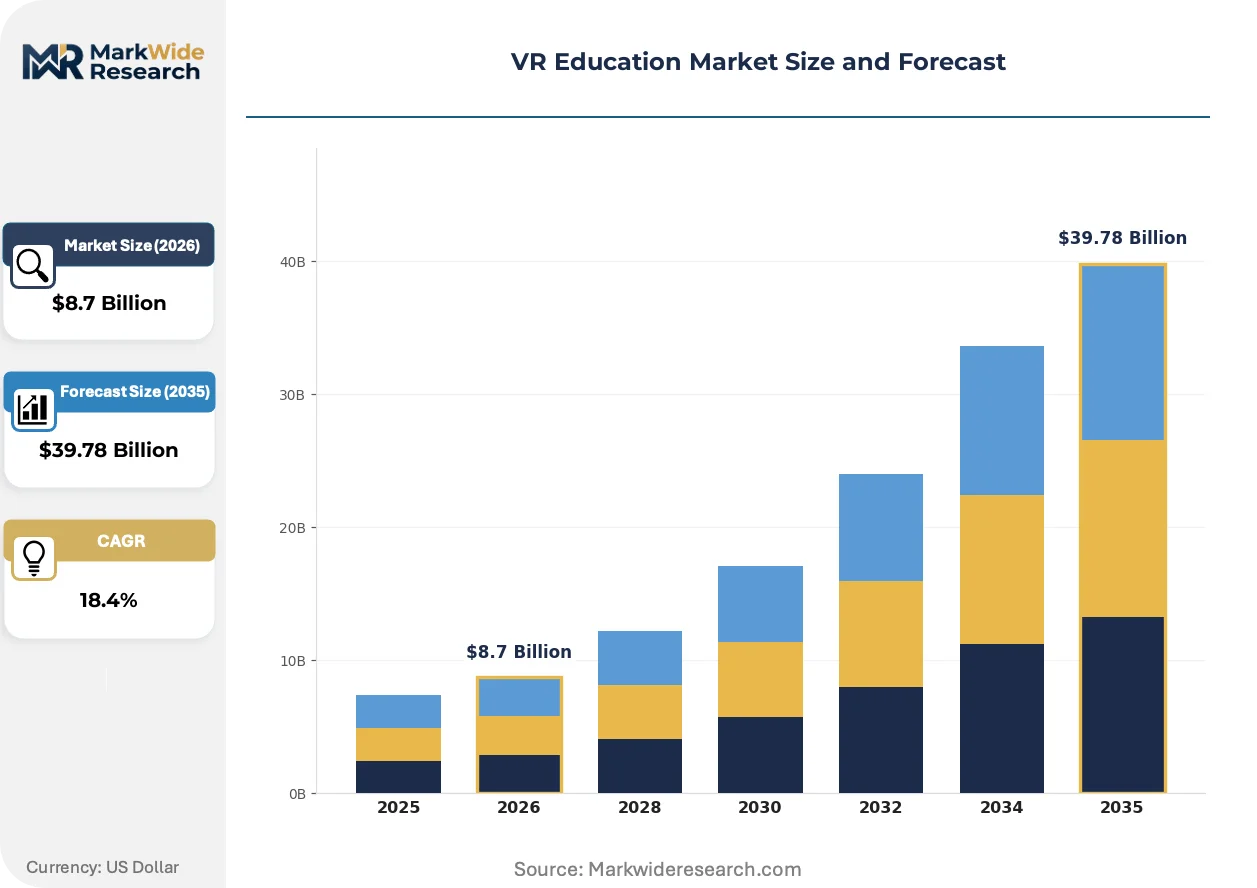
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $39.78 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Headsets, Software Platforms, Learning Management Systems, Simulation Tools Industry Vertical: K-12 Education, Higher Education, Corporate Training, Vocational Training End User: Students, Teachers, Institutions, Corporations Delivery Mode: On-site, Remote, Hybrid, Blended |
| Companies Covered | Microsoft Corporation, Meta Platforms, Inc., Google LLC, HTC Corporation, Samsung Electronics Co., Ltd., EON Reality, Inc., zSpace, Inc., Unity Technologies, Avantis Systems Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
VR Education Market Trends and Innovations
Artificial intelligence inference at the edge is reshaping how immersive environments adapt to individual learner biometrics, compressing the latency between user action and system response below perceptible thresholds.
Generative AI is converging with real-time 3D engines to produce scenario variations on demand, eliminating the content bottleneck that previously constrained simulation-based curricula to fixed branching narratives. Medical residency programs in the United States and Germany are piloting these systems for rare procedure training where physical patient exposure cannot be scheduled. The technology is converging with haptic hardware to create full sensory immersion that textbook and video instruction cannot replicate.
The EU AI Act imposes documentation requirements on adaptive tutoring algorithms that modify difficulty based on learner performance, compelling VR education vendors to maintain audit trails for automated pedagogical decisions. Industrial consequence includes delayed product launches for European markets as engineering teams rearchitect opaque neural networks into interpretable rule-based systems. Higher education procurement offices in France and the Netherlands are now requiring algorithmic transparency certifications as mandatory evaluation criteria.
University purchasing committees are consolidating vendor relationships around platform ecosystems rather than licensing individual simulations, displacing the fragmented point-solution procurement that dominated early VR adoption. This concentration favors vendors offering content marketplaces where faculty upload custom scenarios alongside publisher libraries. The shift is most visible in United States research-intensive universities where centralized IT governance has replaced departmental autonomous purchasing.
VR Education Market Segmentation
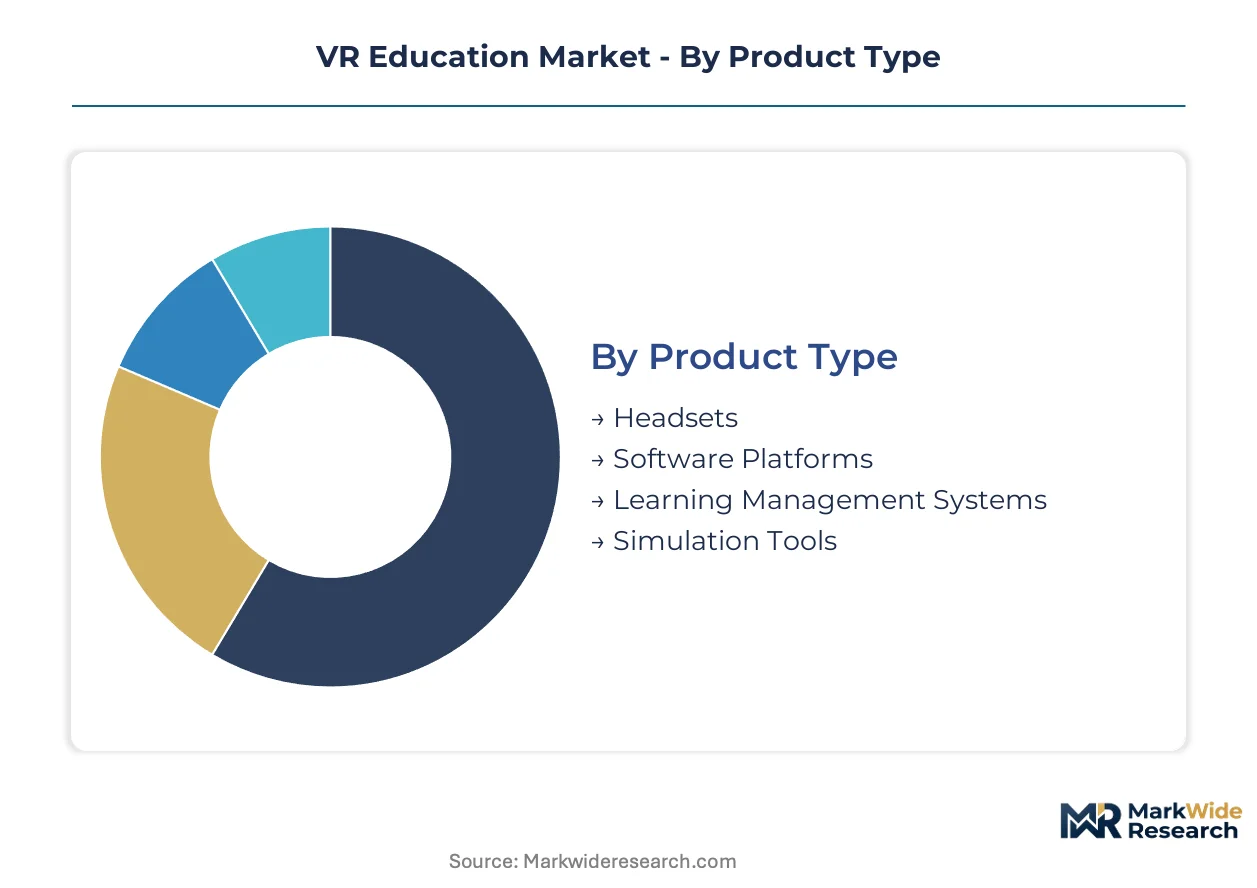
Procurement patterns in VR education diverge sharply across institutional buyer types, with universities prioritizing enterprise-grade immersive labs while K-12 districts optimize for cost-per-seat economics. Product architecture choices determine total cost of ownership more than upfront licensing fees, as hardware refresh cycles and integration complexity dominate multi-year budgeting decisions.
Product Type:
Hardware refresh cycles and integration architecture drive procurement committee evaluations more than content library depth alone.
- Headsets:Standalone and tethered devices with 90+ Hz refresh rates prevent motion sickness in extended training sessions. Demand concentrates in United States medical residency programs where competency-based curricula mandate eighteen-month hardware replacement schedules.
- Software Platforms:Cloud-rendered environments with real-time adaptive difficulty algorithms require gigabit broadband infrastructure. European universities under EU AI Act compliance mandates now require algorithmic transparency documentation as mandatory evaluation criteria.
- Learning Management Systems:Proprietary VR platforms demand custom API development to feed assessment data into existing student information systems.
- Simulation Tools:Vocational training modules for industrial maintenance and hazardous materials handling enable risk-free skill repetition without physical mock-up capital expenditure.
Headsets lead on scale; simulation tools lead on momentum.
Industry Vertical:
Return-on-investment measurability determines adoption velocity, with direct skill assessment capabilities accelerating procurement in training-intensive sectors.
- K-12 Education:Budget-constrained districts favor mobile VR deployments with sub-$400 hardware price points despite 15-20% first-time user dropout rates from motion sickness.
- Higher Education:Research-intensive universities in the United States consolidate vendor relationships around platform ecosystems with centralized IT governance replacing departmental autonomous purchasing.
- Corporate Training:Enterprise learning and development departments demand repeatable skill assessment metrics that justify immersive infrastructure spending to executive stakeholders.
- Vocational Training:Union apprenticeship programs possess training budgets for software licenses but lack capital for physical equipment mock-ups, creating underpenetrated white space in industrial maintenance simulation.
Higher education leads on scale; vocational training leads on momentum.
End User:
Autonomous procurement authority separates institutional buyers from individual adopters, with budget holders prioritizing integration over standalone functionality.
- Students:Primary beneficiaries of spatial concept visualization and remote collaborative instruction, though rarely direct purchasers.
- Teachers:Instructional design talent scarcity delays curriculum deployment as pedagogical theory expertise fails to bridge 3D environment design requirements.
- Institutions:Medical schools and surgical training programs compress hardware refresh cycles as competency-based instruction replaces lecture-based delivery.
- Corporations:Industrial maintenance and hazardous materials handling training programs seek force-feedback haptic integration for tactile skill transfer previously impossible in screen-based simulation.
Institutions lead on scale; corporations lead on momentum.
Delivery Mode:
Infrastructure dependency creates geographic exclusion, with broadband availability determining which deployment architectures remain viable for target user populations.
- On-site:Dedicated immersive labs with localized rendering eliminate latency concerns but require physical space allocation and IT support staffing.
- Remote:Cloud-rendered synchronous delivery depends on FCC broadband subsidy eligibility; rural United States counties lacking gigabit infrastructure cannot sustain this architecture.
- Hybrid:Split architectures with edge inference for biometric adaptation and cloud streaming for content delivery balance responsiveness with content breadth.
- Blended:Rotational models combining VR immersion with traditional instruction maximize hardware utilization rates in budget-constrained environments.
On-site leads on scale; hybrid leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medical schools in the United States and Germany anchor immersive training infrastructure development. China's vocational institutes drive hardware certification requirements. European universities under harmonized standards accelerate procurement velocity.
United States
Medical residency programs and research-intensive universities compress hardware refresh cycles to eighteen months as competency-based curricula replace lecture-based instruction. The Federal Communications Commission shapes broadband subsidy eligibility that determines which rural counties can sustain synchronous remote VR delivery. Procurement concentrates in Massachusetts and California where university IT governance consolidates vendor relationships around platform ecosystems.
Germany
Industrial apprenticeship programs and medical residency systems generate concentrated demand for tactile skill transfer simulations. The EU AI Act imposes algorithmic transparency requirements on adaptive tutoring software, compelling vendors to maintain audit trails for automated pedagogical decisions. Development clusters in Bavaria and Baden-Württemberg pilot rare procedure training where physical patient exposure cannot be scheduled.
China
Vocational training institutes and district-level education bureaus drive procurement of electromagnetic-compatible hardware for mass classroom deployment. The Ministry of Industry and Information Technology enforces GB standards for hardware electromagnetic compatibility that foreign vendors must satisfy for market access. Manufacturing corridors in the Yangtze River Delta and Pearl River Delta concentrate domestic equipment production for direct-to-district sales channels.
United Kingdom
Higher education procurement offices and corporate learning departments demand repeatable skill assessment metrics that justify immersive infrastructure spending. The national data protection framework shapes content certification requirements for student biometric data collection. London and the Southeast anchor platform ecosystem adoption where centralized IT governance has replaced departmental autonomous purchasing.
India
State technical universities and private medical colleges expand immersive lab procurement as accreditation bodies mandate simulation-based competency verification. The Bureau of Indian Standards develops electromagnetic compatibility protocols for imported hardware. Karnataka and Maharashtra concentrate ed-tech startup activity developing localized vocational training modules for industrial maintenance certification.
VR Education Market Competitive Landscape
Capital-heavy hardware producers compete with asset-light software designers for procurement committee attention across institutional buyer segments. The vendor base fragments across three strategic tiers: cloud-platform ecosystems anchoring university relationships, specialized stereoscopic hardware vendors penetrating budget-constrained districts, and simulation studios delivering vocational content for union apprenticeship programs. Dominant competitive moves include platform ecosystem consolidation around content marketplaces and pre-certification of hardware against national electromagnetic compatibility standards to unlock direct procurement channels.
Within the platform ecosystem tier, Microsoft Corporation and Meta Platforms, Inc. occupy positions reflecting divergent institutional trust models. Among specialized hardware vendors, zSpace, Inc. represents the stereoscopic desktop archetype that circumvents headset deployment barriers in K-12 environments. EON Reality, Inc. exemplifies the simulation-focused vendor archetype targeting vocational training verticals with industrial maintenance and hazardous materials handling content.
| Leading Market Players |
|---|
| Microsoft Corporation |
| Meta Platforms, Inc. |
| Google LLC |
| HTC Corporation |
| Samsung Electronics Co., Ltd. |
| EON Reality, Inc. |
| zSpace, Inc. |
| Unity Technologies |
| Avantis Systems Ltd. |
| Others |
Pricing and Supply Chain Analysis
Enterprise-immersive versus mobile-VR hardware divergence splits procurement committees into distinct budget archetypes, with medical residency programs absorbing eighteen-month refresh cycles while K-12 districts cap spending at sub-$400 per seat. This bifurcation concentrates margin capture in headset tiers certified for 90+ Hz refresh rates, while supply chain configuration tracks the geographic locus of Micro-OLED fabrication capacity.
Pricing Analysis
Bundled platform-and-content subscriptions dominate university procurement, while unbundled hardware-plus-software licensing persists in vocational training where union apprenticeship programs lack capital for full ecosystem commitments. Price differentiation rests on refresh rate certification tiers and haptic integration depth, with force-feedback surgical modules commanding substantial premiums over controller-based alternatives. Cost compression in budget mobile VR intensifies as sub-90 Hz panels flood mass classroom channels. K-12 districts exhibit acute price sensitivity, whereas medical schools prioritize performance metrics over per-seat economics.
Supply Chain Analysis
GB standards compliance and FCC electromagnetic certifications gate market access for foreign hardware vendors seeking direct-to-district channels in China and rural United States counties. Component supply draws from Korean and Japanese Micro-OLED fabs, Chinese PCB assembly corridors, and Taiwanese lens foundries. Single-source vulnerability concentrates in high-refresh display panels where six-month lead times constrain hardware vendors outside East Asian supply chains. Distribution runs through university procurement offices and vocational training consortiums rather than retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The VR education market compounds steadily as competency-based curricula displace lecture-based instruction across medical and technical training programs. This structural shift in pedagogy creates durable demand for repeatable skill assessment infrastructure.
For Market Incumbents: Anticipate compression in hardware refresh cycles by pre-positioning upgrade pathways for medical residency programs transitioning to haptic-integrated surgical modules. Consolidate platform ecosystems around content marketplaces to capture centralized IT governance budgets displacing departmental autonomous purchasing. Certification investment in EU AI Act algorithmic transparency documentation secures procurement preference in French and Dutch higher education.
For New Entrants and Emerging Players: Direct-to-union digital sales channels bypass capital-intensive physical mock-up requirements in industrial maintenance and hazardous materials handling vocational verticals. Target underpenetrated union apprenticeship programs in Germany and the United States where training budgets exist but physical simulation infrastructure does not. Lead with scenario-variety subscriptions powered by generative AI rather than fixed branching narratives.
For Investors and Strategic Acquirers: Consolidation pressure builds where instructional design talent scarcity delays curriculum deployment timelines by 8-12 months. The market supports 5-10 year holding periods for simulation studios bridging pedagogical theory with 3D environment design. Acquisition candidates display proprietary haptic hardware integration with surgical training software. Monitor EU AI Act enforcement velocity as inflection indicator for European procurement acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Ecosystem Consolidation | Centralized IT governance in United States research universities favors vendors offering faculty content marketplaces. |
| Haptic Hardware Integration | Force-feedback gloves with surgical training software enable tactile skill transfer commanding premium pricing in medical residencies. |
| GB Standards Pre-Certification | MIIT electromagnetic compliance unlocks direct-to-district sales channels in China's vocational training institutes. |
| Generative AI Content Engines | Real-time scenario variation eliminates fixed branching narrative bottlenecks constraining simulation-based curricula. |
| EU AI Act Compliance Architecture | Algorithmic transparency documentation becomes mandatory evaluation criterion in French and Dutch procurement offices. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combined with secondary validation. The research incorporates structured interviews with medical school curriculum directors, university IT procurement officers, vocational training consortium managers, and VR content studio learning scientists. Secondary sources include FCC broadband subsidy eligibility databases, EU Digital Education Action Plan implementation reports, MIIT GB standards certification records, and SEC filings from publicly traded hardware vendors. Bottom-up demand modeling triangulates against top-down market sizing across hardware, software platform, and simulation tool revenue streams.
Rate-of-change decomposition separates volume growth from price evolution across the projection horizon. Segmentation dimensions include product type (headsets, software platforms, simulation tools), industry vertical (higher education, K-12, corporate training, vocational), and delivery mode (on-site, remote, hybrid, blended). CAGRs derive from logistic adoption curves fitted to institutional procurement cycle data and hardware replacement schedule compression observed in competency-based curricula. Industry-specific inputs encompass refresh rate threshold compliance rates and motion sickness dropout incidence in first-time adolescent users.
The model assumes a particular technology adoption path; alternative pathways for standalone versus tethered headset architectures would alter the outlook. Forecasts reflect assumptions regarding broadband infrastructure deployment velocity, regulatory harmonization timelines, and component supply lead time stability. A model refresh is warranted upon material change in FCC subsidy eligibility criteria or EU AI Act enforcement granularity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Educational Technology (EdTech)
Global Social Learning Platforms Market
Educational Technology (EdTech)
Edutainment Market
Educational Technology (EdTech)
Global K-12 Software Market
Educational Technology (EdTech)
Global AI in Education Market
Educational Technology (EdTech)
Blockchain in Edutech Market
Educational Technology (EdTech)
Asia-Pacific Digital Education Market
Educational Technology (EdTech)
Education Technology Market
Educational Technology (EdTech)
Edtech Market
Educational Technology (EdTech)
Global Micro-Learning Market
Educational Technology (EdTech)
Digital Classroom Market
Educational Technology (EdTech)
Higher Education Technology Market
Educational Technology (EdTech)
Global Edutainment Centers Market
Educational Technology (EdTech)
Global Gamification in Education Market
Educational Technology (EdTech)
ASEAN Smart Education and Learning Market
Educational Technology (EdTech)
M-Education Market
Educational Technology (EdTech)
Education Apps Market