
 Higher Education Learning Systems Market | 2026-2036
Higher Education Learning Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Higher Education Learning Systems Market Foresight
A widening capability gap between cloud-native specialists and legacy on-premises vendors is reorganizing competitive dynamics in higher education technology. Blackboard Inc. leverages decades of institutional relationships to sustain installed-base revenue across North American research universities. Instructure Holdings Inc. differentiates through open-source architecture and API extensibility that appeals to technology-forward campuses. Anthology Inc. anchors its position in student information systems integration, creating bundled procurement advantages against point-solution competitors.
Higher education learning systems constitute integrated software platforms that orchestrate course content delivery, student assessment, administrative record-keeping, and learning analytics through web-based interfaces, mobile applications, and cloud infrastructure with sub-second response times for concurrent users exceeding ten thousand. These systems serve the core commercial purpose of reducing instructional delivery costs while expanding enrollment capacity through asynchronous and hybrid modalities. Learning Management Systems command the largest revenue share due to their centrality in every course workflow, while Artificial Intelligence segments within technology are attracting disproportionate R&D investment for automated grading and predictive retention analytics. Cloud-Based Solutions dominate deployment preferences as institutions depreciate aging data center assets, though Hybrid Models persist where FERPA compliance and latency sensitivity constrain full SaaS migration.
FDA oversight of educational software remains limited, but FERPA and HIPAA govern student data handling for health-profession programs, while the EU AI Act imposes risk-classification requirements on automated assessment algorithms used by European institutions. These frameworks compel vendors to maintain parallel compliance architectures, elevating engineering costs for smaller competitors. Stakeholders must monitor whether emerging state-level AI transparency legislation fragments certification requirements beyond federal baselines.
Market Dynamics
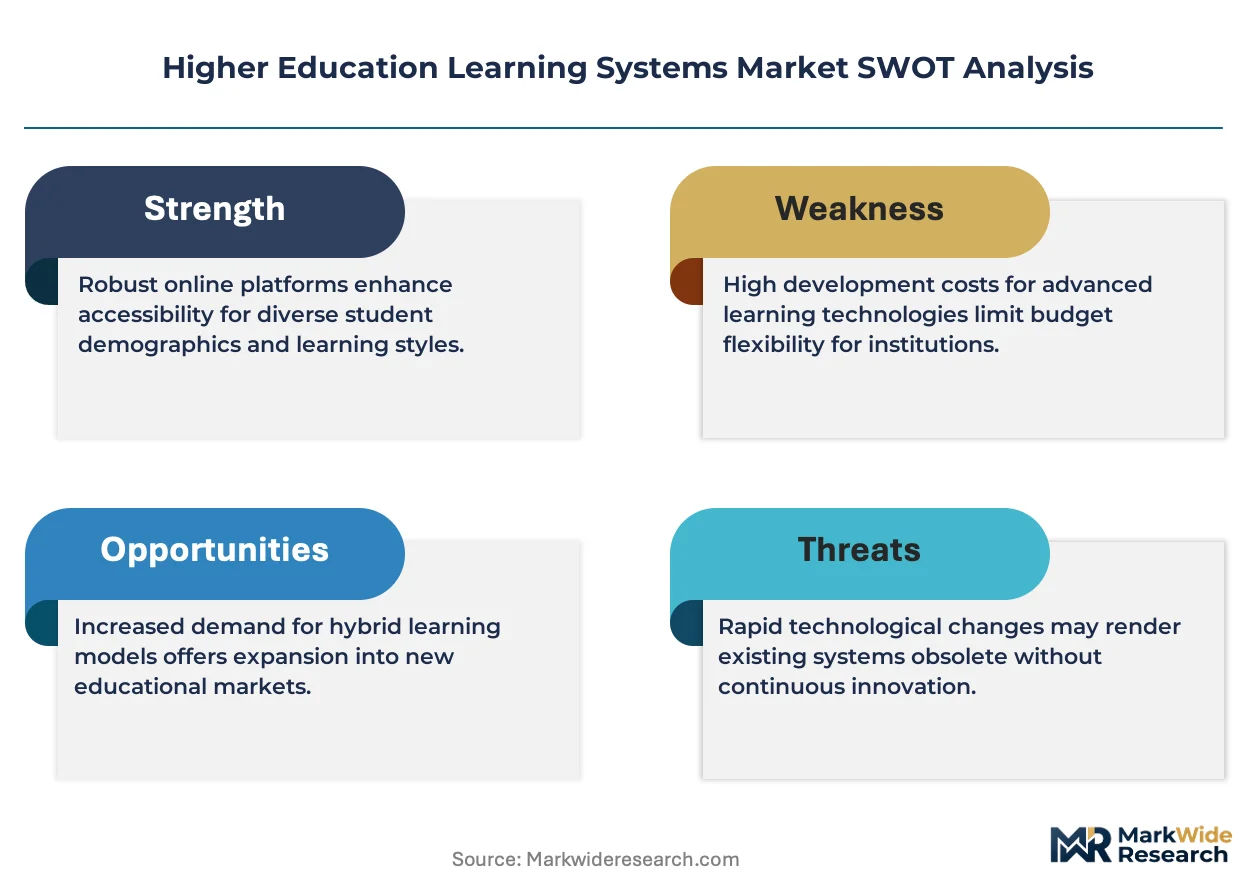
Cloud-native architecture is decomposing the monolithic learning management stack that dominated campus IT for two decades, forcing vendors to rebuild around microservices and API-first design or surrender procurement cycles to agile competitors.
Growth Catalysts
- EU AI Act compliance mandates:European institutions must certify automated assessment algorithms by risk classification, creating certified-vendor preference effects that accelerate platform consolidation.
- Hybrid learning infrastructure buildouts:Research-intensive universities in the United States are procuring synchronous-asynchronous blended systems to expand enrollment capacity without proportional facility expansion.
- Federal research funding requirements:National Science Foundation data management plans now mandate learning analytics interoperability, pulling grant-dependent institutions toward open-API platforms.
Market Restraints
- Parallel compliance architecture costs:Vendors serving both United States and European Union markets must maintain separate FERPA and GDPR technical implementations, elevating engineering overhead disproportionately for mid-tier competitors.
- Data center depreciation timelines:Institutions with recent on-premises capital investments face sunk-cost constraints that delay full SaaS migration despite superior cloud economics.
- Latency-sensitive simulation workloads:Health-profession programs using haptic training modules cannot tolerate cloud round-trip delays, perpetuating hybrid deployment complexity.
Strategic Opportunities
- India's National Education Policy implementation:The country's 2020 framework mandates digital infrastructure across 40,000 colleges, creating procurement volume for scalable cloud-native platforms.
- Generative AI tutoring convergence:Large language models paired with learning analytics engines enable personalized study pathways that differentiate premium platform tiers.
- State-level AI transparency legislation:Emerging disclosure requirements in California and Illinois create first-mover certification advantages for vendors with interpretable algorithmic architectures.
Industry Challenges
- Instructional designer talent scarcity:Pedagogical-technical hybrid roles required for effective platform deployment command salary premiums that strain community college budgets.
- Legacy SIS integration complexity:Student information systems running COBOL-era architectures resist API connectivity, forcing expensive middleware development for unified campus workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Higher Education Learning Systems Market |
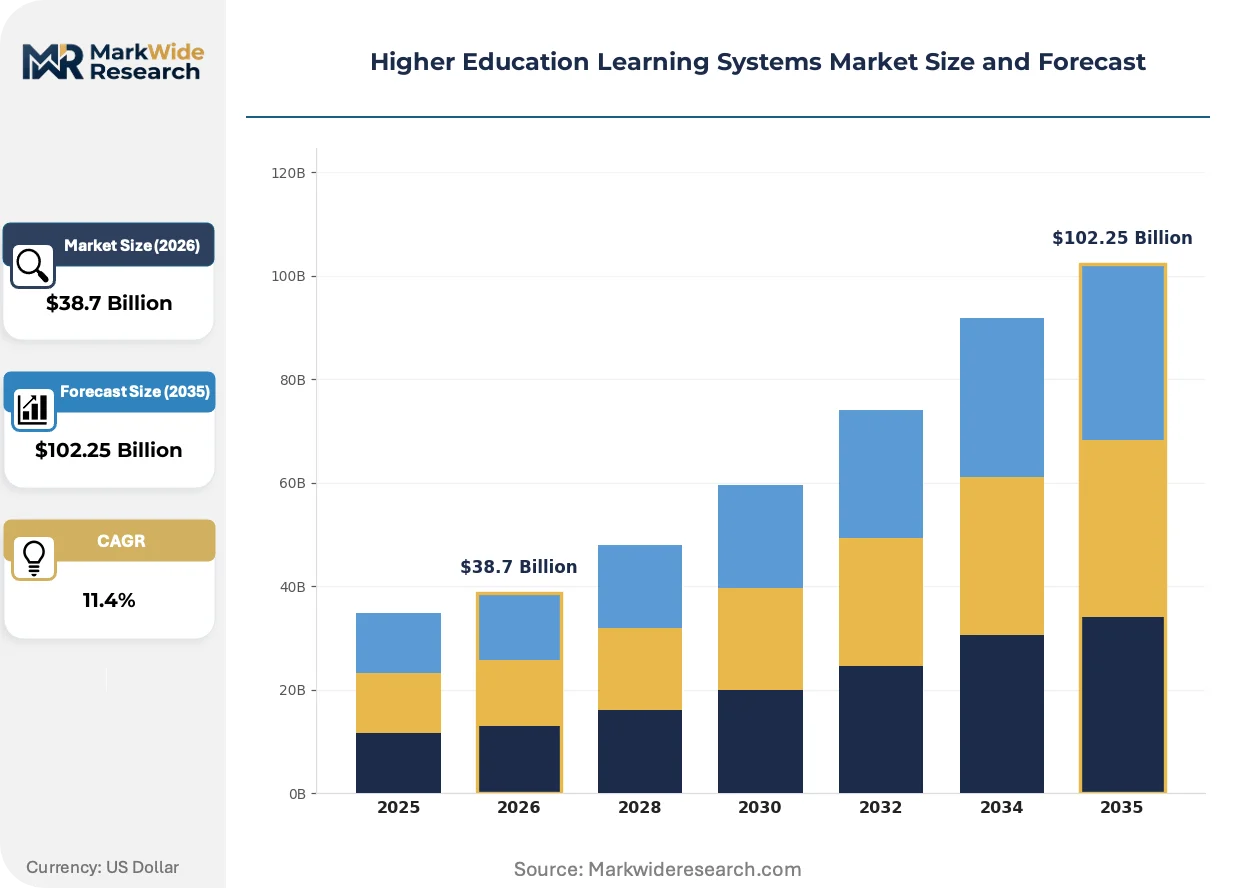
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $102.25 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Learning Management Systems, Virtual Classrooms, Assessment Tools, Collaboration Software End User: Universities, Colleges, Corporate Training, Online Learning Platforms Technology: Cloud-Based Solutions, Mobile Applications, Artificial Intelligence, Analytics Tools Deployment: On-Premises, Hybrid Models, SaaS, Managed Services |
| Companies Covered | Blackboard Inc., Instructure Holdings Inc., Anthology Inc., Ellucian Company L.P., Desire2Learn Corporation, Cornerstone OnDemand Inc., Jenzabar Inc., SAP SE, Workday Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Higher Education Learning Systems Market Shifts & Advancements
Artificial intelligence capabilities are reorganizing competitive advantage around predictive retention and automated feedback loops rather than content repository scale, compressing the traditional LMS feature hierarchy.
Microservices-based learning platforms are decomposing the integrated suite model that Blackboard and Canvas established. Carnegie Mellon and Georgia Tech are piloting componentized architectures where assessment engines, content repositories, and analytics modules interoperate through open standards. This decomposition enables institutions to swap individual components without full-platform displacement, eroding vendor lock-in and compressing switching costs toward zero.
The EU AI Act's risk-classification framework for educational algorithms is restructuring vendor development priorities. Automated essay-scoring systems now face conformity assessment requirements equivalent to medical device software, compelling European deployments to maintain human-in-the-loop architectures. German and French institutions are demanding algorithmic impact documentation that United States campuses rarely require, fragmenting product roadmaps between compliance-heavy and lightweight variants.
Subscription fatigue among procurement officers is shortening platform evaluation cycles from multi-year RFP processes to semester-length pilot programs. Community college systems in Texas and Florida are unbundling learning management from student information systems, selecting point solutions through rapid procurement vehicles. This behavioral shift favors vendors with freemium entry tiers and self-service implementation over traditional enterprise sales models.
Higher Education Learning Systems Market Segmentation
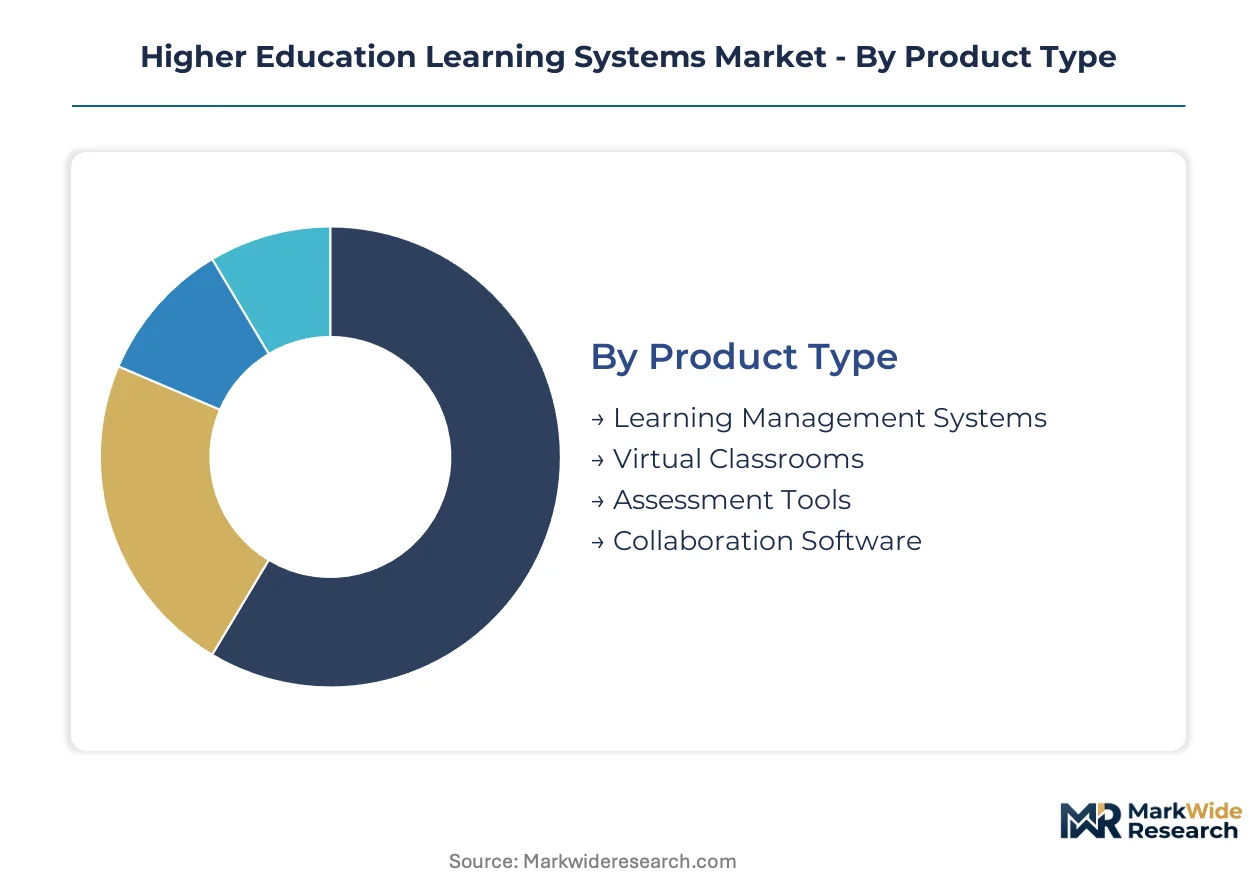
Segmentation in higher education learning systems reveals how procurement priorities diverge across institutional archetypes. Technology-forward research universities favor modular, API-extensible platforms while resource-constrained colleges prioritize bundled solutions with minimal IT overhead.
Product Type:
Substitution pressure from generative AI tutoring tools is compressing margins for traditional content repositories while amplifying demand for assessment and analytics engines.
- Learning Management Systems:Core platforms orchestrating course delivery, gradebooks, and content repositories through web interfaces. Demand concentrates at doctoral-granting institutions in the United States building hybrid learning infrastructure, driven by enrollment expansion mandates without proportional facility investment.
- Virtual Classrooms:Synchronous video conferencing tools with breakout rooms, whiteboarding, and attendance tracking. Adoption clusters among professional schools in Germany and France facing EU AI Act compliance deadlines for remote proctoring algorithms.
- Assessment Tools:Automated grading engines and plagiarism detection systems.
- Collaboration Software:Team workspaces and peer-review platforms for project-based curricula.
Learning Management Systems retain volume leadership; Artificial Intelligence-enabled assessment tools hold the steepest expansion curve.
End User:
Cost tier stratification separates enterprise-grade deployments at research universities from lightweight implementations at community colleges and corporate training divisions.
- Universities:Research-intensive institutions with federated IT governance and grant-compliance requirements. Procurement in the United States emphasizes open-API architectures satisfying National Science Foundation data management mandates.
- Colleges:Two-year and four-year undergraduate institutions with centralized purchasing. Budget constraints in Texas and Florida community college systems are accelerating unbundling of learning management from student information systems.
- Corporate Training:Enterprise learning and development departments.
- Online Learning Platforms:Degree-granting and certificate-focused digital-native institutions.
Universities command the highest per-seat pricing; Online Learning Platforms are gaining share fastest through enrollment scalability.
Technology:
Application maturity varies sharply, with cloud infrastructure now baseline while artificial intelligence capabilities differentiate premium tiers.
- Cloud-Based Solutions:Multi-tenant SaaS architectures with elastic scaling for enrollment spikes. Migration accelerates among United States institutions depreciating on-premises data center assets, though FERPA compliance requirements perpetuate hybrid deployments for health-profession programs.
- Artificial Intelligence:Predictive retention analytics and automated feedback engines. European deployments face EU AI Act risk-classification requirements that United States campuses rarely impose, fragmenting vendor development roadmaps.
- Mobile Applications:Native iOS and Android clients for asynchronous learning.
- Analytics Tools:Learning data warehouses and visualization dashboards.
Cloud-Based Solutions dominate installed base; Artificial Intelligence represents the fastest-growing trajectory for R&D investment.
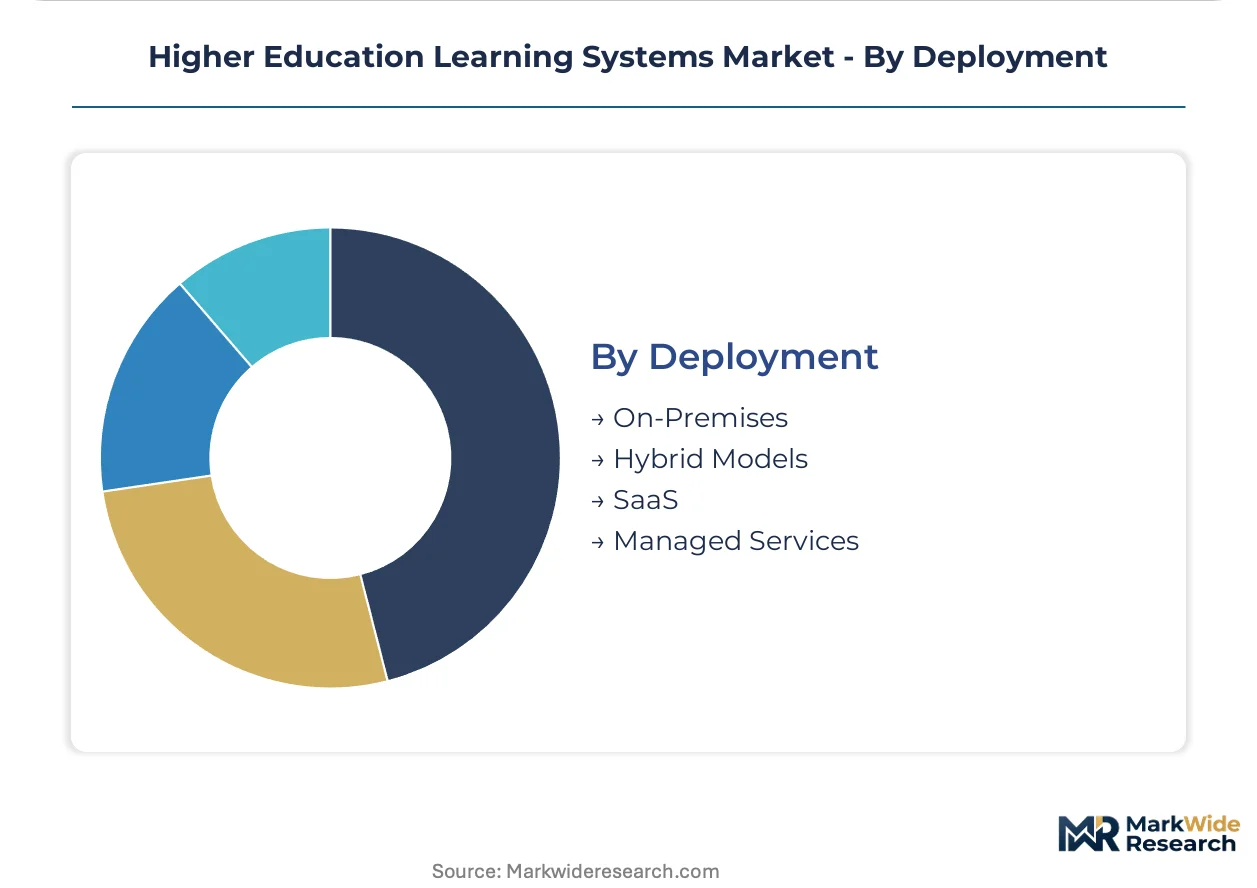
Deployment:
Customer type dictates deployment architecture, with latency-sensitive simulation workloads perpetuating on-premises footprints despite cloud economics.
- SaaS:Fully managed cloud subscriptions with vendor-operated infrastructure. Preference strengthens among United States liberal arts colleges lacking dedicated IT security staff, constrained by FERPA technical safeguards.
- Hybrid Models:Split architectures with cloud orchestration and on-premises data residency. Health-profession programs at Carnegie Mellon and Georgia Tech deploy haptic training modules requiring sub-millisecond response times that cloud round-trip delays cannot satisfy.
- On-Premises:Institution-operated data center installations.
- Managed Services:Vendor-hosted single-tenant environments with custom compliance configurations.
Hybrid Models retain structural importance for regulated programs; SaaS is climbing the fastest among general-education institutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States while European compliance costs compress vendor margins. German institutions pay premium rates for EU AI Act certified platforms. Indian procurement volumes expand fastest through national digital infrastructure mandates.
United States
Research-intensive universities in Massachusetts and California drive hybrid learning infrastructure procurement at premium price points. National Science Foundation data management plans mandate open-API interoperability, pulling grant-dependent institutions toward extensible platforms. The Boston-Cambridge cluster anchors demand for AI-enabled assessment tools with FERPA technical safeguards.
Germany
Technical universities in Bavaria and Baden-Württemberg prioritize automated assessment algorithms with EU AI Act conformity documentation. The country's national data protection regulator enforces GDPR technical implementation standards that elevate vendor engineering costs. Munich and Stuttgart host concentrated procurement from automotive engineering programs requiring simulation-integrated learning systems.
France
Grandes écoles and public universities accelerate cloud migration under the national digital education strategy. The country's national data protection authority imposes algorithmic impact assessment requirements beyond baseline EU standards. The Paris-Saclay cluster concentrates demand for research data management platforms with learning analytics interoperability.
India
Implementation of the 2020 National Education Policy drives procurement across 40,000 colleges for scalable cloud-native platforms. The Bureau of Indian Standards develops technical specifications for educational software data security. Karnataka and Telangana host the fastest-growing adoption clusters among technology institutes building hybrid delivery capacity.
United Kingdom
Russell Group universities prioritize AI-enabled retention analytics amid enrollment pressure and international student recruitment competition. The Information Commissioner's Office enforces GDPR-derived standards for student data processing in post-Brexit alignment. The Golden Triangle of Oxford, Cambridge, and London concentrates demand for research-integrated learning infrastructure.
Higher Education Learning Systems Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a bifurcated competitive structure. Cloud-native specialists command premium pricing through API extensibility and microservices architecture, while legacy platform vendors defend position through installed-base relationships and bundled student information system integration. The market consolidates around three strategic archetypes: open-source extensibility providers, vertically integrated suite vendors, and point-solution specialists. Dominant competitive moves include strategic partnerships for interoperability certification and portfolio diversification into adjacent student success analytics.
Within the open-source extensibility tier, Instructure Holdings Inc. exemplifies architecture-first positioning that appeals to technology-forward campuses with federated IT governance. Blackboard Inc. and Anthology Inc. anchor the integrated suite segment, representing decades of institutional relationship depth and bundled procurement advantages against point-solution competitors. These three companies occupy positions that illustrate the market's structural tension between modular flexibility and unified workflow consolidation.
| Leading Market Players |
|---|
| Blackboard Inc. |
| Instructure Holdings Inc. |
| Anthology Inc. |
| Ellucian Company L.P. |
| Desire2Learn Corporation |
| Cornerstone OnDemand Inc. |
| Jenzabar Inc. |
| SAP SE |
| Workday Inc. |
| Others |
Supply & Pricing Matrix
Ninety-day implementation cycles for cloud-native learning platforms compress procurement timelines while amplifying vendor pricing power through certified-compliance scarcity. This lead-time compression concentrates margin capture among EU AI Act-certified providers serving European institutions, while forcing mid-tier competitors into price-dilutive customization contracts to retain United States research university accounts.
Pricing Analysis
Configured-to-order pricing for FERPA-compliant hybrid deployments commands spreads exceeding standard SaaS tiers by factors tied to data residency architecture and algorithmic audit documentation. Subscription structures dominate with seat-based annual contracts, though algorithmic certification grade and institutional enrollment scale differentiate realized rates. Cost compression in mid-market community college segments intensifies because procurement officers unbundle learning management from student information systems, while research universities exhibit lowest price sensitivity due to grant-funded infrastructure mandates.
Supply Chain Analysis
Port congestion at Los Angeles-Long Beach and Rotterdam elevates inbound logistics costs for server hardware destined to on-premises data centers at health-profession programs. Supply concentrates in the United States, Ireland, and India for cloud infrastructure, with Taiwan and South Korea anchoring semiconductor components for AI inference accelerators. Single-source vulnerability rests on NVIDIA GPU allocation for automated grading engines, while distribution runs through direct enterprise sales teams supplemented by regional systems integrators for legacy SIS middleware.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Higher education learning systems are approaching a platform-economics inflection as microservices decomposition erodes vendor lock-in and API interoperability becomes the primary procurement filter. This shift rewards ecosystem orchestrators over monolithic suite providers.
For Market Incumbents: Shield installed-base revenue through embedded student information system integration at community college systems in Texas and Florida, where unbundling pressure threatens point-solution displacement. Prioritize certification investment for EU AI Act high-risk algorithm categories to maintain pricing power in German and French technical universities. For New Entrants and Emerging Players: Differentiate on interpretable AI architectures that satisfy emerging state-level transparency mandates in California and Illinois ahead of incumbent compliance roadmaps. Target India's National Education Policy implementation wave with freemium cloud-native platforms scalable across 40,000 colleges, deploying through self-service implementation to bypass entrenched enterprise sales cycles. For Investors and Strategic Acquirers: Carve-out targets emerge from legacy ERP parents seeking to divest education-focused software divisions amid portfolio streamlining pressures. Long-term viability centers on API-extensible architectures capable of componentized procurement; monitor National Science Foundation data management plan enforcement as the signal indicating acceleration toward open-standard platforms over proprietary suites.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Certification Investment | Conformity assessment for automated assessment algorithms unlocks procurement preference at German technical universities. |
| Microservices Platform Integration | Componentized architecture enables Carnegie Mellon and Georgia Tech to swap assessment engines without full-platform displacement. |
| Strategic Partnership with SIS Vendors | API connectivity with Ellucian and Jenzabar systems creates bundled procurement advantages against point-solution competitors. |
| Acquisition of Specialist Firm | Predictive retention analytics engines complement core learning management platforms with differentiated AI capabilities. |
| Geographic Expansion | Karnataka and Telangana technology institutes in India offer fastest-growing adoption clusters for hybrid delivery infrastructure. |
Research Methodology
Initial hypotheses were tested against primary input from chief information officers, instructional technology directors, procurement officers at research universities, and learning analytics specialists, then refined through secondary validation. Primary fieldwork encompassed CTOs at doctoral-granting institutions in Massachusetts and California, platform engineers at cloud-native vendors, and integration specialists managing legacy SIS connectivity. Secondary sources included SEC filings from publicly traded education technology firms, EDUCAUSE infrastructure survey data, National Science Foundation grant documentation, and EU AI Act implementation guidance from European data protection regulators. Bottom-up enrollment projections and top-down IT spending allocations were triangulated against vendor-reported subscription metrics.
Variance decomposition across the projection horizon isolates enrollment growth, cloud migration velocity, and regulatory compliance cost pass-through as distinct drivers. Segmentation dimensions modeled encompass deployment architecture, institutional Carnegie classification, integration complexity with existing campus systems, and regional regulatory framework. CAGRs were derived from logistic diffusion curves fitted to historical SaaS adoption patterns and adjusted for FERPA technical safeguard implementation timelines. AI capability penetration and hybrid learning infrastructure buildout intensity served as industry-specific forecast inputs.
Material uncertainties — state-level AI transparency legislation fragmentation, federal research funding volatility, and instructional designer talent scarcity — sit outside the modeled envelope. Forecasts reflect assumptions about procurement cycle normalization and compliance architecture cost trajectories. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Educational Technology (EdTech)
Education Apps Market
Educational Technology (EdTech)
Artificial Intelligence (AI) in Education Market
Educational Technology (EdTech)
Global Edutainment Centers Market
Educational Technology (EdTech)
Education Security Market
Educational Technology (EdTech)
Edtech and Smart Classroom Market
Educational Technology (EdTech)
Global Adaptive Learning Market
Educational Technology (EdTech)
Virtual Schools Market
Educational Technology (EdTech)
Edutainment Market
Educational Technology (EdTech)
Blockchain in Edutech Market
Educational Technology (EdTech)
Smart Education and Learning Market
Educational Technology (EdTech)
Smart Education System Market
Educational Technology (EdTech)
Virtual Reality in Education Market
Educational Technology (EdTech)
Higher Education Technology Market
Educational Technology (EdTech)
Digital Badges Market
Educational Technology (EdTech)
Child Care Software Market
Educational Technology (EdTech)
Global Smart Classroom Market