
 Augmented Reality (AR) Market | 2026-2036
Augmented Reality (AR) Market Size, Share, and Industry Trends Forecast 2026-2036
Augmented Reality (AR) Market Analysis
Asian optical component manufacturing is hardening as the backbone of AR headset supply chains. Meta leverages its social platform ecosystem to anchor consumer-facing spatial computing distribution. Magic Leap sustains deep R&D intensity in enterprise-grade photonics, while Xreal competes aggressively on price-performance in tethered smart glasses for gaming and media consumption.
Augmented Reality overlays computer-generated imagery, spatial audio, and haptic feedback onto the physical world through optical see-through or video see-through displays, typically requiring sub-20 millisecond motion-to-photon latency to prevent user discomfort. Its primary commercial purpose spans real-time task guidance, remote collaboration, and immersive training across industrial and service workflows. Healthcare applications currently lead enterprise deployment, with surgical navigation and medical education driving premium headset procurement. Smart glasses as a device category are growing fastest among consumer segments, fueled by lighter form factors and smartphone tethering that reduces onboard compute costs.
The FDA oversees software-as-medical-device classifications for AR diagnostic overlays, while the EU AI Act imposes risk-tiered conformity assessments on biometric inference systems embedded in smart glasses. FCC spectrum allocations for millimeter-wave and Wi-Fi 6E directly shape untethered headset performance thresholds in the United States. Stakeholders must monitor how evolving electromagnetic exposure standards and data privacy rulings from the FTC and state attorneys general will constrain always-on camera and sensor architectures.
Market Dynamics
Enterprise manufacturing workflows are absorbing AR-guided assembly systems at scale, compressing deployment timelines from pilot programs to production floor integration within single fiscal cycles. This acceleration reflects pressure from labor shortages and quality consistency mandates rather than experimental technology appetite.
Growth Catalysts
- EU AI Act Conformity Pathways:Risk-tiered assessment frameworks for biometric inference systems are creating clarity for medical device developers, accelerating regulatory submissions for surgical navigation overlays.
- Defense contracting channels:Pentagon procurement offices are channeling multi-year commitments into head-worn display R&D, stabilizing volume forecasts for domestic photonics suppliers.
- Wi-Fi 6E spectrum allocation:FCC millimeter-wave licensing is enabling untethered headset architectures with sub-20 millisecond latency, removing cable constraints from industrial floor deployments.
Market Restraints
- Compound semiconductor supply concentration:Gallium arsenide and indium phosphide substrate fabrication clusters in Taiwan and South Korea create single-source vulnerability for waveguide illumination engines.
- FDA software-as-medical-device validation:Diagnostic overlay classifications require 18-24 month premarket review cycles, freezing feature iteration timelines for healthcare developers.
- Smartphone-tethered substitution:Lightweight smart glasses streaming compute from handsets are capturing price-sensitive gaming segments, compressing margins for standalone headset architectures.
Strategic Opportunities
- India PLI scheme incentives:Production-linked subsidies for electronics manufacturing are attracting optical component assembly investments, diversifying supply chain geography beyond East Asian concentration.
- Remote assistance-as-a-service models:Industrial equipment vendors are unbundling AR support from hardware sales, creating recurring revenue streams through subscription-based expert access.
- 5G network slicing convergence:Guaranteed bandwidth partitions for industrial AR are enabling real-time holographic collaboration between field technicians and centralized engineering teams.
Industry Challenges
- Photonics systems integration talent scarcity:Optical design, waveguide physics, and thermal management expertise pools remain shallow relative to deployment demand, inflating compensation costs for specialized engineering roles.
- Legacy ERP integration friction:Manufacturing execution systems built on 1990s architectures require custom middleware development to ingest spatial computing data streams, extending implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Augmented Reality (AR) Market |
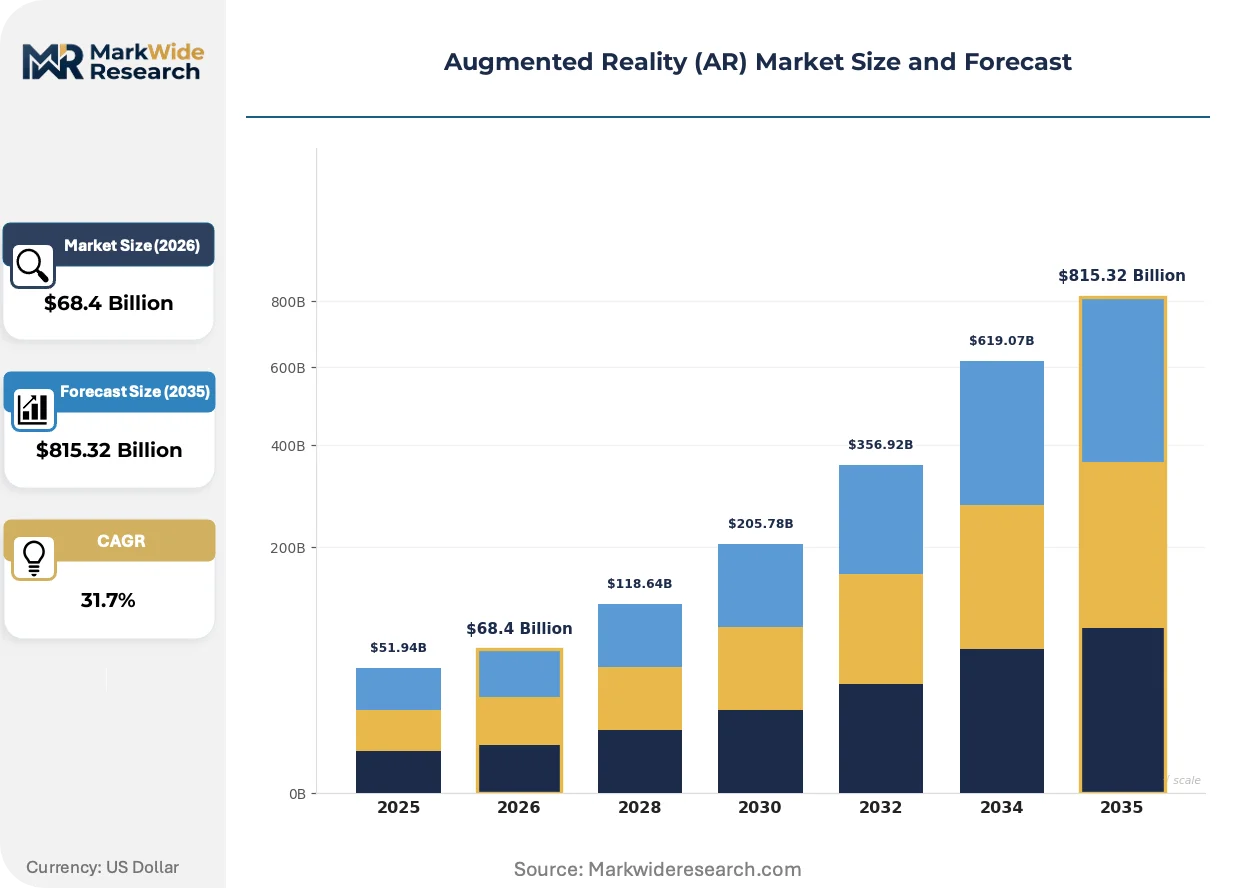
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $815.32 Billion |
| CAGR (2026 – 2036) | 31.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Retail, Healthcare, Education, Entertainment Device Type: Smart Glasses, Mobile Devices, Headsets, Wearable Technology Technology: Marker-Based, Markerless, Projection-Based, Superimposition End User: Consumers, Enterprises, Educational Institutions, Government |
| Companies Covered | Magic Leap, Xreal, Meta, Marxent, Groove Jones, Snap Inc., Treeview, Quytech, Niantic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Augmented Reality (AR) Market Emerging Trajectories
Spatial computing hardware is bifurcating into enterprise-grade precision systems and consumer-accessible tethered devices, with each trajectory demanding distinct optical architectures and software stacks. This divergence is compressing development resource allocation decisions across the vendor base.
Silicon carbide waveguide substrates are absorbing thermal load from high-brightness micro-LED arrays, enabling brighter field-of-view performance without active cooling penalties. Automotive head-up display suppliers are adopting these materials for next-generation windshield projection systems. The technology is absorbing market share from legacy LCoS illumination engines in premium industrial headsets.
EU MDR Article 10 software validation requirements are tightening documentation burdens for AR surgical planning tools, forcing developers to restructure quality management systems around IEC 62304 medical device software standards. German notified bodies are experiencing 40% application volume increases, extending certification queue lengths. Class IIa device manufacturers are responding by front-loading clinical evidence collection in early development phases.
Industrial buyers are consolidating vendor relationships around full-stack spatial computing providers capable of delivering hardware, proprietary software, and implementation services under unified contracts. Distributor networks specializing in discrete IT hardware are losing relevance as direct enterprise sales teams capture procurement decision authority. This pattern is most visible in United States automotive manufacturing, where tier-one suppliers are bypassing traditional channel partners for OEM-direct AR deployment programs.
Augmented Reality (AR) Market Segmentation
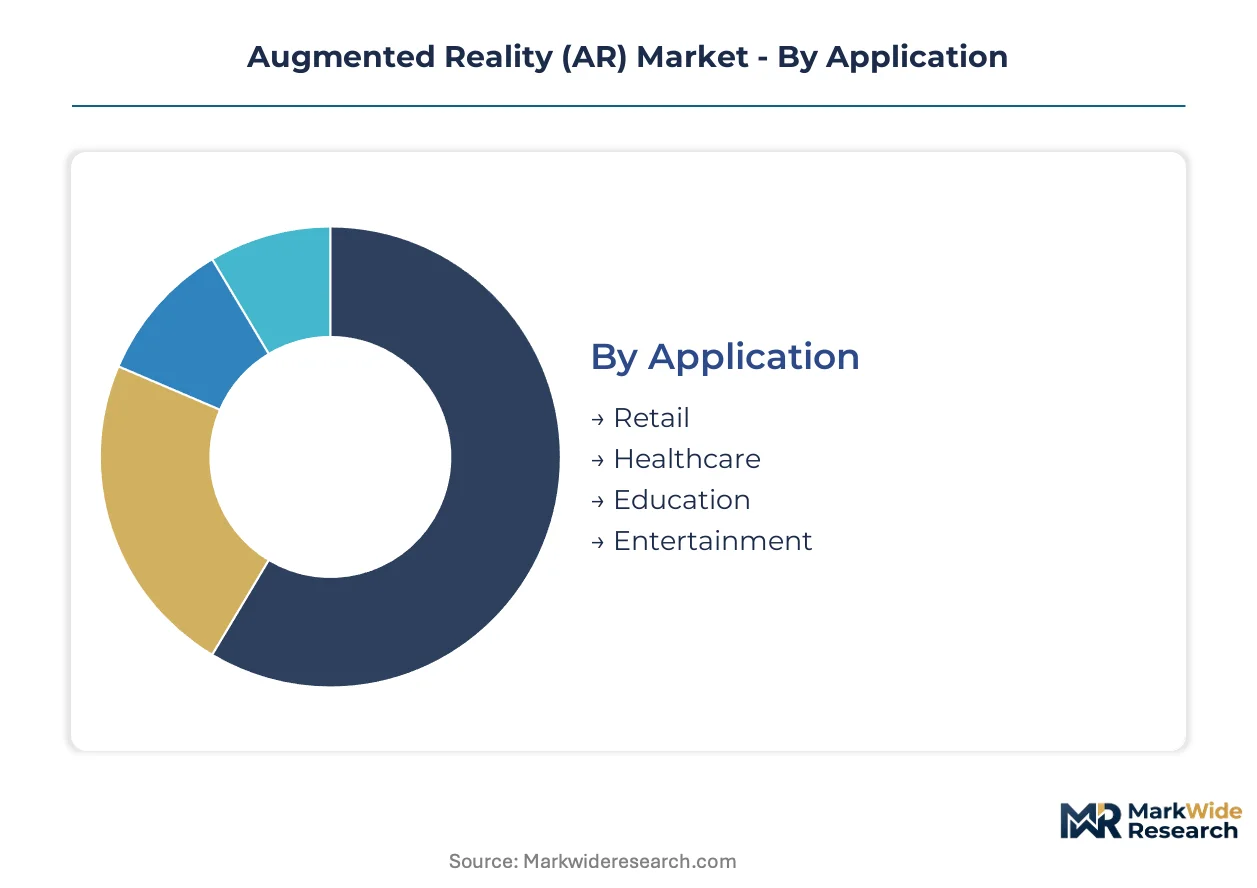
AR market segmentation reveals how optical architectures and compute distribution strategies fragment across use cases. Each axis—application, device, technology, and buyer type—carries distinct margin profiles and regulatory exposure that shape vendor resource allocation.
Application:
Optical precision requirements and latency tolerances diverge sharply across vertical deployments, creating specialized hardware procurement patterns.
- Healthcare:Surgical navigation overlays demand sub-10 millimeter spatial accuracy and FDA software-as-medical-device validation. United States hospital systems are consolidating procurement around integrated hardware-software platforms that bundle liability coverage with technical support.
- Entertainment:Gaming and immersive media prioritize field-of-view breadth over positional precision, with smartphone-tethered smart glasses capturing price-sensitive demand in living-room and mobile contexts.
- Retail:Virtual try-on and spatial merchandising applications favor cloud-rendered graphics streamed to lightweight endpoints.
- Education:Medical training and technical vocational programs require durable hardware with shared sterilization protocols.
Healthcare leads on scale; entertainment leads on momentum.
Device Type:
Form factor economics determine whether compute resides on-head or remains tethered to external processors, with direct implications for bill-of-materials composition.
- Smart Glasses:Smartphone-tethered architectures offload rendering and thermal management to pocketed handsets, enabling sub-80 gram designs that bypass active cooling. United States consumer electronics retailers are expanding shelf space for these devices as prescription lens integration matures.
- Headsets:Fully untethered systems with onboard Snapdragon XR processors serve industrial floor deployments where cable snag hazards violate OSHA safety protocols.
- Mobile Devices:Tablet and handset AR through camera passthrough dominates education procurement due to existing device management infrastructure.
- Wearable Technology:Smart contact lenses and haptic vests remain pre-commercial, with regulatory pathways through FDA and FCC still unresolved.
Smart glasses dominate volume expansion; headsets command premium pricing power.
Technology:
Tracking methodology selection locks developers into specific sensor fusion stacks and content authoring pipelines with multi-year switching costs.
- Markerless:Simultaneous localization and mapping through depth cameras and visual-inertial odometry enables arbitrary environment deployment without physical infrastructure preparation. Enterprise manufacturing workflows in automotive assembly plants favor this approach for flexibility across reconfigurable production lines.
- Marker-Based:Printed fiducial tracking delivers centimeter-grade stability at minimal compute cost, sustaining relevance in fixed-installation museum and retail deployments.
- Projection-Based:Spatial light modulators project imagery directly onto physical surfaces without user-worn optics, finding niche adoption in automotive head-up displays.
- Superimposition:Object recognition-driven replacement of real-world elements with virtual counterparts serves medical education and architectural visualization.
Markerless systems anchor new deployment growth; marker-based retains installed base stability.
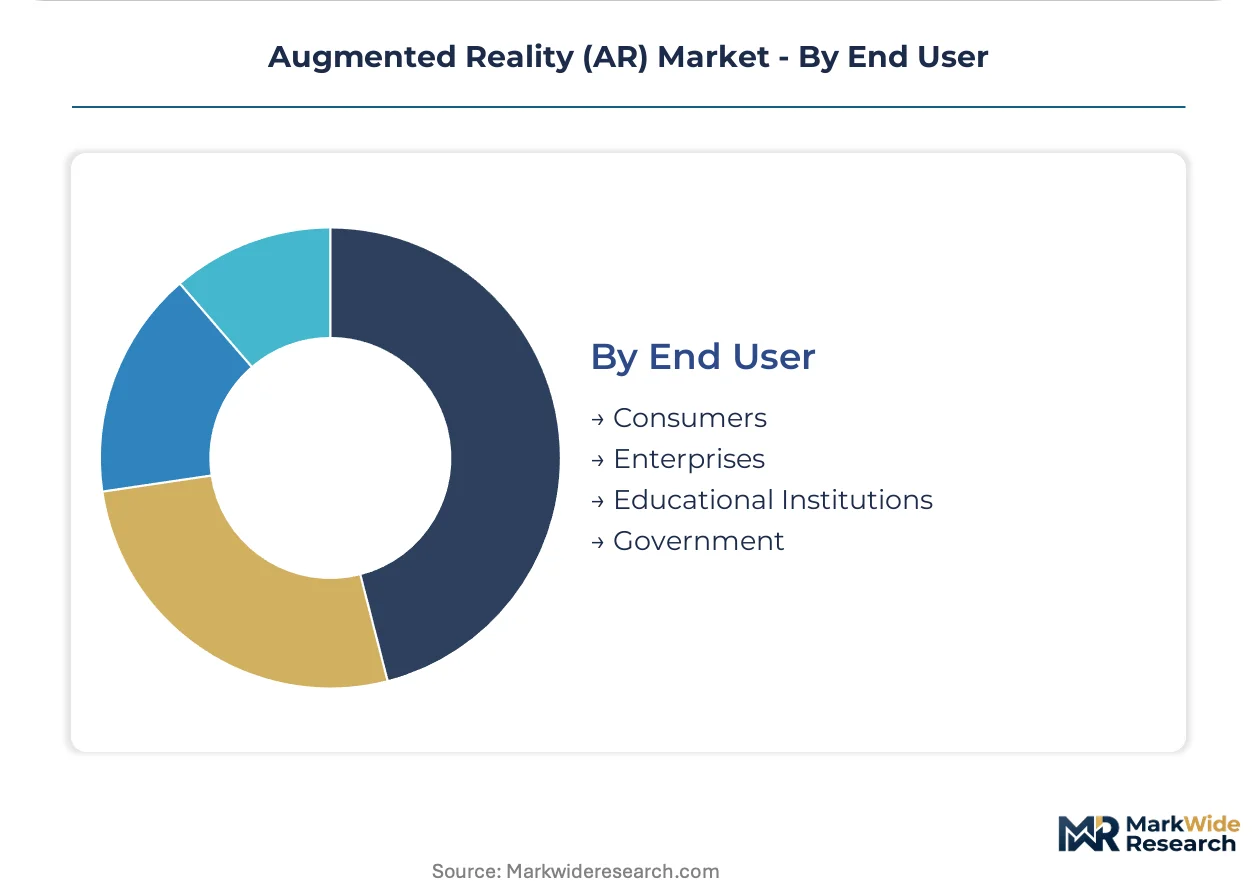
End User:
Budget cycles and procurement authority structures fragment the addressable market across fundamentally different sales motion requirements.
- Enterprises:Manufacturing, logistics, and field service organizations deploy AR for task guidance and remote expert access, with procurement centralized through IT and operational technology convergence committees. United States defense contractors are channeling multi-year R&D commitments into head-worn display development.
- Consumers:Individual purchasers prioritize aesthetic discretion and social acceptability, driving demand toward eyewear-industrial-design partnerships.
- Educational Institutions:K-12 and university procurement flows through district-level technology coordinators with extended evaluation timelines.
- Government:Municipal and federal agencies require TAA-compliant supply chains and Section 508 accessibility certification.
Enterprises concentrate revenue concentration; consumers are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redistributing AR hardware assembly toward jurisdictions with streamlined electronics certification pathways. Taiwan and South Korea maintain photonics substrate dominance, while India and Vietnam attract final assembly through production-linked incentives that offset East Asian labor cost premiums.
United States
Pentagon procurement offices channel multi-year R&D commitments into head-worn display development, stabilizing volume forecasts for domestic photonics suppliers. FDA software-as-medical-device classifications for surgical navigation overlays impose 18-24 month validation cycles that freeze feature iteration timelines. Greater Boston and Silicon Valley clusters concentrate enterprise AR startups targeting healthcare IT and defense contracting channels.
China
MIIT standards for millimeter-wave device certification and GB compliance frameworks shape domestic headset performance thresholds. NMPA oversight of AR diagnostic overlays parallels FDA pathways but with accelerated review timelines for Class II devices. Shenzhen and Dongguan manufacturing corridors dominate optical component assembly, though Yangtze River Delta facilities are absorbing premium micro-LED backend processes.
Germany
Automotive OEMs in Bavaria and Baden-Württemberg deploy AR-guided assembly systems for electric vehicle powertrain integration, compressing supplier qualification timelines. EU MDR Article 10 software validation requirements and notified body queues extending 40% above historical baselines force developers to front-load clinical evidence collection. Berlin-Brandenburg hosts enterprise software vendors specializing in industrial IoT-AR convergence.
South Korea
Samsung and LG display divisions anchor gallium arsenide substrate fabrication for waveguide illumination engines, creating single-source vulnerability for global headset supply chains. MFDS medical device software guidelines align with IEC 62304 standards, enabling parallel regulatory submissions with EU notified bodies. Seoul Capital Area concentrates R&D intensity for tethered smart glasses targeting gaming and media consumption segments.
India
PLI scheme incentives for electronics manufacturing attract optical component assembly investments, diversifying supply chain geography beyond East Asian concentration. CDSCO medical device rules for software-based diagnostics remain in formative stages, creating regulatory lag for healthcare AR developers. Karnataka and Tamil Nadu host emerging design centers for smartphone-tethered AR applications serving price-sensitive consumer segments.
Augmented Reality (AR) Market Vendor Landscape
United States technology conglomerates anchor one tier through social platform distribution and defense contracting channels; Chinese and Korean specialists hold manufacturing scale advantages in optical component fabrication. The vendor base stratifies across enterprise-grade precision systems and consumer-accessible tethered devices, with each trajectory demanding distinct capital allocation patterns. Three archetypes dominate: full-stack spatial computing providers, optical component specialists, and software-platform aggregators. Competitive dynamics center on strategic partnerships with automotive OEMs and healthcare systems, plus backward integration into photonics substrate supply.
Within the full-stack enterprise tier, Magic Leap and Meta exemplify divergent strategic postures—one sustaining deep R&D intensity in photonics, the other leveraging social platform ecosystem lock-in for consumer distribution. Xreal occupies a position on the price-performance vector for tethered smart glasses, competing aggressively against smartphone-integrated camera-passthrough solutions. These three anchors illustrate how vendor resource allocation fractures across optical architecture choices and compute distribution strategies.
| Leading Market Players |
|---|
| Magic Leap |
| Xreal |
| Meta |
| Marxent |
| Groove Jones |
| Snap Inc. |
| Treeview |
| Quytech |
| Niantic |
| Others |
Supply Flow & Price Mechanics
Enterprise procurement consolidation around full-stack spatial computing providers is compressing distributor margins and forcing optical component suppliers to absorb certification cost burdens or cede volume to vertically integrated OEMs. This demand-side pressure reshapes how Taiwan and South Korean substrate fabricators negotiate long-term offtake agreements with headset manufacturers.
Pricing Analysis
Distributor margins in industrial AR hardware have compressed from traditional IT channel norms as direct enterprise sales teams capture procurement authority from specialized hardware resellers. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated surgical navigation systems from OSHA-compliant factory floor headsets and smartphone-tethered consumer smart glasses. Price differentiation rests on certification grade and after-sales service bundling rather than raw optical performance. Healthcare systems exhibit lowest price sensitivity due to liability coverage requirements, while education procurement shows acute sensitivity to per-unit capital expenditure limits.
Supply Chain Analysis
Reverse-logistics flows for AR headsets remain underdeveloped, with enterprise customers demanding refurbishment programs for premium devices while consumer channels lack standardized battery replacement or waveguide repair infrastructure. Gallium arsenide and indium phosphide substrate fabrication concentrates in Taiwan and South Korea, creating single-source vulnerability for waveguide illumination engines. Raw material dependencies include rare-earth phosphors, precision glass substrates, and high-brightness micro-LED dies. Distribution runs through direct OEM sales for enterprise contracts and consumer electronics retailers for tethered smart glasses, with logistics chokepoint exposure concentrated in Shanghai-Shenzhen maritime corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Defense contracting stability and healthcare IT modernization create a stable compounding foundation for AR market expansion, with multi-year R&D commitments insulating volume forecasts from consumer electronics cyclicality.
For Market Incumbents: Lock in photonics substrate supply through long-term offtake agreements with Taiwan and South Korean fabricators before gallium arsenide capacity constraints intensify. Deepen backward integration into waveguide manufacturing to defend margin position against smartphone-tethered substitution eroding standalone headset pricing power. Prioritize FDA 510(k) pathway investments to freeze out feature-iteration competitors in surgical navigation segments. For New Entrants and Emerging Players: EU AI Act conformity pathways in Germany and France open a window for biometric inference specialists to capture medical device software contracts from legacy hardware vendors lacking risk-tiered assessment expertise. Target India PLI scheme incentives for optical component assembly serving price-sensitive tethered smart glasses demand in Karnataka and Tamil Nadu education procurement. Lead with 5G network slicing partnerships to differentiate real-time holographic collaboration offerings from cable-constrained industrial incumbents. For Investors and Strategic Acquirers: Asymmetric upside sits with full-stack spatial computing providers capable of bundling hardware, proprietary software, and implementation services under unified enterprise contracts. Five-to-ten year viability favors vendors with captive photonics R&D and established healthcare system relationships over pure-play software aggregators. Monitor FDA software-as-medical-device premarket review queue lengths as inflection indicator for healthcare AR feature velocity and competitive moat durability.| Strategic Initiative | Industry Significance |
|---|---|
| Photonics Substrate Backward Integration | Captive gallium arsenide supply insulates waveguide costs from Taiwan-South Korea concentration risk. |
| FDA 510(k) Software Validation | Premarket clearance for surgical navigation overlays locks in multi-year hospital system procurement cycles. |
| 5G Network Slicing Partnership | Guaranteed bandwidth partitions enable untethered industrial deployments with sub-20 millisecond latency. |
| India PLI Manufacturing Footprint | Production-linked subsidies attract optical assembly investments diversifying beyond East Asian supply chains. |
| Remote Assistance-as-a-Service Launch | Subscription expert access unbundled from hardware sales creates recurring revenue in industrial equipment support. |
Methodological Framework
Bottom-up enterprise deployment modeling reconciled against top-down optical component supply tracking forms the analytical core of this study. Primary interviews with AR hardware procurement officers at automotive OEMs, biomedical engineers at United States hospital systems, and photonics R&D directors at Taiwan substrate fabricators combined with secondary validation from FDA 510(k) filings, EU MDR notified body queue data, and Pentagon R&D budget disclosures. Triangulation across these sources ensures volume estimates for surgical navigation, factory floor assembly, and defense applications reflect actual procurement authority structures rather than vendor shipment claims.
Input-output matrices map micro-LED die supply, waveguide substrate availability, and Snapdragon XR processor allocation against modeled demand across healthcare, manufacturing, and consumer segments throughout the forecast period. Segmentation dimensions include application vertical, device form factor, tracking methodology, and end-user procurement type. CAGRs derive from logistic diffusion curves fitted to enterprise pilot-to-production transition timelines and consumer tethered-glasses adoption patterns. Industry-specific inputs encompass FCC spectrum allocation rulings, EU AI Act implementation guidance, and India PLI scheme disbursement schedules.
Revisions become necessary when FDA software-as-medical-device review timelines extend beyond historical baselines, when gallium arsenide substrate fabrication capacity constraints trigger allocation rationing, or when 5G network slicing commercialization lags behind industrial AR latency requirements. Practitioners should monitor EU MDR notified body queue lengths, Taiwan semiconductor equipment import data, and Pentagon head-worn display procurement award announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Virtual Reality (VR) and Augmented Reality (AR)
Global VR for Medical Market
Virtual Reality (VR) and Augmented Reality (AR)
VR Headsets Market
Virtual Reality (VR) and Augmented Reality (AR)
Italy Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
Mixed Reality Headsets Market
Virtual Reality (VR) and Augmented Reality (AR)
Neuro-Gaming Technology Market
Virtual Reality (VR) and Augmented Reality (AR)
US Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Virtual Mobile Infrastructure Market
Virtual Reality (VR) and Augmented Reality (AR)
AR Glasses Market
Virtual Reality (VR) and Augmented Reality (AR)
Augmented Reality (AR) Glasses Market
Virtual Reality (VR) and Augmented Reality (AR)
UK Virtual Tour Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality in Retail Market
Virtual Reality (VR) and Augmented Reality (AR)
AR Collaboration Software Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual and Augmented Reality in Tourism Market
Virtual Reality (VR) and Augmented Reality (AR)
Internet of Senses Market
Virtual Reality (VR) and Augmented Reality (AR)
Automotive Augmented Reality (AR) HUD System Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality for Consumer Market