
 Asia-Pacific Virtual Reality Market | 2026-2036
Asia-Pacific Virtual Reality Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Virtual Reality Market Outlook
Standalone chipset architecture is tilting development away from PC-tethered systems toward all-in-one headsets with onboard spatial computing. HTC Corporation leverages its early Vive ecosystem to sustain premium enterprise channel control across Taiwanese and Japanese medical verticals. Sony Corporation anchors console-integrated VR through PlayStation hardware dominance in Japanese and South Korean living rooms. ByteDance competes aggressively on price-performance ratios for mass-consumer headsets distributed through Chinese e-commerce channels.
Virtual reality denotes computer-generated immersive environments rendered through stereoscopic displays with sub-20ms motion-to-photon latency, employing inside-out tracking via embedded cameras and inertial measurement units to enable six-degrees-of-freedom positional interaction. The technology serves commercial purposes spanning procedural training, architectural visualization, remote collaboration, and therapeutic intervention. Hardware claims the dominant revenue share due to headset, controller, and sensor component manufacturing scale, though haptic feedback technology within the technology dimension attracts disproportionate R&D allocation from Japanese and South Korean component suppliers. Content remains structurally constrained by production cost barriers, while training applications within the application dimension yield the highest per-seat enterprise pricing and renewal rates.
China's MIIT enforces GB standards for electromagnetic compatibility and optical safety in head-mounted displays, effectively filtering low-quality imports from non-compliant vendors. Japan's METI promotes VR adoption through digital transformation subsidies tied to JIS standards conformance for industrial training systems. South Korea's MFDS regulates software-as-medical-device classifications for therapeutic VR applications, creating differentiated compliance pathways for healthcare entrants. Stakeholders must monitor how divergent national certification regimes fragment cross-border content licensing and hardware interoperability standards across the region.
Market Dynamics
Standalone chipset architecture is collapsing the tethered PC-VR supply chain, forcing component suppliers to reconfigure around all-in-one spatial computing platforms. This structural shift redistributes value capture from GPU manufacturers to SoC designers and sensor integrators across the Asia-Pacific manufacturing corridor.
Growth Catalysts
- MIIT GB Standards:China's electromagnetic compatibility and optical safety mandates for head-mounted displays are filtering low-quality imports and accelerating domestic hardware quality benchmarks.
- Surgical Training:Healthcare providers in Japan and South Korea are expanding VR deployment for procedural training and patient rehabilitation applications.
- Shenzhen-Shanghai Clusters:Concentrated headset production and content development capabilities in China's eastern manufacturing corridor are compressing development cycles.
Market Restraints
- Display Panel Concentration:OLED and micro-OLED supply concentrates among South Korean and Japanese panel makers, creating input cost volatility for mid-tier headset assemblers.
- Content Production Costs:Photorealistic immersive content requires specialized pipelines and talent pools that remain structurally scarce across the region.
- Cross-Border Certification Friction:Divergent national regimes for software-as-medical-device classification fragment content licensing and hardware interoperability standards.
Strategic Opportunities
- Therapeutic VR in South Korea:MFDS regulatory pathways for software-as-medical-device classifications create differentiated compliance frameworks for healthcare entrants.
- Industrial Training Subsidies:Japan's METI digital transformation incentives tied to JIS standards conformance open enterprise channel expansion for training system vendors.
- Haptic Feedback Convergence:Integration of force-feedback gloves with spatial computing platforms is opening new therapeutic and industrial simulation applications.
Industry Challenges
- Spatial Computing Talent Gap:Shortage of engineers proficient in simultaneous localization and mapping, computer vision, and low-latency rendering pipelines constrains product development velocity.
- Legacy System Integration:Enterprise buyers require compatibility with existing learning management systems and medical record platforms, extending sales cycles and implementation complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Virtual Reality Market |
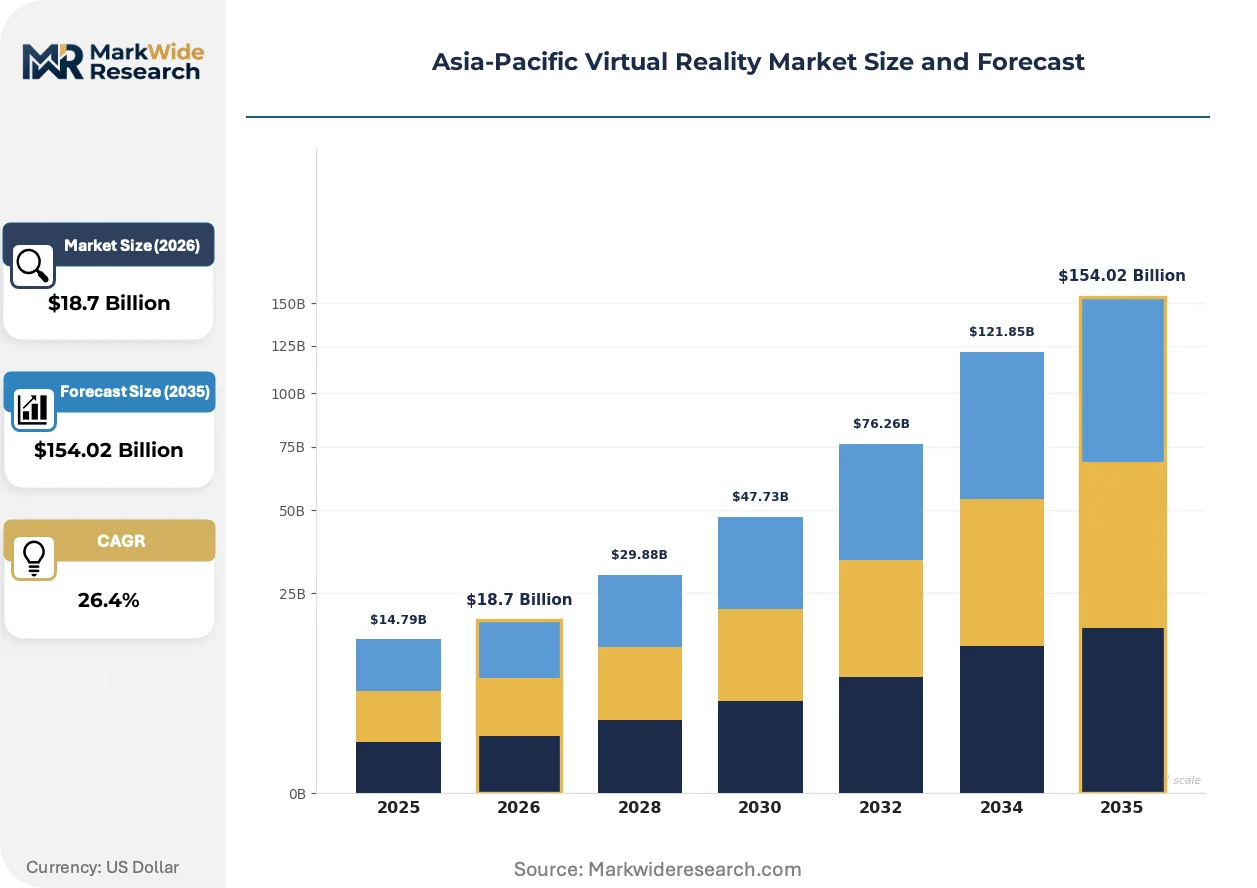
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $154.02 Billion |
| CAGR (2026 – 2036) | 26.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hardware, Software, Accessories, Content End User: Gaming, Education, Healthcare, Real Estate Technology: Augmented Reality, Mixed Reality, 3D Simulation, Haptic Feedback Application: Training, Entertainment, Marketing, Therapy |
| Companies Covered | HTC Corporation, Microsoft Corporation, Sony Corporation, Xiaomi, Lenovo, ByteDance, Meta Platforms, Inc., Seiko Epson Corporation, Samsung Electronics, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Virtual Reality Market Strategic Shifts
Pancake lens optics and gaze-contingent rendering are compressing form factors and power budgets simultaneously. These advances are enabling sustained wearability and opening new use cases beyond session-based entertainment.
Waveguide-based pancake optics is collapsing the thickness constraints that previously limited all-day wearable designs. Japanese optical component suppliers are shipping volume to headset assemblers in Taiwan and mainland China. The technology is collapsing the boundary between dedicated VR hardware and augmented reality glasses, forcing suppliers to dual-source optical stacks.
South Korea's MFDS software-as-medical-device classification framework is creating compliance precedents for therapeutic VR applications. The regulation requires clinical evidence packages for pain management and psychiatric intervention software. Japanese and Australian regulators are observing these precedents for potential harmonization, compressing time-to-market for cross-border healthcare content licensing.
Enterprise procurement of VR training systems is consolidating around outcome-validated pilot programs rather than hardware-centric RFPs. Industrial buyers in Japan and South Korea now require measurable skill transfer metrics before scaling deployments. This pattern is most visible in automotive and precision manufacturing verticals, where training cost accountability has displaced technology demonstration as the primary buying criterion.
Asia-Pacific Virtual Reality Market Segmentation
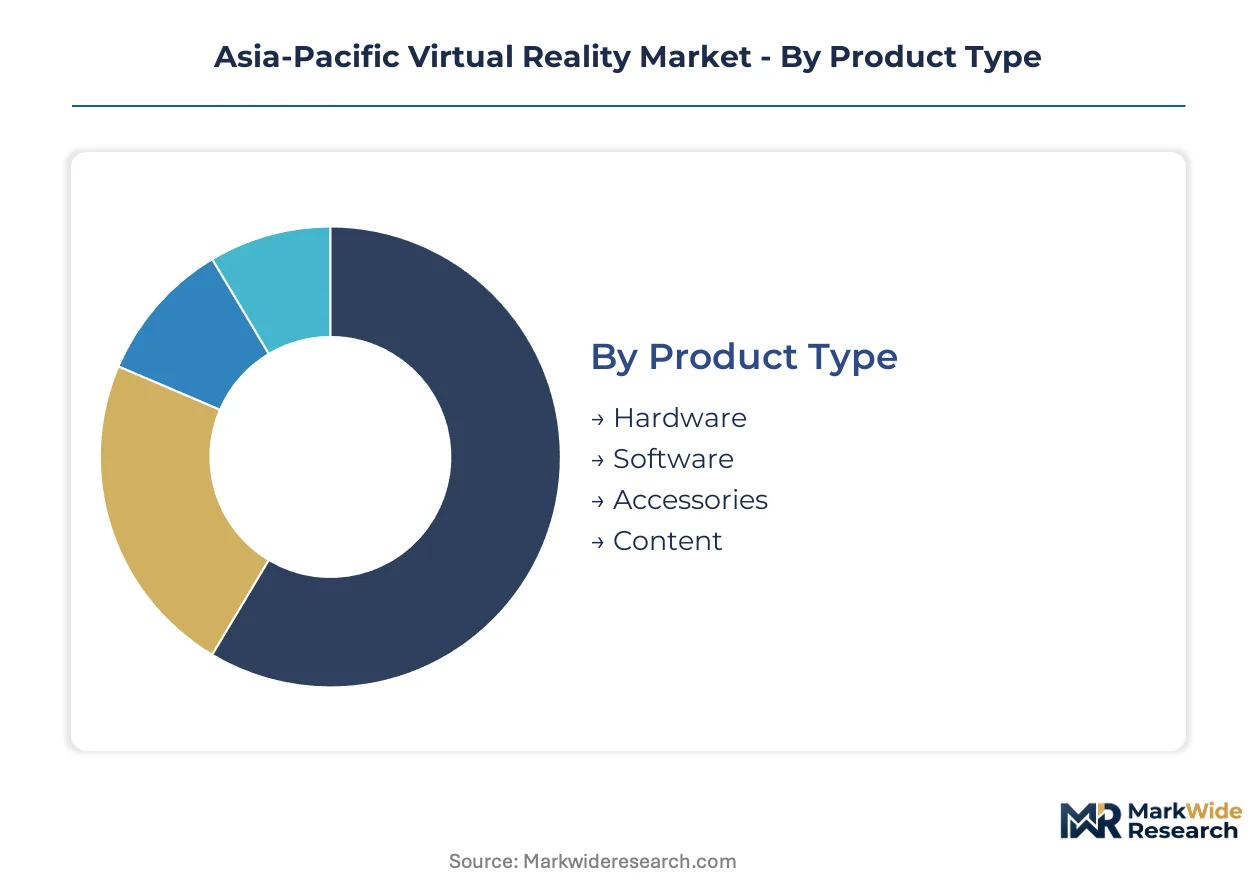
Segmentation in the Asia-Pacific virtual reality market reveals how divergent technical requirements and compliance pathways fragment procurement patterns. Buyers in Japan's medical verticals demand entirely different certification packages than Chinese industrial training coordinators.
Product Type:
After-sales service intensity varies dramatically across product categories, with hardware demanding field calibration support while content requires continuous version management.
- Hardware:Headset assemblies, controller modules, and sensor arrays constitute the revenue foundation. Shenzhen and Shanghai production clusters compress component sourcing cycles for domestic Chinese assemblers. Demand concentrates in enterprise channels where JIS and GB certification compliance extends replacement timelines.
- Software:Spatial computing platforms, rendering engines, and SDKs enable application development. South Korean and Japanese buyers prioritize integration with existing enterprise systems, elongating sales cycles but securing multi-year maintenance contracts.
- Accessories:Controller peripherals, charging stations, and protective cases extend hardware utility.
- Content:Immersive experiences, training modules, and entertainment titles complete the ecosystem.
Hardware holds the largest share; momentum sits with software as platform economics displace unit-sales dependency.
End User:
Cost tier stratification separates medical-grade deployments from mass-consumer gaming, with reimbursement pathways determining viable price points.
- Gaming:Console-integrated and standalone headsets target living-room entertainment. Japanese and South Korean households drive volume through PlayStation and PC-tethered ecosystems.
- Education:Institutional procurement of immersive learning systems concentrates in Chinese vocational colleges and Japanese technical schools.
- Healthcare:Surgical training simulators and therapeutic interventions command premium pricing. MFDS software-as-medical-device classifications in South Korea and METI subsidies in Japan accelerate hospital procurement.
- Real Estate:Architectural visualization and virtual property tours serve development marketing and buyer decision support.
Healthcare claims the steepest expansion trajectory; gaming retains volume leadership.
Technology:
Application maturity determines which technology layers attract R&D allocation versus commoditized supply.
- Augmented Reality:Overlay graphics onto physical environments through transparent waveguide optics. Japanese optical component suppliers ship volume to Taiwan and mainland China assemblers.
- Mixed Reality:Blend virtual and physical elements with spatial anchoring. Enterprise buyers in South Korean manufacturing pilot these systems for assembly guidance.
- 3D Simulation:Photorealistic environment generation for training and visualization.
- Haptic Feedback:Force-feedback gloves and tactile interfaces enable manual skill transfer. South Korean and Japanese component suppliers allocate disproportionate R&D to this layer.
Mixed Reality is gaining share fastest; Augmented Reality holds established deployment scale.
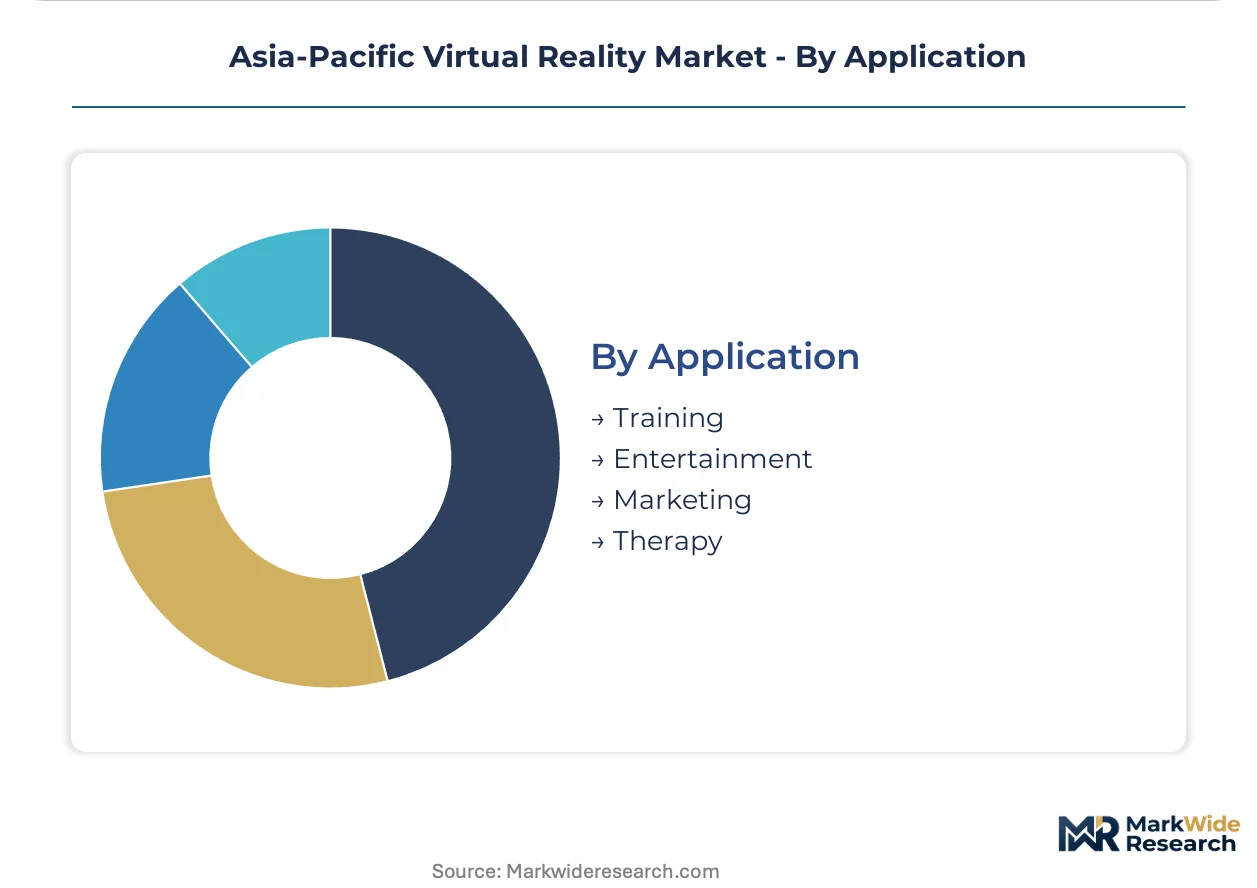
Application:
Customer type bifurcation separates outcome-accountable enterprise buyers from session-based consumer users.
- Training:Procedural skill transfer and safety simulation yield the highest per-seat enterprise pricing. Japanese automotive and precision manufacturing verticals now require measurable competency metrics before scaling.
- Entertainment:Gaming, cinematic experiences, and social platforms serve consumer markets. ByteDance competes aggressively through Chinese e-commerce distribution.
- Marketing:Brand activation and product visualization serve campaign-specific deployments.
- Therapy:Pain management and psychiatric interventions operate under MFDS medical device pathways in South Korea, with Australian and Japanese regulators observing for harmonization.
Training commands the largest share; therapy is climbing the fastest as regulatory precedents mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise buyers in Japanese automotive and South Korean healthcare verticals drive premium procurement, while Chinese mass-market channels absorb volume shipments through e-commerce distribution networks.
China
Industrial training coordinators and consumer gaming households constitute the dominant buyer archetypes. MIIT enforces GB standards for electromagnetic compatibility and optical safety in head-mounted displays, filtering low-quality imports. Shenzhen and Shanghai anchor headset production clusters where domestic assemblers compress component sourcing cycles.
Japan
Hospital procurement officers and automotive training managers command the highest per-seat pricing for surgical simulators and procedural skill transfer systems. METI promotes VR adoption through digital transformation subsidies tied to JIS standards conformance for industrial training. Tokyo and Osaka medical verticals demand entirely different certification packages than Chinese industrial buyers.
South Korea
Therapeutic VR software vendors and precision manufacturing training coordinators represent the fastest-expanding customer segments. MFDS regulates software-as-medical-device classifications for pain management and psychiatric intervention applications. Busan-Ulsan manufacturing pilots mixed reality systems for assembly guidance.
Australia
Vocational education institutions and mining safety training departments constitute the primary public-sector demand. TGA observes South Korean MFDS precedents for potential harmonization of therapeutic VR regulations. Sydney and Melbourne technical schools concentrate institutional procurement of immersive learning systems.
Taiwan
Optical component fabricators and enterprise channel distributors serve as critical supply chain intermediaries. The island's national standards bureau aligns with regional certification frameworks for cross-border hardware interoperability. Taipei-based suppliers ship waveguide-based pancake optics volume to mainland China headset assemblers.
Asia-Pacific Virtual Reality Market Competitive Environment
Channel-controlling players compete with product-specialist players across tiered market strata. The vendor base fragments between premium enterprise integrators, mass-market hardware assemblers, and component specialists. Three archetypes dominate: ecosystem platform owners, manufacturing-scale fabricators, and optical technology specialists. Competitive moves concentrate on strategic partnerships for content licensing and backward integration into sensor component supply.
Within the ecosystem platform tier, HTC Corporation and Sony Corporation exemplify contrasting channel strategies. HTC leverages early Vive ecosystem presence to sustain premium enterprise control across Taiwanese and Japanese medical verticals. Sony anchors console-integrated positioning through PlayStation hardware dominance in Japanese and South Korean living rooms. ByteDance occupies a distinct mass-market position, competing aggressively on price-performance ratios for consumer headsets distributed through Chinese e-commerce channels.
| Leading Market Players |
|---|
| HTC Corporation |
| Microsoft Corporation |
| Sony Corporation |
| Xiaomi |
| Lenovo |
| ByteDance |
| Meta Platforms, Inc. |
| Seiko Epson Corporation |
| Samsung Electronics |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in South Korean OLED panel fabrication is forcing display suppliers into volume-discount negotiations while compressing margins for mid-tier headset assemblers across China's eastern manufacturing corridor. This utilization dynamic simultaneously erodes component pricing power and accelerates supplier consolidation toward vertically integrated SoC designers.
Pricing Analysis
Cost-plus contracts with Korean Won indexation dominate display procurement for Taiwanese and mainland Chinese headset assemblers. Three-tier pricing structure across medical-grade certified, enterprise-standard, and consumer-economy levels separates JIS-conforming surgical simulators from mass-market gaming hardware. Pricing pressure stems from ByteDance's aggressive subsidy strategy in Chinese e-commerce channels. Hospital procurement officers in Japan exhibit the lowest price sensitivity due to METI subsidy coverage, while Chinese vocational colleges face acute budget constraints.
Supply Chain Analysis
Contract manufacturing concentrates at Foxconn, Goertek, and Luxshare facilities across Shenzhen, Shanghai, and Vietnam border zones. Component sourcing draws from South Korean OLED foundries, Japanese optical waveguide specialists, and Taiwanese SoC packaging houses. Single-source vulnerability in micro-OLED deposition equipment creates bottleneck exposure. Distribution runs through enterprise channel partners for medical verticals and direct-to-consumer e-commerce platforms for mass-market segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated Japanese automotive OEMs and South Korean hospital networks, fragmenting procurement among smaller Chinese vocational institutions and eroding vendor pricing leverage.
For Market Incumbents: Harden ecosystem lock-in through exclusive content licensing with Japanese medical device distributors and backward integration into haptic sensor component supply. Sony's console-integrated positioning and HTC's enterprise channel control face emerging threat from ByteDance's subsidy-funded volume plays. Prioritize JIS and MFDS certification investment to sustain premium tier access.
For New Entrants and Emerging Players: Build out therapeutic VR software portfolios targeting South Korea's MFDS software-as-medical-device pathway, where clinical evidence requirements create defensible moats. Australian vocational education institutions represent the most penetrable public-sector segment due to TGA's harmonization observation of Korean regulatory precedents. Pursue pilot-to-scale procurement frameworks with measurable skill transfer metrics.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among enterprise training platform vendors with multi-year maintenance contracts tied to JIS standards conformance. Long-term viability favors optical component specialists shipping waveguide-based pancake optics volume across Taiwan-China supply corridors. Watch for MFDS-Australian TGA regulatory harmonization as inflection signal for cross-border healthcare content licensing scalability.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | HTC's Vive ecosystem consolidation with Japanese medical distributors tightens enterprise channel control. |
| Regulatory Certification Investment | MFDS software-as-medical-device pathways in South Korea create differentiated compliance moats for therapeutic entrants. |
| Backward Integration | In-house haptic sensor production by Japanese component suppliers captures R&D allocation from South Korean rivals. |
| Strategic Partnership | Sony's PlayStation hardware alliances with South Korean living-room entertainment networks defend console-integrated positioning. |
| Geographic Expansion | ByteDance's e-commerce distribution penetration across Chinese mass-market channels displaces premium-tier volume. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of MIIT GB standard filings, METI digital transformation subsidy disclosures, and MFDS software-as-medical-device registration databases. Interviews with surgical training coordinators, automotive manufacturing engineers, hospital procurement officers, and optical component suppliers informed demand-side validation. Top-down market sizing triangulated against bottom-up shipment estimates from Shenzhen and Shanghai production clusters.
Forecast inputs span hardware unit economics, content production cost curves, and certification timeline distributions across the analysis window. Segmentation dimensions include product type, end-user vertical, technology layer, and application purpose. CAGRs derive from regression analysis of historical penetration rates against regulatory milestone schedules. Spatial computing talent availability and display panel cost trajectories served as industry-specific sensitivity variables.
Stress conditions across OLED supply concentration, cross-border certification friction, and enterprise procurement consolidation were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding MIIT enforcement continuity and METI subsidy renewal patterns. Quarterly review of MFDS-TGA regulatory harmonization indicators and Shenzhen production cluster utilization rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Virtual Reality (VR) and Augmented Reality (AR)
Global Augmented Reality Headsets Market
Virtual Reality (VR) and Augmented Reality (AR)
Extended Reality (XR) Market
Virtual Reality (VR) and Augmented Reality (AR)
Europe Virtual Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Mirror Market
Virtual Reality (VR) and Augmented Reality (AR)
North America Virtual Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Fitting Room Market
Virtual Reality (VR) and Augmented Reality (AR)
Augmented Reality Connected Service Market
Virtual Reality (VR) and Augmented Reality (AR)
Global VR for Medical Market
Virtual Reality (VR) and Augmented Reality (AR)
India Desktop Virtualization Market
Virtual Reality (VR) and Augmented Reality (AR)
3D Virtual Fence Market
Virtual Reality (VR) and Augmented Reality (AR)
US Augmented and Virtual Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Location-Based Virtual Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Augmented Learning Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality Headset Market
Virtual Reality (VR) and Augmented Reality (AR)
Europe Augmented Reality (AR) and Mixed Reality (MR) Market
Virtual Reality (VR) and Augmented Reality (AR)
Asia-Pacific Augmented Reality Market