
 Virtual Office Market | 2026-2036
Virtual Office Market Size, Share, and Industry Trends Forecast 2026-2036
Virtual Office Market Intelligence
Cloud-native workspace orchestration is reconfiguring how virtual office services are assembled and delivered to end users. WeWork leverages its physical-digital hybrid footprint to anchor enterprise clients seeking flexible presence in multiple cities simultaneously. Servcorp competes through premium serviced infrastructure that sustains higher price points in financial and legal verticals. Regus dominates geographic coverage, operating the broadest location network among established incumbents.
A virtual office denotes a technology-enabled service framework that substitutes physical workplace infrastructure with distributed digital access, typically integrating VoIP telephony, mail handling, video conferencing substrates, and on-demand physical meeting space. Its primary commercial purpose centers on reducing fixed real estate overhead while preserving corporate legitimacy, regulatory address requirements, and client-facing professionalism. Cloud-based deployment leads solution uptake because it eliminates capital expenditure and accelerates provisioning timelines for small enterprises and startups. Video conferencing and collaboration tools command the densest margin pools as integrated platform stickiness rises. Hybrid deployment architectures are gaining fastest among corporate departments that must reconcile legacy on-premises security policies with remote workforce mobility.
FCC guidelines in the United States govern VoIP service reliability and emergency calling compliance, directly shaping product architecture for providers serving North American clients. GDPR in Europe and analogous frameworks in other jurisdictions mandate data residency controls, forcing platform operators to segment infrastructure geographically. ISO standards for information security management underpin procurement criteria for corporate and government buyers. Stakeholders must monitor how evolving data localization mandates and AI-actuated collaboration features reshape compliance burdens and vendor selection criteria.
Market Dynamics
Cloud-native orchestration is collapsing the distinction between physical and digital workspace infrastructure, forcing providers to rearchitect delivery models around API-first service composition rather than bundled facility leases.
Growth Catalysts
- Freelancer Platform Integration:Gig-economy marketplaces embed virtual office provisioning directly into contractor onboarding workflows, creating embedded distribution channels.
- GDPR Data Residency Mandates:European data sovereignty requirements compel providers to establish localized infrastructure, expanding compliant addressable supply.
- Professional Services Mobility:Law and accounting firms adopt virtual presence to maintain bar-admitted addresses across multiple jurisdictions without physical occupancy.
Market Restraints
- Commercial Real Estate Concentration:Prime address inventory clusters in landlord-dense metropolitan cores, limiting geographic arbitrage opportunities.
- VoIP Reliability Standards:FCC emergency calling compliance adds architectural complexity that raises operational overhead for North American deployments.
- Mail Handling Liability Exposure:Physical document receipt creates jurisdictional tax nexus risks that deter multi-state expansion.
Strategic Opportunities
- Secondary City Penetration:Tier-2 US metropolitan areas offer lower commercial rent basis for premium address positioning.
- AI-Actuated Collaboration:Convergence of generative AI with meeting transcription and task automation creates differentiated platform tiers.
- ISO 27001 Procurement Tailwinds:Corporate security certification requirements favor providers with documented information management frameworks.
Industry Challenges
- Hybrid IT Integration Complexity:Enterprise clients demand seamless SSO federation between virtual office platforms and legacy identity providers.
- Compliance Talent Scarcity:Shortage of professionals versed in multi-jurisdictional corporate registration and tax nexus law constrains service scaling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Virtual Office Market |
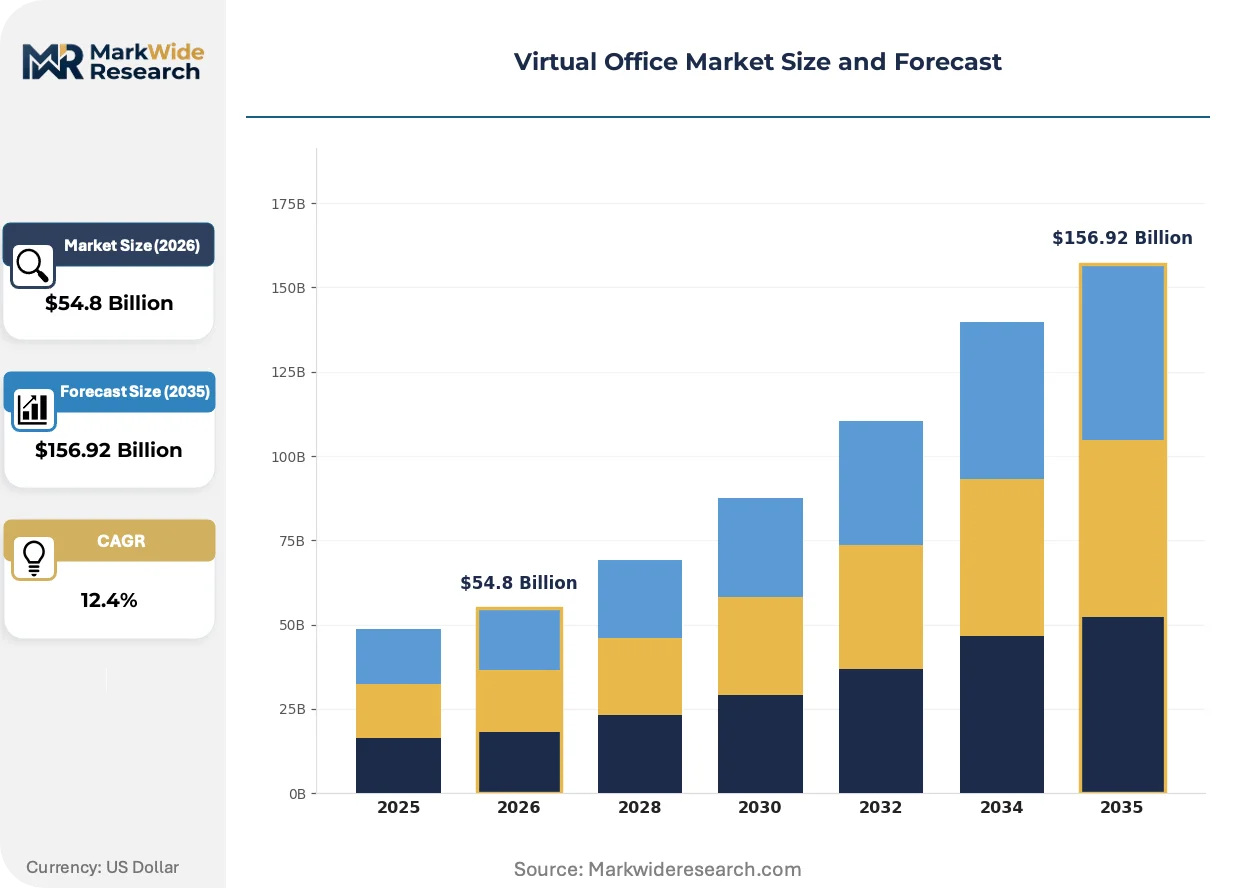
| Market Size in 2026 | $54.8 Billion |
| Market Size in 2035 | $156.92 Billion |
| CAGR (2026 – 2036) | 12.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, Edge Computing Solution Offering: Video Conferencing, Virtual Receptionist, Collaboration Tools, Document Management, Project Tracking Use Case: Remote Team Management, Client Interaction, Virtual Meetings, Workflow Automation Customer Type: Freelancers, Small Enterprises, Startups, Corporate Departments |
| Companies Covered | Alliance Virtual Offices, WeWork, Opus Virtual Offices, Intelligent Office, Cloud Virtual Office, Regus, Servcorp, eOffice, Davinci Virtual, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Virtual Office Market Strategic Shifts & Innovations
Workspace technology is compressing provisioning timelines from weeks to minutes while fragmenting buyer decision-making across functional stakeholders rather than centralized real estate teams.
Serverless edge computing is collapsing the latency gap between distributed users and centralized collaboration infrastructure. Mid-market professional services firms adopt these architectures fastest, eliminating VPN friction for client-facing staff. The technology is collapsing traditional geographic constraints on talent deployment, enabling single-address firms to operate nationally without performance degradation.
CSRD sustainability disclosure requirements in Europe mandate scope-3 emissions reporting that captures virtual office supply chains. Providers must now document energy consumption of data centers, mail processing facilities, and meeting room HVAC systems. Financial and legal verticals in Germany and France face the steepest compliance curves, driving procurement preference toward providers with certified carbon accounting.
Subscription unbundling is fragmenting historically integrated virtual office packages into component services purchased through separate procurement workflows. Enterprise buyers now source VoIP, mail handling, and meeting room access from distinct vendors, compressing switching costs and eroding platform stickiness. This pattern concentrates most visibly among venture-backed startups in the United States, where finance teams optimize vendor spend through granular service decomposition.
Virtual Office Market Segmentation
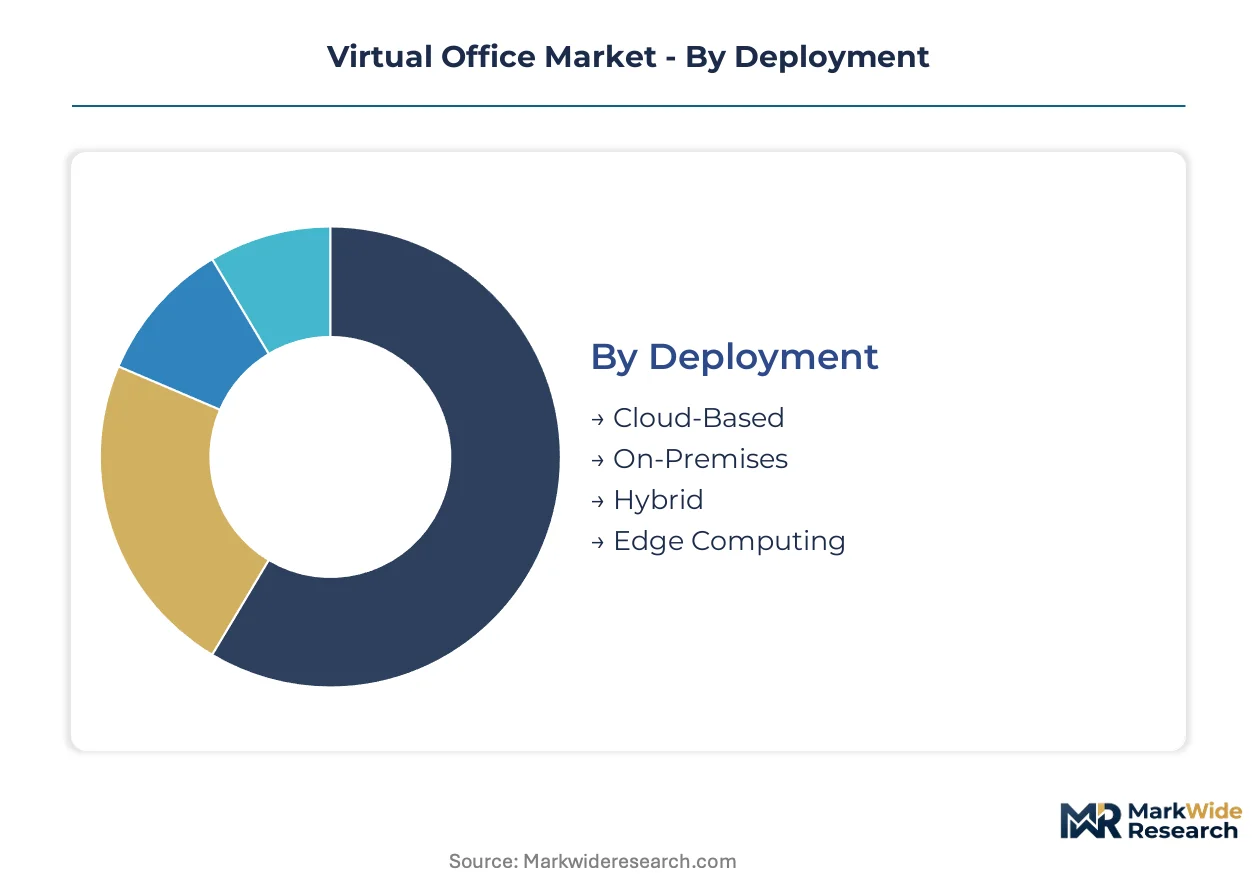
Virtual office market segmentation reveals how deployment architectures, solution bundles, and buyer profiles create distinct commercial territories. Providers must align infrastructure investments with the specific workflow and compliance requirements embedded in each segment combination.
Deployment:
Cost tier differentiation separates capital-intensive from operational expenditure models across the installation base.
- Cloud-Based:Multi-tenant SaaS architectures eliminate server procurement and reduce provisioning to minutes. Freelancers and startups in the United States concentrate here, driven by zero upfront capital requirements and automatic software updates.
- Hybrid:Split workloads between private infrastructure and public cloud balance legacy security policies with remote workforce mobility. Corporate departments in financial services adopt this fastest, constrained by internal data classification rules that prohibit full public cloud migration.
- On-Premises:Dedicated hardware installations within client-controlled facilities serve organizations with strict data sovereignty mandates.
- Edge Computing:Distributed micro-datacenters position compute resources within 50 kilometers of end users, collapsing latency for real-time collaboration.
Cloud-Based holds installed capacity. Hybrid is rotating up the share rankings.
Solution Offering:
Application maturity varies widely across functional modules, with communication tools leading and administrative services trailing.
- Video Conferencing:Real-time audiovisual infrastructure with screen sharing, recording, and breakout room functionality anchors platform stickiness. Small enterprises across professional services verticals drive premium tier uptake, requiring HIPAA-compliant encryption for client consultations.
- Collaboration Tools:Persistent workspaces combining messaging, file co-editing, and task boards displace email for project coordination. Startups in venture-backed technology clusters adopt these fastest, integrating with CI/CD pipelines and product management workflows.
- Virtual Receptionist:AI-augmented call routing and appointment scheduling substitutes human administrative staff.
- Document Management:Version-controlled repositories with e-signature integration streamline contract execution.
- Project Tracking:Gantt visualization and resource allocation modules support professional services delivery.
Video Conferencing commands margin concentration. Collaboration Tools are climbing the fastest.
Use Case:
Customer type determines which workflow scenarios generate recurring platform engagement and expansion revenue.
- Remote Team Management:Distributed workforce coordination spanning hiring, onboarding, performance review, and offboarding workflows. Corporate departments with 50-200 employees concentrate here, replacing fragmented point solutions with unified platforms.
- Virtual Meetings:Scheduled and ad-hoc synchronous communication for client and internal purposes. Freelancers across creative and consulting disciplines anchor volume, requiring professional backgrounds and noise cancellation for client-facing calls.
- Client Interaction:External relationship management through branded portals and secure file exchange.
- Workflow Automation:Trigger-based task routing and approval chains reduce manual administrative overhead.
Remote Team Management holds installed capacity. Virtual Meetings is rotating up the share rankings.
Customer Type:
Volume scale and procurement sophistication create four distinct buyer personas with incompatible sales motions.
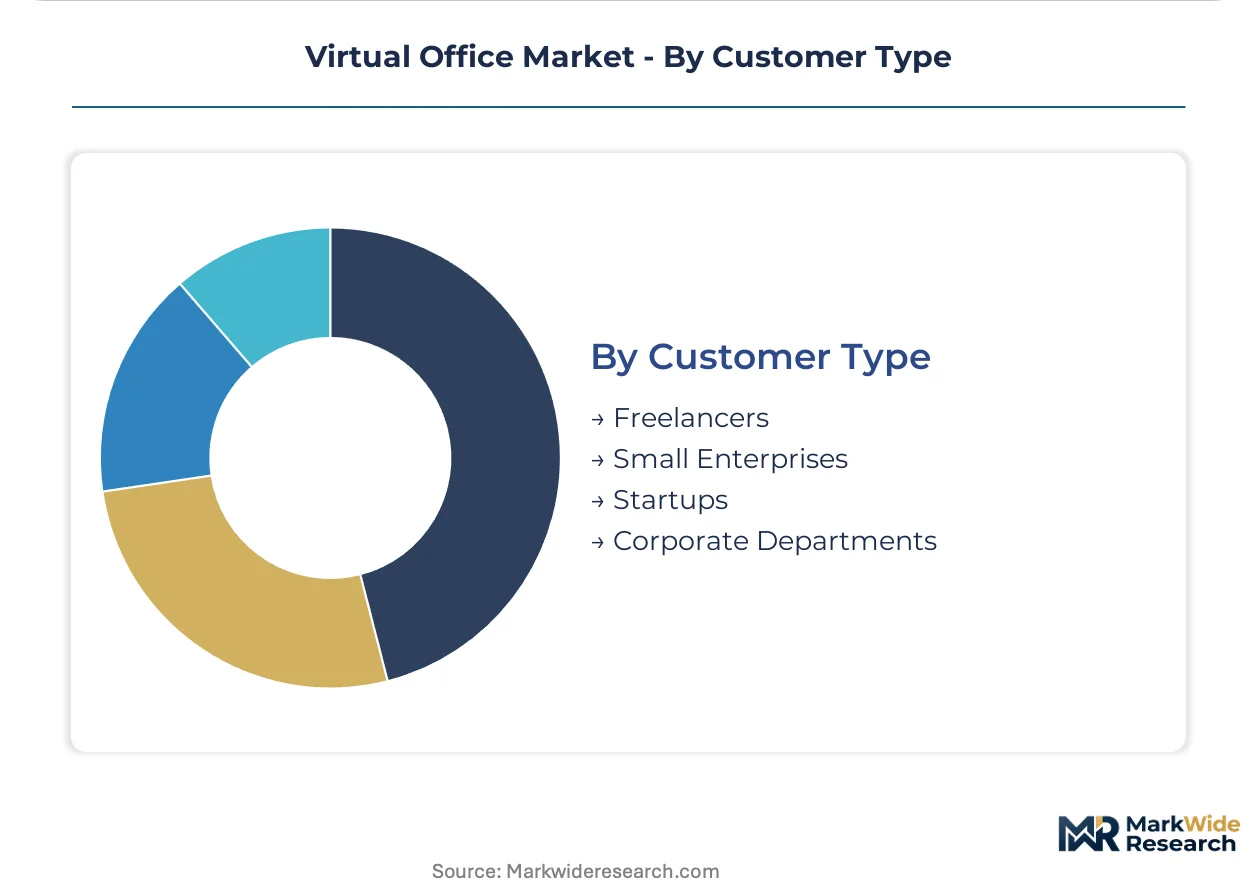
- Freelancers:Individual operators purchasing month-to-month subscriptions without procurement review. Gig-economy platforms embed virtual office provisioning into contractor onboarding, creating embedded distribution in the United States and United Kingdom.
- Corporate Departments:Business units within larger enterprises with centralized IT security requirements. Legal and compliance teams in multinational firms drive ISO 27001-certified solution selection, constrained by SSO federation mandates.
- Small Enterprises:Organizations with 2-50 employees seeking legitimacy through premium business addresses.
- Startups:Venture-funded companies prioritizing scalability and investor-facing professionalism.
Corporate Departments hold installed capacity. Freelancers are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States-based providers export virtual office infrastructure to professional services firms across Canada, the United Kingdom, and Australia, establishing trade corridors for cloud-based workspace orchestration.
United States
Venture-backed startups and professional services firms in New York, San Francisco, and Austin drive premium solution uptake for distributed workforce management. FCC guidelines govern VoIP service reliability and emergency calling compliance, directly shaping product architecture for North American deployments. The Greater Boston corridor concentrates demand for HIPAA-compliant video conferencing among healthcare consulting practices.
United Kingdom
Legal and financial services firms in London and Edinburgh adopt virtual presence to maintain regulatory addresses across multiple jurisdictions without physical occupancy. GDPR mandates data residency controls, forcing platform operators to segment infrastructure geographically with UK-specific data centers. The Manchester-Leeds corridor shows fastest adoption among mid-market accounting practices seeking ISO 27001-certified solutions.
Germany
Industrial Mittelstand firms and professional services clusters in Frankfurt and Munich prioritize compliance-certified platforms for client-facing operations. CSRD sustainability disclosure requirements mandate scope-3 emissions reporting that captures virtual office supply chains, driving procurement preference toward providers with certified carbon accounting. The Berlin-Brandenburg startup ecosystem concentrates demand for scalable, investor-facing professional addresses.
Japan
Corporate headquarters in Tokyo and Osaka deploy hybrid architectures to reconcile legacy on-premises security policies with remote workforce mobility. METI guidelines influence information security standards for cross-border data handling in professional services. The Nagoya-Chubu manufacturing corridor shows emerging demand for virtual receptionist services among precision engineering exporters.
Australia
Professional services firms in Sydney and Melbourne adopt cloud-native workspace orchestration to maintain client presence across Asia-Pacific markets without physical expansion. The country's national privacy regulator enforces data localization expectations that complement GDPR-aligned provider architectures. The Brisbane-Southeast Queensland corridor concentrates fastest-growing demand among resources sector consultancies serving remote mining operations.
Virtual Office Market Key Industry Players
On the supply side, the industry is consolidating around three distinct strategic tiers: global facility networks, cloud-native platform specialists, and premium serviced infrastructure operators. Incumbents compete through geographic coverage density, compliance certification depth, and API-first service composition rather than bundled facility leases. Dominant competitive moves include strategic partnerships with gig-economy marketplaces and portfolio diversification into AI-augmented collaboration tools.
Among global facility network operators, WeWork, Regus, and Servcorp occupy positions across the premium and scale-driven segments. WeWork exemplifies the physical-digital hybrid archetype through flexible presence offerings in multiple cities simultaneously. Regus represents the geographic coverage leader with the broadest location network among established incumbents. Servcorp anchors the premium serviced infrastructure tier, sustaining higher price points in financial and legal verticals through compliance-certified address positioning.
| Leading Market Players |
|---|
| Alliance Virtual Offices |
| WeWork |
| Opus Virtual Offices |
| Intelligent Office |
| Cloud Virtual Office |
| Regus |
| Servcorp |
| eOffice |
| Davinci Virtual |
| Others |
Cost & Logistics Intelligence
Overcapacity in cloud-native virtual office infrastructure across United States metropolitan cores compresses margin capture for tier-2 address positioning while simultaneously enabling aggressive subscriber acquisition pricing. FCC VoIP compliance costs and GDPR-mandated data center localization create divergent cost structures that fragment pricing power across regional deployments.
Pricing Analysis
Next-generation AI-augmented collaboration platforms command premium positioning against legacy video conferencing tiers and basic mail-handling economy offerings. Three-tier pricing structure across premium, standard, and economy levels dominates, with ISO 27001 certification and HIPAA-compliant encryption driving differentiation between tiers. Pricing pressure stems from subscription unbundling as enterprise buyers decompose bundled services into separate vendor relationships. Freelancers exhibit highest price sensitivity through month-to-month churn, while corporate legal departments accept premium tiers for multi-jurisdictional address compliance.
Supply Chain Analysis
Tariff exposure between United States and European Union data center equipment flows dominates supply chain risk planning for infrastructure expansion. Hardware sourcing concentrates in Taiwan, South Korea, and United States for server and networking components, while mail processing physical infrastructure draws from domestic commercial real estate markets. Single-source vulnerability in specialized VoIP gateway manufacturing creates procurement concentration. Distribution runs through direct SaaS provisioning for cloud-based tiers and facility-based channel partners for hybrid deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Distributed workforce normalization represents a structural disruption amplifying addressable demand for virtual office infrastructure, with GDPR and CSRD compliance mandates creating regulatory moats for prepared providers.
For Market Incumbents: Insulate core revenue streams by deepening API-first service composition that embeds virtual office provisioning into gig-economy marketplace workflows. Prioritize ISO 27001 certification maintenance against emerging cloud-native platform specialists threatening enterprise accounts. Expand compliant data center footprint across European Union and United Kingdom jurisdictions before localization mandates tighten. For New Entrants and Emerging Players: Build out secondary city penetration in tier-2 United States metropolitan areas where commercial rent basis enables premium address positioning at lower cost structures. Target mid-market accounting and legal practices in Manchester-Leeds corridor and Brisbane-Southeast Queensland resources corridor with CSRD-ready carbon accounting bundles. Pursue channel partnerships with professional services associations rather than direct enterprise sales. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among hybrid deployment providers serving corporate departments with 50-200 employees, where SSO federation requirements create switching cost stickiness. Long-term viability favors platforms combining physical address networks with AI-augmented collaboration capabilities. Monitor freelancer platform integration announcements as inflection indicators for embedded distribution channel formation.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Augmented Collaboration Launch | Generative AI integration with meeting transcription creates differentiated platform tiers for professional services. |
| GDPR-Compliant Data Center Expansion | Localized United Kingdom and European Union infrastructure captures procurement preference from regulated verticals. |
| Gig-Economy Marketplace Partnership | Embedded virtual office provisioning in contractor onboarding locks in freelancer segment volume. |
| CSRD Carbon Accounting Certification | Documented scope-3 emissions reporting meets German and French financial vertical procurement requirements. |
| Secondary City Facility Network | Lower commercial rent basis in tier-2 metropolitan areas enables premium address positioning at compressed cost. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with virtual office platform executives, commercial real estate leasing directors, and corporate IT procurement officers; and secondary validation through SEC filings of publicly traded workspace providers, FCC regulatory dockets, GDPR implementation guidance, and commercial real estate transaction databases. Bottom-up triangulation against top-down market sizing anchored volume estimates.
Forecast inputs span deployment architecture, customer type, solution offering bundle, and geographic regulatory cluster across the analysis window. Segment-specific CAGRs derived from installer base growth rates, subscriber acquisition cost trajectories, and addressable market penetration curves. VoIP reliability compliance costs and data localization infrastructure requirements shaped regional growth differentials.
The forecast holds incumbent behavior within observed patterns; aggressive moves by hyperscaler-backed collaboration platforms or regulatory acceleration beyond CSRD timelines would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Cognitive Supply Chain Market
Digital Solutions
Global Process Orchestration Market
Digital Solutions
Advanced Process Control (APC) and Online Optimization Market
Digital Solutions
Disaster Recovery As a Service (Draas) Market
Digital Solutions
Supply Side Platform (SSP) Market
Digital Solutions
Image Recognition in Retail Market
Digital Solutions
Global Drilling Data Management Systems Market
Digital Solutions
Email Marketing Market
Digital Solutions
Beacons Management Software Market
Digital Solutions
Fuel Management Software Market
Digital Solutions
Community Engagement Software Market
Digital Solutions
Electronic Records Management Solutions Market
Digital Solutions
Virtual Hiring Tools Market
Digital Solutions
Computer Aided Design (CAD) Market
Digital Solutions
Crowdsourcing Market
Digital Solutions
Global Interactive Voice Response Market