
 Neuro-Gaming Technology Market | 2026-2036
Neuro-Gaming Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Neuro-Gaming Technology Market Foresight
ISO 13485 medical device quality management certification is unwinding the competitive landscape for neuro-gaming hardware vendors seeking clinical credibility. Emotiv Inc. leverages its EEG headset platform to anchor consumer and research channels across North America and Asia-Pacific. NeuroSky Inc. competes on cost-optimized brainwave sensors for casual gaming peripherals. iMotions A/S dominates multimodal biometric integration software used by academic and commercial research labs.
Neuro-gaming technology fuses real-time neural signal acquisition—typically via electroencephalography sampling cortical electrical activity at 256–1024 Hz—with adaptive game mechanics that respond to attention, emotional valence, or cognitive load states. The primary purpose spans entertainment immersion, therapeutic intervention for attention disorders, and accelerated skill acquisition through closed-loop neurofeedback. Headsets and wearables capture the dominant hardware margin pool due to sensor miniaturization and electrode material costs, while software layers extract recurring revenue through SDK licensing to developers and institutional research platforms. Machine Learning algorithms processing raw neural data represent the fastest-expanding technology segment as pattern recognition accuracy improves training efficacy and reduces calibration time.
The FDA regulates neuro-gaming devices with therapeutic claims as Class II medical devices under 510(k) pathways, while the FCC governs wireless transmission protocols for wearable headsets. The EU AI Act's biometric identification and emotion recognition classifications impose conformity assessment burdens on vendors deploying neural data analytics across European markets. Stakeholders must monitor evolving neurodata privacy statutes and clinical evidence requirements that will determine which product architectures secure reimbursement and institutional procurement eligibility.
Market Dynamics
Machine learning inference at the edge is decomposing hardware-software boundaries in neuro-gaming, forcing vendors to rearchitect around on-device neural signal processing rather than cloud-dependent analytics pipelines.
Growth Catalysts
- FDA Breakthrough Device Designation:The pathway accelerates clinical validation timelines for neuro-gaming systems targeting attention-deficit disorders, reducing regulatory friction for therapeutic-grade hardware.
- EEG sensor miniaturization:Dry-electrode advances cut electrode preparation time from 15 minutes to under 60 seconds, expanding addressable use cases beyond controlled lab environments into home-based cognitive training.
- Healthcare facilities:Rehabilitation centers in the United States, Germany, and Japan are embedding neuro-gaming protocols into stroke recovery and traumatic brain injury therapy regimens.
Market Restraints
- Silver and chloride electrode costs:Raw material volatility in conductive gel and sintered silver-silver chloride sensors squeezes hardware margins for mid-tier headset manufacturers.
- Single-source foundry concentration:Taiwan-based semiconductor fabrication for low-noise analog front-end chips creates geographic supply vulnerability for EEG acquisition hardware.
- EU AI Act biometric classification:Neural data processing systems face conformity assessment burdens and third-party audit requirements that extend European market entry timelines by 12-18 months.
Strategic Opportunities
- India's PLI scheme for electronics manufacturing:Production-linked incentives for wearable devices offer cost-competitive assembly alternatives to China-dependent supply chains.
- Convergence of fNIRS and EEG:Hybrid optical-electrical neuroimaging enables hemodynamic validation of electrical signals, opening research budgets in academic neuroscience departments.
- Direct-to-clinic distribution:Bypassing traditional medical device distributors through institutional sales teams captures margin and accelerates pilot-to-scale conversion in university hospitals.
Industry Challenges
- ISO 13485 certification timelines:Medical device quality management implementation requires 18-24 months for software-heavy neuro-gaming vendors lacking prior regulated device experience.
- Signal processing talent scarcity:The intersection of neurophysiology, embedded systems engineering, and machine learning pipeline development concentrates hiring competition among a narrow candidate pool.
- Interoperability with EHR systems:Therapeutic neuro-gaming platforms face integration complexity with Epic and Cerner electronic health record architectures in US hospital networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Neuro-Gaming Technology Market |
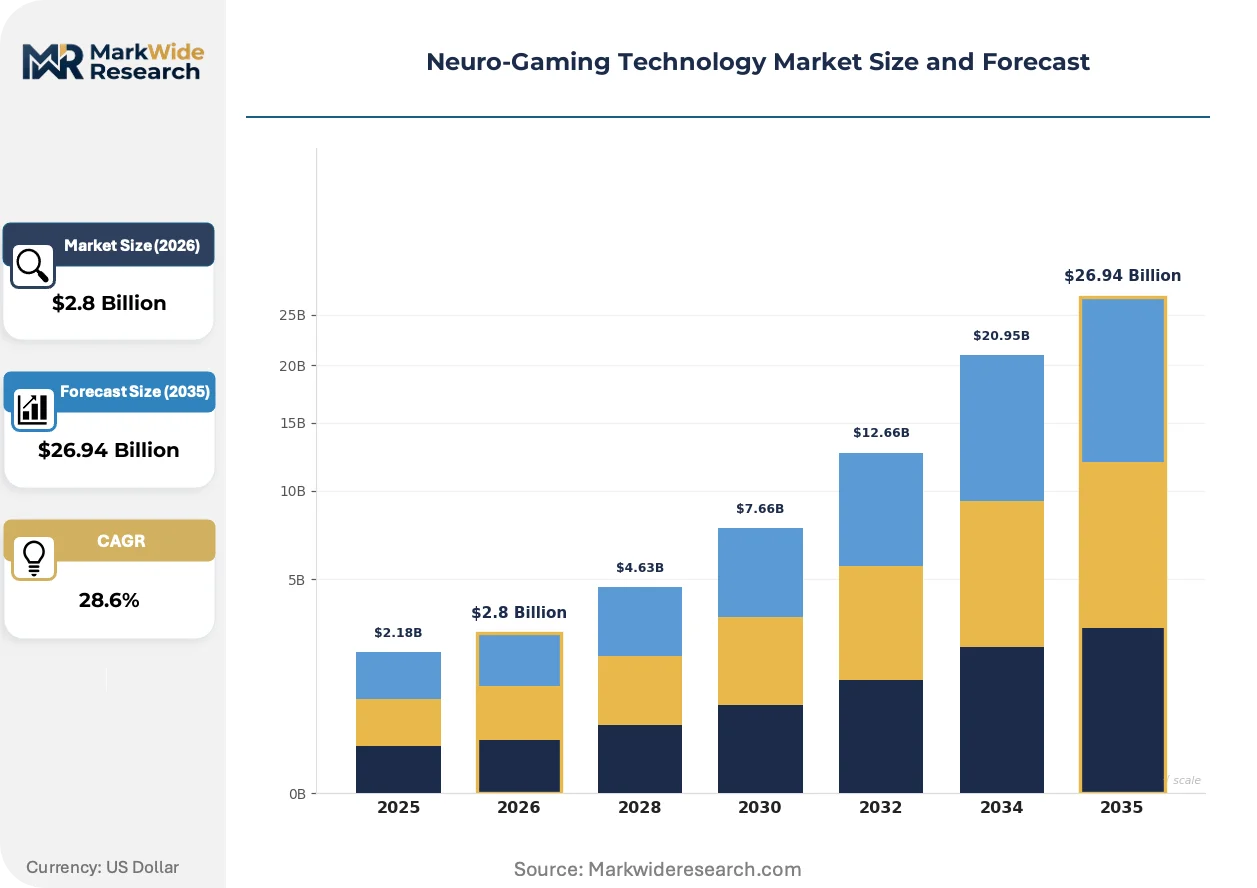
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $26.94 Billion |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Headsets, Controllers, Software, Wearables End User: Gamers, Developers, Educational Institutions, Healthcare Facilities Technology: EEG, fNIRS, Machine Learning, VR Application: Skill Training, Therapy, Entertainment, Research |
| Companies Covered | Emotiv Inc., NeuroSky Inc., Ultraleap Ltd., iMotions A/S, Qneuro Inc., Smart Eye AB, Neuro-gaming Ltd, OpenBCI LLC, Neurable Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Neuro-Gaming Technology Market Shifts & Advancements
Real-time adaptive difficulty algorithms are rewriting how neuro-gaming systems calibrate to individual cognitive states, replacing static level designs with closed-loop feedback architectures.
Edge-deployed transformer architectures for EEG artifact rejection are decomposing the traditional cloud-processing dependency in consumer neuro-gaming headsets. Academic research labs at Stanford and ETH Zurich are piloting on-device models that cut latency from 200ms to under 30ms. This compression enables competitive multiplayer neuro-gaming where reaction-time parity with conventional controllers becomes technically viable.
The EU AI Act's emotion recognition system classification is tightening conformity obligations for neuro-gaming vendors deploying affective computing features across European markets. Systems inferring emotional states from neural signals now face third-party conformity assessment and CE marking under heightened scrutiny. German and French health technology assessment bodies are incorporating these compliance timelines into reimbursement evaluation frameworks.
Subscription-based SDK licensing is displacing perpetual software licenses among enterprise neuro-gaming deployments. Research institutions and clinical trial operators in the United States and United Kingdom are prioritizing usage-based pricing that scales with participant enrollment rather than fixed-seat arrangements. This shift compresses upfront procurement cycles while extending vendor-customer relationship duration through continuous model retraining services.
Neuro-Gaming Technology Market Segmentation
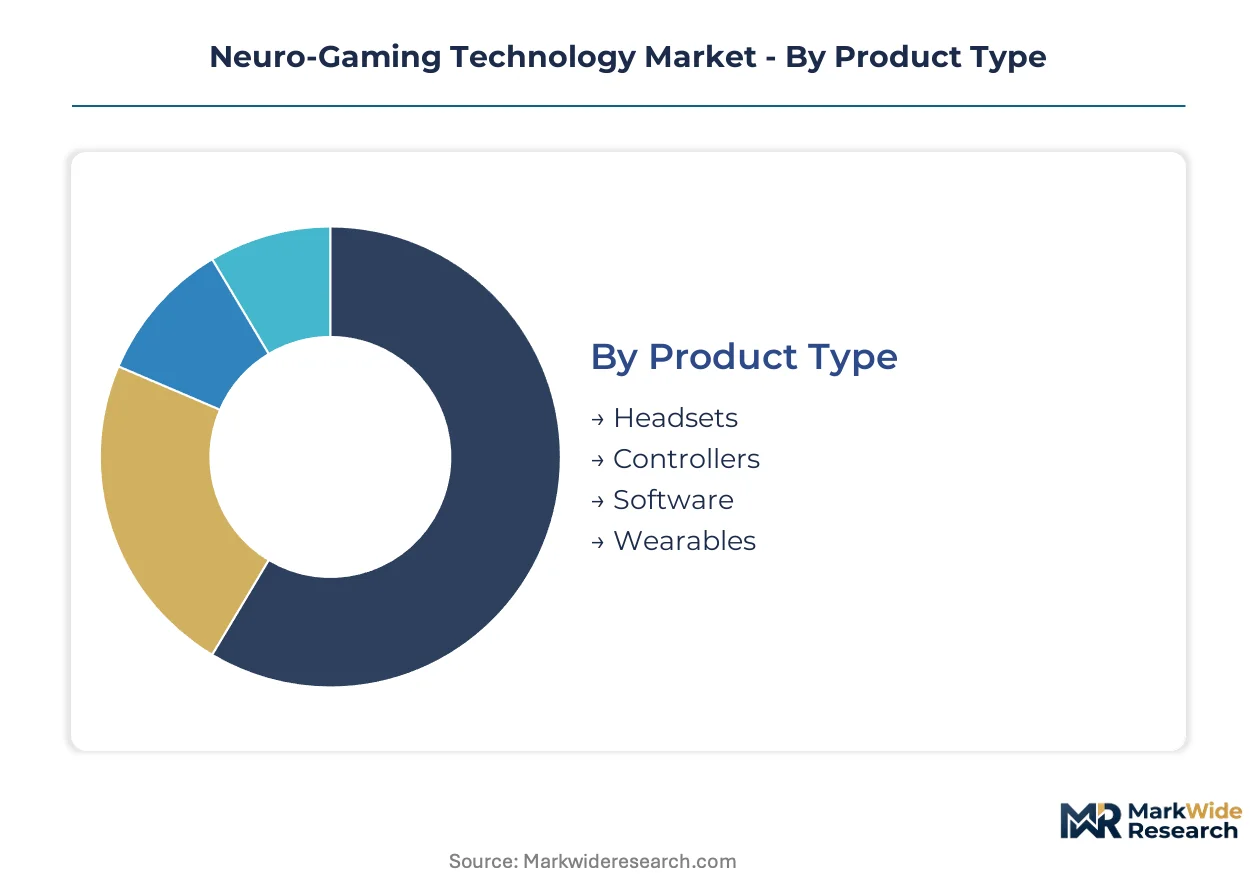
Neuro-gaming technology segments diverge sharply by regulatory pathway and procurement channel. Hardware vendors face ISO 13485 certification timelines while software layers extract recurring revenue through institutional licensing.
Product Type:
Domestic assembly concentrates in India under PLI incentives, while premium sensor modules remain import-dependent from Taiwan and South Korea.
- Headsets:Dry-electrode EEG headsets sample cortical activity at 256–1024 Hz through silver-silver chloride sensors. Demand clusters in United States rehabilitation centers and German university hospitals where FDA breakthrough and EU MDR pathways validate therapeutic claims.
- Software:SDK licensing and adaptive algorithm platforms process raw neural data into attention and cognitive load metrics. Research institutions in the United Kingdom and Japan prioritize subscription pricing that scales with participant enrollment rather than perpetual licenses.
- Controllers:Peripheral brainwave interfaces for casual gaming operate at lower sampling rates with reduced electrode counts.
- Wearables:Wrist and arm-mounted form factors capture peripheral neural signals for fitness and wellness applications.
Headsets hold the largest share; momentum sits with software as machine learning inference shifts to edge deployment.
End User:
Procurement authority separates consumer-direct sales from institutional tender processes with diverging compliance requirements.
- Healthcare Facilities:Stroke recovery and traumatic brain injury therapy protocols in United States, German, and Japanese rehabilitation centers drive therapeutic-grade hardware procurement. FDA 510(k) clearance and EU MDR conformity assessment gates extend sales cycles to 18–24 months.
- Educational Institutions:Academic neuroscience departments at Stanford and ETH Zurich pilot hybrid fNIRS-EEG systems for hemodynamic validation studies. Research budgets favor multimodal biometric integration platforms with open API architectures.
- Gamers:Consumer demand concentrates in attention-training and immersive entertainment applications with lower regulatory barriers.
- Developers:Indie and AAA studios license neural signal processing SDKs for adaptive difficulty mechanics in competitive multiplayer titles.
Healthcare facilities command premium pricing; educational institutions are expanding most quickly as research funding diversifies beyond traditional neuroscience departments.
Technology:
Patent thickets and talent scarcity concentrate competitive advantage in signal processing algorithm stacks rather than sensor hardware alone.
- Machine Learning:Edge-deployed transformer architectures for EEG artifact rejection cut inference latency from 200ms to under 30ms. On-device pattern recognition reduces calibration time and enables competitive multiplayer neuro-gaming with reaction-time parity against conventional controllers.
- EEG:Electroencephalography remains the dominant electrical acquisition modality with established clinical validation pathways. Dry-electrode advances from 15-minute to 60-second preparation times expand addressable use cases into home-based cognitive training.
- fNIRS:Functional near-infrared spectroscopy provides hemodynamic validation of electrical signals through optical neuroimaging.
- VR:Virtual reality headsets integrate neural signal acquisition for immersive therapeutic and entertainment environments.
EEG holds the largest share; machine learning gains share fastest as vendors rearchitect around on-device processing pipelines.
Application:
Reimbursement eligibility separates clinically validated therapeutic protocols from discretionary consumer entertainment spend.
- Therapy:Attention-deficit disorder interventions and cognitive rehabilitation protocols qualify for insurance reimbursement in United States and German healthcare systems. FDA breakthrough device designation accelerates clinical validation timelines for therapeutic-grade neuro-gaming systems.
- Skill Training:Closed-loop neurofeedback accelerates motor skill and cognitive task acquisition through real-time adaptive difficulty algorithms. Military and aviation training budgets in the United States and United Kingdom fund pilot programs for accelerated expertise development.
- Entertainment:Immersive gaming experiences respond to attention and emotional valence states without therapeutic claims.
- Research:Academic and commercial trials generate demand for multimodal biometric data collection platforms with precise synchronization capabilities.
Therapy commands the highest unit economics; skill training shows the steepest expansion trajectory as defense and enterprise training budgets formalize procurement protocols.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA breakthrough device designations and India's PLI scheme for electronics manufacturing are redirecting investment flows toward clinical-grade hardware production and cost-competitive assembly alternatives.
United States
Rehabilitation centers in California and Massachusetts embed neuro-gaming protocols into stroke recovery and traumatic brain injury therapy regimens. FDA 510(k) pathways regulate therapeutic-grade devices while FCC governs wireless transmission standards for wearable headsets. The Greater Boston cluster anchors academic neuroscience research at MIT and Harvard Medical School, where hybrid fNIRS-EEG pilot programs attract defense and NIH funding.
Germany
University hospitals in Bavaria and North Rhine-Westphalia drive therapeutic hardware procurement for cognitive rehabilitation protocols. EU MDR conformity assessment and the AI Act's biometric classification impose third-party audit requirements that extend market entry timelines. The Munich-Stuttgart corridor concentrates precision sensor engineering talent and ISO 13485-certified contract manufacturers serving European medtech demand.
Japan
PMDA regulatory frameworks validate neuro-gaming systems for attention-deficit interventions in Tokyo and Osaka metropolitan healthcare networks. METI funding programs support domestic semiconductor fabrication for low-noise analog front-end chips. The Kansai region hosts clinical trial operators piloting closed-loop neurofeedback for elderly cognitive maintenance, leveraging aging-demographics research budgets.
India
Production-linked incentives under the electronics manufacturing scheme attract assembly investment for consumer-grade headsets in Karnataka and Tamil Nadu. BIS certification requirements and CDSCO medical device rules create dual compliance pathways for vendors targeting clinical versus wellness segments. The Bangalore-Hyderabad corridor supplies embedded systems engineering talent for signal processing algorithm development.
United Kingdom
Academic neuroscience departments at Imperial College London and University of Cambridge pilot multimodal biometric integration platforms for research applications. MHRA regulatory alignment with EU MDR post-Brexit maintains conformity assessment burdens for therapeutic claims. The Oxford-Cambridge arc anchors subscription-based SDK licensing demand from clinical trial operators prioritizing usage-based pricing models.
Neuro-Gaming Technology Market Competitive Landscape
Listed leaders compete with private specialists across certification depth and procurement channel access, creating a tiered structure where ISO 13485 medical device quality management separates clinical-credible vendors from consumer-peripheral suppliers. Strategic archetypes include EEG hardware platform anchors, cost-optimized sensor specialists, and multimodal biometric software integrators. Dominant competitive moves center on direct-to-clinic distribution bypassing traditional medical device distributors, and edge-deployed machine learning rearchitecture eliminating cloud-processing dependencies.
Within the EEG hardware platform tier, Emotiv Inc. and NeuroSky Inc. represent contrasting positioning archetypes—one anchoring premium research and clinical channels, the other exemplifying cost-optimized consumer peripheral strategies. iMotions A/S occupies a distinct position in multimodal biometric integration software, serving academic and commercial research labs with open API architectures. These three entities collectively illustrate the market's segmentation across hardware margin pools, software recurring revenue models, and institutional versus consumer procurement pathways.
| Leading Market Players |
|---|
| Emotiv Inc. |
| NeuroSky Inc. |
| Ultraleap Ltd. |
| iMotions A/S |
| Qneuro Inc. |
| Smart Eye AB |
| Neuro-gaming Ltd |
| OpenBCI LLC |
| Neurable Inc. |
| Others |
Supply & Pricing Matrix
ISO 13485 medical device quality management certification gates both supplier qualification and price differentiation simultaneously, creating tiered hardware economics where clinical-grade EEG headsets command substantial premiums over consumer peripherals while certification timelines lock out cost-optimized competitors from therapeutic procurement channels.
Pricing Analysis
Certification level (ISO/FDA-grade) creates the primary spread between therapeutic and consumer hardware tiers. Three-tier pricing structure across clinical-grade, research-grade, and casual-gaming levels segments buyers by validation depth and electrode precision. Cost compression in mid-tier headsets is intensifying because silver-silver chloride sensor volatility squeezes margins. Healthcare facilities demonstrate lowest price sensitivity due to reimbursement eligibility, while casual gamers drive aggressive cost optimization demands.
Supply Chain Analysis
Inventory lead times for low-noise analog front-end chips stretch procurement cycles due to Taiwan-based foundry concentration. Hardware assembly draws from India, Taiwan, and South Korea for sensor modules and semiconductor fabrication. Sintered silver, chloride conductive gels, and dry-electrode polymers anchor raw material dependencies. Single-source semiconductor vulnerability creates geographic supply risk. Distribution runs through direct-to-clinic institutional sales teams and medical device distributors for therapeutic segments, with consumer channels employing electronics retail and direct e-commerce.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The neuro-gaming technology market is entering a cyclical recovery phase as FDA breakthrough device designations compress clinical validation timelines and reopen institutional procurement pipelines that stalled during extended regulatory uncertainty.
For Market Incumbents: Secure ISO 13485 certification depth as a defensive moat against emerging software-only entrants lacking regulated device experience. Deepen backward integration into electrode material supply to offset silver price volatility threatening hardware margins. Lock in exclusive distribution partnerships with university hospital networks before reimbursement pathways formalize.
For New Entrants and Emerging Players: SDK subscription gaps in adaptive algorithm platforms expose incumbents' underinvestment in usage-based pricing for research institutions. Target educational neuroscience departments piloting hybrid fNIRS-EEG systems where budget flexibility exceeds healthcare procurement rigidity. Deploy open API architectures as the primary go-to-market wedge against closed-platform incumbents.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across edge-deployed machine learning segments as on-device processing eliminates cloud infrastructure dependencies. Long-term viability favors vendors with dual revenue streams combining hardware margins and recurring software licensing. Acquisition targets should demonstrate ISO 13485 certification progress plus institutional sales traction. Monitor FDA breakthrough device designation velocity as the critical inflection signal for therapeutic segment expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Pathway | Clinical credibility gates reimbursement eligibility in US and German healthcare systems. |
| Edge ML Architecture Migration | On-device inference cuts latency below 30ms for competitive multiplayer viability. |
| Direct-to-Clinic Distribution | Bypassing traditional distributors captures margin and accelerates pilot-to-scale conversion. |
| Hybrid fNIRS-EEG Development | Hemodynamic validation opens research budgets at Stanford and ETH Zurich. |
| Subscription SDK Repricing | Usage-based licensing aligns vendor revenue with clinical trial enrollment scaling. |
Research Methodology
Desk research of FDA 510(k) filings, EU MDR conformity assessment databases, and academic neuroscience publication corpora preceded structured interviews with biomedical engineers, hospital purchasing committee members, EEG hardware product managers, and clinical trial operators. Primary fieldwork combined with secondary validation against SEC disclosures from listed neurotechnology vendors and NIH grant award databases. Bottom-up unit economics modeling triangulated against top-down market sizing from healthcare procurement records and research institution budget allocations.
Variance decomposition across product type, end user, technology modality, and application segments shaped the analytical framework over the projection horizon. Modeled dimensions included hardware-software revenue mix, regulatory pathway classification, and geographic adoption patterns. CAGRs were derived from segment-level growth rate reconciliation. Forecast inputs incorporated EEG sensor miniaturization curves, FDA breakthrough designation velocity, and EU AI Act implementation timelines.
Underlying assumptions cover reimbursement pathway formalization and semiconductor supply stabilization, with deviation risk concentrated in EU MDR audit backlog delays and silver commodity price spikes. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Virtual Reality (VR) and Augmented Reality (AR)
Internet of Senses Market
Virtual Reality (VR) and Augmented Reality (AR)
Germany Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Production Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality Headset Market
Virtual Reality (VR) and Augmented Reality (AR)
Augmented Learning Market
Virtual Reality (VR) and Augmented Reality (AR)
Tourists Virtual Reality Headsets Market
Virtual Reality (VR) and Augmented Reality (AR)
Commercial Augmented Reality Glasses Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality (VR) Simulator Market
Virtual Reality (VR) and Augmented Reality (AR)
North America Virtual Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Augmented Reality Book Market
Virtual Reality (VR) and Augmented Reality (AR)
AR and VR Display Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Dressing Room Market
Virtual Reality (VR) and Augmented Reality (AR)
3D Virtual Reality Glasses Market
Virtual Reality (VR) and Augmented Reality (AR)
Consumer Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
Immersive Virtual Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Virtual Reality Software Market