
 Immersive Simulator Market | 2026-2036
Immersive Simulator Market Size, Share, and Industry Trends Forecast 2026-2036
Immersive Simulator Market Outlook
Defense procurement offices are reorganizing training budgets toward mixed-reality platforms, pulling spend from legacy screen-based systems. Siemens AG leverages its industrial automation heritage to dominate manufacturing simulation deployments across European facilities. EON Reality anchors its position in educational institutions through scalable virtual-reality content libraries. AVEVA Group specializes in energy-sector immersive training, competing on physics fidelity for hazardous-environment replication.
An immersive simulator integrates hardware peripherals, software engines, and sensory feedback mechanisms to replicate operational environments with real-time physics modeling and spatial audio rendering. These systems enable risk-free skill acquisition for procedures ranging from surgical techniques to emergency response protocols. Hardware segments currently capture the largest revenue share due to headset and motion-platform refresh cycles, while haptic feedback technology represents the fastest-expanding margin pool as force-feedback gloves and full-body suits penetrate medical and military applications. Software segments remain mature in entertainment but show accelerating uptake in corporate training modules where Autodesk and IBM Corporation navigate enterprise IT integration requirements.
The EU AI Act and GDPR impose algorithmic transparency and data residency rules on European-deployed training software, while the U.S. FAA and OSHA set equipment safety benchmarks for aviation and industrial simulators. China's MIIT enforces GB standards for virtual-reality hardware electromagnetic compatibility, constraining import pathways for non-certified peripherals. Stakeholders must monitor evolving certification reciprocity agreements between national regulators to anticipate deployment friction in cross-border training contracts.
Market Dynamics
Defense procurement offices are redirecting training budgets from legacy screen-based systems toward mixed-reality platforms, compressing refresh cycles for headset and motion-platform hardware while forcing software vendors to recertify under emerging algorithmic transparency mandates.
Growth Catalysts
- Mixed-reality combat trainers:Defense forces in the United States, Germany, and South Korea are scaling procurement of spatial computing platforms for risk-free tactical rehearsal.
- EU AI Act compliance:Algorithmic transparency requirements for European-deployed training software are creating certified-vendor moats that favor established platform providers.
- Haptic feedback penetration:Force-feedback gloves and full-body suits are penetrating medical and military skill-acquisition protocols, expanding addressable use cases beyond visual immersion.
Market Restraints
- Hardware refresh cost concentration:Headset and motion-platform replacement cycles burden training budgets with capital intensity that software-only vendors avoid.
- GB standards enforcement:China's MIIT electromagnetic compatibility certification constrains import pathways for non-certified peripherals, fragmenting hardware supply.
- Physics fidelity thresholds:Energy-sector hazardous-environment replication demands computational load that mid-tier systems cannot deliver, capping addressable share.
Strategic Opportunities
- Enterprise IT integration:Corporate training modules show accelerating uptake as Autodesk and IBM Corporation navigate middleware requirements for seamless deployment.
- Educational institution scaling:Virtual-reality content libraries anchor position in secondary and post-secondary credential programs, creating recurring content revenue.
- GDPR data residency:European data-localization rules favor regional cloud infrastructure providers for training-software hosting, displacing US-centric architectures.
Industry Challenges
- Certification reciprocity gaps:Cross-border training contracts face deployment friction where FAA, EASA, and national military standards lack mutual recognition.
- Legacy system integration:Industrial facilities with entrenched SCADA and automation hardware resist full-stack simulator replacement, demanding middleware adaptation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Immersive Simulator Market |
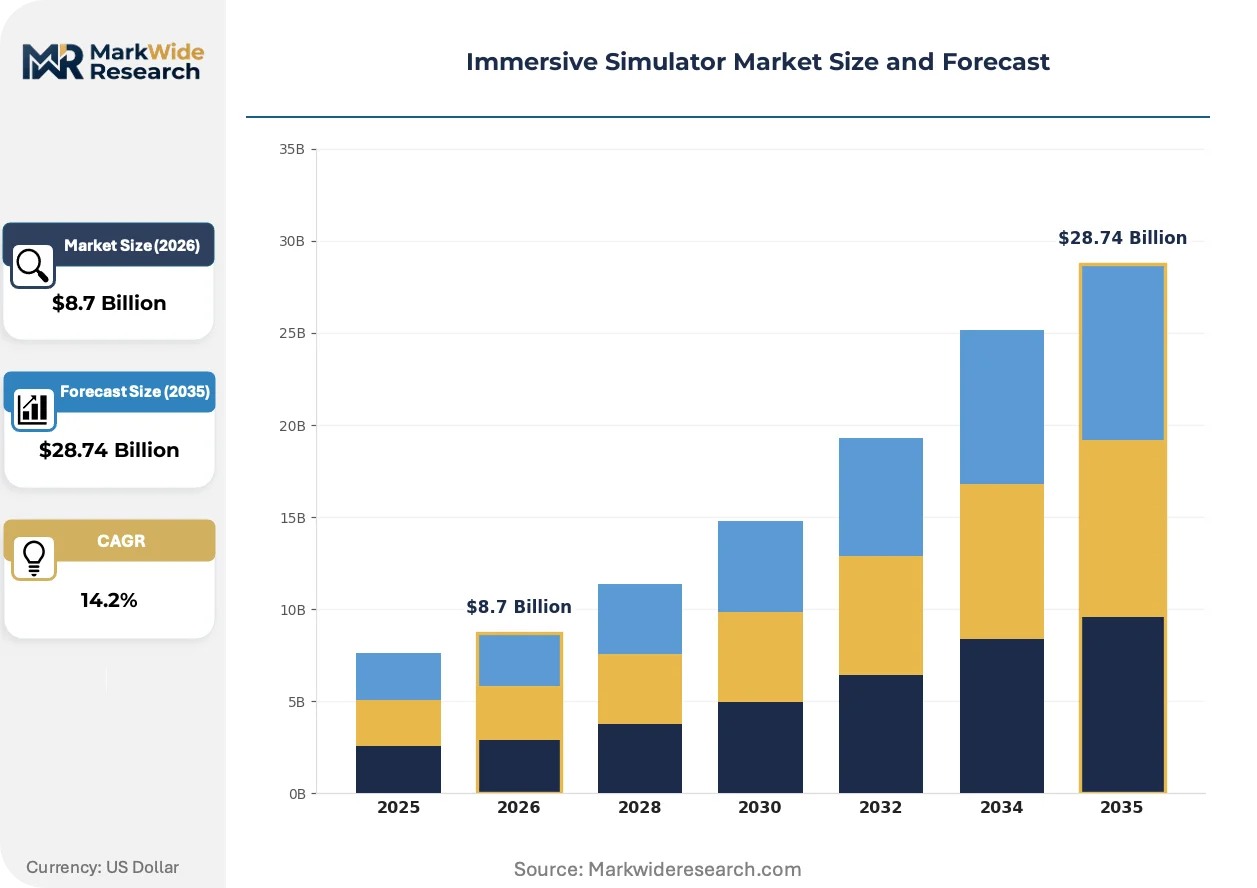
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hardware, Software, Accessories, Training Tools Application: Education, Military Training, Healthcare, Entertainment End User: Educational Institutions, Defense Forces, Medical Facilities, Corporate Sector Technology: Virtual Reality, Augmented Reality, Mixed Reality, Haptic Feedback |
| Companies Covered | AVEVA Group, Siemens AG, EON Reality, Microsoft Corporation, Schneider Electric SE, ESI Group, IBM Corporation, Autodesk, Honeywell International Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Immersive Simulator Market Strategic Shifts
Spatial audio rendering and real-time physics modeling are converging with force-feedback peripherals to compress the fidelity gap between synthetic and operational environments, reshaping how training outcomes are validated.
Optical waveguide displays are miniaturizing. These components reduce headset weight while maintaining field-of-view specifications essential for pilot and surgeon training. Defense procurement offices in the United States are adopting refreshed hardware at 18-month cycles rather than legacy 36-month intervals. This compression is miniaturizing the addressable market for bulky projection-based systems while expanding margins for integrated optics suppliers.
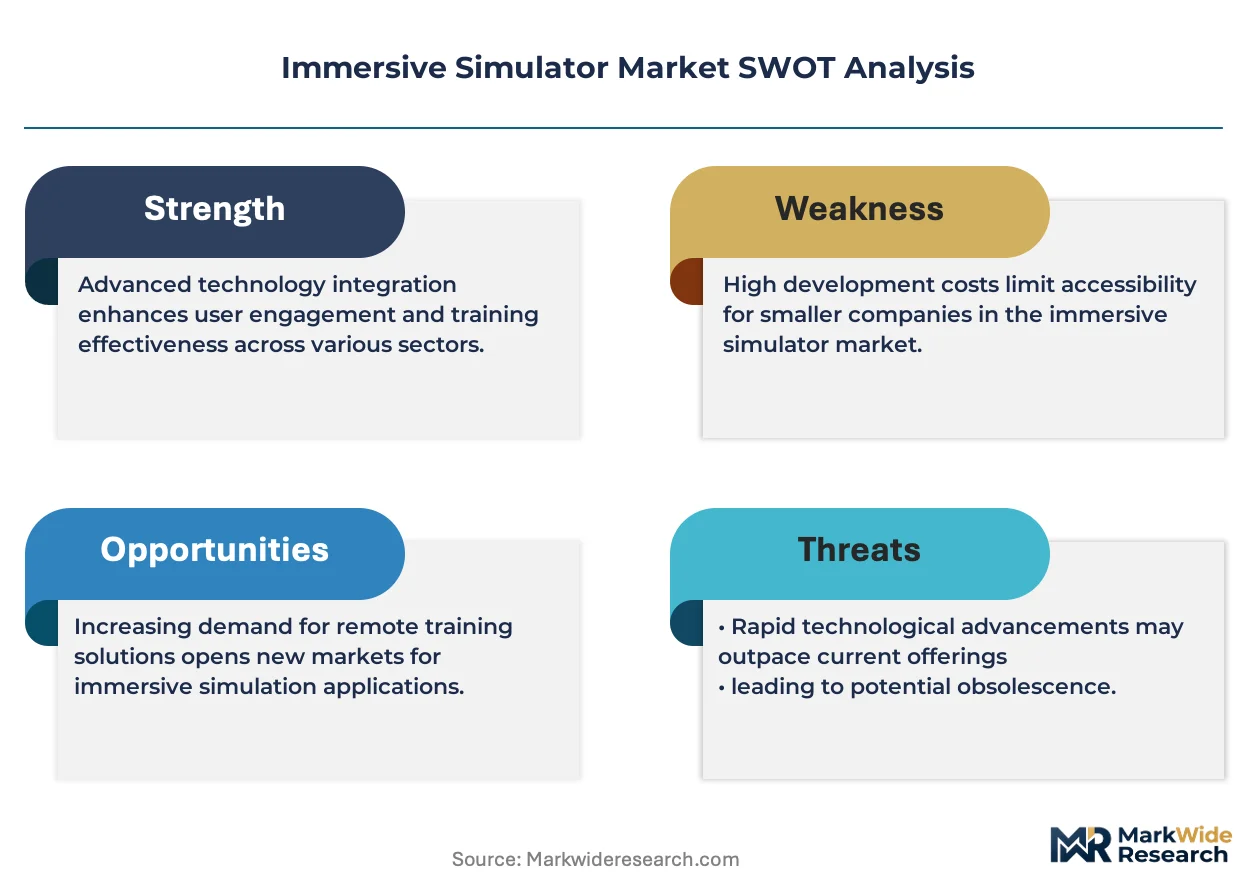
The EU AI Act imposes algorithmic transparency and data residency rules on European-deployed training software. Industrial consequence: vendors must document decision pathways for adaptive difficulty algorithms and scenario generation. Manufacturing simulation deployments across German facilities face the steepest compliance burden, with Siemens AG and competitors restructuring certification workflows to maintain deployment velocity.
Buyers are unbundling after-sales service from hardware procurement. Defense and industrial training departments now contract simulator maintenance through third-party technical service providers rather than original equipment manufacturers. This fragmentation is most visible in South Korea, where military procurement offices separate platform acquisition from five-year sustainment contracts, compressing OEM service margins while expanding specialized maintenance vendor pools.
Immersive Simulator Market Segmentation
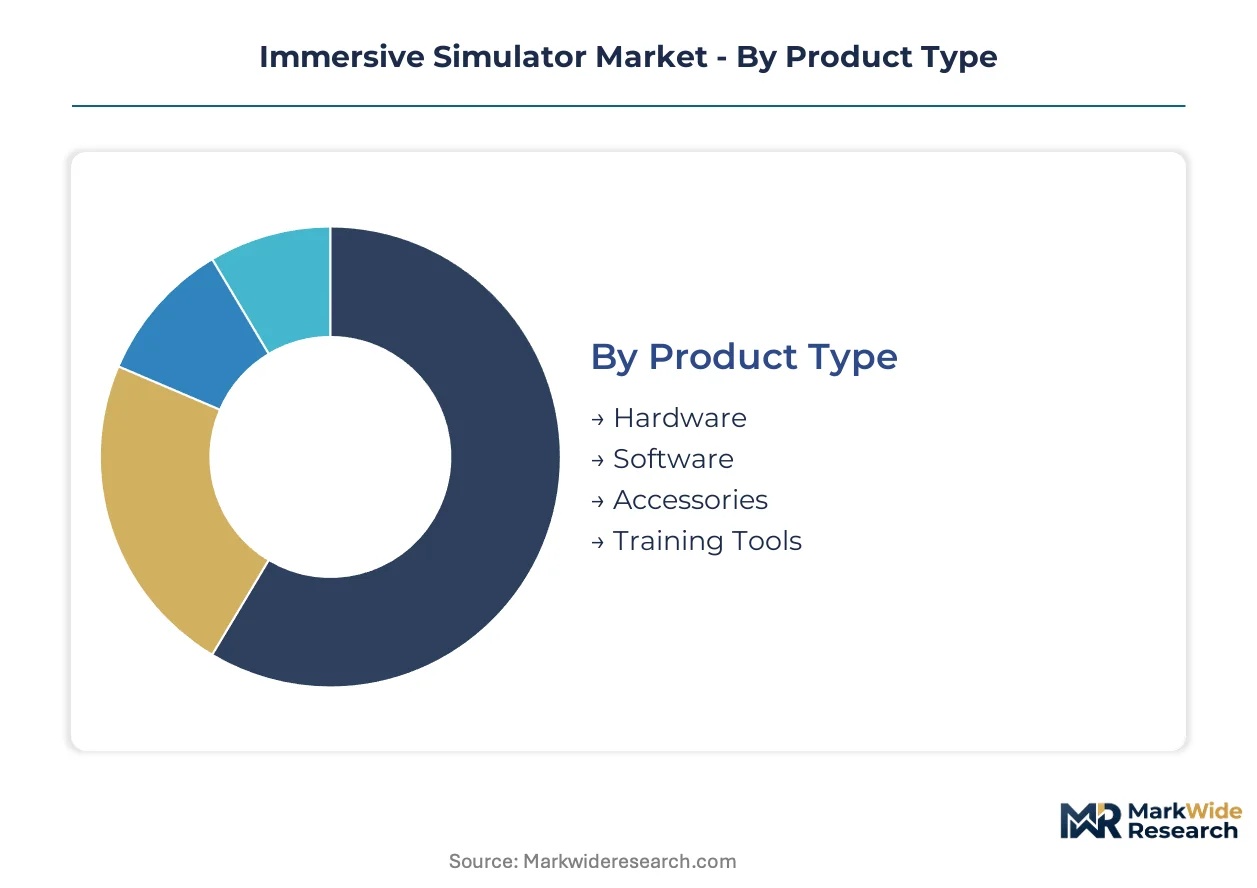
Segmentation in the Immersive Simulator Market reveals distinct procurement patterns across hardware refresh cycles, software licensing models, and service integration requirements. Channel strategy varies sharply between defense procurement offices, educational institutions, and corporate training departments.
Product Type:
Hardware flows through direct defense procurement channels and industrial systems integrators, while software increasingly routes through cloud marketplaces and enterprise IT catalogs.
- Hardware:Headsets, motion platforms, and display systems constitute the revenue foundation. Defense forces in the United States and South Korea drive 18-month refresh cycles for combat training platforms, compressing replacement timelines from legacy 36-month intervals.
- Software:Physics engines, scenario generation platforms, and adaptive difficulty algorithms face EU AI Act compliance requirements for European deployments. German manufacturing facilities demand algorithmic transparency documentation that vendors must embed in certification workflows.
- Accessories:Peripheral ecosystems including tracking sensors and input devices.
- Training Tools:Curriculum packages and assessment modules delivered as subscription services.
By volume, Hardware leads. By growth pace, Software is expanding most quickly.
Application:
Cost tier stratification separates capital-intensive military platforms from scalable educational deployments and high-margin medical applications.
- Education:Secondary and post-secondary institutions deploy scalable virtual-reality content libraries for credential programs. EON Reality anchors position through recurring content revenue models across European and North American campuses.
- Military Training:Mixed-reality combat trainers demand the highest physics fidelity and spatial audio rendering specifications. Defense procurement offices in Germany and the United States are scaling spatial computing platforms for risk-free tactical rehearsal.
- Healthcare:Surgical technique simulators and emergency response protocols leverage force-feedback peripherals for skill acquisition.
- Entertainment:Consumer-facing applications show mature software uptake with established distribution channels.
By capital intensity, Military Training commands premium pricing. By addressable expansion, Healthcare is gaining share fastest.
End User:
Customer type determines integration complexity, with defense forces requiring air-gapped systems and medical facilities demanding FDA validation pathways.
- Educational Institutions:Public and private secondary schools, universities, and vocational training centers procure through aggregated purchasing consortia. Content library subscriptions generate recurring revenue with lower customer acquisition costs than enterprise sales.
- Defense Forces:National military procurement offices specify electromagnetic compatibility and cybersecurity requirements that constrain vendor pools. South Korean military procurement separates platform acquisition from five-year sustainment contracts, fragmenting supplier relationships.
- Medical Facilities:Hospitals and surgical training centers require regulatory validation for patient-facing applications.
- Corporate Sector:Industrial training departments navigate middleware requirements for SCADA and automation hardware integration.
By contract value, Defense Forces dominate. By deployment velocity, Educational Institutions show the steepest expansion trajectory.
Technology:
Technology maturity curves separate established virtual-reality deployments from emerging mixed-reality platforms and nascent haptic feedback penetration.
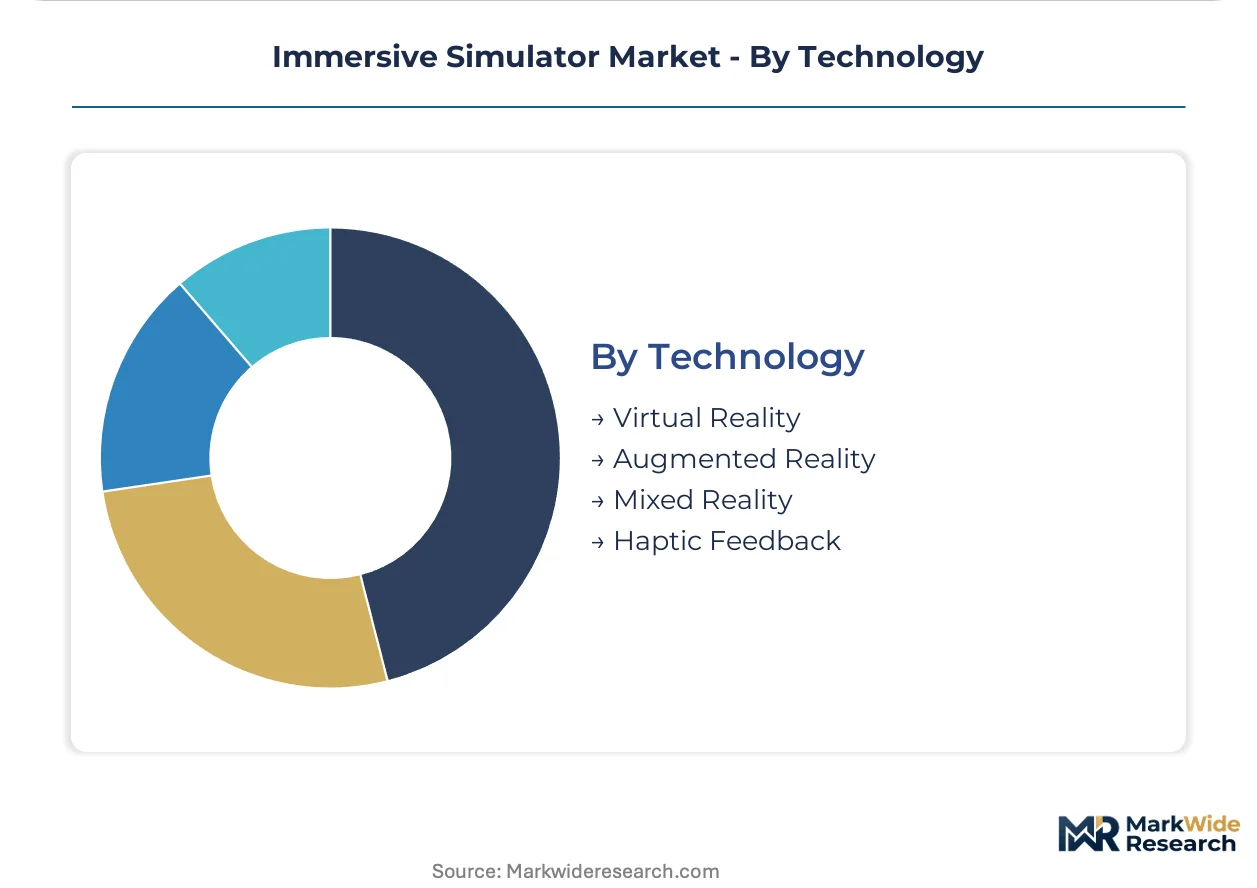
- Virtual Reality:Fully immersive head-mounted displays with positional tracking constitute the installed base. Optical waveguide displays are miniaturizing headset weight while maintaining field-of-view specifications essential for pilot training.
- Mixed Reality:Spatial computing platforms overlay synthetic elements on physical environments. Defense procurement offices are redirecting budgets from screen-based systems toward these platforms, forcing software vendors to recertify under emerging mandates.
- Augmented Reality:Heads-up displays and mobile-overlay systems for maintenance and field operations.
- Haptic Feedback:Force-feedback gloves and full-body suits penetrate medical and military skill-acquisition protocols, expanding use cases beyond visual immersion.
By installed base, Virtual Reality leads. By margin expansion, Haptic Feedback is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German industrial automation exporters supply manufacturing simulation systems to North American defense contractors and Asian medical training centers. Trade corridors concentrate hardware procurement in the United States, Germany, South Korea, China, and Japan.
United States
Defense procurement offices redirect training budgets toward mixed-reality combat platforms, compressing refresh cycles to eighteen months. FAA and OSHA equipment safety benchmarks constrain aviation and industrial simulator certifications. Austin and Orlando anchor military training technology clusters where spatial computing vendors cluster near defense installations.
Germany
Manufacturing facilities demand algorithmic transparency documentation under EU AI Act mandates for adaptive training software. GDPR data residency rules favor regional cloud infrastructure for training-software hosting. Bavarian industrial zones concentrate Siemens AG deployments for factory-floor simulation integration.
South Korea
Military procurement offices separate platform acquisition from five-year sustainment contracts, fragmenting supplier relationships. National electromagnetic compatibility standards align with GB certification reciprocity frameworks. Seoul Capital Area defense technology parks host mixed-reality tactical rehearsal system integration centers.
China
MIIT enforces GB standards for virtual-reality hardware electromagnetic compatibility, constraining import pathways for non-certified peripherals. Domestic dual carbon goals accelerate energy-sector immersive training for hazardous-environment protocols. Yangtze River Delta electronics manufacturing bases produce optical waveguide display components for headset miniaturization.
Japan
METI industrial policy prioritizes surgical simulator validation for patient-facing medical applications. JIS standards govern haptic feedback device precision thresholds for skill-acquisition protocols. Kansai region medical device clusters concentrate force-feedback peripheral development for emergency response training.
Immersive Simulator Market Competitive Environment
Listed leaders compete with private specialists across capital intensity tiers, creating a bifurcated structure where scale-driven conglomerates dominate defense procurement while niche vendors capture medical and educational verticals. The vendor base organizes around three archetypes: industrial automation heritage platforms, cloud-native software specialists, and component-focused haptic technology developers. Dominant competitive moves include strategic partnerships for middleware integration and portfolio diversification into adjacent training verticals.
Within the industrial automation tier, Siemens AG and AVEVA Group exemplify heritage platform providers that anchor manufacturing and energy-sector deployments through physics fidelity advantages. Schneider Electric SE occupies a position bridging operational technology integration with immersive training modules. EON Reality represents the educational content archetype, with Microsoft Corporation and IBM Corporation sitting within enterprise IT integration vectors for corporate training scale.
| Leading Market Players |
|---|
| AVEVA Group |
| Siemens AG |
| EON Reality |
| Microsoft Corporation |
| Schneider Electric SE |
| ESI Group |
| IBM Corporation |
| Autodesk |
| Honeywell International Inc. |
| Others |
Value Chain & Pricing Dynamics
Headset manufacturing scale economies in China compress component costs for motion-platform integrators while elevating price floors for EU-certified software vendors facing algorithmic transparency documentation burdens. Defense procurement offices exploit this asymmetry by unbundling hardware acquisition from sustainment contracts, fragmenting supplier pricing power across the value chain.
Pricing Analysis
Next-generation optical waveguide displays command premium positioning against legacy projection-based systems and prior-generation LCD headsets. Three-tier pricing structure across premium, standard, and economy levels separates FAA-validated aviation platforms from industrial training modules and educational content subscriptions. Pricing pressure stems from eighteen-month hardware refresh cycles in United States and South Korean defense procurement, which compress margins for non-integrated component suppliers. Educational institutions exhibit highest price sensitivity due to aggregated purchasing consortia, while medical facilities absorbing FDA validation costs show lowest sensitivity.
Supply Chain Analysis
China and South Korea anchor optical waveguide display fabrication and electromagnetic compatibility testing for headset miniaturization. Taiwan supplies precision motion sensors and haptic feedback micro-actuators. Raw material dependencies span rare-earth elements for display phosphors, high-purity silicon for sensor substrates, and specialized polymers for force-feedback glove membranes. Supply chain risk centers on MIIT GB standards enforcement fragmenting import pathways for non-certified peripherals. Distribution runs through defense procurement channels, industrial systems integrators, and cloud marketplaces for software licensing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among defense procurement offices that separate platform acquisition from sustainment contracts, fragmenting vendor relationships and compressing OEM service margins.
For Market Incumbents: Compound certification investments under EU AI Act algorithmic transparency mandates to erect vendor-moat defenses against cloud-native software specialists. Acquire regional cloud infrastructure providers in Germany to satisfy GDPR data residency requirements. Prioritize backward integration into optical waveguide display sourcing to hedge against China MIIT import pathway constraints. For New Entrants and Emerging Players: Differentiate on haptic feedback peripheral specialization for medical skill-acquisition protocols, where force-feedback glove precision thresholds remain underpenetrated by industrial automation heritage platforms. Target educational institution content library subscriptions as the most penetrable segment given lower integration complexity and recurring revenue conversion. Pursue channel partnerships with aggregated purchasing consortia to bypass direct enterprise sales friction. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among educational content library providers with campus-wide deployment contracts spanning secondary and post-secondary credential programs. Long-term viability favors vendors with demonstrated EU AI Act certification workflows and established defense procurement relationships. Monitor GB standards reciprocity framework negotiations as the inflection indicator for hardware supply chain reconfiguration.| Strategic Initiative | Industry Significance |
|---|---|
| Algorithmic Transparency Certification | EU AI Act compliance creates certified-vendor moats favoring established platform providers with documentation workflows. |
| Haptic Feedback Peripheral Development | Force-feedback glove precision expands addressable use cases beyond visual immersion into surgical training protocols. |
| Regional Cloud Infrastructure Acquisition | GDPR data residency rules displace US-centric architectures for European training-software hosting deployments. |
| Defense Sustainment Contract Separation | South Korean military procurement fragmentation expands specialized maintenance vendor pools while compressing OEM margins. |
| Optical Waveguide Display Integration | Miniaturization reduces headset weight for pilot and surgeon training while maintaining field-of-view specifications. |
Study Parameters
The analysis maps hardware refresh cycles, software licensing models, and service integration requirements, each validated through defense procurement officers, educational technology directors, industrial training managers, and medical simulation coordinators. Primary interview data triangulates against secondary sources including FAA equipment safety filings, EU AI Act regulatory documentation, MIIT GB standards publications, and defense procurement contract disclosures. Bottom-up segment sizing and top-down macroeconomic benchmarking ensure cross-validation consistency.
Outputs were validated against external benchmarks including defense training budget reallocation patterns, enterprise IT integration spend disclosures, and educational institution technology adoption surveys across the projection horizon. Segmentation dimensions modeled include product type, application, end user, and technology maturity curves. CAGRs derive from installed base growth rates, replacement cycle compression, and penetration trajectory analysis for haptic feedback peripherals.
Material uncertainties — regulatory reciprocity negotiations, electromagnetic compatibility certification delays, and physics fidelity threshold advancements — sit outside the modeled envelope. Forecasts reflect assumptions regarding defense budget continuity, EU AI Act enforcement consistency, and GB standards reciprocity framework stability. Recalibration cycles align with material shifts in procurement regulation, certification pathway harmonization, and hardware refresh cycle velocity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Virtual Reality (VR) and Augmented Reality (AR)
Consumer Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
Canada Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Prototype Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Virtual Reality in Therapy Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality in Construction Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality Content Creation Market
Virtual Reality (VR) and Augmented Reality (AR)
Immersive Virtual Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
France Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality Headset Market
Virtual Reality (VR) and Augmented Reality (AR)
VR Box Glasses Market
Virtual Reality (VR) and Augmented Reality (AR)
Germany Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Enterprise Augmented Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Mobile Augmented Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Asia-Pacific Virtual Reality (VR) Health Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Augmented and Mixed Reality (VR/AR) Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Augmented Reality and Virtual Reality (AR/VR) in Aviation Market